
 Electric Commercial Deep Fryers Market | 2026-2036
Electric Commercial Deep Fryers Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Commercial Deep Fryers Market Foresight
Maintenance subscription packages for oil filtration and heating element replacement is rebalancing how operators budget capital versus operating expenses. Frymaster leverages its service network to anchor recurring revenue in high-volume fast food chains. Henny Penny specializes in pressure fryer configurations that dominate the chicken QSR segment. Pitco competes through durable floor fryer designs that sustain long replacement cycles in independent restaurants.
An electric commercial deep fryer is a thermostatically controlled cooking appliance that submerges food in heated oil at temperatures typically ranging from 325°F to 375°F, using electric resistance elements or induction coils to transfer thermal energy for crisping, browning, and rapid cooking in foodservice environments. Floor fryers with large oil capacity dominate institutional and high-throughput chain kitchens where volume throughput determines equipment selection. Oil filtration technology commands premium positioning as operators face rising edible oil costs and waste disposal regulations. Countertop fryers serve food trucks and catering services where space constraints and mobility requirements limit installation options.
The US Department of Energy sets minimum efficiency standards for commercial kitchen equipment, while the EU Ecodesign Directive restricts standby power consumption and mandates recyclable material content in new fryer sales. NSF International certification governs food safety construction standards, creating a compliance barrier for unlisted manufacturers seeking North American distribution. Stakeholders must monitor how state-level electrification incentives and municipal grease interceptor codes reshape site preparation costs and equipment specification criteria.
Market Dynamics
Energy-efficiency mandates from the US Department of Energy and the EU Ecodesign Directive are compelling operators to replace conventional electric resistance fryers with induction and convection systems, compressing replacement cycles and reshaping equipment procurement budgets.
Growth Catalysts
- US Department of Energy efficiency standards:Minimum performance thresholds for commercial kitchen equipment are accelerating fryer turnover in institutional kitchens and chain restaurants.
- Quick-service restaurant automation:Labor cost pressures are driving automated fry line installations across high-volume foodservice operations.
- Induction coil technology:Faster heat recovery and precise temperature control are displacing traditional resistance elements in premium equipment specifications.
Market Restraints
- Edible oil price volatility:Fluctuating commodity costs for frying oils strain operating budgets and complicate total cost of ownership calculations.
- NSF International certification barriers:Unlisted manufacturers face blocked North American distribution until completing lengthy food safety construction validation.
- Gas fryer substitution:Natural gas infrastructure in existing kitchens limits electric equipment penetration in retrofit applications.
Strategic Opportunities
- Food truck and mobile catering expansion:Space-constrained operators are driving countertop electric fryer demand for portable, high-output cooking.
- State-level electrification incentives:Utility rebate programs in Texas and Florida are offsetting upfront equipment costs for chain restaurant buildouts.
- Oil filtration-as-a-service:Subscription models for filtration and heating element replacement are anchoring recurring revenue streams with high-volume operators.
Industry Challenges
- Heating element replacement skill shortages:Technicians trained on induction coil systems remain scarce relative to conventional electric repair expertise.
- Municipal grease interceptor code compliance:Site preparation requirements vary by jurisdiction, complicating standardized equipment specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Commercial Deep Fryers Market |
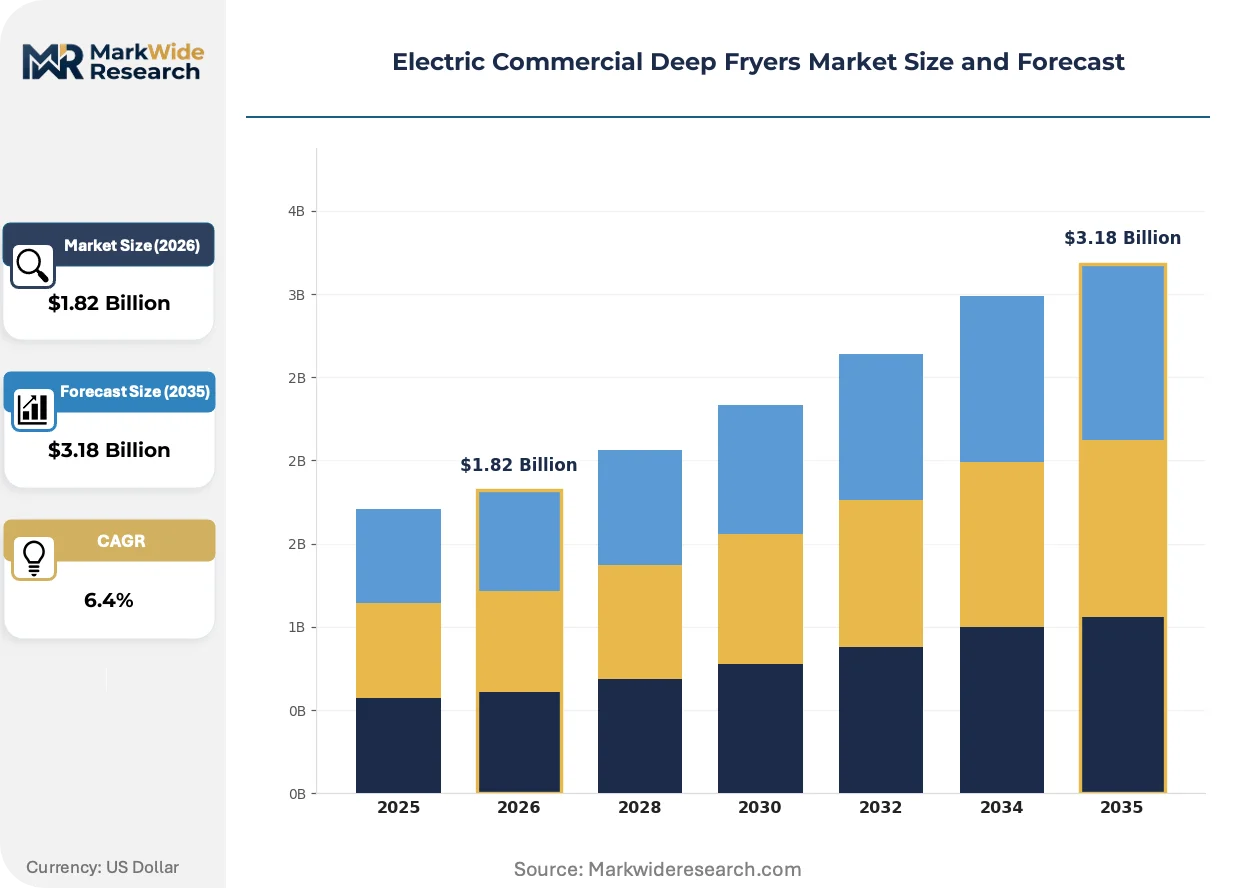
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Fryers, Floor Fryers, Multi-Function Fryers, Pressure Fryers End User: Restaurants, Catering Services, Food Trucks, Fast Food Chains Size: Small Capacity, Medium Capacity, Large Capacity, Extra Large Capacity Technology: Convection System, Direct Oil Heating, Induction Heating, Oil Filtration Technology |
| Companies Covered | Imperial, Wells Manufacturing, Frymaster, Vollrath, Winco, Pitco, Henny Penny, Range of California, Vulcan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Commercial Deep Fryers Market Shifts & Advancements
Equipment manufacturers are converging thermal efficiency improvements with predictive maintenance capabilities, while regulatory pressure and shifting procurement models compress traditional sales cycles into service-oriented relationships.
Induction heating technology is integrating into commercial fryer architectures to deliver sub-minute temperature recovery and eliminate the thermal lag inherent in resistance-element designs. High-throughput chicken QSR chains are specifying these systems for consistent product quality across peak demand periods. The technology is integrating oil filtration cycles with heating performance data, enabling predictive maintenance that reduces unplanned downtime.
The EU Ecodesign Directive is mandating standby power limits and recyclable material content thresholds for new fryer sales across member states. Manufacturers must redesign control systems and housing materials to maintain market access. Pressure fryer configurations face particular scrutiny due to embedded electronics and insulation requirements, driving redesign investment toward modular component architectures.
After-sales service unbundling is separating equipment sales from maintenance contracts in procurement negotiations. Independent restaurants are gravitating toward third-party service providers rather than manufacturer-captive networks. Texas and Florida chain buildouts demonstrate this most visibly, with operators negotiating multi-site service agreements that span equipment brands and standardize response time commitments.
Electric Commercial Deep Fryers Market Segmentation
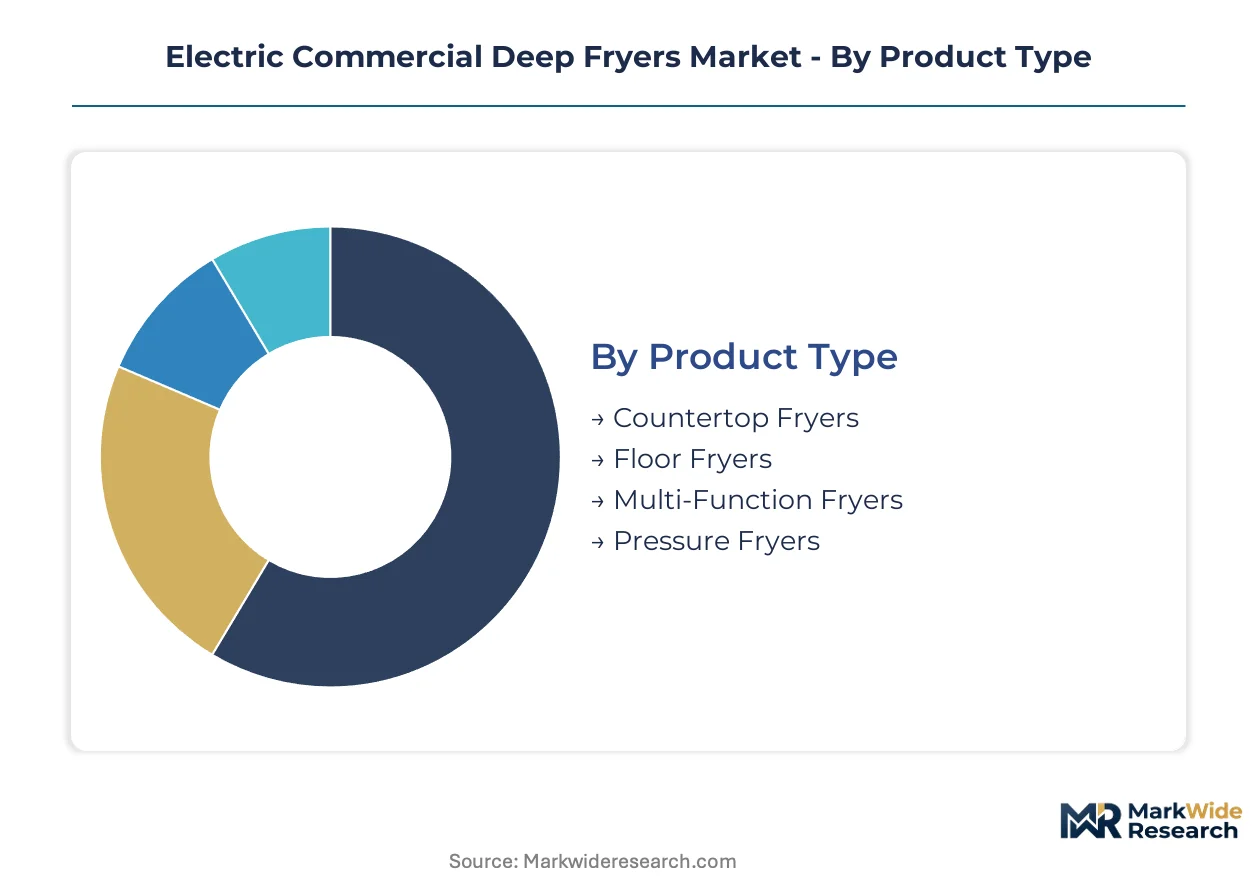
Equipment specification in commercial deep frying diverges sharply by operational throughput, site constraints, and energy infrastructure availability. Buyers prioritize oil recovery speed, footprint efficiency, and compliance with local electrification mandates when mapping segment choices to capital budgets.
Product Type:
Volume throughput and kitchen layout constraints determine whether operators prioritize mobility or stationary high-capacity installation.
- Floor Fryers:Stationary units with oil capacities exceeding 50 pounds dominate institutional kitchens and high-volume chain operations. Demand concentrates in Texas and Florida where aggressive QSR buildouts require equipment that sustains continuous production during peak service windows.
- Countertop Fryers:Compact electric units with rapid heat-up cycles serve food trucks and catering operations where space constraints and mobility requirements limit installation options. Growth tilts toward mobile catering segments in urban clusters with strict ventilation codes.
- Pressure Fryers:Sealed cooking environments that accelerate protein preparation while reducing oil absorption, primarily specified by chicken-focused QSR chains.
- Multi-Function Fryers:Hybrid equipment combining frying with secondary cooking modes, gaining traction in independent restaurants seeking equipment consolidation.
Volume sits with Floor Fryers; growth tilts toward Countertop Fryers.
End User:
Labor cost pressures and automation readiness separate high-volume chains from independent operators in procurement behavior.
- Fast Food Chains:Standardized equipment specifications across multi-site networks prioritize rapid oil recovery and predictive maintenance integration. Chains in the United States negotiate multi-year service agreements that bundle filtration subscriptions with equipment procurement.
- Restaurants:Independent full-service and casual dining operators select equipment based on menu breadth and peak demand variability, with durability concerns dominating replacement decisions.
- Food Trucks:Mobile operators demand UL-listed electric units with low amp draw requirements to accommodate generator or shore power limitations.
- Catering Services:Event-based foodservice requires rapid deployment capability and equipment that withstands transport vibration without calibration drift.
Procurement scale concentrates with Fast Food Chains; expansion is climbing fastest among Food Trucks.
Size:
Oil volume capacity directly correlates with hourly throughput and total cost of ownership calculations for frying oil.
- Large Capacity:Oil reservoirs exceeding 75 pounds serve institutional cafeterias and airport concessions where batch consistency across extended operating hours determines equipment selection.
- Extra Large Capacity:Industrial-scale fryers with 100+ pound oil capacity anchor central commissary operations supplying multiple satellite locations.
- Medium Capacity:40-75 pound units balance throughput flexibility with oil change frequency, preferred by mid-scale independent restaurants.
- Small Capacity:Under 40-pound configurations serve specialty frying applications and test kitchen environments with limited production requirements.
Installed base clusters in Large Capacity; steepest expansion trajectory belongs to Extra Large Capacity commissary configurations.
Technology:
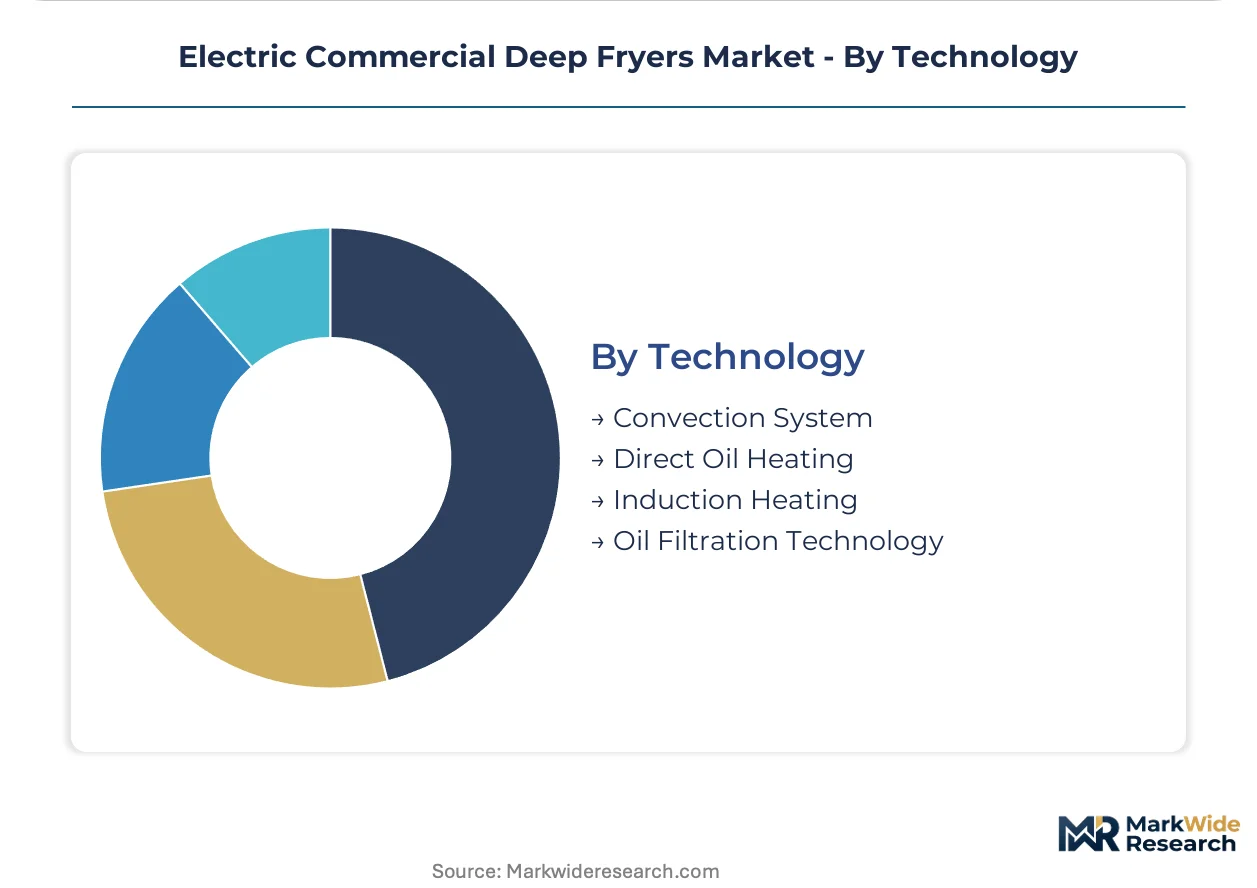
Energy efficiency mandates from the US Department of Energy are compressing replacement cycles toward advanced thermal transfer methods.
- Induction Heating:Electromagnetic coil systems deliver sub-minute temperature recovery and eliminate thermal lag inherent in resistance elements. High-throughput chicken QSR chains in the United States specify these systems for consistent product quality across peak demand periods.
- Oil Filtration Technology:Integrated filtration systems extend oil life and reduce waste disposal costs, commanding premium positioning as edible oil prices fluctuate.
- Convection System:Forced-air circulation improves heat distribution uniformity, specified by operators prioritizing product consistency over raw speed.
- Direct Oil Heating:Traditional resistance element configurations face displacement as efficiency standards tighten, remaining relevant only in retrofit applications with electrical infrastructure constraints.
Deployment share concentrates in Oil Filtration Technology; induction configurations are gaining share fastest as electrification incentives expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters in Germany and China supply the bulk of commercial fryer exports, while consumption concentrates in the United States and select European markets where quick-service restaurant automation accelerates replacement cycles.
United States
Texas and Florida chain restaurant buildouts drive floor fryer procurement at scale, with operators negotiating multi-site service agreements that bundle filtration subscriptions. The US Department of Energy efficiency standards compress replacement cycles toward induction systems. Dallas-Fort Worth and Miami metropolitan clusters anchor aggressive QSR expansion with standardized equipment specifications.
Germany
Industrial equipment fabricators supply precision-engineered fryer components to European and export markets. The EU Ecodesign Directive mandates standby power limits and recyclable material content, forcing control system redesigns. Baden-Württemberg manufacturing corridors concentrate thermal engineering expertise for premium equipment tiers.
China
Domestic foodservice growth and export manufacturing capacity expand simultaneously, with coastal provinces serving both regional restaurant chains and international OEM supply. GB standards and MIIT industrial policy shape equipment certification requirements. Yangtze River Delta production hubs scale induction coil manufacturing for cost-competitive export tiers.
United Kingdom
Independent restaurant operators and pub chains sustain mid-capacity equipment demand, with procurement patterns favoring durability over automation integration. CE marking alignment post-Brexit creates dual compliance pathways for manufacturers. London and Southeast England clusters concentrate catering service operators driving countertop fryer adoption.
Japan
Compact kitchen footprints in urban centers prioritize space-efficient countertop configurations with precise temperature control. METI energy efficiency guidelines and JIS standards govern equipment specifications for domestic sales. Kanto region restaurant density supports premium-tier induction system penetration in high-throughput operations.
Electric Commercial Deep Fryers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct tiers. The market structure consolidates around three to five dominant equipment manufacturers with captive service networks, while regional fabricators occupy price-sensitive segments. Strategic archetypes separate premium-tier automation specialists from durability-focused floor fryer builders and countertop mobility providers. Competitive moves center on after-sales service unbundling and multi-site maintenance contract aggregation.
Among North American equipment specialists, Frymaster and Henny Penny exemplify divergent specialization paths within the premium tier. Pitco occupies a position emphasizing replacement cycle durability for independent restaurant operators. These three manufacturers represent distinct competitive archetypes: service-network anchoring, pressure-frying configuration dominance, and long-cycle floor equipment reliability.
| Leading Market Players |
|---|
| Imperial |
| Wells Manufacturing |
| Frymaster |
| Vollrath |
| Winco |
| Pitco |
| Henny Penny |
| Range of California |
| Vulcan |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators in Baden-Württemberg and the Yangtze River Delta anchor component supply, creating pricing discipline through captive thermal engineering expertise and limited spot-market participation. Their ownership structure insulates pricing from quarterly earnings pressure while concentrating negotiation leverage with OEM assemblers.
Pricing Analysis
Cost-down pressure on standard resistance-element fryers accelerates because induction systems capture premium positioning through US Department of Energy compliance advantages. Three-tier pricing structure across premium induction, standard convection, and economy resistance levels separates buyers by certification tier and after-sales bundling intensity. Price differentiation hinges on NSF International listing status and multi-site service contract attachment. Independent restaurants exhibit highest price sensitivity, deferring replacement until regulatory mandates force action; fast-food chains accept premium tiers for predictive maintenance integration.
Supply Chain Analysis
Refurbishment flows for heating elements and control systems concentrate in Texas and Florida service hubs, extending equipment life cycles and compressing new unit demand. Manufacturing draws from Germany, China, and the United States for precision thermal components, stainless steel reservoirs, and induction coil assemblies. Supply chain risk centers on single-source vulnerability for specialized electromagnetic components subject to MIIT export licensing. Distribution runs through manufacturer-captive service networks and third-party foodservice equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric commercial deep fryer market sits in a technology-transition phase where induction coil architectures displace resistance-element legacy systems. This displacement reconfigures procurement criteria toward energy efficiency certification and predictive maintenance capability.
For Market Incumbents: Anticipate accelerated replacement cycles driven by US Department of Energy efficiency standards compressing equipment lifespans. Defend installed base through vertical integration into filtration-as-a-service subscriptions that anchor recurring revenue. Counter gas fryer substitution threats in retrofit applications by emphasizing total cost of ownership advantages in electrification incentive territories.
For New Entrants and Emerging Players: Food truck operators represent an underserved buyer archetype with unmet demand for UL-listed countertop units with sub-30 amp draw requirements. Target mobile catering clusters in urban markets with strict ventilation codes where generator compatibility determines equipment selection. Penetrate through direct-to-operator digital channels bypassing traditional dealer networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor induction technology specialists in Texas and Florida where chain buildouts concentrate procurement volume. Long-term viability favors manufacturers with captive service networks capable of aggregating multi-site maintenance contracts. Monitor state-level electrification incentive expiration as inflection indicator for replacement demand velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Induction Technology Migration | US Department of Energy standards accelerate displacement of resistance-element legacy systems. |
| Filtration-as-a-Service Launch | Subscription models anchor recurring revenue with high-volume QSR chains in Texas and Florida. |
| Countertop Product Line Expansion | Food truck and mobile catering segments demand UL-listed units with low amp draw specifications. |
| Multi-Site Service Contract Aggregation | Standardized response commitments across equipment brands capture chain restaurant procurement. |
| EU Ecodesign Compliance Redesign | Standby power limits and recyclable material mandates force control system architecture changes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with foodservice equipment procurement directors, chain restaurant facility managers, aftermarket service technicians, and commercial kitchen design consultants combined with secondary sources including US Department of Energy efficiency standard documentation, EU Ecodesign Directive implementation guidance, and NSF International certification databases. Bottom-up equipment shipment tracking and top-down foodservice construction spending analysis provided triangulation validation.
Data-stream reconciliation across shipment volumes, replacement cycle surveys, and regulatory compliance timelines structured the analytical framework. Segmentation dimensions modeled include product type, end user category, oil capacity tier, and heating technology architecture across the projection horizon. CAGRs derived from equipment replacement elasticity coefficients and electrification incentive diffusion curves. Forecast inputs incorporated state-level rebate program allocations and municipal grease interceptor code adoption patterns.
Revisions become necessary when US Department of Energy standard implementation delays, edible oil price volatility spikes, or induction technician training bottlenecks materialize. Forecasts reflect assumptions about regulatory enforcement continuity and chain restaurant expansion velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Instant Pot Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Global Roti Maker Market