
 Scroll Chiller Market | 2026-2036
Scroll Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Scroll Chiller Market Analytics
Chinese compressor manufacturing is restructuring capacity toward higher-efficiency scroll platforms. Daikin Industries leverages its Osaka R&D base to sustain technology leadership in compact modular designs. Carrier anchors North American distribution through extensive contractor networks. Trane competes on integrated building automation compatibility.
A scroll chiller employs orbiting and fixed scrolls to compress refrigerant, typically achieving cooling capacities from 10 to 1,500 tons with part-load efficiency ratios exceeding full-load performance by 15-25%. Water-cooled configurations dominate large commercial installations where cooling towers permit heat rejection, while modular scroll systems are gaining fastest in data center applications requiring redundant, scalable capacity. Process cooling commands premium margins due to precise temperature stability requirements in pharmaceutical and semiconductor fabrication.
The US Department of Energy and China's MIIT enforce divergent minimum efficiency performance standards, forcing manufacturers to maintain dual certification tracks. EPA SNAP regulations and the EU F-Gas Regulation are accelerating refrigerant transitions toward lower-GWP alternatives. Stakeholders must monitor refrigerant phase-down schedules and efficiency tier migrations to time capital deployment and avoid stranded equipment portfolios.
Market Dynamics
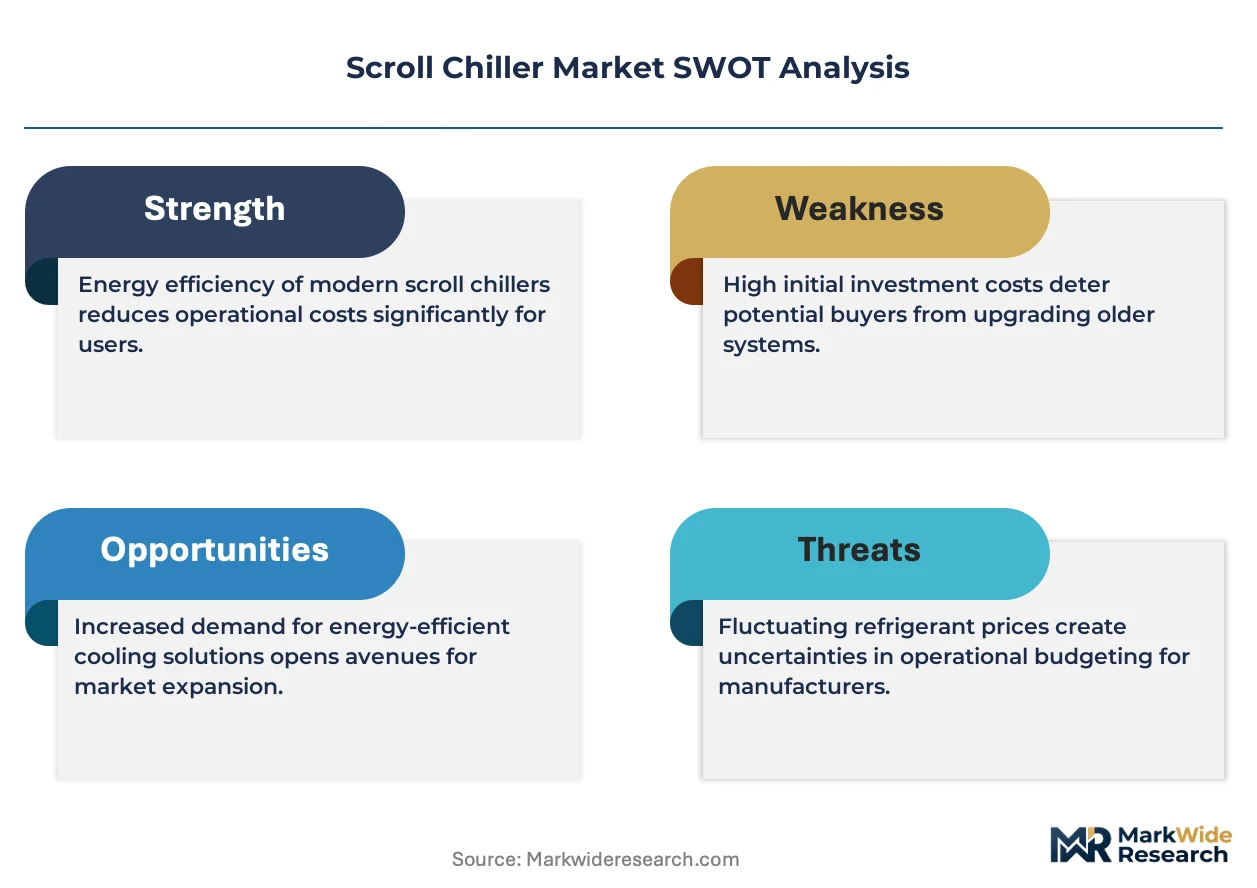
Refrigerant phase-down mandates under the EPA SNAP program and EU F-Gas Regulation are forcing simultaneous equipment redesign and supply chain requalification across scroll chiller manufacturing footprints.
Growth Catalysts
- Data Center Expansion:Hyperscale operators in Singapore and Northern Virginia are commissioning modular scroll systems to support AI-driven thermal loads. This infrastructure buildout sustains order visibility for 200-500 ton capacity units.
- Industrial Retrofit Mandates:China's MIIT efficiency standards are accelerating replacement cycles in Jiangsu and Zhejiang provinces. Facility managers are specifying variable-speed scroll compressors to meet tiered performance thresholds.
- Process Cooling Premiumization:Semiconductor fabrication and pharmaceutical manufacturing require temperature stability within ±0.5°C. Scroll chillers with advanced electronic expansion valves are capturing this specification-driven demand.
Market Restraints
- Copper and Rare Earth Volatility:Compressor motor laminations depend on neodymium magnet supply concentrated in Chinese processing facilities. Price swings in these inputs compress margin predictability for OEMs.
- Refrigerant Transition Friction:The shift from R-410A to lower-GWP alternatives like R-32 and R-454B requires complete system redesign. Dual certification tracks for US DOE and China MIIT standards extend development timelines.
- Alternative Cooling Displacement:Magnetic bearing centrifugal chillers are gaining specification in installations above 300 tons. This technology substitution threatens scroll penetration at the upper capacity boundary.
Strategic Opportunities
- India Industrial Corridor Penetration:The PLI scheme for semiconductor manufacturing is attracting fabrication investments in Gujarat and Tamil Nadu. Scroll chiller suppliers can anchor early relationships in these greenfield facilities.
- Heat Recovery Integration:Converging scroll compressor technology with heat pump functionality enables simultaneous cooling and process hot water generation. Food processing and district heating applications represent untapped specification potential.
- Refrigerant-as-a-Service Models:Leasing structures that bundle equipment, refrigerant management, and compliance liability are emerging in European markets. The EU F-Gas Regulation's phasedown creates natural demand for this channel innovation.
Industry Challenges
- Refrigerant Handling Certification:Technicians require EPA Section 608 or equivalent credentials for low-flammability A2L refrigerants. Training pipeline constraints are lengthening commissioning schedules in North American markets.
- Legacy Control System Integration:Building automation protocols from BACnet to proprietary legacy networks create interoperability friction. Scroll chiller OEMs must maintain multiple communication module variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scroll Chiller Market |
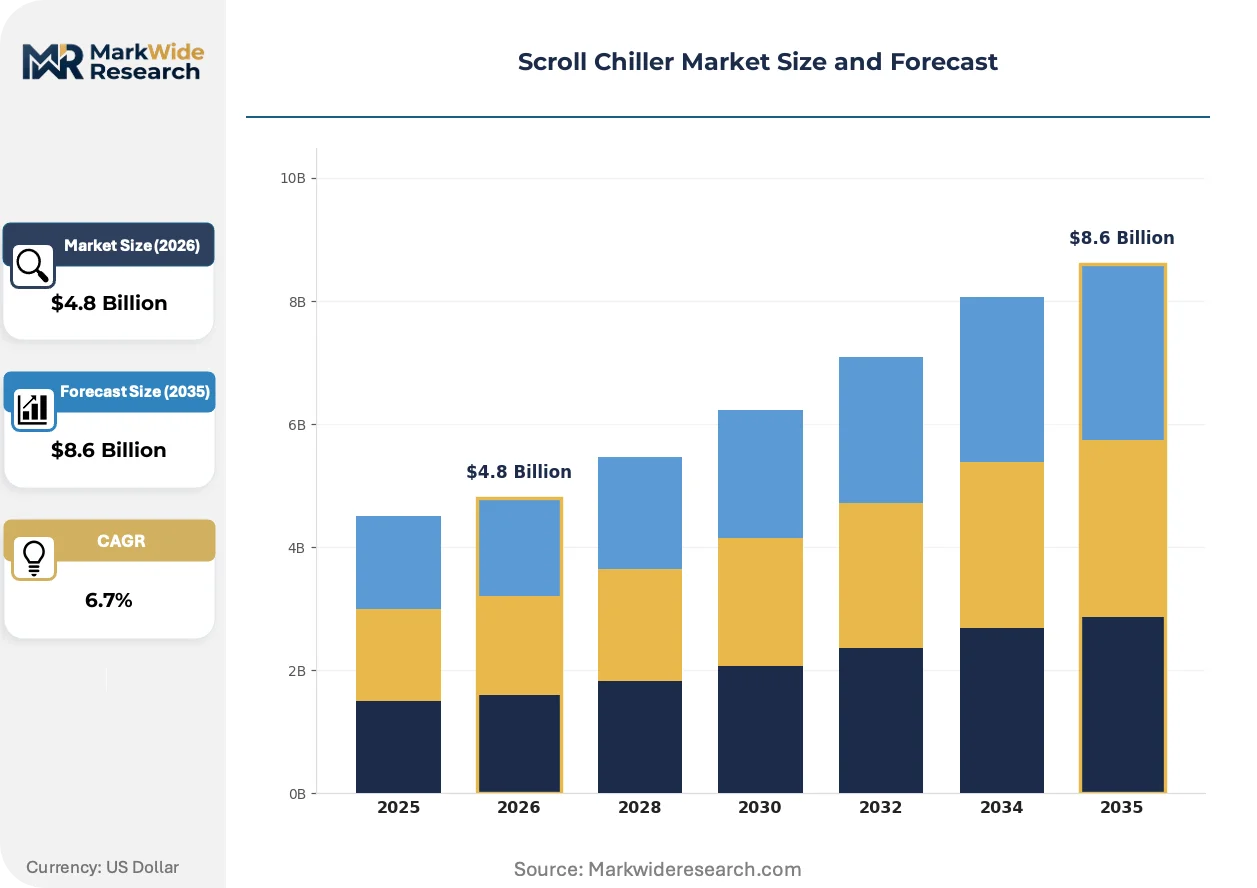
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Scroll, Modular End User: Healthcare Facilities, Manufacturing Plants, Data Centers, Residential Buildings Application: Heating, Ventilation, Air Conditioning, Process Cooling Installation Type: Indoor, Outdoor, Centralized, Decentralized |
| Companies Covered | Johnson Controls, Daikin Industries, Trane, Carrier, Hitachi Appliances, Broad Air Conditioning, Thermax, Mitsubishi Electric, Midea Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scroll Chiller Market Evolving Landscape
Predictive maintenance algorithms and refrigerant monitoring sensors are embedding intelligence directly into scroll compressor architectures, shifting competitive differentiation from hardware efficiency to operational uptime guarantees.
Variable-speed drive technology is automating part-load optimization in data center applications. Colocation operators are specifying these units to match cooling output against fluctuating server rack densities. The technology is automating energy arbitrage decisions that previously required manual setpoint adjustments.
The EU F-Gas Regulation's quota-based phasedown is compressing refrigerant availability for service and new equipment. OEMs are accelerating R-32 and R-454B platform introductions to maintain market access. Process cooling segments with long equipment lifecycles are most exposed to refrigerant availability risk.
Buyer concentration among hyperscale data center operators is consolidating procurement leverage. These entities are unbundling equipment purchase from installation and commissioning services. Northern Virginia and Singapore markets exhibit the most pronounced shift toward direct OEM relationships and away from traditional contractor intermediaries.
Scroll Chiller Market Segmentation
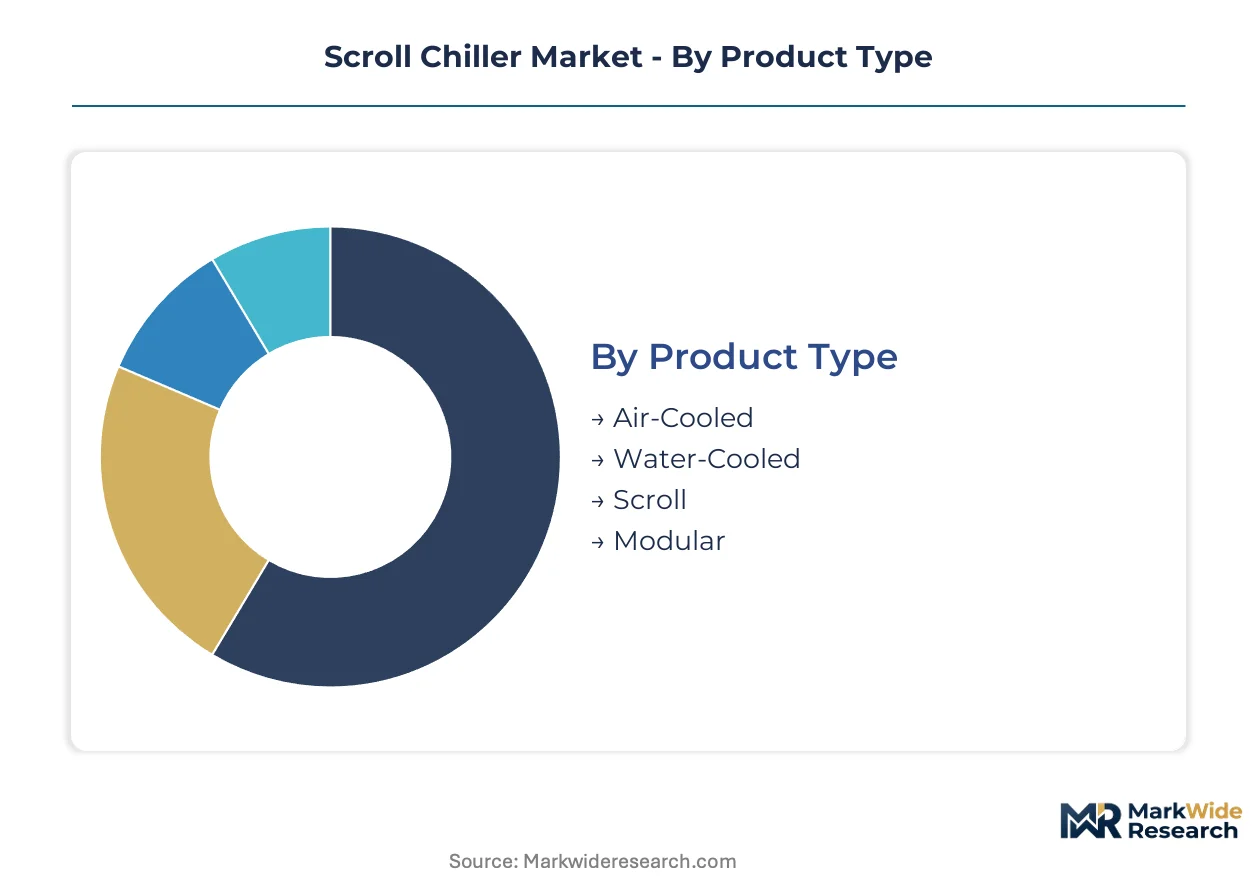
Scroll chiller procurement decisions bifurcate sharply between efficiency-mandated retrofits and greenfield capacity expansion. Specification requirements diverge across certification regimes, with EPA SNAP, EU F-Gas, and China MIIT standards forcing parallel equipment development tracks.
Product Type:
Certification burden concentrates on water-cooled and modular configurations, where EPA Section 608 and EU F-Gas handling credentials apply most stringently to refrigerant circuits above defined charge thresholds. Air-cooled systems face lighter compliance overhead in distributed installations.
- Air-Cooled:Eliminates cooling tower infrastructure through direct ambient heat rejection. Demand clusters in Singapore data centers and Northern Virginia colocation facilities where water scarcity or discharge restrictions prohibit evaporative cooling.
- Water-Cooled:Achieves superior thermodynamic efficiency via cooling tower integration. Jiangsu and Zhejiang manufacturing retrofits specify these units to meet MIIT tiered performance thresholds with lower operating expenditure.
- Scroll:Compressor architecture employing interleaved orbiting and fixed spirals. Pharmaceutical cleanrooms in Basel and Singapore semiconductor fabs specify these for vibration isolation and precise capacity modulation.
- Modular:Scalable capacity through parallel compressor staging. Hyperscale operators in Ashburn and Singapore commission 200-500 ton modules for N+1 redundancy against AI workload thermal spikes.
Leading the category by volume: Water-Cooled. Expanding most quickly: Modular.
End User:
Cost tier stratification separates mission-critical process cooling from comfort applications, with semiconductor and pharmaceutical facilities absorbing 40-60% price premiums for temperature stability guarantees.
- Healthcare Facilities:Surgical suites and imaging departments require continuous cooling with failover redundancy. US hospital systems specify BACnet-integrated scroll chillers to mesh with existing building automation infrastructure.
- Manufacturing Plants:Automotive paint lines and metal forming operations demand robust part-load performance. German OEMs in Stuttgart and Munich specify variable-speed drives to match cooling output against batch production cycles.
- Data Centers:Hyperscale and colocation operators drive specification toward refrigerant leak detection and predictive maintenance integration. Singapore's tropical climate and Northern Virginia's density constraints favor modular scroll architectures.
- Residential Buildings:Mid-rise multifamily and luxury single-family installations specify compact air-cooled units. Tokyo and Osaka developers prioritize Daikin and Panasonic systems for acoustic performance in dense urban envelopes.
Dominant by revenue: Data Centers. Steepest expansion trajectory: Healthcare Facilities.
Application:
Application maturity separates commodity HVAC from specification-driven process cooling, with margin structures inversely correlated to equipment standardization.
- Heating:Heat pump configurations recovering compressor discharge energy for process hot water. District heating networks in Copenhagen and Stockholm specify scroll chillers with integrated heat recovery for simultaneous cooling and thermal output.
- Ventilation:Dedicated outdoor air systems with integrated dehumidification. Singapore commercial towers specify these to manage latent loads in tropical conditions without overcooling occupied spaces.
- Air Conditioning:Comfort cooling for commercial and institutional buildings. Standard efficiency tiers dominate, though EU Ecodesign regulations are compressing allowable energy consumption bands.
- Process Cooling:Temperature stability within ±0.5°C for semiconductor lithography and pharmaceutical fermentation. Basel pharmaceutical clusters and Hsinchu fabrication facilities specify electronic expansion valve control and redundant compressor staging.
Largest installed base: Air Conditioning. Premium margin concentration: Process Cooling.
Installation Type:
Customer type bifurcation separates owner-operated centralized plants from third-party-managed decentralized systems, with procurement authority residing in facilities engineering versus sustainability officers.
- Indoor:Mechanical room placement with acoustic enclosure requirements. Urban data centers in Tokyo and Frankfurt specify these to comply with municipal noise ordinances while maintaining service access.
- Outdoor:Rooftop or pad-mounted configurations eliminating building footprint allocation. US retail and logistics facilities favor these for speed of deployment and minimal structural modification.
- Centralized:Single plant serving multiple building systems or tenants. University campuses and hospital systems in Boston and Philadelphia specify these for operational simplicity and bulk refrigerant management.
- Decentralized:Dedicated units per building zone or tenant. Colocation operators in Northern Virginia specify these to unbundle cooling costs from lease structures and enable tenant-specific efficiency upgrades.
Highest volume: Centralized. Gaining share fastest: Decentralized.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium magnet processing concentrates in Chinese refining facilities, conditioning compressor motor supply chains and manufacturing footprints across major demand centers.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives specification of modular scroll systems for AI workload cooling. EPA SNAP regulations mandate refrigerant phase-down timelines that compress equipment redesign cycles. Ashburn colocation operators are unbundling equipment procurement from installation services, shifting purchasing authority toward direct OEM relationships.
China
Jiangsu and Zhejiang provinces are retrofitting industrial facilities with variable-speed scroll compressors under MIIT efficiency tier requirements. The country's dual carbon goals accelerate replacement cycles in eastern manufacturing corridors. Suzhou and Hangzhou facility managers specify water-cooled configurations to meet stringent performance thresholds with lower operating expenditure.
Germany
Automotive paint lines in Stuttgart and Munich specify scroll chillers with variable-speed drives to match cooling output against batch production cycles. EU F-Gas Regulation quotas compress refrigerant availability for service and new equipment. Basel pharmaceutical clusters across the Swiss border drive demand for temperature stability guarantees within tight tolerances.
Singapore
Tropical climate constraints and water scarcity prohibit evaporative cooling, favoring air-cooled scroll architectures in data center applications. The country's national environmental regulator enforces strict discharge restrictions that eliminate cooling tower infrastructure. Hyperscale operators commission 200-500 ton modular units for N+1 redundancy against thermal spikes from AI server racks.
India
PLI scheme incentives for semiconductor manufacturing attract fabrication investments in Gujarat and Tamil Nadu, creating greenfield specification opportunities. Central Electricity Authority efficiency guidelines shape industrial cooling procurement decisions. Ahmedabad and Chennai facility planners are evaluating scroll chiller platforms for process cooling in emerging fab complexes.
Scroll Chiller Market Competitive Landscape
Global majors compete with regional champions across certification regimes, technology platforms, and distribution architectures. The vendor base separates into consolidated multinational OEMs with full-stack building automation integration and specialized regional fabricators serving price-sensitive retrofit segments. Three strategic archetypes dominate: integrated HVAC conglomerates with captive compressor manufacturing, modular system specialists targeting data center redundancy requirements, and industrial process cooling engineers serving pharmaceutical and semiconductor fabs. Competitive moves concentrate on refrigerant platform transitions and predictive maintenance service bundling.
Within the integrated conglomerate tier, Johnson Controls and Daikin Industries occupy positions spanning commercial comfort and mission-critical process applications. Trane exemplifies the building automation integration archetype, while Carrier anchors North American distribution density through extensive contractor networks. Chinese manufacturers including Midea Group and Broad Air Conditioning represent scale-driven regional champions competing on modular system cost structures in domestic and select export markets.
| Leading Market Players |
|---|
| Johnson Controls |
| Daikin Industries |
| Trane |
| Carrier |
| Hitachi Appliances |
| Broad Air Conditioning |
| Thermax |
| Mitsubishi Electric |
| Midea Group |
| Others |
Value Network & Pricing Analysis
Captive compressor manufacturing in Chinese facilities anchors both supply security and pricing power for scroll chiller OEMs. Daikin Industries and Carrier leverage in-house production of orbiting scroll sets to buffer margin pressure from rare earth magnet volatility, while third-party assemblers absorb copper lamination cost swings through contract pass-through clauses.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium scroll chiller offerings from unbundled equipment transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier (EPA SNAP versus baseline efficiency) and customization depth. Pricing pressure stems from hyperscale data center operators consolidating procurement leverage in Northern Virginia and Singapore. Healthcare facilities exhibit lowest price sensitivity due to uptime guarantee requirements, while commercial retrofit segments in China's eastern provinces drive aggressive standard-tier negotiation.
Supply Chain Analysis
Freight cost differentials between ocean and air cargo conditioning compressor motor distribution favor regional assembly hubs over centralized manufacturing. Neodymium magnet processing concentrates in Chinese refining facilities, while copper tube extrusion feeds from Chilean and Indonesian smelters. Single-source vulnerability in rare earth magnet supply creates exposure to export quota shifts. Distribution runs through OEM-direct channels for hyperscale data center contracts and contractor networks for commercial comfort applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scroll chiller manufacturing is becoming a vertical-integration race, with captive compressor production and refrigerant management capabilities determining who captures margin in the transition to lower-GWP platforms.
For Market Incumbents: To counter magnetic bearing centrifugal displacement above 300 tons, anchor N+1 redundancy specifications in hyperscale data center contracts. Deepen backward integration into electronic expansion valve production to secure process cooling tier margins. Prioritize EPA Section 608 certification pipelines to accelerate A2L refrigerant commissioning capacity. For New Entrants and Emerging Players: The gap between premium process cooling tiers and economy comfort segments offers white-space entry around mid-tier modular systems for Indian semiconductor fabs. Target Gujarat and Tamil Nadu greenfield facilities before incumbent relationships solidify. Pursue heat-recovery integration as a specification differentiator against pure-play cooling vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to HVAC conglomerates seeking refrigerant platform coverage. Long-term viability hinges on refrigerant-as-a-service model adoption in EU markets. Watch EU F-Gas quota auction prices as the inflection signal for stranded equipment risk concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | EPA SNAP and EU F-Gas timelines compress R-32 and R-454B development cycles for market access retention. |
| Predictive Maintenance Integration | Sensor-embedded compressor architectures shift competitive differentiation toward uptime guarantees in data center applications. |
| Heat Recovery Convergence | Simultaneous cooling and hot water generation opens district heating and food processing specification channels. |
| Modular Capacity Scaling | Parallel compressor staging addresses hyperscale operator requirements for N+1 redundancy against AI thermal spikes. |
| Technician Certification Pipeline | EPA Section 608 and equivalent credentials for A2L refrigerants determine commissioning speed in North American markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this scroll chiller market analysis. Primary interviews with facilities engineering directors, data center sustainability officers, HVAC contractor principals, and compressor OEM procurement leads combined with AHRI certification databases, EPA SNAP submissions, China MIIT efficiency tier listings, and EU F-Gas quota registry extracts. Bottom-up equipment shipment tracking and top-down construction spend triangulation validated volume estimates.
Granularity-level modeling disaggregated the analysis window by product configuration (air-cooled, water-cooled, modular), end-use vertical (data center, healthcare, manufacturing, residential), and geographic regulatory cluster (US EPA SNAP, EU F-Gas, China MIIT). CAGRs derived from least-squares fitting of annual shipment trajectories against construction pipeline and retrofit mandate timelines. Refrigerant phase-down schedules and efficiency tier migrations served as scenario boundary conditions.
Inputs from AHRI certification registries and national customs authorities were available through the study window; gaps in real-time hyperscale data center procurement data introduce uncertainty bands around modular segment projections. Forecasts reflect assumptions about refrigerant transition pace and copper price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Commercial Griddles and Flat Top Grills Market
Food Service Equipment
Catering Equipment Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Kegerator Equipment Market