
 Restaurant Dish Delivery Equipment Market | 2026-2036
Restaurant Dish Delivery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant Dish Delivery Equipment Market Insights
Equipment leasing and subscription-based financing is narrowing the capital barrier for independent restaurants seeking commercial-grade delivery infrastructure. Middleby Corporation leverages its broad kitchen equipment ecosystem to bundle dish delivery systems with core cooking lines. Ali Group sustains competitive pressure through manufacturing scale across multiple European and North American facilities. Duke Manufacturing specializes in custom fabrication for high-volume catering operators with specific tray-size requirements.
Restaurant dish delivery equipment encompasses insulated transport vessels, heated carts, and modular carrier systems engineered to maintain food temperatures between 140°F and 165°F during transit from kitchen to end consumer. Stainless steel and aluminum chassis construction dominates commercial specifications due to durability and cleanability under repeated sanitization cycles. Among material segments, stainless steel anchors the premium tier where health inspectors enforce strict surface-grade standards, while plastic competes aggressively in cost-sensitive food truck deployments. Insulated bags represent the fastest-growing product type as third-party delivery platforms standardize lightweight, branded thermal packaging for gig-economy drivers.
The FDA Food Code and NSF International certification requirements shape product design decisions for any manufacturer targeting US foodservice operators, with specific mandates on surface materials and temperature retention testing. OSHA ergonomic guidelines influence cart and trolley specifications to reduce worker injury liability in high-turnover restaurant environments. Electrolux Professional navigates these overlapping compliance layers by pre-certifying equipment bundles for multi-jurisdiction operators. Stakeholders must monitor how municipal ghost kitchen regulations in cities like New York and Chicago rewrite facility requirements and, by extension, the specifications for delivery handoff equipment.
Market Dynamics
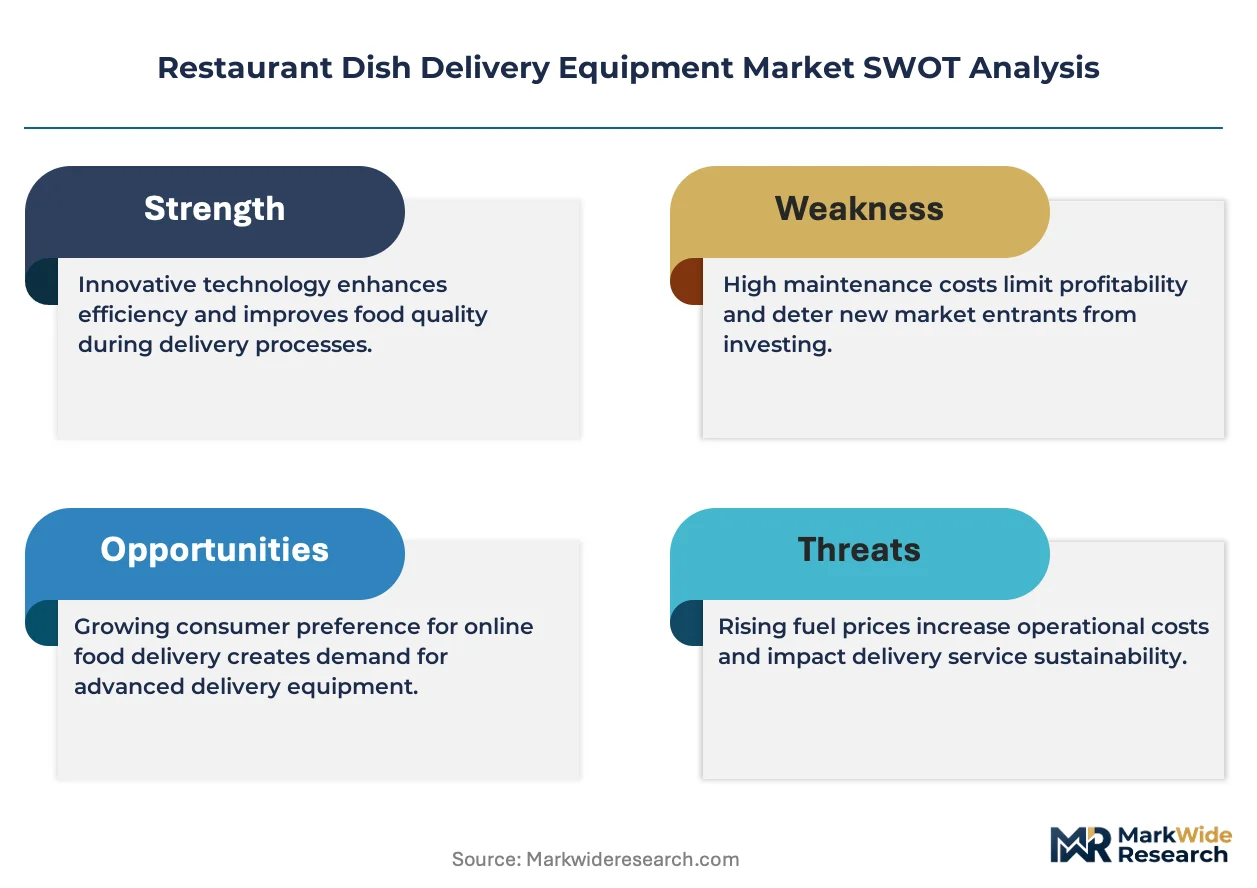
The FDA's updated Food Code hot-holding mandates are compressing product development cycles for insulated transport equipment, forcing manufacturers to integrate real-time temperature logging before NSF certification renewals.
Growth Catalysts
- Cloud kitchen proliferation:Ghost kitchen operators in the United States are scaling dedicated delivery infrastructure with heated cart fleets to maintain food safety temperatures across fragmented last-mile networks.
- NSF International certification:Surface material standards and temperature retention testing protocols are pulling commercial-grade stainless steel specifications into mid-market restaurant procurement decisions.
- Urban India demand concentration:Quick-service restaurant chains are building captive delivery infrastructure across Mumbai, Bangalore, and Delhi NCR, creating localized equipment procurement clusters.
Market Restraints
- Aluminum price volatility:Input cost swings for chassis-grade aluminum are compressing margins for manufacturers serving cost-sensitive food truck deployments.
- Supply concentration risk:Electrified heating element production clusters in East Asian component hubs expose cart assemblers to single-source vulnerability.
- Plastic substitution ceiling:Health inspector surface-grade enforcement in premium commercial segments caps downward migration to polymer-based insulated vessels.
Strategic Opportunities
- Subscription financing penetration:Equipment-as-a-service models are opening commercial-grade delivery infrastructure to independent restaurants previously blocked by capital constraints.
- Integrated IoT convergence:Bluetooth-enabled temperature loggers and GPS tracking modules are hybridizing into carrier systems for chain operators with multi-jurisdiction compliance obligations.
- Municipal ghost kitchen tailwinds:New York and Chicago facility regulations are rewriting delivery handoff specifications, creating upgrade cycles for existing cart inventories.
Industry Challenges
- Ergonomic compliance complexity:OSHA guidelines for cart and trolley specifications require redesign cycles to reduce worker injury liability in high-turnover restaurant environments.
- Multi-jurisdiction certification lag:Manufacturers targeting operators across state lines face staggered NSF, FDA Food Code, and local health department approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant Dish Delivery Equipment Market |
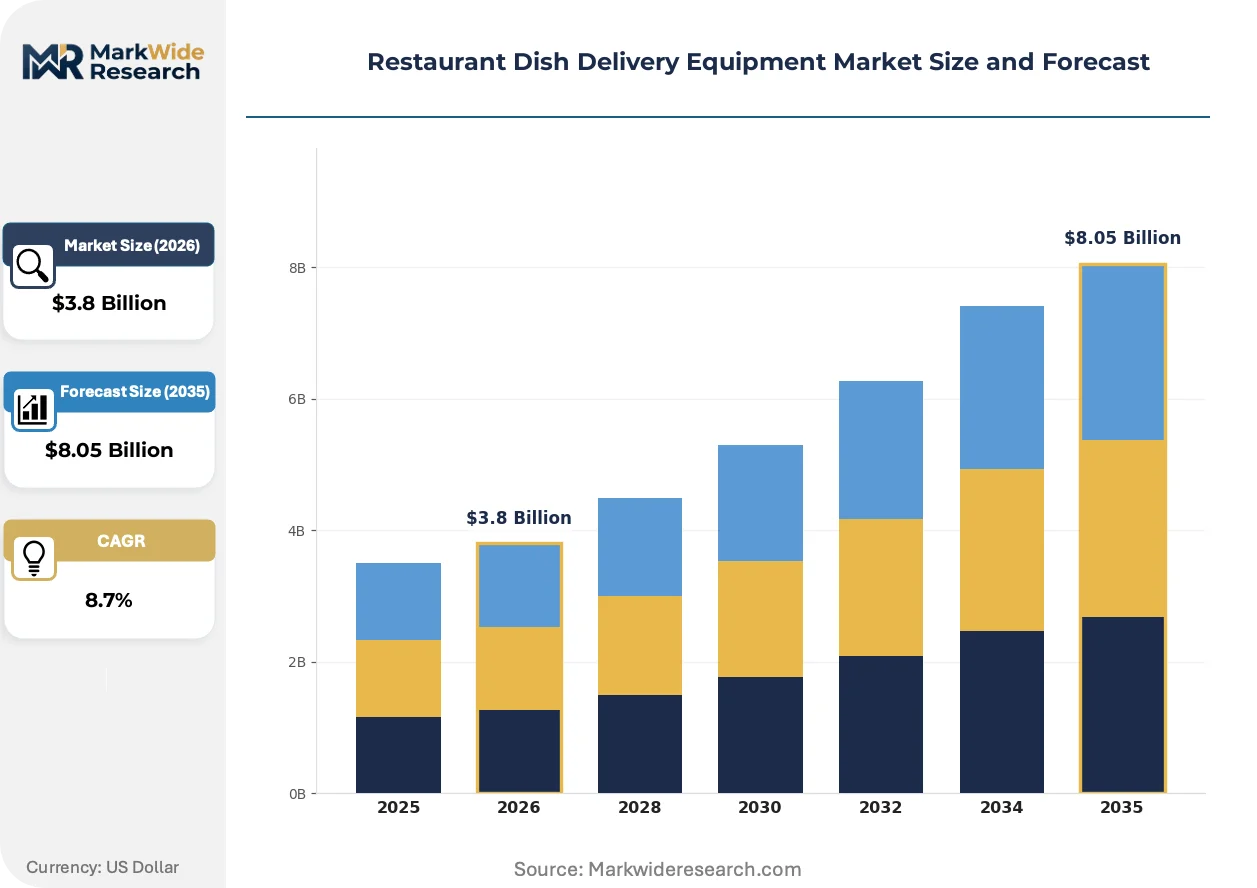
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Delivery Carts, Insulated Bags, Trolleys, Food Carriers Material: Plastic, Aluminum, Stainless Steel, Fiberglass End User: Restaurants, Catering Services, Food Trucks, Cafés Application: Party Deliveries, On-Demand Orders, Corporate Events, Takeout Services |
| Companies Covered | Middleby Corporation, Ali Group, Welbilt, ITW Food Equipment Group, Hoshizaki Corporation, Electrolux Professional, Duke Manufacturing, Rational AG, MEIKO Maschinenbau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant Dish Delivery Equipment Market Trends and Innovations
Active thermal management systems are displacing passive insulation as the baseline specification for commercial delivery equipment, with sensor integration becoming a procurement prerequisite rather than a premium add-on.
Phase-change material inserts are hybridizing with traditional insulated bag construction to extend temperature retention windows without adding electrical weight. Third-party delivery platforms operating gig-economy driver networks are specifying these hybrid vessels for branded thermal packaging standardization. The technology is compressing the performance gap between lightweight consumer-grade bags and powered heated carts.
REACH substance restrictions in the European Union are limiting certain polymer formulations used in food-contact surfaces, redirecting R&D toward compliant alternative resins. Manufacturers with European distribution are accelerating material qualification cycles ahead of enforcement deadlines. The regulation is most affecting insulated bag producers serving cross-border quick-service restaurant chains with unified pan-European specifications.
Chain operators are consolidating vendor relationships around pre-certified equipment bundles that satisfy overlapping FDA Food Code, NSF International, and municipal health department requirements. Electrolux Professional and similar multi-jurisdiction suppliers are capturing this preference shift through bundled certification offerings. The United States exhibits the clearest concentration of this procurement pattern among national restaurant groups with standardized kitchen footprints.
Restaurant Dish Delivery Equipment Market Segmentation
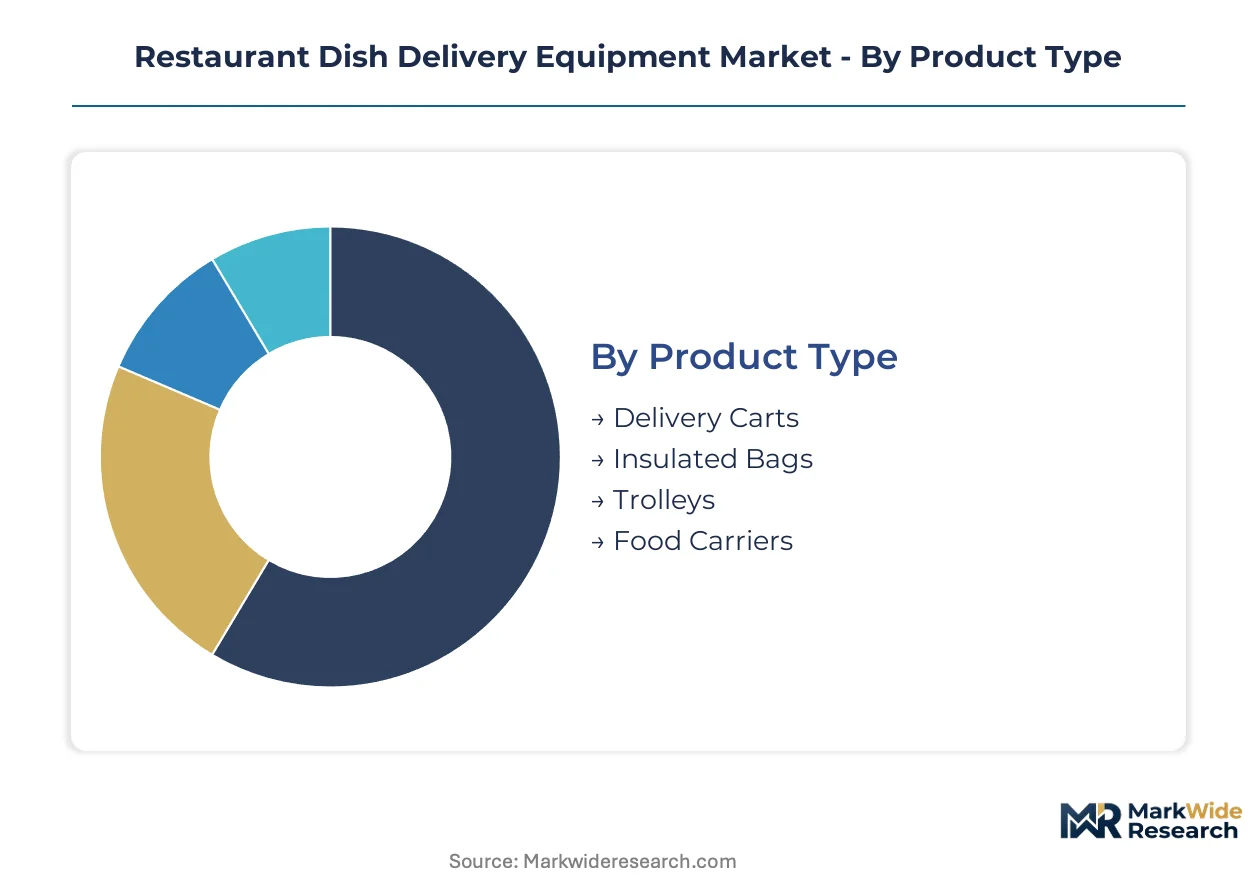
Segmentation in restaurant dish delivery equipment reveals how procurement decisions split across operational scale, regulatory exposure, and last-mile logistics complexity. Equipment specifications diverge sharply between cloud kitchen operators managing high-volume thermal compliance and independent cafés prioritizing capital efficiency.
Product Type:
Mature categories dominate commercial procurement while emerging formats reshape gig-economy logistics.
- Delivery Carts:Electrified chassis with integrated heating elements maintain 140°F to 165°F holding temperatures across fragmented last-mile networks. Cloud kitchen operators in the United States are scaling dedicated cart fleets to satisfy FDA Food Code hot-holding mandates during extended delivery windows.
- Insulated Bags:Lightweight thermal vessels constructed with phase-change material inserts extend temperature retention without electrical weight. Third-party delivery platforms in urban India are standardizing these for branded gig-driver packaging across Mumbai, Bangalore, and Delhi NCR.
- Trolleys:OSHA-compliant ergonomic frames reduce worker injury liability in high-turnover restaurant environments. NSF International surface-grade specifications apply to food-contact zones.
- Food Carriers:Modular tray systems accommodate variable dish dimensions for catering operators with custom fabrication requirements.
Delivery carts retain volume leadership; insulated bags hold the steepest expansion curve.
Material:
Cost tier stratification aligns material selection with health inspector enforcement intensity and sanitization frequency.
- Stainless Steel:Grade 304 or 316 alloys dominate premium commercial specifications where health inspectors enforce strict surface-grade standards under NSF International protocols. FDA Food Code updates on cleanability are pulling stainless specifications into mid-market restaurant procurement decisions.
- Aluminum:Chassis-grade alloys balance durability with weight reduction for food truck deployments. Input cost volatility from East Asian smelter concentration compresses margins for manufacturers serving cost-sensitive operators.
- Plastic:Polymer formulations compete aggressively in food truck and independent café segments. REACH substance restrictions in the European Union redirect R&D toward compliant alternative resins for cross-border quick-service chains.
- Fiberglass:Composite construction offers intermediate thermal performance for catering operators with moderate sanitization cycles.
Stainless steel commands premium positioning; aluminum faces margin pressure from supply concentration.
End User:
Application-driven specifications separate enterprise-grade compliance investments from capital-constrained independent operations.
- Restaurants:Full-service and quick-service chains deploy integrated IoT-enabled carrier systems with Bluetooth temperature loggers for multi-jurisdiction compliance. Subscription financing models are opening commercial-grade infrastructure to independent operators previously blocked by capital constraints.
- Catering Services:High-volume operators with specific tray-size requirements drive custom fabrication demand. Duke Manufacturing captures this segment through specialized production lines.
- Food Trucks:Mobile operators prioritize lightweight plastic and aluminum construction for fuel efficiency and maneuverability.
- Cafés:Limited-service formats concentrate procurement in entry-tier insulated bags with minimal heating elements.
Restaurants anchor equipment value; catering services generate the most complex specification requirements.
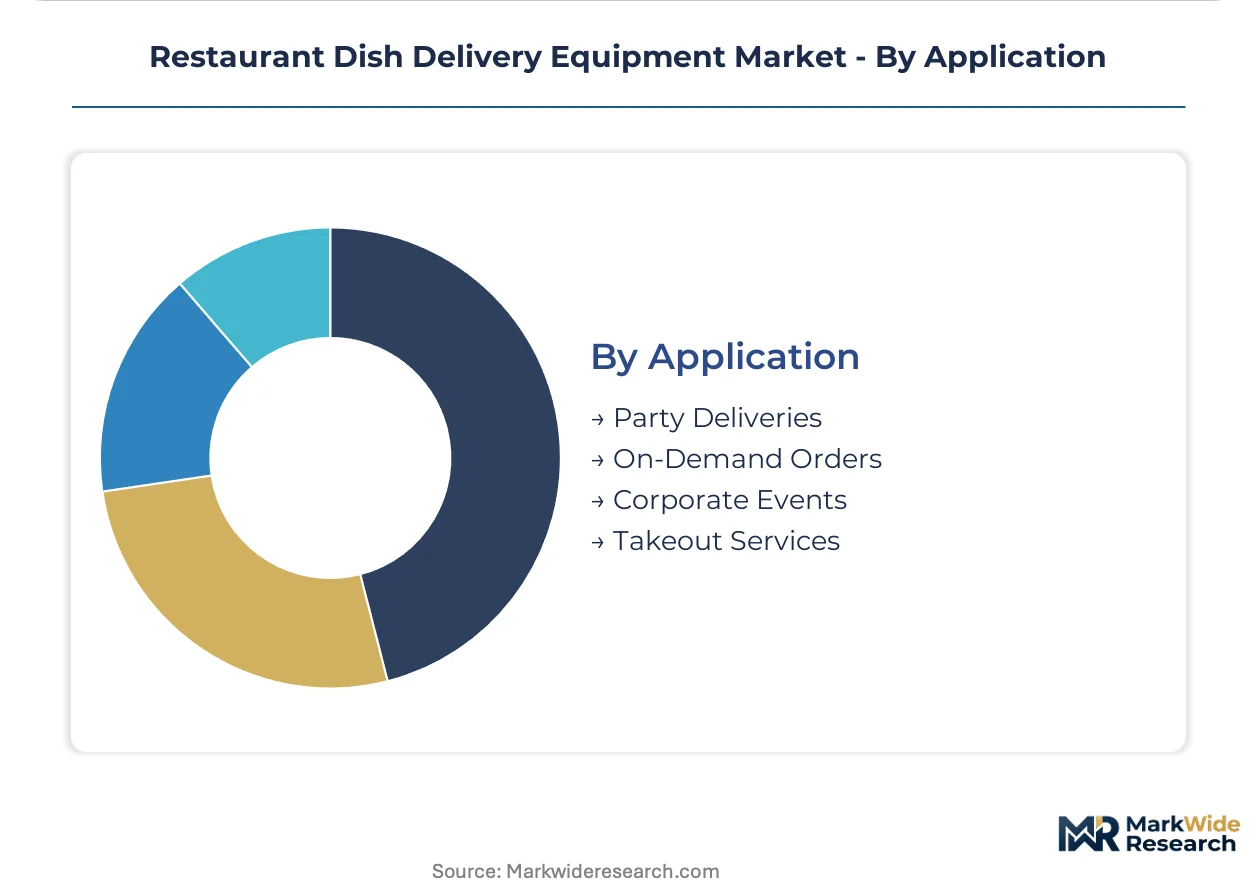
Application:
Volume concentration and delivery urgency shape thermal performance specifications across use cases.
- On-Demand Orders:Third-party platform standardization demands lightweight, branded thermal packaging with GPS tracking modules. Real-time temperature logging is becoming a procurement prerequisite rather than a premium add-on.
- Corporate Events:Scheduled bulk deliveries accommodate heavier electrified carts with extended battery capacity. Municipal ghost kitchen regulations in New York and Chicago are rewriting handoff specifications for this segment.
- Party Deliveries:Variable dish counts and transport distances drive modular carrier system adoption.
- Takeout Services:Customer-facing pickup operations prioritize compact footprint and rapid sanitization turnaround.
On-demand orders are expanding most quickly; corporate events sustain the highest average transaction values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Food Code updates on hot-holding requirements are accelerating equipment replacement cycles across multiple jurisdictions. Cloud kitchen regulations in major metropolitan areas are rewriting delivery handoff specifications and procurement priorities.
United States
Ghost kitchen operators in New York and Chicago are scaling heated cart fleets to satisfy municipal facility regulations and FDA hot-holding mandates. NSF International certification requirements pull commercial-grade stainless steel specifications into mid-market restaurant procurement decisions. Cloud kitchen clusters in Los Angeles and Dallas-Fort Worth are driving concentrated demand for integrated IoT-enabled carrier systems.
Germany
REACH substance restrictions on polymer formulations are redirecting R&D toward compliant alternative resins for insulated bag producers. ECHA enforcement timelines are accelerating material qualification cycles ahead of deadline pressure. Industrial equipment manufacturers in Baden-Württemberg and North Rhine-Westphalia are capturing pan-European quick-service chain procurement with pre-certified bundled offerings.
India
Quick-service restaurant chains are building captive delivery infrastructure across Mumbai, Bangalore, and Delhi NCR, creating localized equipment procurement clusters. FSSAI food safety standards are tightening surface material requirements for commercial-grade transport vessels. Cloud kitchen operators in Hyderabad and Pune are expanding electrified cart deployments to maintain temperature compliance across fragmented last-mile networks.
China
GB standards for food-contact materials are influencing insulated vessel design specifications for domestic and export markets. SAMR enforcement of food safety protocols is elevating certification requirements for commercial kitchen equipment manufacturers. Manufacturing clusters in Guangdong and Zhejiang provinces are scaling production of heating elements and thermal management components for regional cart assemblers.
United Kingdom
Food Standards Agency hygiene regulations are shaping procurement decisions for catering operators with high-volume event delivery requirements. CE marking alignment post-Brexit is creating dual-certification complexity for equipment suppliers serving both UK and EU markets. London-based cloud kitchen operators are driving demand for compact, ergonomic trolley systems suited to dense urban logistics constraints.
Restaurant Dish Delivery Equipment Market Competitive Landscape
On the supply side, the industry is moderately consolidated around diversified kitchen equipment conglomerates with cross-selling capabilities. Tiered competitive dynamics separate premium stainless steel specialists from cost-optimized aluminum and polymer fabricators. Three archetypes dominate: integrated equipment bundlers leveraging broad kitchen portfolios, scale-driven manufacturers with multi-continental production footprints, and custom fabrication specialists serving high-volume catering operators with specific tray-size requirements. Dominant competitive moves include strategic bundling of delivery systems with core cooking lines and pre-certification of equipment packages for multi-jurisdiction operators.
Within the integrated bundler tier, Middleby Corporation and Ali Group exemplify scale-driven competitive positioning through manufacturing breadth across multiple facilities. Electrolux Professional occupies a distinct position through bundled certification offerings targeting national restaurant groups with standardized kitchen footprints. Duke Manufacturing anchors the custom fabrication specialist archetype, serving high-volume catering operators with specific dimensional requirements.
| Leading Market Players |
|---|
| Middleby Corporation |
| Ali Group |
| Welbilt |
| ITW Food Equipment Group |
| Hoshizaki Corporation |
| Electrolux Professional |
| Duke Manufacturing |
| Rational AG |
| MEIKO Maschinenbau |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian heating element production clusters is compressing supplier margins and forcing tiered pricing discipline across electrified cart assemblers. Utilization rates below nameplate capacity in Guangdong and Zhejiang provinces are accelerating price competition for chassis-grade components while insulating premium stainless steel fabricators from equivalent pressure.
Pricing Analysis
Certification level creates the primary spread across commercial-grade delivery equipment, with NSF International and FDA Food Code pre-certification commanding substantial premia over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects material grade stratification: Grade 316 stainless steel anchors the top tier, aluminum chassis occupy the mid-market, and polymer-based vessels compete on entry pricing. Cost compression in aluminum tiers is intensifying because of smelter concentration in East Asian supply basins. Independent restaurants and food truck operators exhibit the highest price sensitivity, while national quick-service chains prioritize compliance-grade specifications over unit economics.
Supply Chain Analysis
Chassis-grade aluminum feedstock draws from smelter concentration in China, Russia, and Canada, with secondary refining capacity distributed across European and North American fabricators. Heating element production rests on rare earth processing in China, nickel alloy supply from Indonesia and the Philippines, and ceramic substrate manufacturing in Japan and Germany. Single-source vulnerability in East Asian component hubs exposes cart assemblers to disruption from trade policy shifts or logistics chokepoints. Distribution runs through commercial kitchen equipment dealers, direct OEM sales forces to national accounts, and emerging equipment-as-a-service platforms targeting capital-constrained independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The restaurant dish delivery equipment market is undergoing high-growth disruption from active thermal management convergence, where sensor integration and real-time temperature logging are shifting from premium add-ons to baseline procurement requirements. FDA Food Code updates on hot-holding mandates are compressing product development cycles and creating upgrade windows across installed base inventories.
For Market Incumbents: Entrench certification leadership through accelerated NSF International renewal cycles and bundled multi-jurisdiction pre-approval offerings. Deepen backward integration into heating element production to offset East Asian supply concentration risk. Defend against emerging IoT-native entrants by capturing cloud kitchen operator relationships before municipal facility regulations in New York and Chicago solidify vendor preferences.
For New Entrants and Emerging Players: Pursue white-space opportunity in subscription-financed insulated bag deployments for third-party delivery platforms standardizing gig-driver thermal packaging. Target urban India procurement clusters in Mumbai, Bangalore, and Delhi NCR where quick-service restaurant chains are building captive delivery infrastructure with limited incumbent penetration. Lead with phase-change material hybrid technology to compress the performance gap against powered heated carts at lower capital intensity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across equipment-as-a-service sub-segments as financing platforms absorb depreciation risk. Long-term viability favors suppliers with certification moats and recurring revenue exposure over transactional hardware vendors. Acquisition target archetype: mid-scale custom fabricators with catering operator relationships and capacity for stainless steel specification expansion. Signal to monitor: municipal ghost kitchen ordinance adoption velocity in major metropolitan jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Integration | Bluetooth-enabled temperature loggers satisfy FDA Food Code mandates for chain operators. |
| Equipment-as-a-Service Launch | Subscription financing opens commercial-grade infrastructure to capital-constrained independents. |
| Multi-Jurisdiction Pre-Certification | Bundled NSF and FDA approvals capture national restaurant group procurement consolidation. |
| Phase-Change Material R&D | Hybrid insulated bags extend retention windows without electrified weight penalties. |
| East Asian Supply Diversification | Alternative heating element sourcing mitigates single-source vulnerability in component hubs. |
Research Methodology
The analysis maps heated delivery carts, insulated bags, trolleys, and modular carrier systems, each validated through equipment procurement directors at national restaurant groups, cloud kitchen facility operators, third-party delivery platform logistics heads, and commercial kitchen equipment dealers. Primary interviews with NSF International certification specialists and FDA Food Code compliance officers were cross-referenced against secondary sources including FDA regulatory filings, NSF certification databases, customs trade records for aluminum and stainless steel inputs, and municipal ghost kitchen ordinance documents. Bottom-up equipment unit demand estimates were triangulated against top-down foodservice industry expenditure patterns.
Forecast assumptions held cloud kitchen proliferation rates and FDA enforcement intensity as primary demand drivers while varying aluminum price volatility and REACH regulatory timelines as scenario modifiers. Segmentation dimensions modeled include product type, material grade, end-user scale, and application urgency across the projection horizon. CAGRs were derived from equipment replacement cycle analysis, new facility buildout pipelines, and technology substitution curves for passive versus active thermal management. Industry-specific inputs incorporated FSSAI enforcement patterns in India, municipal ordinance adoption velocity in United States metropolitan areas, and pan-European quick-service chain standardization timelines.
Macroeconomic conditions sit as an overlay; deviation in foodservice labor availability, commercial real estate costs for ghost kitchen facilities, or consumer delivery demand elasticity would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement continuity and supply chain normalization that may require revision. Cross-checking against foodservice equipment industry association shipment data and restaurant chain capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Countertop Ice Dispensers Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Coffee Equipment and Supplies Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Culinary Torch Market