
 Meal Replacement Products OEM Market | 2026-2036
Meal Replacement Products OEM Market Size, Share, and Industry Trends Forecast 2026-2036
Meal Replacement Products OEM Market Insights
North American contract manufacturers is broadening powder and ready-to-drink capacity to serve surging private-label demand. Abbott Laboratories leverages its clinical nutrition heritage to anchor hospital and retail channel supply. Nestlé S.A. sustains global formulation scale across dairy-based and plant-based portfolios. Glanbia PLC specializes in sports nutrition OEM, competing on grass-fed whey and clean-label ingredient sourcing.
Meal Replacement Products OEM refers to third-party manufacturing of nutritionally complete formulations designed to substitute conventional meals, typically containing 15-30 grams of protein, vitamin-mineral premixes, and controlled macronutrient ratios produced via spray-drying, extrusion, or aseptic liquid processing for fitness, weight management, and convenience applications. Ready-to-drink liquid formats command premium OEM pricing due to aseptic filling complexity and shorter shelf-life logistics, while powder segments dominate volume through lower per-unit production costs and flexible co-packing arrangements. Plant-based ingredient sourcing is the fastest-growing segment as brands reformulate to capture flexitarian consumers, though dairy-based formulations retain margin strength in performance-oriented channels.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements under 21 CFR Part 111, mandating identity testing and contaminant controls that elevate compliance costs for smaller OEMs. EFSA novel food assessments in Europe delay plant-protein ingredient approvals, shaping reformulation timelines for exporters. ISO 22000 and FSSC 22000 certifications increasingly function as table stakes for multinational brand-owner procurement. Stakeholders must monitor evolving protein quality scoring methodologies and front-of-pack labeling mandates as these standards will determine which OEMs retain preferred-supplier status.
Market Dynamics
Direct-to-consumer subscription models are compressing traditional wholesale channels and forcing contract manufacturers to reconfigure production scheduling around smaller, more frequent batch runs with accelerated formulation turnaround.
Growth Catalysts
- Fitness Enthusiast Demand:Personalized nutrition protocols are pulling OEM volume toward high-protein, low-carbohydrate formulations with custom micronutrient stacks for CrossFit and endurance athletes.
- 21 CFR Part 111 Compliance:FDA-mandated identity testing and contaminant controls are filtering out subscale manufacturers and consolidating preferred-supplier relationships with certified contract producers.
- Aseptic Liquid Processing:Advances in shelf-stable filling technology are unlocking ready-to-drink distribution through gym networks and convenience retail previously blocked by refrigeration requirements.
Market Restraints
- Whey Protein Concentrate Volatility:Dairy commodity price swings compress margin predictability for powder-focused OEMs locked into annual supply agreements with New Zealand and European cooperatives.
- EFSA Novel Food Assessments:European novel protein ingredient approvals face 18-24 month evaluation timelines, delaying plant-based reformulation launches for exporters targeting EU markets.
- Refrigerated Logistics:Cold-chain requirements for fresh-format meal replacements limit distribution radius and exclude rural and exurban addressable markets from same-day delivery coverage.
Strategic Opportunities
- Germany Functional Food Channel:Pharmacy and drugstore distribution remains underpenetrated for sports nutrition OEMs, creating first-mover positioning ahead of domestic brand saturation.
- AI-Driven Flavor Matching:Machine learning platforms analyzing consumer preference data are enabling rapid prototype iteration and reducing formulation-to-market cycles from months to weeks.
- India FSSAI Harmonization:Streamlined food safety and standards authority protocols for dietary supplements are lowering import barriers for contract manufacturers establishing local co-packing partnerships.
Industry Challenges
- FSSC 22000 Certification Backlogs:Audit capacity constraints at accredited bodies are extending certification timelines and delaying preferred-supplier qualification for multinational procurement.
- Legacy ERP Integration:Batch record digitization and electronic quality management system deployment face resistance from plant-floor operators and require parallel manual documentation during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meal Replacement Products OEM Market |
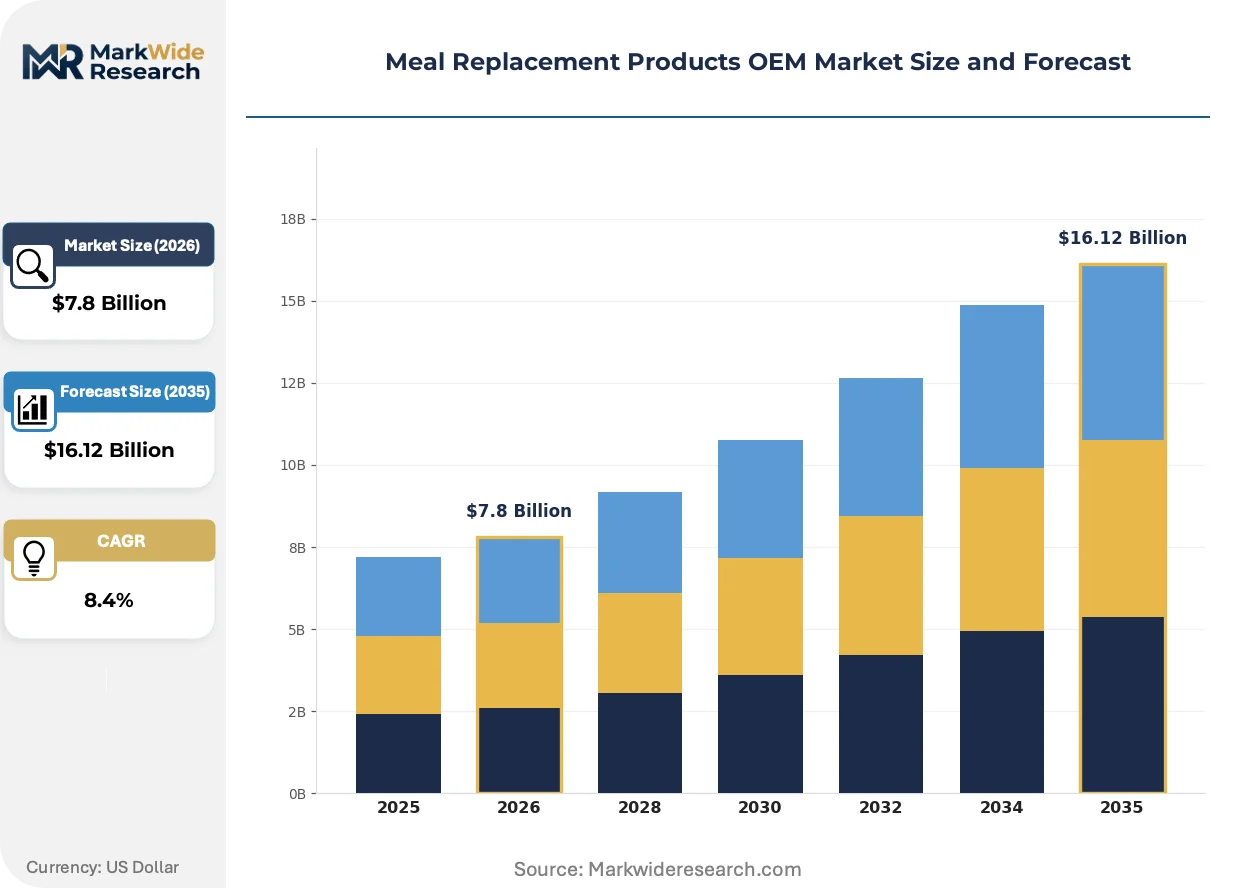
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Bar, Ready-to-Drink, Liquid End User: Fitness Enthusiasts, Weight Loss Programs, Busy Professionals, Athletes Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms Ingredient Source: Plant-Based, Dairy-Based, Synthetic, Natural |
| Companies Covered | Abbott Laboratories, Nestlé S.A., Herbalife Nutrition Ltd., Glanbia PLC, General Mills Inc., Kellogg Company, Star Combo Pharma, Sirio Pharma, NCS Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meal Replacement Products OEM Market Trends and Innovations
Formulation science and production automation are converging to collapse development cycles and enable mass customization at previously impossible scale economics.
High-throughput screening platforms for protein-flavor interactions are automating sensory optimization that previously required months of panel testing. Mid-tier OEMs in the United States and Netherlands are deploying these systems to compete with incumbent scale advantages. The technology is automating formulation decisions previously reserved for senior food scientists.
EFSA's evolving novel food guidance on precision-fermented proteins is forcing European contract manufacturers to maintain parallel development tracks for approved and pending ingredient categories. Brands targeting EU distribution are front-loading toxicology studies to preempt regulatory delays. Plant-based ready-to-drink lines face the most acute compliance timeline pressure.
Direct brand relationships are displacing traditional broker-mediated procurement as fitness influencers and celebrity athletes launch private-label lines with minimum viable order quantities. Gym chains and boutique studios in California and Texas are becoming launch channels for these micro-brands. This channel compression is most visible in performance-oriented powder segments where formulation differentiation commands premium positioning.
Meal Replacement Products OEM Market Segmentation
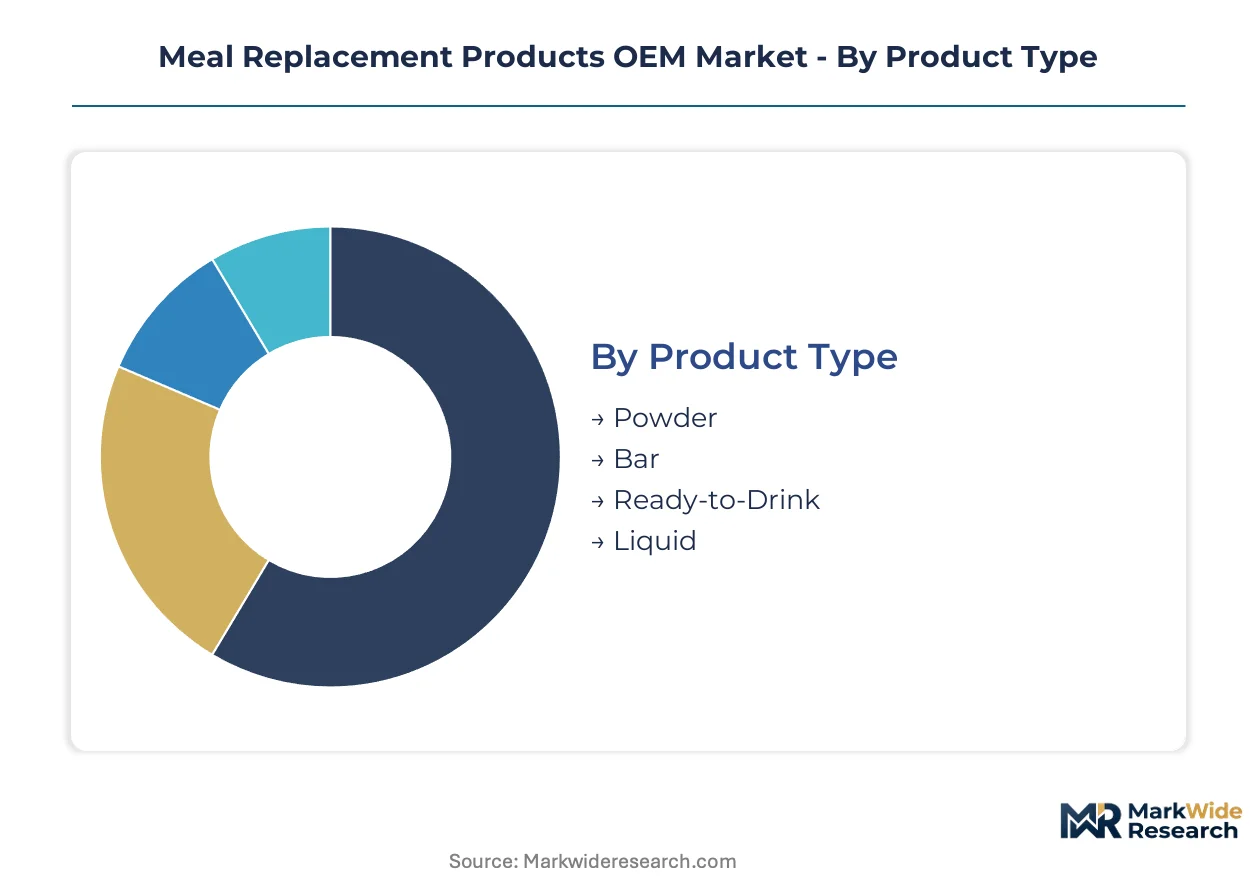
Meal replacement OEM contracts diverge sharply by production complexity and regulatory burden. Powder formulations attract high-volume private-label brands seeking flexible co-packing economics. Ready-to-drink formats command premium slotting fees due to aseptic processing requirements and cold-chain logistics.
Product Type:
Powder and ready-to-drink segments separate buyers by capital intensity and shelf-life engineering requirements.
- Powder:Spray-dried or agglomerated formulations with 12-24 month stability enable economical bulk packaging and flexible flavor rotation. Demand concentrates in direct-to-consumer subscription brands operating from Nevada and Utah fulfillment centers, driven by lower per-unit shipping weights versus liquid alternatives.
- Ready-to-Drink:Aseptic UHT processing and multilayer barrier packaging deliver 9-12 month ambient stability for gym channel distribution. Growth tilts toward Texas and Florida boutique fitness chains seeking grab-and-go placement without refrigeration infrastructure.
- Bar:Extruded or cold-pressed formats with protein binding and moisture control specifications. Energy bar specialists in California dominate contract volumes.
- Liquid:Refrigerated fresh formats with 14-30 day shelf life requiring HPP or thermal processing. Cold-chain constraints limit addressable radius for same-day delivery models.
Volume sits with powder; growth tilts toward ready-to-drink.
End User:
Application-specific macronutrient ratios and micronutrient fortification levels determine formulation complexity and batch minimums.
- Fitness Enthusiasts:High-protein, low-carbohydrate profiles with branched-chain amino acid premixes and creatine monohydrate options. CrossFit and HYROX training communities in Arizona and Colorado drive custom stack demand.
- Weight Loss Programs:Calorie-controlled formulations with soluble fiber and satiety-enhancing ingredients. Medical weight management clinics in Minnesota and Wisconsin anchor institutional procurement.
- Busy Professionals:Balanced macronutrient ratios emphasizing convenience and neutral flavor masking. Urban same-day delivery corridors in New York and Illinois concentrate demand.
- Athletes:NSF Certified for Sport or Informed Sport third-party testing requirements with banned substance screening. Collegiate athletic programs in Texas and California mandate batch-level documentation.
Volume sits with fitness enthusiasts; expansion tilts toward weight loss programs.
Distribution Channel:
Channel selection dictates packaging format, case configuration, and retailer-specific compliance documentation.
- Online Retail:Direct-to-consumer fulfillment with shipper-ready case packs and subscription portal integration. Amazon and Shopify-native brands in Washington and Massachusetts drive automated reorder algorithms.
- Supermarkets:Mass-market positioning with front-of-pack labeling compliance and quarterly promotional calendars. Kroger and Albertsons category managers in Ohio and Idaho set formulation specifications.
- Health Stores:Premium positioning with non-GMO Project verification and clean-label ingredient decks. Whole Foods Market and Sprouts regional buyers in Colorado and Arizona require supplier diversity documentation.
- Gyms:Point-of-sale placement with single-serve packaging and commission-based revenue share. Equinox and Life Time Fitness procurement teams in Texas and Florida negotiate exclusive flavor development.
Volume sits with online retail; expansion tilts toward gyms.
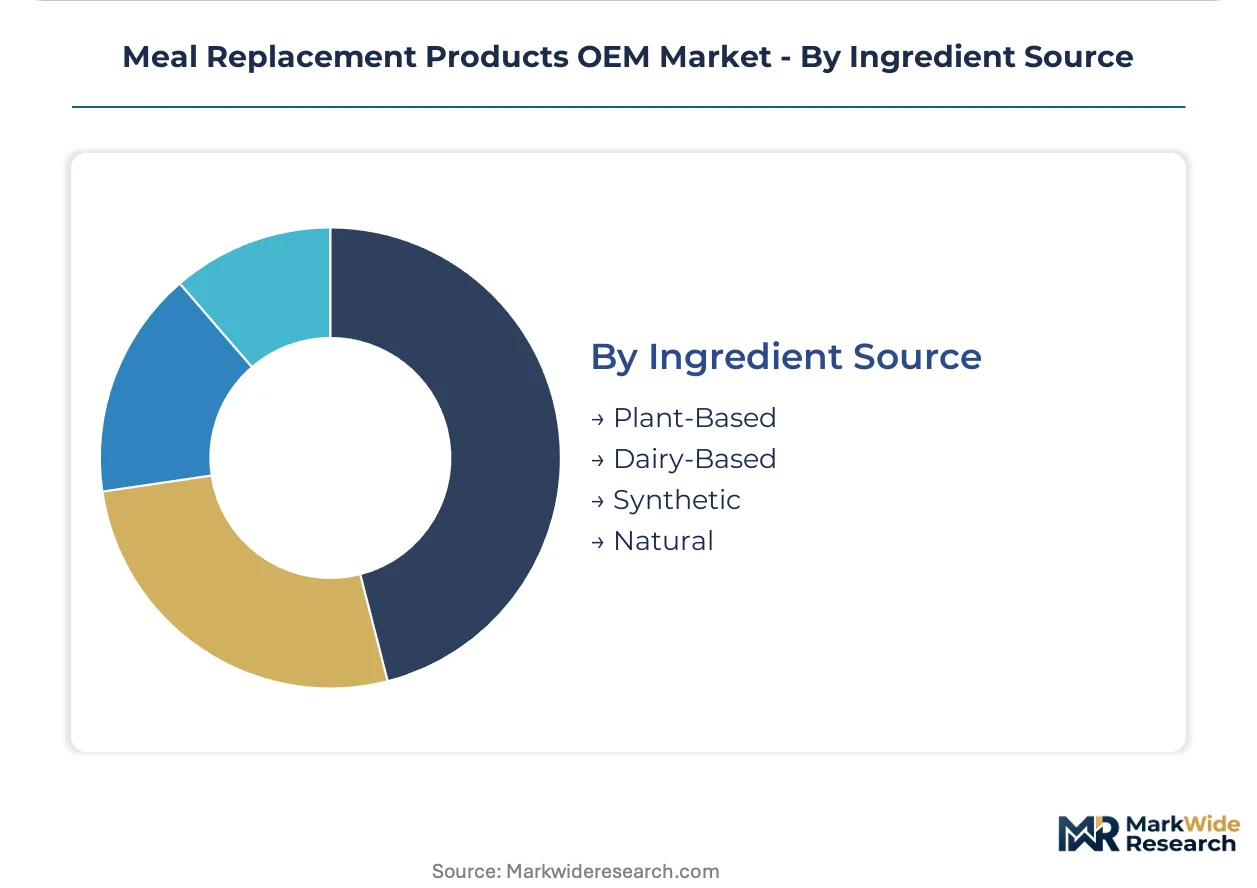
Ingredient Source:
Raw material provenance determines allergen management protocols, sustainability certification requirements, and margin structure.
- Plant-Based:Pea, rice, pumpkin seed, and fava bean protein blends with complementary amino acid profiling. Flexitarian consumers in Oregon and Vermont accelerate reformulation timelines as FDA GRAS notifications accumulate for novel protein isolates.
- Dairy-Based:Whey protein concentrates and isolates from grass-fed New Zealand and European cooperative supply pools. Performance-oriented channels in Utah and Idaho retain margin strength despite commodity price volatility.
- Synthetic:Vitamin-mineral premixes and engineered macronutrient substrates with precise bioavailability specifications. Clinical nutrition applications in Minnesota and Massachusetts require pharmaceutical-grade documentation.
- Natural:Whole-food ingredient decks with minimal processing claims and recognizable source labeling. Premium positioning in California and Colorado natural products channels commands 40-60% formulation cost premiums.
Volume sits with dairy-based; expansion tilts toward plant-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand grass-fed dairy cooperatives anchor protein concentrate supply for North American and European contract manufacturers, while Chinese pea protein isolates and Indian rice protein extraction capacity reshape plant-based sourcing maps.
United States
Direct-to-consumer subscription brands and boutique fitness chains in Texas and Florida drive ready-to-drink OEM volume. FDA 21 CFR Part 111 compliance mandates filter subscale manufacturers from preferred-supplier lists. Utah and Idaho host spray-drying clusters serving private-label powder brands with accelerated formulation turnaround.
Germany
Pharmacy and drugstore channels remain underpenetrated for sports nutrition OEMs seeking first-mover positioning. EFSA novel food assessments delay precision-fermented protein launches by 18-24 months. Bavaria-based contract manufacturers maintain parallel development tracks for approved and pending ingredient categories.
China
Pea and rice protein extraction capacity expansion targets flexitarian export demand from European and North American brand owners. SAMR dietary supplement registration requirements elevate documentation burdens for foreign OEM partnerships. Yangtze River Delta processing clusters specialize in high-throughput agglomeration for bulk powder export.
India
FSSAI harmonization for dietary supplements lowers import barriers for contract manufacturers establishing local co-packing partnerships. Maharashtra and Gujarat host emerging spray-drying capacity serving domestic weight management clinics. Telangana-based ingredient suppliers accumulate FDA GRAS notifications for novel protein isolates.
Australia
Grass-fed whey protein concentrate from Victorian and New South Wales dairy cooperatives commands premium positioning in performance-oriented channels. TGA therapeutic goods manufacturing standards shape export documentation for clinical nutrition applications. Sydney and Melbourne contract manufacturers specialize in NSF Certified for Sport third-party testing protocols.
Meal Replacement Products OEM Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-driven flavor matching and precision-fermented protein platforms. The vendor base stratifies across multinational nutrition conglomerates, mid-tier sports nutrition specialists, and regional co-packing operators. Three archetypes dominate: clinical heritage players leveraging hospital channel relationships, clean-label sourcing specialists competing on grass-fed whey provenance, and plant-based reformulation engines capturing flexitarian demand. Competitive moves concentrate on aseptic liquid processing capacity expansion and FSSC 22000 certification acquisition to secure multinational procurement slots.
Within the clinical nutrition tier, Abbott Laboratories and Nestlé S.A. occupy positions anchored by pharmaceutical-grade manufacturing heritage and institutional channel penetration. Glanbia PLC exemplifies the sports nutrition specialist archetype, competing on grass-fed whey sourcing and clean-label ingredient decks. These three entities represent contrasting scale vectors: multinational conglomerate breadth, dairy cooperative verticality, and performance-channel focus respectively.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé S.A. |
| Herbalife Nutrition Ltd. |
| Glanbia PLC |
| General Mills Inc. |
| Kellogg Company |
| Star Combo Pharma |
| Sirio Pharma |
| NCS Science |
| Others |
Pricing and Supply Chain Analysis
Whey protein concentrate futures from New Zealand dairy cooperatives cascade through contract manufacturing tiers, compressing margin buffers for powder-focused OEMs while amplifying pricing power for aseptic liquid processors with locked-in annual offtake agreements. FDA 21 CFR Part 111 compliance costs filter subscale competitors from preferred-supplier lists, consolidating procurement leverage among certified contract manufacturers with established quality management systems.
Pricing Analysis
Service bundling separates full-service formulation partners from toll-manufacturing operators, with the former commanding slotting premiums for accelerated turnaround and regulatory documentation support. Three-tier pricing structure across premium, standard, and economy levels reflects FSSC 22000 certification status, grass-fed whey provenance, and minimum order volume thresholds. Cost compression in standard-tier powder contracts is intensifying because Chinese pea protein isolates are undercutting European dairy cooperative pricing. Private-label subscription brands exhibit highest price sensitivity, while hospital and clinical nutrition channels absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Regional distribution centers in Nevada, Utah, and Texas orchestrate hub-and-spoke fulfillment patterns for direct-to-consumer subscription brands, with same-day delivery corridors radiating from Dallas-Fort Worth and Salt Lake City metro clusters. Raw material sourcing draws from New Zealand grass-fed dairy cooperatives, Chinese pea protein extraction facilities, and Indian rice protein processors. Single-source vulnerability concentrates in aseptic UHT filling equipment, where European and Japanese machinery suppliers command 18-24 month lead times. Distribution runs through gym network consignment, Amazon FBA, and pharmacy channel direct-to-warehouse drop-shipping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
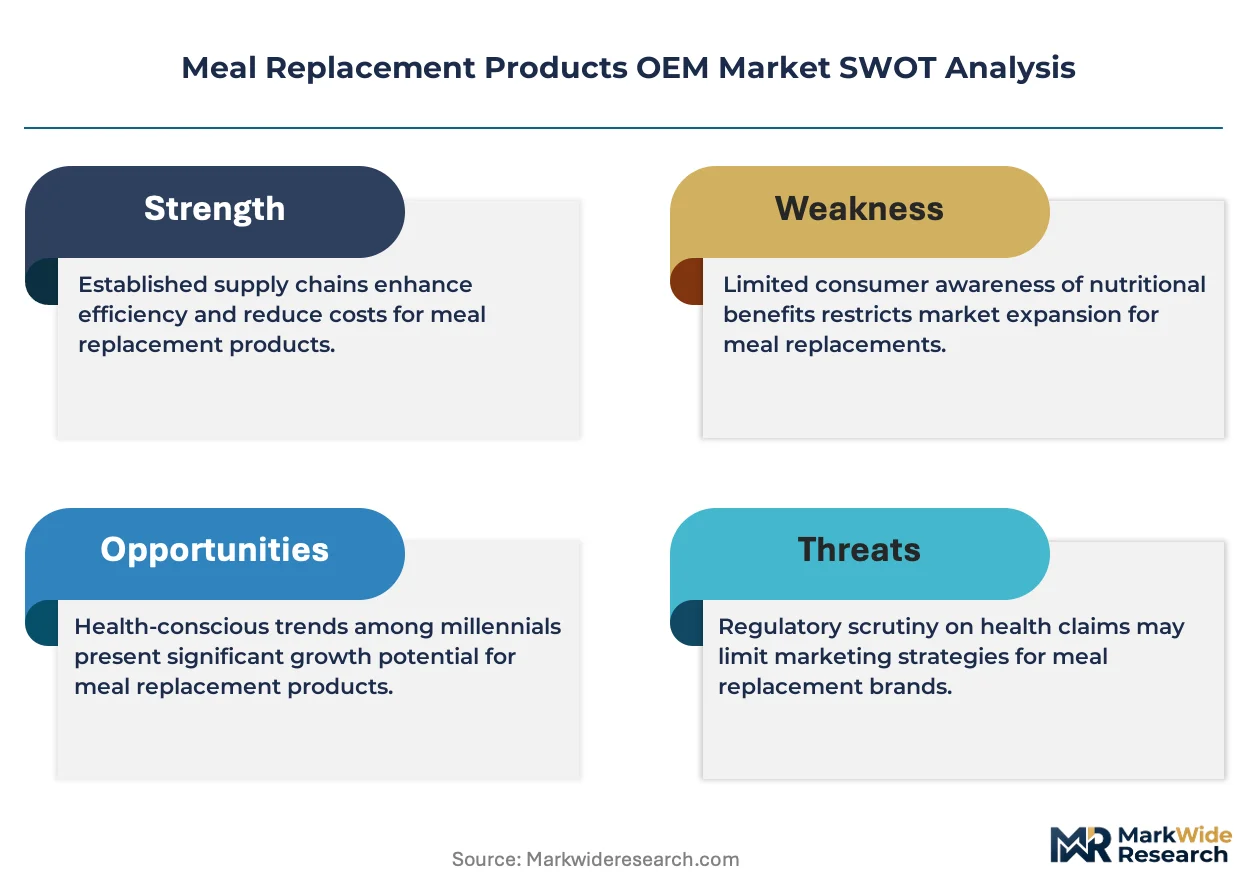
FDA 21 CFR Part 111 compliance mandates erect a barrier-to-entry moat that rewards incumbent contract manufacturers with established quality systems while filtering subscale competitors from multinational procurement lists. The cost-of-compliance story favors players with capital reserves to absorb identity testing and contaminant control investments.
For Market Incumbents:Hedge against whey protein concentrate volatility by securing backward integration into grass-fed dairy cooperative supply pools or diversifying into plant-protein formulation capabilities. Add aseptic liquid processing capacity in Texas and Florida to capture gym channel growth ahead of refrigeration-free distribution demand. Certification investment in FSSC 22000 and NSF Certified for Sport protocols reinforces preferred-supplier positioning against emerging mid-tier competitors.
For New Entrants and Emerging Players:Capture underpenetrated pharmacy and drugstore channels in Germany where domestic sports nutrition saturation has not yet reached contract manufacturing partnerships. Target precision-fermented protein formulation services for EU-bound brands navigating EFSA novel food assessment timelines. A white-label AI-driven flavor matching platform offers rapid prototype iteration as a differentiated go-to-market angle against incumbent scale advantages.
For Investors and Strategic Acquirers:The window for entry favors mid-tier sports nutrition specialists with clean-label sourcing credentials and existing FSSC 22000 certification. Long-term viability hinges on formulation flexibility across dairy-based and plant-based portfolios as flexitarian consumer preferences shift. Watch EFSA novel food approval timelines for precision-fermented proteins as the inflection signal determining which OEMs secure first-mover positioning in next-generation ingredient categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Liquid Processing Capacity Expansion | Unlocks gym channel distribution in Texas and Florida without refrigeration infrastructure requirements. |
| Precision-Fermented Protein Platform Investment | Positions OEMs ahead of EFSA novel food approvals for flexitarian market capture in European export channels. |
| AI-Driven Flavor Matching Technology Deployment | Collapses formulation-to-market cycles from months to weeks for direct-to-consumer subscription brands. |
| Grass-Fed Whey Sourcing Backward Integration | Secures margin stability against New Zealand dairy cooperative price volatility for performance-oriented channels. |
| FSSC 22000 Certification Acquisition | Qualifies contract manufacturers for multinational brand-owner procurement slots and preferred-supplier status. |
Research Methodology
Document review covered FDA 21 CFR Part 111 guidance documents, EFSA novel food assessment records, and FSSC 22000 certification databases, complemented by interviews with contract manufacturing operations directors, brand-owner procurement managers, and sports nutrition formulation scientists. Secondary validation drew from customs trade data for whey protein concentrate and pea protein isolate flows, SEC filings of listed nutrition conglomerates, and NSF Certified for Sport third-party testing protocols. Bottom-up demand modeling from end-user segment consumption patterns was cross-checked against top-down supply-side capacity assessments across spray-drying and aseptic liquid processing facilities.
Segmentation outputs across product type, end user, distribution channel, and ingredient source dimensions were projected across the analysis window using elasticity-adjusted growth rates derived from historical volume correlations with fitness participation indices and weight management clinic expansion. CAGRs were computed from year-over-year progression curves fitted to OEM order flow data and private-label launch cadence tracking. Model inputs included dairy commodity price volatility indices, EFSA approval timeline distributions, and gym network point-of-sale placement velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA regulatory shifts, precision-fermented protein commercialization timelines, and flexitarian demand elasticity. Outputs reflect documented assumptions on certification adoption rates and cold-chain logistics cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Canada Whey Protein Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Policosanol Market
Nutritional Supplements
Immunity Boosting Food Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
Lipid Nutrition Market