
 Central & South America Food Safety Testing Market | 2026-2036
Central & South America Food Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Central & South America Food Safety Testing Market Analytics
Subscription-based laboratory information management is decoupling testing capacity from fixed capital deployment across the region. SGS Société Générale de Surveillance SA leverages its pan-regional laboratory network to anchor multi-year service contracts with protein exporters. Bureau Veritas competes through specialized auditing protocols that integrate traceability software with physical sampling regimes.
Central and South America food safety testing encompasses analytical verification of contaminants, adulterants, and nutritional parameters in food matrices using standardized methods with detection thresholds measured in parts per billion. Its primary commercial purpose is to certify compliance with importer country standards and domestic public health mandates. Microbiological testing dominates current volume as salmonella and listeria protocols remain mandatory for meat and dairy exports, while rapid testing technology captures expanding margin pools through same-turnaround guarantees. PCR-based pathogen identification sustains premium positioning in high-value seafood and fresh produce corridors.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce harmonized residue limits and laboratory certification requirements that determine market access for domestic producers and foreign testing providers. These agencies mandate ISO 17025 accreditation and periodic proficiency testing, creating structural barriers for uncertified entrants. Stakeholders must monitor regulatory convergence between Mercosur sanitary standards and destination-country import protocols to anticipate capability investments.
Market Dynamics
Export certification mandates from the United States, European Union, and China are compressing testing turnaround requirements, forcing laboratories to restructure workflows around rapid pathogen detection protocols. Cold chain expansion for perishables across Brazil and Mexico intensifies surveillance obligations at multiple handoff points.
Growth Catalysts
- ANVISA Laboratory Accreditation Mandates:Brazil's updated food safety protocols require ISO 17025 certification for all facilities handling export-bound protein samples, accelerating equipment upgrades and proficiency testing investments.
- PCR-Based Pathogen Identification:Meat processing facilities adopt polymerase chain reaction systems to meet same-day turnaround guarantees demanded by high-value seafood and fresh produce corridors.
- Mercosur Sanitary Harmonization:Convergence between regional sanitary standards and destination-country import protocols creates unified compliance frameworks that reduce redundant testing for cross-border trade.
Market Restraints
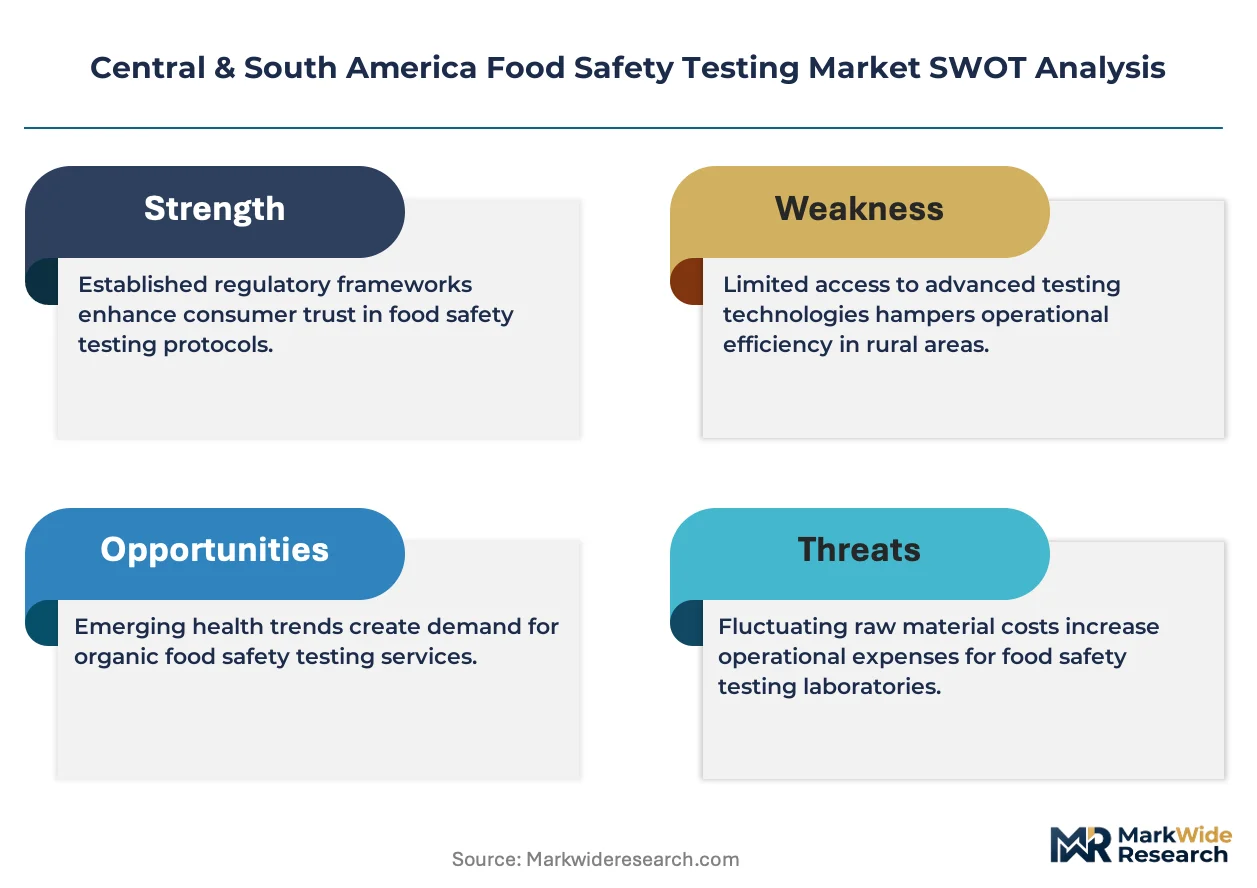
- Reagent Supply Concentration:Specialized PCR reagents and certified reference materials concentrate among North American and European suppliers, exposing laboratories to currency volatility and extended lead times.
- ISO 17025 Certification Barriers:Proficiency testing and accreditation timelines stretch 18-24 months, freezing uncertified entrants from contract eligibility with major protein exporters.
- Technical Talent Scarcity:Qualified analytical chemists and microbiologists with molecular biology training remain concentrated in São Paulo and Mexico City, constraining laboratory expansion into secondary markets.
Strategic Opportunities
- Colombian Cold Chain Buildout:INVIMA's expanding surveillance mandates for imported perishables create first-mover advantages for accredited laboratories establishing presence in Bogotá and Medellín logistics corridors.
- Blockchain-Traceability Convergence:Integration of distributed ledger systems with physical sampling regimes enables real-time verification that commands premium pricing from traceability-conscious buyers.
- Subscription LIMS Models:Cloud-based laboratory information management systems decouple testing capacity from fixed capital deployment, lowering entry barriers for mid-tier processors seeking in-house verification capability.
Industry Challenges
- Multi-Agency Proficiency Coordination:Laboratories serving both ANVISA and COFEPRIS jurisdictions must maintain parallel proficiency testing schedules, doubling administrative overhead without corresponding revenue uplift.
- Legacy Equipment Integration:Automated rapid testing platforms require reconfiguration of existing HACCP documentation systems, creating workflow friction during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central & South America Food Safety Testing Market |
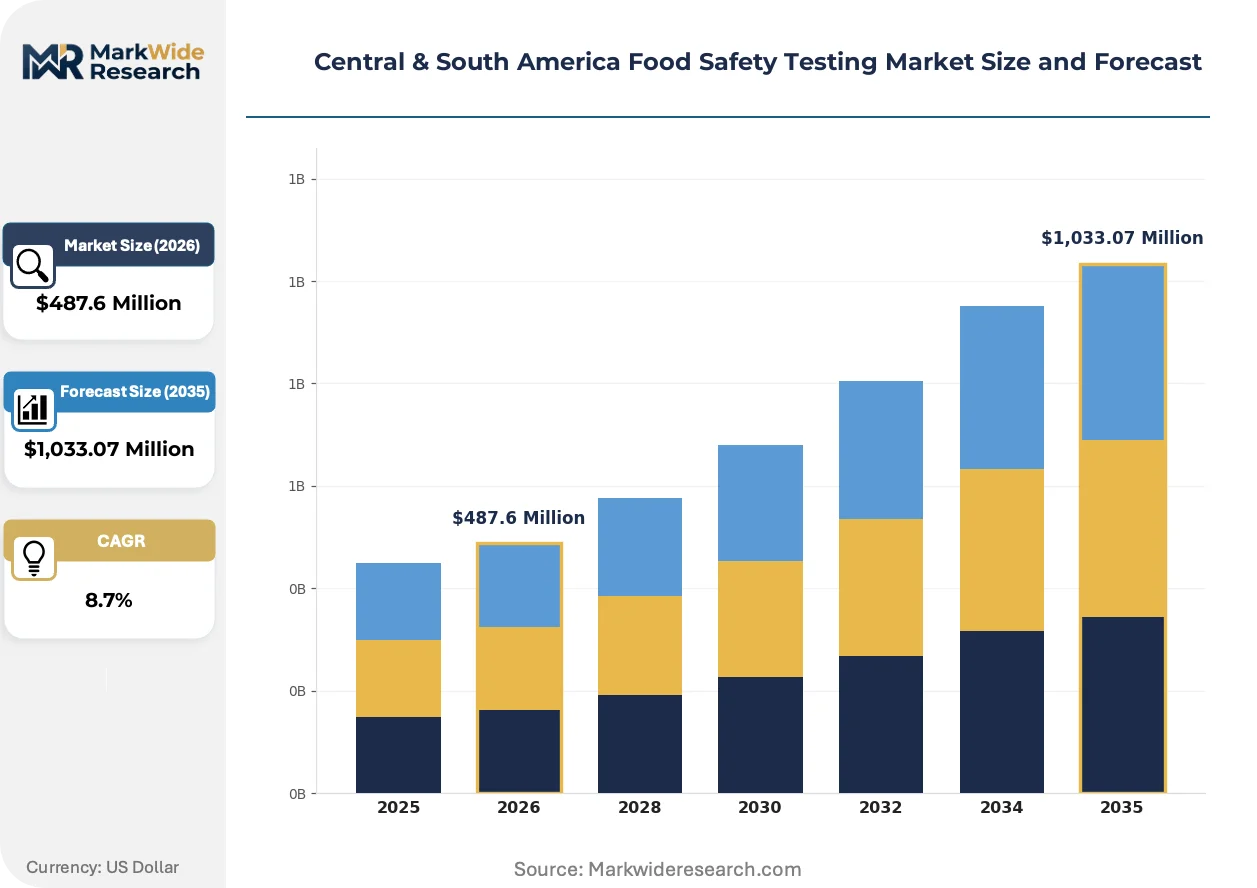
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Microbiological, Chemical, Nutritional, Allergen Application: Packaged Foods, Fresh Produce, Meat Products, Beverages Technology: PCR, ELISA, Chromatography, Rapid Testing End User: Food Manufacturers, Retailers, Laboratories, Government Agencies |
| Companies Covered | ALS, LGC Limited, Bureau Veritas, Microbac Laboratories, Inc., Mérieux NutriSciences Corporation, Intertek Group plc, Eurofins Scientific, TÜV SÜD, SGS Société Générale de Surveillance SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central & South America Food Safety Testing Market Evolving Landscape
Digital verification architectures and portable detection systems are compressing the physical distance between sampling points and analytical confirmation, restructuring how compliance data flows through protein supply chains.
Portable nucleic acid amplification devices are modularizing field-based pathogen screening for remote slaughterhouses and fishing ports. Medium-scale meat processors in Brazil's interior states deploy these units to bypass sample transport delays to centralized laboratories. The technology is modularizing testing infrastructure by distributing analytical capability to peripheral production nodes previously dependent on urban laboratory networks.
COFEPRIS in Mexico has tightened residue limit enforcement for veterinary antibiotics in dairy exports, aligning domestic standards with European Union Maximum Residue Levels. Dairy cooperatives face expanded testing panels and documentation requirements for each production batch. Smallholder-dominated supply chains in Jalisco and Querétaro are consolidating around shared-service laboratory models to distribute compliance costs.
Buyer concentration among multinational retailers is compressing supplier certification cycles from annual to semi-annual verification. Protein exporters now demand continuous monitoring data rather than point-in-time certificates, displacing transactional testing relationships with subscription-based surveillance contracts. This pattern is most visible in Brazil's southern poultry corridor, where integrators bundle testing services into long-term supply agreements with European supermarket chains.
Central & South America Food Safety Testing Market Segmentation
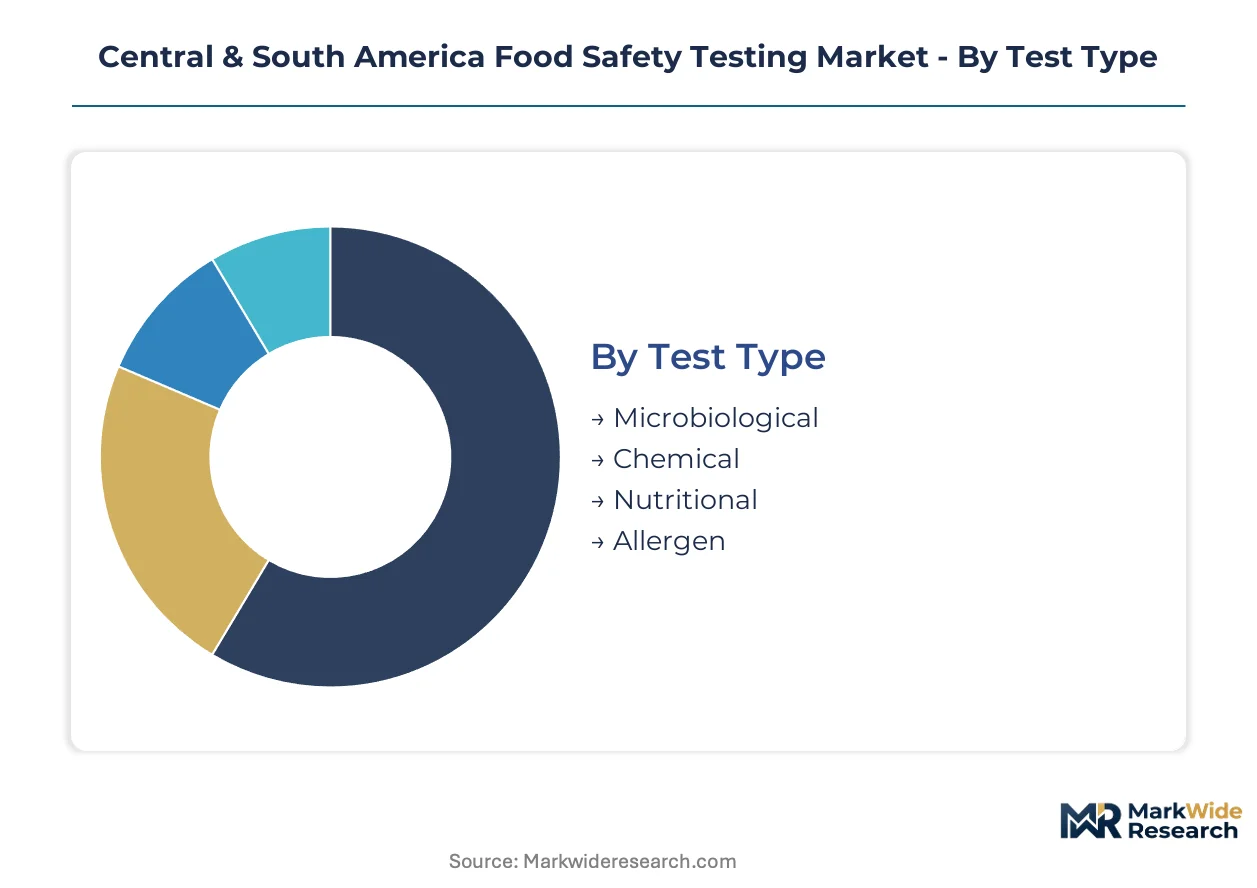
Segmentation in Central and South America food safety testing reveals how compliance requirements fragment across product risk profiles and buyer sophistication tiers. Laboratories configure service portfolios differently for export-bound protein processors versus domestic fresh produce distributors.
Test Type:
Standardized pathogen protocols dominate high-volume contracts, while specialized contaminant panels command customization premiums from niche exporters.
- Microbiological:Salmonella and listeria detection protocols anchor mandatory export certification for Brazilian beef and Mexican poultry shipments. ANVISA's ISO 17025 mandates accelerate laboratory upgrades for same-day pathogen confirmation.
- Chemical:Pesticide residue and veterinary antibiotic screening concentrates in fresh produce corridors serving European Union buyers. Jalisco dairy cooperatives face expanded testing panels under COFEPRIS's tightened residue enforcement.
- Nutritional:Label verification and macronutrient quantification supports packaged food compliance with Mercosur harmonized standards.
- Allergen:Gluten and peanut protein detection serves bakery and confectionery manufacturers supplying multinational retailers with strict supplier protocols.
Leading the category by volume: Microbiological. Expanding most quickly: Chemical.
Application:
Perishables drive surveillance intensity through cold chain handoff points, while shelf-stable products concentrate testing at manufacturing origin.
- Meat Products:Brazilian integrators bundle PCR-based pathogen surveillance into long-term supply agreements with European supermarket chains. Continuous monitoring data now displaces point-in-time certificates in the southern poultry corridor.
- Fresh Produce:Field-based nucleic acid amplification devices modularize screening for remote harvesting operations. Colombia's INVIMA mandates intensify surveillance at Bogotá and Medellín logistics hubs.
- Packaged Foods:Nutritional labeling verification and shelf-life stability testing dominates processed food manufacturing in São Paulo and Mexico City industrial zones.
- Beverages:Contaminant screening for bottled water and soft drinks concentrates around municipal supply quality variance and flavor additive compliance.
Revenue concentrates in: Meat Products. Steepest expansion trajectory: Fresh Produce.
Technology:
Capital-intensive platforms compete with portable systems for deployment flexibility across centralized versus distributed sampling architectures.
- PCR:Polymerase chain reaction systems sustain premium positioning through same-day turnaround guarantees. Meat processing facilities adopt these for high-value seafood and fresh produce corridor compliance.
- Rapid Testing:Portable nucleic acid amplification devices enable field-based screening at remote slaughterhouses and fishing ports. Medium-scale Brazilian processors deploy units to bypass urban laboratory transport delays.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective allergen and mycotoxin detection for mid-tier food manufacturers.
- Chromatography:High-performance liquid and gas chromatography systems anchor chemical residue confirmation in accredited reference laboratories.
Dominant by installed base: PCR. Gaining share fastest: Rapid Testing.
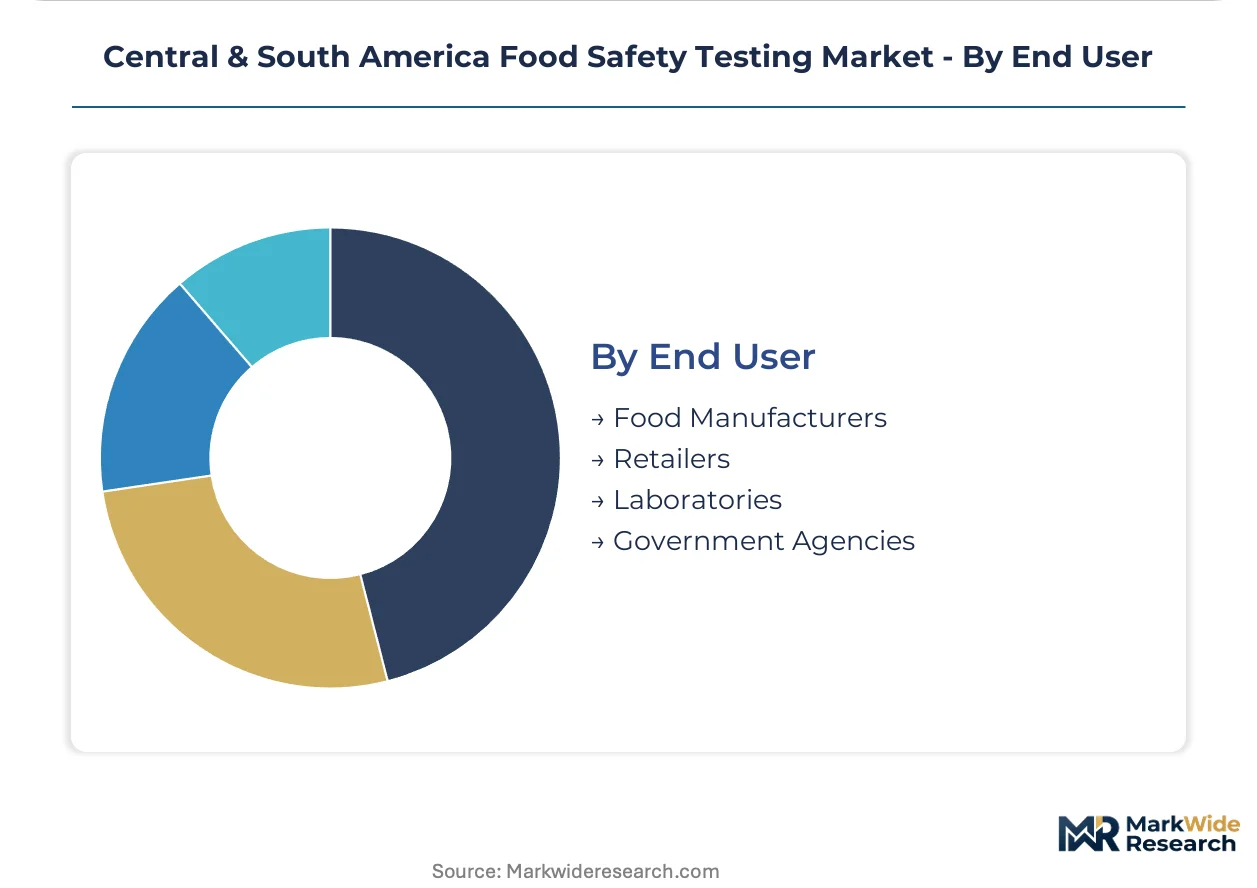
End User:
Buyer sophistication stratifies between integrated processors with captive laboratory capacity versus outsourced compliance for fragmented supplier bases.
- Food Manufacturers:Large protein exporters maintain in-house verification capability or contract multi-year service agreements with pan-regional laboratory networks. Subscription-based LIMS models decouple testing capacity from fixed capital deployment.
- Laboratories:Independent testing facilities compete through ISO 17025 accreditation and specialized auditing protocols integrating traceability software with physical sampling regimes.
- Retailers:Multinational supermarket chains compress supplier certification cycles from annual to semi-annual verification, demanding continuous monitoring data streams.
- Government Agencies:ANVISA, COFEPRIS, and INVIMA enforce harmonized residue limits and laboratory certification requirements that determine market access.
Primary demand source: Food Manufacturers. Fastest-growing procurement segment: Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central and South America food safety testing concentrates where protein exports and cold chain infrastructure intersect. Brazil and Mexico absorb the majority of laboratory capacity investments, while secondary markets emerge around logistics corridor buildouts.
Brazil
ANVISA's ISO 17025 accreditation mandates accelerate equipment upgrades across São Paulo and Rio Grande do Sul. Meat integrators in the southern poultry corridor bundle PCR-based surveillance into multi-year supply agreements with European retailers. Cold chain expansion into Mato Grosso and Pará drives field-based testing deployment at remote slaughterhouses.
Mexico
COFEPRIS tightened veterinary antibiotic residue limits for dairy exports to European Union standards. Jalisco and Querétaro dairy cooperatives consolidate around shared-service laboratory models to distribute compliance costs. Mexico City industrial zones anchor chromatography-based chemical confirmation capacity for packaged food manufacturers.
Colombia
INVIMA surveillance mandates for imported perishables intensify at Bogotá and Medellín logistics hubs. Fresh produce corridors serving North American buyers deploy portable nucleic acid amplification devices at harvest points. Caribbean port infrastructure upgrades attract accredited laboratories establishing regional certification nodes.
Argentina
Buenos Aires province concentrates reference laboratory capacity for grain and oilseed export certification. Mercosur sanitary harmonization reduces redundant testing for cross-border meat shipments to Brazil. Rosario industrial belt mid-tier processors adopt subscription LIMS models to decouple testing capacity from capital deployment.
Chile
Salmon export corridors drive pathogen surveillance investment in Puerto Montt and Chiloé aquaculture zones. European Union buyer protocols mandate same-day turnaround guarantees that favor PCR-based laboratory networks. Santiago metropolitan area anchors nutritional labeling verification for packaged food multinationals.
Central & South America Food Safety Testing Market Competitive Landscape
Top-tier vendors anchor multi-year service contracts with protein exporters, while mid-tier specialists compete on regional accreditation breadth. The market structures around pan-regional laboratory networks, specialized auditing integrators, and equipment-agnostic service platforms. Strategic archetypes include accreditation-heavy incumbents, rapid-testing technology licensors, and traceability-software bundlers. Competitive moves concentrate on geographic footprint expansion and proficiency testing schedule consolidation.
Within the pan-regional network tier, SGS Société Générale de Surveillance SA and Bureau Veritas exemplify scale-driven positioning through multi-jurisdictional laboratory footprints. Eurofins Scientific occupies a position bridging chemical residue specialization with molecular biology capability. These entities represent the accreditation-intensive archetype that dominates export certification mandates across ANVISA, COFEPRIS, and INVIMA jurisdictions.
| Leading Market Players |
|---|
| ALS |
| LGC Limited |
| Bureau Veritas |
| Microbac Laboratories, Inc. |
| Mérieux NutriSciences Corporation |
| Intertek Group plc |
| Eurofins Scientific |
| TÜV SÜD |
| SGS Société Générale de Surveillance SA |
| Others |
Value Network & Pricing Analysis
Qualified analytical chemists and microbiologists with molecular biology training in São Paulo and Mexico City anchor labor-cost differentials that widen pricing-tier spreads between premium PCR-based laboratories and economy-tier rapid testing providers.
Pricing Analysis
Margin tightening in economy-tier rapid testing reflects reagent import dependency and currency volatility exposure. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited reference laboratories from proficiency-testing-pending facilities and uncertified field-screening operators. Price differentiation hinges on certification grade and turnaround guarantee tier. Smallholder dairy cooperatives in Jalisco exhibit highest price sensitivity, while European supermarket chain procurement teams prioritize certification tier over unit cost.
Supply Chain Analysis
ISO 17025 certification gating concentrates accredited reagent supply among North American and European specialty chemical manufacturers. Brazil, Mexico, and Colombia draw from concentrated PCR reagent, certified reference material, and chromatography consumable sources. Single-source vulnerability for polymerase enzymes and nucleotide mixes creates procurement risk during currency devaluation cycles. Distribution runs through pan-regional laboratory networks with centralized warehousing in São Paulo and Mexico City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive reagent sourcing and in-house proficiency testing capability is accelerating as laboratories seek margin defense against import cost volatility.
For Market Incumbents: Lock in multi-year service contracts with protein exporters by bundling PCR surveillance with blockchain-traceability verification. ANVISA's expanding accreditation mandates threaten uncertified competitors, creating acquisition opportunities for laboratories with spare proficiency testing capacity. Backward integration into reference material production reduces exposure to North American supplier lead times.
For New Entrants and Emerging Players: COFEPRIS's tightened veterinary antibiotic residue enforcement in Mexico opens a window for chromatography-specialist laboratories serving Jalisco dairy cooperatives. Colombia's INVIMA surveillance expansion for imported perishables offers first-mover positioning in Bogotá logistics corridors. Shared-service laboratory models distribute compliance costs across smallholder supply chains.
For Investors and Strategic Acquirers: Re-rating potential sits with ISO 17025-accredited mid-cap laboratories given ANVISA's 18-24 month certification timeline freezing new supply. Long-term viability favors operators with pan-regional footprint and traceability-software integration. Watch for European supermarket chain procurement shifts from annual to semi-annual verification cycles as inflection indicator for subscription revenue predictability.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | ANVISA mandates certification for export-bound protein sample handling, freezing uncertified competitors from contract eligibility. |
| Blockchain-Traceability Integration | Real-time verification commands premium pricing from European supermarket chains with strict supplier protocols. |
| PCR Platform Deployment | Same-day turnaround guarantees sustain premium positioning in high-value seafood and fresh produce corridors. |
| Shared-Service Laboratory Model | Cost distribution across smallholder dairy cooperatives in Jalisco addresses COFEPRIS expanded testing panel requirements. |
| Portable Nucleic Acid Amplification Rollout | Field-based screening at remote Brazilian slaughterhouses bypasses urban laboratory transport delays. |
Research Methodology
Document review covered ANVISA regulatory filings, COFEPRIS residue limit updates, ISO proficiency testing records, and pan-regional laboratory accreditation databases, complemented by interviews with laboratory operations directors, protein exporter quality assurance managers, dairy cooperative procurement leads, and chromatography equipment distributors. Secondary validation drew from customs reagent import data, Mercosur sanitary standard harmonization documents, and cold chain infrastructure investment disclosures. Bottom-up service revenue estimates triangulated against top-down protein export certification volume projections.
Market sizing outputs incorporate test volume by technology platform, accreditation tier, and end-user sophistication across the projection horizon. Segmentation dimensions span test type, application category, technology modality, and buyer archetype. CAGRs derive from regression against protein export growth trajectories, laboratory capacity expansion timelines, and regulatory mandate implementation schedules. Forecast inputs include ANVISA accreditation mandate compliance curves and European Union Maximum Residue Level adoption rates.
The model assumes a particular technology adoption path; alternative pathways for portable nucleic acid amplification devices would alter the outlook if field-based screening displaces centralized laboratory volumes faster than projected. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Mycotoxin Testing Market
Food Safety Testing
Food Allergens and Intolerance Testing Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Fresh Food Residue Testing Market
Food Safety Testing
Global Bacteriological Testing Market
Food Safety Testing
South Africa Food Safety Testing Market
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
Animal Feed Safety Testing Equipment Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Chromatography Food Testing Market
Food Safety Testing
Food Pathogen Testing Market