
 Commercial Microwaves Market | 2026-2036
Commercial Microwaves Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Microwaves Market Outlook
Preventive maintenance subscriptions and remote diagnostics software is expanding the revenue model beyond unit sales for commercial microwave OEMs. Panasonic Corporation leverages its semiconductor expertise to sustain inverter technology leadership in heavy-duty kitchen environments. Electrolux AB anchors European commercial kitchen portfolios with modular under-counter configurations. Sharp Corporation differentiates through specialized magnetron designs that compete on energy recovery metrics in high-throughput catering operations.
Commercial microwaves are industrial food-heating appliances employing magnetron-generated microwave radiation at 2.45 GHz to excite water molecules in prepared foods, with power ratings from 1,000 to 3,000 watts and stainless-steel cavities designed for continuous daily cycles. Their primary commercial purpose is rapid thermal processing in foodservice environments where speed and labor minimization override precision cooking requirements. Heavy-duty product types lead installed base value due to durability premiums and extended warranty attach rates, while speed cook configurations represent the fastest-growing segment as operators seek dual-function equipment that combines microwave acceleration with convection browning. End user demand skews toward restaurants and catering services, where volume throughput and menu standardization create the most favorable total-cost-of-ownership profiles.
The U.S. Department of Energy and the FDA's Center for Devices and Radiological Health jointly shape commercial microwave standards through efficiency mandates and leakage limits that determine product certification and market access. NSF International sanitation protocols further constrain design geometry and material selection for food-contact surfaces. CE marking requirements under EU electromagnetic compatibility directives govern export eligibility for manufacturers serving European foodservice distributors. Stakeholders must monitor evolving efficiency tier thresholds and emerging connected-kitchen data privacy obligations as regulatory scope extends from hardware performance to operational telemetry.
Market Dynamics
Quick-service restaurant chains are compressing kitchen footprints through microwave-based automation, forcing equipment manufacturers to prioritize speed-to-temperature metrics and modular stacking configurations over standalone unit sales.
Growth Catalysts
- Ghost Kitchen Proliferation:Delivery-only foodservice operators in the United States require compact, high-throughput reheating equipment that minimizes labor touchpoints and real estate costs.
- Inverter Technology Maturation:Semiconductor-controlled power modulation enables precise wattage delivery that reduces food waste and energy consumption in high-volume catering environments.
- DOE Efficiency Standards:The U.S. Department of Energy's standby power mandates are accelerating replacement cycles among institutional foodservice buyers seeking compliant equipment.
Market Restraints
- Magnetron Supply Concentration:Specialized vacuum tube manufacturing clusters in East Asia create single-source vulnerability for heavy-duty oven producers.
- Stainless Steel Input Volatility:Grade 304 and 316 sheet metal price swings compress margin predictability for cavity fabricators.
- Radio Frequency Interference Limits:FCC Part 18 emission constraints restrict power density scaling for compact high-wattage designs.
Strategic Opportunities
- Connected Kitchen Telemetry:IoT-enabled cycle counting and predictive maintenance subscriptions create recurring revenue streams beyond hardware margins.
- Speed Cook Convergence:Hybrid microwave-convection systems capture replacement demand from operators seeking dual-function equipment in constrained floor plans.
- European NSF-Equivalent Certification:CE-marked sanitation-compliant designs open distributor channels across EU foodservice markets.
Industry Challenges
- Magnetron Engineering Talent Scarcity:Specialized vacuum electronics expertise is concentrating among retiring workforce cohorts with limited pipeline replacement.
- Multi-Protocol Integration Complexity:Legacy kitchen management systems require costly middleware development to ingest connected oven telemetry streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Microwaves Market |
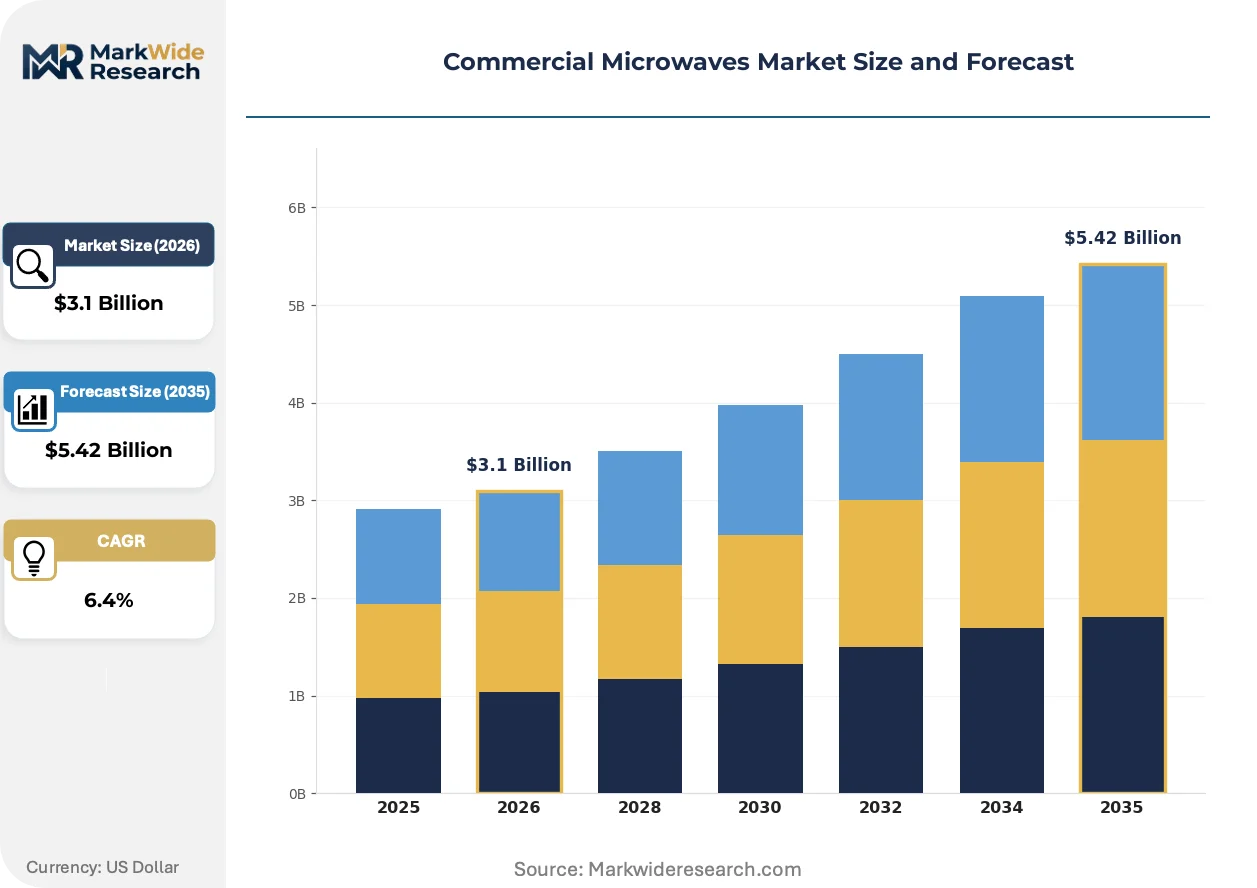
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Conveyor, Heavy-Duty, Speed Cook End User: Restaurants, Cafes, Catering Services, Food Trucks Technology: Microwave Radiation, Combination, Convection, Infrared Installation Type: Built-in, Portable, Under-counter, Wall-mounted |
| Companies Covered | Alto-Shaam Inc., Panasonic Corporation, Whirlpool Corporation, Sharp Corporation, Amana Corporation, Electrolux AB, GE Appliances, The Vollrath Company, ITW Food Equipment Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Microwaves Market Strategic Shifts
Equipment functionality is bifurcating between pure-speed reheating platforms and precision-hybrid systems, with semiconductor power control and sensor feedback loops enabling the latter category to capture premium positioning.
Inverter-based solid-state power generation is overtaking conventional transformer-magnetron architectures in mid-duty segments. Fast-casual chains with standardized menu portfolios are adopting these systems for repeatable temperature profiles. The technology is compressing warranty claim rates and extending replacement intervals for fleet operators.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are constraining insulation foam chemistries and refrigerant-adjacent cooling systems in exported equipment. Manufacturers serving European distributors are reformulating thermal barrier materials and redesigning cavity ventilation. Heavy-duty product lines face the steepest compliance cost escalation.
Foodservice procurement departments are consolidating vendor relationships through equipment standardization mandates across multi-unit footprints. National restaurant groups are negotiating enterprise pricing for unified microwave specifications. This concentration is most visible in United States-based quick-service and fast-casual verticals with centralized supply chain authority.
Commercial Microwaves Market Segmentation
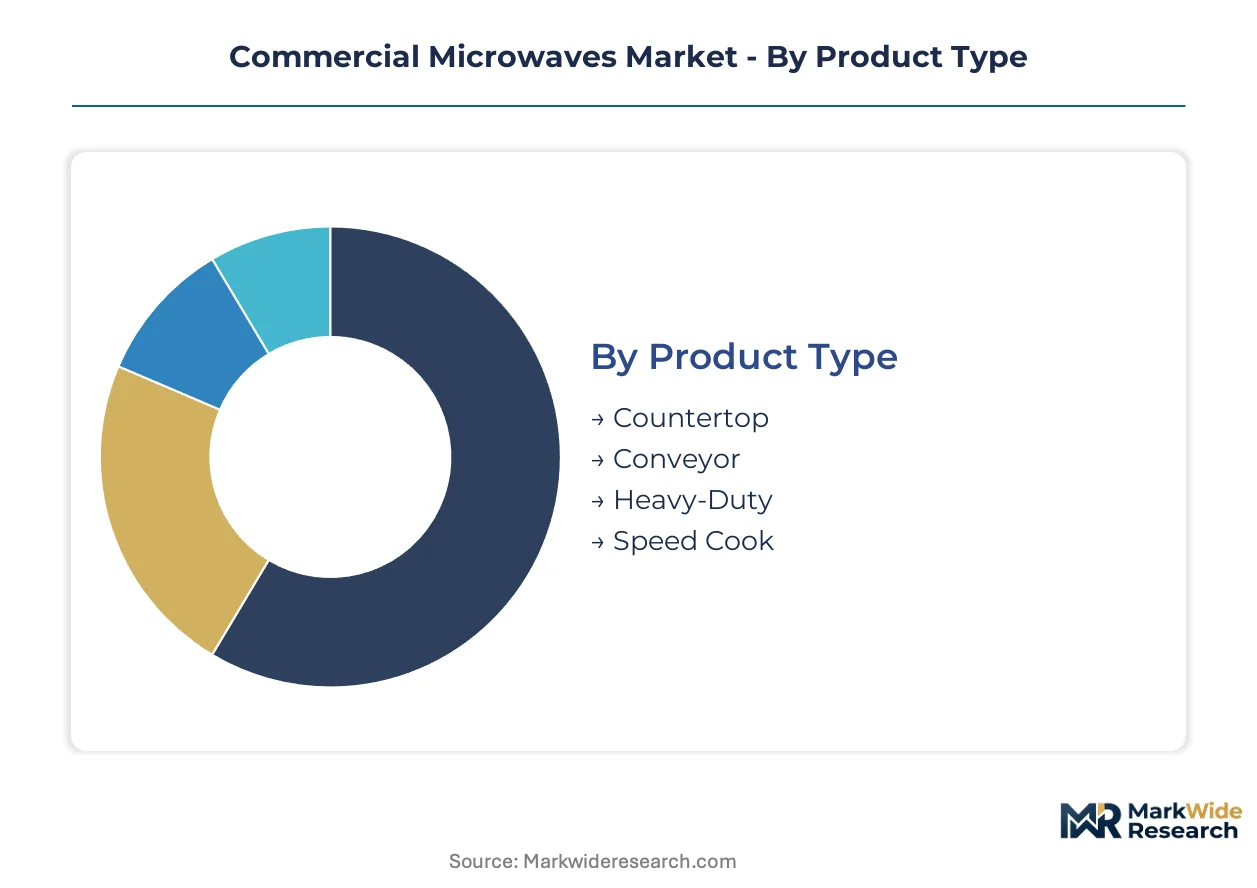
Commercial microwave segmentation reveals how equipment specifications align with distinct operational economics across foodservice environments. Product architecture, power delivery methods, and physical configuration each create divergent margin profiles and replacement cycle dynamics for manufacturers and distributors.
Product Type:
Supply concentration for magnetron assemblies and cavity fabrication favors producers with captive metalworking capacity and vertical integration into semiconductor power modules.
- Heavy-Duty:Stainless-steel cavities rated for 200+ daily cycles with reinforced door hinges and industrial-grade magnetrons. Demand concentrates in United States quick-service restaurant chains where extended warranty attach rates and fleet standardization justify premium positioning against total-cost-of-ownership metrics.
- Speed Cook:Hybrid architectures combining microwave acceleration with convection airflow or infrared browning elements. Fast-casual operators in constrained urban kitchen footprints drive adoption as dual-function equipment compresses capital expenditure and floor space requirements.
- Countertop:Compact units with 1,000-1,500 watt ratings for low-volume reheating tasks in office breakrooms and small cafes.
- Conveyor:Continuous-feed designs with automated belt systems for high-throughput catering and institutional foodservice batch processing.
Today's leader: Heavy-Duty. Tomorrow's challenger: Speed Cook.
End User:
Procurement authority patterns split between centralized enterprise buyers and fragmented independent operators, reshaping channel strategy and pricing architecture.
- Restaurants:Full-service and limited-service establishments with standardized menu engineering requirements. United States-based ghost kitchen operators and national chain retrofit cycles sustain replacement volume for inverter-equipped models meeting DOE standby power mandates.
- Catering Services:Mobile and fixed-location high-volume food production requiring rapid thermal processing for batch consistency. Institutional buyers prioritize NSF International sanitation certification and predictive maintenance telemetry subscriptions.
- Cafes:Coffee-focused operations with intermittent food warming needs and limited kitchen real estate.
- Food Trucks:Mobile operators constrained by generator capacity and space, favoring compact high-efficiency units.
Enterprise restaurant procurement is consolidating vendor relationships. Independent catering operators retain price sensitivity with equipment financing dependency.
Technology:
Power delivery architectures are bifurcating between legacy transformer-magnetron systems and semiconductor-controlled alternatives with diverging engineering talent requirements.
- Inverter:Solid-state power modulation replacing conventional transformer architectures with precise wattage control and reduced standby draw. Panasonic Corporation and Electrolux AB anchor manufacturing concentration for these systems in heavy-duty kitchen environments where energy recovery metrics determine specification wins.
- Microwave Radiation:Conventional 2.45 GHz magnetron-generated systems dominating installed base value through lower first-cost positioning.
- Combination:Stacked microwave-convection or microwave-grill configurations for menu flexibility in limited equipment budgets.
- Convection:Forced-air thermal systems integrated with microwave acceleration for browning and texture control.
- Infrared:Radiant heat elements for surface finishing in specialized catering and banquet applications.
Inverter systems command specification authority in new-build installations. Conventional microwave radiation retains replacement market dominance.
Installation Type:
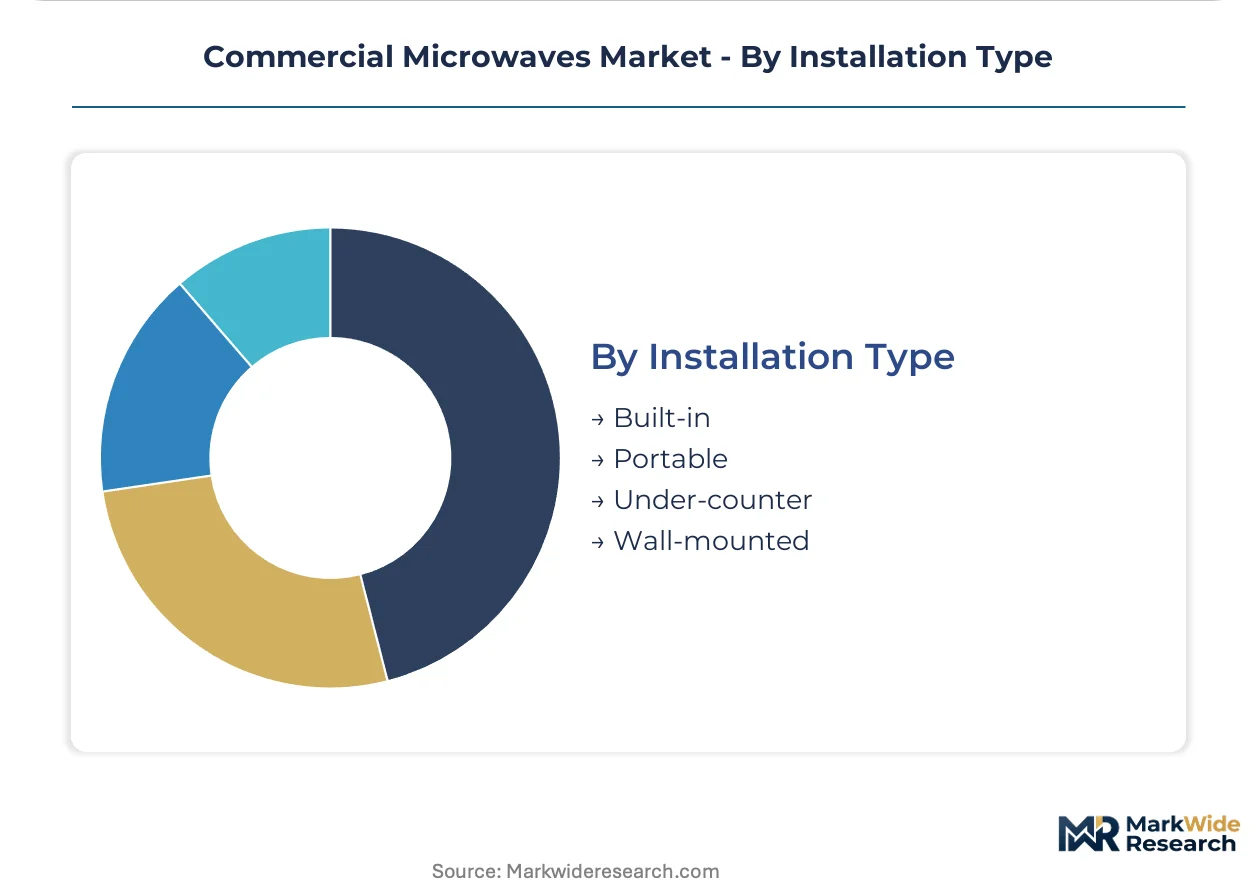
Real estate cost trajectories in urban foodservice markets are compressing kitchen footprints and elevating under-counter and built-in configurations.
- Under-counter:Modular configurations integrated into stainless-steel kitchen suites for workflow optimization. European fast-casual chains and United States ghost kitchen operators specify these designs for labor efficiency and cleaning protocol standardization.
- Built-in:Flush-mounted units for front-of-house visibility or back-of-house architectural integration in premium foodservice environments.
- Portable:Castor-mounted or lightweight units for temporary foodservice and catering event deployment.
- Wall-mounted:Elevated installations preserving counter space in severely constrained kitchen geometries.
Under-counter specifications are climbing fastest in new construction. Portable units face margin compression from rental and secondary market alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ghost kitchen proliferation outpaces European fast-casual expansion, while China's inverter manufacturing clusters reshape component sourcing economics for equipment assemblers worldwide.
United States
Ghost kitchen operators in New York Metro and Los Angeles sustain replacement volume for compact high-throughput units. The Department of Energy's standby power mandates accelerate retrofit cycles among institutional foodservice buyers. Chicago and Dallas-Fort Worth anchor distributor consolidation as national restaurant groups negotiate enterprise pricing for standardized specifications.
Germany
Fast-casual chains in Berlin-Brandenburg and Bavaria specify modular under-counter configurations for labor efficiency. REACH substance restrictions constrain insulation foam chemistries in exported equipment. The Eindhoven Region across the Dutch border supplies semiconductor power modules to inverter system integrators serving Central European markets.
China
Domestic catering services in Shanghai and Guangzhou drive demand for heavy-duty conveyor systems. GB standards and MIIT efficiency directives shape magnetron manufacturing specifications. The Yangtze River Delta concentrates specialized vacuum tube production clusters supplying global oven assemblers.
Japan
Convenience store chains in Tokyo and Osaka deploy precision-hybrid systems for standardized menu portfolios. METI energy efficiency programs promote semiconductor-controlled power modulation. Nagoya's industrial corridor hosts captive metalworking capacity for stainless-steel cavity fabrication.
United Kingdom
London's delivery-only operators compress kitchen footprints through microwave-based automation. CE marking requirements under EU electromagnetic compatibility directives govern equipment eligibility for European distributor channels. The Midlands region hosts refurbishment centers extending replacement intervals for fleet operators.
Commercial Microwaves Market Competitive Environment
Top-tier vendors anchor specification authority in heavy-duty segments, while mid-tier fabricators compete on first-cost positioning for countertop and portable categories. The vendor base stratifies across three tiers: diversified appliance conglomerates with captive semiconductor expertise, specialized foodservice equipment houses with stainless-steel fabrication scale, and regional assemblers sourcing magnetron modules from East Asian suppliers. Dominant competitive moves include backward integration into magnetron manufacturing and strategic partnerships with ghost kitchen real estate developers.
Among diversified appliance conglomerates, Panasonic Corporation and Electrolux AB exemplify archetypes with divergent geographic emphases. Sharp Corporation occupies a position bridging semiconductor power control and specialized magnetron design. These three entities represent distinct strategic postures: Japanese electronics expertise applied to kitchen environments, Swedish modular system integration for European fast-casual chains, and dual-technology positioning across inverter and conventional architectures.
| Leading Market Players |
|---|
| Alto-Shaam Inc. |
| Panasonic Corporation |
| Whirlpool Corporation |
| Sharp Corporation |
| Amana Corporation |
| Electrolux AB |
| GE Appliances |
| The Vollrath Company |
| ITW Food Equipment Group |
| Others |
Value Chain & Pricing Dynamics
Specialized vacuum electronics engineers concentrated in Japan's Nagoya industrial corridor and China's Yangtze River Delta command wage premiums that widen spreads between premium inverter systems and conventional magnetron tiers. Labor-cost differentials in magnetron manufacturing cascade through finished-equipment pricing, with Japanese-engineered semiconductor power modules carrying certification premiums against Chinese-assembled conventional architectures.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for conventional magnetron assemblies. Pricing stratifies across heavy-duty inverter-equipped systems, mid-duty transformer-based units, and economy countertop configurations differentiated by NSF International certification grade and warranty attach rates. Cost compression in the economy tier is intensifying because stainless-steel Grade 304 sheet metal price volatility feeds directly into cavity fabrication costs. Ghost kitchen operators and independent catering services exhibit the highest price sensitivity, while United States quick-service restaurant chains with fleet standardization mandates absorb premium positioning for total-cost-of-ownership advantages.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from national restaurant groups, while specialized foodservice distributors serve fragmented independent operators. Magnetron vacuum tube production draws from manufacturing clusters in China, Japan, and South Korea, with semiconductor power module fabrication anchored in Taiwan and Japan. Stainless-steel Grade 304 and 316 sheet metal, ceramic magnetron insulators, and solid-state power semiconductors constitute the critical input dependencies. Single-source vulnerability in specialized vacuum electronics engineering creates structural risk for heavy-duty oven producers. Distribution runs through three-tier channels: captive direct sales for enterprise accounts, authorized distributors for regional chains, and e-commerce platforms for replacement parts and countertop units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Japanese semiconductor-controlled power modulation expertise and Chinese magnetron manufacturing scale, with the DOE's standby power mandates creating regulatory-driven demand concentration in the United States that offsets higher labor costs.
For Market Incumbents: To counter inverter technology commoditization from Chinese semiconductor manufacturers, Panasonic Corporation and Electrolux AB should deepen backward integration into captive magnetron production and accelerate predictive maintenance subscription attach rates. Certification investment in CE-marked NSF-equivalent designs opens European distributor channels insulated from price competition. For New Entrants and Emerging Players: Capture white-space in United States ghost kitchen real estate partnerships by supplying compact under-counter configurations with IoT-enabled cycle counting. The most penetrable segment is independent catering operators in secondary United States metropolitan markets currently underserved by enterprise-focused incumbents. A go-to-market angle through equipment financing partnerships with foodservice lenders addresses capital-constrained buyer economics. For Investors and Strategic Acquirers: Diversified appliance conglomerates with captive semiconductor expertise are the most active acquirer in this space, seeking magnetron engineering talent and stainless-steel fabrication scale. Acquisition target archetypes include regional assemblers with established distributor relationships and specialized vacuum electronics houses with retiring workforce knowledge transfer risks. The signal to watch is DOE efficiency tier threshold revisions that would accelerate replacement cycles among institutional buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetron Manufacturing | Captive supply of vacuum tubes insulates against East Asian single-source vulnerability and extends margin control. |
| Predictive Maintenance Subscription Launch | Recurring revenue from IoT-enabled cycle counting transforms hardware margins into service-based cash flows. |
| CE-Marked NSF-Equivalent Certification | REACH and EU F-Gas Regulation compliance unlocks distributor channels across German and UK fast-casual markets. |
| Ghost Kitchen Real Estate Partnership | Direct specification authority with delivery-only operators in New York Metro and Los Angeles compresses sales cycles. |
| Speed Cook Hybrid System Development | Dual-function microwave-convergence captures replacement demand from space-constrained urban kitchen footprints. |
Study Parameters
Multiple input streams — primary interviews with commercial kitchen equipment procurement directors, foodservice distributor account managers, and NSF International certification specialists; secondary validation through DOE appliance efficiency filings, FCC Part 18 emission databases, and SEC 10-K disclosures from diversified appliance manufacturers; and trade flow analysis of magnetron vacuum tube customs records — were reconciled through bottom-up unit shipment modeling and top-down value chain triangulation.
Historical shipment volumes were cross-referenced against panel input from equipment OEMs and aftermarket service providers to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product architecture (heavy-duty, speed cook, countertop, conveyor), power delivery technology (inverter, conventional magnetron), installation configuration, and end-user procurement authority pattern. CAGRs were derived from replacement cycle analysis, regulatory mandate timing, and fleet standardization penetration curves, with ghost kitchen proliferation rates and DOE efficiency tier adoption thresholds serving as industry-specific forecast inputs.
Magnetron supply disruption, stainless-steel commodity price spikes, and FCC emission constraint revisions are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented base-case assumptions regarding regulatory implementation schedules and foodservice labor cost trends. Periodic stress-testing of base assumptions against DOE rulemaking announcements and ghost kitchen real estate development pipelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Retail Cooler Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Commercial Griddles and Flat Top Grills Market
Food Service Equipment
Hospital Foodservice Equipment Market