
 Commercial Gas Restaurant Ranges Market | 2026-2036
Commercial Gas Restaurant Ranges Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Gas Restaurant Ranges Market Outlook
Modular range configurations that separate burner tops from base ovens is realigning how kitchen designers specify equipment packages. Middleby Corporation leverages its portfolio breadth to bundle ventilation with cooking suites, while Electrolux Professional AB anchors its position through European manufacturing scale. Garland Commercial Industries LLC differentiates via heavy-duty chassis construction for high-heat applications.
Commercial gas restaurant ranges are heavy-duty cooking appliances fabricated from stainless steel with cast-iron grates, typically delivering burner outputs from 25,000 to 35,000 BTU per hour for continuous-duty foodservice operations. Floor model ranges dominate institutional installations where volume and durability requirements exceed countertop alternatives, while combination ovens capture premium positioning by consolidating multiple cooking modes into single-footprint units. Natural gas maintains share leadership in urban corridors with established utility infrastructure, though propane configurations gain traction in mobile and remote installations where pipeline access is absent.
The EPA sets commercial kitchen equipment efficiency thresholds that influence gas range burner design and hood integration requirements, while OSHA workplace safety standards govern ventilation and surface temperature exposure in professional cooking environments. The Department of Energy periodically revises test procedures for commercial cooking equipment, creating compliance cycles that favor manufacturers with active engineering pipelines. Stakeholders must monitor evolving electrification mandates in municipal building codes that could restrict new gas connections in certain jurisdictions.
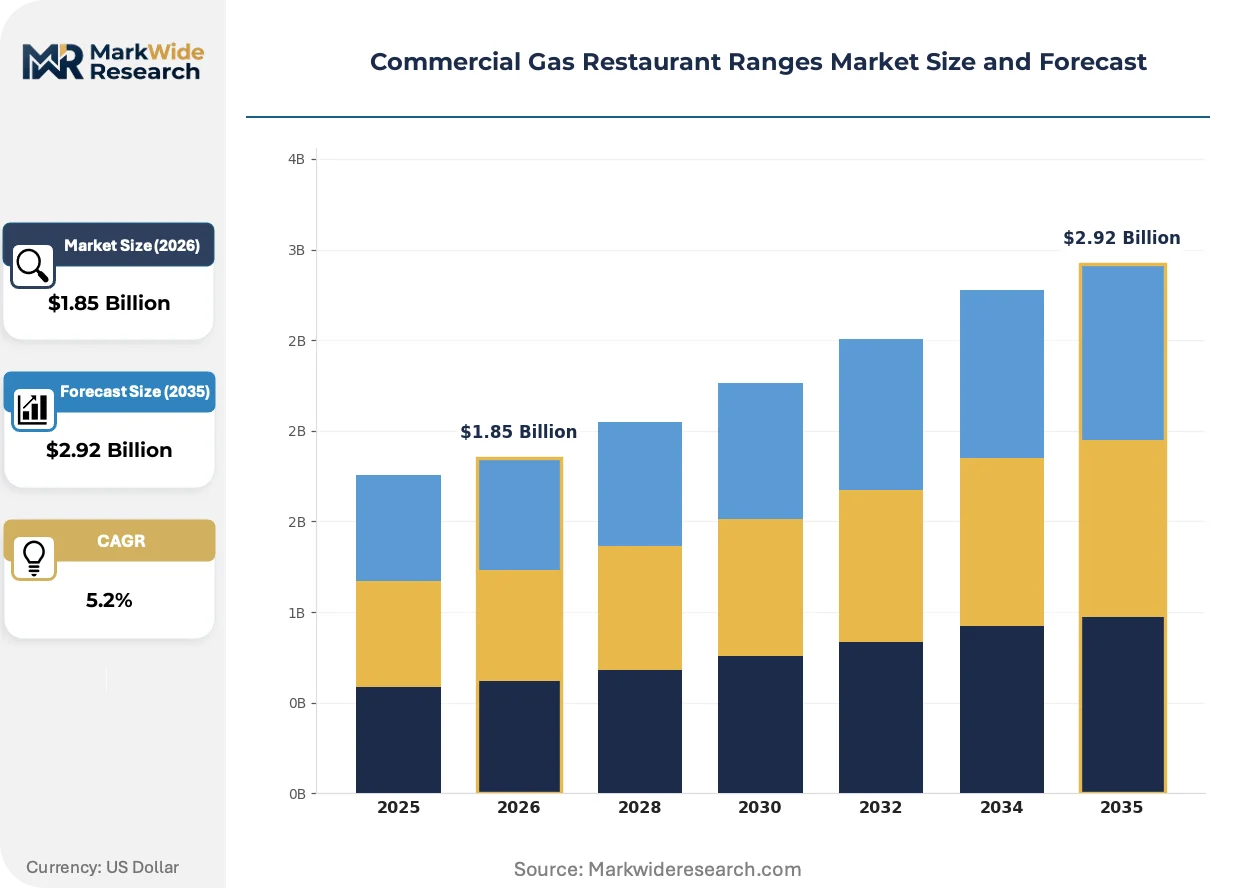
Market Dynamics
Full-service restaurant chains are expanding kitchen footprints to accommodate higher-volume cooking lines, while the EPA's commercial kitchen energy efficiency standards are pushing operators toward certified gas range models that reduce exhaust hood loads. This dual pressure is compressing specification cycles and elevating the importance of integrated ventilation-cooking bundles.
Growth Catalysts
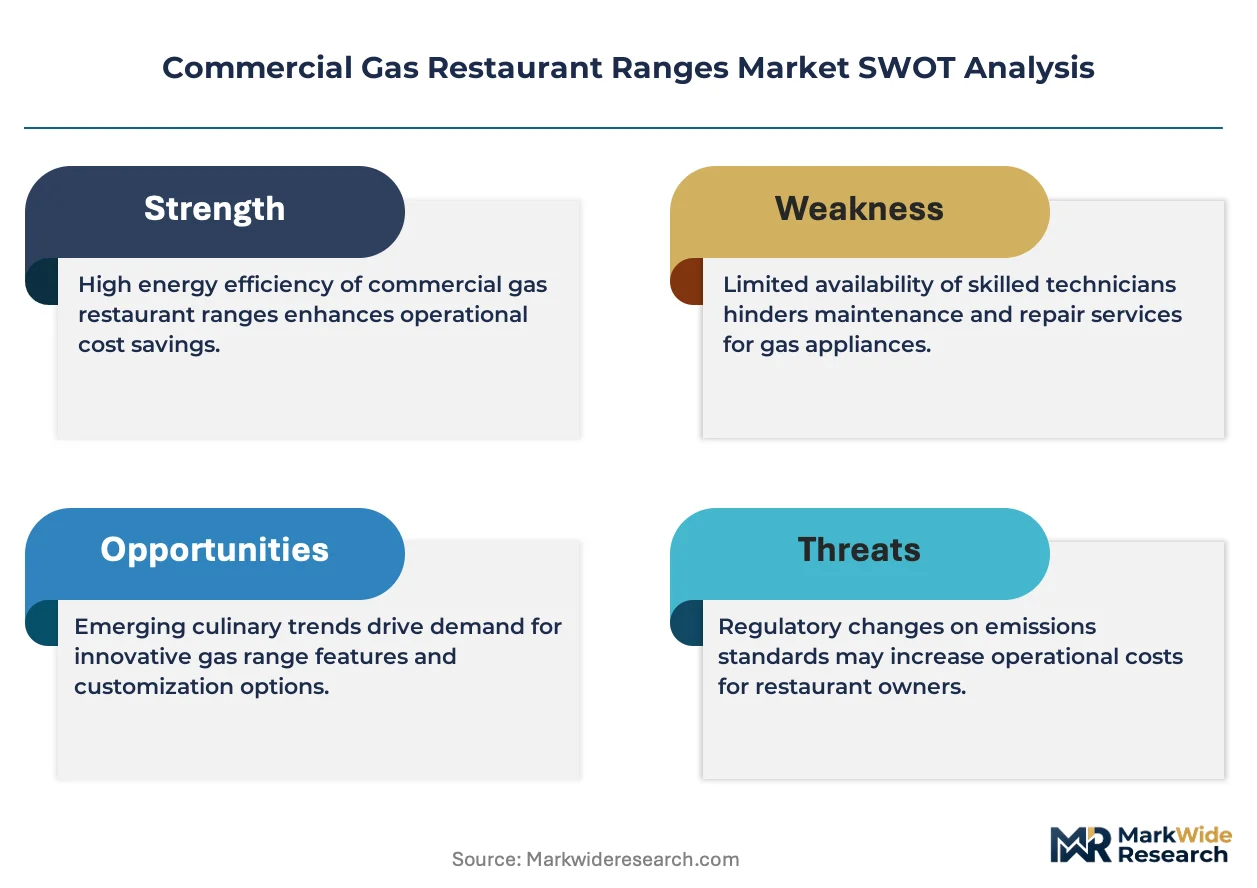
- Sun Belt Construction Surge:Restaurant construction permits across Texas, Florida, and Arizona are sustaining elevated equipment procurement volumes for new commercial kitchen installations.
- EPA Energy Efficiency Standards:The EPA's commercial kitchen equipment efficiency thresholds are mandating burner redesigns that favor manufacturers with active engineering pipelines and certified product portfolios.
- Modular Kitchen Configurations:Separated burner tops and base ovens are enabling flexible equipment packages that align with variable menu throughput requirements in multi-concept food halls.
Market Restraints
- Electrification Mandates:Municipal building codes in California, New York City, and Seattle are restricting new gas connections, compressing addressable market geography for traditional gas range suppliers.
- Stainless Steel Input Volatility:Raw material cost fluctuations for food-grade stainless steel chassis and cast-iron grates are compressing margin stability for manufacturers without captive foundry capacity.
- Propane Infrastructure Gaps:Remote and mobile installations lacking pipeline access face higher operational costs and supply reliability constraints versus natural gas configurations.
Strategic Opportunities
- Mobile and Remote Segments:Propane-configured ranges are capturing unmet demand in food trucks, catering operations, and rural resort kitchens across the Mountain West and Gulf Coast.
- Department of Energy Test Procedure Revisions:Periodic compliance cycles are creating acquisition windows for engineering-active manufacturers to displace laggards in institutional procurement channels.
- Combination Oven Convergence:Integration of convection, steam, and radiant modes into single-footprint gas-powered units is opening premium positioning in space-constrained urban kitchens.
Industry Challenges
- Ventilation Integration Complexity:OSHA workplace safety standards governing surface temperature exposure require specialized hood engineering that extends project timelines and elevates installation coordination costs.
- Certification Pipeline Bottlenecks:Third-party efficiency certification and local fire marshal approvals are creating multi-month delays that mismatch with accelerated restaurant opening schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Gas Restaurant Ranges Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.92 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Ranges, Floor Model Ranges, Combination Ovens, Griddles End User: Restaurants, Catering Services, Food Trucks, Hotels Installation Type: Freestanding, Built-In, Mobile, Wall-Mounted Heat Source: Natural Gas, Propane, Biogas, Others |
| Companies Covered | Middleby Corporation, GE Appliances, Rational AG, Electrolux Professional AB, ITW Food Equipment Group LLC, Ali Group, Welbilt, Inc., Vulcan Equipment, Garland Commercial Industries LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Gas Restaurant Ranges Market Strategic Shifts
Equipment specification is pivoting from standalone product selection toward integrated kitchen system design. This shift is elevating vendors with ventilation bundling capabilities and compressing the relevance of pure-play cooking equipment manufacturers.
Open-burner infrared technology is rewriting thermal efficiency benchmarks in high-heat applications. Independent steakhouse chains and wok-intensive Asian concepts are specifying these configurations for precise temperature control and reduced recovery time. The technology is compressing the performance gap between traditional cast-iron and premium radiant alternatives.
The EPA's evolving commercial kitchen energy efficiency standards are mandating burner design modifications that reduce exhaust hood loads. Manufacturers are responding with staged combustion systems and optimized flame geometry that maintain output while lowering ventilation requirements. Institutional buyers in K-12 and healthcare sectors are prioritizing these certified models to minimize HVAC capital expenditure.
Specification authority is migrating from individual chefs to corporate facilities teams and design-build contractors. National restaurant chains are centralizing equipment decisions through approved vendor lists and master specifications, compressing the influence of local kitchen consultants. This concentration is most visible in quick-service and fast-casual expansion programs across the Sun Belt states.
Commercial Gas Restaurant Ranges Market Segmentation
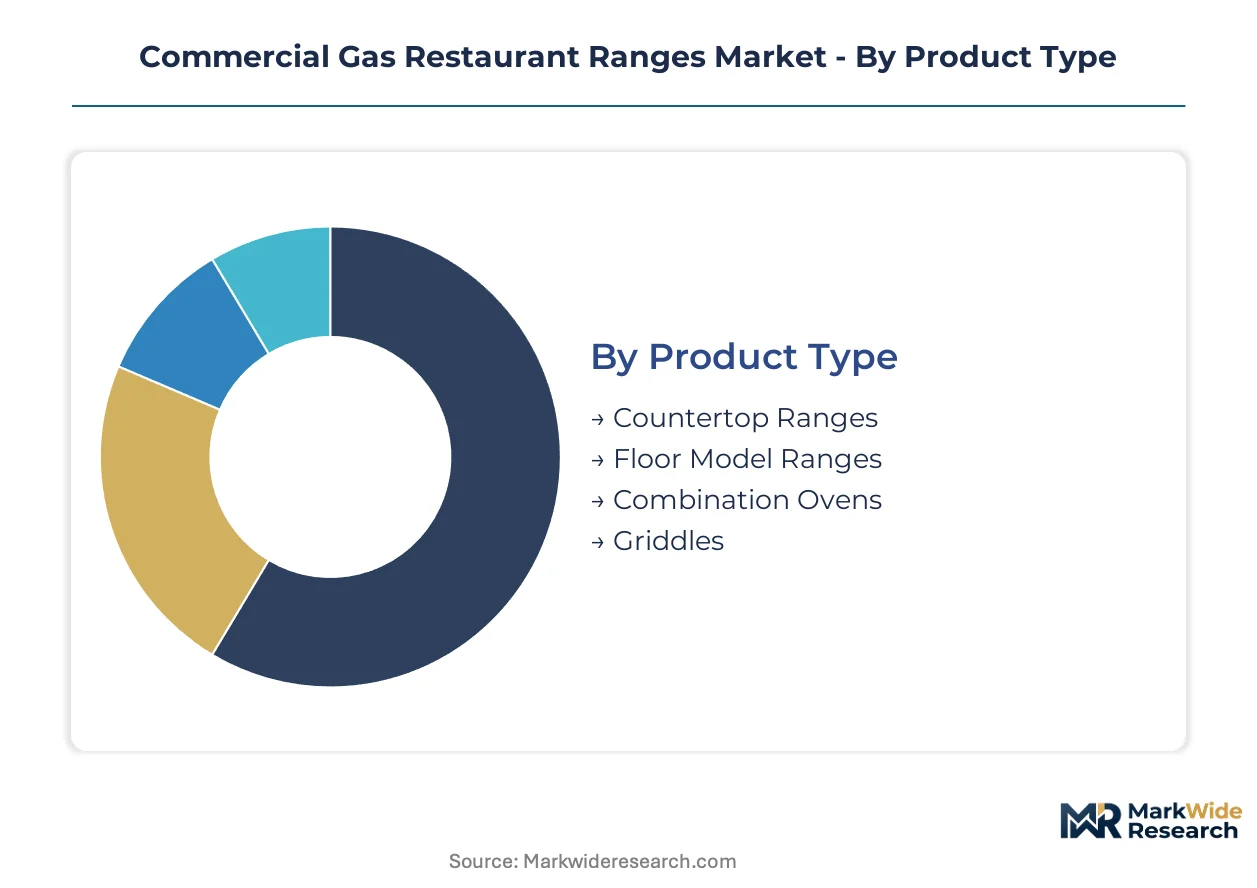
Equipment specification in commercial gas ranges diverges sharply across kitchen formats, from institutional footprints requiring continuous-duty durability to mobile operations prioritizing fuel flexibility. Segmentation reveals how burner output requirements, ventilation integration, and utility access reshape procurement patterns across foodservice verticals.
Product Type:
Volume throughput and durability requirements separate institutional buyers from countertop operators.
- Floor Model Ranges:Heavy-duty stainless steel chassis with cast-iron grates deliver 25,000 to 35,000 BTU per hour for continuous-duty operations. Full-service restaurant chains expanding kitchen footprints in Texas, Florida, and Arizona specify these for high-volume cooking lines.
- Combination Ovens:Single-footprint units integrating convection, steam, and radiant modes command premium positioning. Space-constrained urban kitchens in municipal jurisdictions with electrification mandates prioritize these for operational flexibility.
- Countertop Ranges:Compact units serve low-volume prep stations and satellite kitchens where floor space is constrained.
- Griddles:Flat-top configurations dominate breakfast-focused concepts and diner chains requiring even heat distribution.
Floor model ranges lead volumes today; combination ovens are gaining share fastest.
End User:
Operational mobility and menu complexity drive divergent specification priorities across foodservice channels.
- Restaurants:Full-service chains anchor demand through centralized procurement and approved vendor lists. Corporate facilities teams in Sun Belt expansion programs specify integrated ventilation-cooking bundles to compress project timelines.
- Food Trucks:Propane-configured ranges capture unmet demand where pipeline access is absent. Mobile operators across the Mountain West and Gulf Coast face higher fuel costs but gain locational flexibility.
- Catering Services:Event-based operations require rapid deployment capabilities and multi-fuel compatibility for remote venues.
- Hotels:Multi-outlet properties balance banquet volume requirements with room service flexibility in consolidated kitchen footprints.
Restaurants dominate procurement volumes; food trucks show the steepest expansion trajectory.
Installation Type:
Project timeline constraints and spatial permanence distinguish capital-intensive builds from flexible deployments.
- Freestanding:Self-contained units with integrated bases dominate new construction where utility rough-ins accommodate standard footprints. Institutional buyers in K-12 and healthcare sectors favor these for predictable HVAC load calculations.
- Mobile:Castor-mounted configurations serve food halls and multi-concept venues requiring seasonal repositioning. Food hall operators in Sun Belt metros specify these for menu concept rotation without infrastructure modification.
- Built-In:Custom-fabricated surrounds align with architect-specified kitchen designs in premium hospitality projects.
- Wall-Mounted:Elevated configurations maximize floor space in compact urban kitchens with severe square footage constraints.
Freestanding installations anchor current deployment; mobile configurations are climbing the fastest.
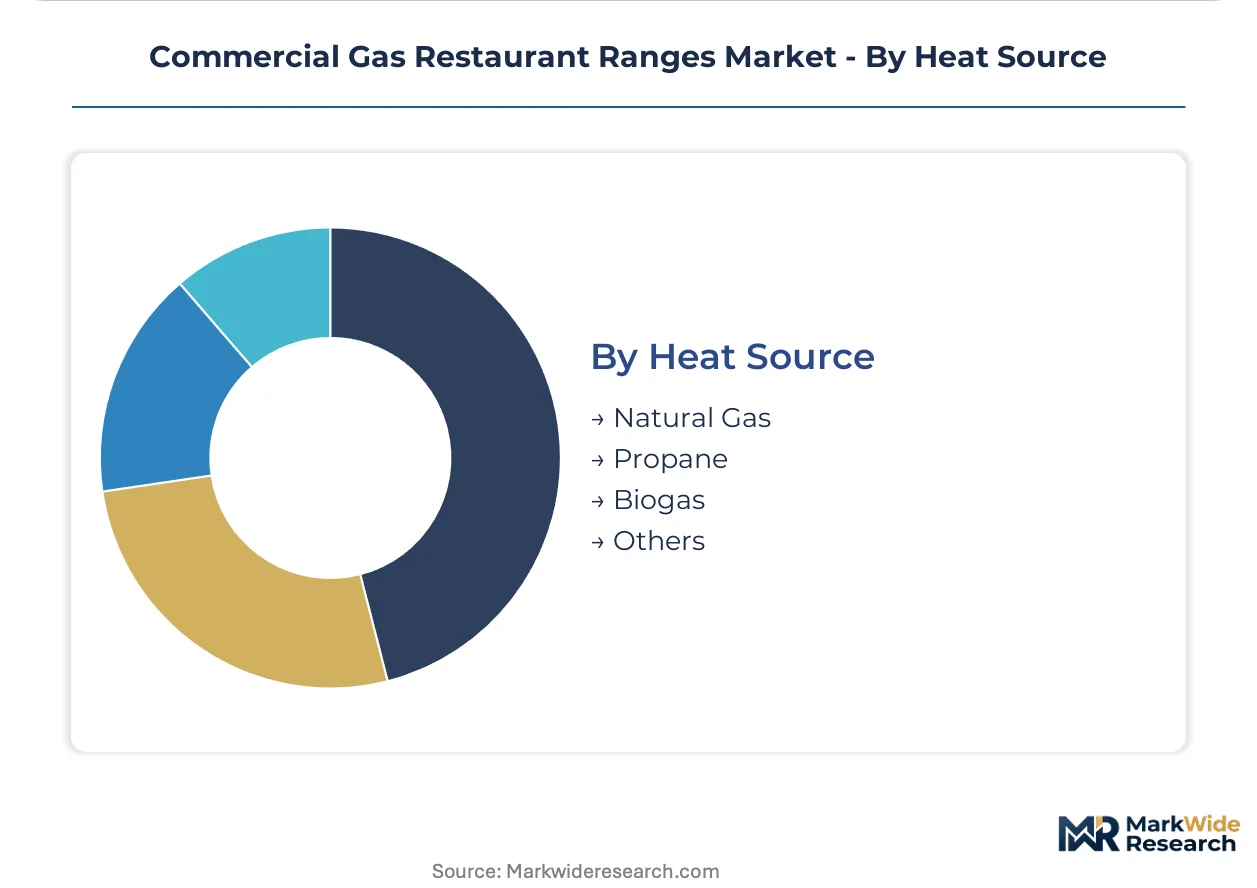
Heat Source:
Utility infrastructure availability and regulatory risk exposure separate geographic markets and operational formats.
- Natural Gas:Established utility corridors in urban centers maintain share leadership through lower operational costs. EPA commercial kitchen energy efficiency standards are mandating burner redesigns that favor manufacturers with certified product portfolios.
- Propane:Cylinder or tank-fed configurations penetrate remote installations and mobile operations lacking pipeline access. Catering operators and rural resort kitchens across the Mountain West absorb higher fuel costs for locational flexibility.
- Biogas:On-site digester-fed systems serve sustainability-focused institutional campuses with organic waste streams.
- Others:Emerging alternatives include hydrogen blends and synthetic methane pilots in jurisdictions with aggressive decarbonization timelines.
Natural gas retains volume leadership; propane is expanding most quickly in addressable segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial gas restaurant ranges industry traces its modern scale to post-war American diner culture and European hospitality equipment manufacturing, with subsequent expansion into Asian commercial kitchen infrastructure during the 1980s-1990s economic liberalization period.
United States
Sun Belt construction activity in Texas, Florida, and Arizona sustains elevated procurement volumes for new restaurant installations. EPA commercial kitchen energy efficiency standards mandate burner redesigns that reduce exhaust hood loads and favor certified product portfolios. Corporate facilities teams in Dallas-Fort Worth and Phoenix specify integrated ventilation-cooking bundles for quick-service expansion programs.
Germany
Precision engineering heritage supports premium equipment manufacturing for export markets across Europe and the Middle East. REACH chemical safety regulations and CE marking requirements govern stainless steel chassis fabrication and surface treatment processes. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate fabrication capacity for heavy-duty institutional ranges.
China
Domestic foodservice expansion and outbound equipment supply reshape procurement patterns across Asia-Pacific markets. GB national standards and MIIT industrial policy directives influence manufacturing quality benchmarks and export certification pathways. Yangtze River Delta manufacturing zones around Shanghai supply cost-optimized ranges for Southeast Asian restaurant chains.
Italy
Design-forward hospitality equipment traditions serve premium European and North American restaurant concepts. EU F-Gas Regulation and energy labeling directives constrain refrigerant integration in combination oven configurations. Emilia-Romagna and Lombardy industrial districts maintain specialized foundry capacity for cast-iron grate production.
Japan
Compact kitchen footprints in urban centers drive demand for space-efficient, high-output burner configurations. METI energy conservation standards and JIS certification requirements govern thermal efficiency testing and product approval timelines. Osaka-based equipment distributors serve wok-intensive Asian cuisine concepts throughout East Asian markets.
Commercial Gas Restaurant Ranges Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with ventilation bundling capabilities. Market concentration reflects scale advantages in certification pipelines and master specification relationships with national restaurant chains. Two strategic archetypes dominate: integrated kitchen system providers combining cooking and ventilation equipment, and specialized heavy-duty fabricators focused on high-heat durability. Dominant competitive moves include portfolio diversification into complementary ventilation products and geographic expansion through distribution partnerships in high-growth Sun Belt markets.
Within the diversified conglomerate tier, Middleby Corporation and Electrolux Professional AB exemplify scale-driven positioning through portfolio breadth and European manufacturing footprint respectively. Garland Commercial Industries LLC occupies a specialist position anchored in heavy-duty chassis construction for demanding high-heat applications. These three entities represent the structural spectrum from integrated system bundling to focused fabrication excellence.
| Leading Market Players |
|---|
| Middleby Corporation |
| GE Appliances |
| Rational AG |
| Electrolux Professional AB |
| ITW Food Equipment Group LLC |
| Ali Group |
| Welbilt, Inc. |
| Vulcan Equipment |
| Garland Commercial Industries LLC |
| Others |
Value Chain & Pricing Dynamics
EPA commercial kitchen energy efficiency standards gate qualified supply and premium-tier pricing access by mandating certified burner redesigns that only engineering-active manufacturers can deliver. Buyers seeking reduced exhaust hood loads must pay certification premiums or accept higher HVAC capital expenditure from non-compliant alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales service bundling. Premium tiers command position through UL-listed efficiency certification and integrated ventilation warranties, while economy configurations serve price-sensitive institutional buyers in K-12 sectors facing procurement budget constraints. Cost compression in mid-tier stainless steel chassis is intensifying because raw material volatility erodes margin stability for fabricators without captive foundry capacity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from national restaurant chains with approved vendor lists, while regional distributors serve independent operators with shorter procurement cycles. Manufacturing concentrates in the United States, Germany, and China, with heavy reliance on food-grade stainless steel from North American mills and cast-iron grate supply from Italian and Chinese foundries. Single-source vulnerability in specialty burner component supply creates procurement risk for manufacturers lacking dual-qualified vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial gas restaurant ranges market functions as a geographic-arbitrage play between Sun Belt construction surges and electrification-mandate compression in California and New York City. Operators can capture cost advantages by siting new facilities in Texas and Florida while regulatory risk concentrates in coastal jurisdictions.
For Market Incumbents: Deploy ventilation bundling capabilities to defend specification authority against pure-play cooking equipment manufacturers. Middleby Corporation's integrated kitchen system model demonstrates how master specification relationships with national chains compress competitor access. Incumbents must accelerate backward integration into foundry capacity to offset stainless steel input volatility and protect margin stability.
For New Entrants and Emerging Players: Launch via propane-configured range specialization targeting food trucks and rural resort kitchens across the Mountain West and Gulf Coast. This segment shows steepest expansion trajectory with lowest incumbent saturation. New entrants should prioritize METI-compliant burner designs for export positioning into Japanese compact kitchen markets.
For Investors and Strategic Acquirers: Roll-up economics work for regional ventilation specialists because corporate facilities teams are centralizing procurement through approved vendor lists that favor bundled capabilities. Acquisition targets should demonstrate active EPA certification pipelines and established fire marshal approval relationships. Watch electrification mandate expansion into additional municipal jurisdictions as inflection indicator for gas range addressable market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Investment | EPA efficiency thresholds mandate burner redesigns that favor engineering-active manufacturers with certified portfolios. |
| Backward Integration into Foundry Capacity | Captive cast-iron grate production insulates margin stability from stainless steel input volatility. |
| Ventilation Bundling Capabilities | Integrated cooking-hood packages compress project timelines for Sun Belt quick-service expansion programs. |
| Propane Configuration Development | Mobile and remote installations across Mountain West and Gulf Coast absorb higher fuel costs for locational flexibility. |
| Regional Distribution Partnerships | Local fire marshal approval relationships accelerate certification timelines for institutional procurement channels. |
Study Parameters
Coverage spans the United States, Germany, China, Italy, and Japan, with primary inputs from each market informing cross-regional demand patterns. The analysis combines structured interviews with commercial kitchen equipment procurement managers, restaurant chain facilities directors, ventilation system engineers, and aftermarket service heads with secondary validation from EPA efficiency standard filings, DOE test procedure revisions, SEC 10-K equipment disclosures, and municipal building permit databases. Bottom-up equipment shipment tracking and top-down foodservice construction spend estimates provide triangulation anchors.
Segmentation granularity extends to product type, end user vertical, installation format, and heat source configuration across the modeling period. CAGRs derive from equipment replacement cycle analysis, restaurant construction permit trajectories, and regulatory compliance deadline clustering. Industry-specific forecast inputs include Sun Belt construction surge persistence and electrification mandate geographic diffusion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated municipal electrification timelines or stainless steel supply disruption scenarios. The analysis reflects assumptions regarding EPA efficiency standard enforcement consistency and natural gas infrastructure maintenance across urban utility corridors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Griddles and Flat Top Grills Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Countertop Ice Dispensers Market
Food Service Equipment
Food Service Equipment Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Commercial Kitchen Knife Market
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market