
 Carton Liners Market | 2026-2036
Carton Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Carton Liners Market Intelligence
Fragmentation of the customer base, driven by the expansion of e-commerce and specialized food delivery services, is broadening the market's scope. Large-scale producers such as International Paper and WestRock leverage their extensive paperboard integration to serve high-volume accounts. Sealed Air Corporation differentiates through its portfolio of high-performance flexible liners for protective packaging. Mondi competes on a global scale with a wide range of both paper and plastic-based liner solutions.
Carton liners are protective inserts placed inside corrugated or paperboard boxes to prevent product damage, contamination, or leakage. These liners are engineered with specific barrier properties, such as moisture resistance using polyethylene coatings or thermal insulation. Flexible liners made from polyethylene represent the largest material segment, driven by food and beverage applications. Demand for rigid paperboard liners is accelerating in the e-commerce channel for protecting electronics during shipment.
Material safety and recyclability are governed by a complex web of international standards. In the United States, the FDA's regulations for food contact materials are paramount, while in Europe, REACH and EFSA guidelines dictate chemical safety and material composition. These regulations directly influence material selection and product design for manufacturers. The key decision for suppliers now centers on balancing the cost of compliance with advanced, sustainable materials against the price sensitivity of bulk applications.
Market Dynamics
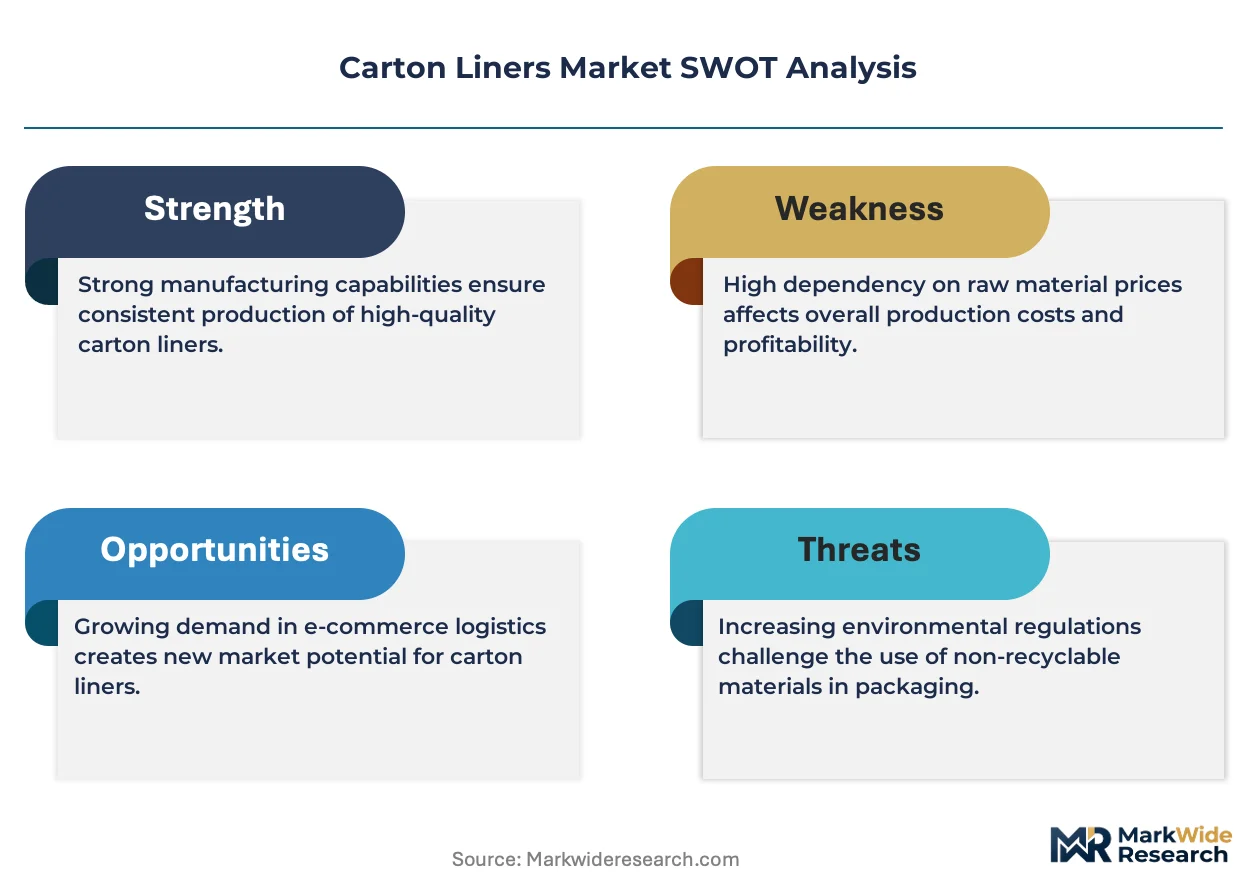
The carton liners market is shaped by the fundamental tension between demands for higher-performance materials in sensitive applications and the persistent price sensitivity of bulk commodity segments. Stringent food contact and pharmaceutical safety regulations from bodies like the FDA and EFSA are forcing a flight to quality, favoring advanced, compliant materials.
Growth Catalysts
- E-commerce Expansion:The growth of online retail, particularly for electronics and consumer goods, drives demand for rigid paperboard liners that provide structural integrity and shock absorption during last-mile delivery.
- Pharmaceutical Logistics:Demand for sterile, high-barrier liners is expanding within pharmaceutical supply chains, especially in European hubs like Germany and Switzerland, to protect temperature-sensitive biologics and active pharmaceutical ingredients from contamination.
- Food Safety Regulations:Increasingly strict standards for food contact materials, such as those mandated by the European Food Safety Authority (EFSA), compel food and beverage producers to adopt higher-grade liners with certified barrier properties.
Market Restraints
- Raw Material Volatility:Fluctuations in the price of polymer resins, particularly polyethylene, create significant cost instability for manufacturers of flexible liners, impacting margins and pricing for end-users in the food sector.
- Substitution from Integrated Packaging:The development of corrugated boxes with built-in barrier coatings and water-resistant treatments presents a direct substitution threat, potentially eliminating the need for a separate liner in certain applications. *Regulatory Compliance Costs: The expense and complexity of certifying materials against divergent international standards, such as the FDA's requirements in the US and REACH in Europe, act as a barrier to entry and strain smaller suppliers.
Strategic Opportunities
- Bio-based and Compostable Materials:Developing liners from polylactic acid (PLA) or other certified compostable polymers opens new avenues, particularly in Europe, where single-use plastic regulations and EU Green Deal initiatives create strong market pull.
- Active and Intelligent Liners:Incorporating antimicrobial coatings or oxygen-scavenging properties into liners creates significant value for extending the shelf life of perishable foods, creating a new premium product tier.
- Cold Chain Logistics in Emerging Markets:Expanding into developing economies in Southeast Asia and Latin America with tailored thermal liners addresses a critical need for protecting food and pharmaceuticals in nascent cold chain infrastructure.
Industry Challenges
- Recycling Infrastructure Mismatch:A primary challenge is the lack of standardized recycling streams capable of processing coated paperboard or multi-material plastic liners, complicating sustainability claims and circularity goals for manufacturers.
- Adhesive and Coating Contamination:Overcoming the technical challenge of ensuring that adhesives, inks, and coatings used on liners do not migrate into the product is a constant focus, requiring rigorous testing to comply with EFSA and FDA standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carton Liners Market |
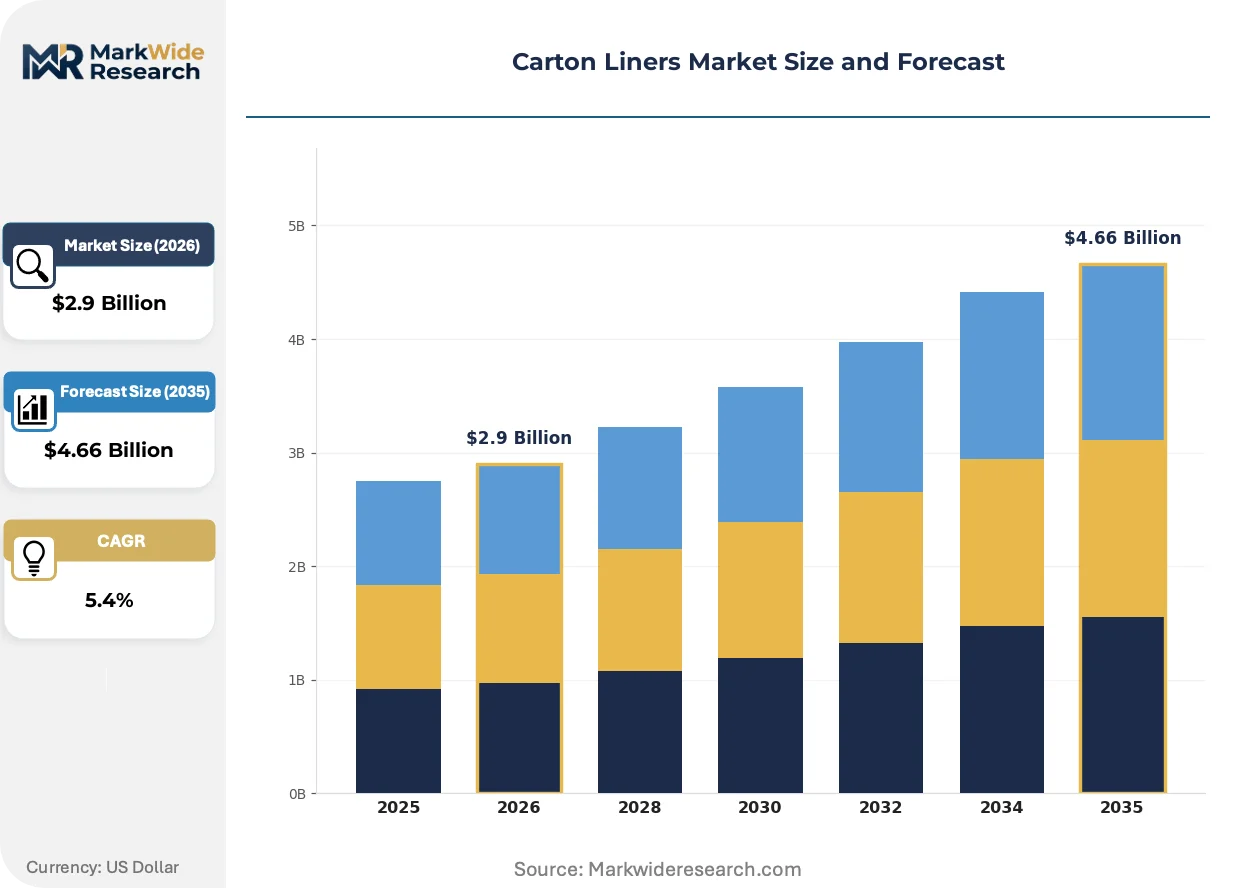
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.66 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Liners, Flexible Liners, Cushion Liners, Waterproof Liners Material: Polyethylene, Polypropylene, Paperboard, Aluminum End User: Food & Beverage, Pharmaceuticals, E-commerce, Electronics Application: Packaging, Insulation, Protection, Customization |
| Companies Covered | Amcor plc, Sealed Air Corporation, Mondi, Inteplast Group, Huhtamaki, International Paper, WestRock, Encore Poly, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carton Liners Market Strategic Shifts & Innovations
Innovation in the carton liner market is pivoting from passive protection to active functionality, driven by a convergence of material science, regulatory pressures, and demand for supply chain visibility. The focus is on creating liners that are not only protective but also sustainable and intelligent.
Smart liners integrated with passive sensor technology are gaining traction. These liners can feature printed indicators that change color to signal temperature excursions or breaches in package integrity. Pharmaceutical and high-value perishable food shippers are the primary adopters, seeking to improve quality control. This technology is automating the validation of cold chain compliance and product quality upon receipt.
European Union directives on single-use plastics and circular economy goals are a significant force for material change. These regulations penalize non-recyclable packaging and incentivize the use of mono-material structures. The flexible liner segment, historically reliant on multi-layer laminates, is now heavily investing in developing recyclable polyethylene-based films that retain necessary barrier properties.
A shift toward subscription-based and direct-to-consumer (DTC) models for specialty goods like meal kits and curated groceries is altering procurement. This trend bypasses traditional high-volume, low-mix orders from distributors, creating demand for smaller, more frequent orders of customized thermal and protective liners. This pattern is most pronounced in North American and Western European metropolitan areas.
Carton Liners Market Segmentation
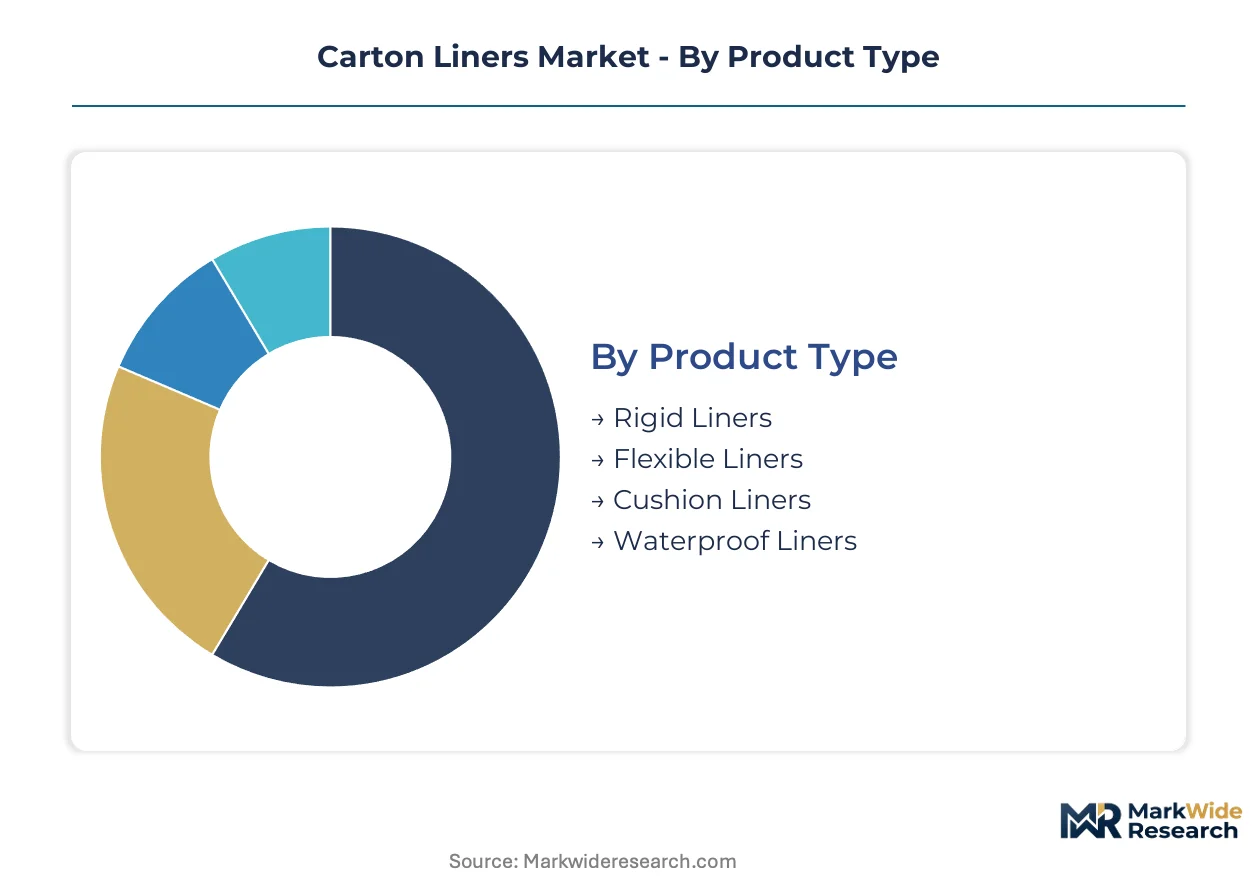
Understanding the carton liners market through segmentation highlights the varied needs across industries and material demands. Different product types and materials address specific protective requirements for goods in transit. This granular view reveals how regulatory compliance and application-specific performance drive market evolution.
Product Type:
Product type segmentation reveals how distinct liner constructions face varying certification burdens and performance standards. Liners designed for sensitive goods, for instance, must meet stringent regulatory approvals.
- Rigid Liners:Constructed from paperboard, these provide structural integrity and shock absorption for delicate items. E-commerce logistics, particularly for electronics, drives their adoption for last-mile delivery protection.
- Flexible Liners:Made primarily from polyethylene, these liners offer versatile barrier properties against moisture and gases. Demand is concentrating in the food and beverage sector, driven by EFSA and FDA food contact material regulations.
- Cushion Liners:These inserts absorb impact and vibrations, primarily used for fragile goods like glassware and ceramics during shipment.
- Waterproof Liners:Designed to prevent liquid ingress or egress, these are critical for protecting moisture-sensitive or liquid-containing products.
Leading the category by volume: Flexible Liners. Growing fastest: Rigid Liners.
Material:
Material segmentation highlights the cost-performance trade-offs inherent in liner selection across different price tiers. Each material offers a distinct balance of protective qualities and economic viability.
- Polyethylene:A versatile polymer, it forms the basis for most flexible liners, offering excellent moisture barrier and heat-sealability. Fluctuations in resin prices impact its adoption in bulk food packaging applications.
- Paperboard:Sourced from wood pulp, this material provides structural rigidity and recyclability, particularly valued in e-commerce for electronics and consumer goods. Its use is expanding due to sustainability initiatives.
- Polypropylene:Offering higher temperature resistance than polyethylene, this polymer is used in specialized flexible liners for medical and industrial applications.
- Aluminum:Typically used as a foil layer in multi-material laminates, aluminum provides superior oxygen and moisture barrier for sensitive pharmaceutical products.
Polyethylene dominates material volume due to its cost-effectiveness, while paperboard gains share from e-commerce expansion.
End User:
End-user segmentation reveals specific application requirements, where each industry necessitates tailored liner properties for product integrity. Performance demands vary widely across these diverse sectors.
- Food & Beverage:This sector requires liners with certified food-contact safety and moisture/oxygen barrier properties to preserve perishable goods. Strict EFSA and FDA regulations drive the adoption of higher-grade materials.
- Pharmaceuticals:Demand is high for sterile, high-barrier liners that protect temperature-sensitive biologics and active ingredients. European hubs like Germany and Switzerland are key markets for advanced pharmaceutical logistics.
- E-commerce:Online retail drives demand for protective liners that ensure product safety and reduce damage during last-mile delivery to consumers.
- Electronics:This segment utilizes liners for shock absorption and anti-static properties, safeguarding delicate components during transit and storage.
Food & Beverage represents the largest end-user segment, with Pharmaceuticals exhibiting the steepest expansion trajectory.
Application:
Application segmentation highlights how different customer needs influence liner design, from basic transit protection to specialized functional requirements. Each application addresses a distinct operational challenge.
- Protection:This fundamental application focuses on preventing physical damage, contamination, or leakage of contents during shipping and handling. It is a universal requirement across all end-user industries.
- Insulation:Thermal liners manage temperature fluctuations, crucial for maintaining the cold chain for perishables like food, biologics, and pharmaceuticals. Demand is high in emerging markets with nascent cold chain infrastructure.
- Packaging:Liners integrate within primary and secondary packaging structures, enhancing product presentation and ensuring containment for various consumer goods.
- Customization:This application involves tailoring liner dimensions, barrier properties, or printing to meet unique product specifications or branding requirements.
Protection forms the mature core of liner applications, while Insulation exhibits significant growth potential in specialized logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for carton liners concentrates in regions with robust e-commerce growth and stringent regulatory frameworks for food and pharmaceuticals. These factors drive the need for specialized packaging solutions to ensure product integrity during transit. Key markets are thus influenced by both consumer behavior and regulatory compliance.
United States
United States demand for carton liners stems from its expansive e-commerce sector and large food & beverage industry. The FDA's stringent regulations for food contact materials necessitate high-performance liner adoption. Major logistics hubs in states like California and Texas drive significant consumption for protective and specialized packaging.
Germany
Germany exhibits strong demand for high-barrier carton liners, particularly within its advanced pharmaceutical and food processing sectors. European regulations like EFSA guidelines and REACH dictate material safety and composition for packaging. The Rhine-Main region, including Frankfurt, serves as a central hub for pharmaceutical logistics requiring specialized protective inserts.
China
China's burgeoning e-commerce market and expanding cold chain infrastructure propel substantial carton liner consumption. The NMPA's evolving standards for pharmaceutical packaging and GB standards for food contact materials influence material selection. Industrial clusters in the Yangtze River Delta and Pearl River Delta drive massive logistics volumes for diverse goods.
Switzerland
Switzerland's pharmaceutical industry, a global leader, generates significant demand for sterile and high-barrier carton liners. Swissmedic's strict oversight on medical device and pharmaceutical packaging mandates premium material use. Basel and Zurich function as critical biopharmaceutical centers where temperature-sensitive products require advanced thermal protection.
India
India's rapidly expanding e-commerce landscape and developing cold chain infrastructure increase the need for protective carton liners. The FSSAI's food safety standards and BIS certifications are increasingly shaping material choices for packaging. Metropolitan areas like Mumbai and Delhi are key consumption centers for both consumer goods and pharmaceutical logistics.
Carton Liners Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized and sustainable material solutions, particularly in response to evolving regulatory landscapes. The market structure is tiered, with large integrated paperboard manufacturers coexisting with niche flexible liner specialists. Strategic archetypes include vertically integrated material suppliers and focused packaging innovators. Companies engage in portfolio diversification and geographic expansion, alongside strategic partnerships, to capture market share across diverse end-user segments.
At the scale-driven end, International Paper and WestRock exemplify companies leveraging extensive paperboard integration to serve high-volume accounts across multiple industries. These global entities anchor a significant portion of the market through their broad manufacturing capabilities and comprehensive product portfolios. Sealed Air Corporation represents a specialist in high-performance flexible liners, differentiating through protective packaging innovations for demanding applications. This company's focus on advanced material properties caters to sensitive applications requiring superior product protection and compliance with strict standards.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Mondi |
| Inteplast Group |
| Huhtamaki |
| International Paper |
| WestRock |
| Encore Poly |
| Smurfit Kappa |
| Others |
Cost & Logistics Intelligence
The clear performance divergence between advanced, certified liners and bulk commodity liners dictates distinct pricing models and supply chain structures. This bifurcation influences material sourcing, production capacities, and distribution networks across the market.
Pricing Analysis
High-volume commodity segments operate on thin margins, while specialized, high-performance liners command premium pricing. The dominant pricing model is per-unit transactional for standard products, shifting to contract-based long-term offtake for customized solutions. Price differentiation stems from certification levels, particularly FDA and EFSA compliance, and the degree of customization. Cost compression in flexible liners is intensifying due to polyethylene resin volatility. Bulk food packaging end-users exhibit the highest price sensitivity, whereas pharmaceutical logistics buyers prioritize performance over cost.
Supply Chain Analysis
Strict regulatory environments often necessitate dual-sourcing strategies, particularly for pharmaceutical and food contact liners. Global supply of carton liner materials draws from manufacturing hubs in China, Germany, and the United States. Key raw material dependencies include polymer resins, especially polyethylene, and wood pulp for paperboard liners. Raw material volatility represents a significant structural risk across the supply chain. Distribution runs through direct sales channels for major industrial accounts and specialized packaging distributors for diverse smaller buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carton liners market operates under supply constraints, particularly for advanced barrier materials, where specialized manufacturing capacity props up pricing.
For Market Incumbents:Deepen backward integration into polymer resin or paperboard production to mitigate raw material volatility and secure supply. Incumbents should also invest heavily in R&D for advanced, sustainable materials to counter substitution threats from integrated packaging. Certification investment for new material formulations strengthens market position against evolving FDA and EFSA regulations. This strategy defends against margin erosion and enhances long-term competitive advantage.
For New Entrants and Emerging Players:Begin with niche applications requiring advanced material properties, such as bio-based or active liners. Target specialized e-commerce segments for perishable goods, which represent a highly penetrable market. Focus on developing certified compostable solutions, particularly for European markets driven by single-use plastic regulations. A direct-to-consumer go-to-market angle can bypass traditional distribution complexities and build brand loyalty quickly.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized material science firms or regional packaging innovators with strong intellectual property. The carton liners market offers long-term viability as critical infrastructure for global logistics and product protection. Target companies with proven expertise in bio-based, compostable, or active packaging solutions. A key signal to watch is the accelerating adoption rates of mono-material recyclable films across major food and pharmaceutical brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-based Liners | Addresses EU Green Deal mandates and growing consumer demand for sustainable packaging materials. |
| R&D in Active Packaging Technologies | Extends shelf life of perishable foods and pharmaceuticals, creating a new premium product tier. |
| Geographic Expansion into Emerging Cold Chains | Captures demand for thermal protection in nascent logistics infrastructure in Southeast Asia. |
| Investment in Recyclable Mono-Material Films | Complies with evolving EU single-use plastic directives and enhances circularity claims for flexible packaging. |
| Strategic Partnerships with E-commerce Platforms | Secures high-volume accounts and tailors protective liner solutions for last-mile delivery challenges. |
Research Approach
Multi-period observation of material consumption trends and regulatory compliance rates anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary interviews included packaging engineers, procurement managers, logistics heads, and regulatory compliance officers. Secondary validation drew from FDA filings, EFSA reports, customs data, and company annual reports. This approach employed both bottom-up market sizing and top-down validation for robust data triangulation.
An input-output matrix structured the quantitative forecasting, mapping raw material supply to end-user demand across the analysis window. Segmentation modeled product type, material, end-user, application, and regional regulatory cluster. Compound annual growth rates were derived from regression analysis of historical trends and projected market drivers. Key inputs included e-commerce growth rates and pharmaceutical R&D spending, influencing future demand.
Underlying measurement precision varies by segment; flexible liners and food & beverage applications carry tighter precision than others. Forecasts reflect assumptions concerning raw material stability and evolving regulatory landscapes. Deviation in raw material price shocks or new regulatory mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
GCC Folding Carton Market
Cartons
Digital Folding Cartons Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Litho Laminated Cartons Market
Cartons
Round Corrugated Box Market
Cartons
Brick Liquid Carton Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Child-Resistant Carton Box Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
Global Open Top Cartons Market
Cartons
Carton Serialization Machine Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Fully Enclosed Cartons Market
Cartons
Brick Carton Packaging Market
Cartons
Global Hand Carton Sealers Market
Cartons
Carton Bottle Market