
 Child-Resistant Carton Box Market | 2026-2036
Child-Resistant Carton Box Market Size, Share, and Industry Trends Forecast 2026-2036
Child-Resistant Carton Box Market Analytics
Single-source to multi-source procurement is recalibrating how pharmaceutical and household brands secure child-resistant carton supply. Amcor plc leverages its global manufacturing footprint to offer integrated material-to-closure solutions across multiple regulatory zones. WestRock Company anchors North American production with specialized paperboard laminates that meet FDA child-resistance protocols. Smurfit WestRock plc competes through European fiber-based expertise, combining recycled content streams with certified push-and-turn mechanisms.
Child-resistant carton boxes are engineered paperboard or composite structures incorporating specialized closure interfaces that require coordinated manual dexterity to open, typically tested under ISO 8317 and 16 CFR 1700 protocols to prevent access by children under five while maintaining adult usability. The primary purpose is to package pharmaceuticals, cannabis products, and hazardous household chemicals in jurisdictions where poison prevention mandates apply. Rigid and semi-rigid formats dominate current volume due to structural integrity requirements in pharmaceutical distribution, while flexible variants represent the fastest-growing category as cannabis and wellness brands seek portable, compliant formats. Closure mechanism selection increasingly determines margin pools, with push-and-turn systems commanding premium positioning against simpler snap-on alternatives.
The US FDA enforces 16 CFR 1700 through CPSC coordination, while the EU applies EN 862 and ISO 8317 through national standards bodies in Germany and France, collectively elevating testing documentation burdens for market entry. EMA guidance on pediatric safety and REACH chemical restrictions further constrain material choices for European suppliers. Stakeholders must monitor evolving state-level cannabis packaging laws in the US and emerging biodegradable certification requirements in EU member states to anticipate specification shifts before they harden into procurement mandates.
Market Dynamics
Regulatory enforcement divergence between jurisdictions is fragmenting compliance pathways and forcing manufacturers to maintain parallel certification portfolios rather than unified global designs.
Growth Catalysts
- Poison Prevention Packaging Act enforcement:The US FDA's 16 CFR 1700 mandates are tightening testing protocols for pharmaceutical cartons, compelling brand owners to upgrade closure systems and expand certified supplier rosters.
- Cannabis legalization waves:State-level cannabis packaging laws in the US and Canada's federal framework are generating fresh demand for child-resistant formats across edibles and concentrates categories.
- Fiber-based material substitution:Brand sustainability commitments are displacing plastic blister packs with paperboard cartons that incorporate compliant push-and-turn mechanisms.
Market Restraints
- Pulp price volatility:Kraft linerboard and coated recycled board inputs fluctuate with energy costs and fiber availability, compressing margins for converters without long-term supply contracts.
- Testing laboratory concentration:ISO 8317 and 16 CFR 1700 certification capacity clusters in Germany, the US, and Japan, creating bottlenecks for new market entrants seeking multi-jurisdiction approval.
- Closure mechanism patent thickets:Proprietary push-and-turn and squeeze-and-turn designs from established suppliers limit design freedom for emerging carton manufacturers.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO-aligned packaging requirements for pediatric formulations create demand for certified carton suppliers serving contract manufacturing organizations in Gujarat and Maharashtra.
- Biodegradable closure integration:EU Green Deal and national plastic reduction targets in France and Italy incentivize fiber-based locking mechanisms that eliminate petroleum-derived components.
- E-commerce direct-to-patient channels:Pharmacy fulfillment networks require secondary child-resistant overwraps, opening specification roles for carton converters previously excluded from primary packaging decisions.
Industry Challenges
- Human-factors engineering talent scarcity:Designers capable of balancing ISO 8317 child-resistance testing with senior adult usability studies command premium compensation and extend development timelines.
- Multi-jurisdiction certification synchronization:Divergent testing protocols between the US CPSC, Germany's BfR, and Japan's PMDA force redundant validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child-Resistant Carton Box Market |
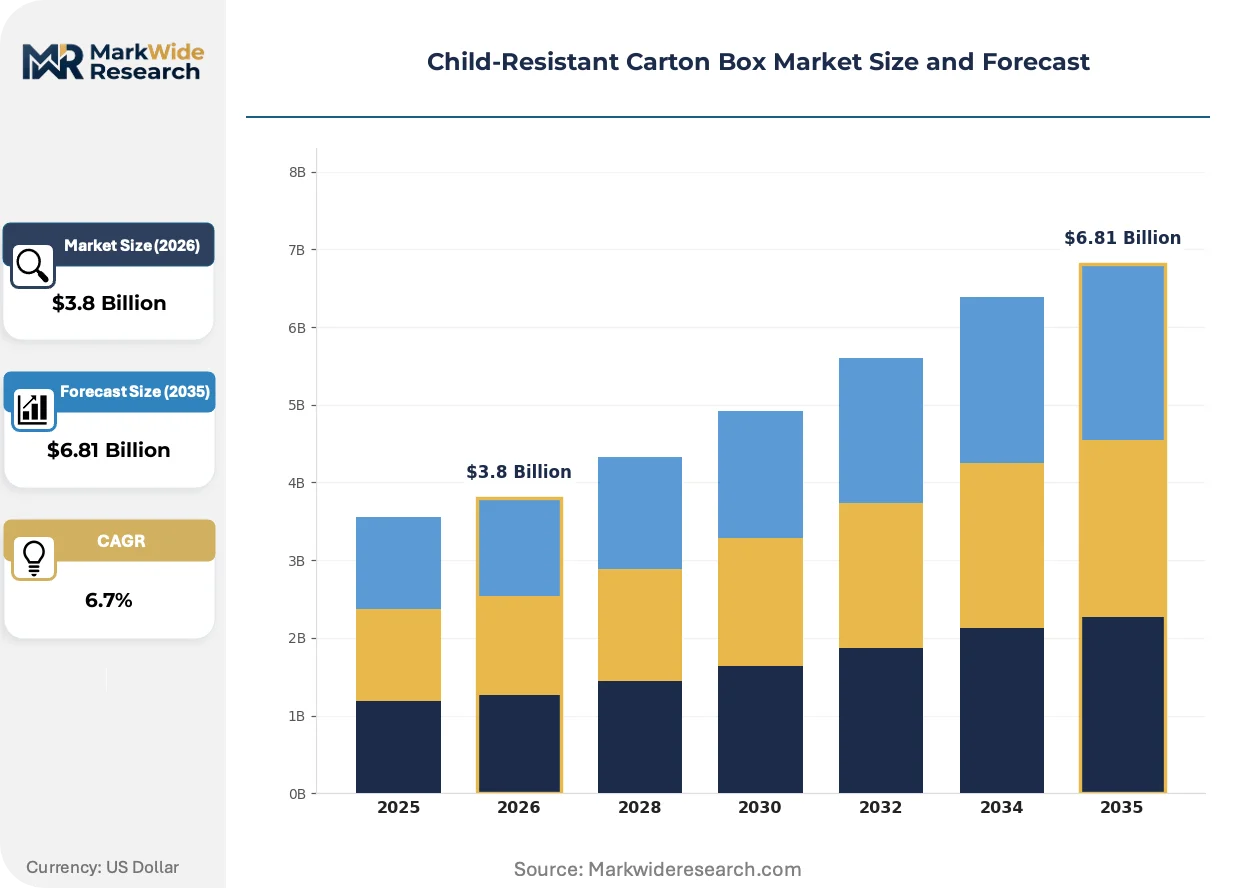
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid, Semi-Rigid, Flexible, Composite End User: Pharmaceuticals, Food & Beverage, Personal Care, Household Products Closure Mechanism: Push-and-Turn, Slide, Flip-Top, Snap-On Material: Paperboard, Plastic, Metal, Biodegradable |
| Companies Covered | Amcor plc, WestRock Company, Gerresheimer AG, Berry Global Group, Inc., Winpak Ltd, AptarGroup, Inc., Smurfit WestRock plc, Bilcare Limited, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child-Resistant Carton Box Market Evolving Landscape
Closure-to-carton integration is advancing from mechanical add-ons to engineered fiber structures, compressing assembly steps and altering converter value capture models.
Push-and-turn fiber mechanisms are consolidating as the dominant compliant format for pharmaceutical and cannabis applications. Brand owners in North American markets are specifying these systems for portable dose formats. This consolidation is compressing demand for simpler snap-fit alternatives and elevating suppliers with in-house tooling capabilities.
REACH chemical restrictions and ECHA substance of very high concern listings are constraining adhesive and coating selections for European-bound cartons. Manufacturers are reformulating closure bonding agents to eliminate restricted phthalates and heavy metal pigments. German and French suppliers are responding fastest, leveraging existing sustainability certification infrastructure to document compliance.
Brand procurement departments are consolidating supplier panels from fragmented regional converters toward integrated material-to-closure providers. This concentration is displacing standalone carton printers who previously outsourced certification testing. The shift is most visible among mid-tier pharmaceutical firms in the US Northeast and Rhineland industrial corridors.
Child-Resistant Carton Box Market Segmentation
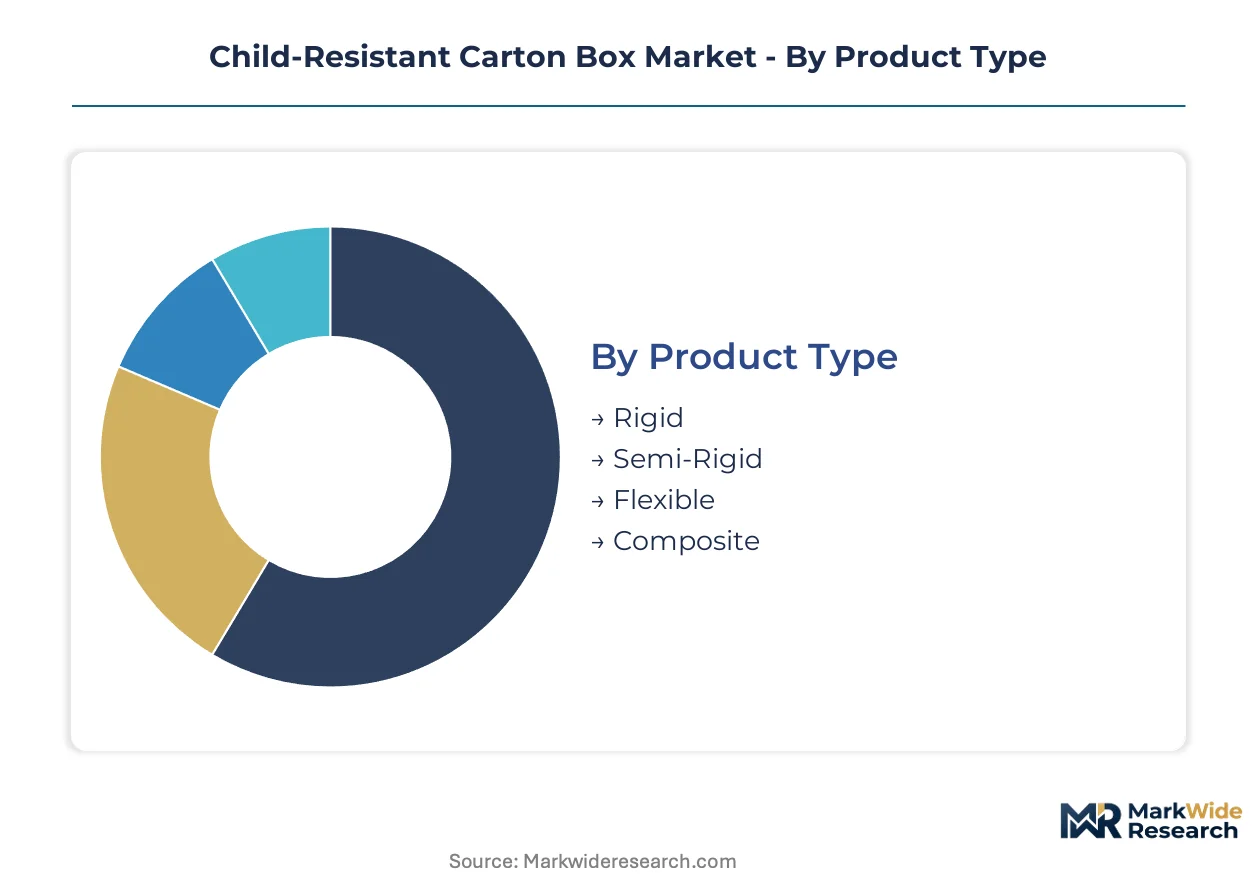
Child-resistant carton box procurement hinges on matching structural formats to regulatory testing protocols and end-use handling requirements. Each segmentation dimension carries distinct margin implications and certification burdens that shape supplier selection.
Product Type:
Standardization dominates high-volume pharmaceutical runs, while customization concentrates in cannabis and wellness segments requiring brand differentiation.
- Rigid:Multi-ply paperboard constructions with structural inserts maintain dimensional stability through distribution. Demand clusters in US pharmaceutical corridors where FDA 16 CFR 1700 testing mandates structural integrity for unit-dose packaging.
- Semi-Rigid:Controlled-deflection boards balance protection with reduced material weight. German and French pharmaceutical contract manufacturers specify these formats for blister pack enclosures to optimize shipping cube efficiency.
- Flexible:Fiber-based laminates with compliant closure interfaces serve portable cannabis edible formats. Canadian licensed producers drive specification evolution for single-serve compliance.
- Composite:Hybrid paperboard-plastic structures integrate rigid bases with flexible lids. Japanese PMDA-aligned pharmaceutical packaging uses these for complex multi-dose regimens.
Leading the category by volume: Rigid. Growing fastest: Flexible.
End User:
Regulatory intensity varies sharply across end-use categories, with pharmaceutical and cannabis applications commanding premium pricing against consumer goods.
- Pharmaceuticals:Prescription and over-the-counter medications require ISO 8317 or 16 CFR 1700 certification. US, German, and Japanese regulators enforce the strictest testing documentation, elevating supplier qualification costs.
- Food & Beverage:Cannabis-infused edibles and concentrates in North American jurisdictions mandate child-resistant formats. State-level US cannabis laws generate fragmented specification demand.
- Personal Care:Nicotine replacement therapies and certain cosmetic formulations trigger poison prevention requirements. European ECHA guidance on nicotine concentration thresholds shapes compliance scope.
- Household Products:Laundry pods, cleaning concentrates, and automotive chemicals fall under CPSC jurisdiction in the US. Retailer sustainability mandates accelerate fiber-based substitution for plastic containers.
Pharmaceuticals capture the largest revenue pool. Food & Beverage climbs fastest on cannabis normalization.
Closure Mechanism:
Patent-protected designs from established suppliers constrain new entrants, while open-source mechanisms enable regional converter participation.
- Push-and-Turn:Coordinated dual-motion interfaces require simultaneous depression and rotation. This mechanism commands the widest regulatory acceptance across FDA, EMA, and PMDA jurisdictions.
- Slide:Linear displacement with concealed release points suits blister pack formats. German pharmaceutical packaging specialists favor these for senior-friendly usability profiles.
- Flip-Top:Hinged lids with secondary locking tabs serve household chemical applications. US-based cleaning product brands specify these for ergonomic handling.
- Snap-On:Simple interference-fit closures offer lowest cost but narrowing regulatory acceptance. Limited to non-pharmaceutical applications in most developed markets.
Push-and-Turn dominates certified pharmaceutical volume. Slide mechanisms gain fastest in senior-accessibility redesigns.
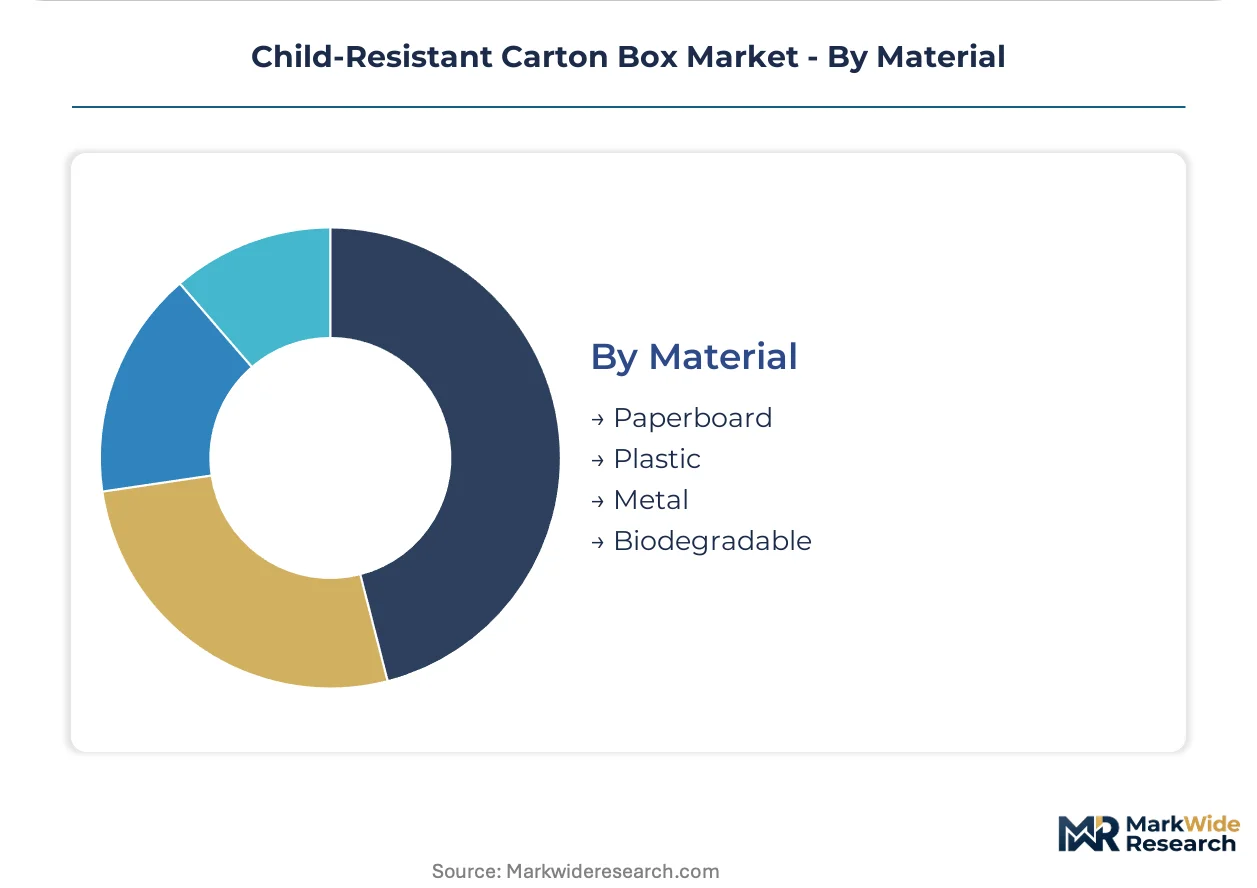
Material:
Sustainability commitments and chemical restriction lists are rewiring material procurement priorities across all end-use segments.
- Paperboard:Coated recycled board and solid bleached sulfate grades provide printable surfaces with structural rigidity. EU Green Deal targets and France's anti-waste law accelerate fiber-based adoption.
- Plastic:Polypropylene and polystyrene components persist in closure mechanisms and window films. REACH SVHC listings and ECHA restrictions on phthalates drive reformulation mandates.
- Metal:Tinplate and aluminum inserts provide tamper-evidence and barrier properties. Japanese pharmaceutical cold-chain packaging retains metal components for stability.
- Biodegradable:Fiber-based locking mechanisms and bio-derived coatings eliminate petroleum content. Italian and French national plastic reduction targets create procurement pull for these materials.
Paperboard leads by installed volume. Biodegradable materials expand most quickly on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical packaging demand concentrates in regulatory jurisdictions with mature poison prevention enforcement, while cannabis legalization generates secondary growth corridors in North American and select European markets.
United States
FDA's 16 CFR 1700 enforcement drives pharmaceutical carton upgrades across prescription and over-the-counter segments. State-level cannabis packaging laws in California, Colorado, and Illinois create fragmented but substantial demand for compliant edible and concentrate formats. New Jersey and Massachusetts pharmaceutical corridors anchor East Coast procurement clusters serving generic drug manufacturers.
Germany
BfR-administered EN 862 standards elevate testing documentation burdens for carton suppliers serving European pharmaceutical distribution. REACH chemical restrictions constrain adhesive selections for closure bonding, pushing converters toward fiber-based locking mechanisms. The Rhineland industrial corridor hosts specialized paperboard laminators supplying contract manufacturers across the EU single market.
Japan
PMDA-aligned cold-chain stability requirements sustain demand for composite paperboard-metal hybrid structures in multi-dose pharmaceutical packaging. METI industrial standards on senior accessibility shape closure mechanism specifications for aging demographics. The Kanto region around Tokyo concentrates domestic converter capacity serving domestic and export pharmaceutical firms.
India
CDSCO packaging requirements for pediatric formulations expand as contract manufacturing organizations in Gujarat and Maharashtra scale export production. Domestic pharmaceutical growth drives demand for ISO 8317-certified carton suppliers capable of supporting ANDA filings. The Ahmedabad-Surat corridor emerges as a procurement hub for North American and European generic drug brands.
Canada
Federal cannabis packaging regulations under Health Canada mandate child-resistant formats across licensed producer supply chains. Provincial distribution monopolies in Ontario, Quebec, and British Columbia standardize procurement specifications, reducing supplier fragmentation. Toronto and Vancouver metropolitan areas concentrate cannabis packaging demand as product formats diversify beyond dried flower.
Child-Resistant Carton Box Market Competitive Landscape
Strategic partnerships dominate the current landscape as converters seek integrated material-to-certification capabilities without captive testing infrastructure. The vendor base organizes around three tiers: multinational integrated packaging groups with parallel FDA-EMA-PMDA certification portfolios, regional specialists leveraging single-jurisdiction regulatory expertise, and emerging converters serving cannabis and wellness segments with faster design cycles. Two competitive moves define positioning: geographic expansion through distribution partnerships in high-growth Asian markets, and technology licensing agreements that bypass proprietary closure patent thickets.
Among integrated multinational groups, Amcor plc, WestRock Company, and Smurfit WestRock plc occupy positions spanning material supply through certified closure integration. Amcor exemplifies the global footprint archetype with manufacturing presence across multiple regulatory zones. WestRock anchors North American production specialization. Smurfit WestRock represents European fiber-based expertise combined with recycled content streams. These three entities sit within the premium tier where certification breadth and tooling capabilities determine procurement access.
| Leading Market Players |
|---|
| Amcor plc |
| WestRock Company |
| Gerresheimer AG |
| Berry Global Group, Inc. |
| Winpak Ltd |
| AptarGroup, Inc. |
| Smurfit WestRock plc |
| Bilcare Limited |
| Constantia Flexibles |
| Others |
Value Network & Pricing Analysis
Pharmaceutical procurement consolidation toward integrated material-to-closure providers is compressing margins for standalone carton converters and elevating pricing power among certified suppliers with in-house tooling capabilities. Brand owners now demand parallel FDA-EMA-PMDA certification portfolios, forcing supply base rationalization that concentrates volume with fewer vendors capable of multi-jurisdiction compliance.
Pricing Analysis
Volume splits between high-run pharmaceutical contracts and low-run cannabis customization create divergent margin structures across the supplier base. Three-tier pricing stratification separates premium push-and-turn certified systems from standard semi-rigid formats and economy snap-on alternatives used in non-regulated household applications. Price differentiation hinges on certification breadth and closure mechanism complexity, with FDA 16 CFR 1700 testing documentation commanding substantial premiums. Cost compression in economy tiers is intensifying as pulp price volatility and energy costs squeeze converters without long-term fiber supply contracts. Generic drug manufacturers in India and mid-tier cannabis brands exhibit highest price sensitivity, while patented pharmaceutical firms in the US and Japan prioritize certification reliability over unit cost.
Supply Chain Analysis
Return flows of non-compliant packaging from failed certification cycles create reverse-logistics burdens that specialized converters absorb as qualification costs rather than pass-through charges. Raw material supply concentrates in the United States, Germany, and Japan where kraft linerboard mills and coated recycled board producers cluster near pharmaceutical manufacturing corridors. Closure mechanism production draws from polypropylene and polystyrene resin streams, with REACH chemical restrictions constraining European adhesive selections. Single-source vulnerability in ISO 8317 testing laboratory capacity creates bottlenecks for new market entrants seeking multi-jurisdiction approval. Distribution runs through direct pharmaceutical supply agreements and specialized packaging distributors serving cannabis licensed producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as multi-jurisdiction certification requirements and proprietary closure patent thickets force regional converters without testing infrastructure toward exit or acquisition.
For Market Incumbents: Lock in certification breadth by securing parallel FDA-CPSC, BfR-EN 862, and PMDA testing documentation before specification mandates harden into procurement requirements. Deepen backward integration into fiber sourcing and push-and-turn tooling production to defend against pulp price volatility and patent-licensing costs that erode margin pools in high-volume pharmaceutical contracts. For New Entrants and Emerging Players: The gap between premium certified pharmaceutical systems and economy household formats offers white-space opportunity for mid-tier converters serving cannabis wellness brands and Indian pharmaceutical exporters. Target flexible format specifications for Canadian cannabis edibles and semi-rigid blister pack enclosures for German contract manufacturers. Lead with faster design cycles and biodegradable closure alternatives that bypass established patent thickets. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing single-jurisdiction certification depth and sustainable material expertise given EU Green Deal procurement mandates and national plastic reduction targets. Long-term viability favors converters with demonstrated ISO 8317 testing relationships and fiber-based locking mechanism R&D pipelines. Monitor state-level US cannabis packaging law harmonization and CDSCO enforcement intensity in India as inflection indicators for specification standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Closure Integration | Eliminates petroleum-derived components to meet France and Italy plastic reduction mandates. |
| Multi-Jurisdiction Certification Expansion | Parallel FDA-EMA-PMDA portfolios unlock procurement access across US, German, and Japanese pharmaceutical corridors. |
| Fiber-Based Material Substitution | Replaces plastic blister packs with paperboard cartons aligned to EU Green Deal sustainability commitments. |
| Testing Laboratory Partnership | Secures ISO 8317 and 16 CFR 1700 capacity in Germany, US, and Japan to bypass certification bottlenecks. |
| E-Commerce Secondary Overwrap Development | Captures pharmacy fulfillment network specifications previously excluded from primary packaging decisions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced against primary interviews with packaging procurement managers, regulatory affairs directors at pharmaceutical firms, carton converter operations heads, and certification laboratory technical leads. Bottom-up volume estimates from fiber grade consumption and top-down pharmaceutical packaging expenditure analysis were reconciled through triangulation. FDA 16 CFR 1700 enforcement records, EMA pediatric safety guidance documents, and CDSCO packaging notifications provided regulatory scope validation.
Data-stream reconciliation across shipment volumes, certification issuance rates, and end-use procurement surveys informed the analytical framework across the projection horizon. Segmentation modeling incorporated product type rigidity, closure mechanism complexity, end-use regulatory intensity, and material sustainability credentials. CAGRs were derived from trend extrapolation of certification demand and pharmaceutical export growth patterns. Pulp price indices and energy cost trajectories informed input cost assumptions.
Inputs from customs records and trade association databases were available through the study window; gaps in real-time cannabis packaging specification data from fragmented US state markets introduce uncertainty bands around flexible format growth estimates. Forecasts reflect assumptions on regulatory enforcement continuity and fiber substitution rates. Practitioners should monitor REACH SVHC listing expansions and Indian CDSCO pediatric packaging mandate implementation for early signals of specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
XXL Packaging Market
Cartons
Luxury Folding Carton Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
Africa Folding Carton Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Cupcake Box Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Microwaveable Carton Market
Cartons
Pick and Place Carton Packers Market
Cartons
Carton Serialization Machine Market
Cartons
Global Open Top Cartons Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Global Crash Lock Bottom Cartons Market