
 Carton Bottle Market | 2026-2036
Carton Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Carton Bottle Market Outlook
Small-format beverage startups is redrawing procurement priorities across the carton bottle value chain. Tetra Pak International S.A. leverages its aseptic filling technology leadership to anchor premium dairy and juice applications. SIG Combibloc Group AG competes through modular filling systems that reduce line changeover times for mid-tier co-packers. Elopak AS specializes in fresh dairy carton bottles with screw-cap closures, occupying a defensible niche in European retail channels.
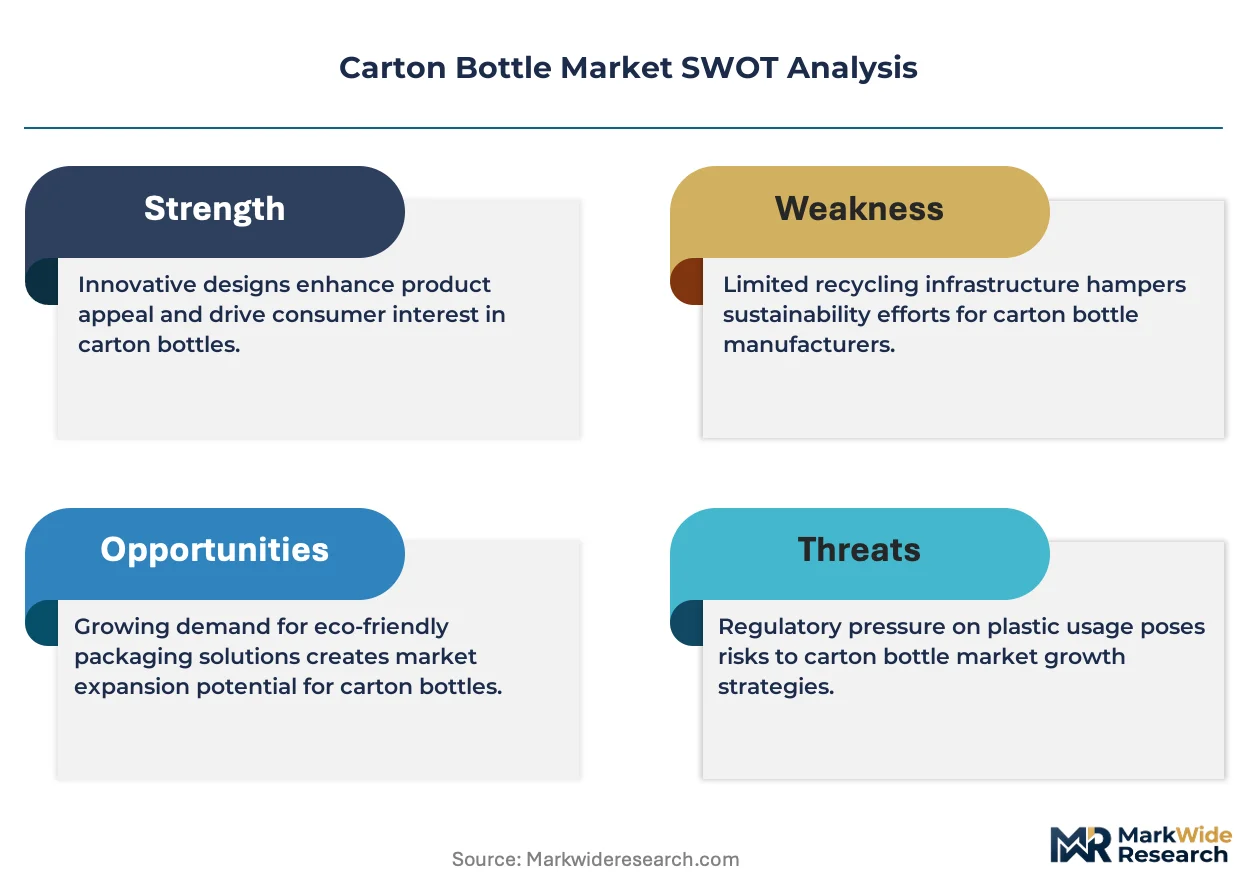
A carton bottle is a fiber-based rigid container formed from laminated paperboard, typically comprising 70-80% renewable paper fiber with aluminum and polymer barrier layers, designed for liquid containment with resealable functionality. Liquid cartons sustain the largest revenue pool due to entrenched dairy and juice infrastructure, while composite cartons represent the fastest structural expansion as brands seek plastic replacement in non-dairy beverages. Biodegradable material formulations command emerging margin premiums despite current scale constraints against conventional paperboard substrates.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications collectively shape material compliance pathways, with EFSA migration limits for mineral oil saturated hydrocarbons directly influencing barrier layer specifications. Germany's national packaging ordinance enforces strict dual-system participation fees that reward lighter fiber formats over glass alternatives. Stakeholders must monitor evolving extended producer responsibility fee structures to determine optimal regional production footprints and material certification investments.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing plastic bottle volumes while fiber-based alternatives capture liquid food and beverage shelf space, restructuring converter capacity investments across the continent.
Growth Catalysts
- EFSA migration limits:Tightened mineral oil saturated hydrocarbon thresholds under EU food-contact frameworks are compelling brands toward advanced barrier laminates in carton bottles.
- Fresh dairy screw-cap adoption:European retailers are expanding resealable carton bottle SKUs for extended shelf-life milk and plant-based alternatives.
- German dual-system fees:Packaging ordinance participation costs favor lighter fiber formats over glass, accelerating carton bottle penetration in discount retail channels.
Market Restraints
- Aluminum barrier supply concentration:Thin-gauge foil sourcing depends on a limited set of European rolling mills, creating input vulnerability.
- Polymer layer technical limitation:Current polyethylene tie-layers constrain heat-seal performance in high-speed aseptic lines above 24,000 units per hour.
- REACH substance authorization:Fluorinated barrier chemistries face sunset clause pressure, forcing premature material transitions.
Strategic Opportunities
- Polish retail modernization:Underserved discount and convenience channels in Central Europe present carton bottle white space as private-label beverage programs expand.
- Plant-based drink convergence:Oat and almond milk brands seek plastic-free packaging differentiation, opening premium carton bottle slots.
- EU Green Deal procurement incentives:Public sector catering and institutional food service contracts now specify renewable packaging quotas.
Industry Challenges
- Aseptic filling engineering scarcity:Qualified technicians for complex carton bottle line commissioning remain concentrated with original equipment manufacturers.
- Migration testing certification timelines:EFSA novel food contact notifications require 18-24 month validation cycles, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carton Bottle Market |
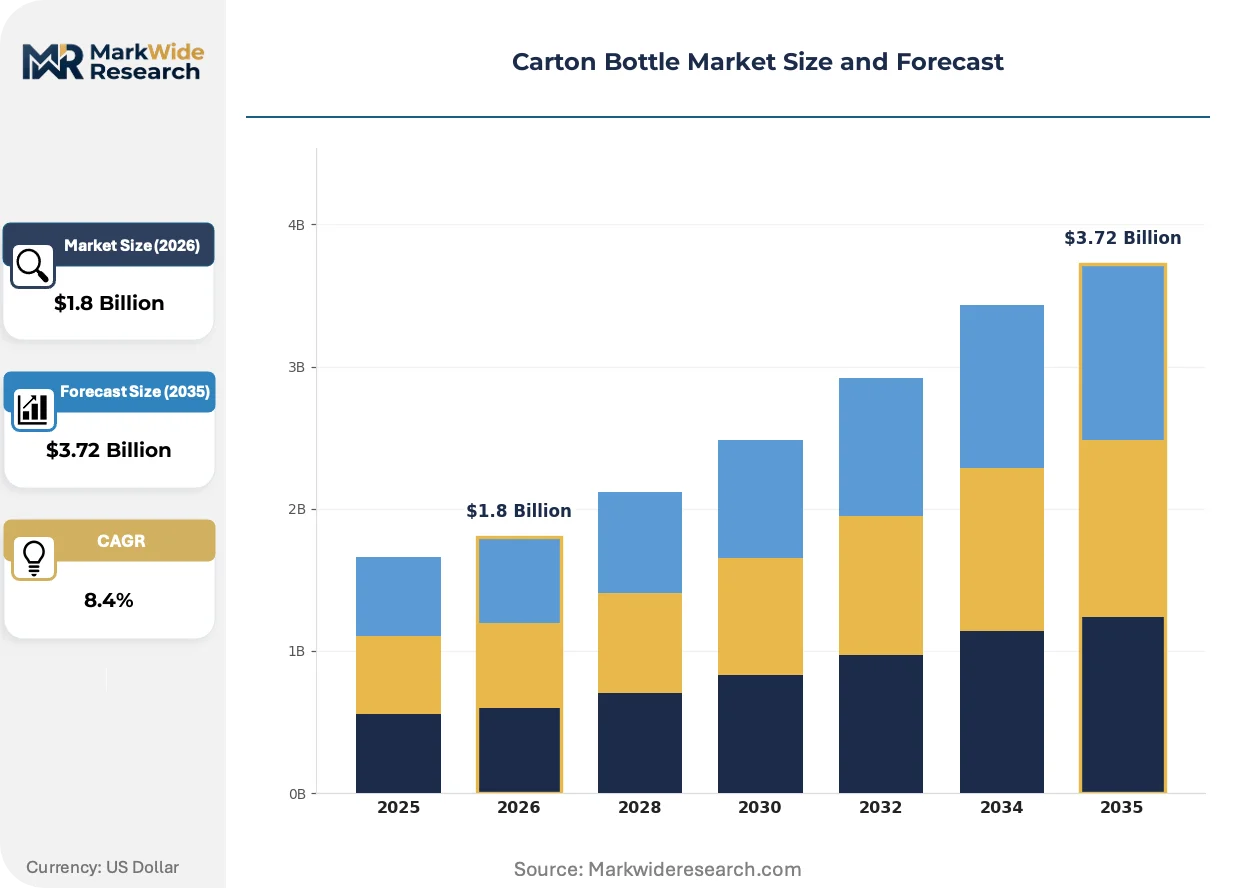
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cartons, Dry Cartons, Composite Cartons, Foldable Cartons Material: Cardboard, Paperboard, Recycled Fiber, Biodegradable Materials End User: Beverage Industry, Healthcare, Personal Care, Food Packaging Size: Small, Medium, Large, Extra Large |
| Companies Covered | Tetra Pak International S.A., SIG Combibloc Group AG, Elopak AS, Pactiv Evergreen Inc., Greatview Aseptic Packaging Co. Ltd., Mondi, WestRock Company, Nippon Paper Industries Co. Ltd., Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carton Bottle Market Strategic Shifts
Barrier material science and filling equipment integration are compressing cost premiums against conventional plastic bottles while regulatory compliance automation reshapes converter operations.
High-barrier bio-polymer coatings are displacing conventional aluminum laminates in ambient-stable juice applications. Mid-tier beverage co-packers in Spain and Italy are piloting these substrates for private-label programs. The displacement is collapsing the historical cost gap between carton bottles and multilayer PET for short-run SKUs.
REACH substance restriction proposals are forcing reformulation roadmaps across European barrier suppliers. Industrial consequence includes accelerated R&D spending on mineral oil-free adhesives and alternative oxygen scavengers. Fresh dairy applications face the steepest compliance burden due to stringent shelf-life requirements.
Retailers are consolidating beverage suppliers around packaging formats that satisfy extended producer responsibility reporting automation. German and Dutch supermarket chains now require digital product passport compatibility from carton bottle providers. This procurement compression favors converters with integrated compliance data infrastructure over fragmented regional suppliers.
Carton Bottle Market Segmentation
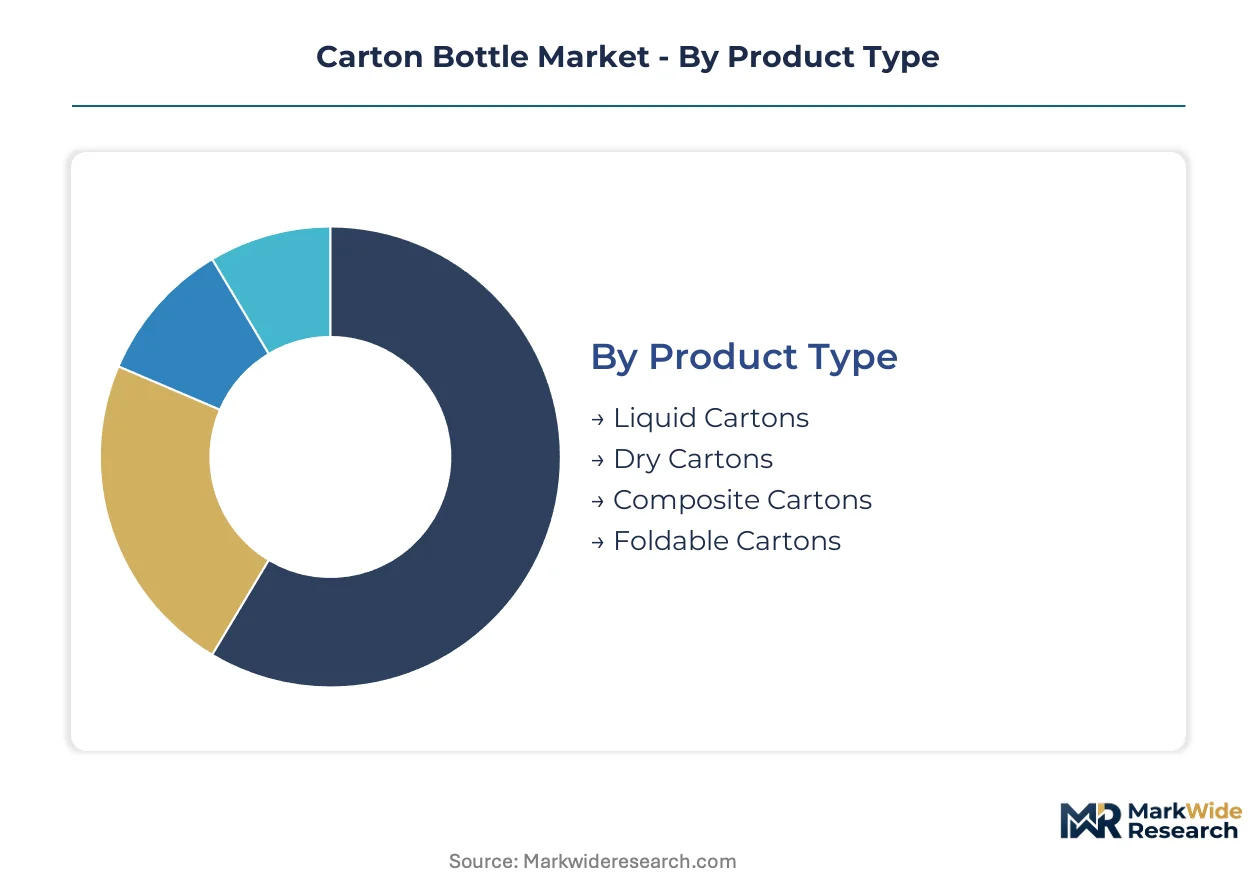
Carton bottle segmentation reveals divergent margin structures across material grades and filling technologies. Understanding where value concentrates helps converters align capacity investments with regulatory-driven demand shifts.
Product Type:
Liquid cartons command the deepest margin pools due to aseptic filling complexity and dairy sector entrenched demand.
- Liquid Cartons:Fiber-based containers with aluminum-polymer barrier laminates engineered for liquid containment across ambient and chilled distribution. Dairy and juice processors in Germany anchor demand, though EFSA mineral oil migration limits are forcing laminate reformulation investments.
- Composite Cartons:Hybrid structures combining paperboard with bio-polymer or thin-gauge foil barriers for non-dairy beverages. Oat and almond milk brands seeking plastic-free differentiation are rotating capacity toward this format fastest.
- Dry Cartons:Single-wall paperboard constructions without liquid barrier requirements for powdered goods and dry food applications.
- Foldable Cartons:Collapsible designs for logistics efficiency in e-commerce beverage fulfillment and secondary packaging.
Liquid cartons hold installed capacity. Composite cartons are rotating up the share rankings.
Material:
Raw material cost tiers stratify sharply between virgin paperboard and certified biodegradable substrates.
- Paperboard:Virgin fiber substrates with 70-80% renewable content forming the structural backbone of conventional carton bottles. German discount retail channels favor this grade for dual-system fee optimization.
- Biodegradable Materials:Bio-polymer coatings and mineral oil-free adhesives meeting EU Green Deal procurement specifications. Public sector catering contracts in the Netherlands specify these substrates, though scale constraints against conventional paperboard persist.
- Cardboard:Lower-grade recycled content packaging for secondary containment and non-food applications.
- Recycled Fiber:Post-consumer paperboard streams facing EFSA food-contact notification barriers for direct beverage contact.
Paperboard dominates tonnage throughput. Biodegradable materials are climbing the fastest on quota-driven procurement.
End User:
Application concentration follows beverage sector plastic replacement timelines and healthcare sterilization requirements.
- Beverage Industry:Water, juice, dairy, and plant-based drink containment representing the primary carton bottle deployment. Major retail chains in Germany have scaled pilot programs into standard assortment.
- Healthcare:Sterile liquid nutritional products and pharmaceutical solutions requiring aseptic barrier performance. EMA medical device regulations overlap with food-contact frameworks for enteral nutrition packaging.
- Personal Care:Shampoo, conditioner, and liquid soap applications pursuing plastic-free brand positioning.
- Food Packaging:Sauces, oils, and liquid condiments in ambient-stable formats.
Beverage applications hold installed capacity. Healthcare is rotating up the share rankings.
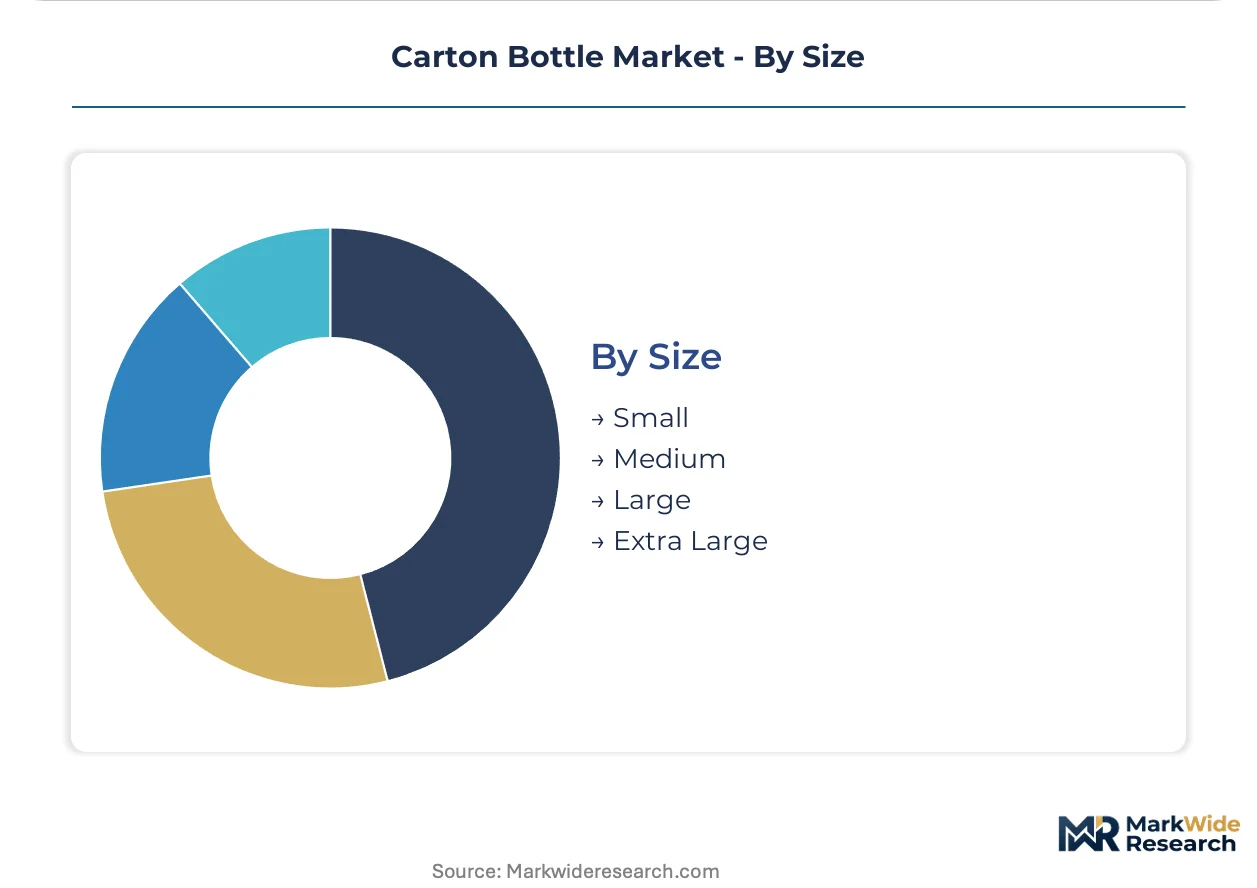
Size:
Format dimensions correlate with retail channel requirements and consumption occasion fragmentation.
- Small:Single-serve portions for convenience retail and on-premise consumption. Urban vending channels in German metropolitan areas favor this format.
- Medium:Standard household sizes for supermarket dairy and juice aisles. This format anchors converter line utilization rates.
- Large:Family-size and food-service volumes for institutional procurement. EU Green Deal catering contracts specify renewable packaging at this scale.
- Extra Large:Bulk dispensing and commercial kitchen applications with limited current carton bottle penetration.
Medium formats hold installed capacity. Small formats are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany, where dual-system fee structures and retail pilot programs have created the continent's deepest carton bottle infrastructure. Tetra Pak International S.A. and SIG Combibloc Group AG maintain their most concentrated European filling equipment and laminate production footprints across the German industrial corridor.
Germany
Discount retail chains and fresh dairy screw-cap adoption drive carton bottle procurement volumes. The national packaging ordinance enforces strict dual-system participation fees that reward lighter fiber formats over glass alternatives. Converter operations concentrate in North Rhine-Westphalia, where laminate rolling and aseptic line commissioning facilities serve pan-European beverage brands.
France
Plant-based drink brands and institutional catering contracts fuel demand for renewable packaging differentiation. The EU Green Deal procurement incentives now mandate renewable packaging quotas for public sector food service contracts. Industrial activity clusters in Île-de-France, where beverage co-packers pilot high-barrier bio-polymer laminates for ambient-stable juice applications.
Netherlands
Retail consolidation around digital product passport compatibility and EPR reporting automation shapes supplier selection criteria. EFSA migration limits for mineral oil saturated hydrocarbons directly influence barrier layer specifications for Dutch dairy processors. The Randstad region hosts pilot programs for biodegradable material formulations in public sector catering channels.
Poland
Underserved discount and convenience retail channels present carton bottle white space as private-label beverage programs expand. REACH substance authorization pressures on fluorinated barrier chemistries force premature material transitions among Polish converters. Industrial modernization concentrates in the Warsaw and Kraków metropolitan areas, where mid-tier co-packers invest in modular filling systems.
Italy
Mid-tier beverage co-packers pilot high-barrier bio-polymer coatings for private-label ambient-stable juice programs. EFSA novel food contact notification timelines create 18-24 month validation cycles that delay product launches for Italian converters. Packaging innovation clusters in Emilia-Romagna, where laminate suppliers reformulate mineral oil-free adhesives for fresh dairy applications.
Carton Bottle Market Competitive Environment
Concentration sits with diversified packaging conglomerates and specialized aseptic filling technology providers. The vendor base stratifies across three tiers: integrated multinational converters with captive equipment manufacturing, regional laminate specialists supplying barrier materials, and mid-tier co-packers operating licensed filling lines. Strategic moves center on barrier material reformulation partnerships and compliance data infrastructure investments.
Within the integrated converter tier, Tetra Pak International S.A. and SIG Combibloc Group AG exemplify aseptic filling technology leadership, while Elopak AS occupies a position among fresh dairy specialists with screw-cap closure expertise. These entities represent the dominant competitive archetypes—multinational technology integrators versus niche application specialists—each anchoring distinct margin pools across European retail channels.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| SIG Combibloc Group AG |
| Elopak AS |
| Pactiv Evergreen Inc. |
| Greatview Aseptic Packaging Co. Ltd. |
| Mondi |
| WestRock Company |
| Nippon Paper Industries Co. Ltd. |
| Oji Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Converter line utilization rates above 80% in Germany's North Rhine-Westphalia corridor create scale economies that compress unit costs while establishing price floors for mid-tier entrants. This capacity concentration shapes procurement negotiations, with major retail chains leveraging volume commitments to extract preferential terms from Tetra Pak and SIG Combibloc while regional co-packers absorb margin compression.
Pricing Analysis
Three-tier pricing structure across premium aseptic lines, standard fresh dairy equipment, and economy modular systems dominates contract structures. Price differentiation rests on barrier laminate certification grade and filling speed capability, with EFSA-compliant mineral oil-free formulations commanding premiums. Cost compression in standard tiers is intensifying because Polish and Italian co-packers are adding licensed capacity. Discount retail channels in Germany exhibit highest price sensitivity, while healthcare sterilization applications show least.
Supply Chain Analysis
Strategic stockpiling of aluminum barrier foil prevails over just-in-time approaches due to thin-gauge rolling mill concentration in Germany, France, and Belgium. Raw material flows draw from Nordic pulp mills, European polymer producers, and specialized adhesive formulators in Italy. Single-source vulnerability sits with aluminum foil supply from a limited European rolling mill base. Distribution runs through converter direct-to-beverage-producer contracts, with secondary logistics via retail chain consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carton bottle market is recovering from cyclical trough conditions as EFSA migration limit compliance investments peak and fresh dairy screw-cap adoption accelerates replacement demand.
For Market Incumbents: Consolidate barrier material reformulation partnerships with Nordic pulp suppliers to secure fiber cost stability against bio-polymer coating competitors. Lock in aseptic filling technician training programs with German technical institutes to defend against engineering scarcity. Priority lever: captive aluminum foil sourcing or long-term rolling mill offtake agreements to mitigate supply concentration risk. For New Entrants and Emerging Players: Lead with biodegradable material formulations targeting Dutch public sector catering contracts and Polish discount retail private-label programs. Most penetrable white space: mid-tier oat and almond milk brands seeking plastic-free differentiation in France and Italy. Go-to-market angle: modular filling system partnerships with Spanish and Italian co-packers piloting high-barrier bio-polymer laminates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional laminate specialists with EFSA notification expertise and integrated compliance data infrastructure. Long-term viability hinges on 5-10 year regulatory trajectory toward extended producer responsibility automation and digital product passport mandates. Acquisition target archetype: mid-cap converters with German retail chain relationships and bio-polymer coating R&D pipelines. Signal to watch: EFSA novel food contact notification approval timelines as inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Material Reformulation Partnership | Secures mineral oil-free adhesive supply for EFSA compliance in German dairy applications. |
| Aseptic Filling Technician Training Program | Addresses engineering scarcity concentrated with original equipment manufacturers in North Rhine-Westphalia. |
| Digital Product Passport Infrastructure Investment | Meets Dutch and German retail chain procurement requirements for extended producer responsibility automation. |
| High-Barrier Bio-Polymer Coating Scale-Up | Displaces aluminum laminates for ambient-stable juice in Spanish and Italian private-label programs. |
| Polish Retail Channel Expansion | Captures white space in underserved discount and convenience segments as private-label beverage programs grow. |
Study Parameters
Desk research of EU regulatory filings, EFSA migration limit documentation, and national packaging ordinance records preceded structured interviews with converter operations managers, beverage brand procurement directors, aseptic filling equipment engineers, and retail chain sustainability officers. Secondary validation drew from trade association capacity surveys, customs data on aluminum foil imports, and rolling mill production disclosures. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Variance decomposition across product type, material grade, end-use application, and geographic production cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories indexed to regulatory compliance timelines and retail pilot program scaling patterns. Key forecast inputs included EFSA novel food contact notification approval velocities and German dual-system fee structure evolution.
The analysis sits within stated boundaries; outcomes outside sustained EFSA enforcement intensity or aluminum foil supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory trajectory and retail procurement automation adoption. Specific risks that could revise projections include REACH substance authorization delays for alternative barrier chemistries and aseptic line commissioning bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Africa Folding Carton Market
Cartons
Cardboard Crates Market
Cartons
Luxury Folding Carton Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Shaped Liquid Cartons Market
Cartons
Liquid Packaging Cartons Market
Cartons
Tablet Cartons Market
Cartons
Shaped Corrugated Packaging Market
Cartons
Carton Form Fill Seal Machine Market
Cartons
Digital Printed Cartons Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Interlocking Boxes Market
Cartons
Child-Resistant Carton Box Market
Cartons
Pick and Place Carton Packers Market
Cartons
GCC Folding Carton Market