
 GCC Folding Carton Market | 2026-2036
GCC Folding Carton Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Folding Carton Market Insights
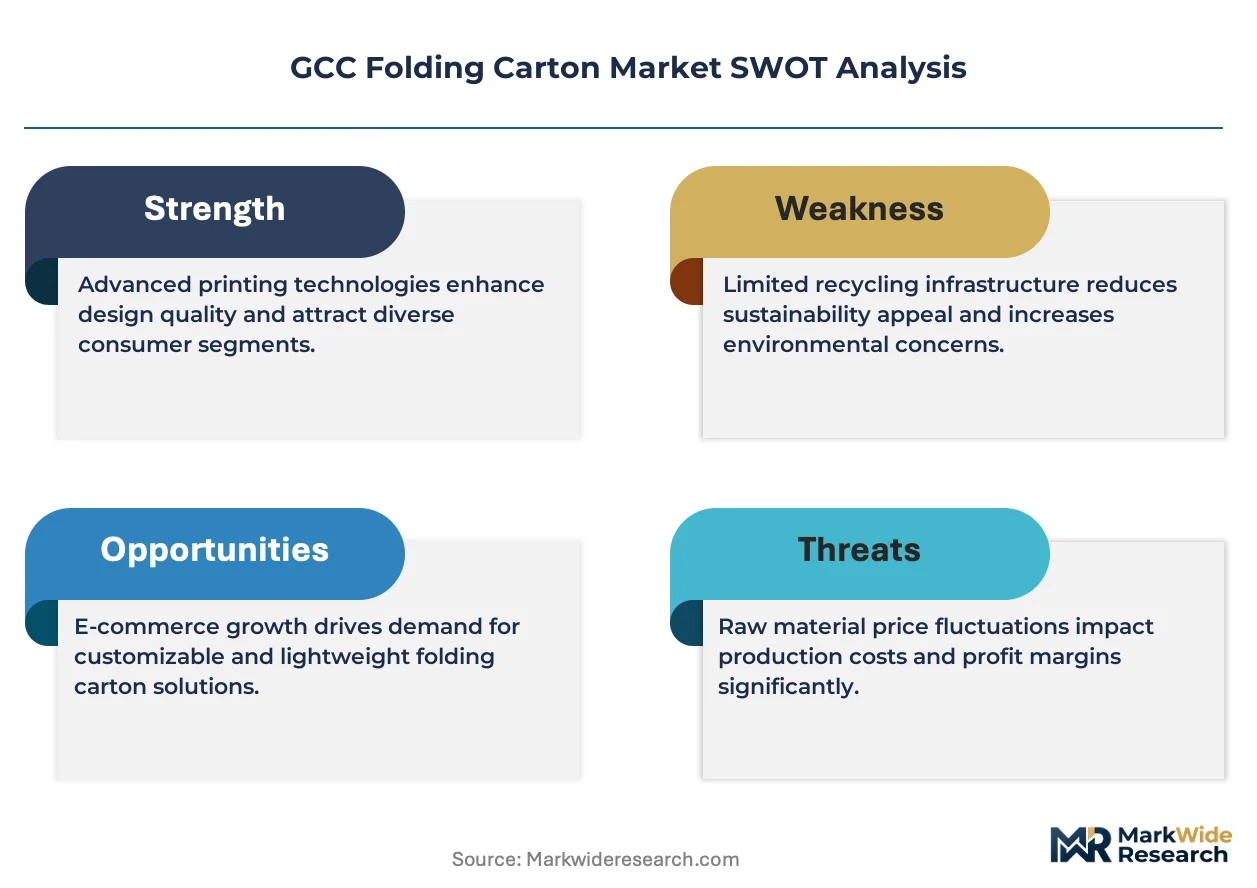
ISO 22000 food safety certification is reorganizing supplier qualification across the GCC folding carton sector, filtering out smaller converters unable to maintain HACCP-aligned production lines. Arabian Packaging Company L.L.C. leverages integrated paperboard sourcing from regional mills to secure margin stability. Obeikan Folding Carton dominates pharmaceutical-grade carton output through cleanroom-compatible finishing capabilities. Noor Carton & Packaging Industry anchors the UAE market with flexographic specialization for fast-moving consumer goods.
Folding cartons are paper-based packaging containers manufactured from 200–400 gsm solid bleached or unbleached sulfate board, typically die-cut, creased, and glued to form rectangular or custom-shaped enclosures for retail product protection and shelf display. Their primary commercial purpose centers on brand communication, tamper evidence, and logistical efficiency in consumer goods distribution. Shelf-ready packaging captures the fastest structural expansion as Gulf retailers automate restocking workflows and reduce labor touchpoints. Recycled materials face technical constraints in food-contact applications, pushing converters toward virgin-paperboard blends with post-consumer content below threshold limits. Digital printing segments gain share in short-run pharmaceutical and personal care campaigns where variable data and regional language customization offset unit cost premiums.
SFDA in Saudi Arabia and MOHAP in the UAE enforce divergent food-contact and pharmaceutical serialization standards that fragment compliance investment across the six GCC states. SASO technical regulations for paper-based packaging add a third compliance layer for exporters serving Saudi Arabia specifically. Stakeholders must monitor harmonization progress between Gulf standardization bodies and assess whether centralized certification investments in one jurisdiction transfer across borders.
Market Dynamics
Modern retail automation across Saudi Arabia and the UAE is compressing carton specification cycles, forcing converters to synchronize shelf-ready packaging formats with retailer-specific restocking protocols rather than generic product protection standards.
Growth Catalysts
- Shelf-ready packaging mandates:Hypermarket chains in Saudi Arabia now require display-ready cartons with tear-away perforations and integrated stacking features, eliminating secondary display preparation labor.
- SFDA food-contact compliance:Saudi Arabia's tightened migration testing for paperboard packaging is filtering supplier pools and rewarding converters with in-house laboratory certification capabilities.
- Digital inkjet adoption:Short-run pharmaceutical serialization campaigns in the UAE leverage variable-data printing for regional language compliance without plate-change downtime.
Market Restraints
- Virgin paperboard cost volatility:GCC converters remain import-dependent on European and Asian bleached sulfate board, exposing margins to freight and pulp price swings.
- Recycled content ceiling:Food-contact applications face strict extractables limits under SFDA and MOHAP guidelines, capping post-consumer fiber below usable thresholds for premium F&B brands.
- MOHAP-SFDA regulatory divergence:Pharmaceutical serialization requirements differ in data-matrix specifications and aggregation rules, fragmenting compliance tooling investments across the six Gulf states.
Strategic Opportunities
- Kuwait and Oman retail modernization:Underdeveloped organized retail infrastructure in these markets presents first-mover positioning for shelf-ready carton specifications ahead of hypermarket expansion.
- Anti-counterfeit integration:Convergence of NFC-enabled packaging with folding carton substrates allows premium cosmetics and pharmaceutical brands to authenticate supply chains at unit level.
- SASO technical regulation alignment:Pending harmonization of Saudi paper-based packaging standards with Gulf Standardization Organization frameworks may enable single-certification regional access.
Industry Challenges
- Cleanroom finishing scarcity:Pharmaceutical-grade carton production requires ISO Class 8 compatible environments, yet qualified converter capacity concentrates in Jeddah and Dubai, creating fulfillment bottlenecks for Bahrain and Qatar orders.
- ISO 22000 audit compression:Food safety certification timelines stretch 8-14 months for HACCP-aligned production line validation, delaying supplier qualification for export contracts to European retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Folding Carton Market |
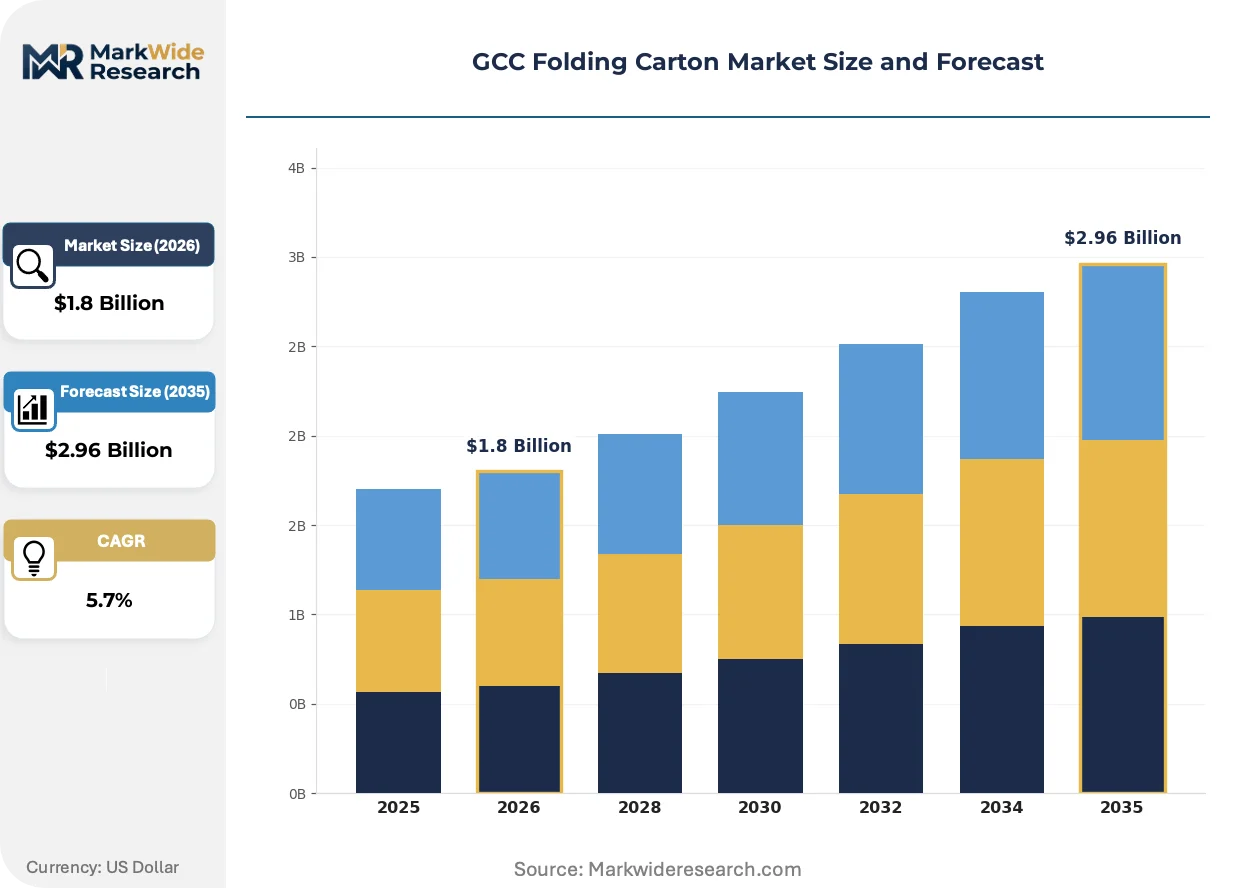
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Cartons, Gusseted Cartons, Die-Cut Cartons, Shelf-Ready Packaging Material: Paperboard, Corrugated Fiberboard, Plastic, Recycled Materials End User: Food & Beverage, Personal Care, Healthcare, Electronics Printing Technology: Flexographic Printing, Offset Printing, Digital Printing, Gravure Printing |
| Companies Covered | Noor Carton & Packaging Industry, Arabian Packaging Company L.L.C., Obeikan Folding Carton, Majan Packaging & Printing, Banawi Industrial Group, Gulf Carton Factory Co., Queenex Corrugated Carton Factory, United Carton Industries Company, NASR Packaging & Printing Co, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Folding Carton Market Trends and Innovations
Digital production workflows and regulatory serialization mandates are restructuring how Gulf converters allocate capital between flexographic volume lines and inkjet customization cells.
Water-based barrier coatings are miniaturizing the functional gap between virgin and recycled paperboard for dry food applications. Saudi dairy and snack brands are piloting these substrates for 12-18 month shelf life requirements. The technology is miniaturizing the premium price gap between sustainable positioning and performance-grade protection.
MOHAP's 2023 pharmaceutical serialization enforcement in the UAE mandates unique identifier aggregation at case and pallet levels. This compels carton converters to integrate track-and-trace data fields into die-cut layouts. Cold-chain biologics and high-value generics in Dubai's free zones face the steepest compliance cost absorption.
Retailer consolidation across the GCC is compressing supplier approval cycles from 18 months to 6-9 months. Lulu Hypermarket and Carrefour Saudi now impose synchronized SKU-launch calendars that demand carton samples within 4 weeks of brief issuance. Personal care and confectionery segments in Riyadh and Abu Dhabi experience the most acute specification velocity pressure.
GCC Folding Carton Market Segmentation
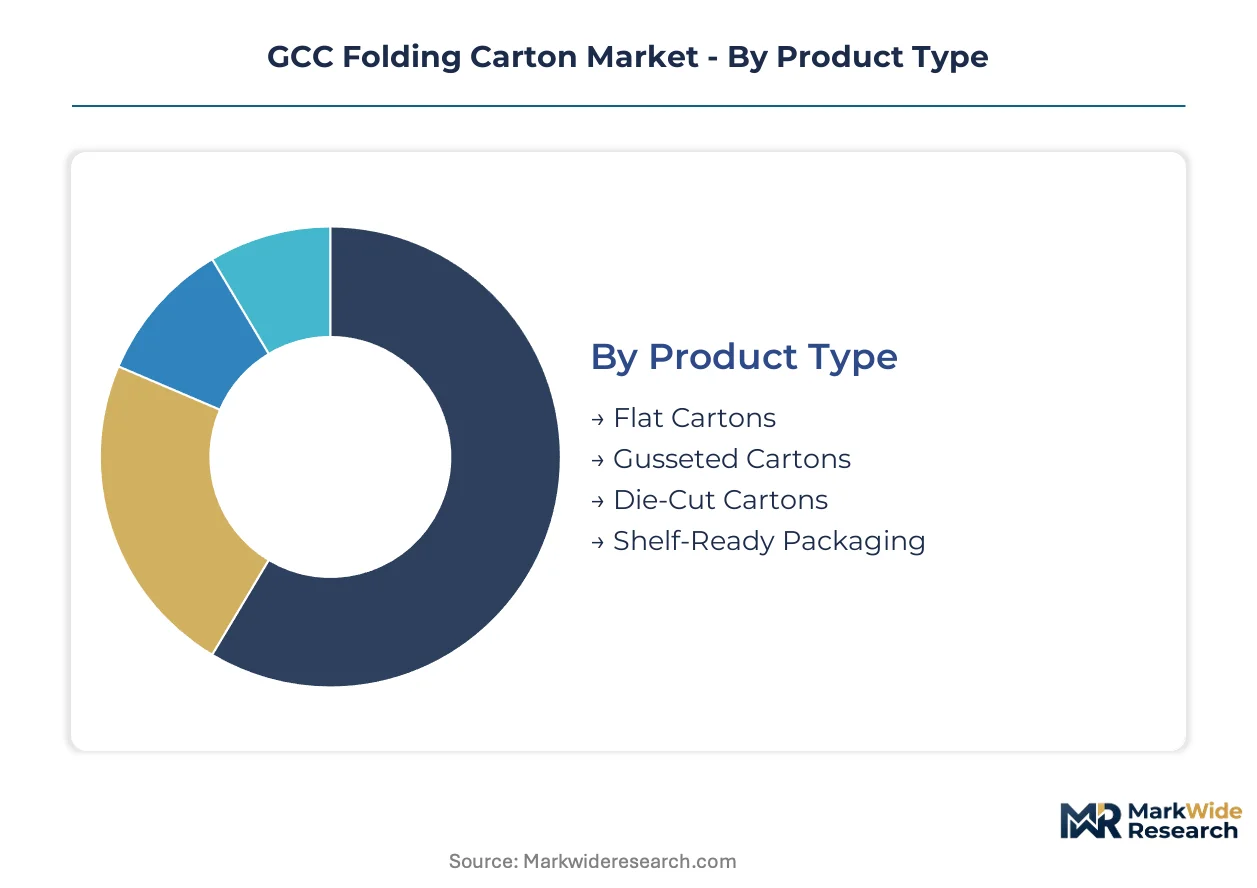
Structural variation across GCC folding cartons determines converter capital allocation between high-volume flexographic lines and short-run digital cells. Segment boundaries increasingly blur as shelf-ready formats absorb die-cut complexity and digital workflows penetrate pharmaceutical serialization campaigns.
Product Type:
Channel-mix dynamics favor shelf-ready formats in Saudi and UAE hypermarkets while flat cartons retain dominance in traditional trade and export-oriented pharmaceutical fulfillment.
- Flat Cartons:Standard rectangular enclosures formed from single-panel paperboard with glued or tucked closures. Saudi pharmaceutical exporters and UAE personal care brands specify these for automated cartoning lines at Jeddah and Dubai packaging facilities. Migration toward child-resistant locking mechanisms absorbs incremental tooling investment.
- Shelf-Ready Packaging:Display-integrated cartons with tear-away perforations, stacking feet, and retail-ready graphics eliminating secondary preparation. Lulu Hypermarket and Carrefour Saudi now mandate these formats for FMCG suppliers, compressing approval cycles to four weeks. Labor cost reduction at store level drives specification velocity.
- Gusseted Cartons:Expandable side panels accommodate volume variation in bulk dry foods and institutional catering packs.
- Die-Cut Cartons:Custom-shaped enclosures for premium cosmetics and electronics with window patches and tactile finishes.
Flat cartons dominate installed base. Shelf-ready packaging is where expansion concentrates.
Material:
Cost tier stratification separates virgin-paperboard premium positioning from recycled-content economy grades, with regulatory ceilings fragmenting food-contact applications.
- Paperboard:Solid bleached sulfate board in 200–400 gsm weights provides printability, rigidity, and barrier performance for dairy and chocolate applications. Saudi dairy brands specify these for 12–18 month shelf life requirements under SFDA migration limits.
- Recycled Materials:Post-consumer fiber blends face strict extractables thresholds under SFDA and MOHAP food-contact guidelines, capping usable content below premium brand tolerance. Water-based barrier coatings are miniaturizing the performance gap for dry snack applications.
- Corrugated Fiberboard:Heavy-duty substrates for secondary shipping containers and bulk retail display units.
- Plastic:Polymer-coated or all-plastic cartons for moisture-critical pharmaceutical and personal care segments.
Paperboard commands volume leadership. Recycled materials face the steepest compliance headwinds.
End User:
Application-specific requirements fragment converter capabilities between ISO 22000 food safety certification and pharmaceutical cleanroom finishing.
- Food & Beverage:Dairy, confectionery, and ready-meal segments drive carton consumption across Saudi Arabia and the UAE. SFDA tightened migration testing is filtering supplier pools toward converters with in-house laboratory certification.
- Healthcare:Pharmaceutical serialization mandates under MOHAP and divergent SFDA requirements demand track-and-trace data fields integrated into die-cut layouts. Cold-chain biologics in Dubai free zones absorb steepest compliance costs.
- Personal Care:Cosmetics and hygiene products specifying premium tactile finishes and anti-counterfeit NFC integration.
- Electronics:Anti-static and protective cartons for consumer device retail packaging.
Food and Beverage anchors volume base. Healthcare is climbing the fastest on regulatory serialization investment.
Printing Technology:
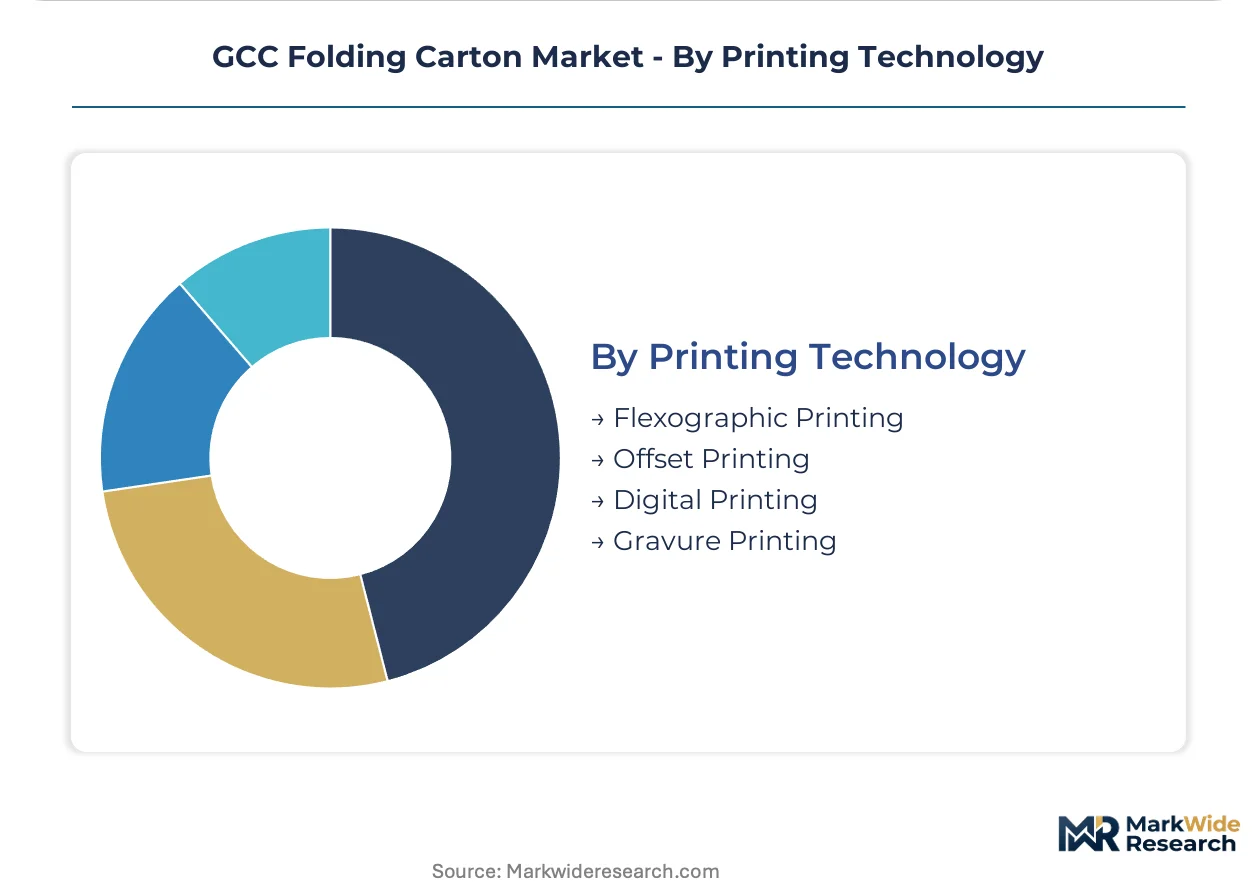
Volume-maturity segmentation separates long-run flexographic efficiency from emerging digital customization for pharmaceutical campaigns and regional language variants.
- Flexographic Printing:Rotary relief printing with polymer plates delivers cost efficiency at 50,000+ unit runs. Noor Carton anchors UAE FMCG supply through specialized flexographic lines for fast-moving consumer goods.
- Digital Printing:Inkjet and toner-based workflows enable variable-data serialization and short-run personalization without plate-change downtime. MOHAP pharmaceutical mandates and regional Arabic customization accelerate adoption in Dubai and Riyadh.
- Offset Printing:Lithographic quality for premium cosmetic and chocolate box applications requiring precise color matching.
- Gravure Printing:Cylinder-based intaglio for ultra-long runs with consistent ink density and metallic effects.
Flexographic printing retains installed base dominance. Digital printing is gaining share fastest on regulatory and customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA and MOHAP regulatory tightening is redrawing production geography across Gulf states, concentrating compliant capacity in Saudi Arabia and the UAE while filtering smaller converters from cross-border supply chains.
Saudi Arabia
Dairy and confectionery brands in Riyadh and Jeddah drive shelf-ready carton demand as Lulu Hypermarket and Carrefour Saudi mandate display-ready formats. SFDA migration testing for paperboard packaging filters supplier pools toward converters with in-house laboratory certification. Jeddah's industrial corridor hosts the densest concentration of ISO 22000-aligned production lines serving domestic and export markets.
United Arab Emirates
Pharmaceutical serialization campaigns under MOHAP rules accelerate digital printing adoption for variable-data compliance in Dubai free zones. Personal care and cosmetics brands specify premium tactile finishes with anti-counterfeit NFC integration. Dubai and Sharjah industrial zones concentrate cleanroom-compatible finishing capacity for cold-chain biologics and high-value generics.
Kuwait
Underdeveloped organized retail infrastructure creates first-mover positioning for shelf-ready carton specifications ahead of hypermarket expansion. The country's national food safety regulator enforces food-contact material standards that mirror SFDA frameworks without equivalent laboratory certification requirements. Kuwait City industrial areas host emerging converter investments targeting Saudi and UAE export qualification.
Oman
Traditional trade channels retain dominance in Muscat and Salalah, sustaining flat carton demand for FMCG distribution outside modern retail networks. Port infrastructure investments at Duqm and Sohar attract secondary packaging converters serving transshipment markets. The sultanate's packaging sector remains import-dependent for pharmaceutical-grade substrates.
Qatar
Pharmaceutical-grade carton fulfillment relies on cross-border supply from Jeddah and Dubai due to domestic cleanroom finishing scarcity. FIFA legacy retail development accelerates shelf-ready packaging adoption for premium food and beverage brands. Doha's industrial zone hosts limited converter capacity focused on corrugated secondary packaging rather than primary folding cartons.
GCC Folding Carton Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and end-use segmentation, producing a bifurcated structure where ISO 22000 food safety credentials and pharmaceutical cleanroom capabilities separate premium-tier suppliers from commodity converters. Three archetypes dominate: integrated paperboard converters with captive regional mill relationships, pharmaceutical-grade specialists with ISO Class 8 finishing environments, and flexographic volume players serving FMCG retail chains. Competitive moves concentrate on laboratory certification investments for SFDA compliance and digital printing cell additions for pharmaceutical serialization campaigns.
Among UAE-based specialists, Noor Carton & Packaging Industry exemplifies flexographic volume positioning for fast-moving consumer goods, while Arabian Packaging Company L.L.C. represents integrated sourcing archetypes with regional paperboard mill relationships. Saudi Arabia's Obeikan Folding Carton anchors pharmaceutical-grade output through cleanroom-compatible finishing capabilities.
| Leading Market Players |
|---|
| Noor Carton & Packaging Industry |
| Arabian Packaging Company L.L.C. |
| Obeikan Folding Carton |
| Majan Packaging & Printing |
| Banawi Industrial Group |
| Gulf Carton Factory Co. |
| Queenex Corrugated Carton Factory |
| United Carton Industries Company |
| NASR Packaging & Printing Co |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety day paperboard inventory cycles at Jeddah and Dubai converters compress pricing power during European pulp price spikes, concentrating margin pressure on import-dependent operators without captive mill relationships. SFDA laboratory certification requirements add fixed-cost layers that stratify converter tiers, with certified suppliers commanding premium positioning against uncertified competitors serving traditional trade channels.
Pricing Analysis
Certification level creates the primary spread across GCC folding carton pricing, with ISO 22000-aligned food safety credentials and pharmaceutical cleanroom capabilities separating premium-tier suppliers from commodity converters. Three-tier pricing structure across certified-premium, standard-industrial, and economy-trade levels reflects divergent compliance investment and buyer risk tolerance. Pricing pressure stems from virgin sulfate board import dependency and freight cost volatility, with European pulp benchmark movements transmitting directly to GCC converter quotations within thirty days. Food and beverage brands exhibit highest price sensitivity due to volume scale and specification standardization, while pharmaceutical serialization campaigns absorb premium pricing for variable-data digital compliance.
Supply Chain Analysis
Ninety-day European paperboard inventory buffers at regional distributors insulate GCC converters from spot price volatility, though extended lead times during Red Sea logistics disruptions expose just-in-time operators. Supply concentrates in Finland, Sweden, and Germany for solid bleached sulfate board, with Asian mills from Indonesia and South Korea supplying secondary grades. Raw material dependencies span northern bleached softwood pulp, titanium dioxide coatings, and water-based barrier formulations. Single-source vulnerability runs through European specialty board grades required for pharmaceutical cleanroom applications. Distribution runs through Jeddah and Dubai industrial corridors serving Saudi and UAE domestic demand, with cross-border fulfillment reaching Bahrain, Qatar, and Oman.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between SFDA and MOHAP frameworks fragments compliance requirements across six Gulf states, creating specialized service niches for certified converters and laboratory-equipped suppliers. Shelf-ready packaging mandates from consolidating hypermarket chains accelerate specification velocity, rewarding agile producers with digital workflow capabilities.
For Market Incumbents: Fortify pharmaceutical-grade capacity through ISO Class 8 cleanroom investments in Jeddah and Dubai, defending against emerging Saudi converters acquiring European finishing technology. Deepen backward integration into regional paperboard sourcing through mill partnerships or captive supply agreements, reducing exposure to European pulp price volatility and freight cost swings. For New Entrants and Emerging Players: Digital serialization service gaps in Kuwait and Oman present first-mover positioning for pharmaceutical track-and-trace compliance ahead of hypermarket retail modernization. Target underdeveloped organized retail infrastructure in Muscat and Kuwait City with shelf-ready packaging specifications, leveraging four-week sample turnaround as competitive wedge against established UAE and Saudi suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory certification barriers and capital-intensive cleanroom requirements favor scaled operators with multi-jurisdictional compliance capabilities. Acquisition focus should center on mid-tier Saudi converters with ISO 22000 credentials and underutilized digital printing cells. Monitor SFDA-MOHAP harmonization progress as signal for cross-border certification portability and regional margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Certification Investment | SFDA in-house migration testing capability filters supplier pools toward qualified converters. |
| Digital Printing Cell Addition | Variable-data inkjet workflows serve MOHAP pharmaceutical serialization mandates in Dubai free zones. |
| Regional Mill Partnership | Captive paperboard sourcing from Arabian Packaging relationships stabilizes margin exposure. |
| Cleanroom Capacity Expansion | ISO Class 8 finishing environments address pharmaceutical-grade scarcity in Bahrain and Qatar. |
| Shelf-Ready Format Development | Tear-away perforation and stacking specifications align with Carrefour Saudi restocking protocols. |
Research Methodology
Desk research of customs trade databases, Gulf Standardization Organization technical regulations, and pharmaceutical packaging industry publications preceded structured interviews with folding carton production managers, SFDA compliance officers at Saudi dairy brands, MOHAP regulatory affairs leads in Dubai free zones, and procurement directors at UAE hypermarket chains. Primary fieldwork captured specification velocity pressures, certification timeline constraints, and digital printing adoption patterns. Secondary validation drew from SASO technical documentation, European pulp price benchmarks, and SEC filings of listed packaging converters. Bottom-up demand modeling triangulated against top-down market sizing across product type, material grade, end-use segment, and printing technology dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation granularity capturing shelf-ready packaging expansion, pharmaceutical serialization compliance costs, and recycled-content regulatory ceilings. Modeled dimensions span structural format, paperboard grade tier, end-use application, and printing technology adoption curve. CAGRs derive from normalized base-year alignment and annual step-down assumptions. Forecast inputs incorporate SFDA laboratory certification penetration rates and MOHAP track-and-trace enforcement intensity across Dubai pharmaceutical free zones.
Underlying assumptions cover sustained hypermarket retail consolidation, stable European pulp supply availability, and incremental Gulf regulatory harmonization progress, with deviation risk concentrated in Red Sea logistics disruptions and divergent national certification requirements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
MET-PET Cartons Market
Cartons
Interlocking Boxes Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Carton Bottle Market
Cartons
Pizza Cartons Market
Cartons
End Load Cartoning Machine Market
Cartons
Japan Corrugated Boxes Market
Cartons
Carton Display Market
Cartons
Pulp Roll Cradles Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Brick Liquid Carton Market
Cartons
Folding Carton in Healthcare Market
Cartons
Tetrahedron Carton Market