
 North America Corrugated and Folding Carton Packaging Market | 2026-2036
North America Corrugated and Folding Carton Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Corrugated and Folding Carton Packaging Market Insights
E-commerce direct-to-consumer channels are reshaping corrugated demand across North America, as fulfillment centers require smaller lot sizes and faster turnaround times. WestRock Company leverages its integrated mill and converting network to control containerboard supply from pulp to finished box. International Paper Company anchors its position through massive kraft linerboard capacity serving the Midwest industrial belt. Georgia-Pacific LLC competes via specialized coated packaging grades targeting premium consumer goods.
Corrugated and folding carton packaging comprises multi-layered paperboard structures—fluted medium sandwiched between linerboards for corrugated, or solid bleached sulfate for folding cartons—manufactured through corrugating, die-cutting, and gluing processes designed to protect goods during distribution and display. Folding cartons dominate personal care and healthcare end uses where print quality and shelf presence command margin premiums, while corrugated boxes sustain volume leadership in food and beverage logistics. Recyclable packaging types are gaining structural share as brand owners face compliance pressure under state-level mandates.
The US EPA, state environmental agencies, and the Canadian Food Inspection Agency collectively govern fiber sourcing, recycled content thresholds, and food-contact safety standards that determine market access for converters. FDA food-contact regulations and emerging state extended producer responsibility frameworks are tightening material traceability requirements across the supply chain. Stakeholders must monitor how pending federal packaging legislation interacts with provincial regulations in Ontario and Quebec to anticipate compliance cost allocation.
Market Dynamics
E-commerce fulfillment networks are compressing order cycles and fragmenting lot sizes across the North American corrugated supply chain, forcing converters to retool for rapid-changeover production while maintaining structural integrity standards.
Growth Catalysts
- EPA Recycled Content Mandates:Federal pressure under the Resource Conservation and Recovery Act is accelerating fiber-based substitution for plastic shipping materials in consumer goods distribution.
- Food Processing Clusters:Concentrated meat, dairy, and beverage operations across Michigan, Ohio, and Illinois generate sustained demand for temperature-stable corrugated containers with moisture-resistant coatings.
- Automotive Parts Logistics:Just-in-time supply chains serving Detroit-area assembly plants require precision-engineered folding cartons for component kitting and sequencing.
Market Restraints
- Old Corrugated Container Price Volatility:Recycled fiber input costs swing with municipal collection rates and export demand to Asian paper mills, squeezing converter margins unpredictably.
- Linerboard Mill Concentration:Containerboard production clusters in the Southeastern United States create freight cost disadvantages for Midwest converters without rail siding access.
- Plastic Pallet Substitution:Reusable plastic bulk containers are capturing closed-loop automotive and beverage logistics, displacing one-way corrugated for high-rotation applications.
Strategic Opportunities
- Quebec and Ontario EPR Expansion:Provincial extended producer responsibility frameworks are creating compliance-service revenue streams for converters offering design-for-recycling certification.
- Pharmaceutical Cold Chain:Temperature-sensitive biologics distribution is opening demand for insulated corrugated shippers with phase-change material integration.
- Digital Print Convergence:Combination of inkjet decoration and inline die-cutting enables lot-size-one customization for direct-to-consumer subscription boxes.
Industry Challenges
- Corrugator Setter Skill Shortage:Experienced technicians capable of calibrating flute profiles and starch adhesive viscosity are retiring faster than apprenticeship programs replace them.
- Legacy ERP Integration:Shop-floor control systems from the 1990s resist cloud-based order management interfaces required by e-commerce fulfillment platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Corrugated and Folding Carton Packaging Market |
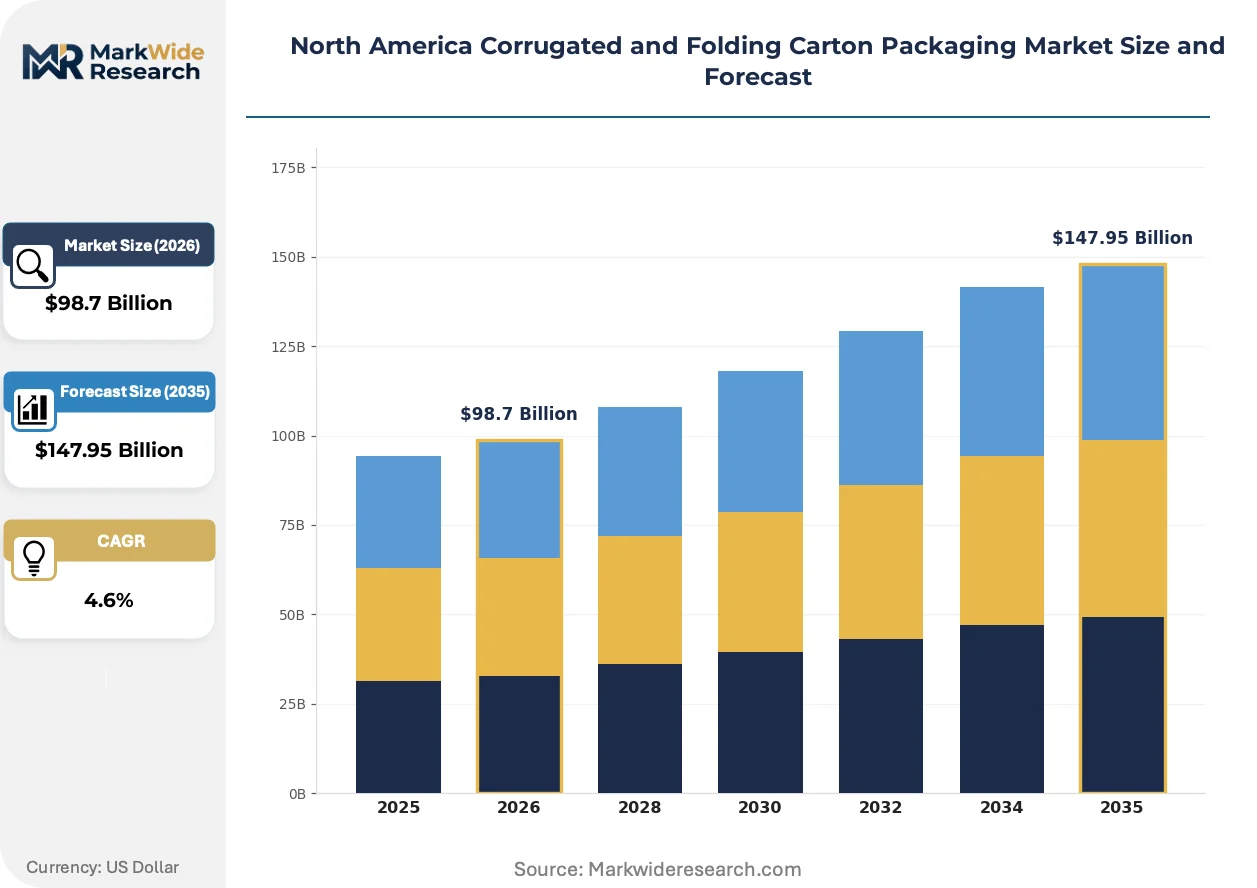
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $147.95 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Boxes, Folding Cartons, Inserts, Trays End User: Food & Beverage, Personal Care, Healthcare, Electronics Packaging Type: Recyclable, Biodegradable, Custom, Standard Material: Paperboard, Kraft Paper, Chipboard, Others |
| Companies Covered | Georgia-Pacific LLC, Sonoco Products Company, International Paper Company, WestRock Company, Cascades Inc., Smurfit WestRock, Graphic Packaging International, Hood Packaging, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Corrugated and Folding Carton Packaging Market Trends and Innovations
Digital workflow integration and material science advances are compressing design-to-delivery timelines while expanding functional performance boundaries for fiber-based packaging across North American supply chains.
Virtual prototyping software is virtualizing physical box compression testing and drop-shock validation. E-commerce fulfillment centers and third-party logistics providers are adopting these platforms to qualify packaging designs without sample production. The technology is virtualizing months from traditional new-product qualification cycles while reducing material waste from iterative physical testing.
State-level extended producer responsibility legislation in California, Maine, and Oregon is mandating recycled content thresholds and recyclability labeling standards. These frameworks are forcing brand owners to document fiber sourcing and end-of-life pathways through the supply chain. Food and beverage manufacturers with national distribution are consolidating supplier bases to converters with multi-state compliance certification capabilities.
Direct procurement relationships between e-commerce platforms and regional corrugated converters are disintermediating traditional merchant distribution channels. Large fulfillment operators are establishing dedicated mill capacity through offtake agreements rather than spot market purchasing. This pattern is most pronounced in the Great Lakes corridor where same-day delivery promises require local production proximity.
North America Corrugated and Folding Carton Packaging Market Segmentation
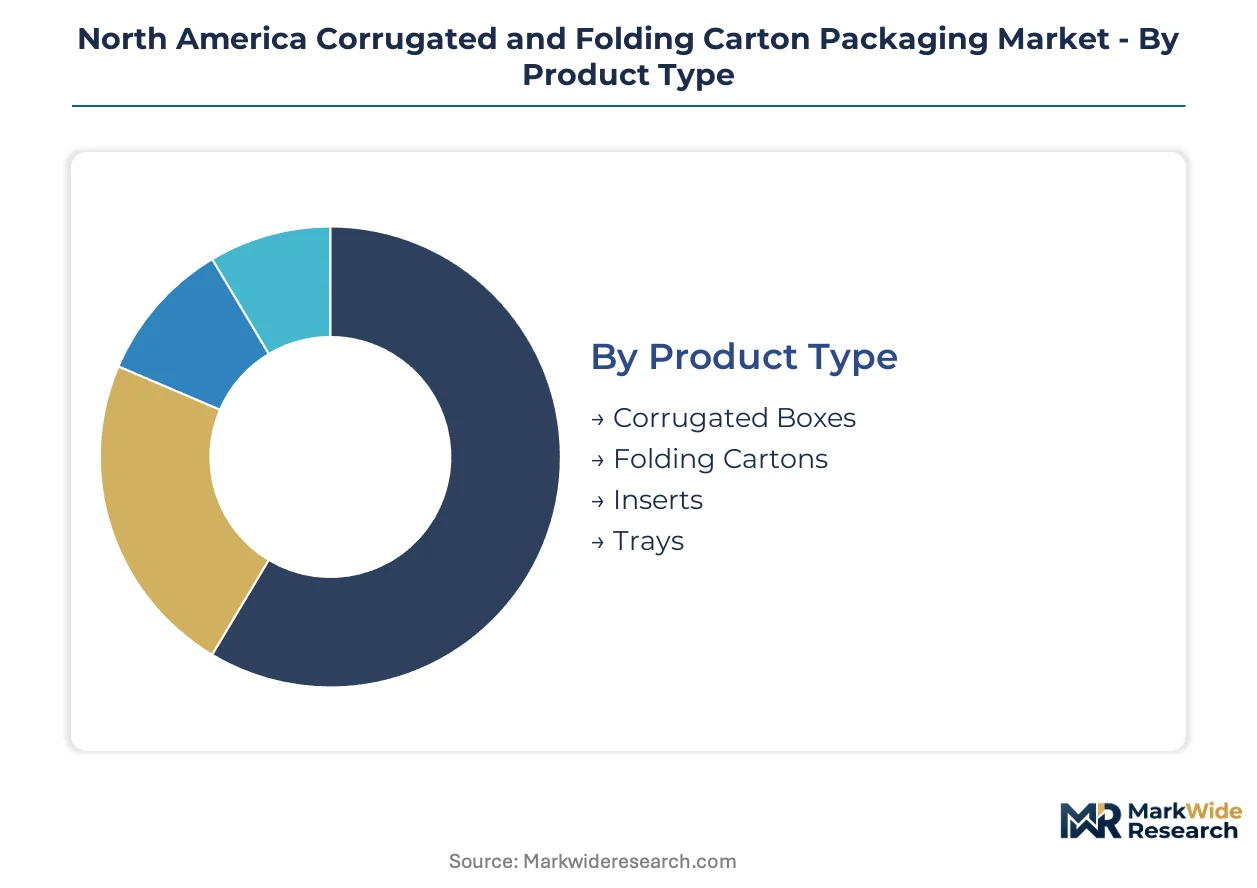
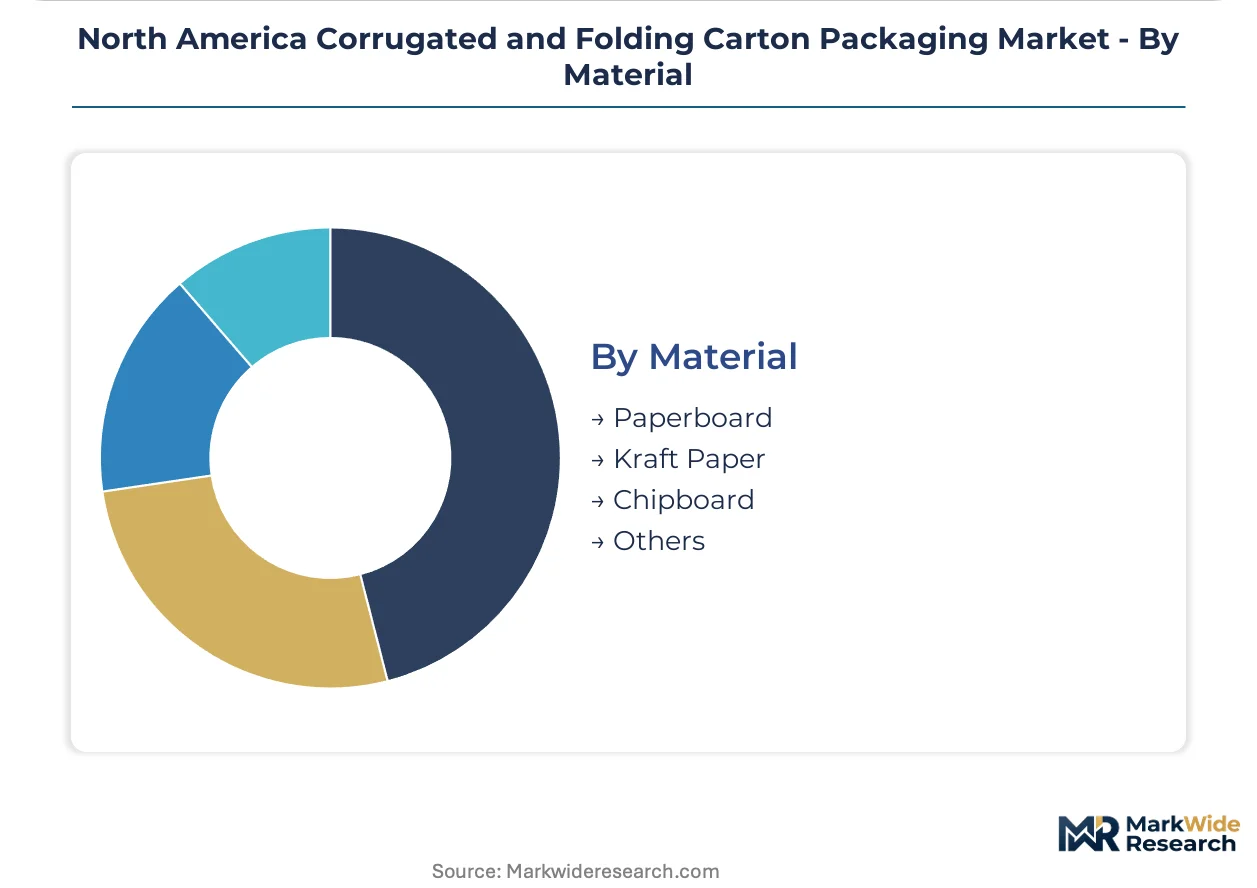
Segmentation reveals how corrugated and folding carton demand fragments across product specifications, end-use requirements, and material grades. Each dimension carries distinct margin profiles and service intensity obligations that shape converter competitiveness.
Product Type:
After-sales service intensity varies sharply across product categories, with complex structural designs demanding ongoing technical support while commodity boxes require minimal post-delivery engagement.
- Folding Cartons:Solid bleached sulfate or coated unbleached kraft construction delivers premium print surfaces for shelf-facing applications. Pharmaceutical and personal care manufacturers in New Jersey and North Carolina concentrate demand here, driven by FDA food-contact compliance requirements and brand differentiation needs.
- Corrugated Boxes:Multi-layer flute structures (A, B, C, E, F profiles) between linerboard facings provide compression strength for distribution environments. E-commerce fulfillment centers across the Great Lakes corridor and Texas generate volume, compelled by same-day delivery promises and automated sortation compatibility specifications.
- Inserts:Die-cut corrugated or paperboard components secure product positioning within primary containers. Electronics manufacturers in California and Mexico border states specify anti-static coatings and precision tolerances.
- Trays:Shallow-depth corrugated platforms enable retail-ready display and unitization. Beverage bottlers in Wisconsin and Colorado favor this format for club store distribution.
By volume, corrugated boxes lead. By growth pace, folding cartons are ahead.
End User:
Cost tier stratification separates commodity food service from premium healthcare applications, with compliance burden and print complexity driving price differentiation.
- Food & Beverage:Temperature-stable corrugated containers with moisture-resistant barriers protect perishables through cold chain distribution. Meat and dairy processors in Michigan, Ohio, and Illinois sustain high-volume demand, pressured by EPA recycled content mandates and state extended producer responsibility frameworks.
- Healthcare:Folding cartons with tamper-evident features and serialization compatibility serve pharmaceutical distribution. Biologics cold chain expansion in Massachusetts and California creates demand for insulated corrugated shippers with phase-change material integration.
- Personal Care:Premium coated paperboard delivers shelf presence for cosmetics and skincare. Brand owners consolidate supplier bases to converters with multi-state compliance certification capabilities.
- Electronics:Anti-static and cushioning-engineered corrugated protects high-value components. Fulfillment networks for direct-to-consumer channels require smaller lot sizes and faster turnaround times.
Food and beverage dominates volume contribution. Healthcare applications are climbing the fastest.
Packaging Type:
Application context determines whether standard specifications suffice or custom engineering becomes essential, with sustainability credentials increasingly gating market access.
- Recyclable:Designs meeting EPA recycled content thresholds and state-level recyclability labeling standards. National food and beverage distributors mandate this category to satisfy California, Maine, and Oregon extended producer responsibility legislation.
- Custom:Engineered specifications for dimensional fit, print registration, or structural performance. Automotive parts kitting for Detroit-area assembly plants requires precision-engineered folding cartons with just-in-time delivery synchronization.
- Biodegradable:Compostable fiber formulations and adhesive systems for organic waste stream compatibility. Emerging demand from organic food processors and municipal composting programs.
- Standard:Commodity specifications from industry association libraries with minimal customization. High-volume, low-margin production for non-branded shipping applications.
Recyclable formats command volume leadership. Custom packaging shows the steepest expansion trajectory.
Material:
Supply concentration in Southeastern linerboard mills creates freight cost disadvantages for converters without rail siding access, favoring material choices with regional availability.
- Paperboard:Bleached or unbleached kraft pulp-based substrates for folding carton and premium corrugated applications. Georgia-Pacific and International Paper anchor supply through massive integrated capacity.
- Kraft Paper:Unbleached virgin or recycled fiber for linerboard and wrapping applications. Automotive and beverage logistics specify this grade for strength-to-weight performance.
- Chipboard:Recycled fiber-based lower-grade board for non-structural applications. Backing boards and secondary packaging where print quality requirements are minimal.
- Others:Specialty substrates including coated recycled board, solid bleached sulfate, and agricultural fiber alternatives. Niche applications in premium consumer goods and emerging sustainable packaging trials.
Paperboard leads by volume. Kraft paper is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The St. Lawrence Seaway and Great Lakes rail-water intermodal corridor underwrites North America's corrugated distribution architecture, linking Midwest manufacturing to Atlantic and Pacific export gateways.
United States
E-commerce fulfillment networks in Michigan, Ohio, and Illinois drive containerboard consumption for same-day delivery infrastructure. The EPA's recycled content mandates under the Resource Conservation and Recovery Act pressure converters toward fiber-based alternatives. Detroit-area automotive assembly plants require precision-engineered folding cartons for just-in-time component kitting.
Canada
Quebec and Ontario extended producer responsibility frameworks create compliance-service revenue streams for converters with design-for-recycling certification. Health Canada and the Canadian Food Inspection Agency govern fiber sourcing and food-contact safety standards for cross-border trade. Toronto and Montreal packaging clusters serve pharmaceutical cold chain expansion into biologics distribution.
Mexico
Nearshoring of electronics assembly to Baja California and Chihuahua generates demand for anti-static corrugated protection in border manufacturing zones. Mexico's federal environmental regulations align with US EPA thresholds for recycled content in export-bound packaging. Mexico City metropolitan area converters supply beverage bottlers serving club store distribution channels.
North America Corrugated and Folding Carton Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying linerboard and coated grades to independent converters. The North American market exhibits moderate consolidation, with integrated mill-and-convert networks competing against regional independent box plants. Two strategic archetypes dominate: vertically integrated producers controlling pulp-to-box supply chains, and specialized coating and printing houses targeting premium consumer goods. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure captive containerboard supply or access digital print capabilities.
Among integrated North American producers, Georgia-Pacific LLC, International Paper Company, and WestRock Company exemplify the scale-driven platform archetype. These entities anchor supply security through massive kraft linerboard capacity serving the Midwest industrial belt. Regional specialists including Cascades Inc. and Packaging Corporation of America occupy positions emphasizing recycled fiber integration and proximity to Great Lakes manufacturing corridors. Sonoco Products Company and Graphic Packaging International represent the diversified packaging conglomerate model, with portfolios spanning multiple substrate categories beyond corrugated.
| Leading Market Players |
|---|
| Georgia-Pacific LLC |
| Sonoco Products Company |
| International Paper Company |
| WestRock Company |
| Cascades Inc. |
| Smurfit WestRock |
| Graphic Packaging International |
| Hood Packaging |
| Packaging Corporation of America |
| Others |
Pricing and Supply Chain Analysis
Old corrugated container price volatility determines both pricing tier spreads and supply chain shape across North American corrugated markets, as recycled fiber input cost swings compress converter margins unpredictably while forcing geographic sourcing diversification away from single-source dependencies.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on certification grade and customization intensity. Premium tiers command spreads through FDA food-contact compliance and multi-state EPR certification, while commodity corrugated faces cost compression from spot-market OCC fluctuations. Automotive and beverage logistics buyers exhibit highest price sensitivity due to closed-loop plastic container substitution threats, whereas pharmaceutical cold chain applications show lowest sensitivity given temperature-performance requirements.
Supply Chain Analysis
Supplier-financing mechanisms including extended payment terms and supply-chain finance facilities have become critical liquidity tools for independent converters facing working capital pressure from rail-served mill dependencies. Containerboard production concentrates in the United States, with Canadian pulp integration and Mexican nearshoring capacity providing geographic balance. The supply chain draws from virgin kraft pulp, recycled OCC fiber, and starch adhesive inputs. Single-source vulnerability to Southeastern linerboard mill concentration creates freight cost disadvantages for Midwest converters lacking rail siding access. Distribution runs through direct procurement relationships between e-commerce fulfillment operators and regional converters, bypassing traditional merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against reusable plastic bulk containers in closed-loop automotive and beverage logistics, where corrugated incumbents must demonstrate total-cost-of-ownership parity to retain high-rotation applications.
For Market Incumbents: Harden supply security through captive linerboard capacity or long-term offtake agreements with Southeastern mills, while accelerating design-for-recycling certification to capture Quebec and Ontario EPR compliance-service revenue. Plastic pallet substitution in automotive sequencing represents the primary threat requiring structural response through integrated phase-change material capabilities for temperature-sensitive biologics cold chain expansion.
For New Entrants and Emerging Players: Regional independent box plants in the Great Lakes corridor without rail siding access represent the most penetrable entry point, given freight cost disadvantages facing incumbent converters. Digital print convergence capabilities enabling lot-size-one customization for direct-to-consumer subscription boxes offer differentiation leverage. Target pharmaceutical cold chain shippers in Massachusetts and California through insulated corrugated with phase-change material integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated producers with mill-and-convert networks over standalone converters exposed to fiber cost volatility. Acquisition candidates should demonstrate multi-state EPR compliance certification and e-commerce fulfillment platform integration. Monitor state-level extended producer responsibility legislation expansion beyond California, Maine, and Oregon as the signal indicating acceleration of compliance-service revenue capture opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linerboard Capacity | Captive containerboard supply insulates margins from OCC price volatility and Southeastern mill concentration. |
| Digital Print Platform Acquisition | Inkjet decoration with inline die-cutting enables lot-size-one customization for e-commerce subscription channels. |
| Multi-State EPR Certification Investment | Design-for-recycling credentials unlock compliance-service revenue under California, Maine, and Oregon frameworks. |
| Phase-Change Material Partnership | Insulated shipper capabilities address biologics cold chain expansion in Massachusetts and California pharmaceutical clusters. |
| Regional Fulfillment Proximity Expansion | Same-day delivery promises in the Great Lakes corridor require local production sites with automated sortation compatibility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA recycled content filings, state environmental agency EPR rulemakings, and containerboard trade flow data through triangulation with mill operators, independent converters, e-commerce fulfillment procurement leads, and automotive Tier 1 packaging engineers. Bottom-up demand modeling across food processing clusters and pharmaceutical distribution networks validates against top-down capacity assessments from integrated producers.
Forecast inputs include corrugator utilization rates, e-commerce fulfillment center expansion pipelines, and state-level EPR adoption trajectories across the projection horizon. Segmentation dimensions encompass product type, end-use industry, material grade, and geographic production cluster. CAGRs derive from demand elasticity modeling against recycled fiber cost scenarios and substitution dynamics with reusable plastic containers.
Practitioners should monitor OCC export demand to Asian paper mills and pending federal packaging legislation interactions with provincial regulations for early signals of margin compression or compliance cost reallocation. Macroeconomic deviation in consumer goods distribution, regulatory acceleration in extended producer responsibility frameworks, or breakthroughs in plastic container reusability would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Beverage Cartons Market
Cartons
Pick and Place Carton Packers Market
Cartons
Twist Opening Cartons Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Wax Boxes Market
Cartons
Tuck Top Box Market
Cartons
Brick Liquid Carton Market
Cartons
Cartoning Machines Market
Cartons
Beverage Cartoners Market
Cartons
Braille Cartons Packaging Market
Cartons
Printed Folding Cartons Market
Cartons
Carton Bottle Market
Cartons
Digital Folding Cartons Market
Cartons
MET-PET Cartons Market
Cartons
Global Hand Carton Sealers Market
Cartons
Soap Boxes Market