
 Round Corrugated Box Market | 2026-2036
Round Corrugated Box Market Size, Share, and Industry Trends Forecast 2026-2036
Round Corrugated Box Market Analytics
Digital print-to-pack workflows and automated die-cutting integration are reshaping how round corrugated boxes are engineered for short-run customization. International Paper leverages its North American containerboard network to sustain cost-competitive supply of specialty round formats. WestRock anchors its position through advanced coating technologies that enhance moisture resistance in food-contact applications. Smurfit Kappa competes across European horticultural channels with tailored nested and infinity configurations for agricultural exporters.
A round corrugated box consists of concentrically formed fluted paperboard layers, typically constructed from kraft linerboard and medium with flute profiles ranging from A-flute to E-flute, engineered to distribute radial compressive loads and protect cylindrical or curved contents during distribution. Virgin fiber and combination board materials command premium positioning where burst strength and printability requirements exceed recycled pulp performance thresholds. Customized round boxes represent the fastest-growing product type as e-commerce fulfillment and subscription gifting channels demand brand-differentiated dimensional formats. Food packaging end-use applications concentrate margin pools, particularly in fresh produce and premium confectionery segments where structural integrity and shelf presentation converge.
FDA food-contact substance regulations and EPA recycled content guidelines in the United States shape material selection and migration testing protocols for domestic converters. The EU Green Deal and F-Gas Regulation indirectly steer fiber-based insulation alternatives, reinforcing corrugated substitution against expanded polystyrene in temperature-sensitive distribution. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple jurisdictions redefine cost allocation between converters and brand owners across circular packaging systems.
Market Dynamics
Digital print-to-pack workflows and automated die-cutting integration are compressing order-to-delivery cycles, forcing converters to reconfigure production lines for batch-size-one economics in round corrugated formats.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are accelerating fiber-based circular designs across European horticultural channels.
- Fresh produce exporters in Latin America:Ocean freight ventilation requirements are expanding adoption of round corrugated formats for improved stacking efficiency.
- Digital print-to-pack workflows:Short-run customization capabilities are unlocking brand-differentiated dimensional formats for e-commerce fulfillment.
Market Restraints
- Recycled fiber quality variance:Burst strength thresholds in food-contact applications require virgin fiber or combination board, elevating material costs.
- Converter concentration in Western India:Food processing clusters near Mumbai and Pune create geographic supply vulnerability for specialized produce packaging.
- EPS substitution resistance:Expanded polystyrene retains cost advantage in temperature-sensitive distribution despite EU Green Deal fiber incentives.
Strategic Opportunities
- Nested and infinity configurations:Agricultural exporters are demanding tailored round box geometries for optimized container utilization.
- Moisture-resistant coating convergence:Advanced barrier technologies are opening premium confectionery segments where structural integrity meets shelf presentation.
- Extended producer responsibility frameworks:Evolving cost allocation rules are creating service-based revenue models for circular packaging systems.
Industry Challenges
- Migration testing protocols:FDA food-contact substance regulations require specialized laboratory capacity that mid-tier converters lack.
- Die-cutting automation integration:Legacy scoring and cutting equipment cannot achieve the radial precision required for concentric flute formation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Round Corrugated Box Market |
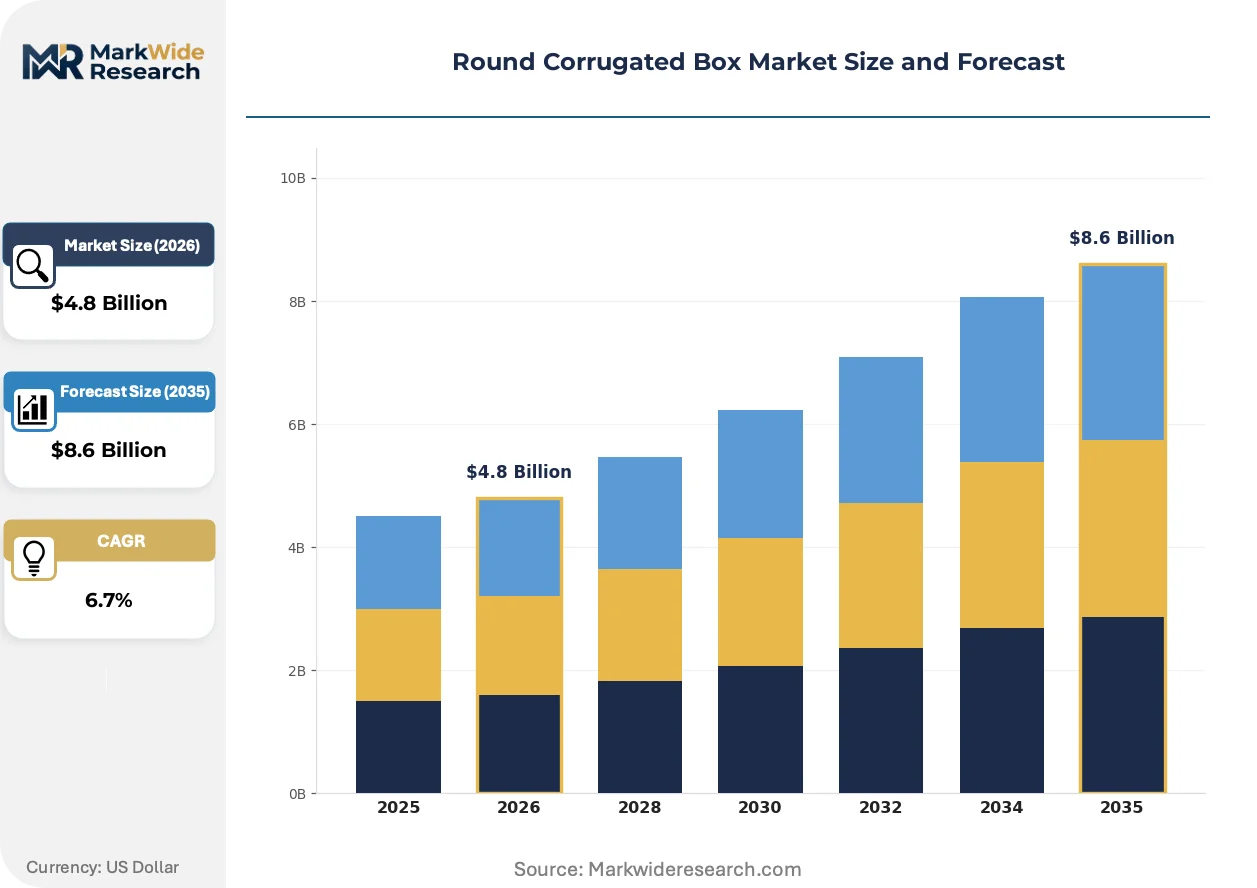
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Round Boxes, Customized Round Boxes, Infinity Round Boxes, Nested Round Boxes Material Type: Recycled Paper, Virgin Fiber, Combination Board, Biodegradable Material End Use: Food Packaging, Industrial Packaging, Retail Packaging, Gift Packaging Size: Small, Medium, Large, Extra Large |
| Companies Covered | International Paper, WestRock, Smurfit Kappa, DS Smith, Packaging Corporation of America, Mondi Group, Rengo, Georgia-Pacific, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Round Corrugated Box Market Evolving Landscape
Automation and material science are converging to redefine how round corrugated boxes are engineered, produced, and specified across fragmented end-use verticals.
High-speed digital printing with aqueous inkjet systems is rendering obsolete conventional flexographic plate costs and setup waste for short-run specialty formats. Premium confectionery brands and subscription box services are adopting these systems at accelerating pace. The technology is compressing minimum order quantities from thousands to hundreds of units.
REACH chemical compliance and the EU F-Gas Regulation are restricting fluorinated barrier treatments in fiber-based insulation applications. Industrial converters are pivoting toward bio-based coatings and wax-alternative moisture barriers. Fresh produce packaging for export markets faces the most acute reformulation pressure.
Brand owners are consolidating supplier relationships around converters offering integrated design-to-delivery platforms. E-commerce fulfillment channels are displacing traditional wholesale procurement for produce and gift packaging. India's western industrial corridor exhibits the most pronounced buyer concentration effects.
Round Corrugated Box Market Segmentation
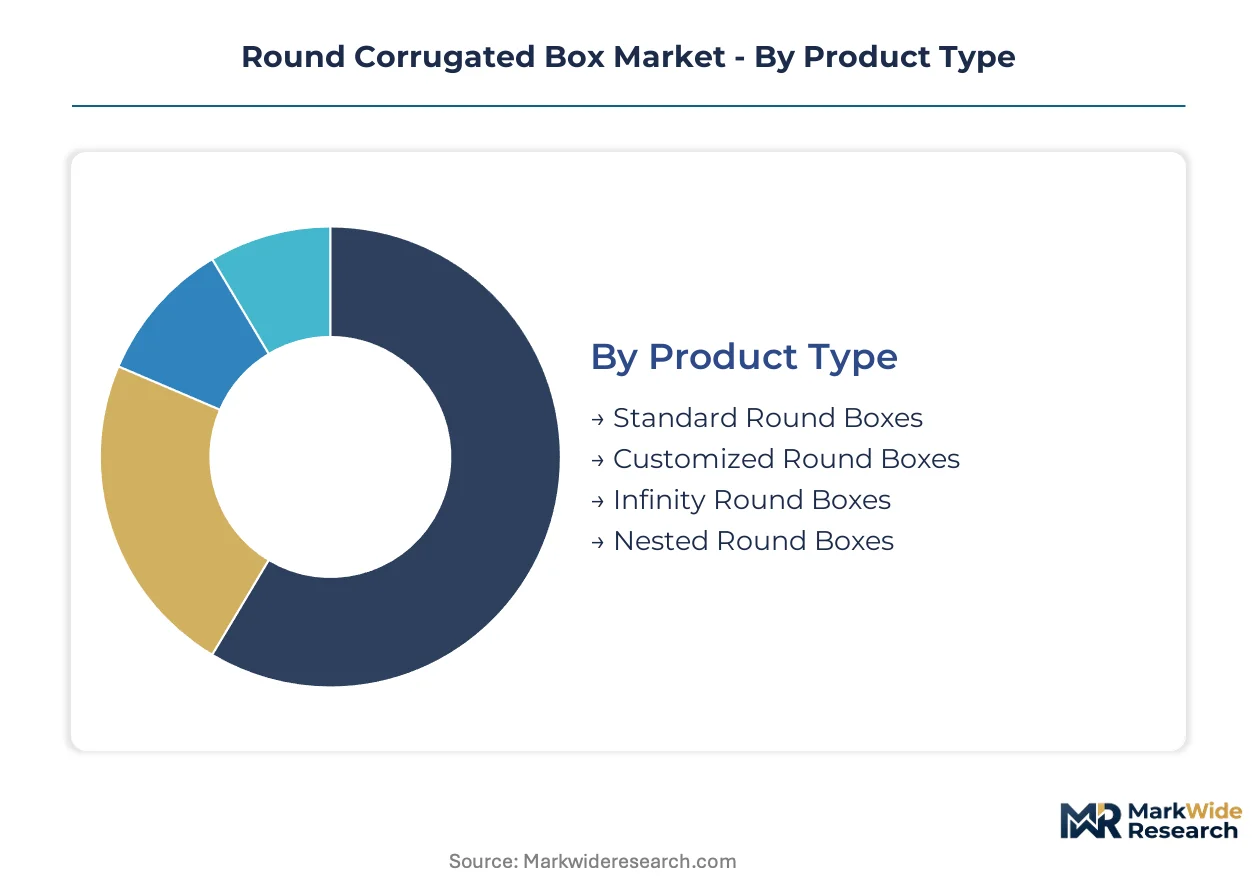
Round corrugated box specifications vary sharply across end-use requirements, from moisture-resistant food-contact grades to decorative gift formats demanding premium print surfaces. Material selection and dimensional tolerances determine converter capability requirements and margin structures.
Product Type:
Converters engineer distinct geometries to match handling automation, nesting density, and brand presentation needs across supply chains.
- Standard Round Boxes:Fixed-diameter formats with uniform flute profiles serve high-volume produce distributors requiring predictable stacking strength. Demand concentrates in Latin American fresh fruit exporters seeking ocean freight ventilation efficiency.
- Customized Round Boxes:Brand-specified dimensions with variable flute configurations and print-ready surfaces dominate e-commerce subscription channels. Short-run digital workflows compress minimum order quantities from thousands to hundreds of units.
- Infinity Round Boxes:Continuous spiral-wound construction eliminates seams for premium confectionery presentation.
- Nested Round Boxes:Concentric diameter sets optimize container cube utilization for agricultural exporters.
The dominant share belongs to Standard Round Boxes, while Customized Round Boxes is closing the gap fastest.
Material Type:
Cost tiers separate applications where burst strength thresholds and food-contact compliance drive specification decisions.
- Virgin Fiber:Unbleached kraft linerboard delivers superior tear resistance and printability for premium retail formats. FDA food-contact substance regulations mandate migration testing protocols that virgin fiber suppliers document comprehensively.
- Combination Board:Virgin linerboard faces with recycled medium balance performance and sustainability positioning. Fresh produce packers in India's western industrial corridor specify this grade for export shipments.
- Recycled Paper:Post-consumer content satisfies EU Packaging and Packaging Waste Regulation recyclability mandates at lower unit cost.
- Biodegradable Material:Bio-based coatings and wax-alternative barriers respond to REACH chemical compliance pressures.
Virgin Fiber commands the premium tier, though Combination Board is expanding most quickly as converters optimize cost-performance ratios.
End Use:
Application-specific performance requirements dictate coating chemistry, structural reinforcement, and print finish specifications.
- Food Packaging:Moisture-resistant barriers and FDA-compliant coatings protect fresh produce and confectionery through distribution. EU F-Gas Regulation restrictions on fluorinated treatments accelerate bio-based coating development.
- Retail Packaging:High-graphic surfaces and dimensional precision support shelf presentation for consumer goods.
- Industrial Packaging:Heavy-duty flute profiles withstand compression loads for automotive and electronics components.
- Gift Packaging:Specialty finishes and nested configurations serve subscription box services and seasonal merchandise.
Food Packaging generates the deepest margin pools, while Gift Packaging is climbing the fastest on e-commerce fulfillment expansion.
Size:
Volume concentration and handling automation compatibility shape production line configuration and die-cutting investment priorities.
- Medium:Diameters between 150-300mm match automated produce packing lines and standard pallet patterns. Mumbai and Pune food processing clusters specify this range for domestic and export shipments.
- Large:Formats exceeding 300mm diameter accommodate bulk produce and industrial components requiring radial load distribution.
- Small:Compact diameters suit premium confectionery and cosmetic sampling programs.
- Extra Large:Specialized diameters serve bulk agricultural commodities with custom handling equipment.
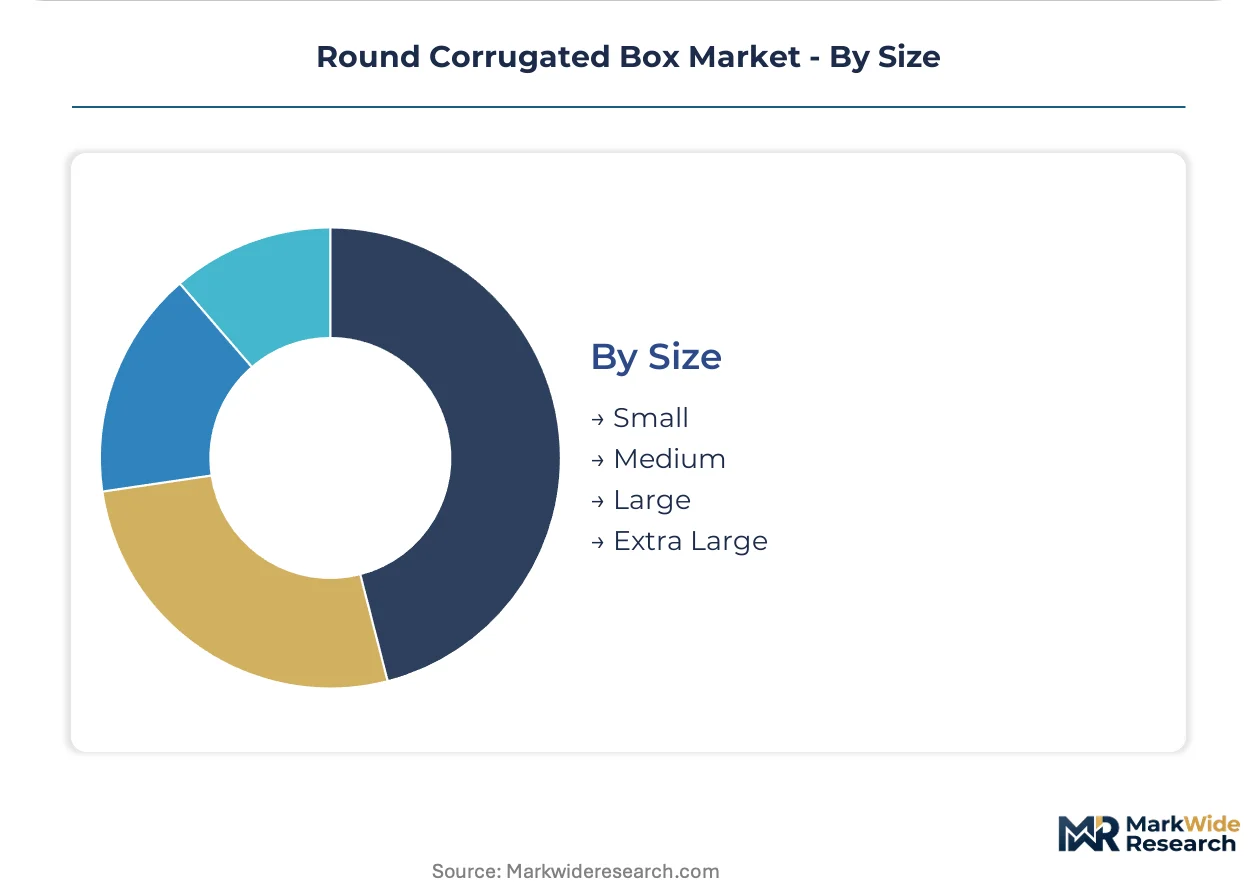
Medium sizes anchor production volumes, while Large formats are gaining share fastest on agricultural export automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin American fresh produce exporters ship round corrugated formats to European retail buyers, while Indian converters supply domestic food processors and Middle Eastern distributors. Regulatory divergence across these trade corridors shapes material specifications and compliance investments.
United States
Food-contact migration testing requirements from FDA drive virgin fiber specification for premium confectionery packaging. EPA recycled content guidelines influence converter procurement strategies in the Southeast. Georgia-Pacific operates integrated containerboard mills serving specialty round format demand from Atlanta-area distribution hubs.
Germany
EU Green Deal targets and REACH chemical restrictions accelerate bio-based coating development for horticultural exports. ECHA compliance documentation requirements favor established converters with dedicated laboratory capacity. Bavarian packaging clusters near Nuremberg specialize in nested infinity configurations for agricultural logistics.
India
FSSAI food safety mandates and DGFT export promotion schemes concentrate investment in Maharashtra's western industrial corridor. BIS quality certification requirements filter supplier participation in institutional procurement. Mumbai and Pune food processing clusters specify combination board grades for domestic retail and Gulf Cooperation Council export shipments.
Brazil
São Paulo state environmental regulations and ANVISA food-contact protocols elevate compliance costs for recycled fiber integration. Fresh fruit exporters in the Triângulo Mineiro region adopt ventilated round formats for European supermarket private label programs. Campinas-based converters expand die-cutting automation for short-run agricultural packaging.
China
SAMR food packaging standards and dual carbon goals reshape material sourcing for premium gift formats. Yangtze River Delta converters develop moisture-resistant barriers for confectionery export to Japan and South Korea. Zhejiang province specialty board producers supply e-commerce subscription box channels with digital print-ready surfaces.
Round Corrugated Box Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Integrated containerboard producers leverage captive pulp supply and North American distribution networks against regional converters with horticultural channel expertise. Three archetypes dominate: scale-driven integrated producers, coating-technology specialists, and agricultural-export-focused format engineers. Competitive moves center on automated die-cutting acquisition and bio-based barrier formulation partnerships.
Among North American integrated producers, International Paper and WestRock occupy positions anchored by containerboard network scale. Smurfit Kapa represents the European horticultural specialist archetype with nested configuration capabilities. These three exemplify how geographic production integration and end-use application depth define competitive differentiation in specialty round format supply.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Smurfit Kappa |
| DS Smith |
| Packaging Corporation of America |
| Mondi Group |
| Rengo |
| Georgia-Pacific |
| Stora Enso |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's Yangtze River Delta containerboard mills is compressing export linerboard pricing, forcing Indian and Brazilian converters to absorb margin erosion or switch toward combination board formulations. This utilization-driven pressure cascades into procurement behavior, with Mumbai-based food processors demanding longer payment terms while São Paulo exporters lock in annual contracts to hedge volatility.
Pricing Analysis
Digital-generation flexographic workflows command 15-20% premiums over conventional plate-based systems, while legacy die-cutting equipment trades at distressed valuations. Three-tier pricing structure across premium, standard, and economy levels stratifies by flute precision and FDA migration documentation completeness. Cost compression in standard grades is intensifying because recycled fiber quality variance forces virgin linerboard substitution. E-commerce subscription channels exhibit least price sensitivity, while Latin American agricultural exporters negotiate aggressively on ocean-freight volume commitments.
Supply Chain Analysis
Tariff exposure between the United States and Canada disrupts kraft linerboard arbitrage flows that historically supplied Northeastern US specialty converters. Raw material procurement draws from Swedish bleached kraft pulp, Brazilian eucalyptus hardwood, and recycled OCC collections across the EU. Single-source vulnerability concentrates in moisture-resistant coating chemistries, where REACH-compliant bio-based formulations remain limited to three German chemical suppliers. Distribution runs through converter-direct relationships with Mumbai and Pune food clusters, bypassing traditional merchant paper distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Round corrugated box supply is evolving into a service-attach business, where extended producer responsibility compliance management and digital print-to-pack workflow integration generate recurring revenue streams expanding faster than physical box production.
For Market Incumbents: Pre-empt coating-technology commoditization by acquiring bio-based barrier formulation startups before EU F-Gas Regulation deadlines tighten. Defend margin position through captive containerboard integration in the US Southeast, where EPA recycled content guidelines favor integrated producers with in-house pulp recovery. Channel control via design-to-delivery platforms locks out mid-tier competitors lacking migration testing laboratory capacity. For New Entrants and Emerging Players: Build out digital print-to-pack service capabilities targeting India's western industrial corridor, where FSSAI certification requirements filter incumbent participation. The most penetrable white space sits in nested infinity configurations for Gulf Cooperation Council agricultural exporters, where Smurfit Kappa's European focus leaves coordination gaps. A design-engineering-led go-to-market model, bundling structural optimization software with physical production, differentiates against commodity converters. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated die-cutting and aqueous inkjet installation, favoring scaled platforms over fragmented regional operators. Long-term viability over a multi-year horizon rests on circular packaging service revenue attachment rates, not box volume growth. Acquisition targets should demonstrate established ECHA or FDA laboratory relationships. The signal to watch is converter consolidation velocity in Maharashtra, where BIS certification backlogs indicate capability scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Die-Cutting Acquisition | Radial precision requirements eliminate legacy scoring equipment from premium produce segments. |
| Bio-Based Coating Partnership | REACH fluorinated restrictions force reformulation alliances with German chemical specialists. |
| Extended Producer Responsibility Service Launch | EU Packaging and Packaging Waste Regulation cost allocation creates recurring compliance revenue. |
| Digital Print-to-Pack Integration | Aqueous inkjet compression of MOQs unlocks e-commerce subscription channel access. |
| Nested Configuration Engineering | Optimized container cube utilization commands premiums from Latin American agricultural exporters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with corrugated plant managers, food processing procurement leads, agricultural export logistics coordinators, and digital print system integrators. Secondary validation drew from customs trade data, SEC containerboard producer filings, FSSAI compliance registries, and EU ECHA substance restriction notices. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Calibration against historical capacity utilization rates and trade flow disruptions shaped the analytical framework. Segmentation dimensions modeled include product geometry type, material grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections incorporating converter capital expenditure cycles and ocean freight rate volatility as industry-specific inputs.
Practitioners should monitor EU Packaging and Packaging Waste Regulation implementation timelines and FDA food-contact substance guidance revisions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Tetrahedron Carton Market
Cartons
Digital Printed Cartons Market
Cartons
Brick Carton Packaging Market
Cartons
Carton Serialization Machine Market
Cartons
Carton Sealer Machine Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Tuck Top Box Market
Cartons
End Load Cartoning Machine Market
Cartons
Fluted Carton Trays Market
Cartons
Europe Corrugated Box Market
Cartons
GCC Folding Carton Market
Cartons
Global Open Top Cartons Market
Cartons
Cartoning Machines Market
Cartons
Carton Sealer Market
Cartons
Global Folding Carton Packaging Market
Cartons
Global Crash Lock Bottom Cartons Market