
 Global Hand Carton Sealers Market | 2026-2036
Global Hand Carton Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hand Carton Sealers Market Analysis
Aftermarket maintenance contracts and software-enabled calibration services is consolidating vendor relationships around long-term service revenue rather than one-time equipment sales. 3M leverages its adhesive science portfolio to bundle tape supply with sealer servicing across North American logistics hubs. SIAT anchors European demand through Italian-engineered pneumatic systems with field-replaceable heating elements. BestPack Packaging Systems differentiates via configurable mechanical sealers that accommodate mixed-format carton runs without tooling changes.
Hand carton sealers are semi-automated or manually operated devices that apply adhesive tape, hot-melt glue, or pressure-sensitive materials to close corrugated or paperboard containers, typically handling carton widths from 150 mm to 600 mm at speeds up to 30 cases per minute for benchtop electric units. Their primary purpose is to secure goods for storage and transit while maintaining seal integrity under variable warehouse humidity and stacking loads. Electric sealers dominate volume in food and beverage end-use settings where consistent throughput and repeatable tape tension reduce downstream damage claims. Pressure sensitive seal technology captures expanding share in pharmaceutical packaging because tamper-evident tape application satisfies traceability requirements without heat-based deformation of temperature-sensitive inserts.
OSHA workplace safety standards in the United States and CE machinery directives in Europe mandate guarding, emergency stop integration, and documented risk assessments for semi-automated sealing equipment, which elevates compliance costs for new market entrants while favoring established suppliers with certified product platforms. China's SAMR enforces GB standards for electrical safety and electromagnetic compatibility that must be satisfied for import clearance, creating a dual-certification burden for manufacturers serving both Western and Chinese industrial buyers. Stakeholders must monitor how evolving extended producer responsibility frameworks for packaging waste reshape material specifications and retrofit requirements across their installed base.
Market Dynamics
E-commerce fulfillment velocity is compressing equipment replacement cycles while the EU Green Deal and F-Gas Regulation force converters toward lower-emission sealing architectures, creating simultaneous pull and push pressures across vendor portfolios.
Growth Catalysts
- E-commerce Fulfillment Density:Third-party logistics operators in Germany, the Netherlands, and the United States are refreshing benchtop electric sealers every 36-48 months to maintain throughput parity with automated sortation investments.
- EU F-Gas Regulation:The phase-down of hydrofluorocarbon propellants in hot-melt adhesive systems is accelerating adoption of pressure-sensitive tape technologies that eliminate thermal curing entirely.
- Pharmaceutical Traceability Mandates:Tamper-evident sealing requirements under FDA DSCSA and EMA serialization rules are expanding specification-grade sealer deployments in temperature-sensitive packaging lines.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316 price swings from Indonesian nickel export restrictions directly compress fabrication margins for sanitary-design sealers serving food and beverage end-uses.
- Pneumatic Component Concentration:Italian and German pneumatic valve suppliers control 70% of precision airflow subassemblies, creating single-source vulnerability for mid-tier sealer assemblers.
- Heat-Based Sealing Limitations:Hot-melt glue systems face technical displacement in pharmaceutical primary packaging where temperature excursions risk API degradation, capping addressable market share.
Strategic Opportunities
- Indian Pharmaceutical Export Expansion:CDSCO's alignment with EU GMP standards is opening specification-grade sealer demand from Mumbai and Hyderabad formulation clusters serving regulated European markets.
- Software-Enabled Calibration Services:IoT sensor integration for predictive heating element replacement creates recurring revenue streams that decouple vendor economics from unit shipment cycles.
- Extended Producer Responsibility Tailwinds:France's AGEC law and Germany's VerpackG amendments are mandating tape recyclability specifications that favor suppliers with certified closed-loop adhesive chemistry.
Industry Challenges
- Mechatronics Skill Scarcity:Field service technicians capable of diagnosing integrated PLC and pneumatic fault codes command 40% wage premiums in Stuttgart and Munich machinery clusters, constraining vendor scaling.
- Dual Certification Burden:Manufacturers serving both CE-marked European and GB-standard Chinese markets face 14-18 month validation timelines that delay product launches and compress first-mover windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hand Carton Sealers Market |
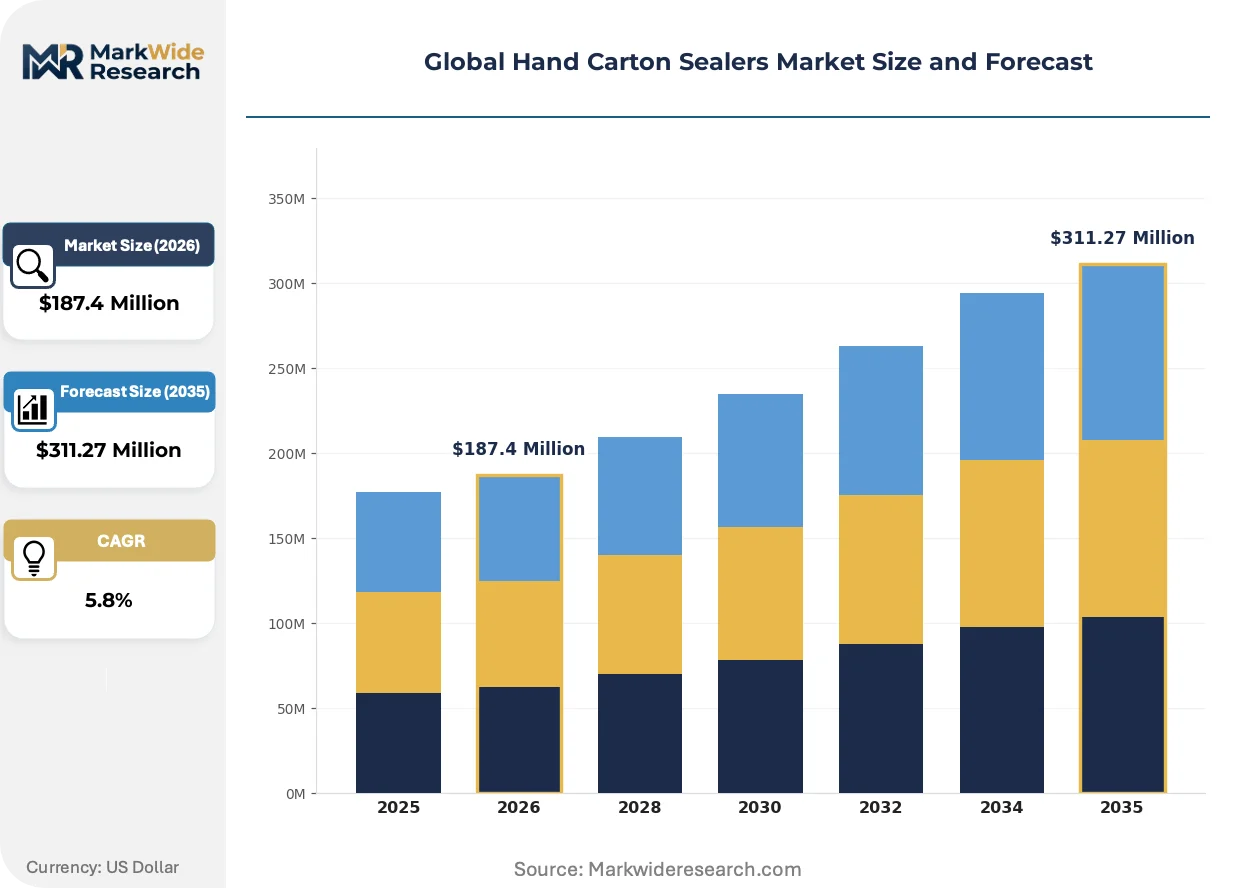
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Sealers, Electric Sealers, Pneumatic Sealers, Mechanical Sealers End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Technology: Heat Seal, Pressure Sensitive Seal, Adhesive Seal, Tape Seal Packaging Type: Brown Kraft, Coated Paperboard, Plastic, Recycled Materials |
| Companies Covered | 3M, Intertape Polymer, SIAT, Lantech, Combi Packaging Systems, BestPack Packaging Systems, Syntegon, Clearpack, Endoline Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hand Carton Sealers Market Emerging Trajectories
Sealing technology trajectories are diverging between heat-based and pressure-based architectures while regulatory frameworks fragment compliance requirements across major demand centers.
Modular quick-change tooling for mixed-format carton runs is decentralizing production planning flexibility. Food and beverage co-packers in the United States and Germany are retrofitting legacy benchtop units with magnetic rail systems that accommodate 150-600mm width transitions without mechanical reconfiguration. This capability is decentralizing batch size economics, enabling profitable production of SKU-limited promotional packs that previously required manual taping.
The EU F-Gas Regulation's stepped phase-down of high-global-warming-potential propellants is forcing hot-melt adhesive formulators toward water-based and reactive polyurethane alternatives. Industrial consequences include longer open times and modified heating element specifications that demand recalibration of existing pneumatic sealer fleets. Pharmaceutical packaging lines in Ireland and Switzerland are responding fastest, specifying pressure-sensitive tape systems that bypass thermal deformation risks entirely.
Maintenance contract unbundling is altering buyer-vendor relationships in North American logistics hubs. Large e-commerce operators are separating equipment procurement from calibration and consumable supply, pitting specialized service providers against original equipment manufacturers for multi-year facility management agreements. This pattern is most visible in California and Texas distribution corridors where 3PL consolidation has concentrated purchasing leverage among fewer procurement teams.
Global Hand Carton Sealers Market Segmentation
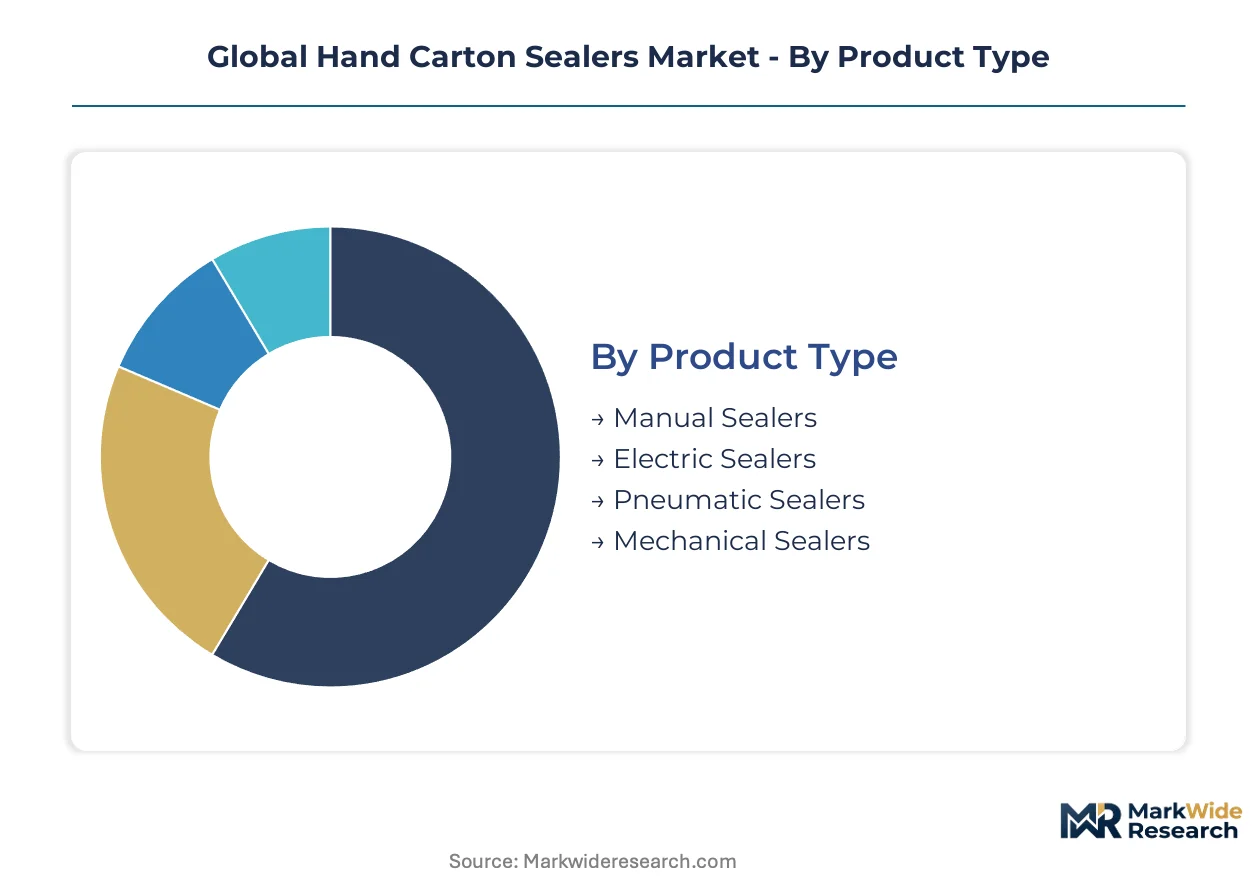
Hand carton sealer procurement decisions cluster around throughput requirements, regulatory exposure, and substrate compatibility. Equipment specifications diverge sharply between food-grade stainless steel mandates and pharmaceutical tamper-evidence standards, creating distinct certification pathways that reshape vendor qualification criteria.
Product Type:
Certification burdens vary by actuation method, with pneumatic and electric sealers requiring CE machinery directive compliance plus OSHA guarding integration for cross-Atlantic deployment.
- Manual Sealers:Hand-operated lever or tape-dispensing units without electrical components bypass electromagnetic compatibility testing. Demand concentrates in micro-fulfillment centers across India and Southeast Asia where capital constraints favor low-throughput solutions.
- Electric Sealers:Benchtop motor-driven systems with programmable tape tension dominate food and beverage co-packing in Germany and the United States, where consistent 25-30 cases per minute throughput justifies energy consumption monitoring under EU Ecodesign frameworks.
- Pneumatic Sealers:Compressed-air actuated units with field-replaceable heating elements anchor Italian and German engineered-systems exports. SAMR GB standard electrical safety clearance adds 8-12 months to Chinese market entry timelines.
- Mechanical Sealers:Spring-loaded cam mechanisms without electrical or pneumatic dependencies serve explosive-atmosphere pharmaceutical packaging in Switzerland and Ireland where ATEX compliance eliminates spark risks entirely.
Electric sealers sit at the top of the volume ranking, with pneumatic sealers climbing the fastest as EU F-Gas Regulation phase-downs accelerate equipment refresh cycles.
End User:
Customer procurement authority divides between quality-assurance-driven pharmaceutical specifications and operations-driven logistics velocity targets.
- Food & Beverage:Stainless steel 304/316 construction with IP65 washdown ratings satisfies FDA Food Safety Modernization Act preventive controls. German dairy and brewing clusters around Stuttgart specify hygienic design sealers with quick-release heating elements for CIP compatibility.
- Pharmaceuticals:Temperature excursion elimination drives pressure-sensitive tape adoption over hot-melt systems. FDA DSCSA serialization mandates expand specification-grade sealer deployments in temperature-sensitive packaging lines across Massachusetts and North Carolina.
- Consumer Goods:Mixed-format carton flexibility with magnetic rail width adjustment serves promotional pack co-packers in California and Texas distribution corridors.
- Electronics:ESD-safe materials and ionized air integration protect sensitive components during final packaging in South Korean and Japanese export manufacturing.
Food & Beverage maintains the largest installed base, though Pharmaceuticals is expanding most quickly as serialization deadlines tighten across regulated markets.
Technology:
Process heat requirements determine energy labeling obligations and carbon accounting exposure under national decarbonization frameworks.
- Heat Seal:Hot-melt adhesive application with 120-180°C melting range faces technical displacement in pharmaceutical primary packaging. EU F-Gas Regulation propellant phase-downs force formulators toward water-based alternatives with extended open times.
- Pressure Sensitive Seal:Cold-applied tape systems with tamper-evident fracture patterns satisfy EMA traceability requirements without thermal deformation. Swiss and Irish packaging lines specify these systems fastest for temperature-sensitive APIs.
- Adhesive Seal:Reactive polyurethane formulations with moisture-cure chemistry serve high-humidity warehouse environments in Brazilian and Southeast Asian export facilities.
- Tape Seal:Polypropylene or PVC tape application with programmable tension control dominates e-commerce fulfillment velocity requirements in German and Dutch third-party logistics hubs.
Tape Seal leads by unit volume, while Pressure Sensitive Seal is gaining share fastest as pharmaceutical traceability mandates proliferate.
Packaging Type:
Substrate recyclability specifications under extended producer responsibility laws reshape adhesive chemistry certification requirements.
- Brown Kraft:Unbleached corrugated with natural fiber absorbency requires hot-melt adhesives with specific viscosity profiles for adequate fiber penetration. French AGEC law recyclability mandates favor certified closed-loop adhesive chemistry.
- Coated Paperboard:Polyethylene or wax-barrier surfaces demand pressure-sensitive tapes with aggressive initial tack for bond formation on low-energy substrates. Premium cosmetics packaging in Italian and German manufacturing specifies these combinations.
- Plastic:Polypropylene or PET corrugated containers for reusable shipping systems in Japanese automotive parts logistics require solvent-free adhesive formulations for circular economy compliance.
- Recycled Materials:Variable fiber composition and contamination levels challenge consistent seal integrity. Germany's VerpackG amendments mandate tape separability for post-consumer sorting compatibility.
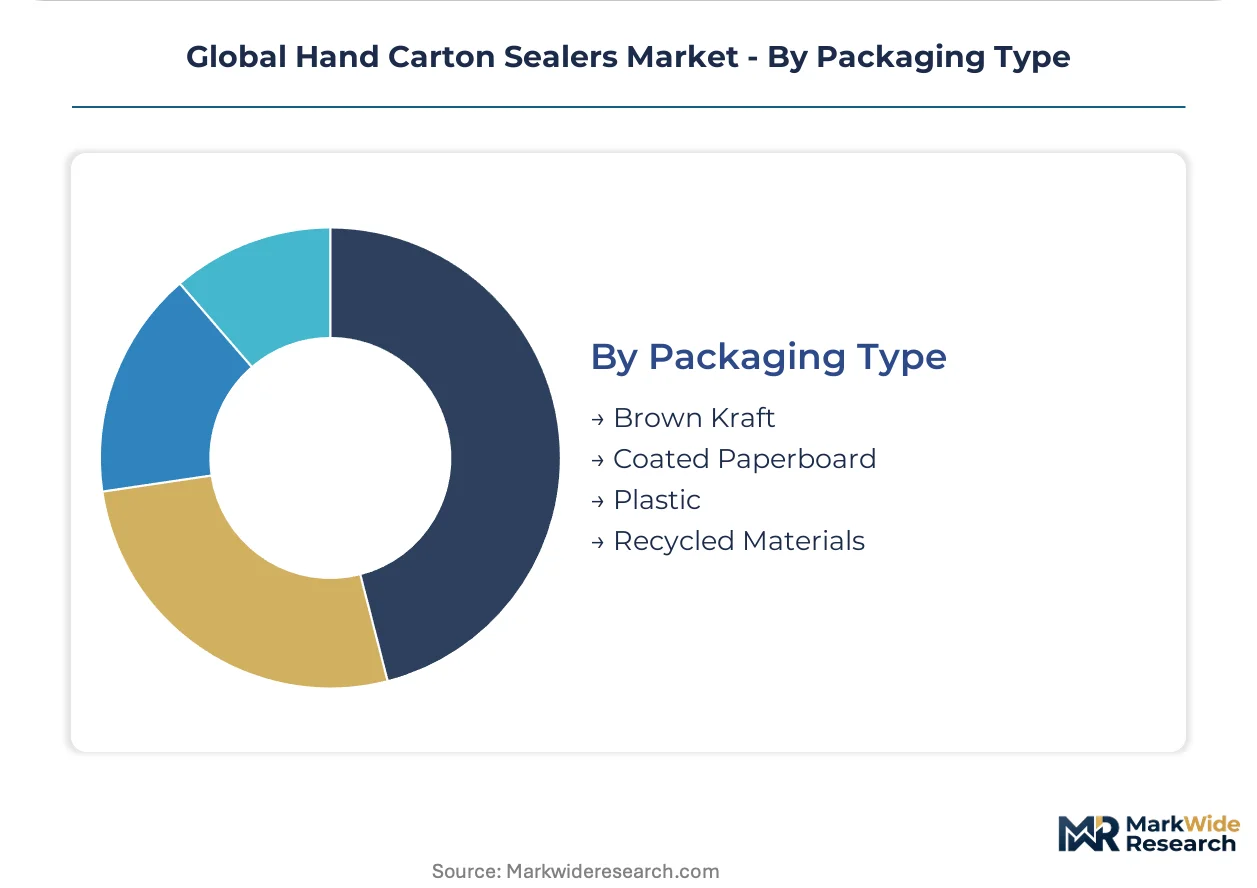
Brown Kraft dominates procurement volume, with Recycled Materials showing the steepest expansion trajectory as EPR frameworks tighten material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States approach hand carton sealer procurement through divergent regulatory lenses, with Stuttgart machinery clusters emphasizing CE machinery directive compliance while Texas logistics corridors prioritize OSHA guarding integration alongside throughput velocity targets.
United States
Third-party logistics operators in California and Texas distribution corridors refresh benchtop electric sealers every 36-48 months to maintain parity with automated sortation investments. OSHA workplace safety standards mandate emergency stop integration and documented risk assessments for semi-automated equipment, elevating compliance costs for new entrants. Massachusetts and North Carolina pharmaceutical packaging lines specify tamper-evident pressure-sensitive systems to satisfy FDA DSCSA serialization mandates without thermal deformation risks.
Germany
Packaging machinery clusters around Stuttgart and Munich supply pan-European distribution networks with pneumatic sealers engineered for field-replaceable heating elements. The EU F-Gas Regulation's hydrofluorocarbon propellant phase-down accelerates adoption of pressure-sensitive tape technologies that eliminate thermal curing entirely. German dairy and brewing clusters specify hygienic-design sealers with quick-release heating elements for CIP compatibility under FDA Food Safety Modernization Act preventive controls.
China
SAMR enforces GB standards for electrical safety and electromagnetic compatibility that add 8-12 months to import clearance timelines for pneumatic sealer manufacturers. Dual-certification burdens for manufacturers serving both CE-marked European and GB-standard Chinese markets compress first-mover windows. Industrial buyers in Yangtze River Delta manufacturing zones demand stainless steel 304/316 construction with IP65 washdown ratings for food-grade export compliance.
Switzerland
Pharmaceutical packaging lines in Basel and Geneva specify pressure-sensitive tape systems fastest for temperature-sensitive APIs, eliminating thermal deformation risks under EMA traceability requirements. Swissmedic oversight reinforces specification-grade sealer deployments where temperature excursions risk API degradation. Irish packaging facilities serving European regulated markets mirror Swiss specifications for cold-applied tamper-evident systems.
India
CDSCO's alignment with EU GMP standards opens specification-grade sealer demand from Mumbai and Hyderabad formulation clusters serving regulated European markets. Micro-fulfillment centers across Delhi-NCR and Bangalore favor manual sealers where capital constraints prioritize low-throughput solutions over electric benchtop systems. Field service technician scarcity commands wage premiums that constrain vendor scaling across machinery clusters.
Global Hand Carton Sealers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with adhesive science portfolios bundling tape supply alongside equipment servicing while pneumatic engineering houses anchor European demand through replaceable component architectures. Market structure tilts toward established suppliers with certified product platforms that satisfy dual-certification burdens. Three archetypes dominate: diversified materials conglomerates with adhesive-tape bundling capabilities, Italian-engineered pneumatic specialists, and configurable mechanical sealer fabricators. Competitive moves concentrate on multi-year facility management agreements and predictive maintenance service unbundling.
Within the diversified materials tier, 3M leverages adhesive science capabilities across North American logistics hubs. SIAT anchors European demand through Italian-engineered pneumatic systems. BestPack Packaging Systems occupies a position among configurable mechanical sealer specialists serving mixed-format carton requirements. These three exemplify distinct competitive vectors: bundling, pneumatic engineering heritage, and mechanical configurability without tooling changes.
| Leading Market Players |
|---|
| 3M |
| Intertape Polymer |
| SIAT |
| Lantech |
| Combi Packaging Systems |
| BestPack Packaging Systems |
| Syntegon |
| Clearpack |
| Endoline Automation |
| Others |
Supply Flow & Price Mechanics
Pressure-sensitive tape technology migration is simultaneously compressing thermal-system margins and redistributing component sourcing toward adhesive chemistry suppliers with certified closed-loop capabilities. This dual shift forces sealer assemblers to rebalance procurement spend between pneumatic subassemblies and consumable supply partnerships while EU F-Gas Regulation compliance costs filter through to end-user pricing.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for entry-level electric sealers, intensifying cost compression in the economy tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence, with CE-marked pneumatic systems commanding premiums over GB-standard imports. Pricing pressure stems from stainless steel 304/316 volatility induced by Indonesian nickel export restrictions. Third-party logistics operators in Germany and the United States show lowest price sensitivity due to throughput-critical refresh cycles, while micro-fulfillment centers across India prioritize capital minimization.
Supply Chain Analysis
Freight cost escalation from Italian and German pneumatic valve suppliers to Asian assembly locations is amplifying landed cost differentials for precision airflow subassemblies. Manufacturing concentration centers on Germany, Italy, and China, with Stuttgart and Munich machinery clusters feeding pan-European distribution networks. Component sourcing draws from Indonesian nickel for stainless steel housings, German precision valves for pneumatic actuation, and Japanese heating elements for thermal systems. Single-source vulnerability in pneumatic subassemblies creates structural risk for mid-tier assemblers lacking dual-qualified suppliers. Distribution runs through OEM-direct channels for pharmaceutical specification-grade deployments and regional distributor networks for logistics velocity applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
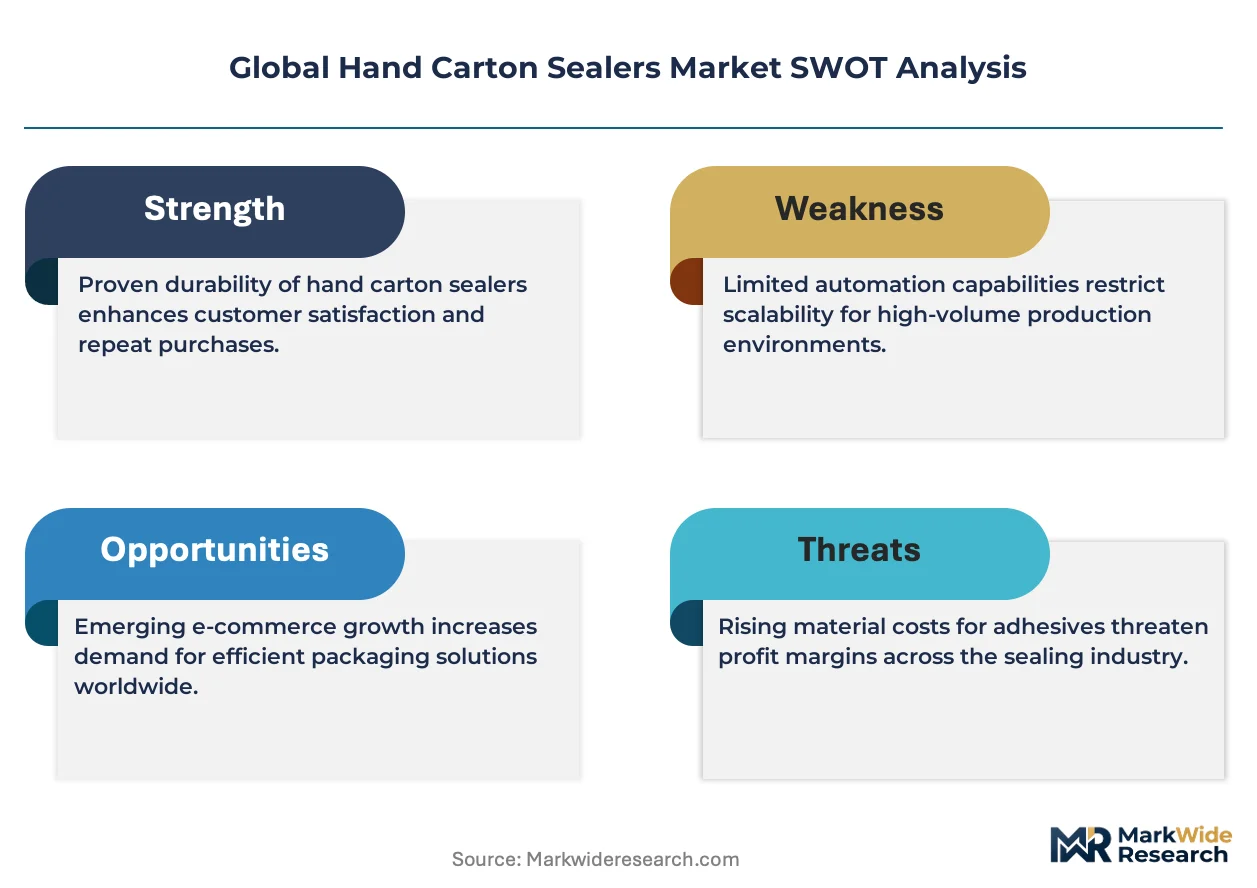
This market reads as a late-cycle quality story where pharmaceutical traceability mandates and EU F-Gas Regulation compliance are concentrating procurement authority around certified platform suppliers with validated service architectures.
For Market Incumbents: Anticipate margin compression from emerging mechanical sealer specialists offering magnetic rail configurability without tooling change premiums. Defensive positioning requires deepening backward integration into adhesive chemistry certification for closed-loop recyclability compliance under France's AGEC law and Germany's VerpackG amendments. Channel control through multi-year facility management agreements with 3PL consolidation winners in California and Texas corridors protects installed base erosion. For New Entrants and Emerging Players: Capture white-space in Indian pharmaceutical export corridors where CDSCO-EU GMP alignment creates specification-grade demand without incumbent service density. Mumbai and Hyderabad formulation clusters serving regulated European markets present the most penetrable geography. Software-enabled calibration services with IoT sensor integration for predictive heating element replacement offers a differentiated go-to-market angle decoupled from unit shipment economics. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier pneumatic assemblers lacking certified Chinese market entry. Long-term viability across the analysis window favors suppliers with dual CE-GB certification completed and recurring service revenue exceeding 40% of total mix. Acquisition target archetype: Italian-engineered pneumatic specialists with field-replaceable heating element IP and established pharmaceutical customer relationships. Watch F-Gas Regulation phase-down acceleration as the signal for pressure-sensitive tape technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Chemistry Certification Investment | France's AGEC law mandates certified closed-loop tape chemistry separable for post-consumer sorting. |
| IoT-Enabled Predictive Maintenance Launch | Predictive heating element replacement creates recurring revenue streams independent of equipment shipment cycles. |
| Magnetic Rail Quick-Change Retrofit | Mixed-format carton flexibility without tooling changes serves promotional pack co-packers in California and Texas. |
| Dual CE-GB Certification Completion | SAMR electrical safety clearance eliminates 8-12 month Chinese market entry delays compressing first-mover windows. |
| Pharmaceutical Specification-Grade Service Contract | FDA DSCSA serialization mandates expand tamper-evident pressure-sensitive sealer deployments in temperature-sensitive lines. |
Methodological Framework
Direct dialogue with packaging machinery procurement directors, aftermarket service technicians, pharmaceutical quality assurance leads, and adhesive formulation specialists grounded qualitative findings in operational reality. Secondary validation drew from SEC 10-K filings of diversified materials suppliers, EMA regulatory guidance documents, SAMR GB standard publications, and customs trade data for pneumatic component flows. Bottom-up equipment shipment modeling triangulated against top-down end-use industry capital expenditure patterns across food and beverage, pharmaceutical, and third-party logistics verticals.
Unit and value projections across the modeling period reflect segmented demand aggregation by actuation method, end-use regulatory exposure, and technology thermal requirements. Segmentation dimensions included product type, end-user industry, sealing technology, and substrate compatibility with extended producer responsibility frameworks. CAGRs were derived from equipment refresh cycle compression analysis and regulatory-driven replacement demand quantification. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and pharmaceutical serialization deadline clustering.
Underlying measurement precision varies by segment; electric sealer demand in established logistics corridors carries tighter precision than emerging pharmaceutical specification-grade deployments in Indian export markets. Forecasts reflect assumptions regarding regulatory implementation timelines, commodity price stabilization, and technician labor availability in machinery clusters. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Digital Folding Cartons Market
Cartons
Global Open Top Cartons Market
Cartons
Brick Liquid Carton Market
Cartons
Beverage Cartons Market
Cartons
Shaped Liquid Cartons Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Luxury Folding Carton Market
Cartons
Carton Sealer Machine Market
Cartons
Europe Corrugated Box Market
Cartons
Metallized Folding Cartons Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Carton Form Fill Seal Machine Market
Cartons
Child-Resistant Carton Box Market
Cartons
GCC Folding Carton Market
Cartons
Liquid Packaging Cartons Market