
 Carton Serialization Machine Market | 2026-2036
Carton Serialization Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Carton Serialization Machine Market Outlook
Stainless steel is replacing coated aluminum in critical contact surfaces, which is realigning total cost of ownership calculations for pharmaceutical packagers. Marchesini Group leverages its integrated approach across filling and packaging lines to sustain premium positioning in European installations. Syntegon Technology anchors its competitiveness through deep specialization in vision-inspection-integrated serialization architectures. Coesia Group competes by controlling a broad portfolio of coding and labeling technologies that span multiple printer modalities.
A carton serialization machine is an automated packaging system that applies unique, machine-readable identifiers—typically 2D Data Matrix or QR codes at 300 dpi or higher resolution—onto individual cartons to enable unit-level traceability through supply chains. These systems integrate print engines, vision verification cameras, and reject mechanisms to ensure code readability and data integrity for regulatory compliance and anti-counterfeiting. Inkjet printers occupy the largest installed base due to flexibility across substrate types and line speeds, while laser printers capture the fastest growth trajectory as permanent, solvent-free marking gains preference in sustainable packaging programs. The pharmaceuticals application segment commands the deepest margin pools because validation requirements and regulatory audit intensity sustain pricing premiums over food or cosmetics deployments.
The FDA's Drug Supply Chain Security Act, the EU Falsified Medicines Directive with its delegated regulation on safety features, and China's NMPA track-and-trace requirements for vaccine and pharmaceutical packaging collectively mandate serialized coding at the saleable-unit level, which directly structures equipment specifications and replacement timelines. ISO 15415 and GS1 standards further constrain permissible code grades and data formats, narrowing the supplier base to vendors with certified compliance architectures. Stakeholders must monitor how evolving national serialization deadlines and reciprocity agreements between regulators reshape geographic deployment priorities and service-network requirements.
Market Dynamics
The EU Falsified Medicines Directive's delegated regulation on safety features is compressing equipment replacement cycles across European pharmaceutical packaging lines. Serial coding mandates at the saleable-unit level are forcing capital redeployment from legacy thermal transfer systems toward vision-integrated architectures.
Growth Catalysts
- EU Falsified Medicines Directive:Mandated 2D Data Matrix codes on all prescription medicines sold in the European Economic Area drive sustained equipment refresh demand.
- Pharmaceutical manufacturers:Dense manufacturing clusters in Germany and Switzerland are executing multi-line serialization retrofits to maintain export compliance.
- Laser marking technology:Permanent, solvent-free coding gains preference in sustainable packaging programs, displacing solvent-based inkjet in high-volume vaccine lines.
Market Restraints
- Stainless steel input costs:Critical contact surface specifications are elevating bill-of-materials volatility beyond coated aluminum baselines.
- Vision system supplier concentration:Specialized camera and optics vendors in Japan and Germany create single-source risk for integrated line builders.
- Validation timeline friction:FDA 21 CFR Part 11 compliance documentation extends commissioning cycles by four to eight months for US-bound installations.
Strategic Opportunities
- India pharmaceutical exports:CDSCO alignment with EU traceability standards creates retrofit demand among domestic formulation exporters.
- Biologics cold-chain serialization:Temperature-sensitive biologics require specialized coding substrates and thermal-transfer-resistant inks.
- Waste reduction mandates:EU Packaging and Packaging Waste Regulation incentives favor laser systems that eliminate consumable ink and solvent disposal.
Industry Challenges
- Commissioning engineer scarcity:Qualified validation specialists for IQ/OQ/PQ documentation are concentrated among a handful of service firms.
- Legacy line integration:Retrofitting serialization modules onto existing cartoning lines without throughput degradation demands custom mechanical engineering.
- Multi-jurisdiction code harmonization:Simultaneous compliance with EU FMD, US DSCSA, and China NMPA requirements complicates software architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carton Serialization Machine Market |
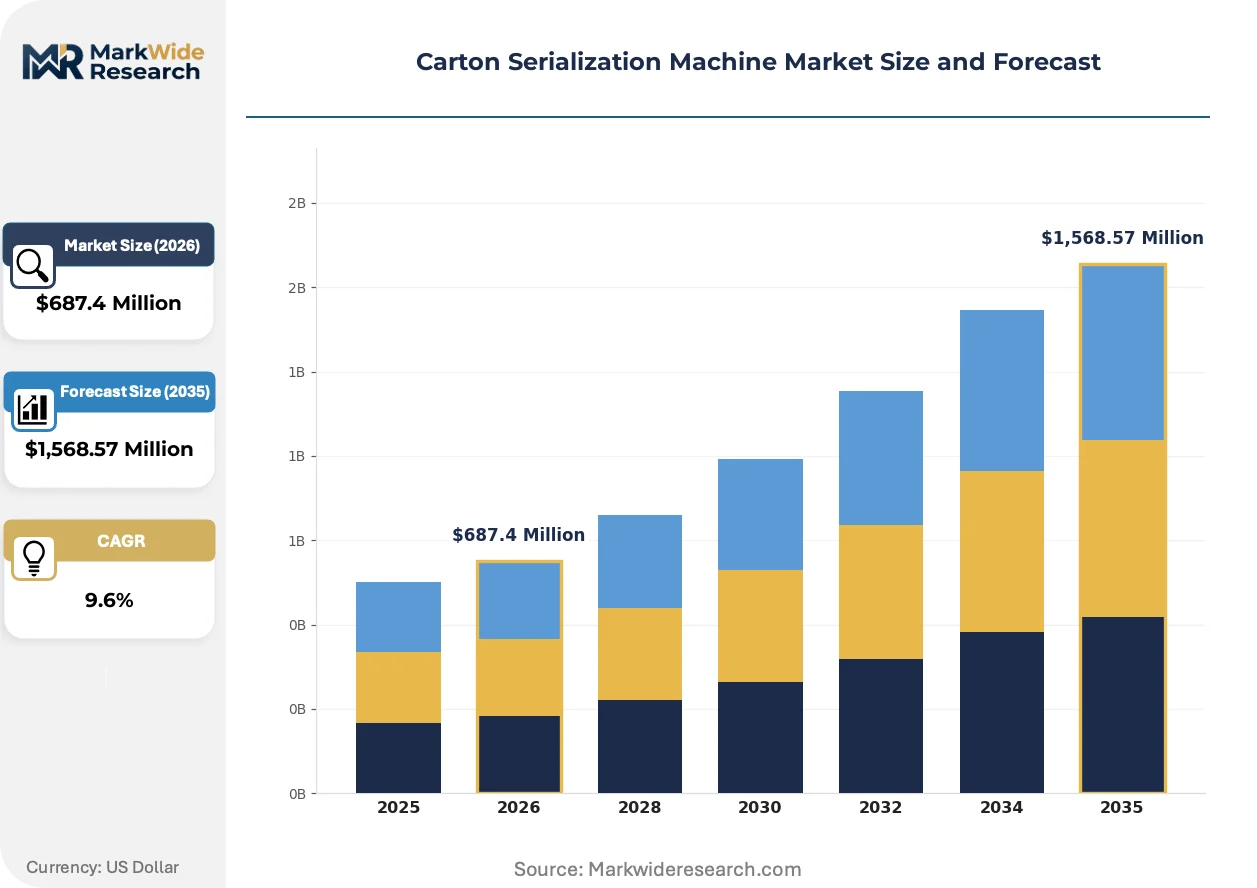
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,568.57 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Printers, Inkjet Printers, Thermal Transfer Printers, Labeling Equipment Application: Pharmaceuticals, Food & Beverage, Cosmetics, Electronics End User: Manufacturers, Distributors, Retailers, Warehouses Technology: 2D Barcodes, RFID, QR Codes, Data Matrix |
| Companies Covered | Shanghai Tops, Grandpackmachine, JOCHAMP Machinery, Marchesini Group, Wenzhou Jiade Packing Machinery Co., Ltd., IMA Group, AIPAK, Coesia Group, Syntegon Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carton Serialization Machine Market Strategic Shifts
Equipment architecture is converging around integrated vision-inspection-print-reject loops that compress quality assurance into single-machine footprints. This integration is eliminating standalone verification stations and reshaping line layout economics.
Laser marking systems are absorbing market share from continuous inkjet in pharmaceutical applications where permanent, abrasion-resistant codes are non-negotiable. Vaccine manufacturers are adopting fiber laser sources at line speeds exceeding 400 cartons per minute. The technology is absorbing capital that previously flowed to thermal inkjet retrofits, compressing the addressable market for solvent-based coding.
The EU's delegated regulation on safety features for medicinal products is mandating unique identifier verification at the point of dispensing. Hospital pharmacies and wholesale distributors must now scan and decommission serialized packs, creating downstream data infrastructure requirements. Small-volume parenteral and orphan drug manufacturers face disproportionate compliance burden relative to batch sizes.
Service contract unbundling is separating hardware warranty from software maintenance and validation support. Mid-tier pharmaceutical packagers are purchasing extended hardware coverage while managing compliance documentation in-house. This bifurcation is most visible in Germany, where dense third-party engineering services enable self-managed validation.
Carton Serialization Machine Market Segmentation
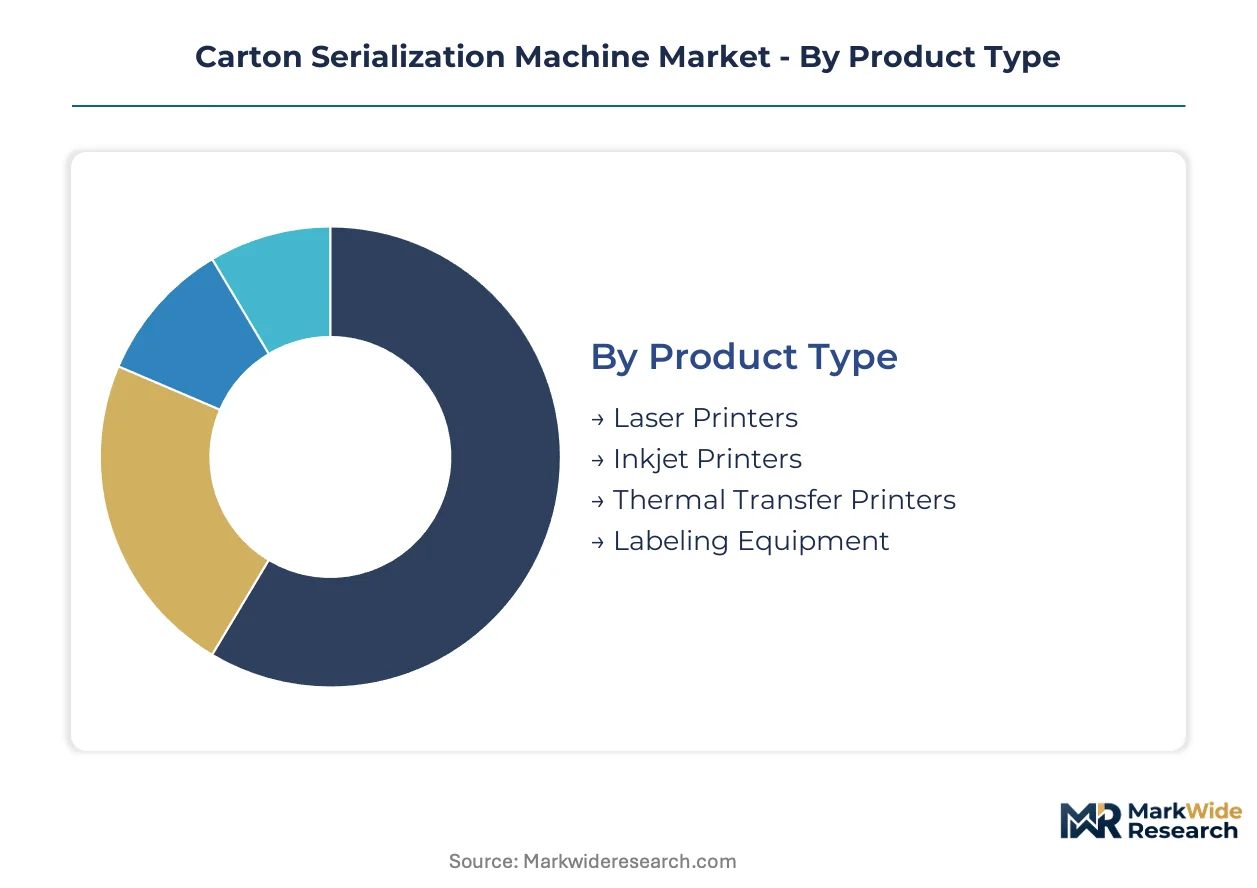
Carton serialization machine procurement patterns diver sharply across product architectures and compliance environments. Equipment specifications in pharmaceutical lines demand vision-integrated validation systems that food or cosmetics operations rarely require.
Product Type:
Supply concentration for print engine subsystems varies significantly across marking modalities, with laser source vendors in Germany and Japan commanding premium positions in permanent coding architectures.
- Laser Printers:Fiber and CO2 laser sources deliver permanent, abrasion-resistant marks without consumable inks or solvents. Vaccine manufacturers in Germany and Switzerland are adopting fiber laser systems at line speeds exceeding 400 cartons per minute to meet EU Packaging and Packaging Waste Regulation waste reduction mandates.
- Inkjet Printers:Continuous inkjet and thermal inkjet systems dominate current installed base through substrate flexibility and lower capital thresholds. Pharmaceutical packagers in India balance CDSCO alignment costs against thermal inkjet retrofit economics for export compliance.
- Thermal Transfer Printers:Ribbon-based coding persists in low-speed applications requiring precise edge definition on coated stocks.
- Labeling Equipment:Pressure-sensitive and shrink-sleeve applicators serve secondary serialization where direct marking risks substrate damage.
Inkjet printers absorb the bulk of installed capacity; laser printers are expanding most quickly.
Application:
Validation intensity and regulatory audit frequency create tiered margin structures across end-use sectors, with pharmaceutical deployments sustaining pricing premiums three to four times above food installations.
- Pharmaceuticals:FDA 21 CFR Part 11 compliance documentation and EU FMD delegated regulation mandates force capital allocation toward vision-verified architectures. German manufacturers execute multi-line retrofits to maintain EEA market access, with IQ/OQ/PQ validation cycles extending commissioning by four to eight months.
- Food & Beverage:Traceability requirements concentrate on allergen management and recall efficiency rather than unit-level serialization. Dairy and meat processors in France deploy batch-level coding under ANSM-aligned food safety protocols.
- Cosmetics:Anti-counterfeiting and grey-market diversion protection drive adoption in premium skincare and fragrance segments.
- Electronics:Component authentication and warranty validation requirements structure equipment specifications for high-value consumer devices.
Pharmaceuticals command the deepest margin pools; food and beverage offers the broadest addressable volume base.
End User:
Capital deployment authority and compliance liability distribution reshape equipment specification priorities across supply chain positions.
- Manufacturers:Primary packagers bear full validation burden for FDA, EMA, and NMPA compliance, driving specification toward integrated print-verify-reject architectures with full audit trail documentation.
- Distributors:Wholesale and logistics operators require aggregation and case-level serialization for supply chain visibility without unit-level marking equipment.
- Retailers:Pharmacy chains and hospital dispensaries in the EEA must now scan and decommission serialized packs under FMD delegated regulation verification mandates.
- Warehouses:Cold-chain storage operators for biologics demand thermal-transfer-resistant code substrates and temperature-stable marking validation.
Manufacturers absorb the bulk of installed capacity; retailers are expanding most quickly as downstream verification mandates proliferate.
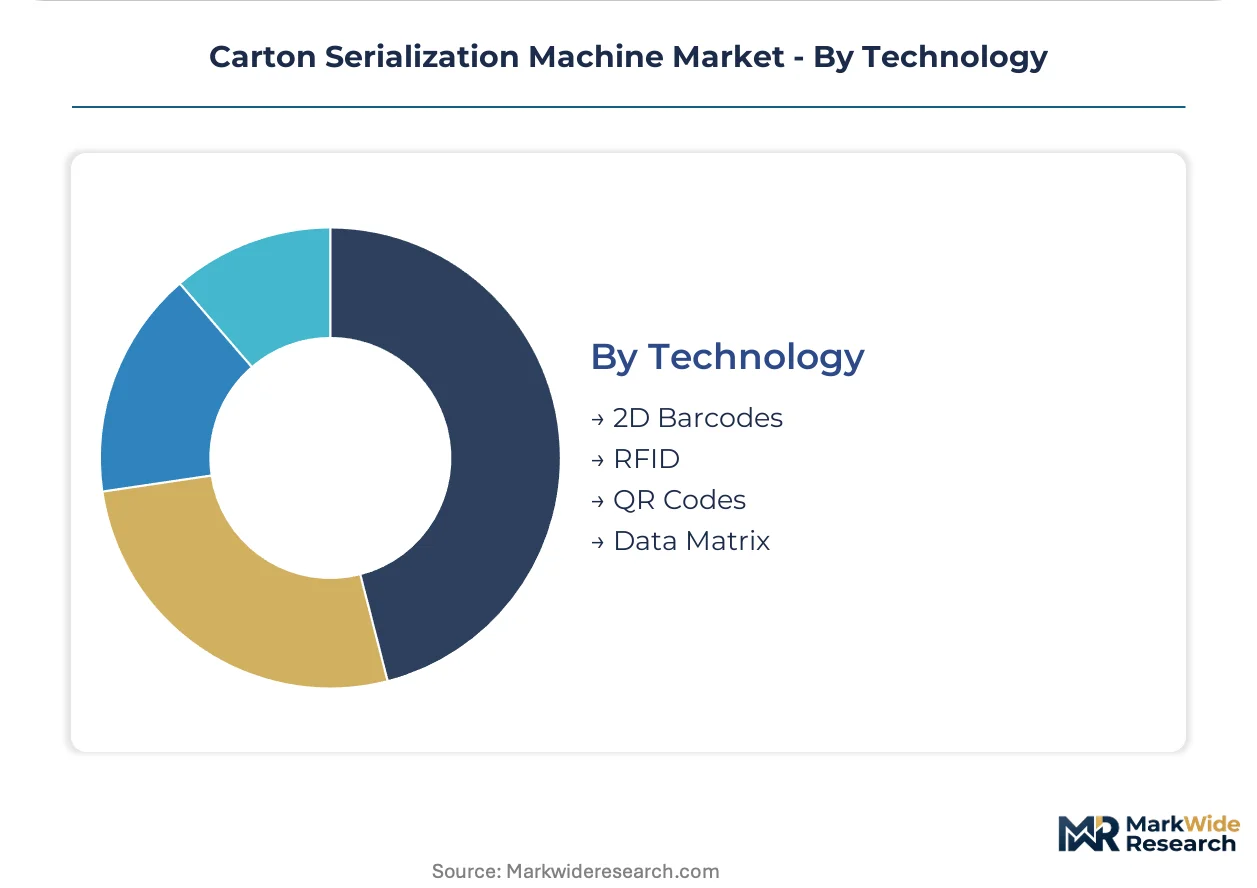
Technology:
Code symbology selection constrains software architecture and camera specification, with GS1 standards narrowing permissible formats for cross-border pharmaceutical shipments.
- 2D Barcodes:Data Matrix and QR code formats at 300 dpi or higher resolution constitute the dominant pharmaceutical standard under EU FMD and US DSCSA requirements.
- RFID:Ultra-high frequency tags enable non-line-of-sight tracking for high-value biologics and controlled substances in hospital pharmacy environments.
- QR Codes:Consumer-facing traceability and authentication applications leverage smartphone-readable formats for grey-market verification.
- Data Matrix:Compact 2D symbology optimized for small-footprint pharmaceutical cartons with high data density in minimal surface area.
2D barcodes absorb the bulk of installed capacity; RFID is climbing the fastest in cold-chain biologics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturing clusters in Germany absorb the deepest equipment investment intensity, with dense packager networks and stringent enforcement of EU Falsified Medicines Directive mandates driving sustained replacement cycles across the European Economic Area.
Germany
Dense pharmaceutical packaging corridors in Baden-Württemberg and Bavaria execute multi-line serialization retrofits to maintain EEA market access. The EU Falsified Medicines Directive's delegated regulation on safety features compresses equipment replacement timelines. Stuttgart and Munich manufacturing clusters anchor European demand for vision-integrated laser marking systems at line speeds exceeding 400 cartons per minute.
United States
FDA 21 CFR Part 11 compliance documentation extends commissioning cycles by four to eight months for domestic pharmaceutical packagers. The Drug Supply Chain Security Act mandates serialized coding at the saleable-unit level, forcing capital redeployment from legacy thermal transfer architectures. New Jersey and Massachusetts biopharma corridors drive specification toward integrated print-verify-reject systems with full audit trail documentation.
India
CDSCO alignment with EU traceability standards creates retrofit demand among domestic formulation exporters targeting European markets. The country's national pharmaceutical regulator enforces serialization mandates for vaccine and pharmaceutical packaging. Gujarat and Maharashtra manufacturing belts balance compliance costs against thermal inkjet retrofit economics for export market access.
Switzerland
Swissmedic oversight sustains premium equipment specifications for high-value biologics and orphan drug packaging. Dense pharmaceutical manufacturing clusters in Basel and Zurich execute validation-intensive installations for temperature-sensitive cold-chain serialization. The country's precision engineering heritage supports adoption of fiber laser systems with permanent, abrasion-resistant coding.
China
NMPA track-and-trace requirements for vaccine and pharmaceutical packaging mandate serialized coding infrastructure across domestic manufacturing bases. Yangtze River Delta pharmaceutical corridors deploy 2D Data Matrix systems at 300 dpi resolution for domestic and export compliance. Shanghai and Suzhou packaging hubs integrate vision verification cameras with reject mechanisms to ensure code readability.
Carton Serialization Machine Market Competitive Environment
Portfolio diversification dominates the current landscape as equipment suppliers extend from print-engine specialization toward integrated line architectures. The vendor base stratifies across three tiers: multinational integrated packaging groups with filling-to-palletization coverage; specialized serialization technology houses with deep vision-inspection expertise; and regional machinery fabricators serving mid-tier pharmaceutical packagers with retrofit-focused economics. M&A activity and technology licensing agreements represent the dominant competitive moves, with larger groups acquiring camera and optics capabilities to reduce single-source supplier risk.
Among European-anchored integrated packaging groups, Marchesini Group and IMA Group exemplify the full-line coverage archetype, spanning filling and packaging line integration. Syntegon Technology occupies a position within the specialized serialization tier, with architecture rooted in vision-inspection-integrated systems. Coesia Group represents the diversified coding technology archetype, controlling portfolio breadth across multiple printer modalities. Chinese machinery fabricators including Shanghai Tops and JOCHAMP Machinery sit within the regional supply tier, serving domestic and emerging market packagers with cost-optimized retrofit solutions.
| Leading Market Players |
|---|
| Shanghai Tops |
| Grandpackmachine |
| JOCHAMP Machinery |
| Marchesini Group |
| Wenzhou Jiade Packing Machinery Co., Ltd. |
| IMA Group |
| AIPAK |
| Coesia Group |
| Syntegon Technology |
| Others |
Value Chain & Pricing Dynamics
Stainless steel sheet and precision-machined components flow from German and Japanese specialty metal suppliers through three distinct pricing tiers before reaching pharmaceutical packagers in Baden-Württemberg and Bavaria. Raw material volatility at the upstream tier compresses margins for mid-market equipment fabricators while integrated European groups capture premium positioning through captive sourcing and extended validation service bundling.
Pricing Analysis
Volume-tier inkjet retrofits compete on capital efficiency while laser-integrated architectures command three to four times the margin pools through FDA 21 CFR Part 11 compliance documentation and IQ/OQ/PQ validation cycles. Three-tier pricing structure across premium, standard, and economy levels separates vision-integrated fiber laser systems from thermal inkjet retrofits and basic thermal transfer configurations. Pricing pressure stems from CDSCO-aligned exporters in India balancing compliance costs against constrained capital budgets. Mid-tier pharmaceutical packagers exhibit highest price sensitivity; vaccine manufacturers and biologics cold-chain operators demonstrate lowest sensitivity due to non-negotiable permanent coding requirements.
Supply Chain Analysis
Single-source vulnerability sits with specialized camera and optics vendors concentrated in Japan and Germany, creating bottleneck risk for integrated line builders sourcing vision verification subsystems. Laser source fabrication concentrates in Germany, Japan, and Switzerland, while precision motion control components draw from established industrial automation corridors in Italy and Taiwan. Stainless steel contact surface specifications elevate bill-of-materials volatility beyond coated aluminum baselines. Tariff exposure runs through precision optics imports for North American installations. Distribution runs through direct OEM sales for pharmaceutical manufacturers and third-party engineering integrators for retrofit deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carton serialization machine market is executing a technology-transition phase as fiber laser marking displaces solvent-based continuous inkjet in high-volume pharmaceutical lines. Permanent, abrasion-resistant coding is becoming mandatory for vaccine and biologics applications where thermal transfer resistance and cold-chain stability are non-negotiable.
For Market Incumbents: Anticipate margin compression in legacy inkjet retrofit segments as Indian and Chinese fabricators compete on capital efficiency. Defensive consolidation moves should prioritize backward integration into vision system capabilities to reduce single-source supplier risk from Japanese and German camera vendors, and expand validation service networks across EEA markets to capture extended commissioning revenue from EU FMD compliance timelines.
For New Entrants and Emerging Players: Enter via CDSCO-aligned pharmaceutical exporters in Gujarat and Maharashtra seeking cost-optimized thermal inkjet retrofits for European market access. White-space targets include mid-tier Indian formulation packagers and Southeast Asian contract manufacturing organizations facing first-time serialization mandates. A equipment-as-service go-to-market angle with bundled validation documentation lowers capital barriers for price-constrained buyers.
For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation waste reduction mandates accelerating laser adoption is the leading indicator that permanent coding technology will absorb capital previously allocated to consumable ink systems. Long-term viability favors integrated architecture specialists with vision-inspection capabilities and established pharmaceutical validation credentials. Acquisition target archetype: specialized serialization technology houses with deep camera integration expertise and EEA service footprints. Watch NMPA enforcement intensity in Yangtze River Delta corridors as the signal for Chinese domestic demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Vision System Capability Acquisition | Reduces single-source dependency on Japanese and German camera vendors for integrated line builders. |
| Laser Source Technology Licensing | Accelerates fiber laser adoption for vaccine lines exceeding 400 cartons per minute under EU waste mandates. |
| Validation Service Network Expansion | Captures extended IQ/OQ/PQ commissioning cycles in Germany and Switzerland driven by EU FMD enforcement. |
| Retrofit-Focused Product Line Launch | Addresses CDSCO-aligned Indian exporters balancing compliance costs against constrained capital budgets. |
| Cold-Chain Serialization Partnership | Develops thermal-transfer-resistant ink substrates for temperature-sensitive biologics in Swissmedic-regulated corridors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews conducted across equipment OEM product managers, pharmaceutical packaging engineers, validation documentation specialists, and aftermarket service directors. FDA 21 CFR Part 11 guidance documents, EMA delegated regulation texts on safety features, CDSCO technical requirements, and NMPA track-and-trace circulars supplied regulatory boundary conditions. Bottom-up equipment shipment tallies by print engine modality were reconciled against top-down pharmaceutical capital expenditure surveys across the analysis window.
Data-stream reconciliation between primary field intelligence and secondary regulatory databases structured the forecast framework. Segmentation dimensions modeled include print engine technology, application sector, end-user position in supply chain, and regional regulatory cluster complexity. CAGRs were derived from equipment replacement cycle analysis tied to mandate enforcement timelines and from line speed upgrade trajectories in vaccine manufacturing. Industry-specific forecast inputs incorporated laser source adoption curves in German pharmaceutical corridors and thermal inkjet retrofit economics among Indian export-oriented packagers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden regulatory deadline acceleration or trade restriction imposition on precision optics imports. Forecasts reflect documented assumptions regarding EU FMD delegated regulation enforcement consistency, CDSCO-EU traceability standard alignment maintenance, and stainless steel input cost stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Indonesia Folding Carton Packaging Market
Cartons
Brick Carton Packaging Market
Cartons
Carton Sealer Machine Market
Cartons
Shaped Liquid Cartons Market
Cartons
GCC Folding Carton Market
Cartons
Mono Carton Market
Cartons
End Load Cartoning Machine Market
Cartons
Soap Boxes Market
Cartons
Wax Boxes Market
Cartons
Round Corrugated Box Market
Cartons
Global Hand Carton Sealers Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Liquid Packaging Cartons Market
Cartons
Cupcake Box Market
Cartons
Japan Corrugated Boxes Market
Cartons
Folding Carton in Healthcare Market