
 Paperboard Container Market | 2026-2036
Paperboard Container Market Size, Share, and Industry Trends Forecast 2026-2036
Paperboard Container Market Analysis
ISO 14001 environmental management certification is redrawing competitive boundaries among container manufacturers. International Paper leverages its North American fiber supply network to sustain cost advantages in corrugated production. Smurfit Westrock anchors European operations through integrated paperboard mills and converting facilities. Mondi competes on specialty coated grades for premium consumer applications.
Paperboard containers are rigid or semi-rigid packaging structures manufactured from layered cellulose fibers, typically ranging from 200 to 800 grams per square meter in basis weight, formed through pulping, sheet forming, drying, and conversion processes to protect, display, and distribute goods. Folding cartons dominate retail shelf presentation for food and personal care brands, while corrugated boxes capture the bulk of e-commerce logistics volume. Rigid boxes command premium positioning in electronics and gift packaging segments where unboxing experience drives brand differentiation. Recycled paperboard grades face tightening quality specifications as post-consumer fiber streams introduce variability in strength and printability.
The EPA regulates container manufacturing emissions under Clean Air Act permits, while OSHA mandates dust exposure limits in converting facilities. The EU Packaging and Packaging Waste Regulation extends producer responsibility requirements to paperboard, forcing redesign for recyclability and recycled content thresholds. Stakeholders must monitor emerging state-level extended producer responsibility laws in the US and evolving EU single-use packaging restrictions that could redirect material flows across Atlantic supply chains.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing a fundamental redesign of paperboard specifications across European supply chains, compressing timelines for recycled content compliance while automotive and e-commerce buyers simultaneously tighten dimensional tolerances.
Growth Catalysts
- E-commerce fulfillment expansion:Protective corrugated shipping boxes are capturing rising order volumes from automated distribution centers serving consumer electronics and home goods retailers.
- EU recycled content mandates:The Packaging and Packaging Waste Regulation is compelling manufacturers to reformulate board grades and secure certified post-consumer fiber streams ahead of enforcement deadlines.
- Automotive precision packaging:German automotive parts exporters are specifying rigid paperboard containers with engineered cushioning for high-value component protection during international transit.
Market Restraints
- Recycled fiber quality variability:Post-consumer pulp streams introduce strength and printability inconsistencies that constrain high-speed converting line throughput.
- Energy cost concentration:Integrated paperboard mills in Germany and Poland face natural gas price exposure that amplifies linerboard production cost volatility.
- Plastic substitution pressure:Flexible plastic films and reusable totes are capturing share in closed-loop logistics applications where moisture resistance exceeds paperboard performance.
Strategic Opportunities
- Indian e-commerce penetration:Underdeveloped protective packaging infrastructure in tier-2 and tier-3 cities creates white space for corrugated box converters establishing regional converting facilities.
- Smart packaging convergence:Integration of printed electronics and RFID inlays into folding cartons enables authentication and supply chain tracking for pharmaceuticals and luxury goods.
- Carbon accounting requirements:The EU CSRD is mandating Scope 3 emissions disclosure that favors suppliers with ISO 14001 certification and verified lifecycle data.
Industry Challenges
- Skilled technician scarcity:Advanced flexographic and digital printing presses require operators with combined mechanical and color management expertise that vocational programs are not producing at sufficient scale.
- Certification timeline compression:ISO 14001 and FSC chain-of-custody audits are backlogging as demand for environmental credentials outpaces accredited auditor availability.
- Legacy ERP integration:Converting facilities running decades-old production planning systems face data architecture gaps when connecting to customer EDI platforms for real-time order tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paperboard Container Market |
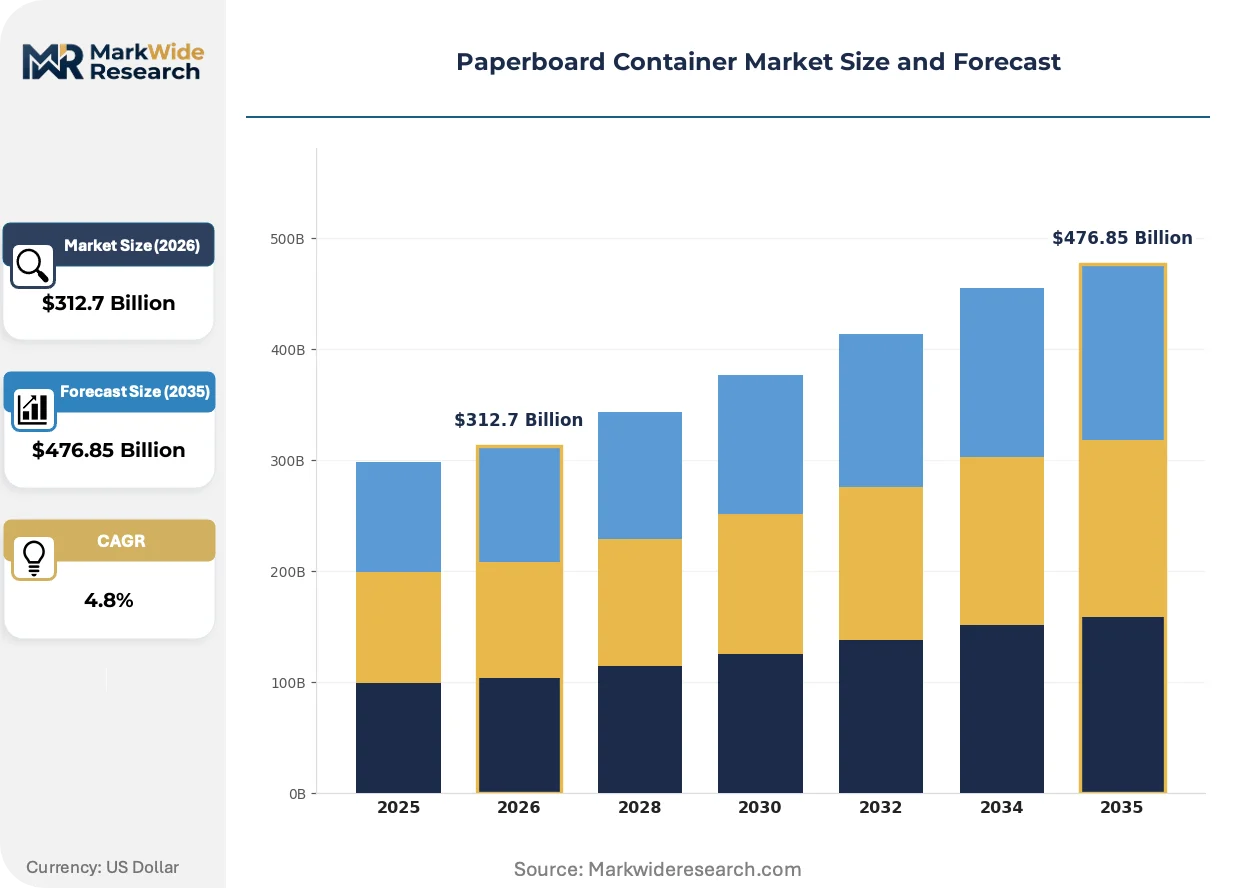
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Cartons, Rigid Boxes, Corrugated Boxes, Trays End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Material: Recycled Paperboard, Virgin Paperboard, Coated Unbleached Kraft, Solid Bleached Sulfate Packaging Type: Retail Packaging, Industrial Packaging, E-commerce Packaging, Gift Packaging |
| Companies Covered | International Paper, Smurfit Westrock, Mondi, Georgia-Pacific, Packaging Corporation of America, Stora Enso, DS Smith, Cascades Inc., Nippon Paper Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paperboard Container Market Emerging Trajectories
Digital printing and automation technologies are compressing production batch sizes while regulatory carbon accounting and circular economy mandates are rewriting material specifications and supplier qualification criteria.
Water-based barrier coatings are supplanting polyethylene extrusion in food-contact folding cartons. European dairy and ready-meal brands are adopting these fluorine-free alternatives at accelerating rates. The shift is enabling mechanical recycling compatibility that aligns with EU single-use packaging restrictions.
The EU Packaging and Packaging Waste Regulation is extending producer responsibility to paperboard with mandatory recycled content thresholds and recyclability-by-design requirements. Manufacturers must redesign multi-material structures and establish reverse logistics for post-consumer collection. Food and cosmetics brands in France and Italy are most affected, accelerating partnerships with mills capable of certified recycled fiber supply.
Brand procurement teams are consolidating supplier rosters around vertically integrated partners with certified environmental management systems. Long-tail converting relationships are giving way to strategic partnerships with mills offering design-to-delivery accountability. This concentration is most visible in German automotive and French luxury goods supply chains where sustainability audit requirements have multiplied.
Paperboard Container Market Segmentation
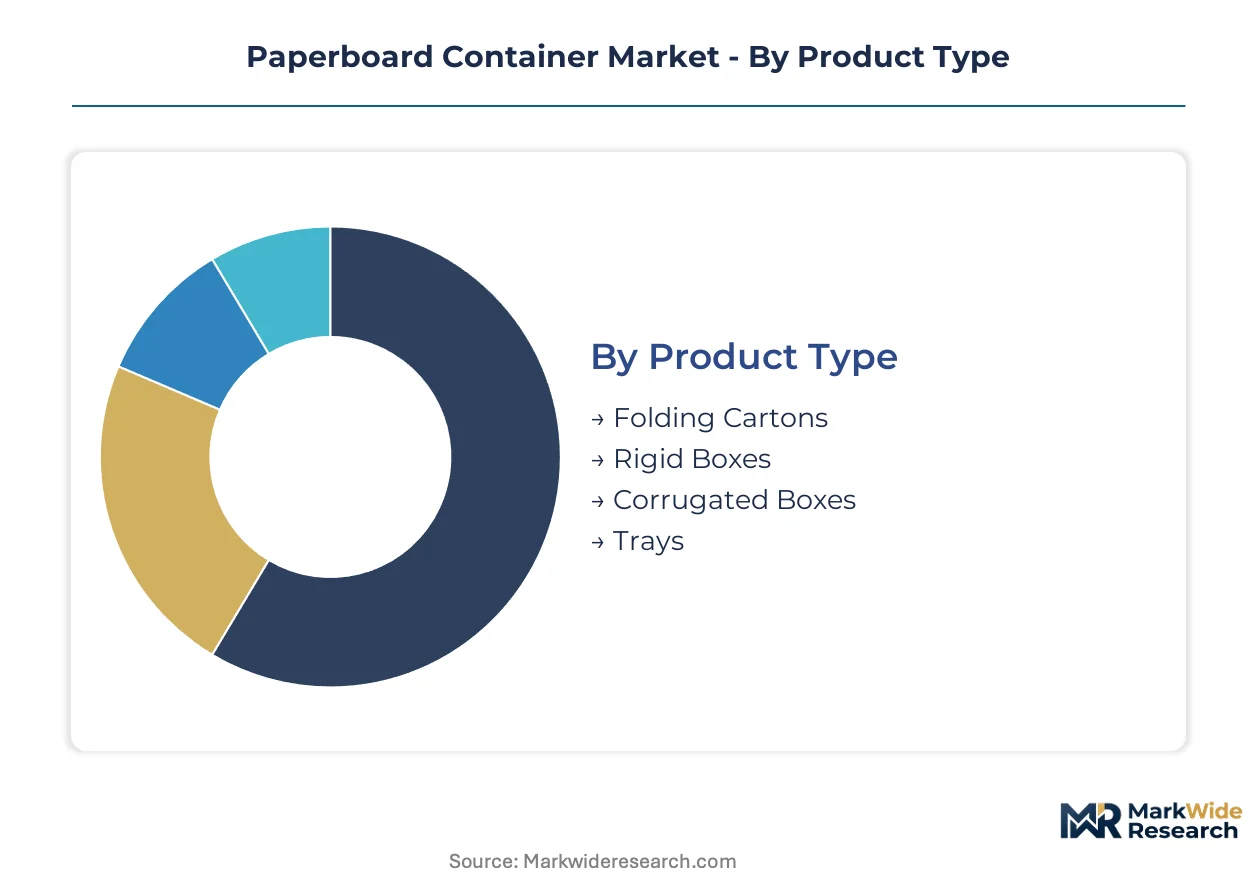
Paperboard container segmentation reveals divergent compliance burdens and performance specifications across product architectures. Regulatory frameworks in Europe and North America apply distinct recycled content thresholds and food-contact safety protocols to each category.
Product Type:
REACH and FDA food-contact regulations impose divergent barrier and migration requirements on each structural format, reshaping mill investment priorities.
- Folding Cartons:Lightweight structures formed from single-ply or multi-ply paperboard with crease-scored panels for flat shipment and retail assembly. Dairy and ready-meal brands in France and Italy are accelerating adoption of water-based barrier coatings to satisfy EU single-use packaging restrictions.
- Corrugated Boxes:Fluted medium sandwiched between linerboard facings creates engineered cushioning for distribution stresses. Automated fulfillment centers serving German automotive parts exporters specify precision-engineered rigid corrugated with engineered cushioning for high-value component protection.
- Rigid Boxes:Thick paperboard walls with wrapped exterior finishes provide structural integrity without folding. Electronics and luxury goods segments in Japan and South Korea specify these for unboxing experience differentiation.
- Trays:Shallow formed structures for food service and retail display applications. Quick-service restaurant chains in the US face FDA and state-level packaging waste regulations driving fiber-based alternatives to expanded polystyrene.
Corrugated boxes handle the majority of throughput; folding cartons are expanding most quickly on share as water-based barrier technologies mature.
End User:
Customer procurement specifications stratify sharply between cost-optimized commodity buyers and premium brand owners demanding certified environmental credentials.
- Food & Beverage:The largest addressable volume spanning dairy, bakery, confectionery, and beverage sub-segments. EU Packaging and Packaging Waste Regulation mandates are forcing redesign for recyclability across French and Italian supply chains.
- Personal Care:Premium positioning requires high-impact printing and structural differentiation. German and UK cosmetics brands are consolidating supplier rosters around ISO 14001-certified converters with verified lifecycle data.
- Pharmaceuticals:Child-resistant and senior-friendly compliance packaging with serialization requirements. US FDA track-and-trace mandates and EU Falsified Medicines Directive drive authentication feature integration.
- Electronics:Anti-static and moisture-barrier specifications for component protection. South Korean and Japanese consumer electronics brands specify precision-engineered rigid boxes with engineered cushioning for international transit.
Food and beverage commands absolute volume; pharmaceuticals posts the steepest expansion trajectory as serialization and authentication requirements proliferate.
Material:
Fiber sourcing strategies determine compliance positioning under FSC chain-of-custody and EU recycled content mandates.
- Recycled Paperboard:Post-consumer fiber streams processed through deinking and repulping operations. Quality variability in strength and printability constrains high-speed converting line throughput for premium applications.
- Virgin Paperboard:Fresh cellulose fibers delivering consistent mechanical properties and food-contact safety. Solid bleached sulfate grades dominate pharmaceutical and premium food segments where FDA and EFSA migration limits apply.
- Coated Unbleached Kraft:Natural brown appearance with clay or polymer surface treatments for printability. E-commerce and industrial packaging buyers in Germany and Poland specify these for cost-optimized corrugated linerboard.
- Solid Bleached Sulfate:Bleached virgin fibers with multi-ply construction for high-end folding cartons. Luxury cosmetics and chocolate brands in Belgium and Switzerland require these grades for premium shelf presentation.
Recycled paperboard carries the heaviest regulatory compliance burden; solid bleached sulfate maintains premium pricing power.
Packaging Type:
Distribution channel requirements dictate structural specifications and batch size economics.
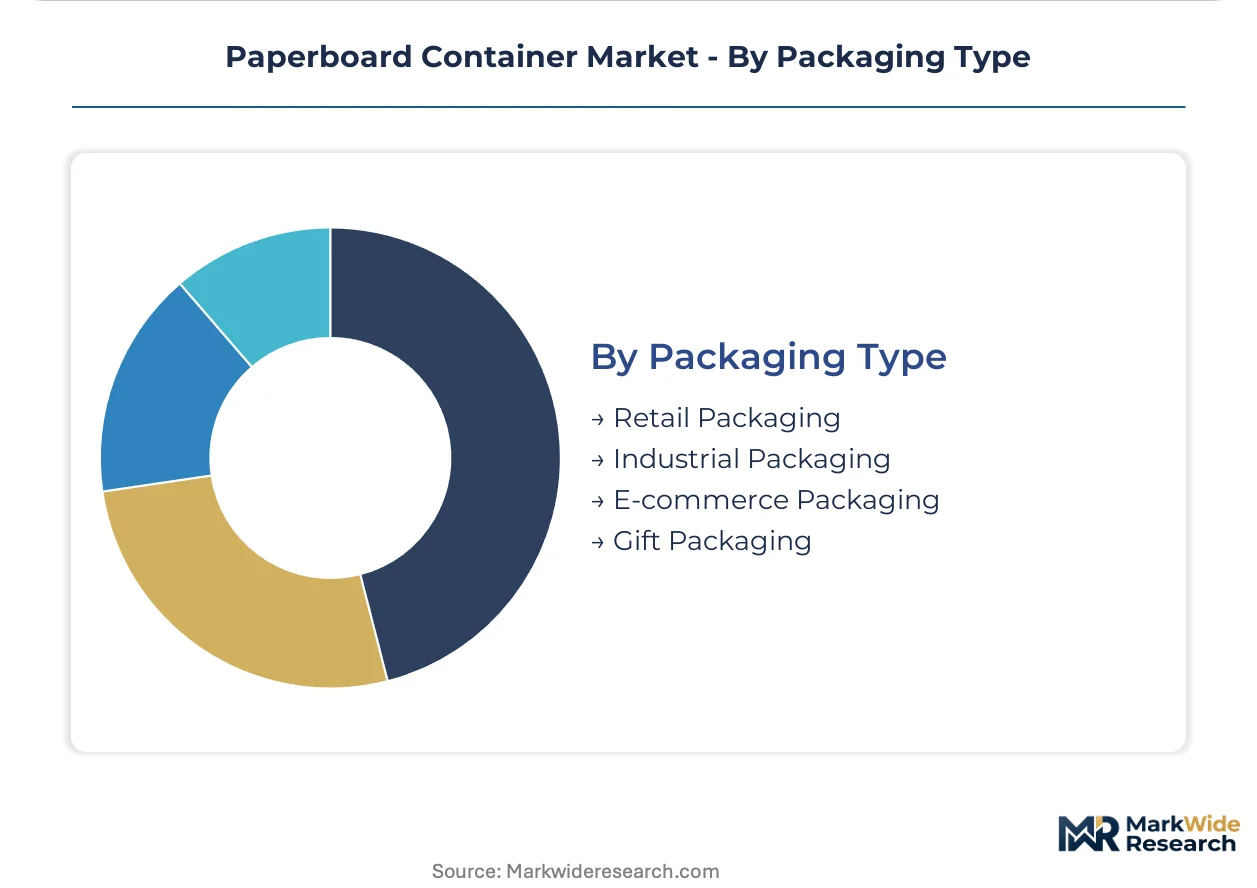
- Retail Packaging:Shelf-ready designs with high-impact graphics and easy-open features. US and European supermarket chains are mandating recyclable-by-design specifications under extended producer responsibility frameworks.
- Industrial Packaging:Bulk containers and protective structures for manufacturing supply chains. German automotive tier suppliers specify engineered cushioning and dimensional precision for just-in-sequence delivery.
- E-commerce Packaging:Rightsized corrugated with frustration-free opening and return-ready engineering. Amazon and major European marketplace fulfillment centers are driving standardization of box sizing algorithms to minimize void fill.
- Gift Packaging:Rigid boxes with premium finishes and magnetic or ribbon closures. Japanese department stores and European luxury houses maintain specialized supplier relationships for seasonal collection launches.
E-commerce packaging is gaining share fastest; retail packaging retains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive parts exporters and e-commerce fulfillment operators concentrate procurement power in Germany, while food and cosmetics brands in France and Italy drive regulatory compliance investments. Divergent recycled content mandates and energy cost exposures are fragmenting competitive positioning across Atlantic supply chains.
Germany
Automotive tier suppliers in Baden-Württemberg and Bavaria specify precision-engineered rigid paperboard with engineered cushioning for just-in-sequence delivery to assembly plants. The EU Packaging and Packaging Waste Regulation forces these exporters to certify recycled content thresholds ahead of enforcement deadlines. Stuttgart and Munich clusters host integrated converting facilities serving BMW, Mercedes-Benz, and Volkswagen supply chains.
United States
Amazon and Walmart fulfillment centers drive standardized box sizing algorithms to minimize void fill across automated distribution networks. FDA food-contact regulations and emerging state-level extended producer responsibility laws in California and New York reshape material specifications. The Pacific Northwest and Southeast regions concentrate linerboard mill capacity with access to certified fiber supply chains.
France
Dairy and ready-meal brands in Île-de-France accelerate adoption of water-based barrier coatings to satisfy EU single-use packaging restrictions. ANSM and DGCCRF enforcement of food-contact migration limits favors mills with EFSA-compliant virgin fiber streams. Paris Basin converting facilities specialize in premium folding cartons for L'Oréal and LVMH luxury cosmetics supply chains.
China
E-commerce penetration in Yangtze River Delta and Pearl River Delta cities drives corrugated box demand from Alibaba and JD.com fulfillment networks. MIIT and SAMR implementation of GB standards for packaging recyclability forces redesign of multi-material structures. Shanghai and Shenzhen clusters concentrate digital printing capacity for consumer electronics unboxing experiences.
India
Flipkart and Amazon India expansion into tier-2 and tier-3 cities creates white space for regional corrugated converting facilities. FSSAI food-contact safety protocols and BIS quality certification requirements constrain imported board grades. Maharashtra and Gujarat industrial corridors attract investments in automated flexographic presses serving FMCG distribution networks.
Paperboard Container Market Vendor Landscape
Player mix skews toward integrated multinational groups with captive fiber supply and regional specialists with converting-only operations. Tier-one positions concentrate among North American and European firms with backward integration into pulp and linerboard production. Strategic archetypes include scale-driven integrated producers, specialty coated-grade specialists, and regional converting operators. Capacity expansion and ISO 14001 certification acquisition represent dominant competitive moves as buyers consolidate supplier rosters around environmental credentials.
Within the integrated multinational tier, International Paper anchors North American operations through fiber network control, while Smurfit Westrock exemplifies European vertical integration with mill and converting facility coordination. Mondi occupies a position among specialty-grade specialists competing on coated paperboard for premium consumer applications. These three represent distinct archetypes: fiber-integrated volume production, regional mill-converting integration, and differentiated coating technology.
| Leading Market Players |
|---|
| International Paper |
| Smurfit Westrock |
| Mondi |
| Georgia-Pacific |
| Packaging Corporation of America |
| Stora Enso |
| DS Smith |
| Cascades Inc. |
| Nippon Paper Industries |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with OCC indexation lock in linerboard supply access and price visibility for German automotive packaging buyers facing EU Packaging and Packaging Waste Regulation recycled content mandates. These agreements tether mill output to converter demand while buffering natural gas cost volatility in integrated European operations.
Pricing Analysis
Cost-plus contracts with Old Corrugated Container indexation dominate linerboard procurement between integrated mills and large-format converters. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified solid bleached sulfate from commodity recycled grades and uncoated unbleached kraft. Pricing pressure stems from energy cost concentration in German and Polish mills. Commodity corrugated buyers in e-commerce fulfillment exhibit highest price sensitivity; luxury cosmetics brands purchasing rigid boxes show least.
Supply Chain Analysis
Baltic Sea port congestion at Gdansk and Klaipėda chokes linerboard export flows from Polish mills to Nordic converters. Supply concentrates in Germany, Poland, and the United States for virgin fiber linerboard; China and Indonesia for recycled pulp feedstock. Raw material dependencies include OCC collections, natural gas for drying energy, and starch adhesives. Single-source vulnerability runs through Russian natural gas displacement in European mill energy profiles. Distribution runs through regional converting facilities serving just-in-sequence automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paperboard container demand tracks a cyclical recovery pattern as e-commerce fulfillment capex cycles and automotive production schedules rebound from inventory corrections. German automotive tier suppliers and Amazon fulfillment networks represent the demand swing factors.
For Market Incumbents: Fortify backward integration into OCC collection networks to secure certified post-consumer fiber streams ahead of EU enforcement deadlines. Add converting capacity in Maharashtra and Gujarat industrial corridors to capture Flipkart and Amazon India expansion. ISO 14001 certification acquisition defends supplier roster positions against sustainability audit requirements from L'Oréal and LVMH procurement teams.
For New Entrants and Emerging Players: Anchor in tier-2 and tier-3 Indian cities where protective packaging infrastructure remains underdeveloped and FSSAI compliance barriers favor domestic converters. Target corrugated box production for FMCG distribution networks seeking BIS-certified regional suppliers. Pursue joint venture structures with established mills for fiber supply security rather than greenfield mill investment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated mills with captive linerboard production and long-term automotive supply contracts. Five-to-ten-year viability favors operators with ISO 14001 certification and verified Scope 3 emissions data under EU CSRD disclosure mandates. Monitor German automotive production schedules and Amazon fulfillment center openings as inflection indicators for corrugated demand cyclicality.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | Secures certified post-consumer fiber streams for EU Packaging and Packaging Waste Regulation compliance. |
| Digital Printing Capacity Expansion | Enables short-run customization for South Korean and Japanese electronics unboxing experiences. |
| Water-Based Barrier Coating Adoption | Aligns French dairy and ready-meal brands with EU single-use packaging restrictions. |
| Regional Converting Facility Buildout | Captures Flipkart and Amazon India demand in Maharashtra and Gujarat industrial corridors. |
| ISO 14001 Certification Investment | Satisfies German automotive and French luxury goods sustainability audit requirements. |
Methodological Framework
Initial hypotheses were tested against primary input from mill operations directors, corrugated converter plant managers, automotive tier supplier procurement leads, and e-commerce fulfillment network planners and refined through secondary validation. Trade data from Eurostat and USITC, SEC 10-K filings from integrated packaging groups, EPA emissions disclosures, and EU Packaging and Packaging Waste Regulation impact assessments supplied quantitative anchors. Bottom-up capacity modeling across linerboard mills and top-down demand sizing from end-use consumption patterns were triangulated.
Variance decomposition across product type, material grade, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier. Modeled inputs included German automotive production schedules, Amazon fulfillment center opening announcements, and EU recycled content mandate implementation timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained e-commerce penetration and EU regulatory enforcement; material deviation in energy cost trajectories or trade policy would warrant model refresh. Practitioners should keep alternative scenarios live as German industrial gas supply arrangements and US state-level extended producer responsibility legislation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Liquid Packaging Board Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Fish Box Market