
 Thailand Folding Carton Packaging Market | 2026-2036
Thailand Folding Carton Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Folding Carton Packaging Market Outlook
Premium folding carton specifications are decoupling from commodity-grade production in Thailand. Huhtamaki (Thailand) Ltd. leverages its global R&D network to develop high-barrier coated cartons for dairy and beverage clients. Siam Toppan Packaging Co. Ltd anchors its position through advanced gravure and lithography capabilities serving Japanese-owned food brands. Thai Containers Group (SCG Packaging) dominates volume production of standard cartons for domestic retail chains.
Folding carton packaging comprises paperboard substrates that are die-cut, scored, folded, and glued into rigid containers, typically ranging from 200 to 400 gsm in caliper, designed to protect, display, and distribute consumer goods. Custom boxes and retail boxes lead value generation as brand owners demand structural differentiation and shelf-impact graphics for cosmetics and electronics. Recycled paperboard and coated paperboard capture the fastest expansion as converters respond to Thai government sustainability mandates and multinational buyer ESG requirements.
Thailand's Industrial Standards Institute (TISI) enforces paperboard quality and food-contact safety benchmarks, while the Thailand Board of Investment channels tax privileges toward biodegradable packaging investments. Stakeholders must monitor how TISI alignment with ASEAN harmonized standards reshapes material certification costs and export qualification thresholds for carton shipments to neighboring markets.
Market Dynamics
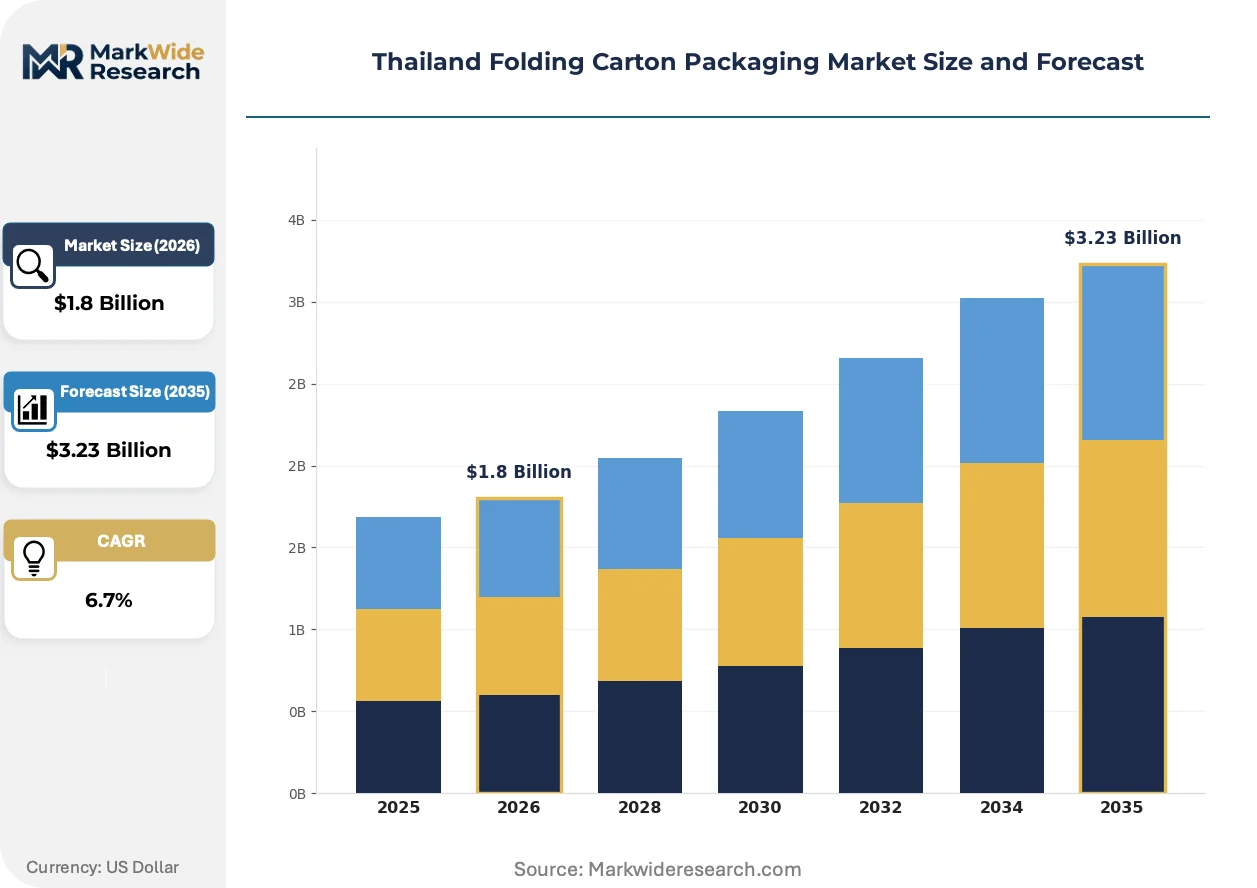
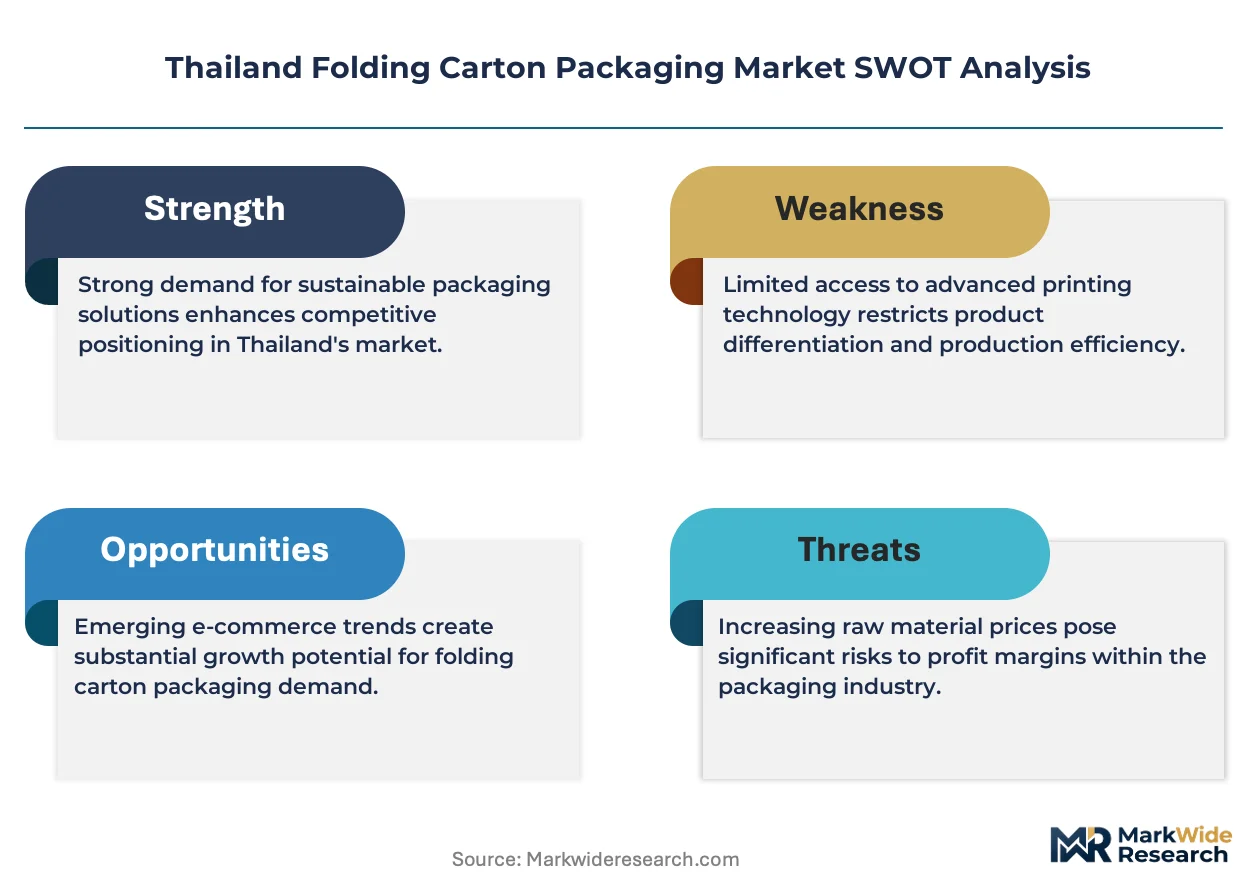
Thailand's Board of Investment incentives for sustainable packaging materials are accelerating converter investments in recycled paperboard capacity and coated substrate lines, reshaping competitive positioning between commodity volume producers and specialty barrier-grade suppliers.
Growth Catalysts
- BOI Tax Privileges:Thailand's Board of Investment grants eight-year corporate income tax exemptions for biodegradable packaging manufacturing investments, directing capital toward coated paperboard and recycled substrate lines.
- ASEAN Export Alignment:TISI harmonization with ASEAN food-contact safety standards reduces certification friction for carton shipments to Vietnam, Indonesia, and the Philippines.
- Ready-to-Eal Meal Expansion:Bangkok-based food brands are scaling high-barrier carton orders for chilled and ambient shelf-stable prepared foods, pulling demand toward 300-400 gsm coated grades.
Market Restraints
- Recycled Pulp Cost Volatility:Old corrugated container (OCC) import dependence exposes Thai converters to Southeast Asian fiber price swings and currency fluctuation against the US dollar.
- Barrier Coating Technical Limitations:Water-based and bio-based barrier coatings still underperform polyethylene laminates for extended shelf-life dairy applications, constraining full substrate substitution.
- Central Plains Supply Concentration:Converting capacity clusters within 150 kilometers of Bangkok, creating logistics cost penalties for brands manufacturing in northern and southern industrial zones.
Strategic Opportunities
- Eastern Economic Corridor Expansion:Rayong and Chonburi provinces host new consumer goods manufacturing estates where carton demand currently outpaces local converting supply.
- Digital Printing Convergence:Combination of inkjet web presses and AI-driven prepress workflows enables economical short-run customization for cosmetics and electronics brands.
- Extended Producer Responsibility Tailwinds:Pending Thai government packaging waste regulations will mandate recycled content minimums, advantaging converters with established recovered fiber supply chains.
Industry Challenges
- Gravure Cylinder Skilled Technician Scarcity:Retirement waves among experienced cylinder engravers constrain Siam Toppan Packaging and competitors from expanding high-quality print capacity.
- Legacy ERP Integration Complexity:Mid-tier converters struggle to synchronize MES and inventory systems with customer EDI requirements from Japanese and European multinational buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Folding Carton Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cartons, Custom Boxes, Retail Boxes, Rigid Boxes End User: Food & Beverage, Personal Care, Pharmaceutical, Consumer Electronics Material: Recycled Paperboard, Coated Paperboard, Solid Bleached Sulfate, Corrugated Board Printing Technology: Flexography, Digital Printing, Lithography, Gravure |
| Companies Covered | Continental Packaging (Thailand) Co. Ltd, Huhtamaki (Thailand) Ltd., Siam Toppan Packaging Co. Ltd, Stora Enso (Thailand) Co., Ltd., Tetra Pak (Thailand) Ltd., Thai Containers Group (SCG Packaging), Oji Paper (Thailand) Ltd., SCG Packaging Public Company Limited, Thung Hua Sinn Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Folding Carton Packaging Market Strategic Shifts
Digital production technologies and bio-based material science are compressing minimum order quantities and enabling substrate substitution previously uneconomical at Thai volume scales.
Water-based barrier coatings are converging with nanocellulose reinforcement layers to achieve oxygen and moisture protection comparable to polyethylene extrusion. Dairy and plant-based beverage brands in Bangkok are piloting these structures for six-month shelf-life products. The technology is converging with flexographic print lines, allowing single-pass production that collapses lead times from three weeks to five days for mid-volume runs.
Thailand's Industrial Standards Institute is tightening food-contact migration limits for recycled paperboard, aligning with evolving EU EFSA guidance on mineral oil saturated hydrocarbons. This regulatory shift forces converters to invest in deinking and cleaning process upgrades or source virgin fiber alternatives. Premium beverage and infant nutrition segments are responding by qualifying coated virgin grades despite 15-20 percent cost premiums over standard recycled board.
Brand procurement teams are consolidating carton specifications across ASEAN manufacturing networks, demanding single-source qualification for multi-country supply. Thai converters serving Japanese-owned food brands must now certify identical structures for sister plants in Vietnam and Indonesia. This consolidation is most visible in the cosmetics and personal care vertical, where Bangkok-headquartered brand owners are reducing qualified supplier pools from twelve to four converters regionally.
Thailand Folding Carton Packaging Market Segmentation
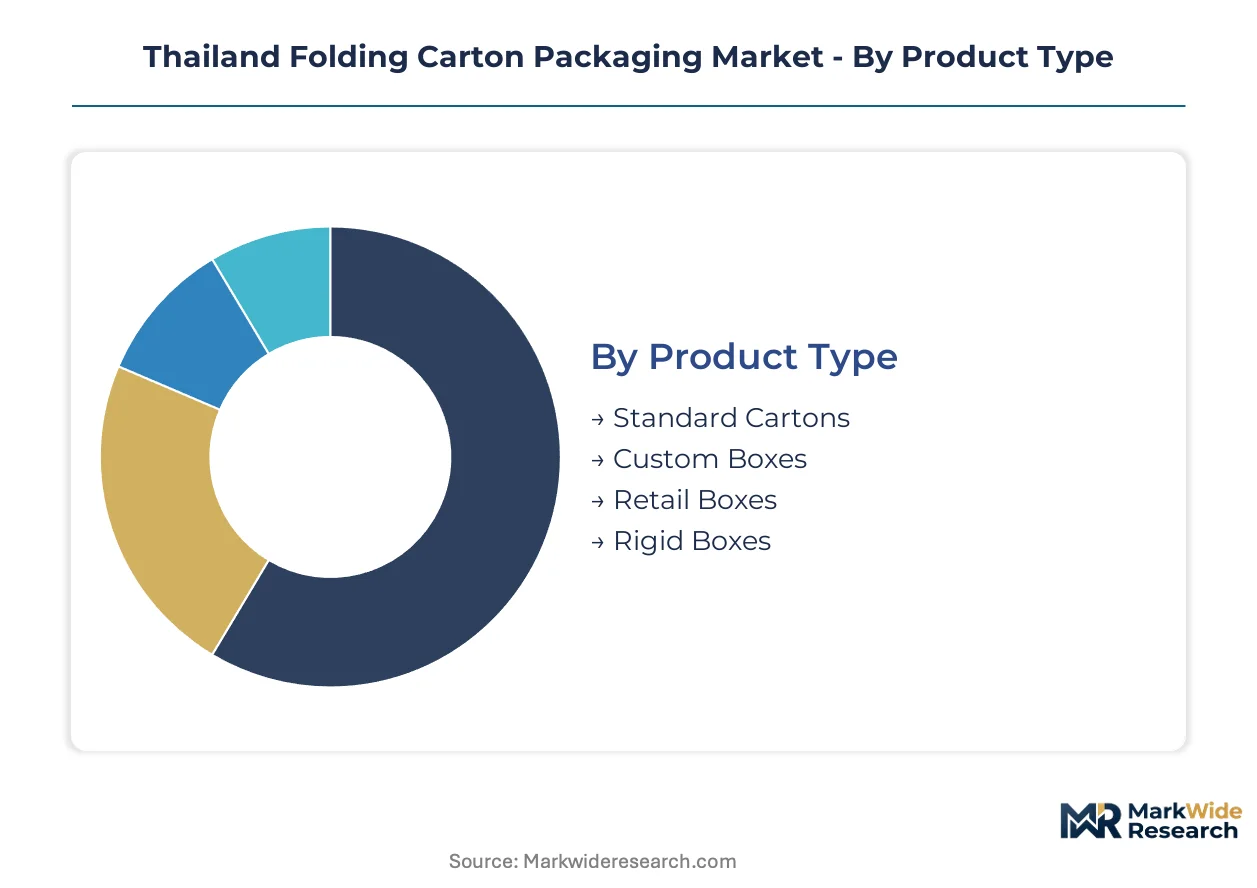
Thailand's folding carton market fragments across four structural dimensions that determine converter capabilities and margin profiles. Product type and material specifications dominate capital allocation decisions, while end-user verticals and print technologies shape operational specialization.
Product Type:
Volume production concentrates in standardized formats, while premium tiers command structural differentiation and shorter runs.
- Custom Boxes:Engineered structures with proprietary die-lines and reinforced corners protect high-value electronics and cosmetics during distribution. Bangkok-based brand owners specify these for flagship product launches requiring unboxing experiences and shelf differentiation.
- Retail Boxes:Pre-designed formats with standardized dimensions serve mass-market consumer goods through high-speed converting lines. Central Plains facilities produce these at scale for domestic retail chains and ASEAN export channels.
- Standard Cartons:Generic folding boxes without structural customization serve commodity food and beverage applications where cost minimization dominates procurement criteria.
- Rigid Boxes:Thick paperboard laminates over chipboard cores create premium packaging for luxury cosmetics and gift sets, requiring manual assembly stages that limit automation.
Mature deployment sits with Standard Cartons. Newer deployment is concentrated in Custom Boxes.
End User:
Customer procurement patterns separate regulated verticals with compliance overhead from price-sensitive retail categories.
- Food & Beverage:Dairy, ready-to-eat meals, and premium beverages in Bangkok and Eastern Economic Corridor drive coated paperboard demand with strict TISI food-contact migration requirements. BOI incentives for biodegradable packaging accelerate substrate transitions in this vertical.
- Pharmaceutical:Blister packs and secondary cartons for OTC and prescription drugs require serialization compatibility and tamper-evident features under Thailand's FDA-equivalent pharmaceutical regulations.
- Personal Care:Cosmetics and skincare brands in Bangkok prioritize shelf-impact graphics and structural innovation for duty-free and retail channels.
- Consumer Electronics:Smartphone and accessory manufacturers specify anti-static coatings and precise fitments for Southeast Asian assembly operations.
Regulatory intensity peaks in Pharmaceutical. Volume scale concentrates in Food & Beverage.
Material:
Sustainability mandates and barrier performance requirements are reshaping substrate qualification across Thai converting capacity.
- Coated Paperboard:Clay or polymer surface treatments provide moisture and grease resistance for chilled food applications. Bangkok dairy brands specify these for extended shelf-life products despite cost premiums over uncoated alternatives.
- Recycled Paperboard:Post-consumer fiber content satisfies multinational ESG procurement criteria and anticipated Thai extended producer responsibility regulations. OCC import dependence creates cost volatility for converters without captive recovered fiber supply.
- Solid Bleached Sulfate:Virgin fiber purity meets stringent food-contact and pharmaceutical hygiene standards where mineral oil migration concerns disqualify recycled grades.
- Corrugated Board:Fluted structures provide cushioning for electronics and bulk food distribution, typically specified as outer shipping containers rather than primary retail packaging.
Specification density runs highest in Solid Bleached Sulfate. Expansion velocity is climbing fastest in Recycled Paperboard.
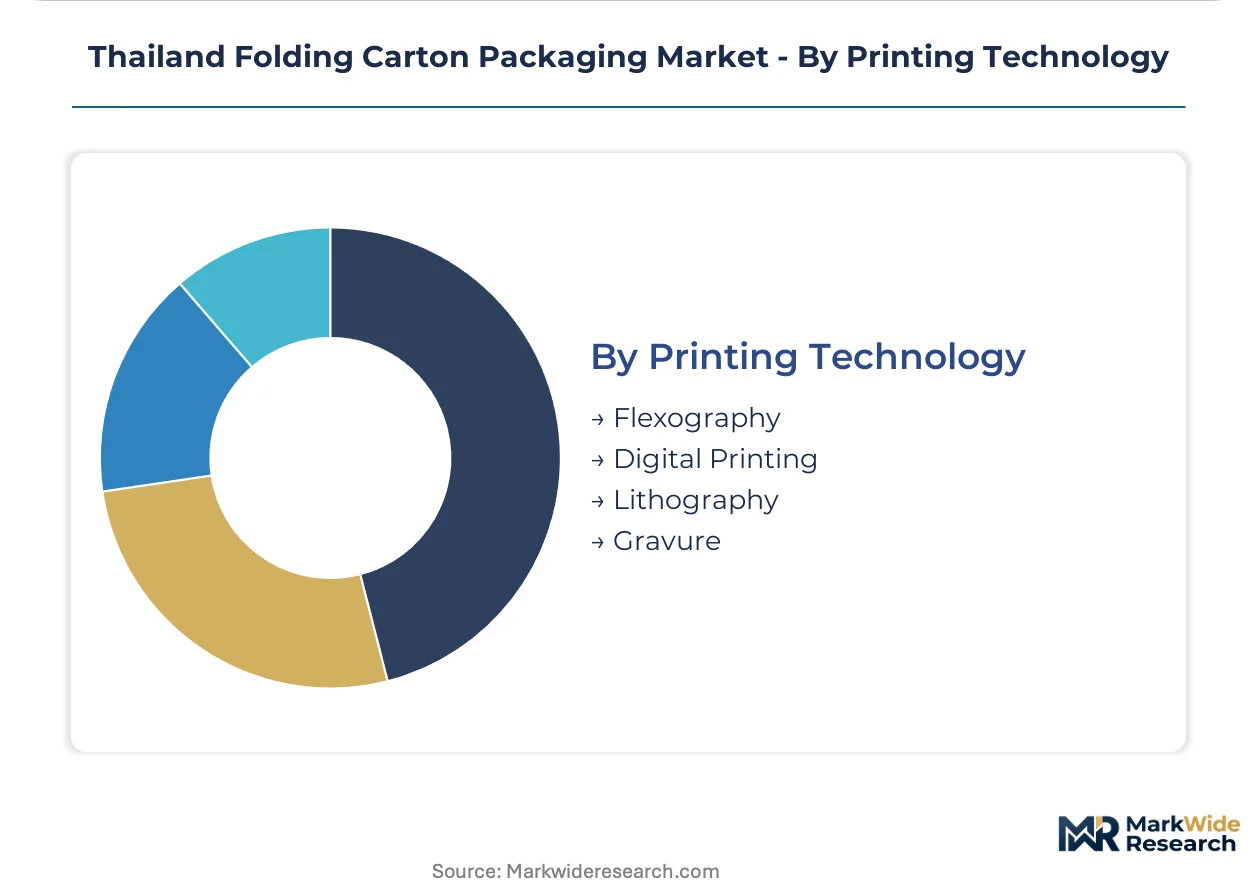
Printing Technology:
Run length economics and graphic complexity determine technology selection across Thai converter investment cycles.
- Gravure:Cylinder-based intaglio printing delivers consistent high-resolution graphics for long-run food and beverage cartons. Siam Toppan Packaging anchors regional capacity, though skilled technician scarcity constrains expansion.
- Digital Printing:Inkjet and toner systems enable economical short runs with variable data for cosmetics limited editions and market testing. Lead times compress from weeks to days for mid-volume orders.
- Flexography:Rubber plate printing serves high-volume commodity cartons with lower capital requirements than gravure, common in standard food packaging applications.
- Lithography:Offset printing on pre-laminated board delivers premium cosmetic and electronics packaging with precise color matching and metallic effects.
Capital intensity peaks with Gravure. Adoption momentum is strongest in Digital Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok and its surrounding Central Plains industrial corridor concentrate Thailand's folding carton converting capacity within a 150-kilometer radius of the capital. This geographic clustering shapes logistics economics and converter-customer relationships across the domestic market.
Central Plains
Pathum Thani and Samut Prakan provinces host the densest concentration of converting facilities serving Bangkok-headquartered food and beverage brands. Thailand's Board of Investment grants eight-year corporate income tax exemptions for biodegradable packaging investments in this zone. Ayutthaya and Nakhon Pathom industrial estates are expanding coated paperboard capacity to meet ready-to-eat meal carton demand from chilled food manufacturers.
Eastern Economic Corridor
Rayong and Chonburi provinces are attracting consumer goods manufacturing estates where carton demand currently exceeds local converting supply. The Thailand Board of Investment channels infrastructure investment toward packaging material suppliers locating near automotive and electronics assembly operations. Laem Chabang port proximity enables export-oriented converters to serve ASEAN markets with reduced freight costs.
Northern Region
Chiang Mai and Lampang industrial zones generate carton demand from agricultural processing and food packaging for domestic distribution. TISI food-contact safety standards apply uniformly nationwide, though northern converters face longer supply chains for imported old corrugated container pulp. Local procurement from paperboard distributors in Bangkok adds 12-15 percent logistics premiums versus Central Plains sourcing.
Southern Region
Songkhla and Surat Thani provinces concentrate seafood processing carton demand for frozen and chilled export products. Thailand's Industrial Standards Institute enforces migration limits for recycled paperboard in direct food contact applications across this zone. Hat Yai industrial estates are developing modest converting capacity to reduce dependence on Bangkok-supplied shipping containers.
Northeastern Region
Khon Kaen and Nakhon Ratchasima host emerging food manufacturing clusters driving carton consumption for processed meat and instant noodle brands. Extended producer responsibility regulations anticipated from Thai government agencies will mandate recycled content minimums affecting procurement patterns. Udon Thani logistics hubs are evaluating converting investments to capture demand from Lao PDR cross-border trade.
Thailand Folding Carton Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier-grade specialization and print technology sophistication. The Thailand folding carton market exhibits tiered concentration where multinational converters with global R&D networks compete against domestic volume producers with captive fiber supply. Three archetypes dominate: global specialists leveraging parent-company technology platforms, integrated paperboard producers with backward control into pulp supply, and regional gravure/lithography houses serving Japanese-owned brand networks. Competitive moves center on coated substrate line expansion and digital print capability acquisition to compress short-run lead times.
Within the multinational specialist tier, Huhtamaki (Thailand) Ltd. and Tetra Pak (Thailand) Ltd. exemplify global platform deployment into high-barrier dairy and beverage applications. Siam Toppan Packaging Co. Ltd occupies a position representing advanced gravure and lithography capability anchored to Japanese food brand supply relationships. Among integrated domestic producers, Thai Containers Group (SCG Packaging) and SCG Packaging Public Company Limited represent volume-scale operations with captive recovered fiber networks serving domestic retail chains. Stora Enso (Thailand) Co., Ltd. exemplifies Nordic-origin sustainable substrate positioning aligned with multinational ESG procurement criteria.
| Leading Market Players |
|---|
| Continental Packaging (Thailand) Co. Ltd |
| Huhtamaki (Thailand) Ltd. |
| Siam Toppan Packaging Co. Ltd |
| Stora Enso (Thailand) Co., Ltd. |
| Tetra Pak (Thailand) Ltd. |
| Thai Containers Group (SCG Packaging) |
| Oji Paper (Thailand) Ltd. |
| SCG Packaging Public Company Limited |
| Thung Hua Sinn Group |
| Others |
Value Chain & Pricing Dynamics
Old corrugated container pulp import costs transmit directly from Southeast Asian fiber markets through Bangkok converting facilities into tiered carton pricing. Central Plains concentration near Bangkok industrial estates compresses logistics premiums for volume buyers while northern and southern manufacturers absorb 12-15 percent freight penalties.
Pricing Analysis
Barrier performance against oxygen and moisture transmission anchors value-based pricing tiers in Thai dairy and beverage applications. Three-tier pricing structure across premium, standard, and economy levels separates coated virgin grades from deinked recycled board and commodity uncoated alternatives. Cost compression in recycled paperboard is intensifying because OCC import dependence exposes converters to currency fluctuation against the US dollar. Domestic retail chains exhibit highest price sensitivity, while Japanese-owned food brands in Bangkok prioritize qualification stability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from multinational buyers mandate Thai converters qualify secondary paperboard suppliers in Indonesia and Vietnam alongside domestic SCG Packaging networks. Raw material dependencies center on imported OCC fiber, clay coating chemicals, and water-based barrier polymers. Single-source vulnerability concentrates in gravure cylinder engraving capacity where Siam Toppan Packaging and limited competitors control regional supply. Distribution runs through Bangkok-based converting clusters with direct mill-to-plant delivery contracts for high-volume food and beverage accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's folding carton market is consolidating as BOI tax privileges for biodegradable packaging manufacturing favor capital-rich players with coated substrate line expansion capability. Smaller gravure houses without digital print integration face displacement.
For Market Incumbents: Acquire digital inkjet web press capacity to compress short-run lead times for cosmetics and electronics limited editions. Backward integration into captive recovered fiber supply chains insulates margin structures from OCC import volatility. Defensive positioning requires certifying identical carton structures for ASEAN sister plants before procurement consolidation reduces qualified supplier pools further. For New Entrants and Emerging Players: Enter via Eastern Economic Corridor converting investments in Rayong and Chonburi where carton demand from automotive and electronics assembly currently exceeds local supply. Target seafood processing applications in Songkhla and Surat Thani with TISI-compliant frozen export packaging. Go-to-market leverage rests on proximity logistics savings versus Bangkok-sourced shipping containers. For Investors and Strategic Acquirers: BOI incentive expiration announcements for biodegradable packaging investments are the leading indicator that consolidation velocity will accelerate among mid-tier converters without tax-privileged capacity. Long-term viability favors integrated producers with captive pulp supply and multi-country ASEAN qualification. Acquisition focus should center on gravure-lithography houses with established Japanese brand relationships and underutilized coated board lines.| Strategic Initiative | Industry Significance |
|---|---|
| Coated Paperboard Line Expansion | Captures BOI tax exemptions while meeting dairy shelf-life barrier requirements under TISI standards. |
| Digital Print Capability Acquisition | Enables five-day lead times for mid-volume cosmetics runs versus three-week gravure cycles. |
| Recovered Fiber Supply Integration | Reduces OCC import exposure and positions converters for pending extended producer responsibility mandates. |
| ASEAN Multi-Country Qualification | Secures single-source procurement consolidation across Thai, Vietnamese, and Indonesian sister plants. |
| Water-Based Barrier R&D Partnership | Develops nanocellulose-reinforced coatings competitive with polyethylene laminates for six-month shelf-life products. |
Study Parameters
Trade publications, TISI regulatory filings, and customs import records formed the secondary backbone for fiber cost and capacity tracking. Primary interviews with converting plant managers, procurement leads at Bangkok-headquartered food brands, gravure cylinder technicians, and BOI investment promotion officers validated operational assumptions. Bottom-up and top-down triangulation reconciled mill capacity disclosures with end-user carton consumption patterns across Central Plains and Eastern Economic Corridor manufacturing estates.
Bottom-up modeling anchored volume projections in individual converting line throughput rates and substrate mix assumptions across the projection horizon. Segmentation dimensions included product type, material specification, end-user vertical, and print technology tier. CAGRs were derived from trend extrapolation of BOI-approved investment flows and food and beverage manufacturing expansion in Rayong and Chonburi provinces. Forecast inputs incorporated TISI alignment timelines with ASEAN harmonized standards and anticipated extended producer responsibility regulation implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt OCC import tariff shifts or accelerated EU EFSA mineral oil migration limit adoption. Deviation in BOI incentive renewal schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Pick and Place Carton Packers Market
Cartons
Japan Corrugated Boxes Market
Cartons
Microwaveable Carton Market
Cartons
Mailers Market
Cartons
Global Printed Cartons Market
Cartons
Pizza Cartons Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Indonesia Folding Carton Packaging Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
North America Corrugated Boxes Market
Cartons
Brick Liquid Carton Market
Cartons
Africa Folding Carton Market
Cartons
Cartoning Machines Market