
 Compression Bags Market | 2026-2036
Compression Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Bags Market Outlook
China is narrowing its cost advantage in compression bag manufacturing as Southeast Asian producers scale woven nylon and polyethylene capacity. Osprey leverages vertical integration in fabric sourcing to sustain margin stability across its technical pack liner range. Sea to Summit dominates the ultralight segment with bonded seam construction that anchors its premium positioning among thru-hikers and alpine climbers. Yuyao Boya Packing Products Co. Ltd. competes on volume throughput for roll-up and zipper-seal variants sold through mass retail channels.
Compression bags are collapsible storage vessels engineered from multi-layer polymers or coated nylons, typically incorporating one-way valves, welded seams, or mechanical roll mechanisms to evacuate air and reduce packed volume by 50-80%. Their primary commercial purpose spans travel logistics, residential space optimization, and protective stowage of moisture-sensitive or bulky textiles. Vacuum-sealed configurations occupy the highest margin tier due to precision valve engineering and repeat-purchase consumable patterns, while roll-up formats lead volume growth among outdoor enthusiasts prioritizing weight minimization. Plastic and polyethylene materials still command the largest share of unit economics, though nylon variants capture expanding share in performance-oriented applications where tear resistance and sub-ounce weights justify price premiums.
The US Consumer Product Safety Commission monitors phthalate content in PVC-based storage products, while California's Proposition 65 labeling requirements shape formulation decisions for brands distributing into that state. The EU REACH framework restricts specific plasticizers and flame retardants, forcing material substitutions that ripple through Asian contract manufacturing networks. Stakeholders must monitor evolving state-level chemical disclosure rules and the trajectory of recycled-content mandates, as these will determine which material platforms and regional supply bases retain access to priority consumer markets.
Market Dynamics
The compression bags market is being fundamentally restructured by the EU REACH framework's restrictions on plasticizers and flame retardants, which forces material substitutions across Asian contract manufacturing networks and reshapes supplier access to European consumer markets.
Growth Catalysts
- REACH chemical safety mandates:European regulatory pressure accelerates R&D investment in bio-based polymer alternatives, creating first-mover advantages for compliant suppliers.
- Van-life residential downsizing:Urban consumers in the United States convert vehicles into living spaces, generating sustained demand for space-efficient storage systems.
- Woven nylon capacity expansion:Southeast Asian producers scale technical fabric output, broadening the supply base for performance-oriented outdoor applications.
Market Restraints
- Petrochemical input volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil markets, compressing margins for volume manufacturers.
- Single-source valve engineering:Precision one-way valve production concentrates among specialized Taiwanese and German component suppliers, creating bottleneck risk.
- Mechanical roll-up substitution:Simple roll-up formats displace vacuum-sealed systems in ultralight backpacking segments where pump accessories add unacceptable weight.
Strategic Opportunities
- India outdoor retail penetration:Organized camping and trekking sectors in Maharashtra and Karnataka remain underserved by branded compression systems.
- Post-consumer recycled content mandates:California's SB 54 and similar state-level packaging laws create procurement preference for rPET and rNylon variants.
- RFID-integrated inventory tracking:Convergence of smart textile tagging with compression storage enables rental and shared-equipment business models.
Industry Challenges
- Welded seam technician scarcity:Bonded construction expertise for ultralight bonded seam systems concentrates among alpine equipment specialists in Italy and Japan.
- Multi-jurisdiction labeling compliance:Simultaneous satisfaction of California Proposition 65, EU REACH, and state-level chemical disclosure rules extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Bags Market |
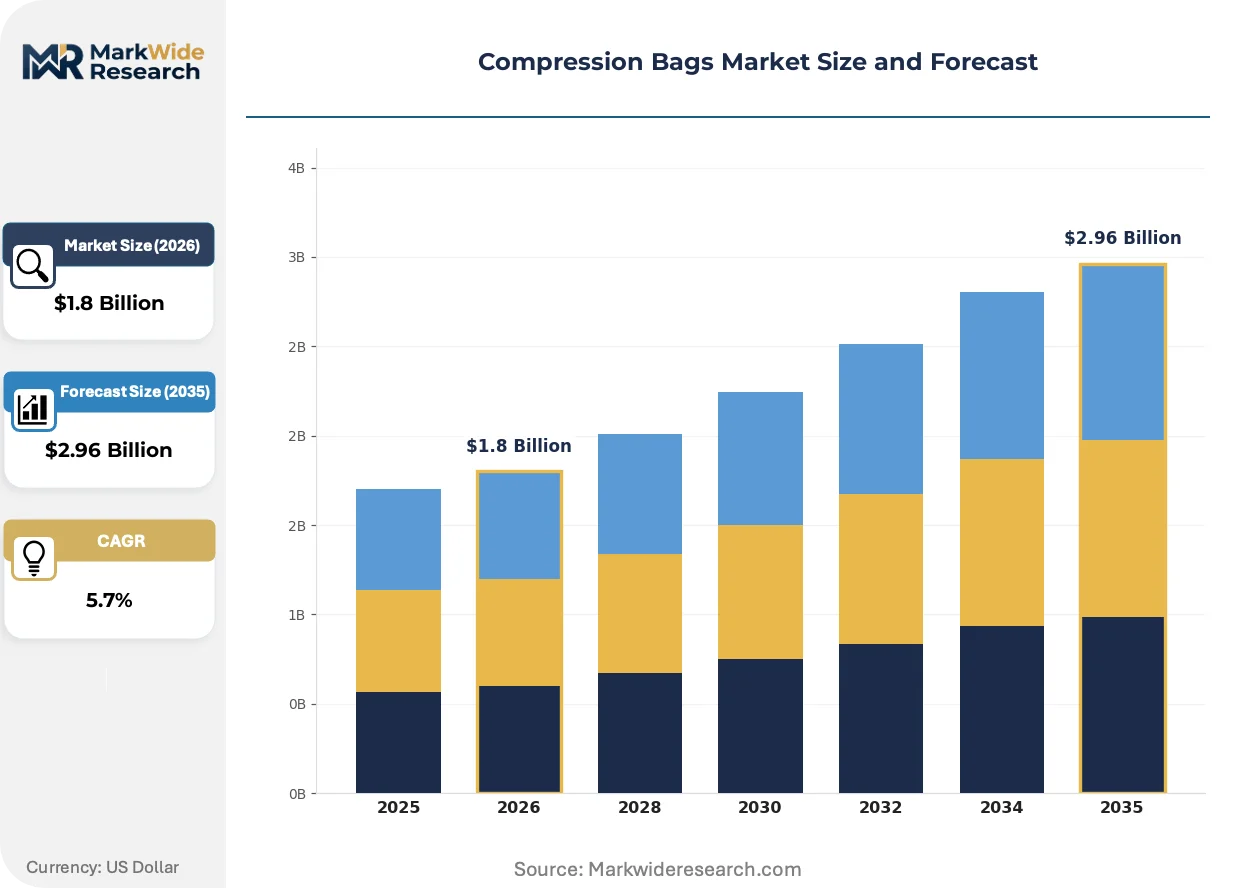
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Sealed, Space Saver, Roll-Up, Zipper Seal Material: Plastic, Polyethylene, Nylon, PVC Application: Travel, Home Storage, Clothing, Seasonal Items End User: Individuals, Families, Outdoor Enthusiasts, Businesses |
| Companies Covered | Gobi Gear, Hyperlite Sacks, Yuyao Boya Packing Products Co. Ltd., Osprey, Sea to Summit, Yiwu City Kaiyun Packaging Co. Ltd., Granite Gear, ZPacks, Real Space Bag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Bags Market Strategic Shifts
Material science breakthroughs and regulatory chemistry restrictions are converging to displace legacy PVC formulations while digital integration opens new service-based revenue models in equipment rental and shared ownership.
Silicone-coated nylon laminates with sub-30-denier weights are rendering obsolete heavier polyurethane-coated fabrics in thru-hiking and alpine climbing segments. Specialty outdoor retailers report bonded seam construction now dominates premium shelf space. This shift compresses the addressable market for conventional heat-sealed PVC alternatives.
REACH Annex XVII restrictions on phthalate plasticizers force compound reformulation across European-bound production lines. Manufacturers serving Germany and France must certify alternative plasticizer systems through ECHA notification procedures. Small-batch producers lacking toxicology testing resources are exiting the EU market entirely.
Subscription-based outdoor equipment rental platforms in Colorado and Oregon now specify compression-compatible storage as a fleet standard. This procurement model displaces individual ownership for occasional users. The behavior is most visible among urban millennials accessing gear through REI and specialized regional cooperatives.
Compression Bags Market Segmentation
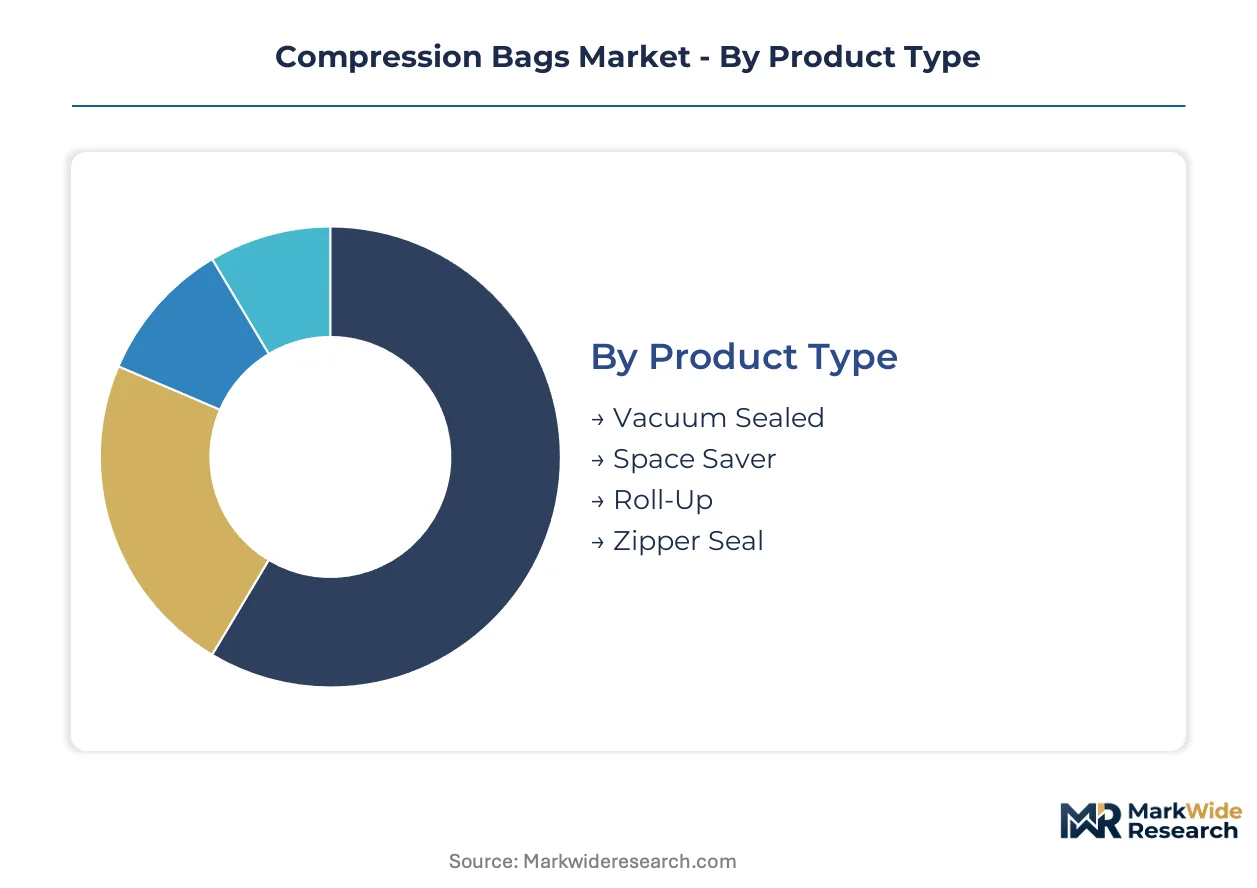
Compression bag segmentation reveals divergent margin profiles across construction methods and user contexts. Product architecture determines whether manufacturers compete on precision engineering or volume throughput. Material selection and end-use application further stratify pricing power and distribution channel requirements.
Product Type:
Mature roll-up formats coexist with emerging smart-valve systems as the category splits between simplicity and technical sophistication.
- Vacuum Sealed:One-way valve systems with pump-assisted air evacuation achieve 70-80% volume reduction through precision-engineered silicone seals. Demand concentrates among residential downsizers in the United States, where California's Proposition 65 labeling requirements force reformulation of valve compounds to eliminate phthalate content.
- Space Saver:Hybrid constructions combining mechanical compression with partial vacuum assistance target urban apartment dwellers managing seasonal wardrobe transitions. German and French consumers drive adoption through REI and Decathlon retail networks, with ECHA notification procedures for alternative plasticizers extending supplier qualification timelines.
- Roll-Up:Simple mechanical expulsion via fabric rolling suits ultralight backpacking where every gram matters.
- Zipper Seal:Basic closure systems dominate mass retail channels with lowest unit economics and highest replacement frequency.
Roll-up formats handle the majority of throughput; vacuum sealed systems are climbing the fastest on share.
Material:
Cost tier stratification separates commodity polymers from technical fabrics with performance certification requirements.
- Plastic:Multi-layer polyethylene laminates with heat-sealed seams constitute the volume base for mass-market roll-up and zipper-seal variants. Walmart and Target procurement in the United States favors this material platform for price-point positioning, though EPA scrutiny of virgin resin content intensifies under state-level recycled mandate trajectories.
- Nylon:Silicone-coated and polyurethane-laminated woven fabrics in 15-30 denier weights deliver tear resistance below one ounce per square yard. Alpine climbing and thru-hiking communities in Colorado and Oregon specify bonded seam construction from this material, with Italian and Japanese technicians commanding scarcity premiums for welded fabrication expertise.
- Polyethylene:Virgin and recycled-grade films serve protective packaging applications with moderate durability requirements.
- PVC:Legacy formulations face REACH Annex XVII phthalate restrictions, forcing exit from EU-bound production lines.
Plastic handles the majority of throughput; nylon is expanding most quickly on share.
Application:
Geography shapes application priority, with mobile lifestyles in the United States diverging from space-constrained European urbanism.
- Travel:Compression systems for luggage optimization target airline carry-on restrictions and checked-bag fee avoidance. TSA-compliant transparent panels and tear-resistant fabrics dominate this segment, with REI and specialized outdoor cooperatives in Oregon specifying fleet standards for rental equipment pools.
- Home Storage:Seasonal textile protection and closet organization drive repeat purchase patterns among suburban homeowners. German consumers prioritize REACH-compliant formulations, while French buyers emphasize aesthetic integration with interior design schemes.
- Clothing:Garment-specific sizing and shoulder shaping preserve formal wear integrity during extended compression.
- Seasonal Items:Bulky duvet and decorative storage solutions prioritize volume reduction over weight minimization.
Home storage handles the majority of throughput; travel is gaining share fastest.
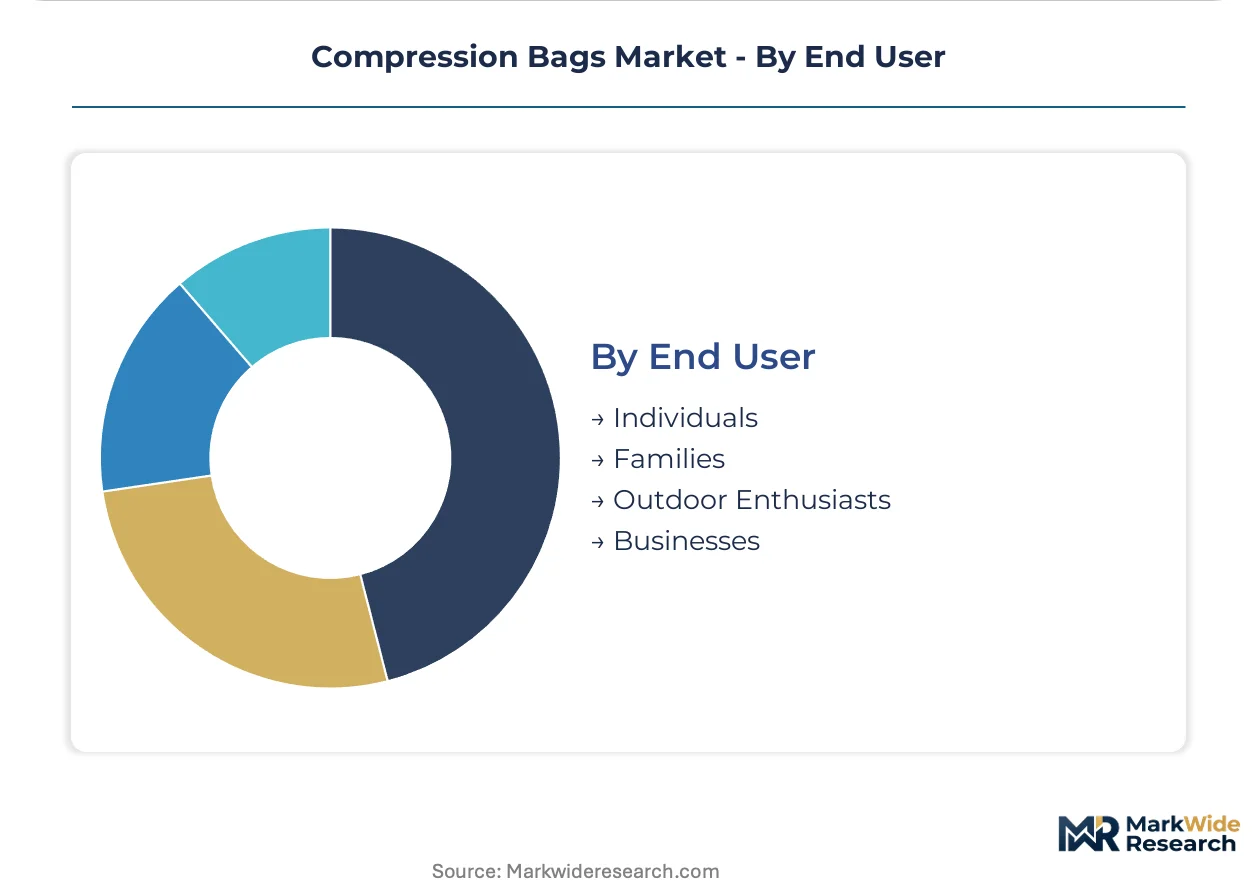
End User:
Customer type determines channel strategy and price elasticity, from individual impulse purchases to enterprise fleet procurement.
- Outdoor Enthusiasts:Thru-hikers, alpine climbers, and van-life converts demand sub-ounce weights with bonded seam integrity. Sea to Summit and Osprey compete for this cohort through specialty retail and direct-to-community engagement, with Colorado-based subscription rental platforms displacing individual ownership for occasional users.
- Families:Multi-unit purchases for household organization prioritize durability and child-safe valve mechanisms over technical weight specifications.
- Individuals:Single-person urban households drive compact-format demand for studio apartment optimization.
- Businesses:Hospitality linen management and emergency services equipment staging require institutional-grade durability with standardized sizing.
Families handle the majority of throughput; outdoor enthusiasts are the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Consumer Product Safety Commission anchors the regulatory environment where van-life downsizing and urban space constraints drive adoption. German and French markets respond to ECHA chemical restrictions, while Asian manufacturing clusters pivot toward compliant material platforms.
United States
California's Proposition 65 labeling requirements and EPA scrutiny of virgin resin content shape formulation decisions for brands distributing nationwide. Colorado and Oregon host subscription-based outdoor equipment rental platforms that specify compression-compatible storage as fleet standards. The Pacific Northwest cluster concentrates bonded seam expertise serving alpine climbing communities.
Germany
REACH Annex XVII restrictions on phthalate plasticizers force compound reformulation across production lines bound for German consumers. ECHA notification procedures for alternative plasticizer systems extend supplier qualification timelines. Bavarian retailers emphasize aesthetic integration with interior design schemes for home storage applications.
France
French buyers prioritize REACH-compliant formulations alongside visual integration with residential spaces. Decathlon retail networks drive mass-market adoption of hybrid space-saver constructions. The Île-de-France region concentrates demand among urban apartment dwellers managing seasonal wardrobe transitions.
China
Yuyao and Yiwu industrial clusters scale woven nylon and polyethylene capacity for roll-up and zipper-seal variants. The country's national chemical safety regulator monitors plasticizer content in PVC-based formulations. Zhejiang Province manufacturers compete on volume throughput for mass retail channels.
India
Maharashtra and Karnataka organized camping sectors remain underserved by branded compression systems. The Bureau of Indian Standards shapes material certification requirements for imported polymer products. Mumbai-based distributors report procurement is shifting toward technical fabrics for emerging trekking communities.
Compression Bags Market Competitive Environment
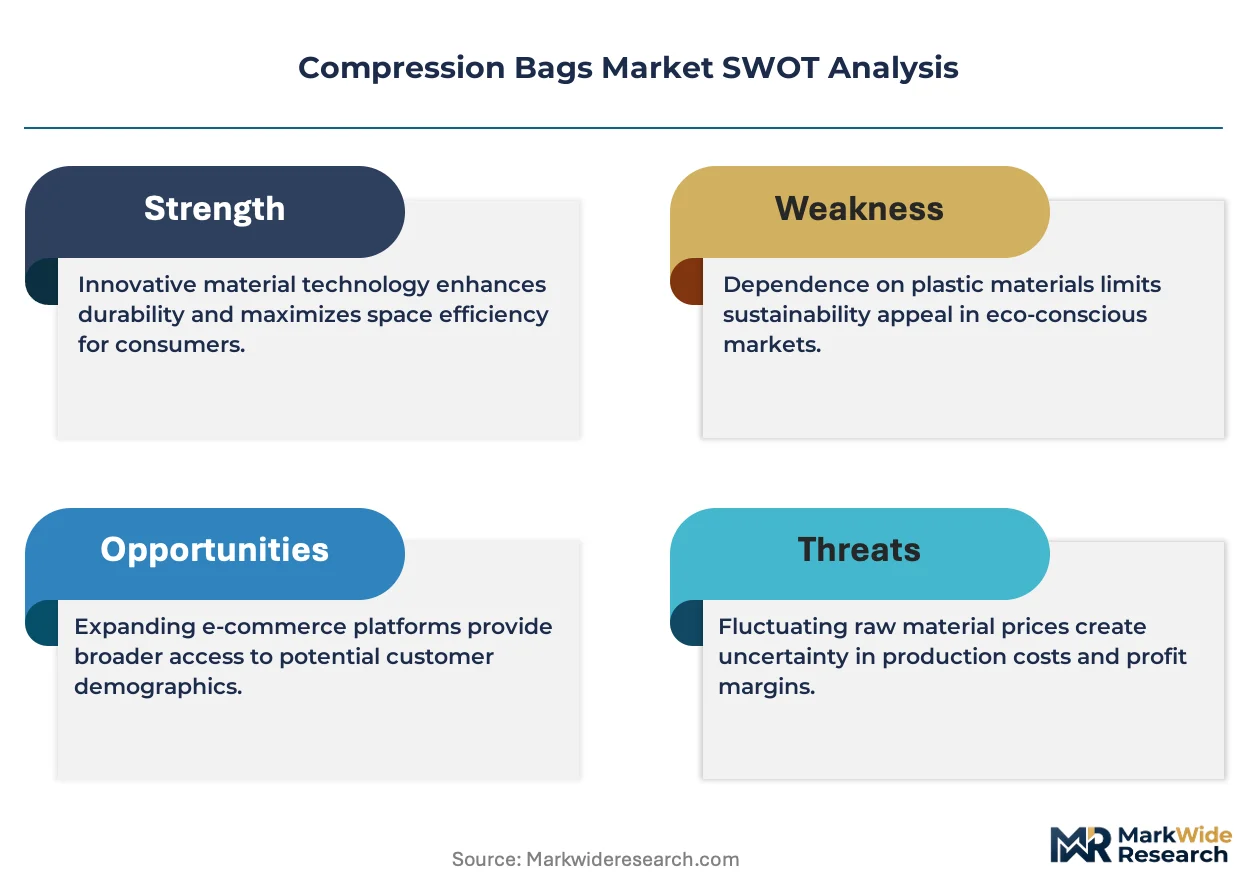
Capability concentration sits with one tier; scale advantage sits with another. Bonded seam construction for ultralight applications concentrates among alpine equipment specialists, while volume manufacturers compete on throughput for mass retail channels. Three strategic archetypes define the structure: technical specialists commanding scarcity premiums for welded fabrication, vertically integrated outdoor brands controlling fabric sourcing, and commodity producers optimizing roll-up and zipper-seal variants. Capacity expansion and portfolio diversification represent the dominant competitive moves as players respond to REACH compliance costs and recycled-content mandates.
Within the technical specialist tier, Sea to Summit and Osprey exemplify premium positioning through bonded seam construction and in-house fabric sourcing. Yuyao Boya Packing Products Co. Ltd. anchors the scale-driven segment, representing commodity manufacturers competing on volume throughput for mass retail distribution. ZPacks occupies a position among ultralight specialists serving thru-hiking communities where sub-ounce weights justify price premiums.
| Leading Market Players |
|---|
| Gobi Gear |
| Hyperlite Sacks |
| Yuyao Boya Packing Products Co. Ltd. |
| Osprey |
| Sea to Summit |
| Yiwu City Kaiyun Packaging Co. Ltd. |
| Granite Gear |
| ZPacks |
| Real Space Bag |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Zhejiang Province's polyethylene film extrusion sector is compressing contract margins for roll-up format producers while simultaneously forcing bonded seam specialists in Italy and Japan to extend lead times and lift pricing for ultralight nylon laminates. This utilization divergence creates a bifurcated sourcing environment where mass-market buyers enjoy procurement leverage while technical outdoor brands absorb scarcity premiums for welded construction expertise.
Pricing Analysis
Geographic price spreads between Yuyao mass-market suppliers and Italian alpine equipment specialists exceed threefold for comparable volume-rated bags, with bonded seam certification and REACH-compliant compound formulation driving differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies by construction method, with silicone-coated nylon variants commanding tier-one positioning and heat-sealed polyethylene occupying tier-three. Pricing pressure stems from Southeast Asian woven nylon capacity expansion, which is eroding China's historical cost advantage in technical fabrics. Families purchasing through Walmart and Target channels exhibit highest price sensitivity, while Colorado-based subscription rental platforms prioritize durability metrics over unit cost.
Supply Chain Analysis
Yuyao Boya Packing Products Co. Ltd. and Yiwu City Kaiyun Packaging Co. Ltd. anchor contract manufacturing concentration for roll-up and zipper-seal variants, with bonded seam fabrication concentrating among Italian alpine equipment specialists and Japanese technical fabric houses. Raw material flows draw from Zhejiang Province polyethylene resin suppliers, Jiangsu silicone-coated nylon weavers, and Taiwanese precision valve component manufacturers. Single-source vulnerability concentrates in one-way valve engineering, where specialized Taiwanese and German suppliers control precision silicone seal production. Distribution runs through Decathlon and REI retail networks for premium tiers, with Amazon and mass-market big-box channels handling volume throughput for commodity formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment rental platform economics are compressing individual ownership cycles and creating fleet-standard procurement power that favors interoperable storage systems across Colorado and Oregon cooperatives.
For Market Incumbents: Insulate margin stability through backward integration into silicone-coated nylon sourcing, mirroring Osprey's captive fabric supply model, while accelerating REACH-compliant compound certification to preempt regulatory exclusion from German and French retail networks. Bonded seam technician scarcity in Italy and Japan represents a defendable capability moat against Southeast Asian volume competitors. For New Entrants and Emerging Players: Build out technical fabric competence targeting Maharashtra and Karnataka's underserved trekking communities, where organized camping sectors lack branded compression system penetration. India's Bureau of Indian Standards certification pathway offers lower competitive density than EU ECHA notification procedures. Direct engagement with Mumbai-based distributors provides faster route-to-market than competing for Decathlon shelf space. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based outdoor equipment rental platforms, which specify compression-compatible storage as fleet standards and generate predictable replacement demand. Acquisition targets should demonstrate welded fabrication expertise or captive technical fabric sourcing. The signal to watch is California SB 54 recycled-content mandate enforcement, which will disqualify virgin polyethylene-dependent producers from priority procurement pools.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Compound Reformulation | ECHA notification procedures for alternative plasticizers secure German and French market access. |
| Bonded Seam Technician Training Programs | Welded fabrication expertise scarcity in Italy and Japan creates defendable capability premiums. |
| Post-Consumer Recycled Content Integration | rPET and rNylon variants satisfy California SB 54 procurement preferences. |
| Subscription Rental Platform Partnerships | REI and regional cooperatives in Colorado displace individual ownership with fleet-standard procurement. |
| RFID-Integrated Smart Valve Development | Convergence with textile tagging enables shared-equipment inventory tracking and rental model expansion. |
Study Parameters
A standing panel of brand managers at outdoor equipment manufacturers, category buyers at REI and Decathlon, bonded seam technicians at Italian and Japanese fabrication houses, and procurement leads at Zhejiang Province contract manufacturers provided ongoing calibration. Primary fieldwork combined structured interviews with supply chain stakeholders and secondary validation through customs records, SEC 10-K filings of publicly traded outdoor brands, and EPA regulatory filing databases. Bottom-up unit economics modeling triangulated against top-down market sizing from retail audit data.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions including construction method, material platform, end-use application, and customer archetype. CAGRs derived from regression analysis of historical capacity expansion patterns and regulatory compliance cost trajectories. Forecast inputs incorporated REACH Annex XVII enforcement timelines and California recycled-content mandate adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Southeast Asian woven nylon producers or accelerated technician training programs by Italian alpine equipment houses would shift outcomes. Quarterly review of ECHA notification approval rates, Zhejiang Province polyethylene resin pricing, and Colorado rental platform fleet expansion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Padding Bags Market
Bags and Containers
On the Go Packaging Market