
 Digital Folding Cartons Market | 2026-2036
Digital Folding Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Folding Cartons Market Outlook
Digital print-to-pack workflows is fragmenting legacy analog supply chains by enabling economic lot sizes below five hundred units. WestRock leverages its North American mill network to anchor high-volume folding carton production while integrating digital modules for hybrid runs. Amcor competes through pharmaceutical-grade barrier coatings that sustain compliance with FDA and EMA serialization directives. Graphic Packaging specializes in food-safe direct-to-board inkjet, dominating quick-serve restaurant and fresh-protein segments where variable data and regional versioning prove essential.
Digital folding cartons are paperboard or corrugated substrates fabricated with crease-scored geometry, digitally printed with pigment or dye-based inks, then die-cut and glued into self-erecting rectangular containers. Typical calipers range from twelve to twenty-four point SBS board, with inline coating units applying aqueous or UV-cured varnish for rub resistance and shelf appeal. Straight tuck and reverse tuck configurations lead unit volume across cosmetics and over-the-counter pharmaceutical applications where hand-fill assembly remains prevalent. Seal end cartons represent the fastest-growing structural category in e-commerce subscription and meal-kit channels, as automated fulfillment lines demand glue-flap closure integrity at speeds exceeding one hundred cartons per minute. Inkjet printing technology captures expanding share among mid-tier brands, displacing offset for runs below ten thousand impressions where plate costs and makeready waste erode margins.
FDA 21 CFR Part 11 and the EU Falsified Medicines Directive shape pharmaceutical carton demand by mandating unique identifier serialization and tamper-evident features. REACH and ECHA restrictions on heavy metals in packaging inks redirect formulation R&D toward mineral-oil-free and UV-curable alternatives. California's Proposition 65 and the EU Packaging and Packaging Waste Regulation intensify scrutiny of recycled fiber content and recyclability claims. Stakeholders must monitor how divergent state-level extended producer responsibility schemes and federal preemption debates in the United States reshape compliance cost structures and regional sourcing decisions.
Market Dynamics
HP Indigo electroink technology is hybridizing with water-based inkjet platforms to collapse analog makeready times from hours to minutes, forcing converters to restructure prepress departments and retrain press crews for digital-first workflows.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization mandates for pharmaceutical packaging require unique identifiers on every carton, driving demand for digital print's variable data capabilities.
- Short-run customization:Brand owners in cosmetics and nutraceuticals now order lot sizes below five hundred units for regional versioning and limited-edition campaigns.
- Meal-kit channel expansion:Seal end cartons with glue-flap closure integrity support automated fulfillment lines operating above one hundred cartons per minute.
Market Restraints
- Pigment ink cost structure:Electroink and UV-curable formulations cost three to five times more per liter than conventional offset inks, compressing margins on price-sensitive food packaging.
- Board supply concentration:Solid bleached sulfate mills in the southeastern United States control sixty percent of North American caliper availability, exposing converters to fiber price volatility.
- Substrate limitation:Digital presses cannot reliably image recycled-content board above eighty percent post-consumer fiber due to surface irregularity and moisture sensitivity.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO serialization requirements align with EU and FDA standards, creating demand for compliant carton supply to generic drug manufacturers in Gujarat and Telangana.
- Regulatory tailwind from California Proposition 65:Warning label variability requirements favor digital production for consumer goods distributed across state lines.
- RFID-NFC convergence:Embedding near-field communication tags during inline die-cutting enables authentication and consumer engagement without secondary labeling operations.
Industry Challenges
- Prepress skill obsolescence:Conventional plate-making expertise does not transfer to color management for electroink dot gain characteristics, creating hiring bottlenecks.
- Legacy ERP integration:Shop floor data from digital presses using JDF protocols often conflicts with analog-era inventory systems, delaying real-time job tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Folding Cartons Market |
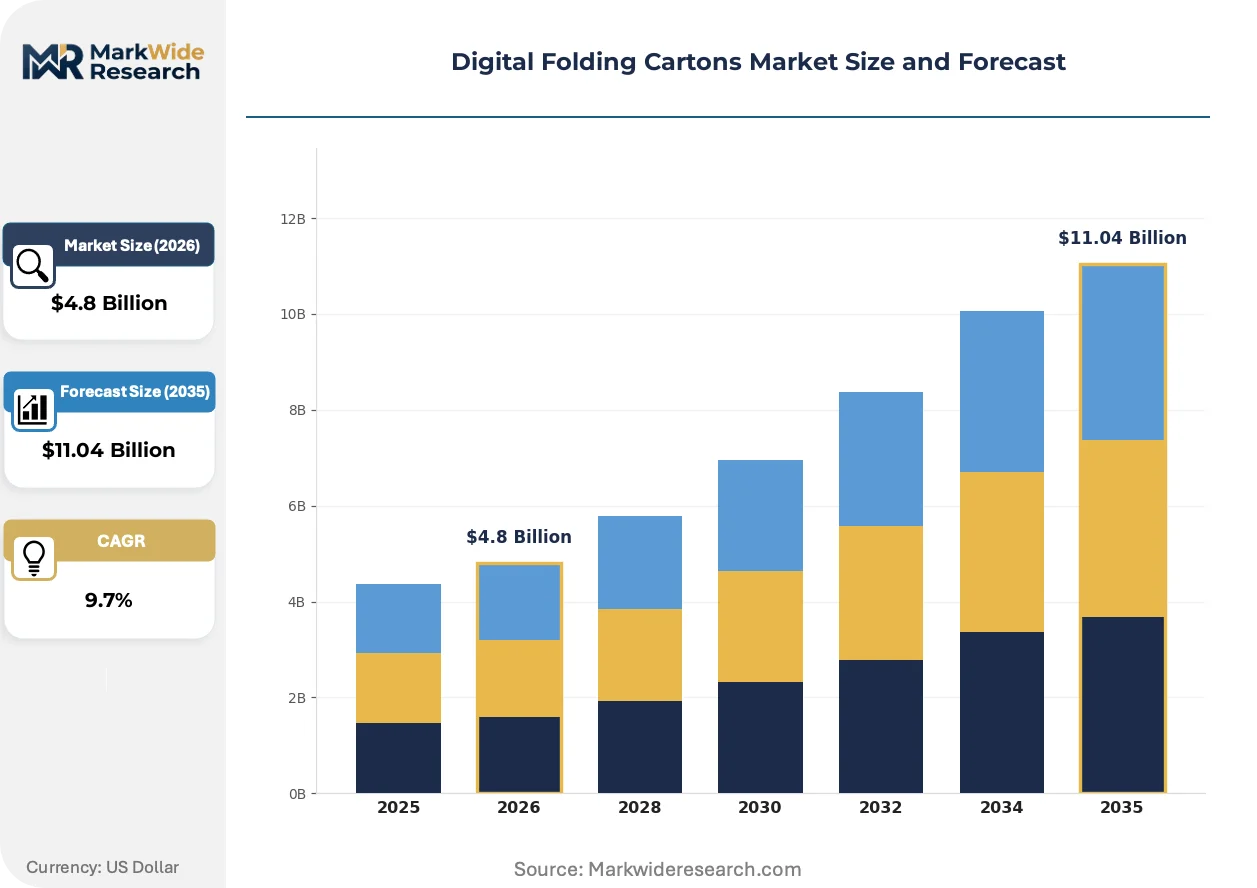
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Tuck, Reverse Tuck, Seal End, Sleeve Type Material: Paperboard, Corrugated Board, Fiberboard, Plastic End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Printing Technology: Inkjet, Laser, Flexographic, Offset |
| Companies Covered | WestRock, Amcor, AR Packaging, Graphic Packaging, Edelmann Group, Rondo-Pak, CCL Industries, Quad/Graphics, HP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Folding Cartons Market Strategic Shifts
Workflow automation and inline finishing systems are compressing the time from file receipt to shipped carton, eliminating the buffer inventory that analog production required.
Single-pass inkjet arrays running aqueous pigment formulations at production speeds are hybridizing with traditional flexo coating stations, enabling converters to switch between decorative and functional layers without press stops. Food processors and fresh-protein packers in Germany and the Netherlands have adopted these hybrid lines for runs between two thousand and twenty thousand impressions. The technology is hybridizing supply chains by collapsing what were separate prepress, printing, and converting vendors into single-source digital carton suppliers.
REACH Annex XVII restrictions on mineral oil aromatic hydrocarbons in food-contact materials are redirecting ink formulation toward UV-curable and electron-beam cured alternatives. The regulation forces converters to validate new chemistries through migration testing protocols. Dairy and dry-goods segments in France and Italy are accelerating compliance timelines to maintain supermarket shelf access.
Brand owners now specify carton suppliers based on verified recyclability credentials rather than unit price alone, with third-party certification displacing self-declared claims. Quick-serve restaurant chains and personal care brands in the United States and United Kingdom are consolidating vendor lists to those with FSC chain-of-custody and How2Recycle labeling approval. This preference shift concentrates volume among converters who invested early in fiber traceability systems and washability testing for direct-to-board inkjet inks.
Digital Folding Cartons Market Segmentation
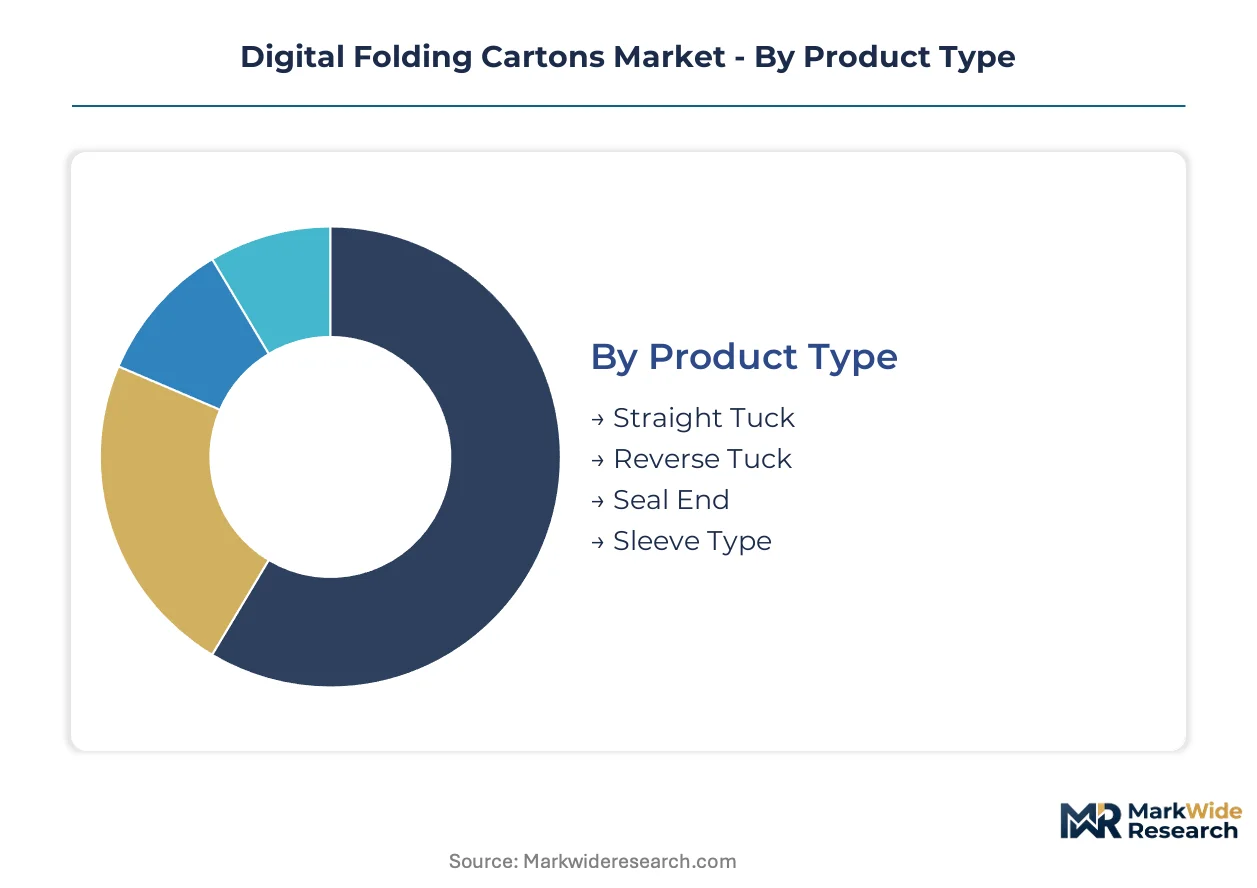
Digital folding carton procurement cycles vary dramatically by structural complexity and regulatory burden. Segmentation reveals where converters earn premium margins versus where volume throughput drives profitability.
Product Type:
Straight tuck configurations turn inventory fastest in hand-fill cosmetics lines, while seal end cartons lock in longer production cycles due to automated fulfillment qualification protocols.
- Straight Tuck:Front panel tucks into rear closure without additional flaps, suiting lightweight pharmaceuticals and cosmetics where manual assembly prevails. Demand concentrates in German and United States cosmetics houses seeking rapid format switches for seasonal campaigns.
- Seal End:Glue-flap closure withstands automated line speeds exceeding one hundred cartons per minute. Meal-kit and e-commerce subscription channels in the United States and Netherlands specify this geometry for fulfillment integrity.
- Reverse Tuck:Rear panel tucks forward, offering cleaner shelf presentation for over-the-counter pharmaceuticals. United States drug chains favor this format for blister pack inserts.
- Sleeve Type:Open-ended wrap construction slides over pre-formed trays or bottles. Fresh-protein and ready-meal applications in Germany and France drive specification.
Straight tuck dominates installed base. Seal end is where expansion concentrates.
Material:
Substrate selection splits between fiber-based options commanding sustainability premiums and plastic retaining niche barrier applications.
- Paperboard:Twelve to twenty-four point solid bleached sulfate forms the standard substrate for pharmaceutical and cosmetic cartons requiring crisp print registration. FDA and EMA serialization mandates in the United States and Europe favor this material for tamper-evident coating compatibility.
- Corrugated Board:E-flute and F-flute micro-corrugates provide structural rigidity for e-commerce shipping applications. United States meal-kit distributors specify this material for stack strength in ambient supply chains.
- Fiberboard:Unbleached kraft liners serve dry-goods and industrial chemical segments where print aesthetics matter less than cost containment.
- Plastic:PET and PP substrates survive moisture exposure in refrigerated protein and fresh produce channels. Limited adoption due to recyclability scrutiny under EU Packaging and Packaging Waste Regulation.
Paperboard commands the revenue base. Corrugated board is climbing the fastest as e-commerce penetration deepens.
End User:
Regulatory intensity and customization frequency separate pharmaceutical procurement from commodity food packaging.
- Pharmaceuticals:Serialization-ready cartons with tamper-evident features and unique identifiers. EU Falsified Medicines Directive and FDA 21 CFR Part 11 compliance requirements in Europe and the United States mandate digital variable data capabilities.
- Food & Beverage:Direct-to-board inkjet with food-safe aqueous coatings. Quick-serve restaurant chains in the United States specify regional versioning for promotional tie-ins.
- Cosmetics:Premium board stocks with soft-touch varnishes and metallic embellishments. Limited-edition campaigns in Germany and France drive short-run digital adoption.
- Electronics:Anti-static coatings and precise fitments for accessory and component protection. Concentrated in China and United States consumer electronics assembly corridors.
Food and beverage generates the volume base. Pharmaceuticals is where margin expansion concentrates.
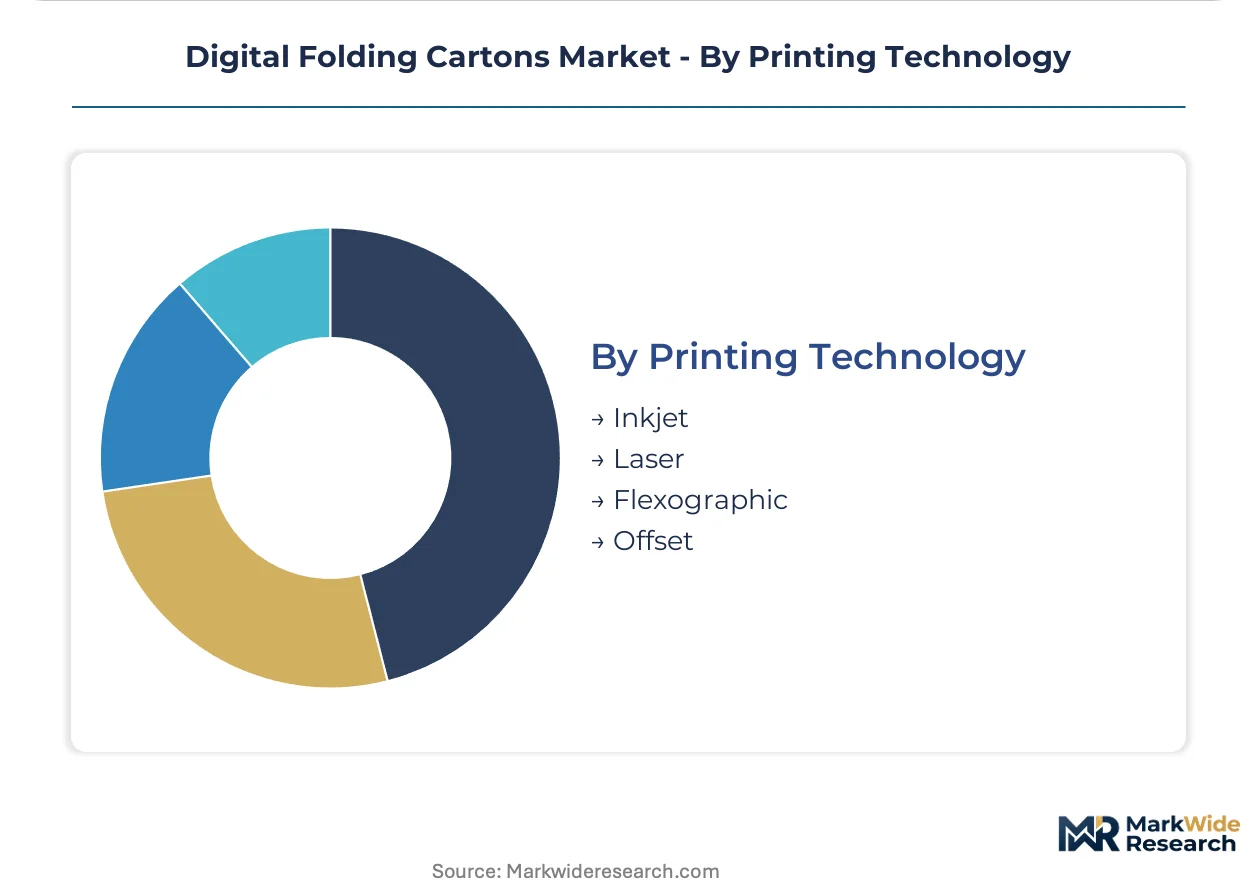
Printing Technology:
Capital intensity and makeready economics determine which technology platforms capture specific run-length bands.
- Inkjet:Single-pass aqueous pigment arrays image porous substrates without plate costs. Mid-tier brands in Germany and the United States deploy this technology for runs between two thousand and twenty thousand impressions.
- Laser:Electrophotographic toner systems excel at ultra-short runs below five hundred units with precise registration. Cosmetics sampling and clinical trial materials in Switzerland and the United States specify this platform.
- Flexographic:Rotary relief printing with photopolymer plates sustains cost efficiency above fifty thousand impressions. Legacy food packaging volumes in the United States remain anchored here.
- Offset:Lithographic transfer from metal plates dominates high-volume pharmaceutical inserts where color consistency across million-unit campaigns matters. United States and China facilities maintain this capacity for blockbuster drug launches.
Offset retains the largest installed base. Inkjet is gaining share fastest as run lengths fragment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports pharmaceutical-grade folding cartons to European Union markets and North American buyers, with serialization-compliant production anchoring cross-border supply chains for generic drug manufacturers.
United States
Meal-kit distributors and quick-serve restaurant chains drive seal end carton specifications for automated fulfillment lines. FDA 21 CFR Part 11 mandates unique identifier serialization for pharmaceutical packaging. The Southeast mill corridor supplies solid bleached sulfate board to converters in Georgia and the Carolinas.
Germany
Cosmetics houses and fresh-protein packers demand short-run customization with rapid format switches. REACH Annex XVII restrictions on mineral oil aromatic hydrocarbons redirect ink formulation toward UV-curable alternatives. The Baden-Württemberg and Bavaria industrial clusters host hybrid inkjet-flexo production lines for food-contact materials.
China
Consumer electronics assembly corridors generate demand for anti-static coated cartons with precise fitments. NMPA serialization requirements for domestic pharmaceutical distribution align with international standards. The Yangtze River Delta and Pearl River Delta concentrate digital press installations serving export-oriented brand owners.
India
Generic drug manufacturers in Gujarat and Telangana require CDSCO-compliant serialization for export to regulated markets. The country's national pharmaceutical regulator enforces traceability standards matching EU and FDA directives. Maharashtra and Karnataka host converting operations supplying pharmaceutical export corridors.
Netherlands
Food processors and fresh-protein packers adopt hybrid aqueous pigment inkjet lines for regional versioning. ECHA restrictions on heavy metals in packaging inks accelerate validation of mineral-oil-free formulations. The Randstad logistics hub enables just-in-time carton delivery to German and Belgian retail distribution centers.
Digital Folding Cartons Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven converters anchor high-volume pharmaceutical contracts while mid-tier specialists capture fragmented cosmetics and nutraceutical demand. The market separates into three strategic archetypes: integrated paperboard suppliers with captive mill networks, pure-play converters with digital-first equipment portfolios, and diversified packaging conglomerates with barrier coating capabilities. Dominant competitive moves include backward integration into board supply and technology licensing partnerships for single-pass inkjet arrays.
Among North American integrated suppliers, WestRock and Graphic Packaging exemplify the mill-network archetype, anchoring volume production while selectively deploying digital modules for hybrid run configurations. Amcor represents the diversified conglomerate position with pharmaceutical-grade barrier coating expertise. These three companies occupy positions across the premium and standard tiers, with their geographic footprints and regulatory compliance capabilities determining access to serialization-mandated pharmaceutical contracts.
| Leading Market Players |
|---|
| WestRock |
| Amcor |
| AR Packaging |
| Graphic Packaging |
| Edelmann Group |
| Rondo-Pak |
| CCL Industries |
| Quad/Graphics |
| HP |
| Others |
Value Chain & Pricing Dynamics
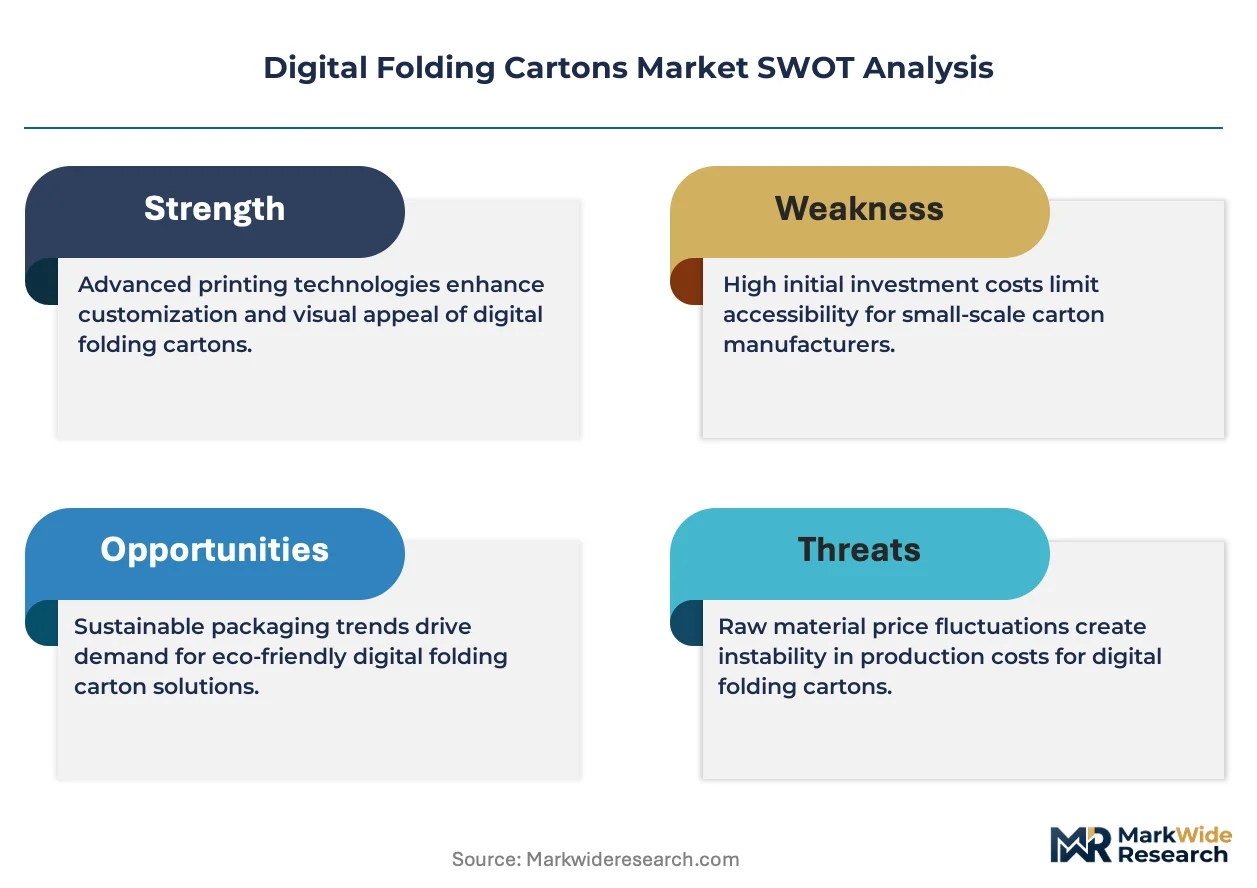
The southeastern United States mill corridor controls solid bleached sulfate caliper availability, concentrating upstream fiber supply in Georgia and the Carolinas. This geographic chokepoint grants incumbent converters pricing leverage over mid-tier competitors who lack captive board supply, while pigment ink cost premiums compress margins on food packaging runs below ten thousand impressions.
Pricing Analysis
Electroink and aqueous pigment inkjet platforms command three-to-five-fold premiums over conventional offset formulations, creating a technology-generation pricing gap that stratifies converter tiers. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade serialization-compliant cartons from commodity food packaging and generic cosmetics. Price differentiation hinges on FDA and EMA certification tiers and volume scale, with quick-serve restaurant chains exhibiting highest sensitivity to unit cost while pharmaceutical brand owners prioritize compliance over price. Cost compression in standard-tier food packaging is intensifying because single-pass inkjet arrays displace flexo for mid-length runs.
Supply Chain Analysis
Upstream feedstock for digital folding cartons draws from solid bleached sulfate mills concentrated in the United States, Germany, and China, with corrugated micro-flutes increasingly sourced from Scandinavian kraft liner producers. Raw material dependencies center on wood pulp pricing, specialty pigment formulations, and UV-curable varnish chemistries. Supply chain risk from single-source vulnerability runs through the southeastern United States mill network, where fiber price volatility transmits directly to converter cost structures. Distribution runs through regional converting hubs co-located with pharmaceutical manufacturing clusters in New Jersey, Bavaria, and Gujarat.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital folding cartons represent a service-attach opportunity where inline finishing and serialization compliance layers expand faster than press hardware sales. Recurring revenue from workflow automation software and regulatory validation services now outpaces equipment margins for technology vendors.
For Market Incumbents: Pre-empt margin erosion from water-based inkjet commoditization by backward integration into mineral-oil-free ink formulation and captive SBS board supply. Anchor high-volume pharmaceutical contracts through EMA and FDA serialization certification investments while deploying digital modules for hybrid run configurations that retain customers during volume fragmentation. For New Entrants and Emerging Players: Build out white-space positions in Indian pharmaceutical export corridors and European fresh-protein regional versioning segments where incumbent coverage remains thin. The most penetrable entry point sits with mid-tier cosmetics houses in Germany seeking sub-five-hundred-unit campaigns with rapid format switches. Lead with JDF-integrated workflow software that resolves legacy ERP conflicts for analog-era converters. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because serialization mandates across FDA, EMA, and CDSCO jurisdictions create durable demand for validated digital carton supply. Acquisition targets should display hybrid press portfolios with pharmaceutical barrier coating capabilities and FSC chain-of-custody certification. The signal to watch is CDSCO enforcement intensity against Gujarat generic manufacturers exporting to regulated markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ink Formulation | Captures margin from REACH-compliant mineral-oil-free pigment chemistry validation. |
| Hybrid Press Portfolio Expansion | Positions converters for run-length fragmentation between flexo and pure digital thresholds. |
| Pharmaceutical Serialization Certification | Unlocks FDA 21 CFR Part 11 and EU Falsified Medicines Directive contract access. |
| Workflow Automation Software Licensing | Resolves JDF protocol conflicts with analog-era ERP systems for mid-tier converters. |
| Fiber Traceability System Investment | Secures How2Recycle and FSC chain-of-custody approval for quick-serve restaurant vendor lists. |
Study Parameters
Desk research of SEC 10-K filings, customs and trade data, and REACH regulatory submissions preceded structured interviews with folding carton plant managers, pharmaceutical packaging procurement leads, digital press OEM sales engineers, and ink formulation R&D directors. Primary fieldwork validated secondary estimates through bottom-up capacity assessments and top-down demand triangulation across pharmaceutical, food, and cosmetics end-use segments.
Forecast assumptions held regulatory enforcement timelines and fiber price volatility within observed historical bands while varying digital press adoption curves and run-length fragmentation rates across the analysis window. Segmentation modeling incorporated structural configuration, substrate material, end-use regulatory intensity, and printing technology capital intensity. CAGRs derived from installed base evolution and replacement demand projections, with pharmaceutical serialization mandate compliance schedules and meal-kit channel penetration serving as key demand inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed converters or sudden REACH enforcement acceleration would shift outcomes beyond modeled ranges. Cross-checking against ECHA substance restriction notifications and FDA warning letter databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Folding Carton in Healthcare Market
Cartons
Africa Folding Carton Market
Cartons
Interlocking Boxes Market
Cartons
Fluted Carton Trays Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Cartoning Machines Market
Cartons
Liquid Packaging Cartons Market
Cartons
Printed Folding Cartons Market
Cartons
Tuck Top Box Market
Cartons
MET-PET Cartons Market
Cartons
Metallized Folding Cartons Market
Cartons
Indonesia Folding Carton Packaging Market
Cartons
Carton Sealer Machine Market
Cartons
End Load Cartoning Machine Market
Cartons
Global Printed Cartons Market
Cartons
Global Beverage Carton Packaging Machinery Market