
 Global Open Top Cartons Market | 2026-2036
Global Open Top Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Open Top Cartons Market Intelligence
The rapid expansion of e-commerce for fresh produce and prepared meals is repositioning the functional requirements for open top cartons away from simple bulk transport. Smurfit Kappa leverages its extensive network of paper mills to ensure a consistent supply of recycled fiberboard for this evolving segment. International Paper competes on its vast manufacturing scale and logistical reach across North America. Mayr-Melnhof Karton AG differentiates with high-quality virgin fiberboard for premium consumer goods and cosmetic packaging.
Open top cartons are single-piece, die-cut paperboard containers without a top lid, facilitating product visibility and access. Structural integrity depends on the caliper of materials like Solid Bleached Sulfate, selected for direct food contact. Corrugated fiberboard dominates high-volume agricultural shipments, while recycled paperboard gains share in consumer goods packaging. Food and beverage applications constitute the largest value pool, with electronics packaging demanding specialized anti-static inserts.
Material safety is governed by frameworks including the US FDA's regulations for food contact substances and the EU's REACH directive for chemical safety. In Asia, China's GB standards dictate specific requirements for packaging materials entering the domestic market. These rules directly influence the selection of adhesives, inks, and paperboard coatings. Future market leadership will depend on developing designs that reduce material use without compromising structural integrity.
Market Dynamics
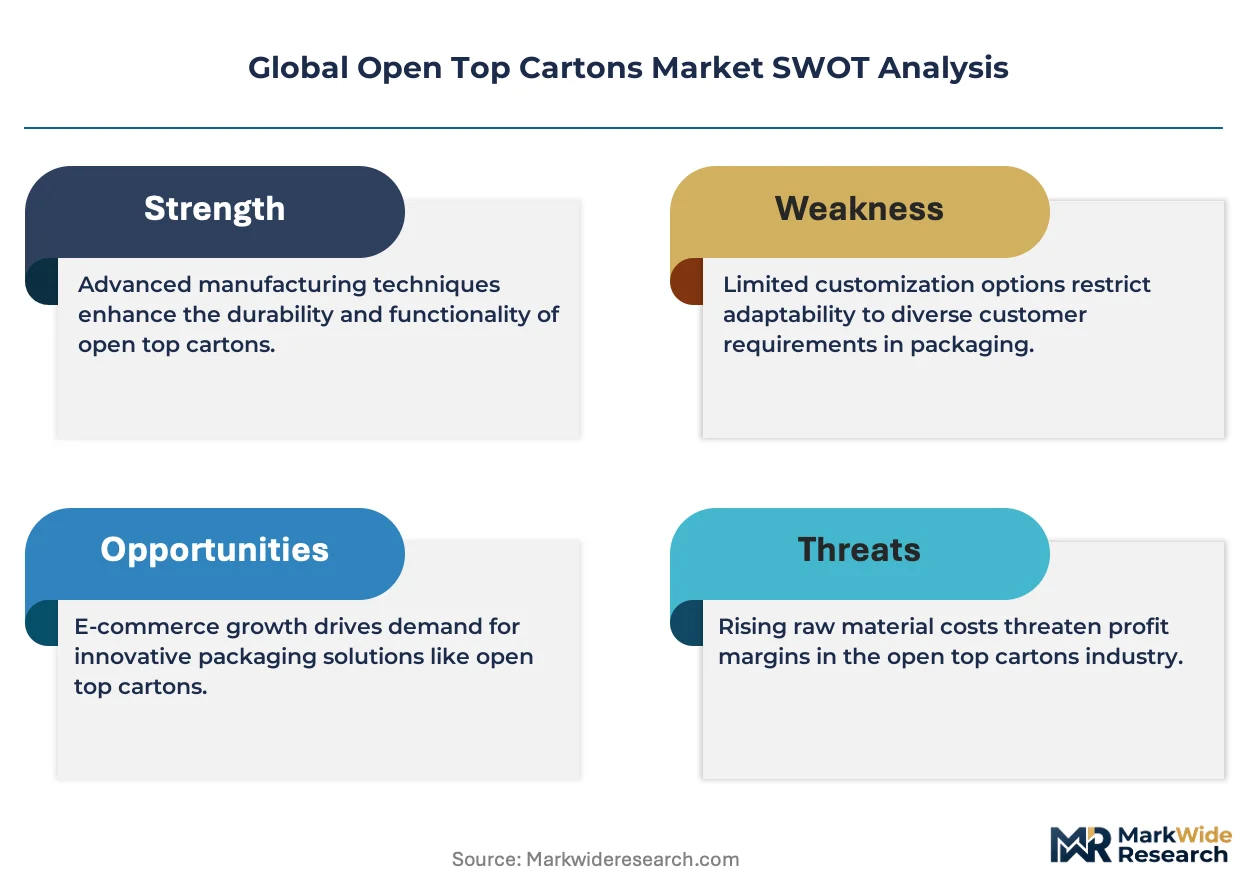
The market's central dynamic is the tension between sustainability mandates, such as the EU Green Deal, demanding circular materials, and the rigorous performance requirements of the expanding e-commerce channel for fresh and prepared foods, which prioritizes structural integrity and product protection.
Growth Catalysts
- E-commerce Expansion:The growth of online grocery and meal-kit delivery services necessitates shelf-ready and visually appealing open top cartons that function as both transport and display packaging.
- Regulatory Pressure on Plastics:European Union policies promoting a circular economy are accelerating the substitution of single-use plastic trays with recyclable and renewable paperboard-based alternatives in the fresh produce sector.
- High-Graphic Printing Demand:In advanced retail markets like Germany, brand owners are leveraging high-quality printing on cartons to differentiate fresh produce at the point of sale, transforming packaging into a marketing tool.
Market Restraints
- Input Cost Volatility:The price and availability of recycled fiberboard, a primary raw material, are subject to fluctuations in global wastepaper collection rates, energy costs, and international trade policies, impacting manufacturer margins.
- Performance Trade-offs:There is an inherent technical challenge in reducing material caliper and weight for sustainability and cost reasons while maintaining the necessary stacking strength and moisture resistance for agricultural supply chains.
- Substitution from RPCs:In closed-loop B2B logistics, particularly for high-volume produce shipments, returnable plastic crates (RPCs) present a durable and reusable alternative that can displace single-use paperboard cartons.
Strategic Opportunities
- Non-Food Application Development:There is an opportunity to engineer specialized open top cartons with features like anti-static coatings and custom inserts for the electronics and small consumer appliance markets.
- Digital Integration:Incorporating QR codes or other digital markers onto cartons enables enhanced supply chain traceability and direct consumer engagement, a valuable feature for premium and organic food brands.
- Emerging Market E-Grocery:Untapped growth exists in developing e-grocery sectors in Southeast Asia and Latin America, where rising disposable incomes and urbanization are creating new demand for packaged fresh foods.
Industry Challenges
- Divergent Food Contact Regulations:Manufacturers face complexity in ensuring packaging materials, adhesives, and inks comply with a patchwork of international standards, including FDA regulations in the US, REACH in Europe, and GB standards in China.
- Packaging Design Skill Gaps:A scarcity of packaging engineers who can effectively use advanced software to design lightweighted cartons that meet structural performance criteria hinders material reduction efforts.
- Capital Investment Hurdles:Competing for premium packaging contracts requires significant capital expenditure in modern, high-speed die-cutting and multi-color flexographic or digital printing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Open Top Cartons Market |
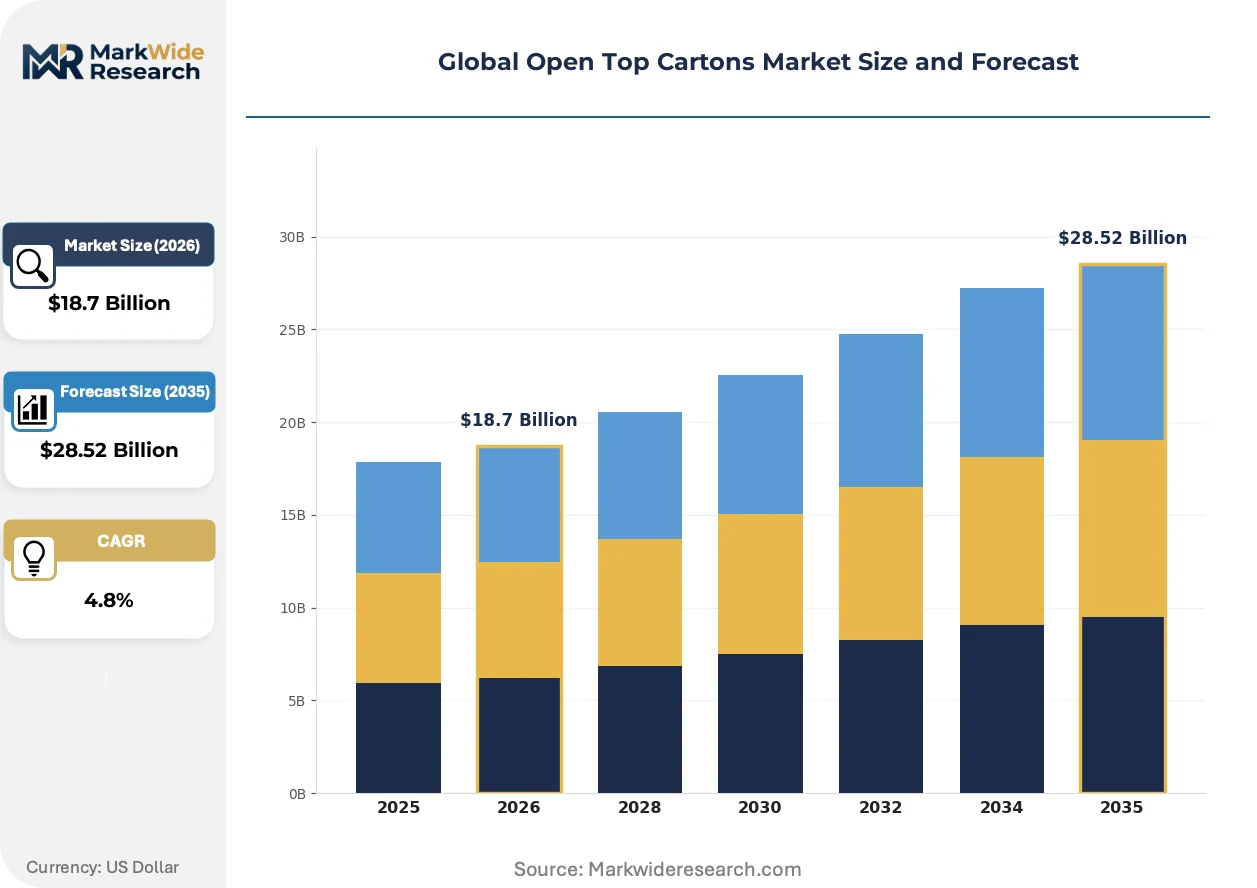
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kraft Paperboard, Corrugated Fiberboard, Recycled Paperboard, Solid Bleached Sulfate, Solid Unbleached Sulfate End Use Application: Electronics Packaging, Food & Beverage Containers, Cosmetic Packaging, Pharmaceutical Packaging, Consumer Goods Storage Manufacturing Process: Die Cutting, Gluing, Folding, Printing, Lamination Distribution Channel: Direct Sales, Retail Chains, Wholesalers, Online Marketplaces, Distributors |
| Companies Covered | Huhtamaki, Graphic Packaging International, Mayr-Melnhof Karton AG, Smurfit Kappa, International Paper, Amcor Plc, Mondi Group, Oliver Inc., WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Open Top Cartons Market Strategic Shifts & Innovations
Material science and digital capabilities are transforming open top cartons from simple containers into strategic assets. Innovations focus on reducing environmental impact through lightweighting and recyclability while enhancing brand communication and supply chain efficiency through advanced printing and data integration.
Digital printing technology enables cost-effective, short-run production of cartons with variable graphics and promotional messaging. Fresh produce growers and private-label food brands are adopting this capability to execute targeted, regional marketing campaigns without the high setup costs of traditional printing methods. The ability to customize packaging on demand is electrifying the shelf-ready segment, converting a logistical necessity into a dynamic point-of-sale marketing instrument.
The EU's Packaging and Packaging Waste Regulation (PPWR) establishes stringent targets for material recyclability and the inclusion of recycled content. This legislation directly pressures manufacturers to abandon multi-material composites and favor mono-material paperboard designs that are compatible with existing recycling infrastructure. The food and beverage segment is most affected, redesigning packaging to ensure compliance and maintain market access in Europe.
Buyers in the grocery sector are shifting their evaluation criteria from a narrow focus on per-unit cost to a total-cost-of-ownership model. This new procurement logic prioritizes carton designs that minimize product spoilage, reduce labor for in-store stocking, and improve logistical density. This behavioral change is most evident in North American and European retail supply chains, where operational efficiency and sustainability metrics are key performance indicators.
Global Open Top Cartons Market Segmentation
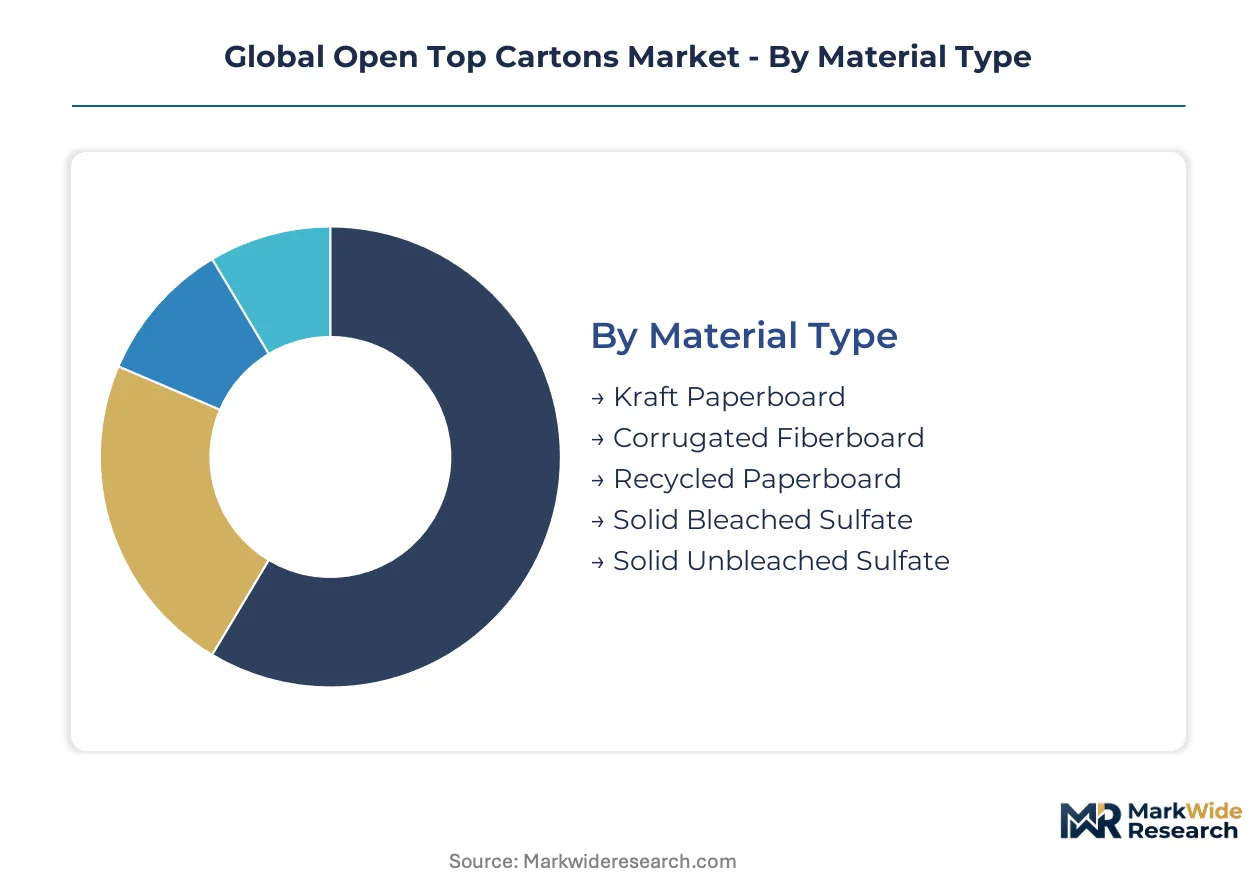
Market segmentation for open top cartons illuminates the diverse material requirements, functional demands, and procurement strategies across various industries. Understanding these distinctions helps manufacturers align product development with specific end-use applications and distribution models.
Material Type:
The supply chain for open top cartons is heavily influenced by the availability and processing capabilities of different paperboard materials, driving distinct market segments.
- Corrugated Fiberboard:This multi-layered paperboard features a fluted corrugated sheet between flat linerboards, providing exceptional strength-to-weight ratio. Demand for corrugated fiberboard dominates high-volume agricultural shipments and e-commerce for its superior protective qualities.
- Recycled Paperboard:Composed of various recovered paper grades, recycled paperboard offers a sustainable and cost-effective material choice. Recycled paperboard gains significant share in consumer goods packaging, driven by EU Green Deal circularity objectives.
- Solid Bleached Sulfate:Virgin fiberboard with a bleached surface, Solid Bleached Sulfate is chosen for premium printing and direct food contact applications.
- Kraft Paperboard:Unbleached pulp material known for its natural strength and tear resistance, Kraft Paperboard is frequently used in industrial packaging.
- Solid Unbleached Sulfate:Strong, unbleached board, Solid Unbleached Sulfate is often used for beverage carriers and heavy-duty general packaging.
Today's leader: Corrugated Fiberboard. Tomorrow's challenger: Recycled Paperboard.
End Use Application:
Different end-use applications impose distinct performance requirements on open top carton designs, shaping product innovation.
- Food & Beverage Containers:This segment requires food-grade materials and often moisture barriers, ensuring product safety and extended shelf life. Food & Beverage Containers constitute the largest value pool, especially for fresh produce and prepared meals in e-grocery.
- Electronics Packaging:This application often necessitates specialized anti-static inserts and custom fitments to protect delicate components during transit. Electronics Packaging is expanding with the growth of small consumer appliances and online electronics sales.
- Consumer Goods Storage:This segment utilizes cartons for retail display and transport of various household items, prioritizing visual appeal and structural integrity.
- Cosmetic Packaging:Cosmetic packaging demands high-quality virgin fiberboard and advanced printing for premium branding and consumer appeal.
- Pharmaceutical Packaging:Pharmaceutical packaging requires strict material safety compliance and often incorporates tamper-evident features for product security.
Food & Beverage Containers are climbing the fastest, driven by shifting consumer purchasing habits.
Manufacturing Process:
High-volume production of open top cartons relies on efficient and automated manufacturing processes, influencing cost structures and design capabilities.
- Die Cutting:This process precisely cuts and scores paperboard sheets into the desired carton shape using specialized tooling. Die Cutting is critical for achieving complex designs and ensuring consistent structural integrity across large batches.
- Printing:This process applies high-graphic images and branding elements using flexographic, lithographic, or digital methods. Printing is essential for brand differentiation and point-of-sale marketing, particularly in advanced retail markets like Germany.
- Folding:Folding involves creasing and bending die-cut blanks into three-dimensional carton structures, often done automatically on production lines.
- Gluing:Gluing secures carton flaps and panels using various adhesive types, ensuring structural stability during transport and display.
- Lamination:Lamination applies a protective or decorative film layer to the paperboard surface, enhancing durability or aesthetic appeal.
Printing technology leads innovation in manufacturing, enabling dynamic marketing campaigns.
Distribution Channel:
The choice of distribution channel reflects the varied purchasing behaviors of open top carton buyers, from large enterprises to smaller businesses.
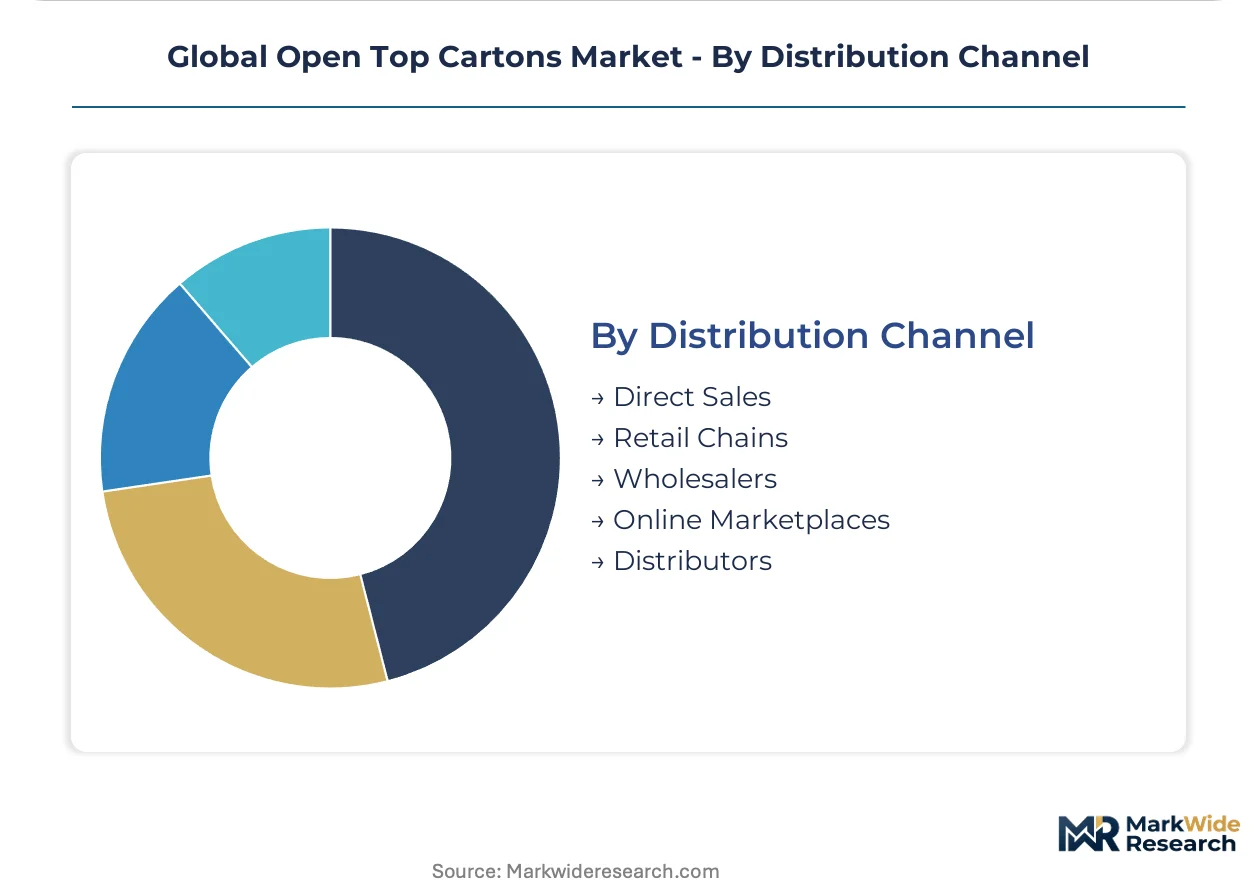
- Direct Sales:This channel involves manufacturers selling directly to large industrial clients or brand owners, facilitating custom orders and integrated supply. Direct Sales are favored by major food and beverage companies requiring bespoke packaging solutions and supply chain integration.
- Online Marketplaces:E-commerce platforms connect buyers and sellers, offering a wide range of standard and customizable carton options. Online Marketplaces are expanding rapidly for small-to-medium enterprises and specialized packaging needs, particularly in emerging e-grocery markets.
- Wholesalers:Wholesalers aggregate products from multiple manufacturers and distribute them to smaller retailers and businesses, offering bulk purchasing options.
- Retail Chains:Retail Chains source open top cartons for their private label products and in-store display needs, often through established supplier relationships.
- Distributors:Distributors serve as intermediaries, managing logistics and inventory for various packaging materials across diverse customer bases.
Online Marketplaces are gaining share fastest, catering to the growing demand from smaller businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr region, a key industrial hub, significantly influences the European open top cartons market. Global demand for these cartons is propelled by expanding e-commerce and regulatory shifts away from plastic packaging. Manufacturers focus on compliance with diverse material safety frameworks across continents.
Germany
Germany's advanced retail market drives demand for high-graphic printed open top cartons for fresh produce. The EU's Packaging and Packaging Waste Regulation (PPWR) mandates increased recyclability. Bavaria's robust food processing industry seeks innovative, compliant carton designs.
United States
United States e-commerce expansion for prepared meals fuels demand for structurally robust open top cartons. The US FDA's regulations for food contact substances influence food packaging material selection. California's vast agricultural sector adopts specialized cartons for efficient distribution.
China
China's burgeoning e-grocery sector and consumer goods market accelerate open top carton adoption. China's GB standards dictate specific material and safety requirements. The Yangtze River Delta's manufacturing centers develop advanced printing capabilities for consumer brands.
India
India's emerging e-grocery market, propelled by rising disposable incomes, increases demand for packaged fresh foods. The Bureau of Indian Standards (BIS) sets quality benchmarks for packaging materials. Bengaluru's tech and logistics hubs pioneer innovative carton solutions for last-mile delivery.
France
French demand for premium food and beverage packaging, alongside strong sustainability mandates, shapes carton innovation. The European Union's REACH directive governs chemical safety in packaging. The Rhône-Alpes region's robust food industry integrates circular economy principles into advanced carton designs.
Global Open Top Cartons Market Key Industry Players
Capacity expansion dominates the current landscape, driven by the increasing need for sustainable packaging solutions. The market exhibits a tiered structure, with large integrated producers alongside specialized regional players. Strategic archetypes include global packaging giants, virgin fiberboard specialists, and recycled content champions. Companies are pursuing both geographic expansion and portfolio diversification to capture new market opportunities and enhance their competitive positioning.
On the premium-tier vector, Mayr-Melnhof Karton AG, an Austrian company, exemplifies a focus on high-quality virgin fiberboard for demanding applications like cosmetic packaging. Smurfit Kappa, a global integrated producer, represents the scale-driven archetype, leveraging its extensive network of paper mills for consistent supply. International Paper, a major North American player, anchors the segment with its vast manufacturing scale and logistical reach, particularly for high-volume applications.
| Leading Market Players |
|---|
| Huhtamaki |
| Graphic Packaging International |
| Mayr-Melnhof Karton AG |
| Smurfit Kappa |
| International Paper |
| Amcor Plc |
| Mondi Group |
| Oliver Inc. |
| WestRock Company |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and private-equity-backed specialists shape the competitive dynamics of the open top cartons market, influencing both supply availability and pricing discipline.
Pricing Analysis
Retailer markup significantly influences the final price of open top cartons, particularly for shelf-ready fresh produce packaging. The dominant pricing model remains per-unit transactional, though long-term contract-based arrangements are common for large volume clients. Price differentiation stems from material quality, such as virgin versus recycled fiberboard, and the complexity of high-graphic printing. Input cost volatility, especially for recycled fiberboard, creates pricing pressure across all tiers. Food and beverage buyers exhibit moderate price sensitivity due to stringent safety and performance requirements, while consumer goods storage applications are more price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements from major brand owners mitigate risk in the open top cartons supply chain, ensuring material continuity. Supply concentration draws heavily from paperboard manufacturing hubs in North America, particularly the United States, and Europe, with Germany and France as key producers. Raw material dependencies center on virgin and recycled fiberboard, alongside specialized adhesives and inks. Commodity price volatility for pulp and wastepaper presents a structural risk. Distribution runs primarily through direct sales to large industrial clients and rapidly expanding online marketplaces for smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The open top cartons market functions as a regulatory compounder, with the EU's Packaging and Packaging Waste Regulation (PPWR) directly driving demand for sustainable, recyclable paperboard solutions.
For Market Incumbents:Anchor existing market share by investing in advanced material science R&D, focusing on lightweighting and enhanced moisture resistance for fresh produce. Capacity additions in key European and North American regions can counter the threat from returnable plastic crates (RPCs) in B2B logistics. Deepening vertical integration into recycled fiber collection and processing ensures consistent raw material supply. Pursue strategic partnerships with e-commerce giants to co-develop optimized packaging solutions.
For New Entrants and Emerging Players:Small-to-medium enterprises in emerging e-grocery markets represent an underserved buyer archetype, offering significant white-space opportunities. Focus on highly customizable, digitally printed cartons for premium and organic food brands in Southeast Asia and Latin America. Offering design consultation and low-volume production capabilities can be a penetrable go-to-market angle. Develop specialized anti-static inserts for the expanding small consumer appliance market.
For Investors and Strategic Acquirers:Integrated packaging solution providers are the most active acquirers in this space, seeking to consolidate capabilities and expand geographic reach. The market demonstrates long-term viability over the next decade, driven by regulatory tailwinds and e-commerce expansion. Target innovative startups specializing in sustainable material development or advanced digital printing technologies. A signal to watch is the accelerating adoption of mono-material paperboard designs by major food brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | To meet growing demand for sustainable packaging in the food and beverage sector. |
| Digital Printing Technology Investment | Enables customized, short-run campaigns for fresh produce brands in Germany. |
| Recycled Fiber Integration | Secures raw material supply and aligns with EU Green Deal objectives. |
| E-commerce Packaging R&D | Develops robust, shelf-ready designs for prepared meals and online grocery. |
| Compliance Certification (FDA/REACH) | Ensures market access and material safety for global food contact applications. |
Research Approach
Multiple input streams — primary interviews, secondary industry reports, and proprietary database analytics — were reconciled to construct a comprehensive market view. Primary engagement included packaging engineers, procurement managers from food and beverage companies, retail buyers, and material suppliers. Secondary sources comprised corporate filings, government publications from the US FDA and European Commission, and trade association data. Bottom-up aggregation and top-down validation ensured data integrity across all segments.
Data-stream reconciliation established the analytical framework for market projections across the analysis window. Segmentation dimensions modeled include material type, end-use application, manufacturing process, and distribution channel, alongside regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market drivers, including e-commerce penetration and plastic substitution rates. Input factors like pulp price forecasts and packaging machinery investment cycles informed the model.
Underlying measurement precision varies by segment; Food & Beverage Containers and Corrugated Fiberboard carry tighter precision than others due to more robust data availability. Forecasts reflect current macroeconomic assumptions and regulatory landscapes. Deviation in global trade policies or raw material supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Carton Bottle Market
Cartons
Brick Liquid Carton Market
Cartons
Shaped Corrugated Packaging Market
Cartons
Folding Cartons Market
Cartons
Luxury Folding Carton Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Carton Display Market
Cartons
Twist Opening Cartons Market
Cartons
Cartoning Machines Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
Braille Cartons Packaging Market
Cartons
Metallized PET Cartons Market
Cartons
Tetrahedron Carton Market
Cartons
Digital Folding Cartons Market
Cartons
Carton Sealer Machine Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market