
 Commodity Liners Market | 2026-2036
Commodity Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Commodity Liners Market Outlook
Multi-source procurement among waste management contractors is shifting toward integrated liner supply partnerships. Berry Global Inc. leverages its North American manufacturing footprint to anchor regional fulfillment networks. Solmax International Inc. sustains technology leadership in geomembrane-grade polyethylene formulations. Thrace Plastics Holding and Commercial S.A. competes through cost-optimized polypropylene production across Mediterranean markets.
Commodity liners are synthetic membrane barriers, typically extruded from polyethylene or polypropylene resins at thicknesses ranging from 0.5 to 3.0 millimeters, engineered to prevent fluid migration in containment applications. Polyethylene formulations dominate municipal landfill installations due to superior chemical resistance and weldability under field conditions. Polypropylene variants are gaining share in agricultural pond lining where flexibility across temperature cycles matters. PVC retains niche positioning in mining heap-leach pads where puncture resistance requirements are most severe.
The EPA enforces Subtitle D standards that mandate minimum 30-mil geomembrane thickness for municipal solid waste landfills, directly dictating material specifications and testing protocols. The EU Green Deal and REACH frameworks restrict phthalate plasticizers in PVC liners while promoting recyclability declarations across the value chain. Stakeholders must monitor evolving state-level liner performance certifications and assess how distributor channel consolidation affects project-level pricing transparency.
Market Dynamics
Landfill containment mandates from the EPA and EU Green Deal are compressing specification windows while resin cost volatility forces contractors toward multi-year supply agreements with integrated manufacturers.
Growth Catalysts
- Subtitle D geomembrane mandates:The EPA's 30-mil minimum thickness requirements for municipal solid waste landfills are accelerating specification upgrades across the United States waste management sector.
- Circular economy material declarations:EU Green Deal recyclability frameworks are creating procurement preference for liners with verified post-consumer content in German and French containment projects.
- Geomembrane-grade polyethylene advances:Enhanced chemical resistance formulations are extending service intervals in mining heap-leach applications, reducing total lifecycle replacement frequency.
Market Restraints
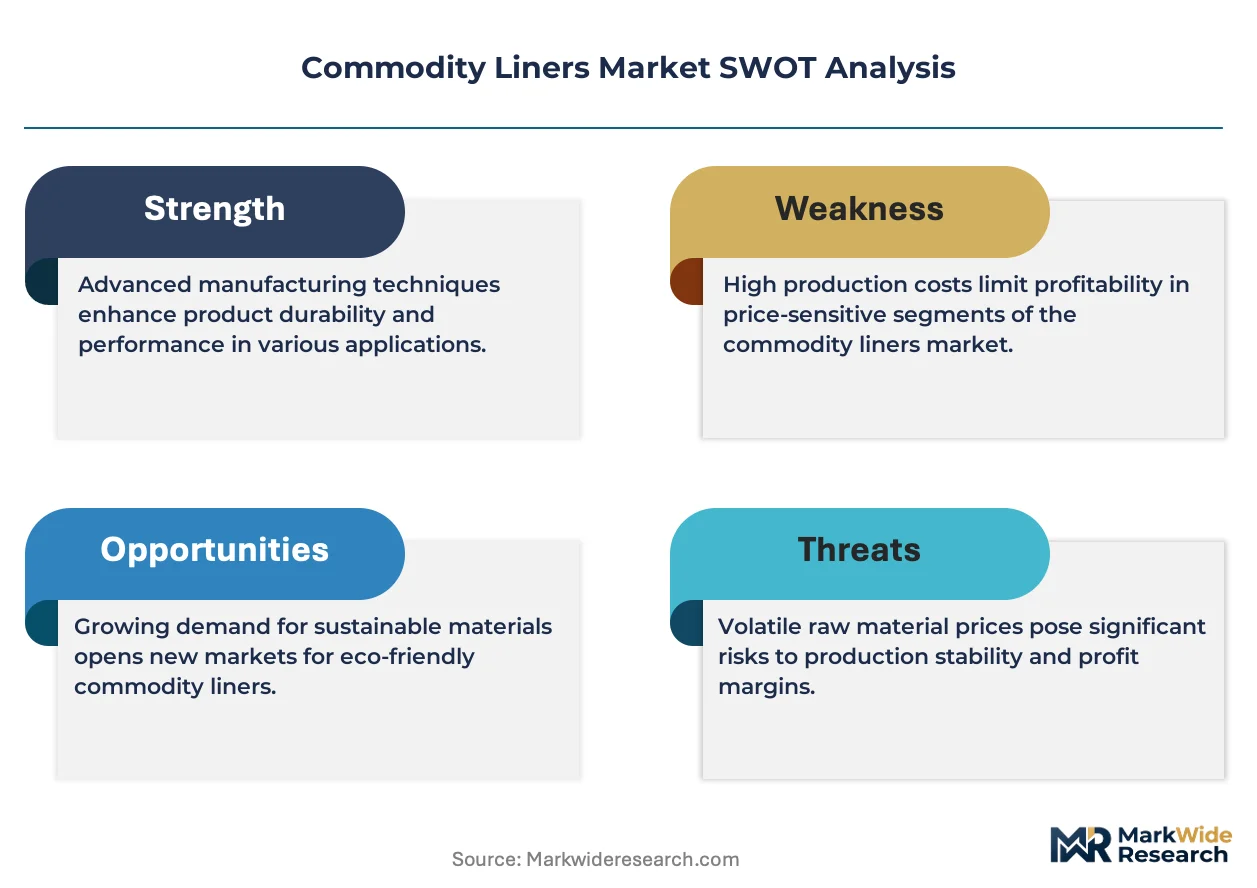
- Polyethylene resin cost volatility:Feedstock price swings tied to naphtha and natural gas liquids are compressing margin predictability for extrusion-dependent manufacturers.
- REACH phthalate restrictions:ECHA limitations on plasticizer chemistry in PVC formulations are forcing reformulation investments without immediate cost recovery mechanisms.
- Geographic supply concentration:North American geomembrane production clusters in the Gulf Coast corridor expose fulfillment networks to hurricane-disruption risk.
Strategic Opportunities
- Indian industrial wastewater containment:BIS standards adoption for chemical processing ponds is opening specification-grade demand as domestic manufacturing scales.
- Agricultural pond lining expansion:Polypropylene flexibility advantages in temperature-variable climates are penetrating irrigation districts across Spain and Italy.
- Integrated liner-service contracting:Waste management authorities in the United States are consolidating procurement toward single-source installation and material provision.
Industry Challenges
- Certified welding technician scarcity:Field seam integrity requirements under EPA testing protocols are outpacing qualified operator availability in remote project locations.
- Multi-jurisdictional compliance documentation:Contractors face fragmented state-level performance certifications that delay project mobilization across the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commodity Liners Market |
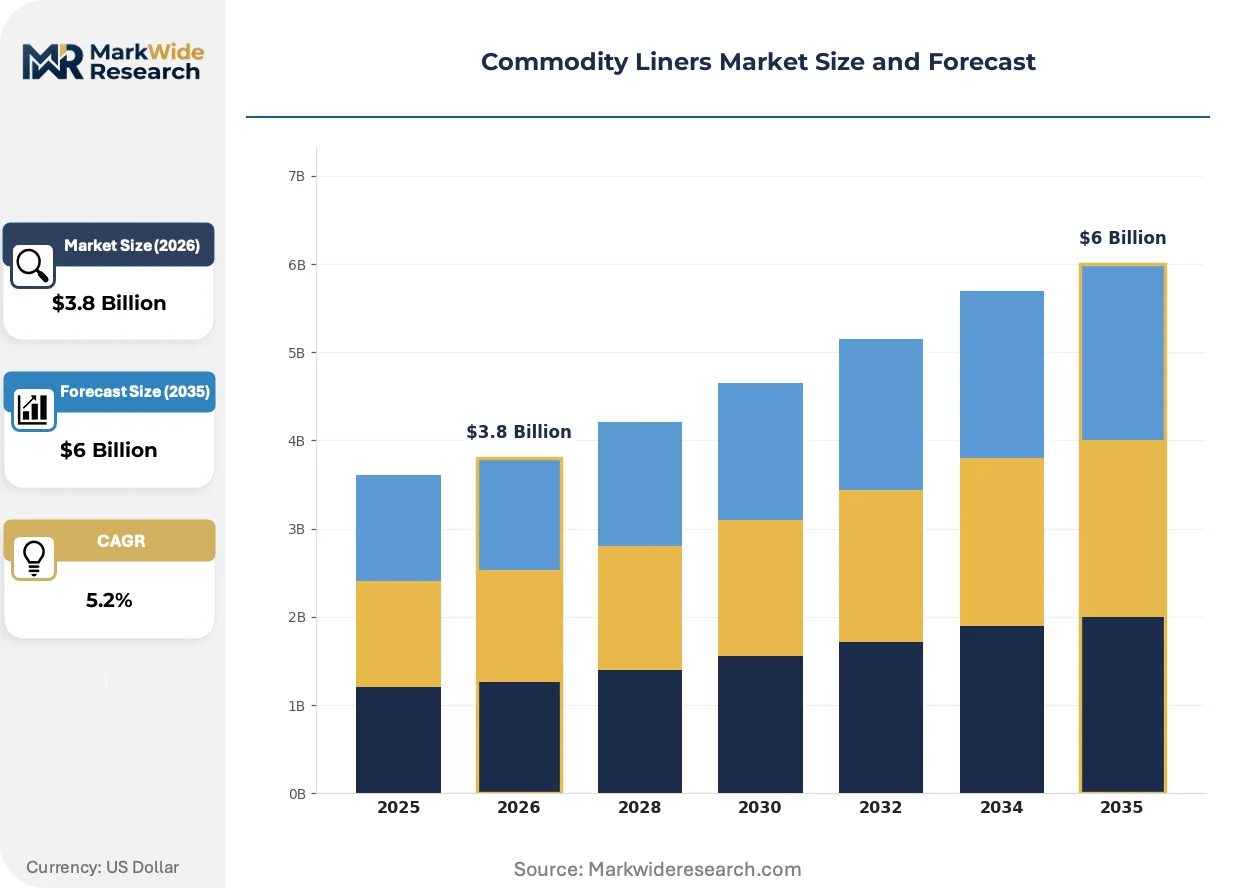
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Others Application: Waste Management, Agriculture, Mining, Construction End User: Municipalities, Commercial, Industrial, Residential Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Cesur Ambalaj Sanayi ve Ticaret A.S., Powertex Inc., Nier Systems Inc., Solmax International Inc., Rishi FIBC Solutions PVT. Ltd., Berry Global Inc., Emmbi Company, AGRU Kunststofftechnik GmbH, Thrace Plastics Holding and Commercial S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commodity Liners Market Strategic Shifts
Material science convergence with digital quality assurance is redefining how containment integrity gets specified, installed, and verified across landfill and industrial applications.
Co-extruded multilayer geomembranes are consolidating field welding protocols by integrating compatible skin layers that reduce thermal variation sensitivity during seam formation. Mining operators in Chile and Australia are specifying these constructions for heap-leach pads where automated deployment demands consistent weldability. The technology is consolidating formerly separate quality-control stages into continuous extrusion-line monitoring, compressing pre-shipment testing cycles.
REACH framework amendments on persistent organic pollutants are tightening acceptable additive chemistries in European liner formulations. Manufacturers serving German landfill operators must now document full material substance inventories through SCIP database entries. Agricultural pond segments face the steepest compliance burden as legacy PVC stocks phase out across Mediterranean markets.
Buyers are bundling liner procurement with installation and post-construction monitoring services under single-contractor accountability structures. United States municipal waste authorities favor this model for Subtitle D compliance projects where seam failure liability is concentrated. The shift compresses distributor margins while rewarding manufacturers with captive installation capabilities and certified field crews.
Commodity Liners Market Segmentation
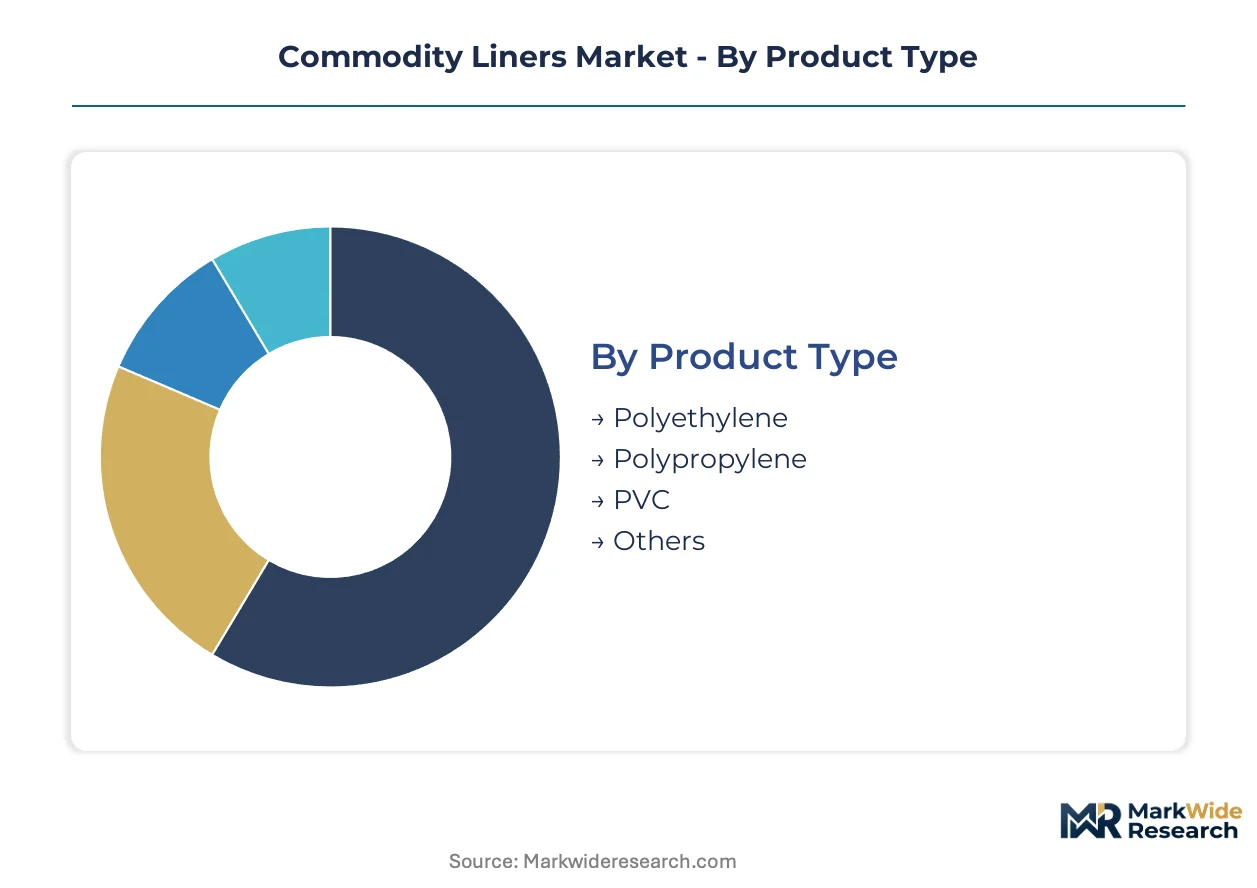
Commodity liner procurement decisions hinge on material performance against containment duty cycles, installation logistics, and regulatory compliance documentation. Segmentation reveals how specification-grade polyethylene commands municipal landfill budgets while flexible polypropylene penetrates temperature-variable agricultural applications. Understanding these splits enables manufacturers to align extrusion capacity with end-use certification requirements.
Product Type:
Polyethylene dominates volume flows through superior chemical resistance and weldability, while polypropylene captures premium positioning in flexibility-critical deployments.
- Polyethylene:Extruded high-density and linear low-density formulations provide the 30-mil minimum thickness mandated by EPA Subtitle D for municipal solid waste containment. German and French procurement authorities specify these geomembranes for landfill base and cap installations where seam integrity testing under field conditions is non-negotiable.
- Polypropylene:Co-polymer formulations deliver temperature-cycle flexibility spanning -40°C to 80°C operational windows without embrittlement. Irrigation districts across Spain and Italy specify these liners for agricultural pond applications where seasonal thermal expansion would compromise polyethylene alternatives.
- PVC:Plasticized formulations retain niche positioning in mining heap-leach pads where puncture resistance against angular ore stockpiles is paramount.
- Others:EPDM and bituminous composite liners serve specialized tunnel waterproofing and reservoir applications outside mainstream containment.
Today's leader: Polyethylene. Tomorrow's challenger: Polypropylene.
Application:
Waste management absorbs the majority of specification-grade volume, yet agricultural pond lining presents the steepest expansion trajectory as water security investments accelerate.
- Waste Management:Municipal landfill containment drives geomembrane procurement through EPA and EU Green Deal mandates for leachate isolation systems. United States waste authorities bundle liner supply with installation and post-construction monitoring under single-contractor accountability structures.
- Agriculture:Irrigation reservoir and anaerobic digester lining demand concentrates in Mediterranean climates where polypropylene flexibility advantages reduce thermal stress failure rates. Spanish agricultural cooperatives are scaling pond rehabilitation programs with specification-grade membrane deployments.
- Mining:Heap-leach pad and tailings containment in Chile and Australia specify co-extruded multilayer constructions for automated deployment compatibility.
- Construction:Tunnel waterproofing and foundation moisture barriers utilize modified bitumen and EPDM formulations outside standard geomembrane specifications.
Waste management anchors current procurement volumes. Agricultural water containment is climbing the fastest.
End User:
Municipal authorities concentrate demand through centralized procurement frameworks, while industrial generators seek captive containment solutions for process wastewater.
- Municipalities:Solid waste authorities in the United States, Germany, and China consolidate liner procurement under multi-year supply agreements with integrated manufacturers. Subtitle D compliance documentation requirements favor single-source accountability over fragmented distributor relationships.
- Commercial:Private waste management contractors serving metropolitan markets bundle liner deployment with collection and processing services.
- Industrial:Chemical processing and power generation facilities specify containment for process ponds and ash impoundments under site-specific environmental permits.
- Residential:Septic system and small-scale water feature applications represent minimal specification-grade demand.
Municipal procurement frameworks dominate contract value. Industrial self-containment is gaining share fastest.
Distribution Channel:
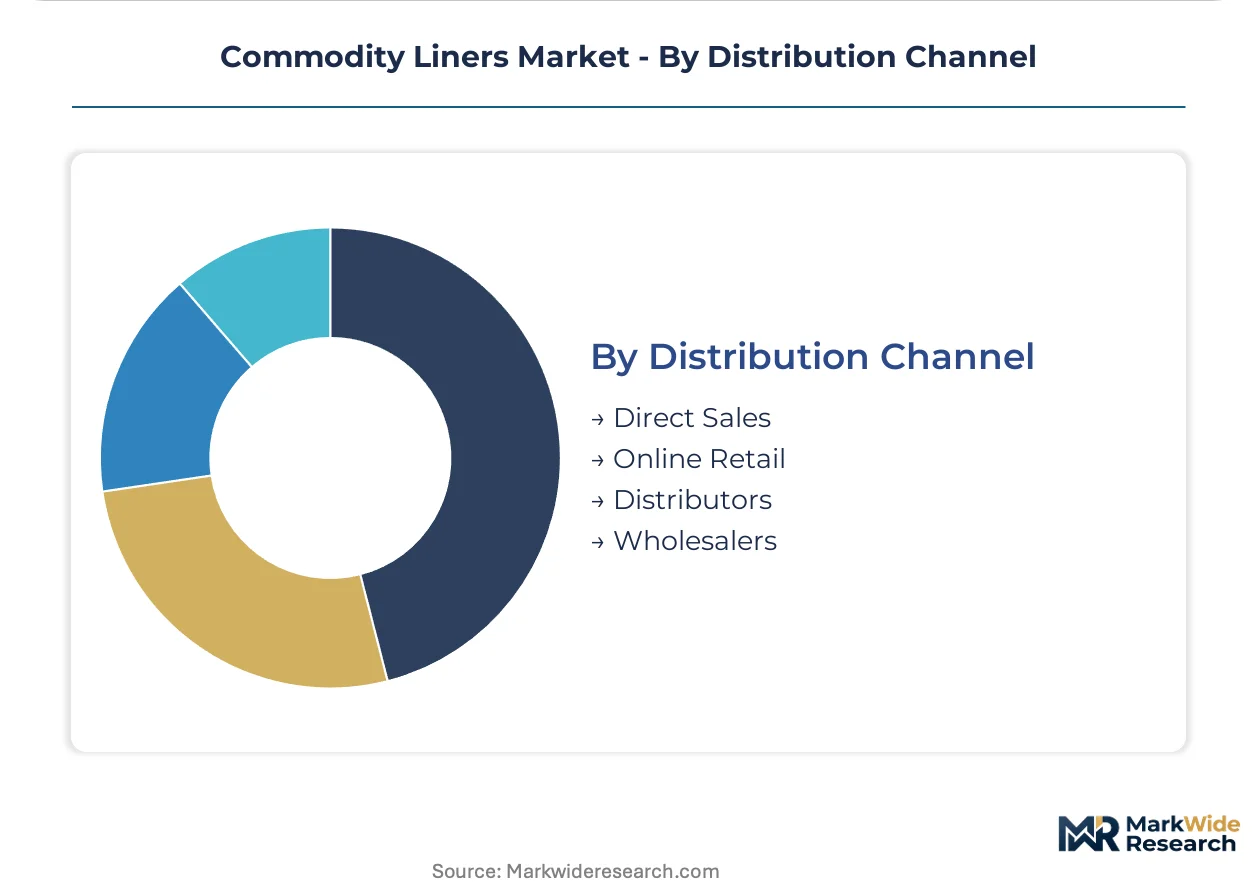
Direct manufacturer relationships are displacing distributor intermediaries as waste authorities consolidate toward integrated supply-installation contracting.
- Direct Sales:Berry Global and Solmax anchor regional fulfillment networks through captive field welding crews and certified installation capabilities. United States municipal authorities favor this channel for Subtitle D projects where seam failure liability concentration demands single-point accountability.
- Distributors:Regional stocking intermediaries serve contractor spot purchasing for agricultural and small-scale construction applications.
- Wholesalers:Volume aggregators supply commodity-grade polyethylene sheeting for non-critical moisture barrier applications.
- Online Retail:E-commerce channels capture minimal specification-grade volume, limited to residential and light commercial cut-to-size orders.
Direct sales channels command premium positioning. Distributor relevance is contracting fastest in municipal segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting geomembrane production toward jurisdictions with lower compliance costs, even as landfill containment mandates tighten specification requirements in mature markets.
United States
Municipal solid waste authorities in Texas and California are accelerating liner replacement cycles under EPA Subtitle D mandates for 30-mil minimum thickness. The EPA enforces rigorous seam integrity testing protocols that favor manufacturers with captive installation crews. Gulf Coast petrochemical corridors near Houston concentrate extrusion capacity, exposing supply chains to hurricane-season disruption risks.
Germany
Landfill operators in Bavaria and North Rhine-Westphalia are procuring liners with verified recyclability declarations under EU Green Deal circular economy frameworks. ECHA REACH restrictions on phthalate plasticizers are forcing PVC reformulation investments without immediate cost recovery. Industrial clusters around Düsseldorf and Munich anchor specification-grade polyethylene demand for containment infrastructure renewal.
China
Municipal waste management expansion in Jiangsu and Zhejiang provinces is absorbing domestic geomembrane production as MEE environmental enforcement tightens leachate isolation standards. The dual carbon goals are pressuring manufacturers toward lower-emission extrusion processes. Yangtze River Delta manufacturing zones are scaling co-extruded multilayer capacity for mining heap-leach exports to Chile and Australia.
India
Chemical processing facilities in Gujarat and Maharashtra are adopting BIS standards for industrial wastewater pond containment as domestic manufacturing scales. State pollution control boards are mandating liner specifications for effluent treatment infrastructure. Ahmedabad and Mumbai industrial corridors represent the steepest specification-grade demand expansion outside OECD markets.
Chile
Copper mining operations in the Atacama Desert are specifying co-extruded multilayer geomembranes for heap-leach pad automation compatibility. SERNAGEOMIN mining safety regulations are tightening tailings containment performance requirements. Antofagasta and Calama mining districts concentrate automated deployment demand for puncture-resistant liner constructions.
Commodity Liners Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue agricultural pond lining and industrial wastewater containment as specification-grade entry points. The market structures around three archetypes: integrated manufacturers with captive installation capabilities, regional extrusion specialists serving distributor channels, and mining-focused multilayer technology providers. Competitive moves concentrate on backward integration into resin compounding and strategic partnerships with waste management authorities for multi-year supply agreements.
Among North American integrated manufacturers, Berry Global Inc. anchors regional fulfillment networks through direct municipal contracting relationships. Solmax International Inc. exemplifies the technology-specialist archetype with geomembrane-grade polyethylene formulation leadership. Thrace Plastics Holding and Commercial S.A. represents Mediterranean-focused cost optimization through polypropylene production scale.
| Leading Market Players |
|---|
| Cesur Ambalaj Sanayi ve Ticaret A.S. |
| Powertex Inc. |
| Nier Systems Inc. |
| Solmax International Inc. |
| Rishi FIBC Solutions PVT. Ltd. |
| Berry Global Inc. |
| Emmbi Company |
| AGRU Kunststofftechnik GmbH |
| Thrace Plastics Holding and Commercial S.A. |
| Others |
Value Chain & Pricing Dynamics
Certified welding technician scarcity across the Gulf Coast corridor amplifies labor-cost differentials between premium specification-grade deployments and economy-tier agricultural applications. Municipal authorities absorbing seam-integrity liability premiums widen pricing spreads against distributor-sourced commodity polyethylene sheeting.
Pricing Analysis
Distributor margins compressing under direct-manufacturer contracting trends reshape pricing architecture across municipal landfill procurement. Project-based long-term offtake agreements dominate Subtitle D compliance work, with price differentiation hinging on certification grade and captive installation capabilities. Pricing pressure stems from polyethylene resin volatility tied to naphtha feedstock swings, forcing margin compression at the standard tier. Commercial waste contractors exhibit highest price sensitivity due to fragmented spot purchasing, while integrated manufacturers serving municipalities command premium positioning through liability bundling.
Supply Chain Analysis
Direct-to-municipality channels handle specification-grade geomembrane demand through captive field crews and certified welding capabilities. Geographic supply concentrates in the United States Gulf Coast, Germany's industrial clusters, and China's Yangtze River Delta manufacturing zones. Raw material dependencies rest on high-density polyethylene resin, linear low-density polyethylene formulations, and polypropylene co-polymers. Single-source vulnerability around Gulf Coast petrochemical corridors exposes fulfillment networks to hurricane-season disruption. Distribution runs through manufacturer-direct relationships for municipal segments, with regional distributors retaining relevance in agricultural spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as EPA Subtitle D mandates and EU Green Deal circular economy frameworks shift procurement preference toward verified performance documentation and post-consumer content declarations.
For Market Incumbents: Acquire certified welding technician training infrastructure to anchor seam-integrity accountability and defend against emerging entrants lacking field-crew capabilities. Deepen backward integration into geomembrane-grade resin compounding to offset polyethylene feedstock volatility compressing standard-tier margins. Consolidate multi-year supply agreements with United States municipal waste authorities before distributor channel fragmentation accelerates.
For New Entrants and Emerging Players: Capture agricultural pond lining expansion across Mediterranean irrigation districts where polypropylene flexibility specifications outpace incumbent polyethylene-focused capacity. Target Indian industrial wastewater containment as BIS standards adoption creates specification-grade entry points without established domestic competition. Pursue co-extruded multilayer technology partnerships with Chilean and Australian mining operators seeking automated deployment compatibility.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional extrusion specialists lacking captive installation capabilities and facing distributor margin compression. Long-term viability centers on manufacturers with demonstrated EPA and EU regulatory compliance documentation, integrated field service networks, and verified recyclability frameworks. Watch for REACH framework amendments on persistent organic pollutants as an inflection signal forcing reformulation investments and consolidation among PVC-dependent producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of geomembrane-grade polyethylene insulates margin against naphtha volatility. |
| Certified Installation Crew Expansion | EPA seam-integrity testing protocols reward manufacturers with qualified field welding technicians. |
| Co-extruded Multilayer Capacity Buildout | Chilean and Australian mining operators specify these constructions for automated heap-leach deployment. |
| Recyclability Declaration Investment | EU Green Deal SCIP database entries are becoming mandatory for German landfill procurement. |
| Multi-year Municipal Supply Agreements | United States waste authorities consolidate procurement toward single-source accountability structures. |
Study Parameters
Direct dialogue with geomembrane extrusion plant managers, municipal waste authority procurement directors, certified welding technicians, and distributor channel partners grounds qualitative assessment. Secondary validation draws from EPA Subtitle D regulatory filings, EU ECHA REACH substance inventory databases, customs and trade flow data for polyethylene resin imports, and SEC 10-K disclosures from integrated manufacturers. Bottom-up shipment analysis and top-down containment infrastructure investment tracking triangulate market sizing.
Bottom-up modeling aggregates extrusion capacity utilization, specification-grade shipment volumes, and project-level pricing bands across product type, application, and end-user segments. Top-down validation cross-references municipal landfill containment expenditure, mining heap-leach capital deployment, and agricultural water security investment flows. CAGRs derive from regression against regulatory mandate implementation timelines and resin cost trajectory scenarios. Forecast inputs include EPA enforcement intensity projections, EU circular economy framework adoption curves, and polyethylene feedstock spread assumptions.
Resin price volatility, regulatory enforcement delays, and certified technician availability constraints are the dominant revision risks to containment infrastructure deployment timelines. Forecasts reflect assumptions regarding mandate compliance schedules and substitution elasticity between material grades. Periodic stress-testing of base assumptions against actual procurement contract awards and seam-failure incident rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Clay Desiccant Bag Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Ventilated FIBC Market
Bags and Containers
Breather Bags Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Laser Scored Bags Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Carry Bag Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Pasted Valve Bags Market