
 Global Crash Lock Bottom Cartons Market | 2026-2036
Global Crash Lock Bottom Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crash Lock Bottom Cartons Market Intelligence
REACH is restructuring material sourcing protocols across European carton supply chains, pushing converters toward certified virgin and recycled fiber streams. Landor Cartons Limited leverages its British manufacturing footprint to anchor pharmaceutical-grade production with batch-traceable board certifications. Northwest Packaging competes through specialized food-service formats that sustain freezer-to-oven performance thresholds. Dodhia Packaging Ltd dominates South Asian export corridors with integrated kraft paperboard mills that control raw material quality from pulp to finished carton.
Crash lock bottom cartons are pre-glued, flat-shipped paperboard containers with interlocking base flanges that snap into position upon opening, typically manufactured from 250-400 gsm folding boxboard via die-cutting and cold-glue pre-assembly to eliminate manual bottom sealing in high-speed packaging environments. Recycled paperboard and kraft paperboard segments lead volume, though virgin paperboard commands the margin pool in pharmaceutical and electronics applications where dimensional stability under humidity stress determines line performance. Food and beverages end use represents the broadest adoption base, while personal care products generates premium pricing through matte-laminated, emboss-ready surface specifications.
FDA enforces carton structural integrity for over-the-counter drug distribution, while EPA guidelines on recycled content thresholds shape board mill output mixes in North America. The EU Green Deal and associated Packaging and Packaging Waste Regulation are forcing converters to document fiber provenance and recyclability pathways for retail channel access. Stakeholders must monitor how diverging national extended producer responsibility schemes recalibrate total cost of ownership calculations across multi-country supply contracts.
Market Dynamics
High-speed filling line automation across food and pharmaceutical manufacturing is compressing assembly time tolerances to sub-second thresholds, forcing carton suppliers to engineer dimensional precision that eliminates manual bottom-sealing interventions entirely.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates fiber-based substitution for plastic retail trays are redirecting frozen food brands toward crash lock formats that maintain structural integrity through cold-chain distribution.
- India's pharmaceutical export corridor:Temperature-sensitive biologics shipments to regulated markets require cartons with batch-traceable board certifications and humidity-stable dimensional performance.
- Automated carton erection systems:Pre-glued flat-ship designs integrate directly with robotic packaging lines, eliminating labor-intensive bottom-sealing stations in Brazilian beverage bottling plants.
Market Restraints
- Recycled fiber price volatility:Post-consumer paperboard supply fluctuations in European mill networks create input cost unpredictability for converters serving retail grocery channels.
- Virgin board supply concentration:Pharmaceutical-grade folding boxboard production clusters among Nordic and North American pulp suppliers, exposing buyers to single-source geographic risk.
- Dimensional stability limitations:Kraft paperboard hygroscopic expansion in tropical climates restricts crash lock carton deployment for humidity-sensitive electronics exports from South Asian assembly hubs.
Strategic Opportunities
- Brazilian beverage export infrastructure:Underdeveloped domestic carton converting capacity creates white space for pre-glued format suppliers capable of freezer-to-oven performance certification.
- EU Green Deal carbon accounting:Documented fiber provenance and recyclability pathway verification unlock premium channel access for converters with certified supply chain transparency.
- Smart packaging convergence:Integration of printed electronics and temperature-indicating inks with crash lock structures creates value-added formats for cold-chain biologics monitoring.
Industry Challenges
- Die-cutting precision engineering:Sub-millimeter flange tolerance requirements for reliable snap-lock performance demand specialized tooling expertise scarce in emerging market converter workforces.
- Multi-jurisdiction certification timelines:Pharmaceutical cartons require sequential FDA, EMA, and national regulator approvals that extend product launch cycles by 18-24 months.
- Cold-glue formulation compatibility:Adhesive systems must maintain bond strength across freezer-to-oven thermal cycling while meeting food-contact and pharmaceutical extractables standards simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crash Lock Bottom Cartons Market |
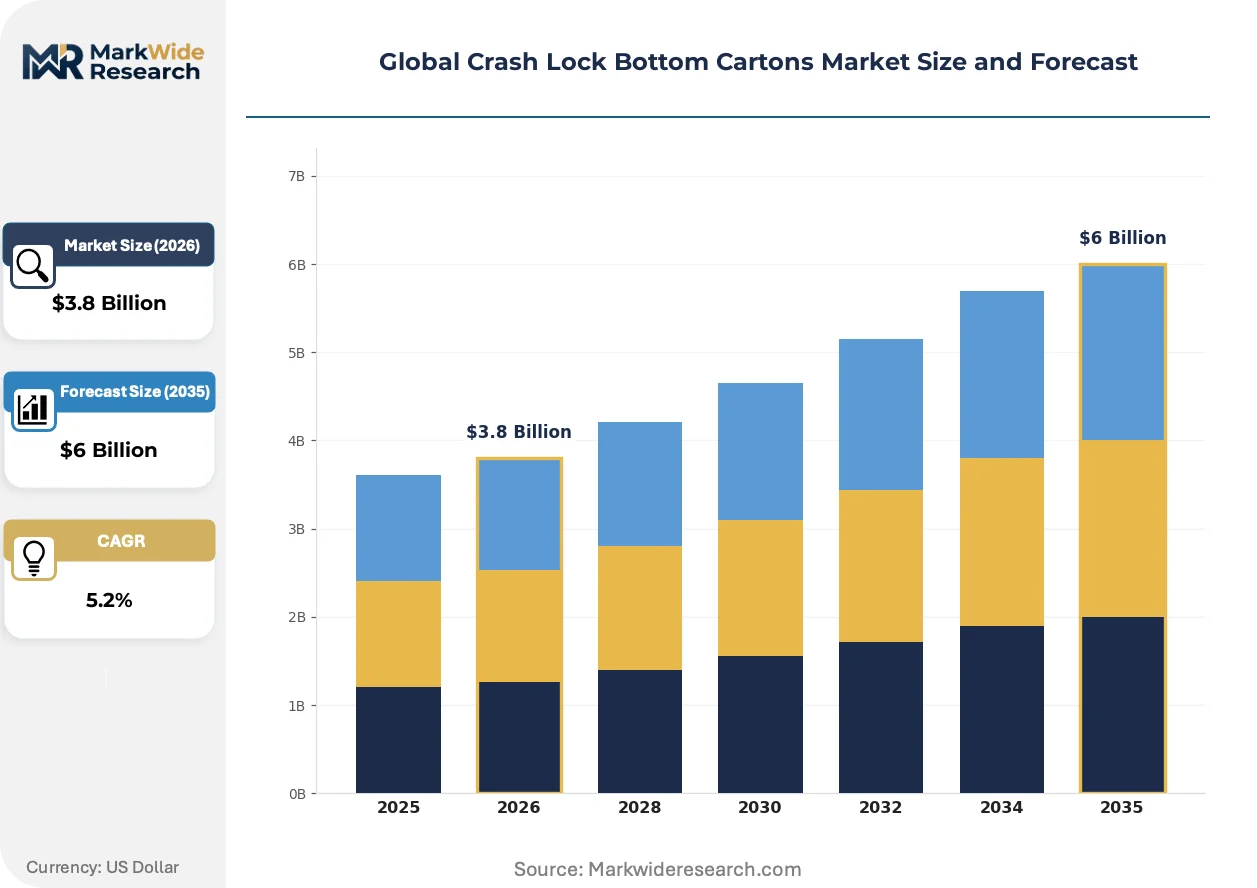
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Corrugated Board, Kraft Paperboard, Virgin Paperboard, Recycled Paperboard, Duplex Board End Use Industry: Consumer Durables, Electronics & Appliances, Food & Beverages, Personal Care Products, Pharmaceuticals Closure Type: Self-Locking, Tuck Flaps, Snap Lock, Adhesive Seal, Tape Seal Distribution Channel: Wholesale, Direct Sales, E-commerce, Retail Stores |
| Companies Covered | Landor Cartons Limited, Northwest Packaging, Dodhia Packaging Ltd, Atlas Packaging Ltd, Pringraf Cartotecnica, GWP Packaging, Jem Packaging, Aylesbury Box Company, Affinity Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crash Lock Bottom Cartons Market Strategic Shifts & Innovations
Material science advances and regulatory disclosure mandates are converging to redefine performance benchmarks and supply chain transparency requirements across carton manufacturing.
Water-based barrier coatings are unifying grease resistance and moisture protection within single-layer paperboard structures previously requiring plastic lamination. Frozen pizza and ready-meal brands in Germany and the United States are specifying these formats for direct-to-oven applications. The technology is unifying sustainability credentials with functional performance, compressing the competitive advantage of conventional polyethylene-coated alternatives.
REACH substance restriction protocols are forcing systematic reformulation of printing inks, adhesives, and surface treatments across European converting operations. Board mills must now document SVHC content and safe-use pathways for downstream pharmaceutical and food-contact applications. German and French retail channels are responding by requiring full material disclosure from carton suppliers as a condition of listing.
Consolidated procurement by multinational beverage and pharmaceutical groups is compressing supplier bases toward converters with integrated certification management and multi-site manufacturing footprints. Long-tail regional suppliers without batch-traceability systems are losing shelf access. This concentration is most visible in India's pharmaceutical export belt, where contract manufacturers now mandate single-source carton supply across their global production network.
Global Crash Lock Bottom Cartons Market Segmentation
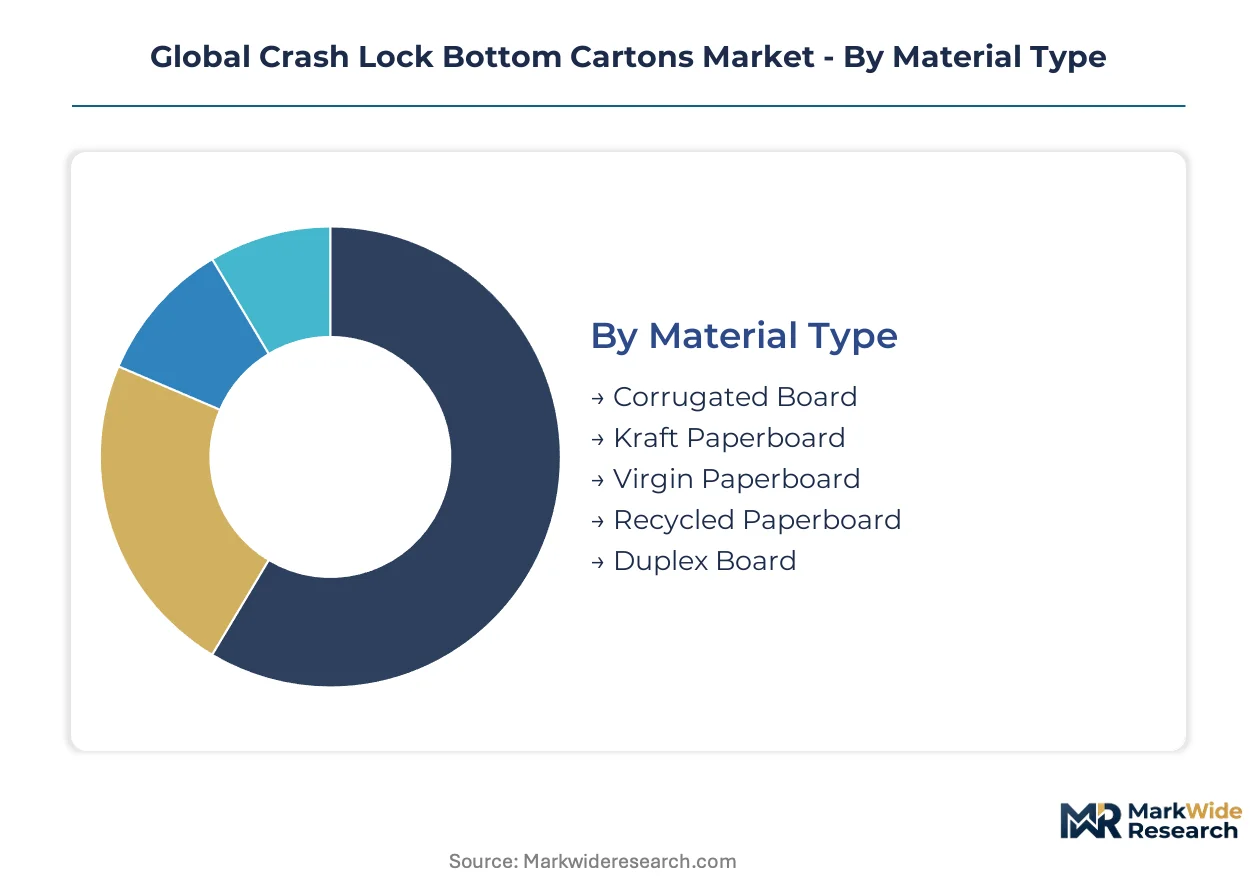
Crash lock bottom cartons serve divergent performance requirements across pharmaceutical cold chains, frozen food distribution, and electronics export corridors. Material selection and closure engineering determine line compatibility, humidity resilience, and regulatory compliance for each end-use environment.
Material Type:
Board composition governs dimensional stability, printability, and compliance pathways for regulated applications.
- Recycled Paperboard:Post-consumer fiber content meets EU Packaging and Packaging Waste Regulation thresholds for retail channel access. Frozen food brands in Germany specify these grades for freezer-to-oven applications where grease-resistant water-based barrier coatings replace polyethylene lamination.
- Virgin Paperboard:Pharmaceutical-grade folding boxboard from Nordic pulp suppliers delivers batch-traceable certifications required for temperature-sensitive biologics exports from India. Humidity-stable dimensional performance prevents snap-lock mechanism failure during monsoon-season distribution.
- Kraft Paperboard:Unbleached fiber structures from integrated South Asian mills control raw material quality from pulp to finished carton for cost-sensitive beverage applications.
- Corrugated Board:Double-wall constructions protect electronics assemblies during ocean freight from South Asian manufacturing hubs to European distribution centers.
- Duplex Board:Clay-coated white top surfaces enable high-resolution pharmaceutical labeling and tamper-evident printing for over-the-counter drug distribution.
Mature deployment sits with virgin paperboard. Newer deployment is concentrated in recycled paperboard.
End Use Industry:
Application environments dictate certification depth, closure precision, and thermal cycling tolerance.
- Food & Beverages:High-speed filling lines in Brazilian bottling plants demand pre-glued flat-ship designs that integrate with robotic carton erection systems. Water-based barrier coatings unify sustainability credentials with direct-to-oven functionality for frozen pizza and ready-meal brands.
- Pharmaceuticals:Temperature-sensitive biologics shipments require cartons with FDA and EMA structural integrity certifications. India's pharmaceutical export corridor mandates batch-traceable board provenance and humidity-stable performance for regulated market access.
- Personal Care Products:Matte-laminated emboss-ready surface specifications command premium pricing for cosmetic and skincare brands in French and German retail channels.
- Electronics & Appliances:Kraft paperboard hygroscopic expansion in tropical climates restricts deployment for humidity-sensitive exports from South Asian assembly hubs.
- Consumer Durables:Heavy-duty corrugated board constructions protect appliance components through multi-modal distribution networks.
Volume concentration centers on food and beverages. Margin expansion is steepest in pharmaceuticals.
Closure Type:
Locking mechanism engineering determines assembly speed, tamper evidence, and line automation compatibility.
- Snap Lock:Interlocking base flanges with sub-millimeter tolerance requirements demand specialized die-cutting tooling. German frozen food manufacturers specify these formats for reliable cold-chain structural integrity.
- Self-Locking:Pre-glued designs eliminate manual bottom-sealing interventions entirely on high-speed pharmaceutical filling lines in India's export corridor.
- Tuck Flaps:Manual closure formats persist in low-volume artisanal food packaging where equipment capital constraints limit automation adoption.
- Adhesive Seal:Cold-glue formulations must maintain bond strength across freezer-to-oven thermal cycling while meeting food-contact extractables standards.
- Tape Seal:Pressure-sensitive closure systems serve temporary or returnable logistics applications in electronics distribution.
Automated line integration favors snap lock. Manual assembly retention sits with tuck flaps.
Distribution Channel:
Channel structure determines order fragmentation, certification documentation requirements, and geographic reach.
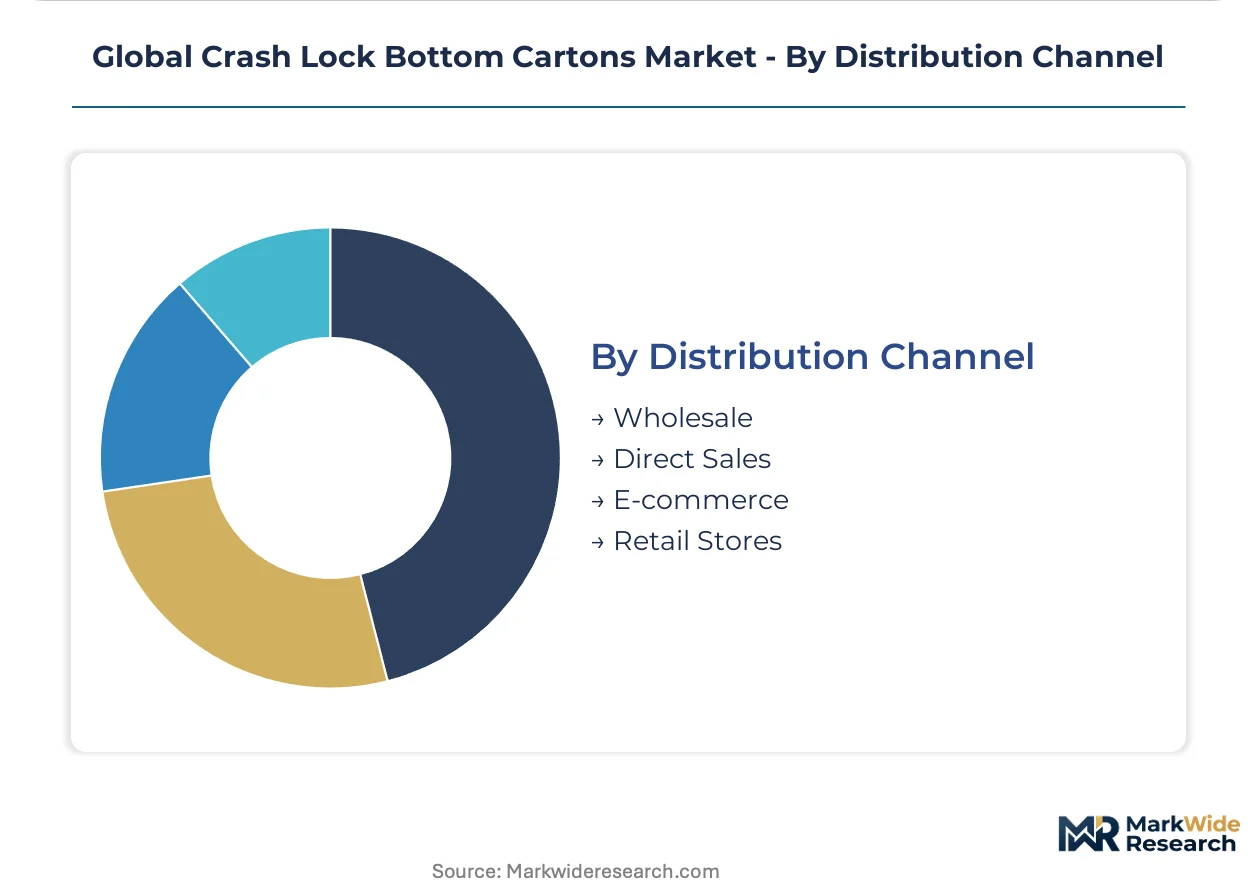
- Direct Sales:Multinational pharmaceutical and beverage groups consolidate procurement toward converters with integrated certification management and multi-site manufacturing footprints. Single-source supply mandates across global production networks favor direct relationships.
- Wholesale:Regional grocery and food-service distributors in Brazil source standardized formats from converters with flexible minimum order quantities.
- E-commerce:Direct-to-consumer frozen meal brands in the United States specify crash lock formats optimized for last-mile cold-chain integrity.
- Retail Stores:Private-label supermarket chains require full material disclosure and fiber provenance documentation as conditions of supplier listing under EU Green Deal transparency mandates.
Contract manufacturing concentration drives direct sales. Emerging brand fragmentation is expanding e-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate Indian pharmaceutical carton manufacturing with tax incentives for export-oriented production. These zones anchor South Asian supply capacity for temperature-sensitive biologics distribution to regulated markets.
United States
Frozen meal brands in the Midwest and Southeast specify water-based barrier coatings for direct-to-oven crash lock formats. FDA structural integrity requirements for over-the-counter drug distribution shape carton certification pathways. Chicago-area converting clusters serve both food-service and pharmaceutical channels with integrated batch-traceability systems.
Germany
EU Packaging and Packaging Waste Regulation mandates redirect frozen food brands toward fiber-based retail tray substitutions. REACH substance restriction protocols force systematic reformulation of printing inks and adhesives across converting operations. The Rhine-Ruhr industrial corridor hosts pharmaceutical-grade folding boxboard production with documented fiber provenance systems.
India
Temperature-sensitive biologics exports to regulated markets require humidity-stable dimensional performance during monsoon distribution. CDSCO alignment with FDA and EMA standards tightens carton integrity specifications for contract manufacturers. Gujarat's pharmaceutical export belt concentrates pre-glued format production with integrated kraft paperboard mills controlling pulp-to-finished-carton quality.
Brazil
Underdeveloped domestic carton converting capacity creates white space for pre-glued format suppliers with freezer-to-oven certification. ANVISA pharmaceutical packaging regulations align with international standards for temperature-controlled distribution. São Paulo-state beverage bottling plants deploy robotic carton erection systems eliminating manual bottom-sealing stations.
United Kingdom
Post-Brexit regulatory divergence complicates multi-jurisdiction certification timelines for pharmaceutical cartons requiring sequential approvals. British manufacturing footprints anchor pharmaceutical-grade production with batch-traceable board certifications. Midlands-based converters specialize in food-service formats sustaining thermal cycling performance thresholds.
Global Crash Lock Bottom Cartons Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across material grades and end-use certifications. The vendor base organizes into three tiers: integrated paperboard mills with captive pulp supply, regional converters with flexible minimum order quantities, and specialized pharmaceutical-grade fabricators with multi-regulator certification management. Two dominant competitive moves shape positioning: backward integration into kraft paperboard production to control raw material quality, and strategic partnerships with automated packaging line OEMs to secure high-speed filling line specifications.
Among British-based specialists, Landor Cartons Limited and Aylesbury Box Company occupy positions within the pharmaceutical-grade certification tier, while Dodhia Packaging Ltd exemplifies the integrated mill-converter archetype with upstream control over South Asian pulp supply. Northwest Packaging represents the regional food-service specialist segment with thermal performance format development.
| Leading Market Players |
|---|
| Landor Cartons Limited |
| Northwest Packaging |
| Dodhia Packaging Ltd |
| Atlas Packaging Ltd |
| Pringraf Cartotecnica |
| GWP Packaging |
| Jem Packaging |
| Aylesbury Box Company |
| Affinity Packaging |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between pharmaceutical and food-service tiers manifests in dual supply chain configurations: batch-traceable virgin board commands 40-60 day lead time premiums from Nordic pulp suppliers, while commodity recycled grades flow through spot-market purchasing from European mill networks. This bifurcation concentrates pricing power upstream with integrated pulp-to-carton producers and downstream with multinational buyers consolidating procurement toward single-source global contracts.
Pricing Analysis
Lead time compression drives tiered pricing: pharmaceutical buyers pay premiums for sub-30-day delivery of FDA-certified virgin board, while frozen food brands capture discounts on spot inventory of recycled grades with flexible specification tolerances. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade certifications from food-service thermal performance from commodity beverage formats. Cost compression in recycled fiber tiers is intensifying because post-consumer supply fluctuations in European mill networks create input unpredictability. Contract manufacturers in India's pharmaceutical export corridor demonstrate least price sensitivity due to regulatory compliance mandates, while Brazilian beverage bottlers exhibit highest sensitivity as they scale automated line investments.
Supply Chain Analysis
Regional distribution centers in Germany, India, and Brazil anchor hub-and-spoke patterns that position finished cartons within 48-hour delivery windows of high-speed filling lines. Raw material sourcing draws from Nordic pulp suppliers for pharmaceutical-grade virgin board, integrated South Asian kraft mills for beverage applications, and European recycled fiber networks for frozen food retail channels. Single-source vulnerability concentrates in pharmaceutical-grade folding boxboard production clustered among Nordic suppliers, exposing buyers to geographic risk. Distribution runs through direct sales relationships with multinational pharmaceutical and beverage groups, supplemented by wholesale channels serving regional Brazilian food-service distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EU Green Deal transparency mandates and batch-traceability requirements force sub-scale converters without certification management systems out of retail and pharmaceutical channels.
For Market Incumbents: Anticipate margin compression from automated packaging line OEMs capturing specification-setting power through direct partnerships with Brazilian and Indian bottlers. Defend position by deepening backward integration into kraft paperboard production to control pulp-to-finished-carton quality, and by securing multi-site manufacturing footprints that satisfy multinational pharmaceutical groups' single-source supply mandates across global production networks. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Brazilian beverage export infrastructure creates white space for pre-glued format suppliers capable of freezer-to-oven performance certification. Target underdeveloped domestic converting capacity in São Paulo-state bottling corridors where robotic carton erection systems eliminate manual bottom-sealing stations. Enter through specialized thermal cycling format development that ANVISA regulations now require for temperature-controlled distribution. For Investors and Strategic Acquirers: Re-rating potential sits with integrated mill-converter archetypes given EU Packaging and Packaging Waste Regulation acceleration of fiber-based plastic substitutions. Long-term viability favors upstream-controlled players with captive pulp supply and documented fiber provenance systems. Watch CDSCO-FDA-EMA alignment timelines as the inflection signal: sequential approval compression from 18-24 months to 12-15 months would unlock acquisition premiums for certification-ready targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Paperboard | Captive pulp supply from South Asian mills insulates converters from post-consumer fiber price volatility in European networks. |
| Multi-Regulator Certification Investment | Simultaneous FDA, EMA, and CDSCO approvals compress pharmaceutical product launch cycles and lock out sub-scale competitors. |
| Automated Line OEM Partnership | Specification-setting power with Brazilian robotic packaging lines secures volume commitments from high-speed beverage bottlers. |
| Water-Based Barrier Coating Scale-Up | German frozen food brands specify direct-to-oven formats that replace polyethylene lamination under EU Green Deal mandates. |
| Smart Packaging Convergence | Printed electronics integration with crash lock structures creates value-added cold-chain monitoring for Indian biologics exports. |
Research Approach
Document review covered customs and trade data, EU regulatory filings, and pharmaceutical packaging standards databases, complemented by interviews with carton converting plant managers, procurement leads at multinational beverage groups, regulatory affairs specialists at Indian contract manufacturers, and distribution channel partners across European retail networks. Secondary validation drew from FDA structural integrity guidelines, EMA packaging material submissions, CDSCO alignment documentation, and SEC filings of integrated paperboard producers. Bottom-up volume estimates from individual facility capacities were triangulated against top-down demand projections from end-use industry consumption patterns.
Cross-referencing historical capacity expansion timelines against expert panel input on automation adoption rates shaped the analytical framework across the analysis window. Segmentation dimensions modeled included material type, end-use industry, closure mechanism, and geographic regulatory cluster. CAGRs were derived from compound growth trajectory analysis applied to verified baseline consumption figures. Industry-specific forecast inputs incorporated high-speed filling line installation rates at Brazilian beverage plants and humidity-stable dimensional performance requirements for Indian monsoon distribution.
Inputs from regulatory filing databases and primary field interviews were available through the study window; gaps in real-time capacity utilization data from private mill operations introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented parameter sets including EU Packaging and Packaging Waste Regulation implementation timelines and CDSCO certification alignment progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Digital Folding Cartons Market
Cartons
Africa Folding Carton Market
Cartons
Soap Boxes Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Brick Carton Packaging Market
Cartons
Metallized Folding Cartons Market
Cartons
Carton Bottle Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Carton Sealer Machine Market
Cartons
Shaped Liquid Cartons Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Cardboard Crates Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Global Cartonboard Market
Cartons
Box and Carton Overwrapping Machines Market