
 Brick Liquid Carton Market | 2026-2036
Brick Liquid Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Brick Liquid Carton Market Outlook
The gap between premium aseptic brick liquid cartons and commodity gable-top formats is expanding as brand owners demand extended shelf-life performance without cold-chain dependency. Tetra Pak International S.A. leverages its integrated filling-machine ecosystem to lock in dairy and beverage converters across emerging markets. SIG Combibloc competes through standardized blank dimensions that reduce converter tooling costs. Elopak anchors its position in fresh milk segments where shorter shelf-life tolerances favor its Pure-Pak profile.
Brick liquid cartons are rectangular aseptic packages formed from multi-layer paperboard substrates, typically incorporating aluminum foil barriers and polyethylene sealing layers, designed to preserve liquid food products without refrigeration for six to twelve months. The format serves industrial-scale dairy, juice, and broth distribution where thermal stability and square-stack efficiency outweigh cylindrical can or bottle alternatives. Paperboard material dominates unit economics across the category, though laminated cardboard variants are gaining traction in premium organic lines where matte print finishes command shelf attention. Milk cartons represent the mature volume base, while sauce packaging applications are expanding fastest as ready-meal brands adopt single-serve brick portions for e-commerce meal kits.
The EU Green Deal and REACH frameworks are mandating fiber-based recovery rates that favor paperboard-dominant brick formats over plastic bottles in European retail channels. The FDA's food-contact substance notifications shape aluminum foil barrier specifications for U.S. dairy exports, while China's GB standards enforce domestic recyclability labeling that influences laminate layer thickness decisions. Stakeholders must monitor how extended producer responsibility schemes in Germany and France reallocate collection infrastructure costs between converters and brand owners.
Market Dynamics
EU Green Deal recyclability mandates are compressing laminate layer specifications and forcing converters to requalify aluminum foil alternatives across European dairy supply chains.
Growth Catalysts
- ASEPTIC Shelf-Life Extension:Dairy processors in Vietnam and Indonesia are abandoning cold-chain-dependent gable-top formats for brick cartons that eliminate refrigeration through ultra-high-temperature processing and multi-layer barrier construction.
- REACH Framework Compliance:European converters are capturing shelf space as retailers delist non-recyclable plastic bottles ahead of extended producer responsibility deadlines in Germany and France.
- E-Commerce Meal Kit Expansion:Ready-meal brands are specifying single-serve brick portions for sauce and broth applications where square-stack density reduces last-mile shipping costs.
Market Restraints
- Aluminum Foil Price Volatility:Barrier layer input costs fluctuate with London Metal Exchange pricing, squeezing converter margins when brand owners lock in twelve-month supply contracts.
- Filling Machine Ecosystem Lock-In:Dairy processors face switching costs when incumbent equipment vendors control spare parts availability and technical service networks across Southeast Asian manufacturing clusters.
- Polyethylene Sealing Layer Limitations:Current hot-melt adhesive specifications restrict line speeds below 24,000 packs per hour, capping throughput for high-volume beverage operations.
Strategic Opportunities
- Indonesia Domestic Consumption Surge:Per-capita liquid food consumption growth in secondary cities is outpacing cold-chain infrastructure buildout, creating pull for ambient-stable packaging formats.
- Fiber-Based Barrier Innovation:Convergence of nanocellulose coatings and bio-based polymers is opening pathways to eliminate aluminum foil while maintaining oxygen transmission rate specifications.
- China GB Standards Alignment:Domestic recyclability labeling mandates are creating first-mover advantage for converters who pre-certify laminate structures ahead of enforcement timelines.
Industry Challenges
- Multi-Layer Separation Infrastructure:Municipal recycling facilities lack hydropulping capacity to isolate paperboard from polyethylene and aluminum fractions, creating collection cost allocation disputes between brand owners and waste management operators.
- Print Registration Tolerance Tightening:Matte finish demand from organic lines requires gravure cylinder investments that strain mid-tier converter capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brick Liquid Carton Market |
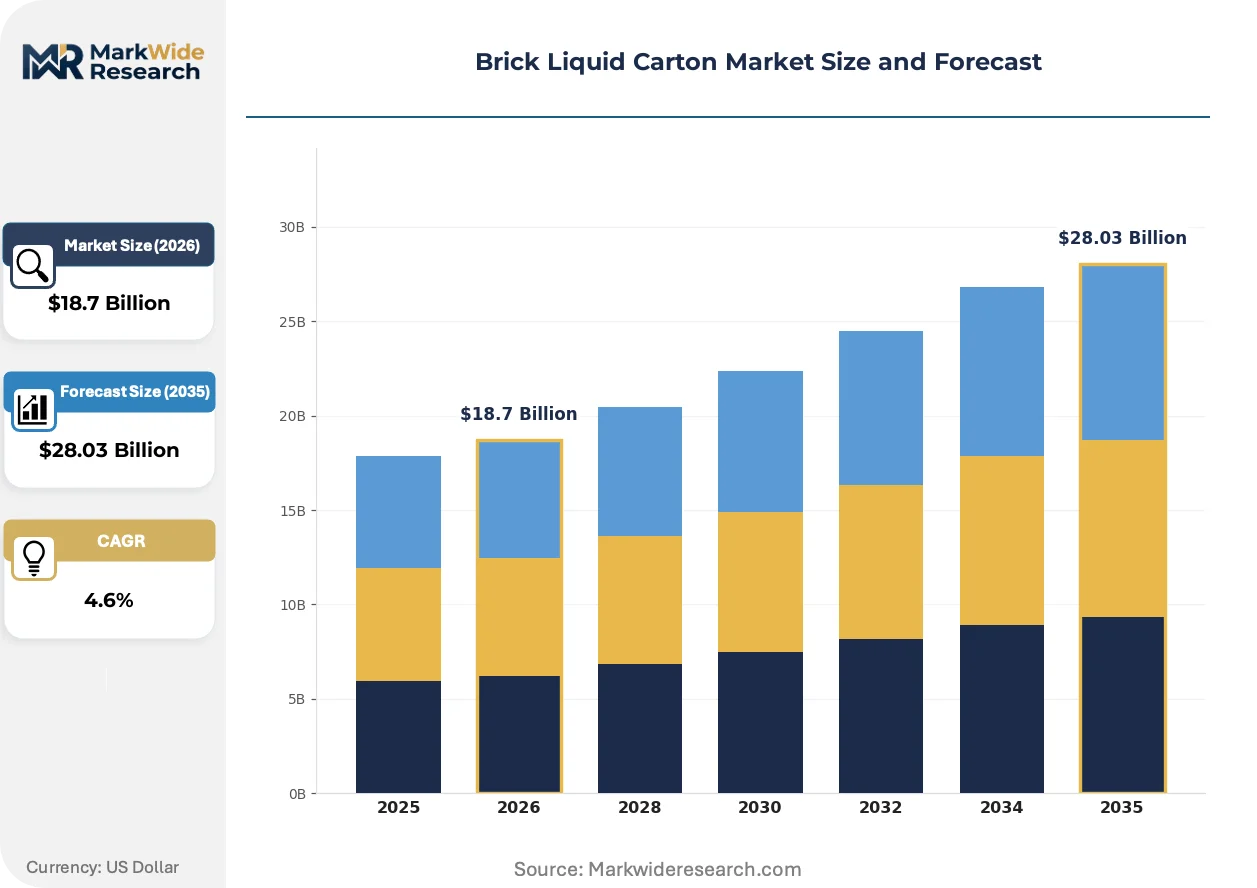
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juice Cartons, Milk Cartons, Soup Containers, Sauce Packagings Material: Paperboard, Laminated Cardboard, Plastics, Aluminum Foil End User: Retailers, Food Service Providers, School Canteens, E-commerce Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesale Distributors |
| Companies Covered | Tetra Pak International S.A., SIG Combibloc, Elopak, Greatview Aseptic Packaging, Evergreen Packaging, Nippon Paper Industries, International Paper, Mondi Group, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brick Liquid Carton Market Strategic Shifts
Material science breakthroughs and regulatory compliance deadlines are compressing traditional laminate architectures while opening alternative barrier pathways.
Polymer-grade nanocellulose coatings are rewriting oxygen barrier economics for premium organic lines. Specialty dairy brands in Nordic markets are piloting aluminum-free structures at commercial scale. The technology is compressing the cost gap between conventional multi-layer cartons and next-generation fiber-dominant alternatives.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing adhesive reformulation across European converter operations. Industrial consequence includes twelve-to-eighteen-month requalification timelines for food-contact substance notifications. Dairy exporters to the United States are most affected, with FDA notification backlogs extending launch schedules for modified sealing layer specifications.
Brand owner specification consolidation is compressing supplier diversity as procurement teams centralize carton sourcing under corporate sustainability scorecards. Regional dairy cooperatives are displacing fragmented local converters through direct tendering relationships with multinational filling-machine vendors. This pattern is most visible in Vietnam, where domestic processors are bypassing traditional distributor networks to secure volume commitments with integrated packaging system providers.
Brick Liquid Carton Market Segmentation
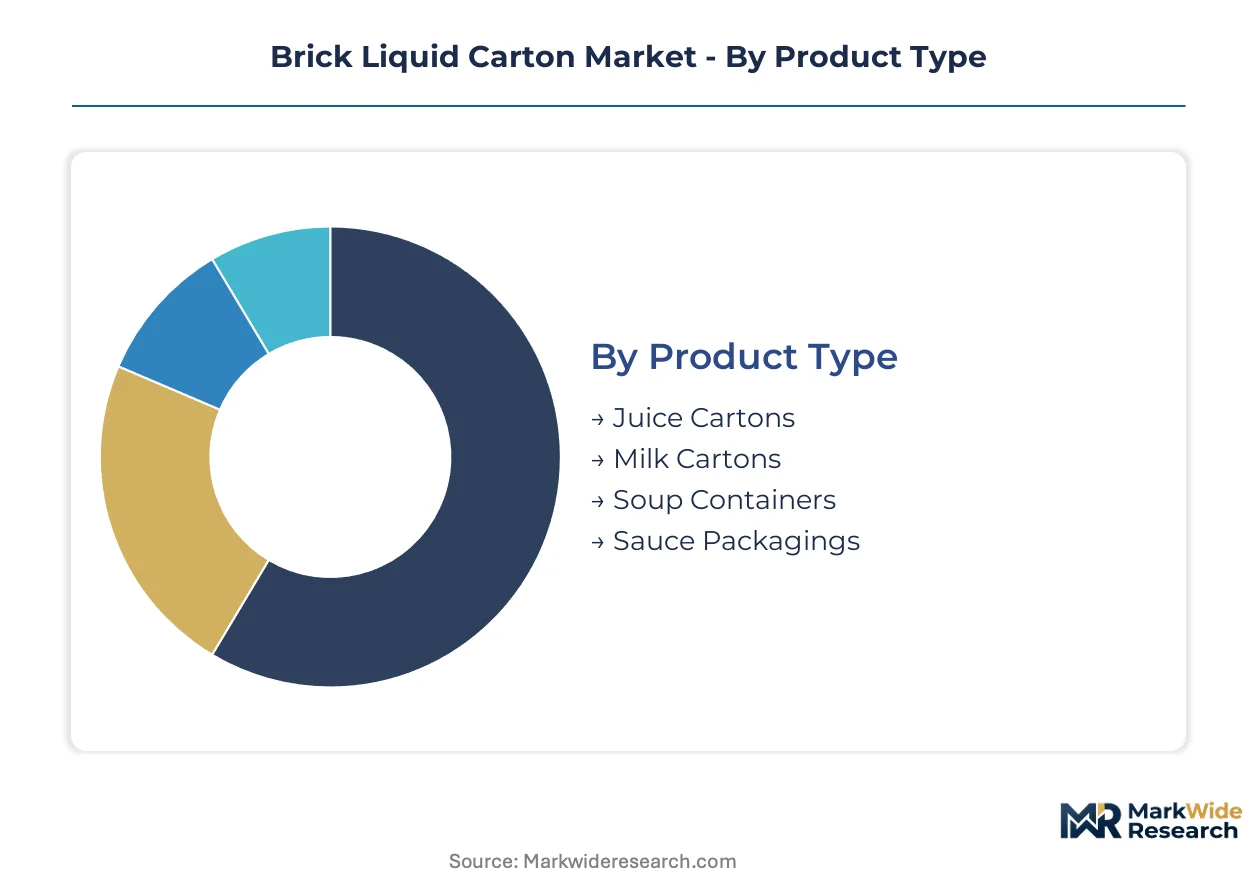
Segmentation in brick liquid cartons reveals how material choices and channel configurations determine margin structures. Dairy processors prioritize shelf-life performance while e-commerce channels demand stack-optimized formats.
Product Type:
Standalone beverage packaging dominates volume, while embedded meal-kit components represent the integration frontier.
- Juice Cartons:Aseptic multi-layer structures with aluminum foil barriers preserve vitamin stability for six-to-twelve-month ambient distribution. Demand concentrates in Southeast Asian retail chains where tropical climates degrade cold-chain infrastructure.
- Milk Cartons:Ultra-high-temperature processed dairy fills represent the mature volume base, with square-stack geometry optimizing pallet utilization for long-haul distribution. Vietnamese and Indonesian processors are converting gable-top lines to brick formats at scale.
- Soup Containers:Single-serve portions for ready-meal brands.
- Sauce Packagings:E-commerce meal-kit specifications driving fastest expansion.
Milk cartons lead volumes today; sauce packagings are gaining share fastest.
Material:
Cost tiers separate fiber-dominant substrates from barrier-intensive laminates, with premium organic lines commanding matte-finish premiums.
- Paperboard:Dominates unit economics across the category, typically 70-80% of laminate mass. EU Green Deal recyclability mandates favor this substrate over plastic bottle alternatives in German and French retail channels.
- Laminated Cardboard:Premium organic lines specify these variants where gravure-printed matte finishes command shelf attention. Nordic dairy brands are piloting aluminum-free nanocellulose-coated structures at commercial scale.
- Plastics:Polyethylene sealing layers restrict line speeds below 24,000 packs per hour.
- Aluminum Foil:Barrier layer input costs fluctuate with London Metal Exchange pricing.
Paperboard leads volumes today; laminated cardboard is gaining share fastest.
End User:
Customer type determines order frequency and specification complexity, with institutional buyers prioritizing cost stability over print customization.
- Retailers:Centralized procurement teams specify corporate sustainability scorecards, consolidating supplier relationships under volume commitments. Extended producer responsibility schemes in Germany and France reallocate collection infrastructure costs.
- Food Service Providers:Bulk-format brick cartons for institutional kitchens where thermal stability and square-stack efficiency reduce storage footprint.
- School Canteens:Government tender specifications favor lowest-unit-cost formats.
- E-commerce:Single-serve sauce and broth portions where stack density reduces last-mile shipping costs.
Retailers lead volumes today; e-commerce is gaining share fastest.
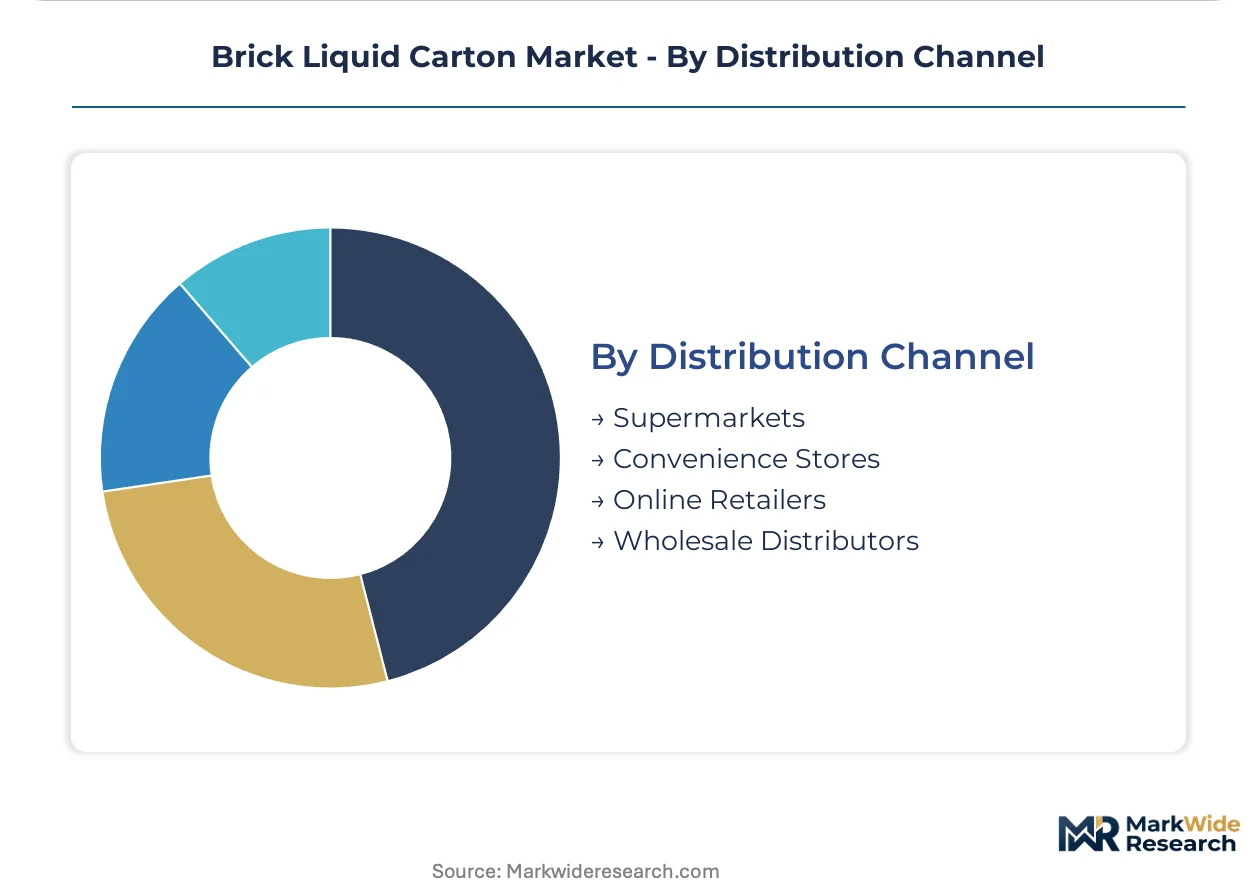
Distribution Channel:
Volume concentration versus margin capture splits between high-throughput retail and specialized wholesale networks.
- Supermarkets:Shelf-space competition drives gravure cylinder investments for matte-finish organic lines. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force twelve-to-eighteen-month adhesive requalification timelines.
- Convenience Stores:Smaller-format brick cartons for grab-and-go consumption in Vietnamese and Indonesian urban centers.
- Online Retailers:Direct-to-consumer shipment specifications favor crush-resistant corner geometries.
- Wholesale Distributors:Pallet-load consolidation for dairy cooperatives bypassing fragmented local converter networks.
Supermarkets lead volumes today; online retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter engineering talent clusters in German industrial regions and Vietnamese manufacturing zones anchor the geographic footprint. Dairy processors in Southeast Asia and beverage brands in Western Europe drive divergent specification demands. Regulatory frameworks in China and Indonesia reshape laminate qualification timelines.
Germany
Dairy cooperatives in Bavaria and North Rhine-Westphalia specify extended shelf-life formats for export markets. Extended producer responsibility schemes under the EU Green Deal reallocate collection infrastructure costs between brand owners and waste operators. Converter engineering clusters around Stuttgart and Hamburg drive barrier layer requalification for aluminum foil alternatives.
China
Domestic liquid food consumption in secondary cities outpaces cold-chain infrastructure expansion. GB standards enforce recyclability labeling that influences laminate layer thickness decisions across converter operations. Yangtze River Delta packaging hubs near Shanghai pre-certify structures ahead of enforcement timelines to capture first-mover positioning.
Vietnam
Per-capita dairy consumption growth in Ho Chi Minh City and Hanoi accelerates format conversion from gable-top to aseptic brick. Domestic processors bypass traditional distributor networks to secure direct tendering relationships with multinational filling-machine vendors. Southern manufacturing clusters absorb technical service networks from incumbent equipment providers.
Indonesia
Urban liquid food demand in Jakarta and Surabaya exceeds refrigerated distribution reach. National regulators align domestic labeling mandates with ASEAN harmonization frameworks. Javanese converter facilities scale blank production to serve emerging dairy brands in secondary cities.
United States
Organic dairy brands in California and Wisconsin specify matte-finish laminated cardboard for premium shelf positioning. FDA food-contact substance notifications shape aluminum foil barrier specifications for export-oriented processors. Midwestern dairy cooperatives consolidate procurement under corporate sustainability scorecards.
Brick Liquid Carton Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the brick liquid carton value chain. Integrated filling-machine vendors lock in dairy processors through spare parts and technical service networks. Three archetypes dominate: system-integrated multinationals, standardized blank specialists, and regional paperboard converters. Competitive moves concentrate on strategic partnerships with filling equipment providers and geographic expansion into Southeast Asian manufacturing clusters.
Among system-integrated multinationals, Tetra Pak International S.A. and SIG Combibloc occupy positions defined by filling-machine ecosystem control. Tetra Pak exemplifies the integrated archetype through its captive machinery and packaging combination. SIG Combibloc represents the standardization-focused tier with interchangeable blank dimensions. Elopak anchors the fresh milk specialist segment where shorter shelf-life tolerances favor distinct format profiles. These three names illustrate how competitive positioning separates ecosystem lock-in from modular flexibility.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| SIG Combibloc |
| Elopak |
| Greatview Aseptic Packaging |
| Evergreen Packaging |
| Nippon Paper Industries |
| International Paper |
| Mondi Group |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
Captive filling-machine ecosystems at Tetra Pak and SIG Combibloc anchor both supply positioning and pricing power across Southeast Asian dairy clusters. Brand owners purchasing integrated machinery-packaging bundles face switching costs that compress price elasticity for converters supplying compatible blanks.
Pricing Analysis
Bundled machinery-service contracts dominate premium tiers while unbundled blank-only supply serves mid-market dairy cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates integrated system providers from standardized blank specialists and regional converters. Pricing pressure stems from aluminum foil volatility on the London Metal Exchange squeezing converter margins. Food service providers exhibit highest price sensitivity; organic dairy brands show lowest sensitivity due to sustainability scorecard mandates.
Supply Chain Analysis
GB standards certification and FDA food-contact substance notifications gate entry for converters serving export-oriented dairy processors. Paperboard supply concentrates in Germany, China, and Indonesia; aluminum foil barrier layers draw from South Korean and Japanese metallurgy suppliers. Single-source vulnerability runs through Tetra Pak's captive spare parts networks in Vietnamese manufacturing clusters. Distribution runs through multinational filling-machine vendors' technical service networks rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's extended producer responsibility schemes impose collection infrastructure costs on European brand owners that Indonesian and Vietnamese processors avoid, creating a regulatory cost arbitrage favoring Southeast Asian manufacturing expansion.
For Market Incumbents: Lock in dairy processors through long-term spare parts contracts and technical service exclusivity in Ho Chi Minh City and Jakarta manufacturing zones. Aluminum foil price hedging and nanocellulose barrier R&D investment counter emerging fiber-based substitutes from Nordic pilot programs. For New Entrants and Emerging Players: EU Green Deal recyclability mandates in Germany and France open a window for aluminum-free laminate structures targeting organic dairy lines. White-space exists in Indonesian secondary cities where cold-chain gaps favor ambient-stable formats; enter through direct tendering relationships with domestic dairy brands bypassing established distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack gravure cylinder capex for matte-finish organic specifications. Five-to-ten-year viability favors converters with pre-certified laminate structures under China's GB standards. Watch for REACH Annex XVII enforcement timelines as inflection indicator for adhesive reformulation compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paperboard Supply | Captive substrate production insulates converters from EU Green Deal fiber recovery mandates. |
| Nanocellulose Barrier Layer Development | Aluminum-free structures capture Nordic organic dairy brands ahead of REACH compliance deadlines. |
| Direct Tendering with Filling-Machine Vendors | Bypassing distributor networks locks in Vietnamese and Indonesian dairy processor volume commitments. |
| GB Standards Pre-Certification | First-mover positioning in Yangtze River Delta hubs ahead of domestic recyclability labeling enforcement. |
| Gravure Cylinder Capacity Addition | Matte-finish capability captures premium organic shelf space from mid-tier competitors. |
Study Parameters
Multiple input streams — converter engineering directors, dairy procurement leads at Vietnamese and Indonesian processors, multinational filling-machine vendor account managers, and EU regulatory affairs specialists — were reconciled against secondary validation. Trade customs data from German and Chinese packaging hubs, SEC filings from paperboard suppliers, ECHA REACH registration databases, and FDA food-contact substance notification logs anchored quantitative estimates. Bottom-up volume builds from individual converter capacity and top-down category sizing from liquid food consumption trends were cross-referenced for triangulation.
Data-stream reconciliation across material type, product format, end-user category, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit adjustments for laminate specification shifts. Forecast inputs incorporated aluminum foil price indexing, filling-machine installation rates in Southeast Asian manufacturing zones, and extended producer responsibility scheme implementation timelines across European markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH adhesive reformulation deadlines or aluminum foil supply disruptions. Model outputs reflect assumptions on nanocellulose barrier commercialization timelines and cold-chain infrastructure buildout rates in Indonesian secondary cities. A model refresh is warranted upon material change in EU Green Deal recyclability threshold enforcement or China's GB standards certification acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Fluted Carton Trays Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Europe Corrugated Box Market
Cartons
End Load Cartoning Machine Market
Cartons
Carton Bottle Market
Cartons
Digital Printed Cartons Market
Cartons
Round Corrugated Box Market
Cartons
Cartoning Machines Market
Cartons
Shaped Liquid Cartons Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Carton Sealer Machine Market
Cartons
North America Corrugated Boxes Market
Cartons
Soap Boxes Market
Cartons
Beverage Cartoners Market
Cartons
Litho Laminated Cartons Market