
 Brick Carton Packaging Market | 2026-2036
Brick Carton Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Brick Carton Packaging Market Analysis
Finland is tilting toward expanded pulpboard capacity to serve Nordic and Baltic dairy packaging demand. Tetra Pak leverages its aseptic filling equipment installed base to anchor long-term carton supply contracts across Europe. Stora Enso sustains integrated control from sustainably managed forests through coated board production, competing on fiber traceability. SIG Combibloc specializes in tethered-cap and aluminum-free barrier innovations, differentiating its portfolio for carbon-conscious beverage brands.
Brick carton packaging denotes a rectangular, gable-topped liquid container formed from laminated paperboard with polyethylene and aluminum barrier layers, typically rated for six-month ambient shelf stability without refrigeration. Its primary purpose is to protect oxygen-sensitive beverages and semi-liquid foods during distribution while minimizing weight versus glass or rigid plastic alternatives. Coated cartons command the largest volume share due to their cost-efficiency in standard milk and juice applications, while laminated cartons capture expanding margin pools in premium plant-based drinks requiring extended shelf life. The dairy end-user segment remains structurally mature in Western Europe, whereas the ready meals category is attracting new carton investment as retortable board barriers improve.
The EU Packaging and Packaging Waste Regulation and Germany's national packaging law shape recycled-content thresholds and extended producer responsibility fees for carton producers selling into European markets. FDA food-contact substance notifications govern aluminum migration limits and adhesive safety for any brick carton exports destined for US beverage bottlers. Stakeholders must monitor whether pending revisions to EU recyclability labeling rules will reclassify multi-layer cartons versus competing monomaterial formats in national sorting infrastructure.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for multi-layer beverage cartons as recycled-content mandates tighten across member states, forcing converters to re-engineer barrier specifications ahead of enforcement deadlines.
Growth Catalysts
- Aseptic filling technology:Dairy and plant-based beverage producers are retrofitting ambient distribution networks with extended-shelf-life brick formats, eliminating cold-chain dependencies in Germany and the Netherlands.
- EU Green Deal packaging targets:The bloc's 2030 recyclability benchmarks are accelerating capital flows into fiber-based barrier research and pilot-scale recycling infrastructure.
- Finnish pulpboard expansion:Nordic paperboard capacity additions are shortening lead times for coated carton substrates serving Baltic and Central European dairy cooperatives.
Market Restraints
- Aluminum barrier dependency:Current laminated structures require thin aluminum layers that complicate mechanical recycling streams and attract scrutiny under evolving EU recyclability definitions.
- German supply concentration:A disproportionate share of European aseptic filling equipment and carton blank production clusters in southern Germany, creating single-point vulnerability for continental supply.
- Polyethylene price volatility:Fossil-derived sealant layers expose converters to ethylene feedstock swings that compress margin predictability on long-term dairy supply contracts.
Strategic Opportunities
- Poland and Czech Republic dairy modernization:Central European cooperatives are upgrading from gable-top to brick aseptic formats, opening equipment and substrate contracts for converters with regional service presence.
- Retortable board ready meals:Improved high-barrier paperboard is enabling ambient pasta and soup applications previously reserved for cans and pouches.
- Aluminum-free barrier convergence:The intersection of bio-based coatings and vacuum deposition technologies is creating certification pathways for carbon-labeled beverage brands.
Industry Challenges
- Multi-layer disassembly expertise:Recycling facilities lack trained technicians and standardized equipment for separating polyethylene, aluminum, and fiber streams at commercial scale.
- Legacy filling line incompatibility:Dairy processors face seven-figure capital commitments to convert existing gable-top or PET lines to aseptic brick formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brick Carton Packaging Market |
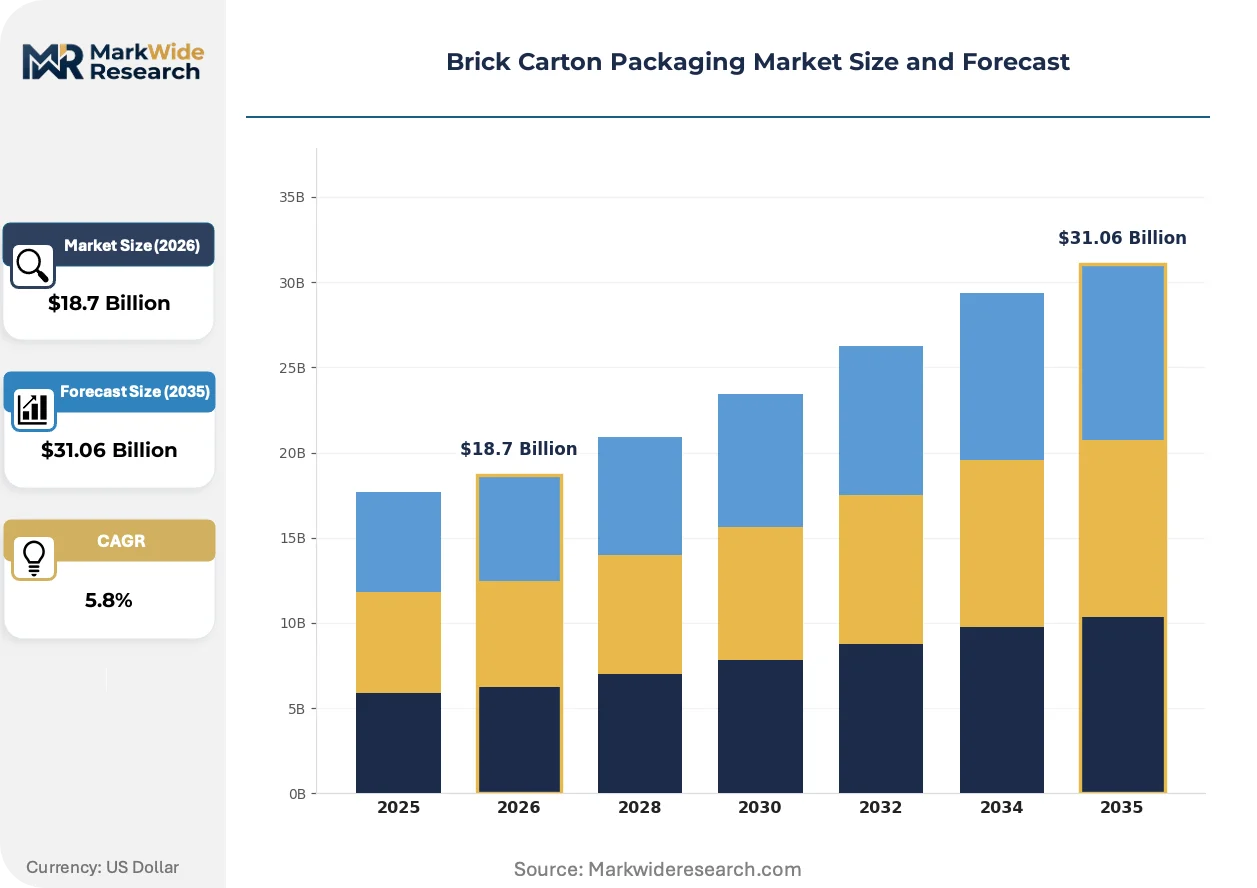
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uncoated Carton, Coated Carton, Laminated Carton, Insulated Carton End User: Dairy Products, Beverages, Sauces, Ready Meals Material: Pulpboard, Recycled Paper, Plastic, Aluminum Packaging Type: Single-Serve, Multi-Packs, Bulk Packaging, Retail Packs |
| Companies Covered | Huhtamaki, Mayr-Melnhof Karton AG, Tetra Pak, Smurfit Kappa, International Paper, SIG Combibloc, Stora Enso, Rengo Co., Ltd., Elopak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brick Carton Packaging Market Emerging Trajectories
Active barrier material science and sorting infrastructure investment are redefining what paper-based liquid packaging can claim on shelf stability and end-of-life credentials. Three developments merit particular attention.
Barrier technology is hybridizing conventional aluminum oxide deposition with bio-based polymer sealants to maintain six-month oxygen protection while improving fiber recovery yields. Premium plant-based beverage brands in Sweden and Denmark are piloting these structures for Q1 2025 line trials. The approach is compressing the performance gap between fully recyclable mono-material trials and incumbent multi-layer specifications.
REACH chemical authorization revisions are tightening scrutiny on adhesive substances used in polyethylene-aluminum lamination, compelling converters to pre-notify alternative chemistries. German carton producers are front-loading toxicology documentation to avoid supply interruptions. The dairy segment faces the steepest compliance timeline given its volume concentration in northern European markets.
Retail private-label buyers are consolidating carton specifications across beverage categories, demanding identical barrier grades for milk, juice, and plant-based alternatives to simplify procurement and inventory. Discounters in Germany and Austria are driving this standardization hardest. The shift is visible in reduced SKU complexity on filling lines and shorter supplier qualification cycles for board converters.
Brick Carton Packaging Market Segmentation
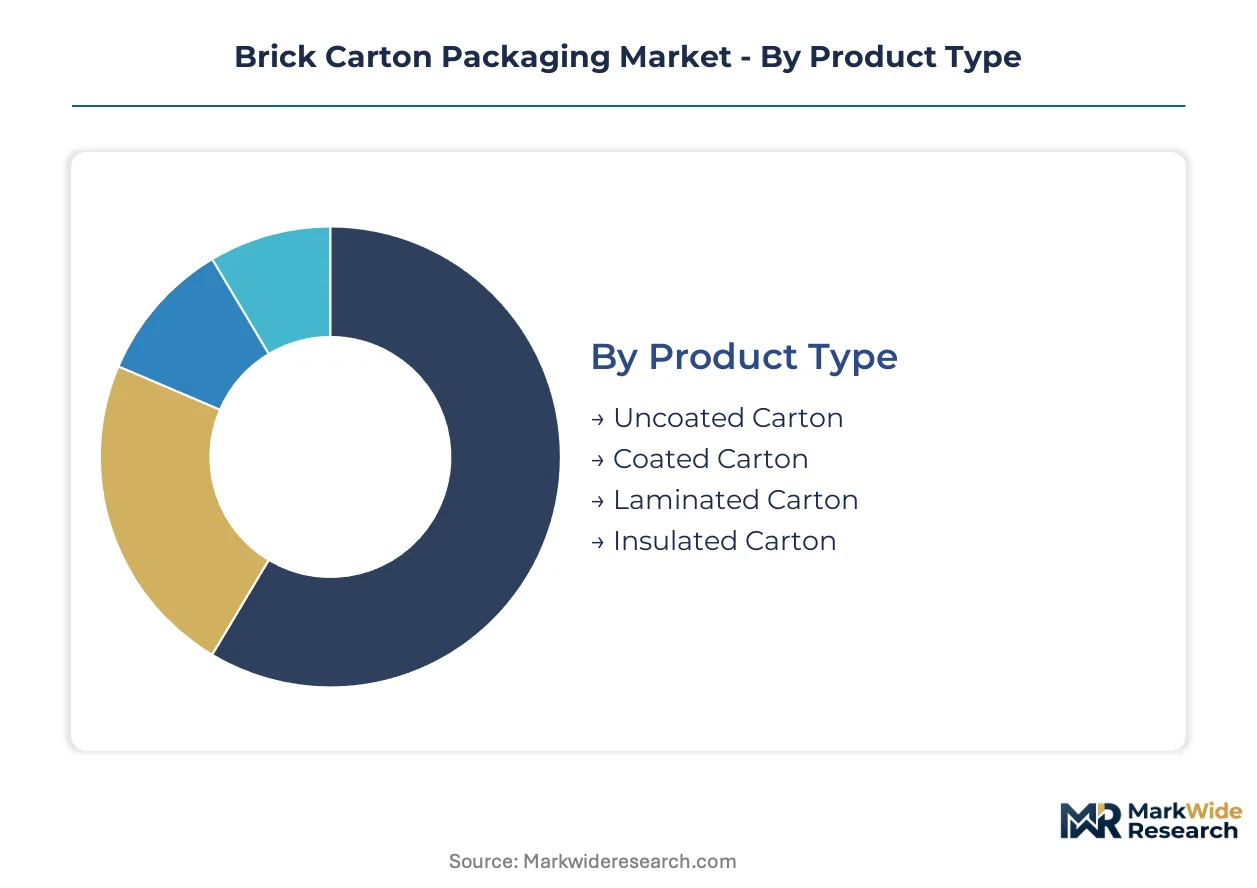
Brick carton packaging segments reflect divergent technical requirements across shelf-life demands, barrier specifications, and distribution temperature regimes. Understanding these divisions reveals where capital is concentrating and which substrate innovations command premium positioning.
Product Type:
Mature formats dominate volume, while emerging barrier technologies reshape margin structures.
- Coated Carton:Polyethylene-coated paperboard delivers moisture resistance for standard chilled milk and juice applications. German dairy cooperatives and Dutch private-label retailers specify this grade for high-throughput filling lines where six-week refrigerated shelf life suffices.
- Laminated Carton:Multi-layer structures incorporating aluminum oxide barriers enable ambient distribution without cold-chain dependency. Swedish oat milk producers and Finnish beverage brands are converting volume to these specifications as extended-shelf-life plant-based drinks displace chilled alternatives.
- Uncoated Carton:Bare pulpboard formats serve short-cycle fresh dairy with rapid turnover in local distribution networks.
- Insulated Carton:Expanded foam or reflective barrier variants protect temperature-sensitive formulations during last-mile delivery to institutional foodservice accounts.
Coated carton retains volume leadership; laminated carton holds the steepest expansion curve.
End User:
Application requirements range from oxygen-sensitive liquid foods to retort-stable semi-solids.
- Dairy Products:Fresh milk, UHT cream, and fermented beverages constitute the installed base demand for aseptic brick formats. Bavarian and Baden-Württemberg processing cooperatives are retrofitting gable-top lines to brick aseptic equipment.
- Beverages:Plant-based milks, functional drinks, and ambient juices require aluminum-barrier laminations for six-month shelf stability. Danish and Swedish brands are piloting aluminum-free alternatives ahead of EU recyclability deadlines.
- Sauces:Viscous condiments and cooking bases utilize modified-rheology board grades with enhanced side-seal integrity.
- Ready Meals:Retortable board barriers are enabling pasta and soup applications previously reserved for metal cans, with Polish and Czech processors testing pilot lines.
Dairy products anchor current volume; ready meals are gaining share fastest as retort technology matures.
Material:
Feedstock strategies diverge between integrated forest ownership and merchant market exposure.
- Pulpboard:Virgin fiber from sustainably managed Nordic forests provides strength and printability for premium beverage branding. Finnish mill expansions are shortening lead times for Central European converters.
- Recycled Paper:Post-consumer fiber incorporation is rising under EU Packaging and Packaging Waste Regulation mandates, though strength degradation limits high-barrier applications.
- Plastic:Polyethylene sealant layers remain essential for liquid-tight heat sealing, with fossil-derived feedstock exposing converters to ethylene price volatility.
- Aluminum:Thin foil or vapor-deposited barriers provide oxygen and light protection, yet complicate mechanical recycling streams under evolving EU recyclability definitions.
Pulpboard dominates premium positioning; recycled paper is climbing the fastest on regulatory pull.
Packaging Type:
Format selection tracks channel economics and consumption occasion fragmentation.
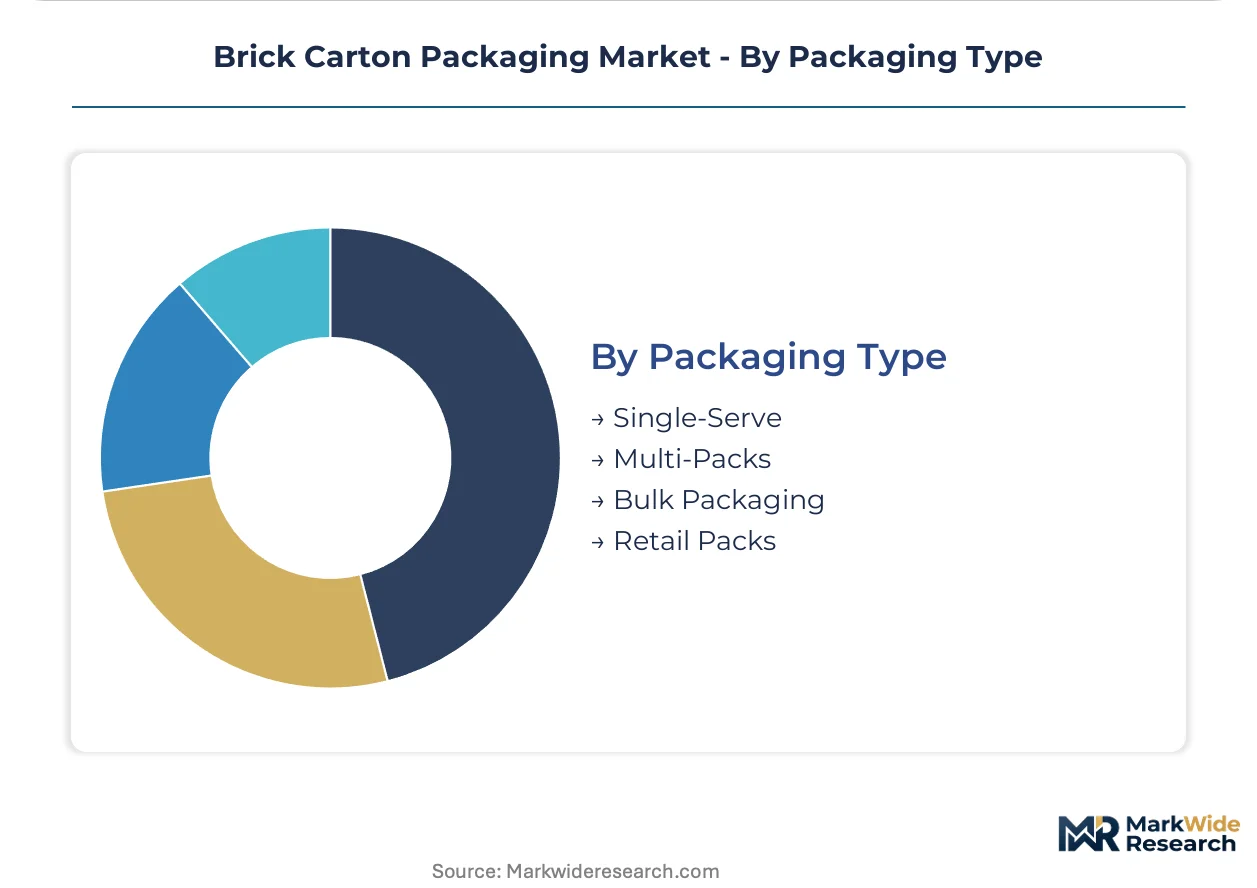
- Single-Serve:200-250ml brick formats target on-the-go consumption in convenience retail and foodservice channels. German railway catering and Dutch airport concessions specify these for ambient distribution.
- Multi-Packs:Four-to-six unit outer wraps serve club retail and family pantry stocking in discount grocery channels.
- Retail Packs:Individual 1-liter bricks dominate standard grocery shelf placement for milk and juice in Austrian and Swiss markets.
- Bulk Packaging:5-10 liter bag-in-box alternatives for foodservice fountains and institutional kitchens use reduced board specifications.
Single-serve captures margin premium; retail packs hold volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation enforcement timelines are compressing investment decisions across European carton converters, with Germany's federal packaging law creating the most immediate compliance pressure for multi-layer barrier formats.
Germany
Dairy cooperatives in Bavaria and Baden-Württemberg are retrofitting gable-top lines to aseptic brick equipment, driven by extended-shelf-life milk demand and discounter private-label consolidation. The national packaging law tightens extended producer responsibility fees for non-recyclable formats. Stuttgart and Munich house the densest clusters of filling equipment engineering and coated board finishing capacity.
Sweden
Oat milk and plant-based beverage brands are piloting aluminum-free barrier cartons ahead of EU recyclability deadlines, converting volume from chilled to ambient distribution formats. REACH chemical authorization revisions are accelerating adhesive substance documentation for converters. Stockholm and Malmö anchor Nordic headquarters for beverage brand technical procurement teams.
Finland
Nordic pulpboard mill expansions are shortening lead times for Central European dairy packaging substrates, with sustainably managed forest certification commanding premium positioning. The EU Green Deal packaging targets are pulling capital into fiber-based barrier research. Kotka and Imatra concentrate integrated pulp-to-board production serving Baltic and German converter networks.
Poland
Central European dairy cooperatives are upgrading from gable-top to brick aseptic formats, opening equipment and substrate contracts for converters with regional service presence. EU cohesion funds are supporting food processing modernization grants. Warsaw and Łódź are emerging as logistics hubs for carton blank distribution into Czech and Slovak markets.
United States
Plant-based beverage bottlers are importing European aseptic filling technology for oat and almond milk ambient distribution, though FDA food-contact substance notifications govern aluminum migration limits for carton exports. California and New York processors are testing brick formats for foodservice and convenience retail channels.
Brick Carton Packaging Market Vendor Landscape
Integrated forest-product conglomerates and specialized filling-equipment bundlers split the market into distinct competitive spheres, with substrate control and aseptic technology lock-in defining sustainable differentiation. Consolidation concentrates around Nordic pulpboard ownership and Swiss-German filling system engineering. Two archetypes dominate: backward-integrated fiber majors controlling raw material-to-board conversion, and equipment-anchored solution providers bundling machinery with long-term carton supply. Competitive moves center on capacity expansion in Nordic pulpboard and strategic partnerships between converters and dairy brand technical teams.
Within the integrated fiber tier, Stora Enso and Mayr-Melnhof Karton AG exemplify backward-integrated positioning, while Tetra Pak occupies the equipment-anchored archetype. These three names represent the structural poles of the competitive landscape, with the Finnish and Austrian entities emphasizing forest certification traceability and the Swiss-based player leveraging installed filling equipment bases to secure carton supply contracts.
| Leading Market Players |
|---|
| Huhtamaki |
| Mayr-Melnhof Karton AG |
| Tetra Pak |
| Smurfit Kappa |
| International Paper |
| SIG Combibloc |
| Stora Enso |
| Rengo Co., Ltd. |
| Elopak |
| Others |
Supply Flow & Price Mechanics
Aluminum barrier dependency compresses pricing tier spreads while tethering supply chain configuration to Nordic pulpboard availability and German equipment engineering clusters. Polyethylene price volatility and EU recyclability mandates simultaneously squeeze margin predictability and force substrate re-engineering investments.
Pricing Analysis
German converters command premium pricing against Polish and Czech competitors due to integrated filling equipment servicing and shorter technical response times. Three-tier pricing structure across premium, standard, and economy levels tracks barrier complexity and certification grade, with aluminum-free laminations capturing carbon-label premiums. Cost compression in standard coated grades is intensifying because Finnish pulpboard expansions are shortening lead times and eroding regional scarcity premia. Discounter private-label buyers in Germany exhibit highest price sensitivity, while Swedish plant-based beverage brands prioritize barrier performance over unit cost.
Supply Chain Analysis
Export-control scrutiny on aseptic filling technology limits equipment flows from Switzerland and Germany to non-EU dairy processors, constraining capacity expansion in target markets. Raw material sourcing draws from Finnish pulpboard mills, Saudi ethylene feedstock for polyethylene sealants, and Russian aluminum foil subject to trade restriction uncertainty. Single-source vulnerability concentrates in southern Germany's filling equipment engineering cluster. Distribution runs through converter-finishing facilities near dairy processing cooperatives in Bavaria, with blank stockpiles positioned at Warsaw and Łódź logistics hubs for Central European fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation enforcement fragments competitive space by creating compliance capability gaps between integrated fiber majors and merchant converters. Plant-based beverage demand diversification into aluminum-free formats opens niche positioning for barrier technology specialists.
For Market Incumbents: Entrench supply relationships through captive pulpboard capacity expansion in Kotka and Imatra, locking Nordic fiber traceability certification ahead of EU Green Deal packaging targets. Anchor long-term filling equipment service contracts with Bavarian dairy cooperatives to block regional challenger entry. Aluminum-free barrier patent portfolios represent the critical defensive lever against SIG Combibloc and emerging bio-coating specialists. For New Entrants and Emerging Players: Central European dairy cooperatives upgrading from gable-top to brick aseptic formats represent the most penetrable entry point, with Polish and Czech processors underserved by incumbent technical service presence. Aluminum-free barrier pilot programs for Swedish oat milk brands offer equipment-light market access. Partner with Finnish mill technical teams for substrate co-development rather than competing on board supply. For Investors and Strategic Acquirers: The EU Packaging and Packaging Waste Regulation's 2030 recyclability benchmarks reshape the acquisition landscape by elevating integrated fiber-to-board converters over merchant-dependent players. Five-to-ten year viability favors backward-integrated Nordic pulpboard owners with certified sustainable forest management and in-house barrier coating capability. Watch for REACH chemical authorization revision enforcement against adhesive-dependent laminators as the signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulpboard Production | Finnish mill expansions shorten lead times for Central European dairy packaging demand. |
| Aluminum-Free Barrier Certification | Swedish oat milk brands pilot bio-based coatings ahead of EU recyclability deadlines. |
| Regional Service Hub Establishment | Warsaw logistics positions converters for Polish and Czech dairy cooperative upgrades. |
| Long-Term Equipment Supply Contract | Tetra Pak leverages installed base to anchor carton supply across German discounters. |
| Sustainable Forest Certification Program | Stora Enso commands premium positioning through fiber traceability from Nordic forests. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, Finnish pulpboard trade data, and dairy processor capital expenditure disclosures. Primary interviews engaged filling equipment engineers at Swiss-German machinery specialists, procurement leads at Bavarian dairy cooperatives, and technical directors at Nordic pulpboard mills. Secondary validation drew from ECHA REACH authorization databases, EU Packaging and Packaging Waste Regulation impact assessments, and SEC filings of integrated forest-product conglomerates. Bottom-up demand modeling from dairy and beverage processor line conversions triangulates against top-down capacity analysis across Nordic board mills.
Forecast inputs incorporate barrier technology substitution curves, EU Green Deal packaging target enforcement timelines, and ethylene feedstock price volatility assumptions. Segmentation dimensions span product type, end-user application, material feedstock strategy, and packaging format across the analysis window. CAGRs derive from installed base equipment depreciation schedules and dairy cooperative modernization grant disbursement patterns. Aseptic filling technology adoption rates and aluminum-free barrier pilot scale-up timelines inform trajectory calibration.
Macroeconomic conditions sit as an overlay; deviation in ethylene commodity pricing, EU regulatory enforcement intensity, or Nordic pulpboard capacity commissioning would shift the trajectory. Forecasts reflect documented assumptions on barrier technology performance convergence and recycling infrastructure investment pacing. Material shifts in EU recyclability labeling rule reclassification of multi-layer cartons would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Fluted Carton Trays Market
Cartons
Mailers Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Pulp Roll Cradles Market
Cartons
Beverage Cartoners Market
Cartons
Tetrahedron Carton Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Carton Bottle Market
Cartons
Carton Liners Market
Cartons
Digital Folding Cartons Market
Cartons
Cardboard Crates Market
Cartons
Folding Carton in Healthcare Market
Cartons
GCC Folding Carton Market
Cartons
Pizza Cartons Market
Cartons
Carton Sealer Machine Market