
 Fully Enclosed Cartons Market | 2026-2036
Fully Enclosed Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Fully Enclosed Cartons Market Foresight
A capital-intensity divergence between integrated pulp-to-box operators and regional converters is reorganizing competitive tiers in fully enclosed cartons. International Paper Company leverages its captive fiber supply and North American mill network to sustain margin stability on high-volume food-grade contracts. WestRock Company anchors its position through automated die-cutting and printing assets that dominate beverage multipack applications. Smurfit Kappa Group competes via European recycling infrastructure and lightweight flute optimization for e-commerce shippers.
Fully enclosed cartons are rigid packaging structures fabricated from corrugated fiberboard, solid board, or polymer composites, sealed on all six faces through folding, adhesive bonding, or mechanical locking to protect contents from contamination, tampering, and environmental exposure. Board caliper typically ranges from 0.4 mm to 6 mm depending on stacking strength requirements, with clay-coated surfaces enabling high-resolution lithographic printing for shelf-ready retail presentation. Cardboard grades capture the dominant volume share across food and beverage end users where moisture resistance and printability balance cost. Recyclable specifications are accelerating fastest as brand owners face extended producer responsibility mandates in the EU and California. Self-locking closure formats occupy premium positioning in pharmaceuticals and electronics by eliminating tape or glue contamination risks during cleanroom handling.
The FDA enforces 21 CFR Part 175 compliance for indirect food contact substances in carton coatings and adhesives, while the EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds and design-for-recycling protocols. ISO 9001 and BRCGS certification frameworks shape supplier qualification criteria for multinational food and pharmaceutical buyers. Stakeholders must monitor evolving state-level extended producer responsibility laws in the US and pending EU harmonization of recyclability performance grades to align capital allocation with compliance timelines.
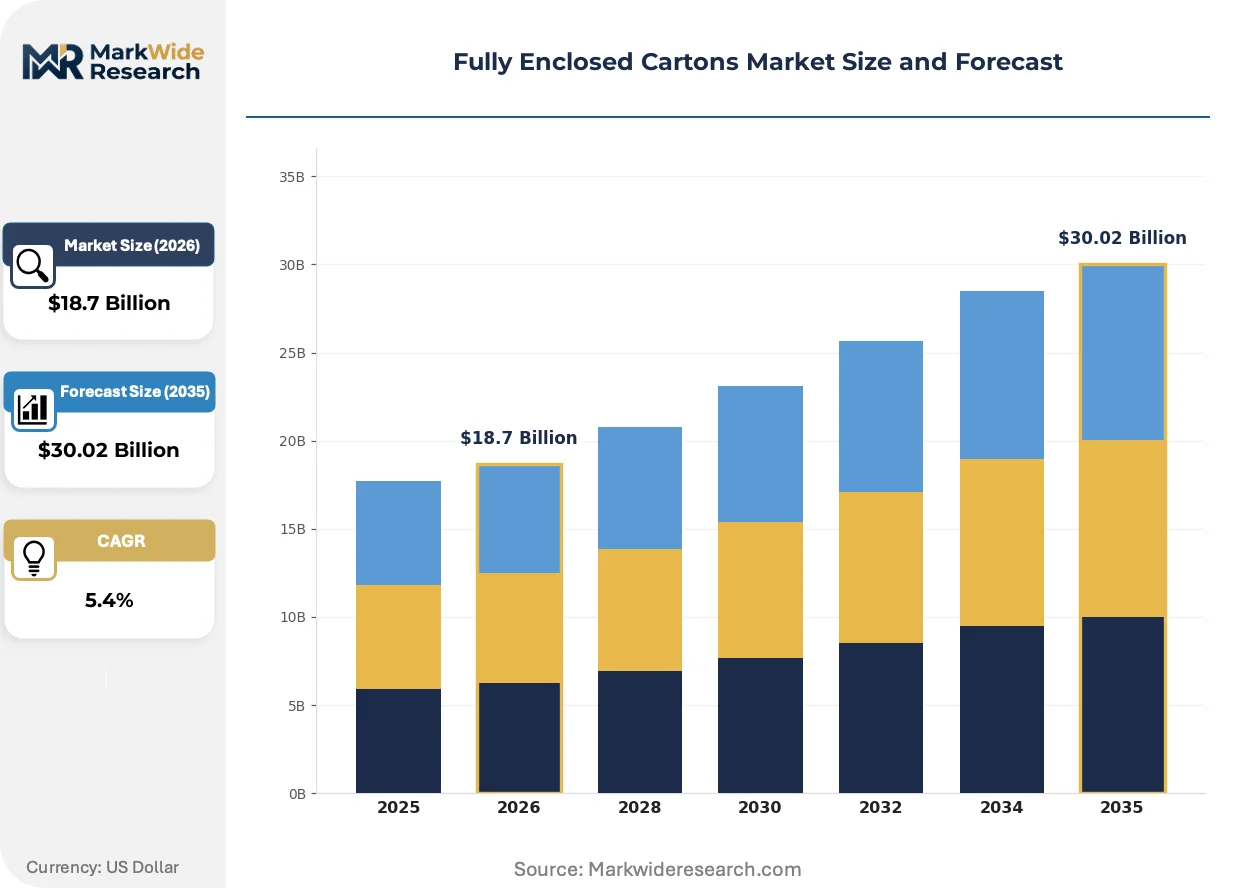
Market Dynamics
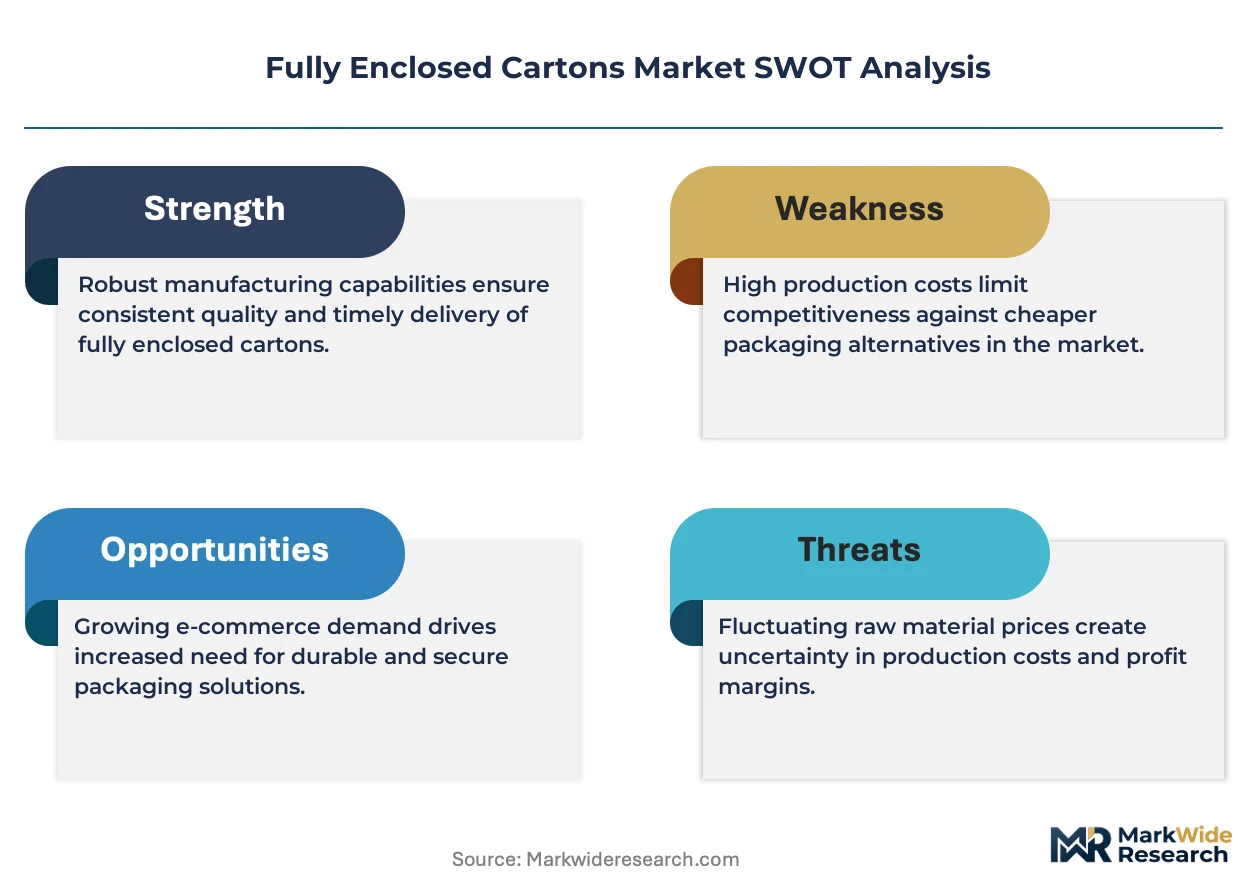
The EU Packaging and Packaging Waste Regulation is forcing material traceability investments across fully enclosed carton supply chains, creating a bifurcation between compliant integrated operators and exposed regional converters facing qualification barriers.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Temperature-stable enclosed cartons are displacing expanded polystyrene in biologics distribution across Germany's Frankfurt-Ludwigshafen manufacturing corridor.
- Extended producer responsibility mandates:California's SB 54 and EU harmonized recyclability grades are pulling brand owners toward recyclable fiberboard specifications with certified recycled content thresholds.
- Cleanroom handling protocols:Self-locking closure formats are eliminating tape and glue contamination risks in electronics and pharmaceutical packaging where ISO 14644 compliance is mandatory.
Market Restraints
- Pulp cost volatility:Kraft linerboard prices swing with Nordic softwood pulp contract settlements, compressing converter margins on fixed-price annual contracts.
- Recycling infrastructure gaps:Polymer-composite cartons with multilayer barriers lack industrial composting or mechanical recycling pathways in most US municipal systems.
- REACH chemical restrictions:ECHA scrutiny of fluorinated barrier coatings is limiting moisture-resistant options for fatty food applications in European markets.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO-aligned cold-chain packaging demand from Mumbai-Pune generic drug clusters is outpacing domestic supplier capacity.
- Digital printing convergence:Inkjet overprint systems combined with clay-coated board are enabling lot-level serialization for track-and-trace compliance without plate changeover costs.
- E-commerce shipper optimization:Lightweight flute designs certified for Amazon Frustration-Free Packaging are opening direct-to-consumer channels for premium food brands.
Industry Challenges
- Die-cutting automation skill gaps:Regional converters struggle to recruit operators for Bobst and Heidelberg high-speed folder-gluer lines capable of sub-millimeter registration tolerance.
- BRCGS certification timelines:Food-grade suppliers face 12-18 month audit cycles to qualify for multinational retailer vendor lists, locking out capital-constrained mid-tier players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fully Enclosed Cartons Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Plastic, Wood, Metal Packaging Grade: Food Grade, Industrial Grade, Recyclable, Biodegradable Closure Type: Self-Locking, Tape, Glue, Strapping End User: Food & Beverage, Electronics, Pharmaceuticals, Consumer Goods |
| Companies Covered | International Paper Company, WestRock Company, Smurfit Kappa Group, Mondi Group, DS Smith Plc, Graphic Packaging International, Huhtamaki, Mayr-Melnhof Karton AG, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fully Enclosed Cartons Market Shifts & Advancements
Active barrier technologies and digital production workflows are compressing run-length economics while regulatory pressure on recyclability is accelerating material substitution away from legacy polymer laminates.
Water-based oxygen barrier coatings derived from cellulose nanofibrils are displacing ethylene vinyl alcohol laminates in retort-ready carton applications. Premium pet food and ready-meal brands in the Netherlands and Denmark are qualifying these specifications for shelf-stable protein packaging. The displacement is compressing demand for multilayer extrusion equipment among European converters.
REACH restriction proposals on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical treatments from food-contact cartons by 2026. Barrier coating suppliers are accelerating bio-wax and clay-based alternatives through EFSA safety assessments. Bakery and fried snack segments in France and Germany are reformulating packaging specifications ahead of enforcement.
Direct-to-retail procurement consolidation is compressing supplier bases as Ahold Delhaize and Carrefour centralize packaging specification authority to category buyers in Brussels and Paris. Legacy broker-mediated sourcing is contracting in favor of audited direct contracts with BRCGS-certified integrated mills. The shift is most visible in private-label beverage multipacks where volume concentration justifies dedicated production lines.
Fully Enclosed Cartons Market Segmentation
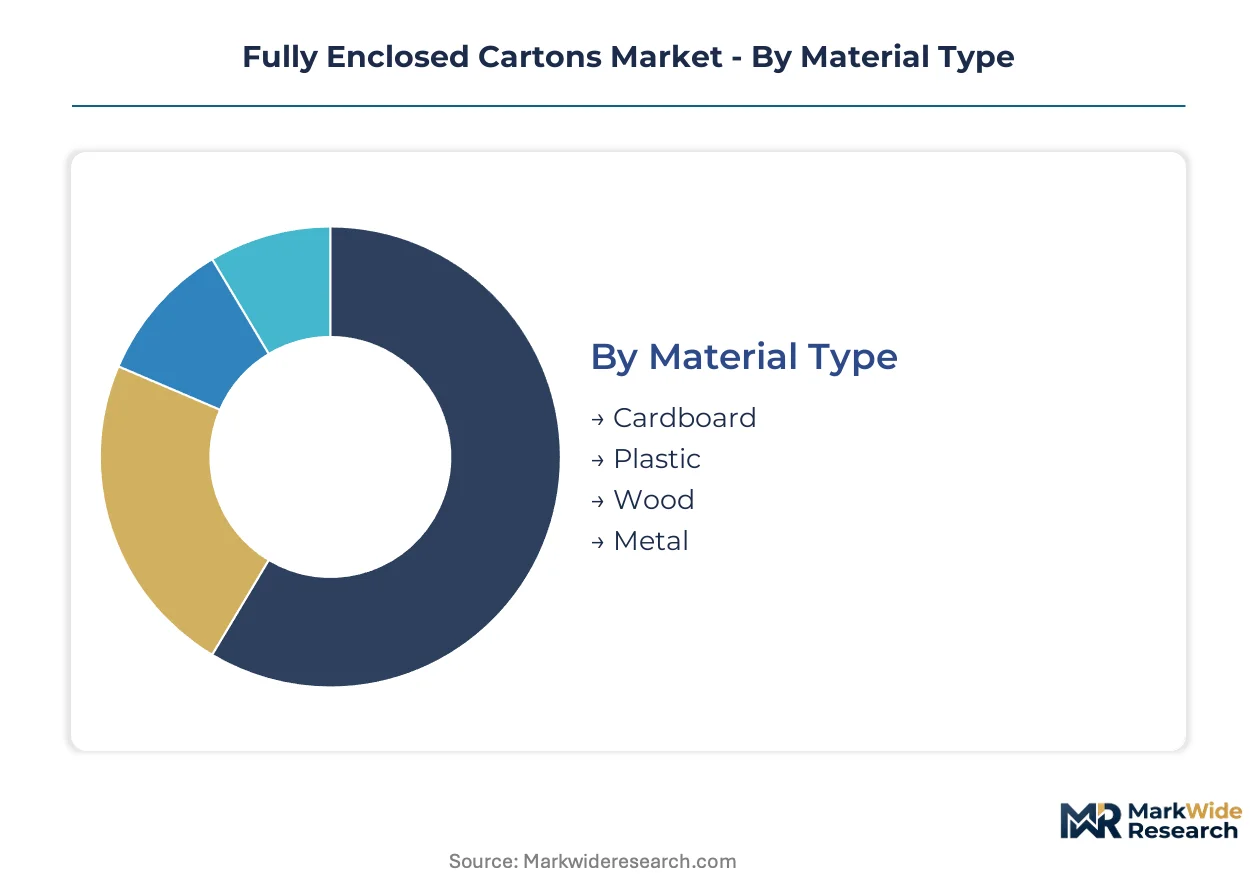
Material specifications, closure mechanics, and end-use compliance requirements create distinct commercial lanes in fully enclosed cartons. Each segment commands different channel access, with food-grade and pharmaceutical specifications flowing through audited supplier networks while industrial grades move through distributor channels.
Material Type:
Channel mix splits between corrugated fiberboard dominating retail grocery and e-commerce fulfillment, polymer composites penetrating temperature-controlled pharmaceutical logistics, and metal systems anchoring heavy industrial applications.
- Cardboard:Corrugated fiberboard and solid board constructions with clay-coated surfaces enable high-resolution lithographic printing. Demand concentrates in German food retail and Amazon Frustration-Free Packaging programs where lightweight flute optimization reduces dimensional weight charges.
- Plastic:Polymer composites and multilayer extrusions incorporate ethylene vinyl alcohol barriers for moisture resistance. Pharmaceutical cold-chain corridors around Frankfurt and Ludwigshafen are displacing expanded polystyrene with temperature-stable enclosed cartons for biologics distribution.
- Wood:Plywood and engineered timber frames serve heavy machinery and export crating applications requiring ISPM-15 heat treatment compliance. Industrial manufacturing clusters in Bavaria and Baden-Württemberg specify these for capital equipment shipment.
- Metal:Steel and aluminum enclosures protect high-value electronics and aerospace components from electromagnetic interference. Cleanroom handling protocols in Dutch semiconductor fabrication facilities drive specification of tape-free closure formats.
Cardboard dominates installed base. Plastic is where expansion concentrates.
Packaging Grade:
Cost tier stratification separates premium certified grades from commodity specifications, with BRCGS and ISO 14644 compliance commanding 40-60% price premiums over industrial-grade alternatives.
- Food Grade:FDA 21 CFR Part 175 compliant coatings and adhesives for indirect food contact. Dutch and Danish ready-meal brands are qualifying cellulose nanofibril oxygen barriers ahead of REACH fluorochemical restrictions.
- Industrial Grade:Uncoated or wax-impregnated board for non-contact manufacturing logistics. German automotive component suppliers specify these for line-side Kanban delivery systems.
- Recyclable:Design-for-recycling protocols meeting EU harmonized recyclability grades. California SB 54 and extended producer responsibility mandates are pulling brand owners toward certified recycled content thresholds.
- Biodegradable:Industrial composting certified materials for organic food and agricultural applications. French bakery segments are reformulating specifications ahead of EFSA safety assessments for bio-wax barrier alternatives.
Food grade captures volume concentration. Recyclable specifications are climbing the fastest.
Closure Type:
Application context determines closure selection, with cleanroom environments mandating adhesive-free mechanical systems while high-speed fulfillment prioritizes tape-based throughput.
- Self-Locking:Mechanical interlocking tabs eliminate tape or glue contamination risks. ISO 14644 compliant pharmaceutical and electronics packaging in Belgian and Dutch cleanroom facilities specify these for particle-controlled handling.
- Tape:Pressure-sensitive adhesive closure for high-volume e-commerce and retail distribution. Amazon Frustration-Free Packaging certification programs are standardizing tape specifications for automated opening.
- Glue:Hot-melt or cold-seal adhesive bonding for tamper-evident food and beverage applications. German beverage multipack converters deploy automated folder-gluer lines capable of sub-millimeter registration tolerance.
- Strapping:Polypropylene or steel banding for heavy-load industrial and export shipments. Machinery exporters in Stuttgart and Munich specify these for ocean container consolidation.
Tape dominates throughput volume. Self-locking formats are gaining share fastest in premium segments.
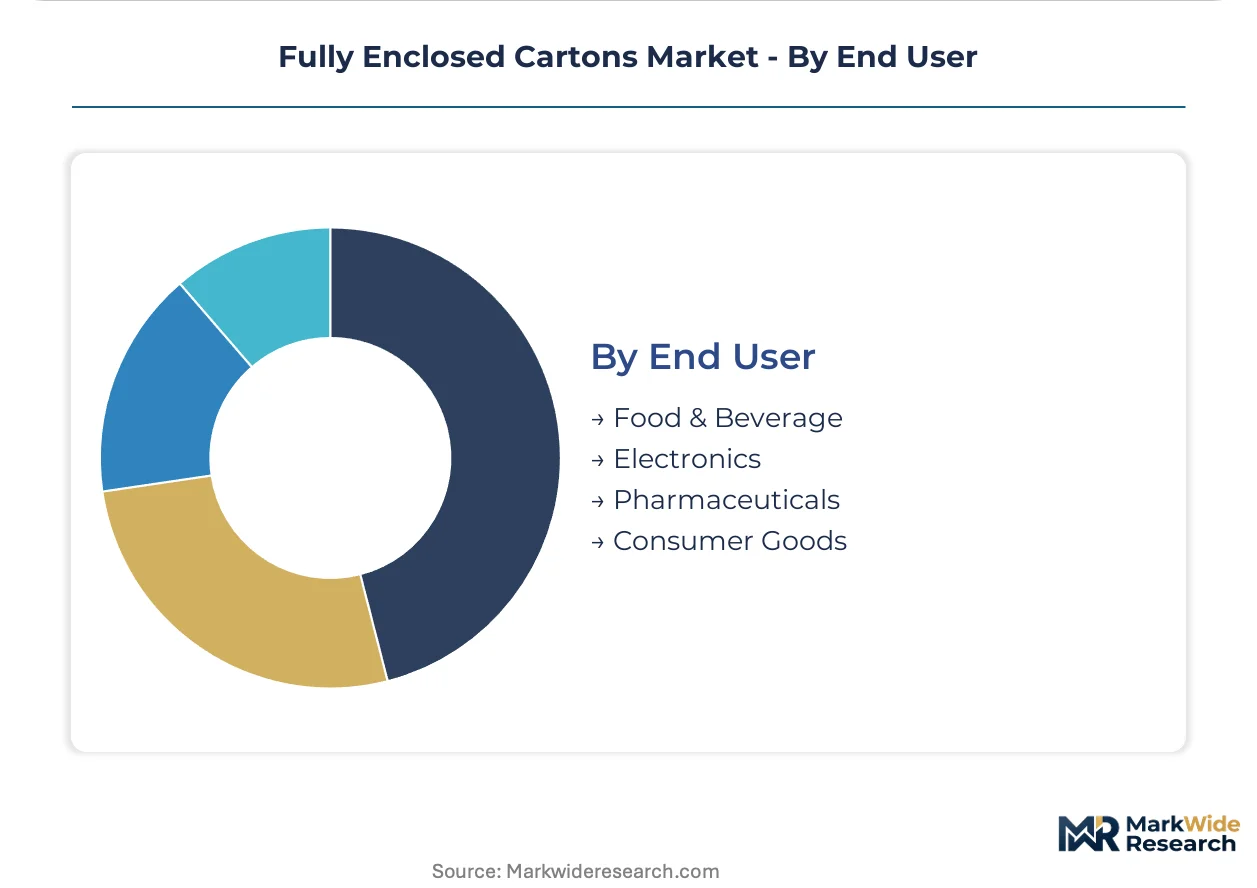
End User:
Customer type segmentation aligns with regulatory intensity, with pharmaceutical and food buyers requiring 12-18 month BRCGS certification cycles while electronics and consumer goods move through faster qualification paths.
- Food & Beverage:Moisture-resistant cartons for shelf-stable proteins and ready-meals. Ahold Delhaize and Carrefour centralized procurement in Brussels and Paris is consolidating supplier bases toward audited direct contracts.
- Electronics:Electrostatic discharge protection and cleanroom-compatible closures. Eindhoven semiconductor fabrication facilities specify self-locking formats to eliminate particulate contamination.
- Pharmaceuticals:Temperature-stable enclosed cartons for biologics and generic drug distribution. CDSCO-aligned cold-chain demand from Mumbai-Pune clusters is outpacing Indian domestic supplier capacity.
- Consumer Goods:Shelf-ready retail presentation with high-resolution graphics. Direct-to-consumer channels for premium personal care brands are adopting lightweight flute Amazon certification.
Food and beverage anchors revenue scale. Pharmaceuticals shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive industrial buyers in India and Brazil squeeze converter margins on commodity grades, while pharmaceutical buyers in Germany and Switzerland absorb 40-60% premiums for certified cold-chain specifications. This elasticity gap is widening as EU traceability mandates raise qualification barriers.
Germany
Pharmaceutical cold-chain demand from biologics distribution is displacing expanded polystyrene in the Frankfurt-Ludwigshafen manufacturing corridor. The EU Packaging and Packaging Waste Regulation enforces minimum recycled content thresholds and design-for-recycling protocols. Automated die-cutting assets in Baden-Württemberg achieve sub-millimeter registration tolerance for beverage multipack contracts.
United States
California's SB 54 extended producer responsibility mandates pull brand owners toward certified recycled content thresholds in fiberboard specifications. FDA 21 CFR Part 175 compliance governs indirect food contact substances in carton coatings and adhesives. Integrated pulp-to-box operators in the Pacific Northwest leverage captive fiber supply to sustain margin stability on high-volume food-grade contracts.
India
CDSCO-aligned cold-chain packaging demand from Mumbai-Pune generic drug clusters outpaces domestic supplier capacity. The country's national pharmaceutical regulator enforces track-and-trace serialization requirements for export markets. Regional converters in Gujarat struggle with 12-18 month BRCGS certification timelines to qualify for multinational retailer vendor lists.
Netherlands
Ready-meal brands in Amsterdam and Utrecht qualify cellulose nanofibril oxygen barriers ahead of ECHA REACH fluorochemical restrictions. EFSA safety assessments accelerate bio-wax and clay-based alternatives through regulatory approval. Eindhoven semiconductor fabrication facilities specify self-locking closure formats to eliminate particulate contamination in cleanroom handling.
Japan
Lightweight flute optimization for e-commerce shippers penetrates direct-to-consumer channels for premium personal care brands. METI promotes circular economy packaging standards aligned with EU harmonized recyclability grades. Kanto region converters deploy inkjet overprint systems for lot-level serialization without plate changeover costs.
Fully Enclosed Cartons Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated mills commanding premium-tier positioning through captive fiber supply while regional converters compete on turnaround speed for short-run industrial grades. The market structure consolidates around three strategic tiers: multinational integrated operators with backward integration into pulp assets, mid-cap European specialists with recycling infrastructure dominance, and regional job-shop converters serving distributor channels. Competitive moves concentrate on M&A-driven geographic consolidation and automated asset deployment to capture BRCGS-certified contract volumes.
Among North American integrated operators, International Paper Company and WestRock Company exemplify scale-driven archetypes with mill network coverage, while Smurfit Kappa Group occupies a position within the European recycling-optimization tier. These three anchors represent divergent capital-intensity strategies: captive fiber supply sustaining margin stability, automated die-cutting and printing assets dominating beverage applications, and lightweight flute optimization capturing e-commerce certification programs respectively.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group |
| Mondi Group |
| DS Smith Plc |
| Graphic Packaging International |
| Huhtamaki |
| Mayr-Melnhof Karton AG |
| Oji Holdings Corporation |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day kraft linerboard order lead times concentrate pricing power with Nordic softwood pulp contract holders, while spot-market converters absorb margin compression on fixed-price annual food-grade agreements. Inventory velocity at German pharmaceutical corridors runs leaner than e-commerce fulfillment nodes, amplifying cost pass-through elasticity divergence between certified cold-chain specifications and commodity industrial grades.
Pricing Analysis
After-market certification and compliance service bundles drive lifetime value capture beyond unit carton sales. Three-tier pricing structure across BRCGS-certified premium, ISO-standard mid-tier, and uncertified economy levels segments buyer archetypes by audit tolerance. Pricing pressure stems from pulp cost volatility transmitted through Nordic softwood contract settlements, squeezing converter margins on annual fixed-price commitments. Pharmaceutical buyers in Germany and Switzerland exhibit lowest price sensitivity, absorbing premiums for temperature-stable specifications, while Brazilian and Indian industrial buyers force aggressive commodity bidding.
Supply Chain Analysis
Strategic stockpiling of clay-coated board and barrier coatings dominates pharmaceutical and food-grade procurement, contrasting with just-in-time kraft linerboard flows to high-velocity e-commerce converters. Supply concentrates in Germany, the United States, and India for integrated pulp-to-box capacity, while specialty polymer-composite inputs draw from Netherlands and Japanese chemical suppliers. Single-source vulnerability concentrates in Nordic softwood pulp settlements that transmit directly to linerboard pricing. Distribution runs through audited direct contracts with multinational retailers, bypassing legacy broker channels for BRCGS-certified volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: twelve-to-eighteen-month BRCGS certification cycles and EU Packaging and Packaging Waste traceability mandates create switching costs that lock qualified suppliers into sticky incumbent positions.
For Market Incumbents: Shield market position by deepening backward integration into captive fiber supply to neutralize pulp cost volatility, while accelerating automated die-cutting asset deployment in Baden-Württemberg to capture beverage multipack consolidation. Prioritize EFSA-aligned barrier coating R&D ahead of REACH fluorochemical enforcement to preempt reformulation cycles that could displace qualified specifications.
For New Entrants and Emerging Players: Short-run digital printing capability gaps in Indian pharmaceutical export corridors present white-space entry points where domestic capacity lags CDSCO-aligned cold-chain demand. Target Mumbai-Pune generic drug clusters with inkjet overprint systems enabling lot-level serialization without plate changeover investments. Lead with Amazon Frustration-Free Packaging certification services to capture lightweight flute optimization demand from direct-to-consumer premium food brands.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automated asset scarcity and certification backlog create acquisition targets among mid-tier European converters with recycling infrastructure but underutilized folder-gluer capacity. Monitor ECHA REACH restriction timelines on per- and polyfluoroalkyl substances as the inflection signal: accelerated enforcement compresses demand for multilayer extrusion equipment and rewards early bio-wax barrier positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Fiber Supply | Nordic softwood pulp contract holders neutralize linerboard cost volatility transmitted to fixed-price food-grade agreements. |
| Automated Die-Cutting Asset Deployment | Sub-millimeter registration tolerance on Bobst and Heidelberg lines captures Ahold Delhaize beverage multipack consolidation. |
| Bio-Wax Barrier Coating R&D Acceleration | EFSA-aligned alternatives displace fluorochemical treatments ahead of ECHA REACH restrictions in French bakery segments. |
| Digital Printing Capability Investment | Inkjet overprint systems enable CDSCO-aligned lot-level serialization for Mumbai-Pune pharmaceutical export corridors. |
| Amazon Frustration-Free Packaging Certification | Lightweight flute optimization opens direct-to-consumer channels for premium food brands facing dimensional weight charges. |
Research Methodology
The analysis maps corrugated fiberboard, polymer-composite, and metal enclosure sub-sectors, each validated through procurement directors at multinational food and pharmaceutical buyers, plant managers at integrated mill operators, and regulatory affairs leads tracking EU Packaging and Packaging Waste compliance. Primary interviews with BRCGS auditors, barrier coating R&D directors, and e-commerce fulfillment category buyers combined with secondary validation from ECHA restriction proposals, FDA 21 CFR Part 175 guidance documents, and customs trade data on kraft linerboard imports. Bottom-up capacity modeling and top-down demand triangulation cross-checked segment outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled material type, packaging grade, closure mechanics, and end-use compliance intensity as core segmentation dimensions. CAGRs derived from installed base erosion rates, replacement demand curves, and greenfield capacity absorption patterns. Forecast inputs incorporated EU harmonized recyclability grade adoption curves and pharmaceutical cold-chain corridor expansion trajectories.
Underlying assumptions cover pulp contract settlement stability, certification audit cycle durations, and REACH enforcement timelines, with deviation risk concentrated in Nordic softwood supply disruptions and EFSA bio-wax approval delays. Revision becomes warranted when EU Packaging and Packaging Waste recycled content thresholds accelerate ahead of supplier qualification capacity or when Indian CDSCO serialization mandates expand beyond Mumbai-Pune clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Global Printed Cartons Market
Cartons
Shaped Corrugated Packaging Market
Cartons
Carton Display Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Carton Sealer Market
Cartons
Folding Carton in Healthcare Market
Cartons
Mailers Market
Cartons
Global Folding Carton Packaging Market
Cartons
Soap Boxes Market
Cartons
Microwaveable Carton Market
Cartons
Digital Folding Cartons Market
Cartons
Global Cartonboard Market
Cartons
Carton Bottle Market
Cartons
Carton Serialization Machine Market
Cartons
Global Beverage Carton Packaging Machinery Market