
 Global Resuscitation Devices Market | 2026-2036
Global Resuscitation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Resuscitation Devices Market Foresight
Germany is narrowing the engineering gap between electromechanical and pneumatic resuscitation platforms through precision manufacturing investments in the Ruhr medical technology cluster. Medtronic plc leverages its cardiac rhythm management heritage to sustain leadership in automated external defibrillator platforms across North American emergency medical services. Koninklijke Philips N.V. anchors its resuscitation portfolio on microprocessor-controlled ventilation algorithms that integrate with hospital monitoring networks. ZOLL Medical Corporation specializes in battery-operated mechanical chest compression devices that dominate pre-hospital care protocols.
Resuscitation devices encompass mechanical, electromechanical, and pneumatic systems designed to restore spontaneous circulation and ventilation in patients experiencing cardiac arrest or respiratory failure, typically operating within compression depths of 5-6 centimeters and ventilation rates of 10-12 breaths per minute per advanced cardiac life support protocols. These instruments serve critical care, emergency medicine, and military medical applications where immediate intervention determines survival outcomes. Automated external defibrillators command the largest revenue pool among product types due to regulatory mandates for public access deployment, while mechanical chest compression devices represent the fastest-expanding category as emergency medical services prioritize crew safety during transport. Microprocessor-controlled technology captures disproportionate margin pools through software-driven diagnostic capabilities and real-time feedback mechanisms that reduce operator error.
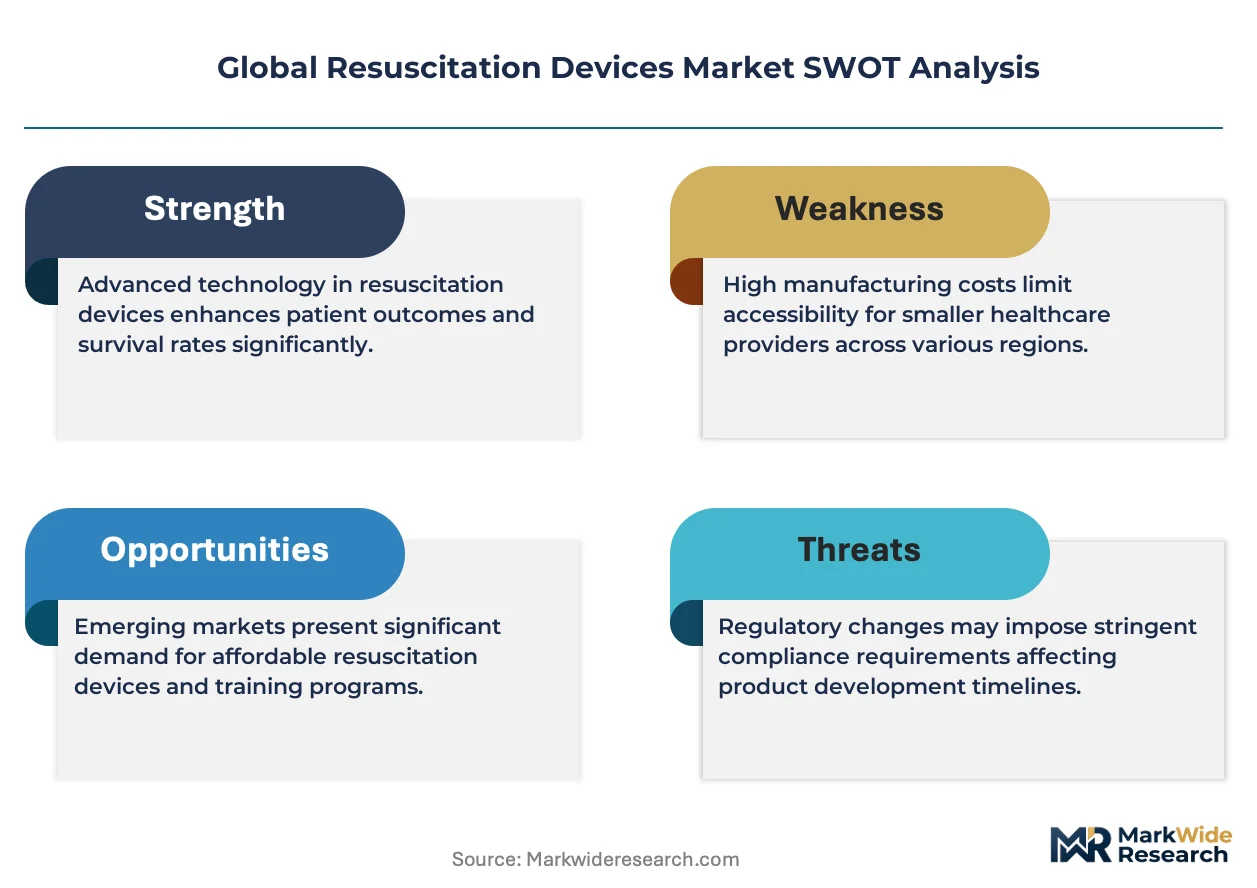
The FDA's 510(k) clearance pathway governs Class II resuscitation device market entry in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for mechanical chest compression systems sold in Europe. ISO 13485 quality management certification and IEC 60601 electrical safety standards constitute baseline compliance thresholds for multinational manufacturers seeking cross-border distribution. Stakeholders must monitor evolving pre-hospital care reimbursement frameworks and emergency response team procurement centralization trends to anticipate demand concentration shifts.
Market Dynamics
Microprocessor-controlled resuscitation platforms are compressing replacement cycles for pneumatic systems across hospital networks, while emergency medical services procurement centralization concentrates purchasing power among fewer regional buyers.
Growth Catalysts
- EU Medical Device Regulation:Enhanced clinical evidence requirements for mechanical chest compression systems accelerate hospital upgrades to compliant electromechanical platforms in Germany and France.
- Ruhr medical technology cluster:Precision manufacturing investments narrow the engineering gap between electromechanical and pneumatic resuscitation platforms, improving device reliability.
- Public access defibrillator mandates:Automated external defibrillator deployment expands across United States emergency response teams, creating replacement demand for aging installed bases.
Market Restraints
- Lithium battery supply concentration:Battery-operated mechanical chest compression devices face input cost volatility from concentrated Asian cell manufacturing.
- FDA 510(k) pathway complexity:Class II premarket notification requirements extend product development cycles for novel ventilation algorithms.
- Manual CPR substitution threat:Low-cost manual resuscitation training programs compete with capital-intensive mechanical systems in budget-constrained municipal services.
Strategic Opportunities
- Military medical applications:Battery-operated mechanical chest compression devices address unmet need in battlefield casualty evacuation protocols.
- Hospital monitoring network integration:Microprocessor-controlled ventilation algorithms converge with electronic health record systems to enable real-time data capture.
- Pre-hospital care reimbursement expansion:Updated emergency medical services funding frameworks in the United States create procurement tailwinds for transport-capable devices.
Industry Challenges
- IEC 60601 electrical safety certification:Multinational manufacturers face extended timeline friction aligning device designs with evolving international standards.
- ISO 13485 quality management integration:Cross-border distribution requires harmonizing production audits across multiple notified body jurisdictions.
- Legacy pneumatic system interoperability:Hospital resuscitation protocol updates demand complex integration pathways with existing compressed gas infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Resuscitation Devices Market |
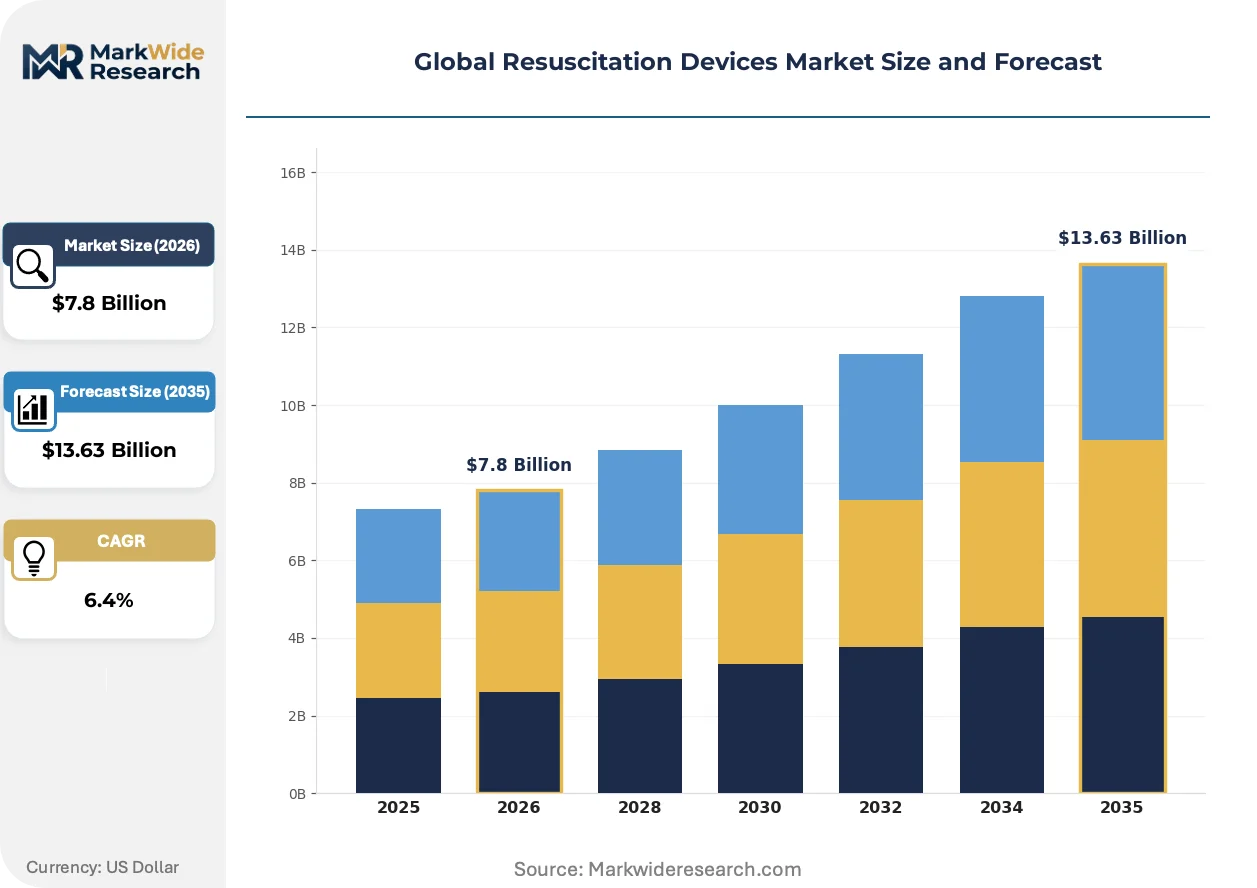
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Resuscitators, Automated External Defibrillators, Mechanical Chest Compression Devices, Infant Resuscitation Devices, Oxygen Resuscitators Technology: Electromechanical, Pneumatic, Microprocessor-Controlled, Battery-Operated, Disposable Application: Emergency Medical Services, Pre-Hospital Care, Ambulatory Surgical Units, Home Healthcare, Sports Medicine End User: Hospitals, Emergency Response Teams, Specialty Clinics, Military Medical Units, Ambulance Services |
| Companies Covered | Medtronic plc, Koninklijke Philips N.V., ZOLL Medical Corporation, Stryker Corporation, Ambu A/S, GE Healthcare, Drägerwerk AG & Co. KGaA, Teleflex Incorporated, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Resuscitation Devices Market Shifts & Advancements
Real-time feedback mechanisms embedded in resuscitation hardware are reducing operator error rates while compressing training requirements for emergency personnel.
Cloud-connected diagnostic modules embedded in automated external defibrillators transmit post-event data to hospital networks for quality review. Emergency medical services in the United States adopt these systems fastest, with fleet-wide deployment timelines compressing from five-year cycles to three. This connectivity layer is virtualizing the traditional service contract model, enabling predictive maintenance and remote software updates that displace on-site technical visits.
The EU Medical Device Regulation imposes post-market surveillance obligations that force manufacturers to maintain active clinical follow-up for mechanical chest compression systems. Device companies must now fund registry studies and periodic safety updates that previously required only passive vigilance. European hospital procurement committees increasingly weight MDR compliance documentation above price in tender evaluations, favoring established suppliers with dedicated regulatory affairs infrastructure.
Consolidated regional purchasing cooperatives now dominate United States emergency medical services equipment acquisition, displacing individual municipal procurement. These cooperatives negotiate multi-year framework agreements that bundle defibrillators, mechanical compression devices, and training services. The concentration of buying power favors vendors with comprehensive service networks and penalizes specialized single-product manufacturers lacking national coverage.
Global Resuscitation Devices Market Segmentation
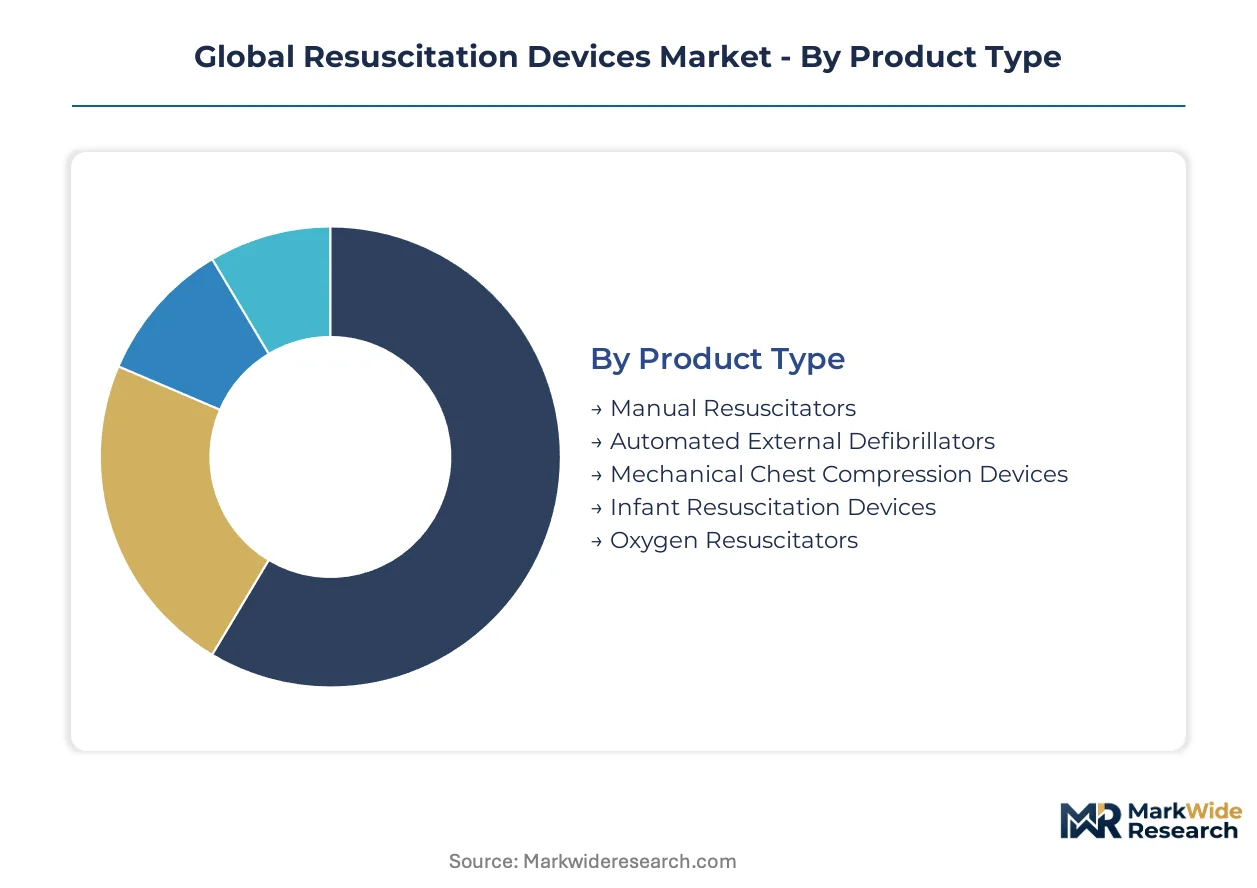
Resuscitation device segmentation reveals divergent technology maturities across clinical settings. Product architecture, power source, and deployment environment each create distinct margin profiles and replacement cycle dynamics that shape vendor strategy.
Product Type:
Mature pneumatic designs coexist with emerging electromechanical platforms across emergency medicine workflows.
- Automated External Defibrillators:These devices deliver biphasic shock waveforms through adhesive electrode pads with voice-guided CPR coaching. Public access mandates in the United States and Germany drive fleet replacement demand as aging installed bases exceed service life limits.
- Mechanical Chest Compression Devices:Battery-powered piston or load-distributing band systems automate 100-120 compressions per minute at 5-6 centimeter depth. Emergency medical services in the United States prioritize these for crew safety during ambulance transport, accelerating procurement.
- Manual Resuscitators:Hand-operated bag-valve-mask systems remain standard in resource-constrained settings.
- Infant Resuscitation Devices:Pressure-limited ventilation circuits address neonatal lung compliance requirements.
- Oxygen Resuscitators:Demand valve and continuous flow systems support pre-oxygenation protocols.
Automated external defibrillators handle the majority of throughput; mechanical chest compression devices are the fastest mover on share.
Technology:
Cost tier stratification separates premium microprocessor platforms from commodity disposable alternatives.
- Microprocessor-Controlled:Real-time feedback algorithms adjust compression depth and ventilation parameters based on impedance and capnography inputs. Hospital networks in Germany favor these for integration with electronic health record systems.
- Battery-Operated:Lithium-ion cell architectures enable 45-60 minute autonomous operation without compressed gas tethering. Military medical units in the United States specify these for battlefield casualty evacuation.
- Electromechanical:Motor-driven piston mechanisms deliver consistent compression mechanics.
- Pneumatic:Compressed gas-powered systems persist in legacy hospital infrastructure.
- Disposable:Single-use components reduce cross-contamination risk in mass casualty scenarios.
Microprocessor-controlled systems command premium pricing; battery-operated configurations are gaining share fastest in pre-hospital segments.
Application:
Customer type concentration varies sharply between institutional purchasers and distributed point-of-care deployers.
- Emergency Medical Services:Regional procurement cooperatives in the United States negotiate multi-year framework agreements bundling devices, training, and maintenance. Centralized purchasing favors vendors with national service networks.
- Pre-Hospital Care:Fire departments and police units require ruggedized, rapid-deployment configurations with minimal training overhead. Updated reimbursement frameworks create procurement tailwinds.
- Ambulatory Surgical Units:Compact footprint devices address space-constrained procedure rooms.
- Home Healthcare:Layperson-operated automated external defibrillators serve high-risk cardiac patients.
- Sports Medicine:Sideline deployment protocols drive demand for portable, weather-resistant units.
Emergency medical services absorb the largest procurement volume; pre-hospital care is expanding most quickly on policy support.
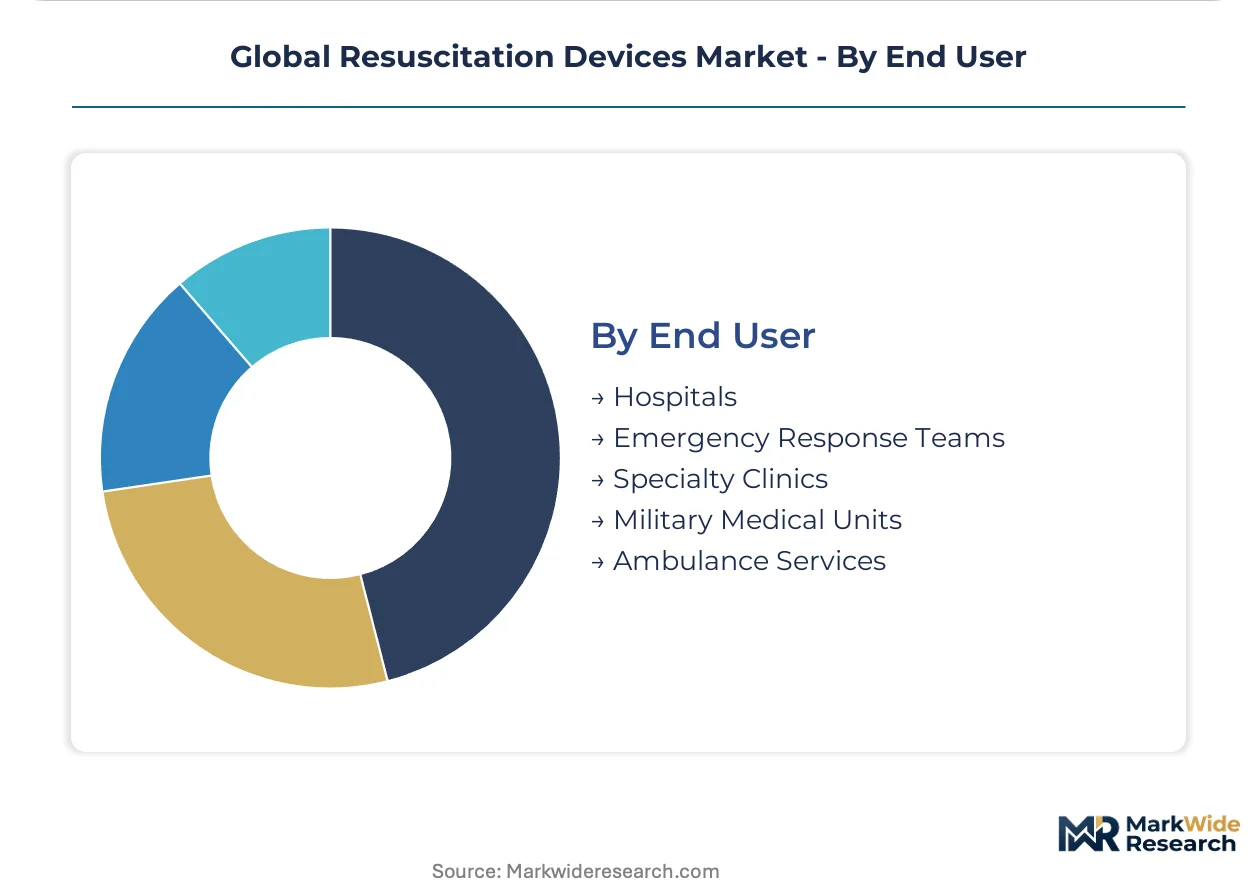
End User:
Volume concentration clusters in tertiary acute care while margin pools concentrate in specialized deployers.
- Hospitals:Resuscitation protocol updates in Germany drive replacement of pneumatic systems with electromechanical platforms. ICU and emergency department integration requirements favor microprocessor-controlled ventilation.
- Emergency Response Teams:Municipal and regional agencies standardize on interoperable device platforms to simplify training and logistics. Consolidated purchasing cooperatives concentrate negotiating leverage.
- Specialty Clinics:Cardiac catheterization labs require defibrillator-integrated monitoring systems.
- Military Medical Units:Battery-operated mechanical compression devices address austere environment constraints.
- Ambulance Services:Transport-capable systems prioritize crew safety and patient stabilization.
Hospitals represent the dominant installed base; emergency response teams show the steepest expansion trajectory on fleet modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States emphasizes pre-hospital fleet modernization through consolidated procurement cooperatives. Germany concentrates on hospital protocol upgrades integrating microprocessor-controlled platforms with electronic health record systems.
United States
Emergency medical services procurement centralization drives demand for transport-capable mechanical chest compression devices. The FDA's 510(k) clearance pathway governs Class II device market entry, extending development cycles for novel ventilation algorithms. Regional purchasing cooperatives in the Midwest and Southeast negotiate multi-year framework agreements bundling devices, training, and maintenance services.
Germany
Hospital resuscitation protocol updates accelerate replacement of pneumatic systems with electromechanical alternatives. The EU Medical Device Regulation imposes enhanced clinical evidence requirements for mechanical chest compression systems, favoring established suppliers with dedicated regulatory infrastructure. The Ruhr medical technology cluster attracts precision manufacturing investments narrowing the engineering gap between platform types.
Japan
Aging demographics expand demand for automated external defibrillators in public access settings. METI guidelines on medical device software validation shape product development priorities for algorithm-driven feedback systems. The Kansai region around Osaka hosts concentrated distribution networks serving acute care facilities.
China
Hospital infrastructure expansion in tier-two cities creates procurement volume for entry-level electromechanical platforms. NMPA registration requirements for Class II resuscitation devices align with international IEC 60601 electrical safety standards. The Yangtze River Delta manufacturing base supplies lithium battery components for portable compression systems.
United Kingdom
NHS ambulance trust fleet standardization programs prioritize interoperable device platforms. MHRA post-market surveillance obligations mirror EU MDR requirements for mechanical chest compression systems. The Southeast England corridor concentrates emergency response training facilities and service provider networks.
Global Resuscitation Devices Market Competitive Landscape
Capability concentration sits with heritage cardiac rhythm management specialists; scale advantage sits with diversified medical technology conglomerates. The vendor base separates into three tiers: integrated critical care platforms, focused resuscitation specialists, and regional equipment fabricators. Dominant competitive moves include strategic partnerships for monitoring network integration and portfolio diversification into adjacent emergency medicine categories.
Within the integrated platform tier, Medtronic plc and Koninklijke Philips N.V. occupy positions anchored by cardiac rhythm management heritage and hospital monitoring network reach respectively. ZOLL Medical Corporation exemplifies the focused specialist archetype, concentrating resources on battery-operated mechanical compression systems. These three entities collectively represent the capability-scale spectrum defining competitive positioning.
| Leading Market Players |
|---|
| Medtronic plc |
| Koninklijke Philips N.V. |
| ZOLL Medical Corporation |
| Stryker Corporation |
| Ambu A/S |
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Teleflex Incorporated |
| Getinge AB |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta battery manufacturing cluster anchors cost structures for portable compression systems, with lithium cell capacity dynamics transmitting directly to OEM pricing power in mechanical chest compression devices. Downward pressure on mid-tier electromechanical platforms intensifies as Chinese cell producers expand cylindrical format output.
Pricing Analysis
Geographic price spreads of 35-50% separate German hospital procurements from municipal EMS acquisitions in the United States. Three-tier pricing structure across premium microprocessor-controlled, standard electromechanical, and economy pneumatic levels reflects FDA 510(k) certification investment recovery timelines. Pricing pressure stems from consolidated regional purchasing cooperatives extracting volume discounts through multi-year framework agreements. Emergency response teams exhibit highest price sensitivity; cardiac catheterization labs show lowest.
Supply Chain Analysis
Contract manufacturing concentrates among Shenzhen and Suzhou-based EMS providers with ISO 13485-certified medical device lines. Component sourcing draws from China for lithium-ion cells, Germany for precision piston motors, and Japan for capacitive sensor modules. Single-source vulnerability in battery management system ICs creates disruption exposure. Distribution runs through hospital group purchasing organizations and EMS cooperative procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resuscitation device economics pivot on platform interoperability with electronic health record ecosystems, as hospital network integration requirements reshape competitive moats around data architecture rather than hardware alone.
For Market Incumbents: Harden regulatory affairs infrastructure against EU MDR post-market surveillance obligations through dedicated clinical follow-up funding. Deepen backward integration into battery pack assembly to offset lithium cell cost volatility from Asian suppliers. For New Entrants and Emerging Players: Establish a beachhead in military medical applications where battery-operated mechanical compression devices face limited established vendor presence. Target austere environment specifications with ruggedized, rapid-deployment configurations bypassing hospital procurement complexity. For Investors and Strategic Acquirers: Long-term, this sits as a software-layer play because microprocessor-controlled ventilation algorithms capture disproportionate margin pools through recurring diagnostic module subscriptions. Monitor FDA 510(k) clearance velocity for novel feedback algorithms as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Investment | European hospital procurement committees weight clinical evidence documentation above price in tender evaluations. |
| Cloud-Connected Diagnostic Module | Remote software updates displace on-site technical visits and virtualize service contract economics. |
| Hospital System Partnership | Electronic health record integration requirements favor vendors with established IT infrastructure relationships. |
| Reimbursement Strategy | Updated EMS funding frameworks in the United States create procurement tailwinds for transport-capable devices. |
| CE Marking Pathway | Enhanced clinical evidence requirements accelerate competitive displacement of pneumatic legacy platforms. |
Research Methodology
Cross-validation between primary interviews with emergency medical services procurement directors, hospital biomedical engineers, GPO contracts managers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and EMS cooperative purchasing records. Bottom-up installed base modeling triangulates with top-down expenditure flow analysis.
Calibration against historical replacement cycle data and procurement centralization trends shapes the analytical framework across the analysis window. Segmentation dimensions include product architecture, power source configuration, deployment environment, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections incorporating protocol update timelines and reimbursement framework evolution.
Sensitivities concentrate around lithium battery supply disruptions, FDA review timeline extensions for novel algorithms, and EU MDR implementation enforcement variance. Quarterly review of 510(k) clearance velocity, notified body audit backlogs, and EMS cooperative purchasing volume is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Transcatheter Heart Valve Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market