
 Intravenous Catheters Market | 2026-2036
Intravenous Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Intravenous Catheters Market Outlook
Aftermarket service revenue is tilting toward catheter placement training and vascular access team consulting as hospitals seek to reduce central line-associated bloodstream infections. B. Braun leverages its integrated vascular access portfolio to sustain recurring service contracts with large health systems. ICU Medical competes through closed-system transfer device compatibility, while Teleflex anchors its position via Arrow catheter technology leadership in critical care segments.
Intravenous catheters are hollow, flexible tubes manufactured from polyurethane, silicone, or polyvinyl chloride, typically ranging from 14 to 24 gauge, designed for percutaneous insertion into peripheral or central veins to enable fluid administration, medication delivery, blood sampling, or parenteral nutrition. Peripheral catheters dominate procedure volume due to their use in short-term infusion therapy across emergency departments and general wards, though central venous catheters command premium pricing and higher margins through specialized tip positioning and multi-lumen configurations. Hospital end users represent the most concentrated demand pool, while ambulatory surgical centers represent the fastest-growing site of care as same-day procedures expand.
FDA premarket notification requirements under 510(k) pathways govern catheter safety claims, while OSHA Bloodborne Pathogens Standards mandate engineered sharps injury protections that shape product design specifications. The European MDR intensifies clinical evidence requirements for extended-dwell catheters, creating compliance barriers for smaller manufacturers. Stakeholders must monitor evolving safety performance benchmarks and reimbursement alignment for vascular access specialty teams as determinants of portfolio prioritization.
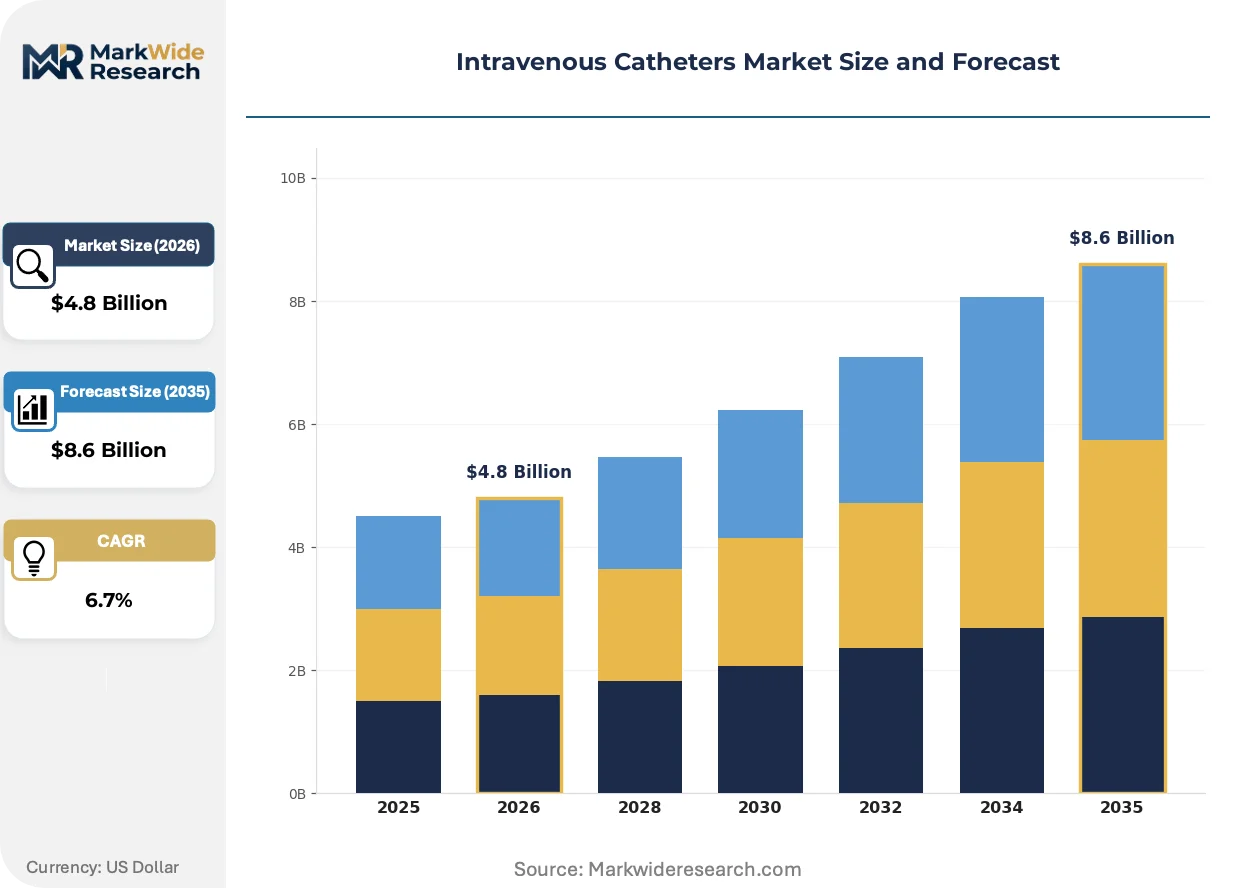
Market Dynamics
OSHA needlestick prevention mandates are compressing conventional catheter designs while safety-engineered alternatives capture procedural volume in hospital emergency departments and oncology infusion centers.
Growth Catalysts
- Emergency Medicine Procedural Volume:Rising trauma admissions and rapid fluid resuscitation protocols in United States Level I trauma centers are expanding peripheral catheter utilization.
- REACH Chemical Compliance:European manufacturers reformulating polyurethane blends to eliminate phthalate plasticizers are unlocking extended-dwell catheter approvals under MDR clinical evidence pathways.
- Closed-System Transfer Integration:Oncology pharmacies are standardizing on needle-free connector compatibility to align with USP 800 hazardous drug handling requirements.
Market Restraints
- Medical-Grade Silicone Volatility:Supply concentration among Asian polymer producers creates input cost instability for silicone catheter manufacturers.
- MDR Clinical Evidence Burden:Extended-dwell central venous catheters face prolonged approval timelines as notified bodies demand prospective safety data under European MDR Article 61.
- Peripheral Insertion Depth Limitations:Anatomical constraints in obese patient populations restrict midline catheter placement success rates below 85% in bariatric units.
Strategic Opportunities
- India Ambulatory Surgical Center Expansion:Government PLI scheme incentives for domestic medical device manufacturing are reducing import dependency for short-term infusion devices.
- Antimicrobial Surface Convergence:Integration of chlorhexidine-impregnated polymers with power-injection compatibility is creating premium positioning in ICU vascular access.
- OSHA Compliance Mandate Tailwind:Bloodborne Pathogens Standard updates requiring active safety mechanisms are accelerating replacement cycles in United States outpatient dialysis centers.
Industry Challenges
- Vascular Access Specialist Certification Bottlenecks:Limited availability of INS-certified infusion nurses is delaying hospital vascular access team expansion.
- Legacy EMR Integration Friction:Smart catheter connectivity protocols require capital-intensive interoperability upgrades with existing Epic or Cerner installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravenous Catheters Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peripheral, Central Venous, Lactated Ringer's, Specialty Material: Polyurethane, Polyvinyl Chloride, Silicone, Nylon End User: Hospitals, Ambulatory Surgical Centers, Homecare, Clinics Application: Fluid Administration, Blood Transfusion, Nutrition Delivery, Medication |
| Companies Covered | Becton Dickinson, B. Braun, Teleflex, ICU Medical, Terumo, Nipro, Medtronic, Boston Scientific, Vygon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravenous Catheters Market Strategic Shifts
Catheter technology is converging around real-time placement verification and antimicrobial protection, while procurement patterns favor integrated vascular access service contracts over discrete device purchasing.
Ultrasound-guided peripheral catheter insertion is virtualizing anatomical landmark assessment in emergency departments. United States academic medical centers are deploying portable point-of-care ultrasound as standard equipment for difficult-access patients. This capability compression is reducing central line dependency for intermediate-duration infusion therapy.
European MDR Article 10 post-market surveillance requirements are intensifying clinical follow-up obligations for extended-dwell devices. Manufacturers must now maintain prospective registries tracking thrombosis and infection events across catheter lifecycles. Central venous access devices face the steepest compliance cost increases as notified bodies demand real-world evidence portfolios.
Hospital supply chain consolidation is compressing vendor panels toward single-source vascular access agreements. Integrated delivery networks in the United States are bundling catheter placement training with device procurement to reduce CLABSI penalties. This contractual unification is most advanced in Medicare Advantage–dominated markets where readmission risk contracts concentrate purchasing authority.
Intravenous Catheters Market Segmentation
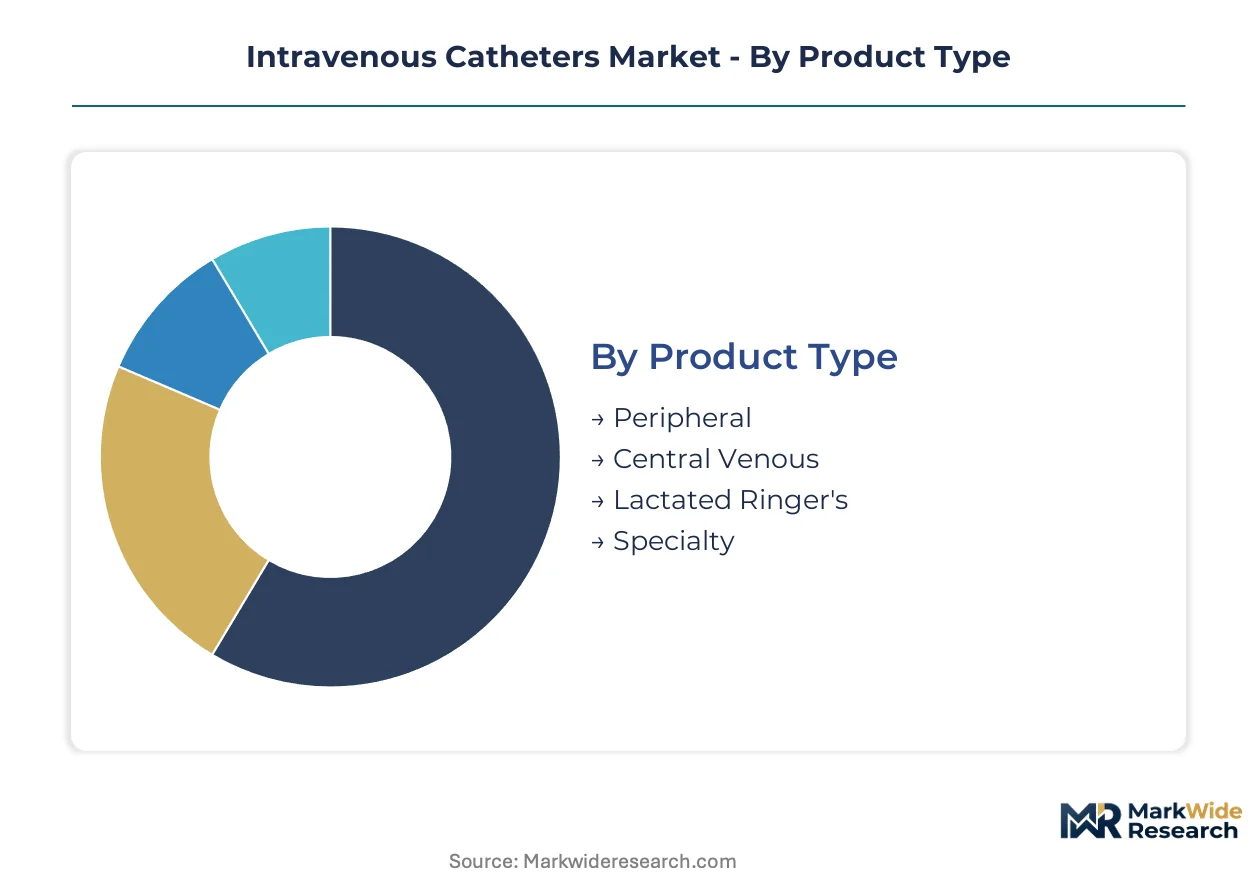
Catheter segmentation reveals divergent replacement cycles that directly shape inventory planning and service contract structures. Cycle times range from hours for emergency peripheral placement to months for tunneled central devices, creating distinct margin profiles across product categories.
Product Type:
Cycle times compress from multi-month central venous dwell periods to single-shift peripheral usage, fragmenting procurement rhythms across hospital departments.
- Peripheral:Short-term polyurethane or Teflon devices inserted into superficial veins of the hand or forearm for infusions under 96 hours. United States emergency departments consume the highest procedural volumes as trauma protocols mandate immediate vascular access for fluid resuscitation.
- Central Venous:Multi-lumen silicone or polyurethane catheters terminating in the superior vena cava for extended chemotherapy, parenteral nutrition, or hemodynamic monitoring. Oncology infusion centers in Medicare Advantage–dominated markets concentrate demand as bundled payment models incentivize CLABSI reduction.
- Lactated Ringer's:Pre-filled closed-system devices designed for rapid crystalloid administration in surgical and trauma settings. Ambulatory surgical centers favor these configurations for same-day procedure efficiency.
- Specialty:Midline, peripherally inserted central catheter (PICC), and dialysis-specific designs addressing anatomical challenges or high-flow requirements. Vascular access specialty teams drive adoption as INS certification standards elevate placement expertise requirements.
Peripheral catheters anchor the volume base while specialty designs gain share at the steepest rate.
Material:
Material selection trades off mechanical performance against biocompatibility and regulatory compliance burden, with European REACH mandates accelerating formulation shifts.
- Polyurethane:High tensile strength polymer enabling thinner catheter walls with larger internal diameters for power injection compatibility. Manufacturers reformulating phthalate-free blends under ECHA guidance are securing MDR approval advantages for extended-dwell indications.
- Polyvinyl Chloride:Cost-optimized standard for short-term peripheral devices where flexibility and kink resistance matter less than unit economics. Indian domestic production under PLI scheme incentives is displacing imported PVC catheter volumes.
- Silicone:Soft, thromboresistant polymer preferred for long-term central access and neonatal applications. Supply concentration among Asian polymer producers creates input cost volatility that compresses margins for specialized manufacturers.
- Nylon:Rigid, high-strength material limited to specific introducer sheaths and arterial applications where column strength is paramount. Niche utilization restricts this segment to cardiovascular procedure suites.
Polyurethane commands the premium tier while PVC maintains the highest shipment volumes.
End User:
Site-of-care migration is redistributing catheter demand from inpatient wards toward outpatient and home settings, altering packaging and training requirements.
- Hospitals:Integrated delivery networks bundling device procurement with vascular access team consulting to reduce CLABSI penalties. United States academic medical centers are standardizing ultrasound-guided placement protocols across emergency and critical care departments.
- Ambulatory Surgical Centers:Fastest-expanding site of care as same-day procedure volumes rise and anesthesia protocols shorten recovery times. Pre-filled closed-system designs dominate procurement to minimize pharmacy compounding overhead.
- Homecare:Infusion therapy displacement enabling chemotherapy and parenteral nutrition administration outside institutional settings. Patient or caregiver training requirements elevate demand for safety-engineered devices with passive needlestick protection.
- Clinics:Physician office-based infusion centers serving stable oncology and immunology patients on recurring schedules. These settings favor midline catheters bridging the gap between peripheral convenience and central durability.
Hospitals retain the revenue concentration while ambulatory surgical centers climb the fastest.
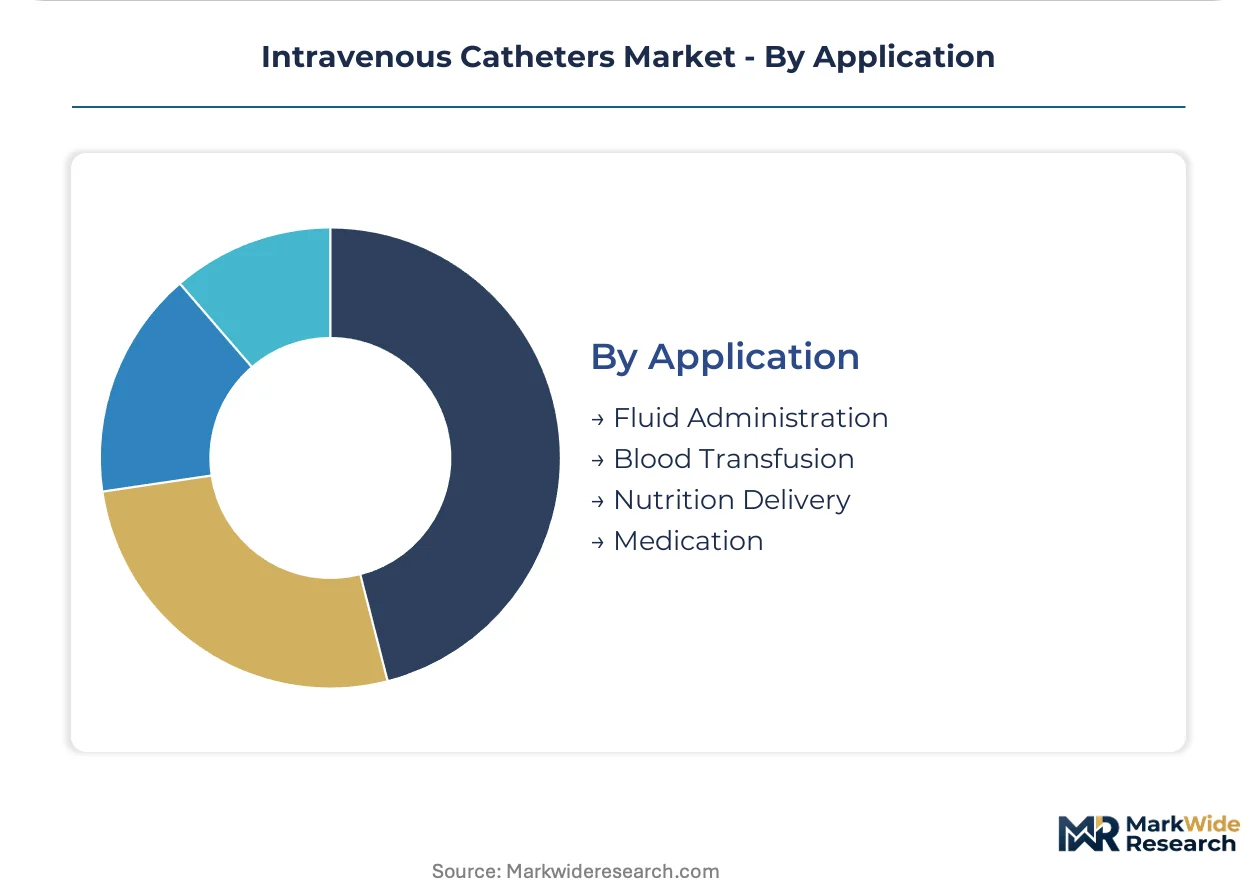
Application:
Application mix shifts with therapeutic innovation, as biologic drug delivery protocols reshape vascular access specifications.
- Fluid Administration:Crystalloid and colloid resuscitation in trauma, surgery, and sepsis management. Level I trauma centers in the United States drive specification demands for large-bore peripheral and intraosseous alternatives.
- Blood Transfusion:Large-gauge devices with filtered tubing sets for rapid red cell and plasma delivery. Transfusion service protocols are standardizing on needle-free connector compatibility to reduce nursing exposure risk.
- Nutrition Delivery:Central venous access for parenteral nutrition in intestinal failure, critical illness, or oncology. Extended-dwell requirements intensify MDR clinical evidence demands for thrombosis and infection tracking.
- Medication:Broadest application spanning antibiotics, analgesics, chemotherapy, and biologics. USP 800 hazardous drug handling mandates are concentrating oncology pharmacy procurement on closed-system transfer device compatibility.
Medication delivery anchors the volume base while nutrition delivery gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States hospitals prioritize safety-engineered designs with OSHA-mandated needlestick protection, while European procurement emphasizes MDR-compliant extended-dwell materials. Emerging markets concentrate demand in cost-optimized short-term devices for high-volume emergency settings.
United States
Level I trauma centers in Baltimore and Houston drive peripheral catheter utilization through rapid fluid resuscitation protocols. OSHA Bloodborne Pathogens Standard enforcement accelerates replacement cycles in outpatient dialysis centers across the Sun Belt. The Cleveland Clinic vascular access program anchors ultrasound-guided placement standardization across academic medical centers.
Germany
Extended-dwell central venous catheters dominate oncology infusion demand in Munich and Heidelberg university hospitals. ECHA REACH compliance mandates phthalate-free polyurethane reformulation for MDR Article 61 approval pathways. The Baden-Württemberg medical technology cluster concentrates catheter manufacturing and notified body consulting expertise.
India
Ambulatory surgical centers in Delhi-NCR and Mumbai expand same-day procedure volumes requiring short-term infusion devices. The PLI scheme for domestic medical device manufacturing reduces import dependency for PVC catheters in Gujarat production zones. Hyderabad's health technology corridor attracts catheter assembly operations targeting Southeast Asian export markets.
Japan
Silicone catheter demand concentrates in neonatal intensive care units across Tokyo and Osaka metropolitan hospitals. PMDA clinical evidence requirements for extended-dwell devices align with MDR-equivalent safety tracking mandates. The Kansai medical device cluster specializes in thromboresistant polymer formulations for long-term vascular access.
Brazil
Emergency department volume in São Paulo and Rio de Janeiro public hospitals sustains high peripheral catheter consumption. ANVISA post-market surveillance requirements intensify for imported central venous devices. The São Paulo state medical industrial park hosts regional distribution hubs serving Mercosur oncology centers.
Intravenous Catheters Market Competitive Environment
Capability concentration sits with integrated vascular access specialists; scale advantage sits with diversified medical device conglomerates. The market structures around three tiers: full-portfolio manufacturers bundling devices with placement training, component-focused suppliers selling into private-label arrangements, and regional fabricators serving price-sensitive procurement. Dominant competitive moves include vertical integration into polymer compounding and exclusive service contracting with integrated delivery networks.
Within the integrated vascular access tier, B. Braun and Teleflex exemplify full-portfolio positioning through recurring service contracts with large health systems. ICU Medical occupies a specialized position emphasizing closed-system transfer compatibility for oncology pharmacy integration. These three anchors represent divergent strategic bets on whether device margins or service revenue will dominate future profitability.
| Leading Market Players |
|---|
| Becton Dickinson |
| B. Braun |
| Teleflex |
| ICU Medical |
| Terumo |
| Nipro |
| Medtronic |
| Boston Scientific |
| Vygon |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Rotterdam container freight corridors transmit polymer cost volatility directly into catheter pricing tiers, as medical-grade silicone concentration among Asian producers amplifies margin compression for European manufacturers while integrated delivery networks in the United States extract volume discounts through consolidated procurement.
Pricing Analysis
Long-term offtake agreements between polyurethane compounders and catheter manufacturers anchor pricing stability for extended-dwell devices, while spot purchasing dominates short-term peripheral catheter transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) pathway complexity, with antimicrobial surface coatings and power-injection compatibility commanding measurable premiums. Pricing pressure stems from Indian domestic PVC production under PLI scheme incentives displacing imported volumes. Ambulatory surgical centers exhibit highest price sensitivity due to thin procedure margins, while academic medical centers prioritize safety-engineered designs regardless of unit cost.
Supply Chain Analysis
Medical-grade silicone feedstock draws from concentrated polymer production in Japan, South Korea, and select Chinese chemical parks, creating input dependency for long-term central venous catheter manufacturers. Polyurethane resin and phthalate-free plasticizer formulations represent critical formulation inputs alongside precision extrusion equipment. Single-source vulnerability in silicone supply creates exposure to regional logistics disruptions or export restriction events. Distribution runs through hospital group purchasing organizations and integrated delivery network consolidated vendor panels, with direct-to-hospital contracting gaining share among full-portfolio manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States, as hospital system mergers compress vendor panels toward single-source vascular access agreements that bundle device procurement with placement training services.
For Market Incumbents: Insulate service revenue streams by embedding vascular access team consulting contracts within device procurement agreements, countering price erosion from emerging regional fabricators in India and Southeast Asia. Secure backward integration into phthalate-free polyurethane compounding to defend margin position against REACH compliance cost inflation. Prioritize MDR Article 61 clinical evidence investments to maintain extended-dwell catheter approval advantages. For New Entrants and Emerging Players: Midline catheter placement in United States bariatric units represents the most penetrable entry point, as anatomical constraints limit incumbent success rates below 85% and create unmet demand for specialized designs. Indian ambulatory surgical centers under PLI scheme expansion offer second-mover positioning for cost-optimized PVC peripheral devices. Partner with regional distribution hubs in São Paulo or Hyderabad to bypass established GPO channel control. For Investors and Strategic Acquirers: Antimicrobial surface technology specialists with chlorhexidine-impregnated polymer IP represent priority acquisition targets, as ICU infection reduction mandates accelerate premium catheter adoption. Long-term viability hinges on regulatory compliance capabilities rather than manufacturing scale alone. Monitor OSHA Bloodborne Pathogens Standard enforcement intensity across Sun Belt dialysis centers as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Article 61 Clinical Evidence Investment | Prospective safety registries satisfy notified body demands for extended-dwell approvals in Germany and France. |
| Phthalate-Free Polyurethane Reformulation | ECHA REACH compliance unlocks premium positioning for oncology infusion centers in European university hospitals. |
| Ultrasound-Guided Placement Training Integration | Cleveland Clinic protocols reduce central line dependency and anchor recurring service contracts with academic medical centers. |
| Closed-System Transfer Device Compatibility | USP 800 hazardous drug alignment secures oncology pharmacy procurement against ICU Medical positioning. |
| PLI Scheme Domestic Manufacturing | Gujarat production zones displace imported PVC catheter volumes for Delhi-NCR ambulatory surgical centers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with vascular access specialists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract records, and OSHA enforcement action reports. Bottom-up catheter shipment estimates by product type and end user triangulated against top-down market sizing from polymer consumption data and medical device trade flows.
Forecast inputs encompassed procedural volume trajectories across emergency medicine and oncology, material substitution patterns between polyurethane and silicone, and site-of-care migration from inpatient wards toward ambulatory settings. Segmentation dimensions modeled included catheter type, material formulation, end-user facility category, and application purpose. CAGRs derived from regression analysis of historical procedural growth rates against demographic and disease prevalence projections, with REACH compliance timelines and OSHA mandate implementation schedules incorporated as regulatory scenario variables.
Practitioners should monitor MDR notified body backlog durations, silicone polymer spot price movements, and integrated delivery network merger announcements for early signals of forecast revision. Cross-checking against CMS Medicare vascular access procedure volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Global Stents Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Blood Pressure Transducers Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Cardiac Sutures Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Intravascular Ultrasound Market