
 Absorbable Nasal Implant Market | 2026-2036
Absorbable Nasal Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbable Nasal Implant Market Outlook
Hospital procurement consortiums in North America and Western Europe are rewriting purchasing criteria for absorbable nasal implants, shifting toward bundled contracts that include post-operative monitoring. Spirox leverages its focused ENT portfolio to sustain direct-to-physician engagement across academic medical centers. Johnson & Johnson anchors its position through backward integration into collagen processing, while Stryker Corporation competes on instrument compatibility with its broader sinus surgery platforms.
An absorbable nasal implant is a bioresorbable polymeric or protein-based scaffold inserted into the nasal cavity to maintain patency, deliver medication, or support tissue regeneration following functional endoscopic sinus surgery or septoplasty, typically degrading through hydrolysis within 30 to 90 days. These devices serve the primary commercial purpose of reducing synechiae formation and sustaining surgical outcomes without requiring secondary removal procedures. Collagen-based formulations currently occupy the premium tier due to established hemostatic properties and physician familiarity, while poly-L-lactic acid variants are gaining traction in indication expansion for longer-duration structural support. Polycaprolactone segments navigate cost-sensitive clinic environments where extended degradation profiles align with polyp management protocols requiring sustained corticosteroid elution.
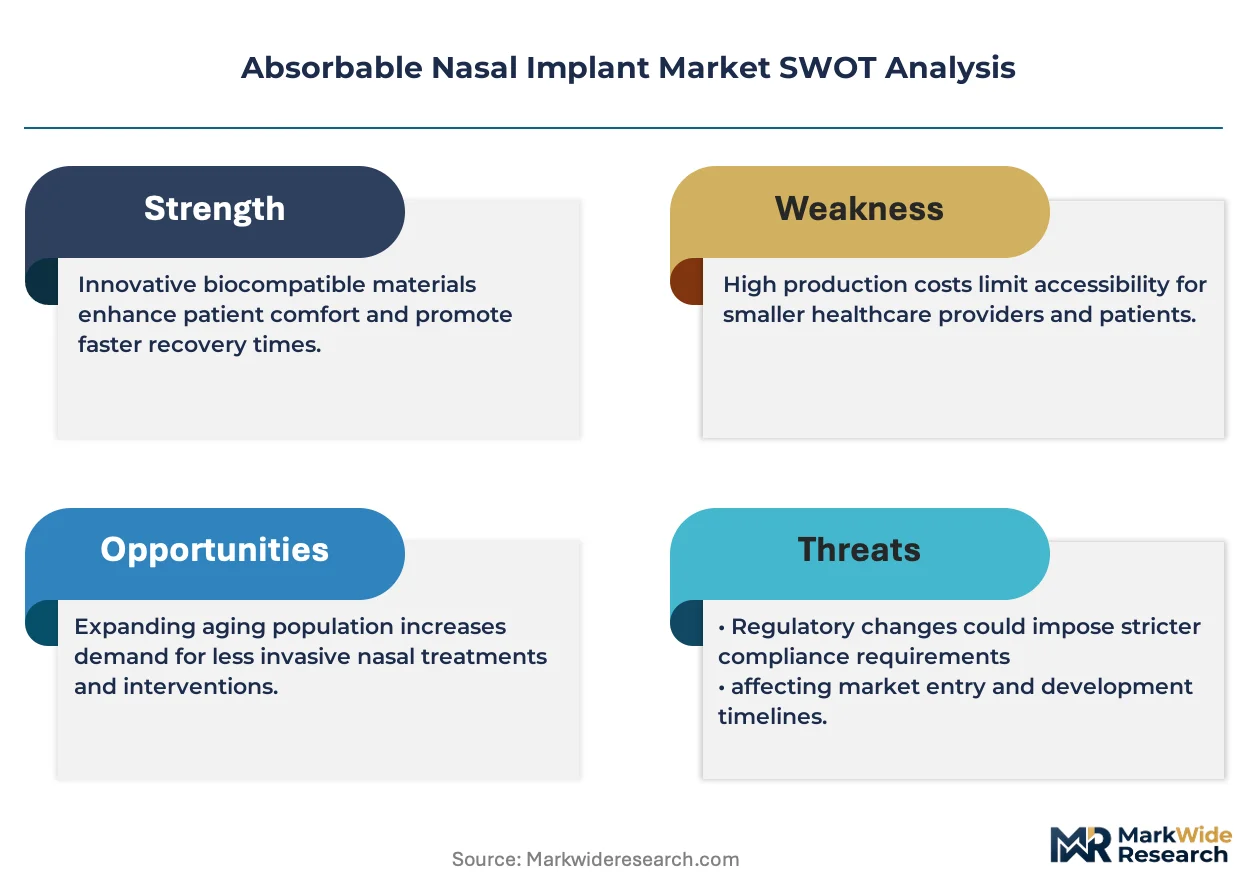
FDA 510(k) premarket notification requirements and the EU MDR's reinforced clinical evaluation obligations are forcing manufacturers to generate implant-specific bioresorption kinetic data beyond generic material master files. Japan's PMDA maintains distinct QMS inspection protocols for absorbable polymer devices that extend approval timelines relative to non-resorbable metallic nasal stents. Stakeholders must monitor evolving reimbursement thresholds for same-day sinus procedures as ambulatory surgical centers in the United States recalibrate implant formularies around total episode cost rather than device price alone.
Market Dynamics
Hospital procurement consortiums in the United States and Germany are rewriting purchasing criteria for absorbable nasal implants, shifting toward bundled contracts that include post-operative monitoring and degradable scaffold performance guarantees rather than discrete device pricing alone.
Growth Catalysts
- FDA 510(k) pathway maturation:Streamlined premarket notification frameworks for polymeric nasal scaffolds reduce time-to-market for resorbable implant innovators, accelerating clinical adoption across ambulatory surgical centers.
- Collagen hemostatic properties:Established physician familiarity with protein-based formulations drives preference in academic medical centers performing complex functional endoscopic sinus surgery.
- Metropolitan hospital clusters:Concentrated demand in United States, German, and Japanese urban centers sustains procedure volumes for nasal obstruction correction without geographic dilution.
Market Restraints
- Lactide monomer price volatility:Poly-L-lactic acid feedstock costs fluctuate with agricultural commodity cycles, compressing margin predictability for manufacturers of extended-duration structural support variants.
- EU MDR clinical evaluation obligations:Reinforced bioresorption kinetic documentation requirements extend regulatory timelines and inflate compliance expenditure for polymeric nasal scaffold submissions.
- Non-resorbable metallic stent substitution:Japan's PMDA maintains distinct QMS inspection protocols that favor shorter approval pathways for permanent nasal stents in specific indication categories.
Strategic Opportunities
- Polycaprolactone polyp management protocols:Extended degradation profiles align with sustained corticosteroid elution requirements in cost-sensitive clinic environments, opening indication expansion beyond post-surgical patency maintenance.
- Same-day sinus procedure reimbursement thresholds:United States ambulatory surgical centers recalibrating implant formularies around total episode cost create white space for value-engineered resorbable formulations.
- Instrument compatibility convergence:Integration with broader sinus surgery platforms enables cross-selling opportunities for manufacturers possessing endoscopic navigation and powered instrumentation portfolios.
Industry Challenges
- Bioresorption kinetic standardization:Absence of harmonized ISO protocols for in-vivo degradation rate measurement forces manufacturers to duplicate testing across FDA, PMDA, and EU MDR submission packages.
- Post-operative monitoring infrastructure:Bundled contract requirements demand investment in remote patency assessment capabilities and patient-reported outcome capture systems that strain legacy device company service models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbable Nasal Implant Market |
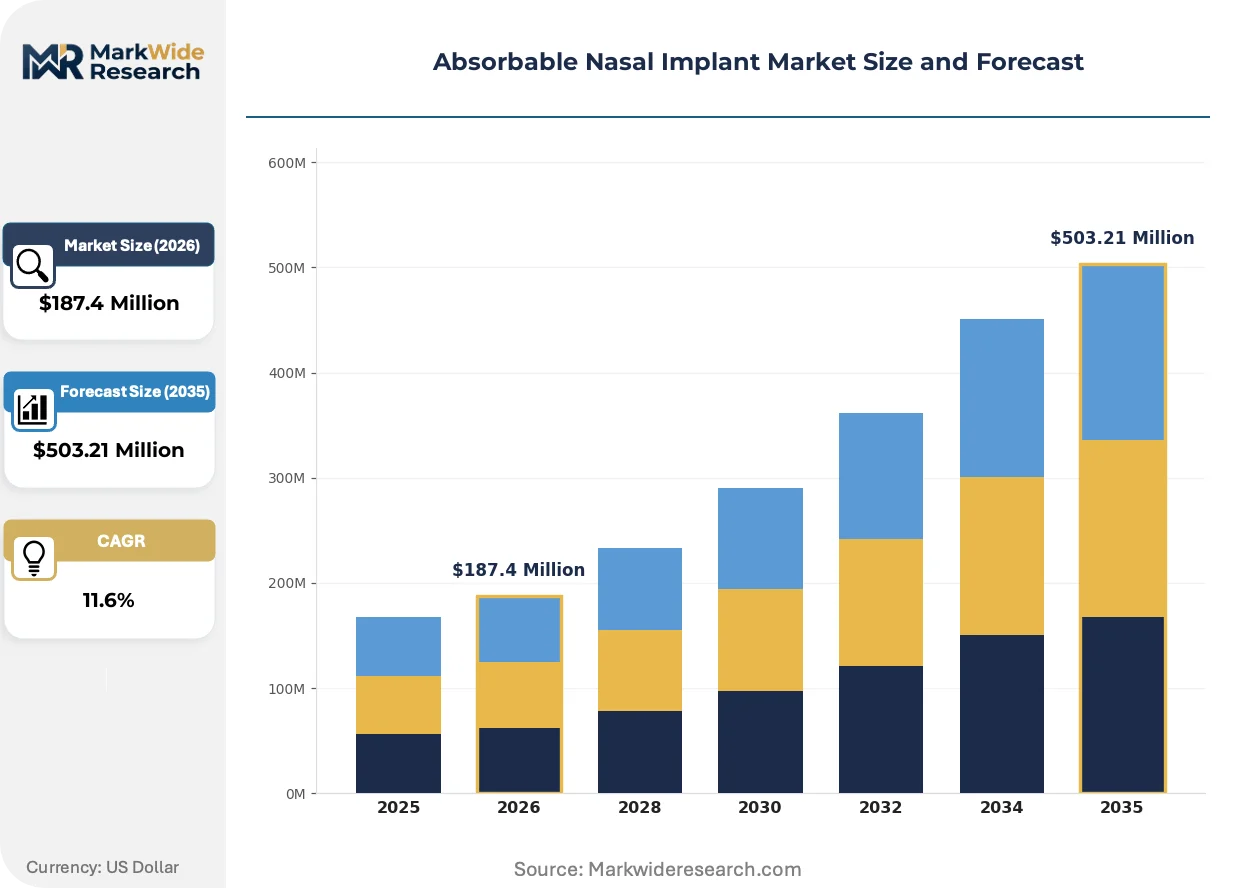
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen-Based, Polycaprolactone, Gelatin, Poly-L-Lactic Acid Indication: Nasal Obstruction, Sinusitis, Polyp Removal, Allergy Management Delivery Mode: Injectable, Implantable, Nasal Sprays, Tablets End User: Clinics, Hospitals, Surgical Centers, Outpatient Facilities |
| Companies Covered | Spirox, Johnson & Johnson, Stryker Corporation, Acclarent, ArthroCare Corporation, Smith & Nephew, Pfizer, Mentor Worldwide, Intersect ENT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbable Nasal Implant Market Strategic Shifts
Computational modeling of polymer hydrolysis rates is virtualizing traditional empirical testing protocols, compressing development cycles while regulatory agencies demand richer biocompatibility datasets than ever before.
Polycaprolactone-corticosteroid composite formulations are virtualizing the standard of care for chronic rhinosinusitis with nasal polyps, enabling sustained drug elution over 60-90 day degradation windows. Outpatient ENT clinics in Germany and the United States are adopting these systems for polyp recurrence prevention, collapsing the historical separation between mechanical scaffolding and pharmaceutical intervention into single-procedure solutions.
EU MDR's reinforced clinical evaluation obligations are mandating implant-specific bioresorption kinetic data beyond generic material master files, forcing manufacturers to establish dedicated in-vivo testing facilities or contract with specialized European CROs. Poly-L-lactic acid variants face the steepest compliance burden due to their longer degradation profiles, with notified bodies in Germany and the Netherlands applying heightened scrutiny to extended-duration structural support claims.
Ambulatory surgical center buying committees are consolidating implant formularies around total episode cost metrics, displacing physician preference items that lack economic outcome documentation. This concentration is most visible in United States metropolitan markets where hospital-owned ASCs now require vendor participation in bundled payment pilots, favoring suppliers capable of delivering post-operative monitoring infrastructure alongside degradable scaffolds.
Absorbable Nasal Implant Market Segmentation
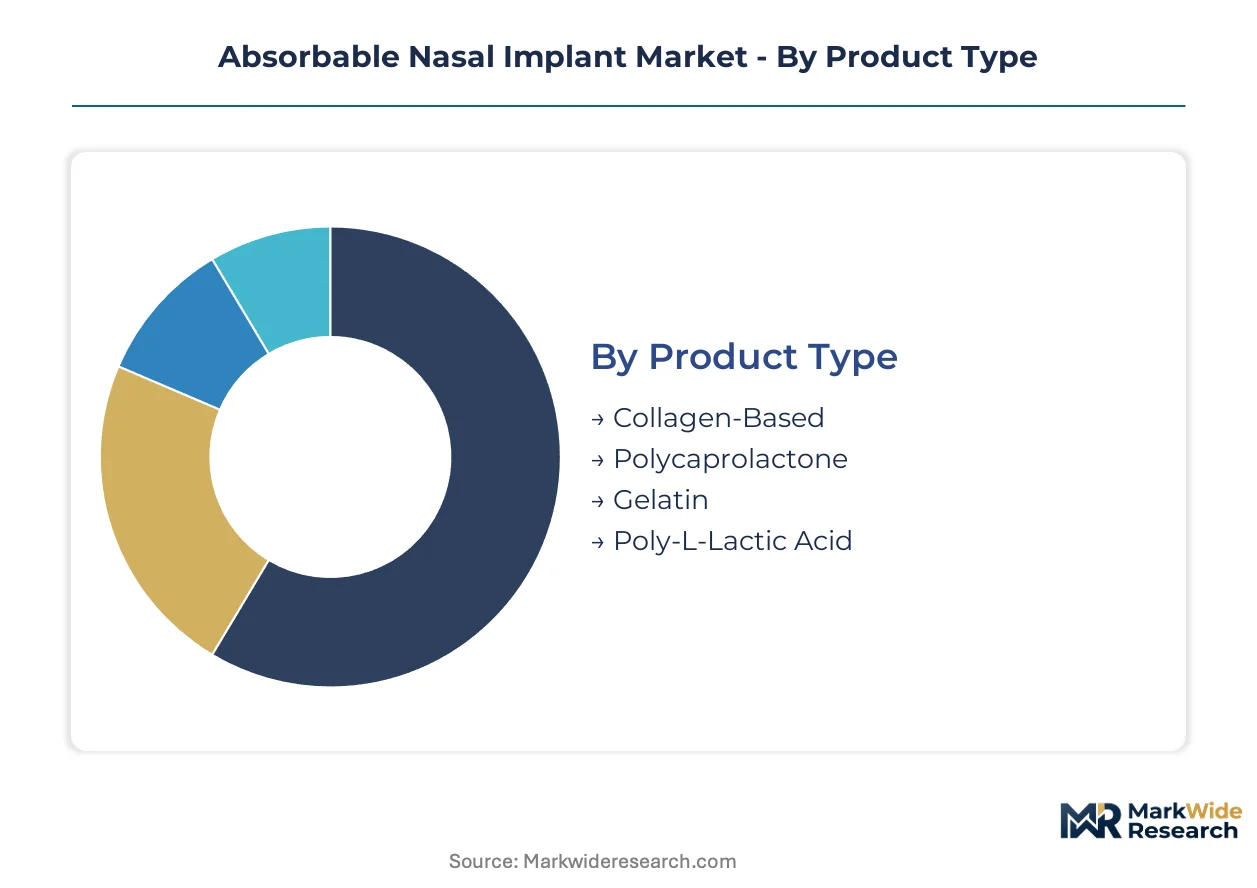
Absorbable nasal implant manufacturers must align service infrastructure with degradation profiles and procedure settings. Each segment demands distinct clinical support, from patency monitoring for extended-duration scaffolds to rapid inventory turnover for same-day polyp procedures.
Product Type:
After-sales intensity varies sharply across material chemistries, with protein-based formulations requiring cold-chain logistics and hydrolysis-rate tracking that synthetic polymers avoid.
- Collagen-Based:Derived from bovine or porcine tissue matrices, these scaffolds leverage intrinsic hemostatic properties to minimize post-operative bleeding in functional endoscopic sinus surgery. Demand clusters in United States academic medical centers where surgeon training programs reinforce familiarity with protein-based hemostats. FDA biocompatibility documentation for xenogenic sourcing adds regulatory service burden.
- Polycaprolactone:Semi-crystalline aliphatic polyester enabling 60-90 day degradation windows suited to sustained corticosteroid elution protocols. German outpatient ENT clinics favor this chemistry for chronic rhinosinusitis with nasal polyps, where extended structural support aligns with recurrence prevention pathways. Remote patency assessment capabilities become critical for these longer-duration implants.
- Gelatin:Rapidly resorbing protein matrix suited to short-duration patency maintenance following uncomplicated septoplasty.
- Poly-L-Lactic Acid:Crystalline polyester providing the longest structural support duration among commercial options; Japan's PMDA applies distinct QMS inspection protocols that extend service timelines for these extended-degradation variants.
Collagen-based formulations hold the largest share; momentum sits with polycaprolactone as polyp management protocols expand.
Indication:
Procedure reimbursement thresholds reshape segment economics, with bundled payment pilots in United States metropolitan markets favoring indications with demonstrable episode-cost reduction.
- Nasal Obstruction:Primary indication encompassing septoplasty and turbinate reduction follow-on care, where scaffold patency maintenance directly correlates with surgical outcome metrics. United States ambulatory surgical centers drive volume through same-day discharge protocols. Post-operative monitoring infrastructure requirements are highest here due to direct functional outcome measurement.
- Sinusitis:Chronic rhinosinusitis applications demand integration with endoscopic navigation systems and powered instrumentation platforms. German hospital clusters emphasize antibiotic elution compatibility for these indications. Service intensity concentrates on coordinating scaffold degradation with antimicrobial therapy timelines.
- Polyp Removal:Recurrence prevention focus creates demand for corticosteroid-composite formulations with precise degradation matching to mucosal healing windows.
- Allergy Management:Emerging application for allergen-barrier scaffolds in seasonal intervention protocols; limited current infrastructure for post-implant immunologic monitoring.
Nasal obstruction commands the greatest procedural volume; polyp removal applications are climbing the fastest as sustained-release formulations mature.
Delivery Mode:
Capital equipment requirements and facility certification standards fragment service models across delivery mechanisms.
- Injectable:Prefilled syringe or hydrogel systems enabling office-based deployment without endoscopic visualization; minimal capital burden but requires physician training on intranasal injection anatomy. United States clinic networks favor this mode for allergy management protocols.
- Implantable:Endoscopically placed solid scaffolds demanding surgical suite infrastructure and instrument compatibility with navigation platforms. Highest service intensity due to integration with powered instrumentation portfolios and post-operative patency assessment protocols.
- Nasal Sprays:Topical delivery of resorbable particulate matrices; limited structural support but suited to mucosal surface applications.
- Tablets:Dissolvable solid inserts for anterior nasal cavity placement; simplest logistics but constrained to accessible anatomical sites.
Implantable delivery dominates revenue concentration; injectable modes are gaining share fastest as office-based polyp management protocols proliferate.
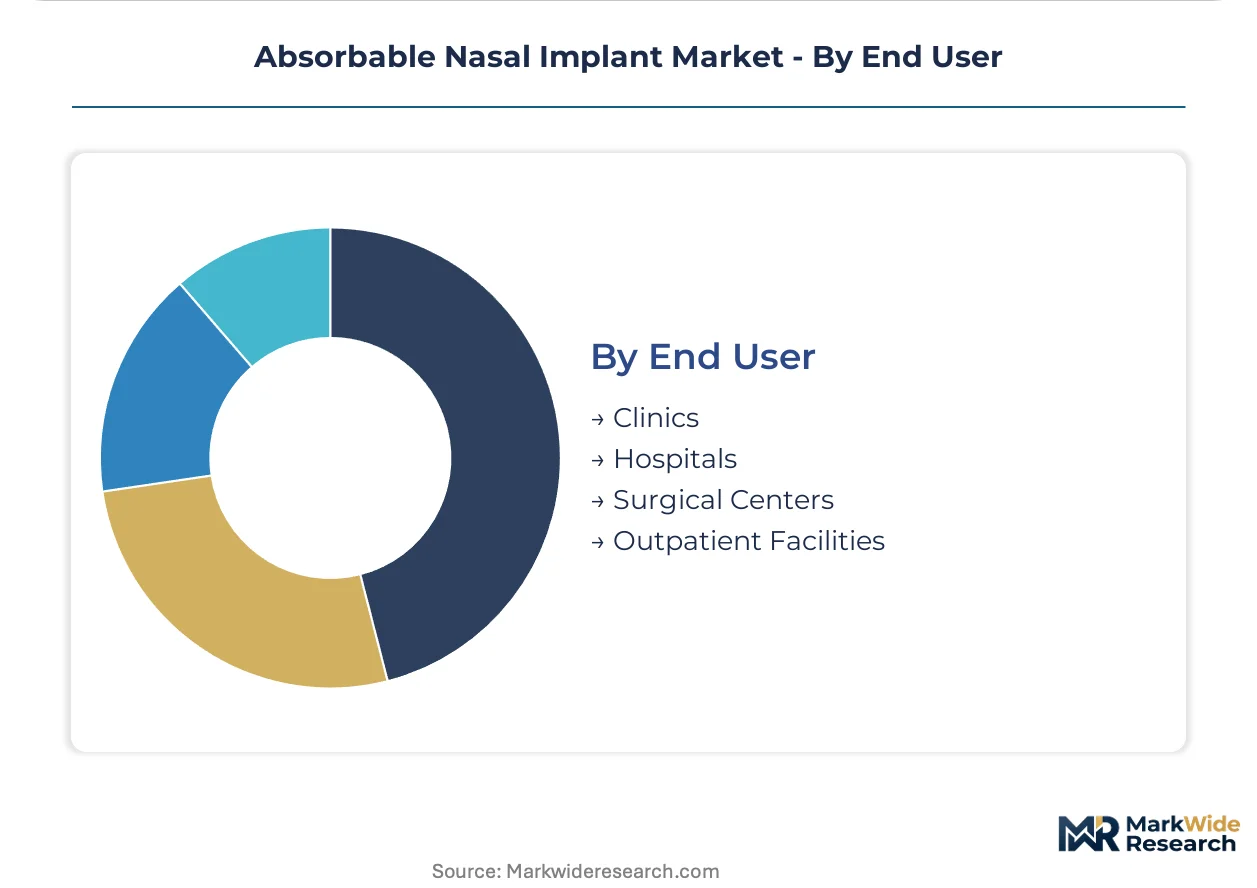
End User:
Procurement consolidation and formulary standardization create divergent service requirements across care settings.
- Hospitals:Academic medical centers in United States, Germany, and Japan anchor demand for complex functional endoscopic sinus surgery cases requiring extended structural support. Bundled contract negotiations demand comprehensive post-operative outcome documentation and remote monitoring infrastructure.
- Surgical Centers:United States ambulatory surgical centers recalibrate implant formularies around total episode cost metrics, favoring suppliers capable of rapid inventory replenishment and standardized degradation profiles that simplify nursing protocols.
- Clinics:German outpatient ENT practices drive adoption of injectable and spray formulations for polyp recurrence prevention; cost-sensitive environments where extended degradation profiles justify premium positioning.
- Outpatient Facilities:Hospital-owned same-day surgery units with hybrid characteristics; procurement decisions increasingly centralized through health system consortiums.
Hospitals retain the largest share; surgical centers are expanding most quickly as United States reimbursement shifts toward site-neutral payment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German metropolitan hospital clusters where bundled procurement contracts command performance guarantees, while Japanese regulatory complexity inflates compliance costs and compresses margins for extended-degradation variants.
United States
Ambulatory surgical centers in metropolitan markets drive volume through same-day discharge protocols for nasal obstruction correction. FDA 510(k) premarket notification frameworks streamline pathways for polymeric scaffold innovators. Hospital procurement consortiums in Greater Boston and the Pacific Northwest now mandate post-operative monitoring infrastructure as a contract prerequisite.
Germany
Outpatient ENT clinics in Bavaria and North Rhine-Westphalia favor polycaprolactone formulations for chronic rhinosinusitis with nasal polyps. EU MDR reinforced clinical evaluation obligations extend approval timelines for implant-specific bioresorption documentation. The Eindhoven-Randstad corridor anchors demand for extended-degradation scaffolds with corticosteroid elution capabilities.
Japan
Academic medical centers in Tokyo and Osaka sustain procedure volumes for complex functional endoscopic sinus surgery requiring structural support. PMDA maintains distinct QMS inspection protocols for absorbable polymer devices that lengthen approval cycles relative to metallic stents. Kanto region hospitals concentrate demand for collagen-based formulations with established hemostatic properties.
United Kingdom
NHS procurement frameworks increasingly weight total episode cost metrics over discrete device pricing for nasal implant selection. MHRA alignment with EU MDR standards elevates biocompatibility documentation requirements for poly-L-lactic acid submissions. London-Southeast hospital clusters pilot bundled payment models incorporating remote patency assessment.
France
Île-de-France academic centers anchor demand for premium-tier protein-based scaffolds in complex septoplasty cases. ANSM oversight of xenogenic collagen sourcing adds regulatory service burden distinct from synthetic polymer pathways. Auvergne-Rhône-Alpes surgical networks emphasize instrument compatibility with navigation platforms in procurement decisions.
Absorbable Nasal Implant Market Competitive Environment
Diversified medical technology conglomerates and focused ENT specialists split the market along integration depth versus clinical specialization vectors. Tiered competitive positioning emerges from divergent resource allocation: backward integration into raw material processing versus forward integration into surgical instrumentation ecosystems. Three archetypes dominate—vertically integrated health care conglomerates, mid-cap ENT pure-plays, and contract manufacturing organizations serving private-label entrants. Consolidation activity concentrates on instrument compatibility assets and European CRO capabilities for bioresorption kinetic testing.
Within the diversified conglomerate tier, Johnson & Johnson and Stryker Corporation exemplify competing integration strategies. Johnson & Johnson anchors positioning through captive collagen processing infrastructure. Stryker Corporation occupies a position emphasizing sinus surgery platform convergence. Spirox represents the focused ENT pure-play archetype with concentrated physician engagement across academic medical centers.
| Leading Market Players |
|---|
| Spirox |
| Johnson & Johnson |
| Stryker Corporation |
| Acclarent |
| ArthroCare Corporation |
| Smith & Nephew |
| Pfizer |
| Mentor Worldwide |
| Intersect ENT |
| Others |
Value Chain & Pricing Dynamics
The Eindhoven-Randstad corridor's polycaprolactone compounding capacity shapes downstream pricing power for extended-degradation nasal scaffolds across Western Europe. German hospital procurement consortiums leverage this geographic concentration to extract performance guarantees that compress margins for collagen-based formulations sourced from dispersed protein processing networks.
Pricing Analysis
Configured-to-order pricing for patient-specific degradation profiles commands a 40-60% premium over standard catalog formulations in United States academic medical centers. Three-tier pricing structure across premium, standard, and economy levels stratifies by biocompatibility certification tier and cold-chain logistics bundling. Pricing pressure stems from ambulatory surgical center formulary consolidation around total episode cost metrics, with United States clinic networks exhibiting highest price sensitivity and Japanese academic medical centers showing lowest.
Supply Chain Analysis
Contract manufacturing for absorbable polymer extrusion concentrates in Germany, the Netherlands, and Switzerland among specialized medical device CMOs with EU MDR notified body relationships. Raw material flows draw from agricultural lactide feedstocks in the United States and pharmaceutical-grade collagen from French and Italian tissue processors. Single-source vulnerability in PMDA-certified polymer synthesis for Japan-bound shipments creates supply chain risk. Distribution runs through hospital procurement consortiums and GPO contracts rather than direct manufacturer-to-facility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through United States hospital procurement consortiums that now mandate post-operative monitoring infrastructure as a contract prerequisite, fragmenting traditional physician-preference purchasing.
For Market Incumbents: Entrench position through backward integration into collagen processing and captive polymer compounding capacity in Germany. Defend against polycaprolactone entrants by securing exclusive instrument compatibility agreements with Stryker and Johnson & Johnson navigation platforms. Priority lever: EU MDR clinical evaluation capabilities that extend approval timelines for challengers. For New Entrants and Emerging Players: Build out remote patency assessment infrastructure to meet bundled contract requirements in United States metropolitan markets. Target German outpatient ENT clinics for polyp management protocols where extended degradation profiles justify premium positioning. Go-to-market angle: corticosteroid-composite formulations with 60-90 day elution windows that collapse mechanical and pharmaceutical intervention into single-procedure solutions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized European CROs with bioresorption kinetic testing capabilities and notified body relationships. Long-term viability rests on capturing the instrumentation-convergence wave as sinus surgery platforms integrate scaffold delivery. Acquisition archetype: focused ENT pure-plays with direct-to-physician engagement at academic medical centers. Signal to watch: PMDA approval timeline compression for absorbable polymers relative to metallic stents.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Advancement | Streamlined premarket notification accelerates time-to-market for polymeric scaffold innovators in ambulatory settings. |
| EU MDR Clinical Evaluation Investment | Dedicated in-vivo testing facilities in Germany and the Netherlands satisfy notified body scrutiny for extended-degradation claims. |
| Hospital System Partnership | Bundled contracts with United States metropolitan consortiums lock in post-operative monitoring infrastructure requirements. |
| Backward Integration into Collagen Processing | Captive supply of bovine and porcine tissue matrices secures hemostatic formulation quality and margin control. |
| Software Companion Development | Remote patency assessment platforms enable outcome documentation required by ASC buying committees. |
Study Parameters
Desk research of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases preceded structured interviews with ENT surgeons, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at notified bodies. Secondary validation drew from PMDA submission records, CMS Medicare reimbursement data, and German hospital procurement frameworks. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Assumptions held fixed include current FDA 510(k) pathway duration, EU MDR notified body capacity constraints, and PMDA QMS inspection protocols for absorbable polymers; variables tested across the analysis window encompassed ambulatory surgical center reimbursement shifts and bundled payment pilot expansion. Segmentation modeling covered material chemistry, indication category, delivery mode, and end-user facility type. CAGRs derived from procedure volume growth rates and implant penetration assumptions, with price elasticity informed by hospital procurement consortium contract terms.
The forecast holds incumbent behavior within observed patterns; aggressive moves by instrument platform conglomerates into captive scaffold manufacturing would shift outcomes. Quarterly review of FDA 510(k) clearance timelines, EU MDR notified body backlogs, and United States ASC reimbursement thresholds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Osteotomy Plates Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Bone Cement Mixers Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Sphincterotomes Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Medical Goggle Market