
 Percutaneous Coronary Intervention Guidance Devices Market | 2026-2036
Percutaneous Coronary Intervention Guidance Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Percutaneous Coronary Intervention Guidance Devices Market Analytics
Capital-intensity divergence between integrated imaging console manufacturers and disposable catheter specialists is redrawing competitive boundaries in PCI guidance. Abbott leverages vertically aligned IVUS and OCT platforms to capture recurring catheter revenue alongside system placements. Boston Scientific Corporation anchors its position through broad coronary physiology and imaging portfolios that sustain hospital loyalty across procedural workflows. Medtronic competes by extending electromechanical navigation capabilities into robotic-assisted PCI delivery systems.
Percutaneous coronary intervention guidance devices comprise intravascular imaging catheters, pressure-sensor guidewires, and optical coherence tomography systems that deliver real-time luminal assessment at resolutions reaching 10-15 micrometers, enabling precise stent sizing and placement optimization. Their primary commercial purpose centers on reducing target lesion revascularization rates by replacing angiographic guesswork with quantitative vessel characterization. Intravascular ultrasound maintains the largest installed base among imaging modalities, though optical coherence tomography captures the fastest expansion as interventional cardiologists prioritize near-histology plaque detail. Pressure wire and fractional flow reserve applications concentrate margin pools in physiology-guided decision-making, where reimbursement specificity rewards documented hemodynamic significance over visual stenosis estimation.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements impose divergent evidence standards on new PCI guidance platforms, with European notified bodies demanding extended clinical follow-up for novel imaging algorithms. Japan's PMDA shapes market access through distinct pharmaceutical and medical device agency review timelines that favor locally conducted registry data. Stakeholders must monitor evolving CMS national coverage determinations for FFR and intravascular imaging to anticipate whether hospital capital budgets shift toward integrated physiology-imaging consoles or maintain standalone device procurement.
Market Dynamics
Hospital catheterization labs are consolidating purchasing power around integrated physiology-imaging consoles, forcing device manufacturers to bundle disposable catheter revenue with capital equipment placements rather than sell standalone components.
Growth Catalysts
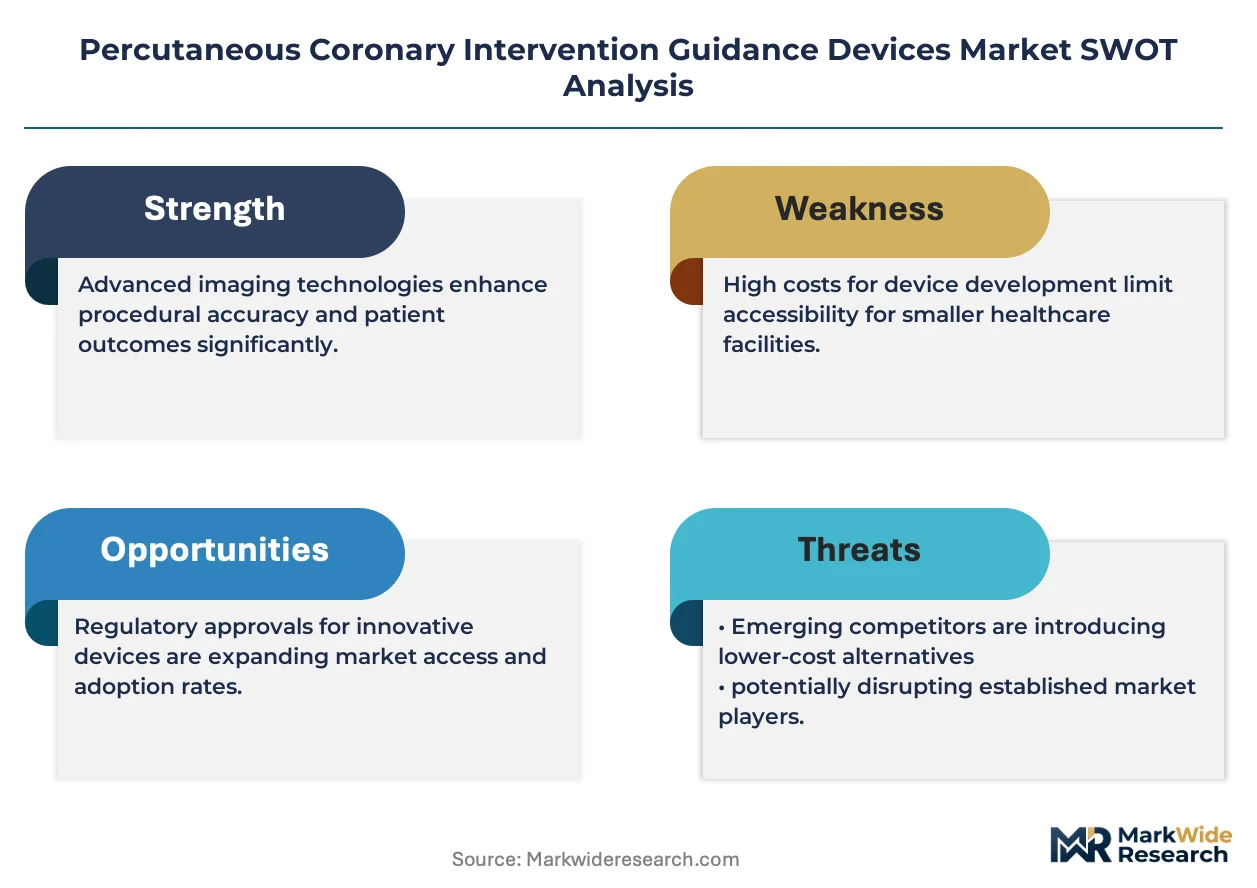
- CMS National Coverage Determinations:Expanded reimbursement for fractional flow reserve and intravascular imaging in the United States rewards documented hemodynamic significance over visual stenosis estimation, pulling catheter volume through hospital procurement channels.
- Japan's PMDA registry pathways:Locally conducted clinical data requirements favor manufacturers establishing domestic registry infrastructure, accelerating market access for imaging platforms with Japanese validation.
- Optical coherence tomography resolution thresholds:Near-histology plaque detail at 10-15 micrometers drives interventional cardiologist preference shifts from angiographic guesswork toward quantitative vessel characterization.
Market Restraints
- EU MDR technical documentation:Extended clinical follow-up demands for novel imaging algorithms delay product launches by 18-36 months versus FDA 510(k) pathways, compressing European revenue windows.
- Single-source sensor foundries:Pressure-wire MEMS manufacturing concentrates in specialized semiconductor facilities, creating input bottlenecks when capacity constraints hit medical-grade sensor production.
- Angiography suite retrofit costs:Legacy cath labs require structural modifications to accommodate integrated imaging consoles, freezing capital budgets at smaller community hospitals.
Strategic Opportunities
- Robotic-assisted PCI delivery:Electromechanical navigation convergence with real-time imaging creates white space for synchronized catheter positioning systems that reduce operator radiation exposure.
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract component assembly operations, lowering landed costs for disposable imaging catheters in price-sensitive Asian markets.
- AI-enabled plaque characterization:Machine learning algorithm integration with intravascular ultrasound automates stent sizing recommendations, differentiating premium console offerings.
Industry Challenges
- Interventional cardiologist training pipelines:Optical coherence tomography interpretation requires specialized credentialing that outpaces fellowship program curriculum updates, throttling adoption velocity.
- Cross-platform data interoperability:Proprietary imaging formats from competing console manufacturers block seamless integration with hospital electronic health record systems, forcing costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Percutaneous Coronary Intervention Guidance Devices Market |
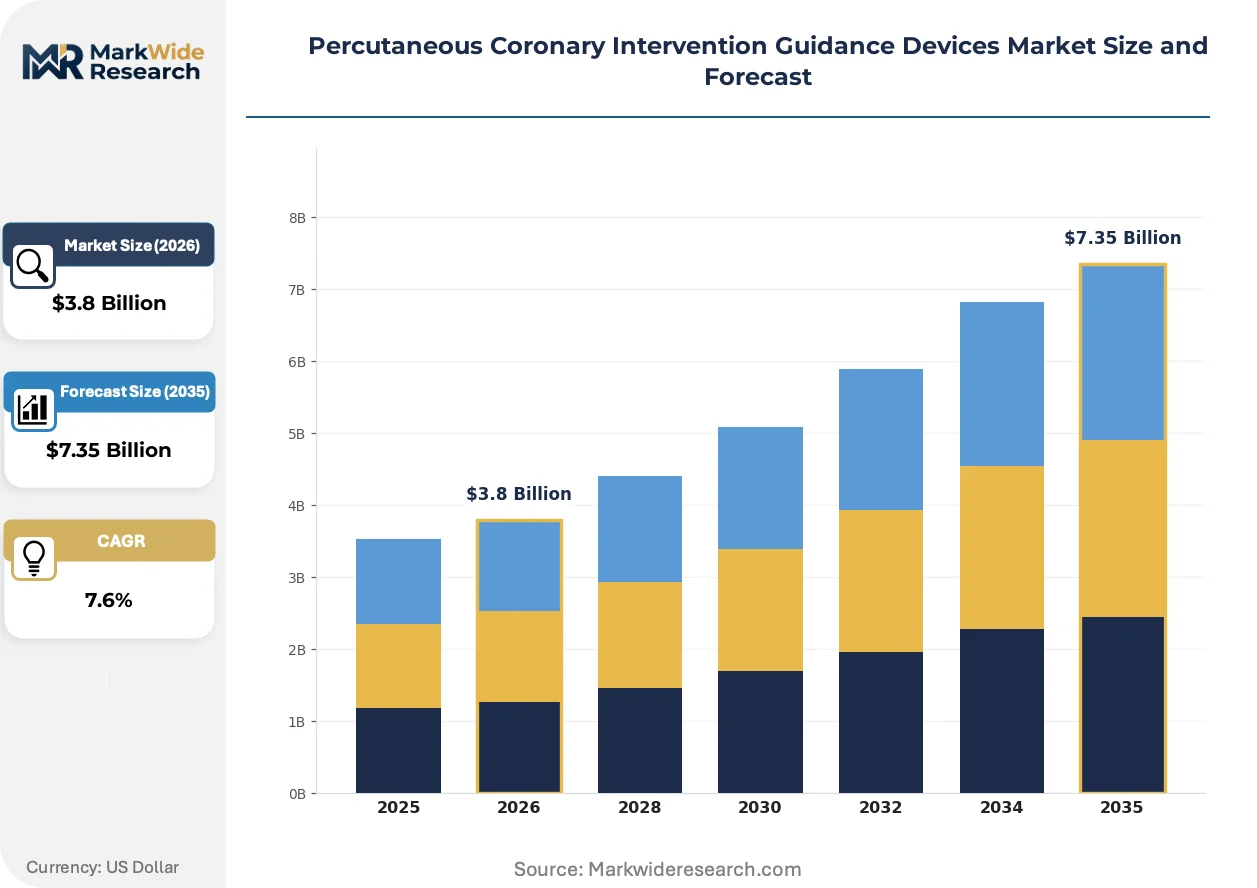
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravascular Ultrasound, Optical Coherence Tomography, Pressure Wire, FFR End User: Hospitals, Cardiac Catheterization Labs, Outpatient Surgical Centers, Specialty Clinics Technology: 3D Imaging, Fluoroscopy, Electromechanical Systems, Robotic Assistance Application: Coronary Angioplasty, Stenting, Plaque Removal, Vessel Assessment |
| Companies Covered | Abbott, Boston Scientific Corporation, Medtronic, Johnson & Johnson Services, Inc., Terumo Corporation, Biosensors International Group, Ltd., B. Braun SE, ASAHI INTECC Company Limited, Meril Life Sciences Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Percutaneous Coronary Intervention Guidance Devices Market Evolving Landscape
Device form factors and regulatory evidence standards are compressing development cycles while procurement centralization reshapes how hospitals acquire integrated systems.
Intravascular ultrasound transducer arrays are miniaturizing to sub-millimeter diameters while maintaining acoustic frequency bandwidth. Interventional cardiologists at high-volume academic medical centers are adopting these catheters for distal vessel assessment. The technology is miniaturizing access to previously unimageable coronary segments, expanding addressable procedure volume beyond proximal lesion interventions.
EU MDR conformity assessment procedures now mandate notified body review of software-as-medical-device components within imaging consoles. Manufacturers must submit algorithm validation datasets spanning multiple clinical sites. European catheterization labs face extended procurement freezes while vendors complete enhanced technical documentation, shifting near-term revenue concentration toward FDA-cleared product lines.
Hospital purchasing committees now unbundle after-sales service contracts from capital equipment acquisitions, negotiating multi-vendor maintenance agreements through third-party clinical engineering firms. Independent service organizations are displacing manufacturer captive service teams for console calibration and repair. This pattern concentrates in Germany's hospital sector, where procurement law mandates competitive tendering for maintenance spend above threshold values.
Percutaneous Coronary Intervention Guidance Devices Market Segmentation
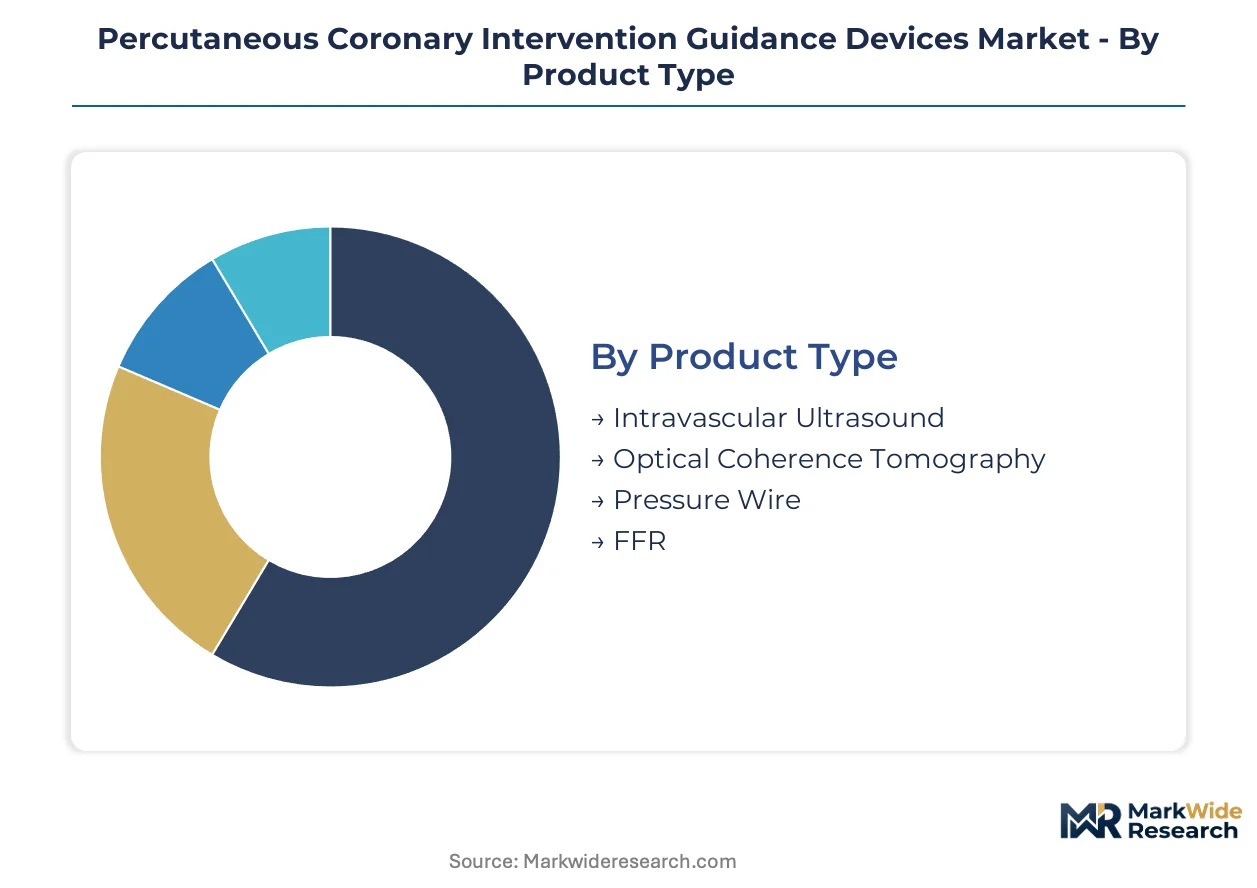
PCI guidance device segmentation reveals how regulatory pathways and reimbursement specificity concentrate revenue across product categories. Hospital procurement committees now evaluate segments through bundled capital-disposable economics rather than standalone device performance.
Product Type:
FDA 510(k) clearance timelines diverge sharply across imaging modalities, with IVUS leveraging predicate device pathways while novel OCT algorithms trigger de novo reviews.
- Intravascular Ultrasound:Solid-state transducer arrays operating at 20-60 MHz deliver cross-sectional vessel imaging with 100-150 micrometer resolution. Hospital catheterization labs in the United States deploy IVUS as the default imaging standard where CMS reimbursement documentation requirements favor established modality codes. This segment handles the majority of throughput; Optical Coherence Tomography is gaining share fastest.
- Optical Coherence Tomography:Near-infrared interferometry achieves 10-15 micrometer resolution for near-histology plaque characterization. Interventional cardiologists at academic medical centers in Germany prioritize OCT for complex bifurcation lesions where stent optimization demands precise landing zone identification.
- Pressure Wire:MEMS sensor-tipped guidewires measure distal coronary pressure for fractional flow reserve calculation. Japanese PMDA registry requirements favor manufacturers with domestic clinical validation infrastructure.
- FFR:Computational physiology platforms derive hemodynamic significance from angiographic reconstruction without sensor wires. Outpatient surgical centers in India adopt FFR-CT alternatives to avoid invasive catheter costs.
IVUS maintains installed base dominance; OCT climbs fastest on interventional cardiologist preference for plaque detail resolution.
End User:
Capital equipment budgets stratify sharply across facility types, with high-volume academic centers absorbing integrated console costs while community sites defer procurement.
- Hospitals:Integrated catheterization labs with 24/7 emergency PCI capability mandate redundant imaging console availability. Tertiary centers in Japan concentrate physiology-guided procedure volume through fellowship-trained operator pipelines.
- Cardiac Catheterization Labs:Dedicated outpatient facilities optimize throughput through streamlined device workflows and direct manufacturer catheter consignment arrangements. German procurement law mandates competitive tendering for maintenance contracts above threshold values.
- Outpatient Surgical Centers:Limited service lines concentrate on diagnostic angiography with selective PCI for stable patients. United States ASC reimbursement differentials reward same-day discharge protocols.
- Specialty Clinics:Cardiology group practices with office-based labs perform diagnostic catheterization and refer complex interventions to hospital partners. India's PLI scheme for medical devices attracts component assembly for disposable catheter supply.
Hospitals absorb the bulk of capital equipment placements; outpatient surgical centers expand fastest on reimbursement migration toward ambulatory settings.
Technology:
Software-as-medical-device classification under EU MDR now captures algorithm-driven imaging platforms, extending conformity assessment timelines for AI-enabled consoles.
- 3D Imaging:Volumetric reconstruction from rotational angiography or intravascular pullbacks enables virtual stent deployment simulation. Academic medical centers in the United States deploy 3D-FFR integration for pre-procedural planning.
- Fluoroscopy:X-ray based real-time guidance remains the foundational visualization layer for all PCI procedures. Radiation dose reduction algorithms now carry mandatory validation under Japan's PMDA software review pathways.
- Electromechanical Systems:Motorized catheter advancement and rotation mechanisms reduce operator hand fatigue during complex interventions. German hospital engineering departments prioritize electromechanical platform interoperability with existing angiography suites.
- Robotic Assistance:Teleoperated catheter navigation systems synchronize with intravascular imaging for precision positioning. United States academic centers evaluate robotic platforms for operator radiation exposure reduction in high-volume labs.
Fluoroscopy underpins all procedural volume; robotic assistance shows steepest expansion trajectory on safety and precision differentiation.
Application:
Procedure reimbursement specificity determines device utilization intensity, with stenting protocols mandating imaging documentation while diagnostic angiography operates under visual estimation.
- Coronary Angioplasty:Balloon dilation without stent deployment concentrates in cost-sensitive markets and calcified lesions requiring sequential preparation. Indian cath labs prioritize balloon catheter economics over imaging system investment.
- Stenting:Metallic or bioresorbable scaffold deployment demands precise sizing and landing zone optimization through IVUS or OCT guidance. United States hospital reimbursement bundles reward documented imaging use with reduced target lesion revascularization penalties.
- Plaque Removal:Atherectomy and thrombectomy procedures require real-time vessel wall assessment to avoid perforation. Japanese operators favor OCT guidance for directional atherectomy device orientation.
- Vessel Assessment:Diagnostic imaging for intermediate stenosis severity drives FFR and instantaneous wave-free ratio adoption. German outpatient clinics concentrate vessel assessment volume through streamlined same-day diagnostic protocols.
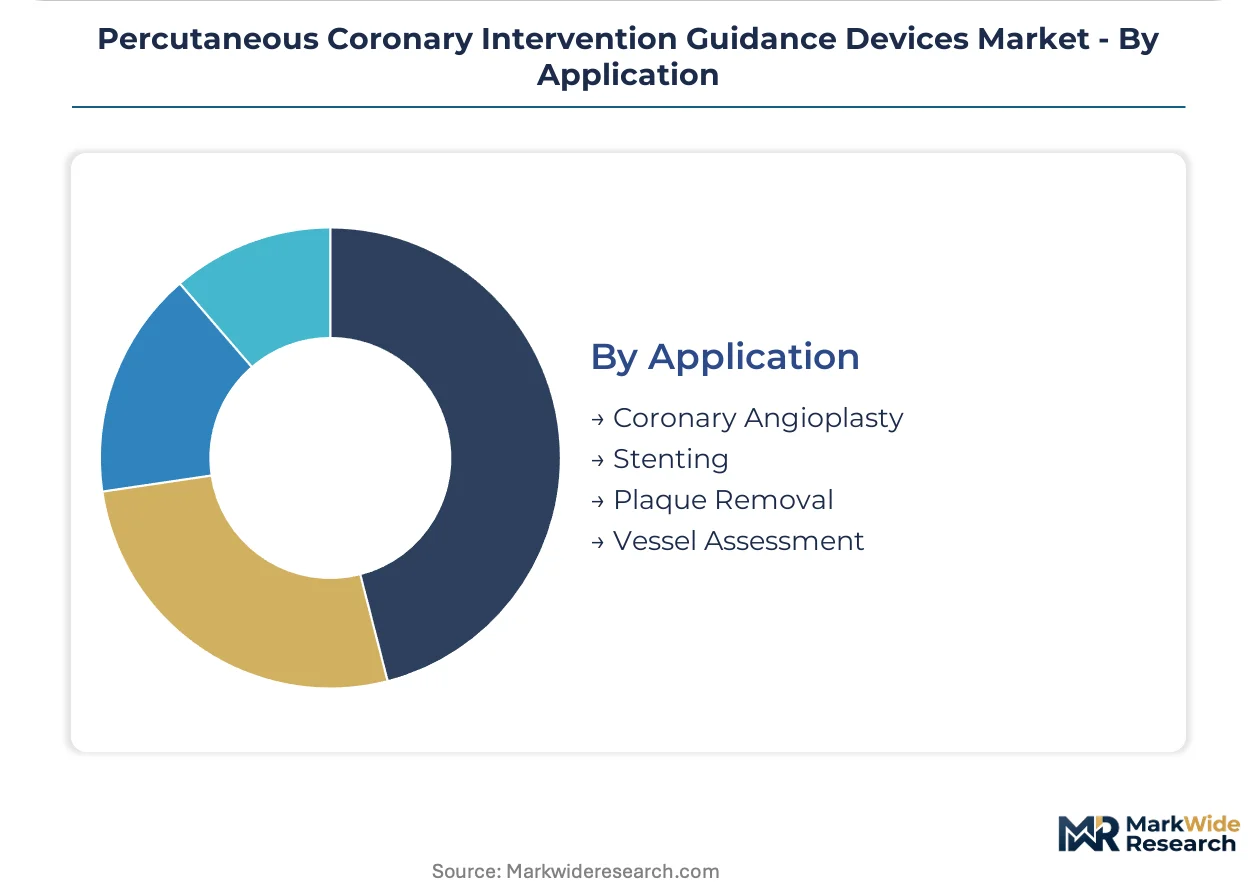
Stenting commands the dominant share of imaging device utilization; vessel assessment expands most quickly on physiology-guided diagnostic adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for PCI guidance devices varies sharply across geographies. United States hospital systems absorb premium integrated console pricing through bundled reimbursement, while Indian cath labs prioritize disposable catheter economics over capital equipment investment.
United States
Hospital catheterization labs concentrate procurement around integrated physiology-imaging consoles that capture recurring catheter revenue streams. FDA 510(k) clearance pathways accelerate market access for predicate device submissions compared to de novo reviews. Academic medical centers in Boston and Cleveland drive adoption of AI-enabled plaque characterization algorithms.
Germany
Interventional cardiologists at university hospitals prioritize optical coherence tomography for complex bifurcation lesions requiring precise landing zone identification. EU MDR technical documentation mandates extended clinical follow-up for novel imaging algorithms, delaying product launches versus FDA timelines. The Rhine-Ruhr hospital network concentrates procurement volume through competitive tendering for maintenance contracts.
Japan
PMDA registry pathways favor manufacturers with domestically conducted clinical validation infrastructure for intravascular imaging platforms. Reimbursement expansion for physiology-guided PCI pulls pressure-wire catheter volume through hospital procurement channels. Tokyo and Osaka metropolitan areas concentrate fellowship-trained operator pipelines that sustain high-volume PCI centers.
India
Price-sensitive cath labs prioritize balloon catheter economics over imaging system investment for coronary angioplasty procedures. The PLI scheme for medical devices attracts component assembly operations that lower landed costs for disposable imaging catheters. Maharashtra and Gujarat industrial corridors host emerging domestic manufacturing clusters for catheter components.
United Kingdom
NHS procurement frameworks bundle after-sales service contracts through third-party clinical engineering firms, displacing manufacturer captive service teams. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating parallel conformity assessment requirements. London and Southeast hospital trusts lead adoption of robotic-assisted PCI delivery systems for operator radiation exposure reduction.
Percutaneous Coronary Intervention Guidance Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in PCI guidance devices. Abbott, Boston Scientific Corporation, and Medtronic anchor the upper tier through vertically aligned imaging platforms and physiology portfolios. The middle tier comprises disposable catheter specialists and regional electromechanical navigation providers. Competitive dynamics center on bundling capital equipment with recurring catheter revenue, and on securing hospital loyalty through integrated procedural workflows.
Within the integrated imaging console tier, Abbott and Boston Scientific Corporation exemplify the capital-disposable bundling archetype. Abbott's position reflects vertically aligned IVUS and OCT platforms. Boston Scientific Corporation occupies a comparable position through broad coronary physiology and imaging portfolios. Medtronic represents the electromechanical navigation convergence archetype, extending capabilities into robotic-assisted PCI delivery systems. Johnson & Johnson Services, Inc. and Terumo Corporation sit within the diversified medical device conglomerate tier, leveraging cross-divisional hospital relationships. B. Braun SE and ASAHI INTECC Company Limited exemplify specialized component and catheter manufacturing expertise.
| Leading Market Players |
|---|
| Abbott |
| Boston Scientific Corporation |
| Medtronic |
| Johnson & Johnson Services, Inc. |
| Terumo Corporation |
| Biosensors International Group, Ltd. |
| B. Braun SE |
| ASAHI INTECC Company Limited |
| Meril Life Sciences Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Disposable imaging catheter substitution for reusable capital equipment is redrawing procurement economics across hospital catheterization labs, shifting margin capture toward manufacturers with captive semiconductor sensor foundries in Japan and Germany while compressing pricing power for standalone console vendors lacking recurring revenue streams.
Pricing Analysis
After-sales service contracts and multi-year maintenance agreements now drive lifetime value more than initial system placements. Three-tier pricing structure across premium, standard, and economy levels stratifies by imaging modality sophistication and regulatory certification tier, with FDA 510(k) cleared platforms commanding premiums over CE-marked equivalents in United States procurement channels. Cost compression in economy-tier balloon catheter segments is intensifying because Indian domestic assembly operations under the PLI scheme are lowering landed costs. Community hospitals and outpatient surgical centers exhibit highest price sensitivity, deferring integrated console investments, while academic medical centers absorb premium positioning for AI-enabled plaque characterization capabilities.
Supply Chain Analysis
Strait of Malacca transit routes for germanium and gallium compounds underpin optical transducer substrate availability, with single-source vulnerability concentrated in specialized MEMS foundries across Japan, Germany, and the United States. Raw material dependencies center on piezoelectric ceramics, near-infrared laser diodes, and medical-grade catheter polymers that draw from chemical processing clusters in the Rhine-Ruhr industrial corridor and Osaka Bay manufacturing zones. Distribution runs through hospital GPO contracts and direct manufacturer consignment arrangements with cardiac catheterization labs, with regulatory restriction risk from EU MDR notified body capacity constraints delaying European product launches relative to FDA clearance timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catheter consumable revenue streams are expanding faster than capital equipment placements, transforming PCI guidance into a service-attach business where disposable pull-through economics determine manufacturer viability.
For Market Incumbents: Shield installed base loyalty by backward integration into pressure-wire MEMS sensor production, eliminating single-source foundry bottlenecks that throttle catheter volume during capacity constraints. Deepen hospital system partnerships through bundled physiology-imaging console placements that lock in recurring catheter procurement against emerging robotic-assisted platform competitors. For New Entrants and Emerging Players: Anchor in India's price-sensitive cath lab segment where PLI scheme incentives enable domestic component assembly cost structures unavailable to established multinationals. Target outpatient surgical centers in the United States with FFR-CT computational platforms that bypass invasive pressure-wire economics, leveraging ASC reimbursement differentials for same-day discharge protocols. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors electromechanical navigation specialists with robotic-assisted delivery capabilities over pure imaging hardware vendors. Acquisition targets should demonstrate software-as-medical-device algorithm validation datasets spanning multiple clinical sites, positioning for EU MDR conformity requirements. Watch Japan's PMDA registry pathway expansion as the inflection signal for which imaging platforms achieve accelerated market access through domestic clinical validation infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Bundled console-catheter contracts with United States academic medical centers lock in recurring revenue streams. |
| Software Companion Development | AI-enabled plaque characterization algorithms differentiate premium offerings under EU MDR software-as-medical-device classification. |
| Reimbursement Strategy | CMS national coverage determination alignment for FFR and intravascular imaging pulls catheter volume through procurement channels. |
| CE Marking Pathway | Extended clinical follow-up datasets satisfy EU MDR notified body demands for novel imaging algorithm clearances. |
| FDASubmission | Predicate device pathways for IVUS platforms accelerate market access versus de novo OCT algorithm reviews. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body technical documentation, and Japanese PMDA registry filings preceded structured interviews with interventional cardiologists, hospital purchasing committee directors, biomedical engineering managers, and GPO contracts specialists. Secondary validation drew from CMS national coverage determinations, hospital procurement databases, and catheterization lab equipment utilization records. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Variance decomposition across product type, end user facility tier, technology modality, and application intensity shaped the analytical framework over the projection horizon. CAGRs derived from segmented procedure volume growth rates applied to average selling price trajectories by imaging modality. Forecast inputs incorporated PMDA registry pathway timelines, EU MDR conformity assessment capacity constraints, and India's PLI scheme manufacturing incentive uptake curves.
Material uncertainties — reimbursement policy reversals, foundry capacity disruptions, and interventional cardiologist training pipeline bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory clearance timelines and hospital capital budget allocation priorities. Practitioners should keep alternative scenarios live as CMS coverage determinations and EU MDR notified body resource constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Abdominal Aortic Aneurysm (AAA) Repair Devices Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market