
 Chile Cardiovascular Devices Market | 2026-2036
Chile Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Cardiovascular Devices Market Outlook
Hospital procurement consortia across Chile's public health system is reconfiguring how cardiovascular devices reach end users, with centralized tenders now governing stent and catheter allocations for regional service networks. Medtronic PLC leverages its broad interventional portfolio to sustain presence across these consolidated purchasing channels. Abbott Laboratories anchors its position through drug-eluting stent specialization aligned with AUGE-GES reimbursement pathways. Siemens Healthineers AG competes in diagnostic imaging by extending its echocardiography and angiography installed base into provincial cardiac centers.
Cardiovascular devices comprise implantable and non-implantable instruments designed to diagnose, monitor, or treat structural and electrical pathologies of the heart and vasculature, with coronary stents typically constructed from cobalt-chromium or platinum-chromium alloys and drug-eluting variants incorporating antiproliferative agents such as sirolimus analogues at coating thicknesses of 5-10 micrometers. Stents and catheters together constitute the dominant product revenue pool, while electrophysiology devices represent the fastest-expanding category as ablation procedure volumes rise in Chile's cardiac clinics. Delivery mode segmentation shows minimally invasive transcatheter approaches displacing open surgical revascularization in eligible patient populations, concentrating margin capture among interventional cardiologists and specialized catheterization laboratory operators.
Chile's national pharmaceutical regulator, the Instituto de Salud Pública, oversees device registration and post-market surveillance under harmonized Mercosur technical regulations, while the Superintendencia de Salud enforces AUGE-GES coverage mandates that directly determine reimbursement eligibility for high-cost cardiac interventions. Compliance with ISP stability testing and clinical evidence requirements shapes market access timelines, particularly for novel drug-eluting platforms and mechanical circulatory support devices. Stakeholders must monitor pending updates to Mercosur medical device directives and their transposition into Chilean technical standards, as these will redefine conformity assessment pathways and competitive entry barriers for imported cardiovascular technologies.
Market Dynamics
Centralized public hospital procurement networks under Chile's AUGE-GES universal coverage system are consolidating purchasing power and reshaping vendor access across the cardiovascular device value chain.
Growth Catalysts
- AUGE-GES Reimbursement Expansion:Chile's guaranteed health access mandates now cover percutaneous coronary intervention procedures, expanding patient eligibility for stent and catheter-based treatments.
- Metropolitan Region Concentration:Santiago's tertiary cardiac centers operate the majority of catheterization laboratories, creating dense procedure volumes that justify premium device investments.
- Drug-Eluting Platform Migration:Antiproliferative coating technologies are displacing bare-metal stents in public hospital inventories as clinical evidence accumulates.
Market Restraints
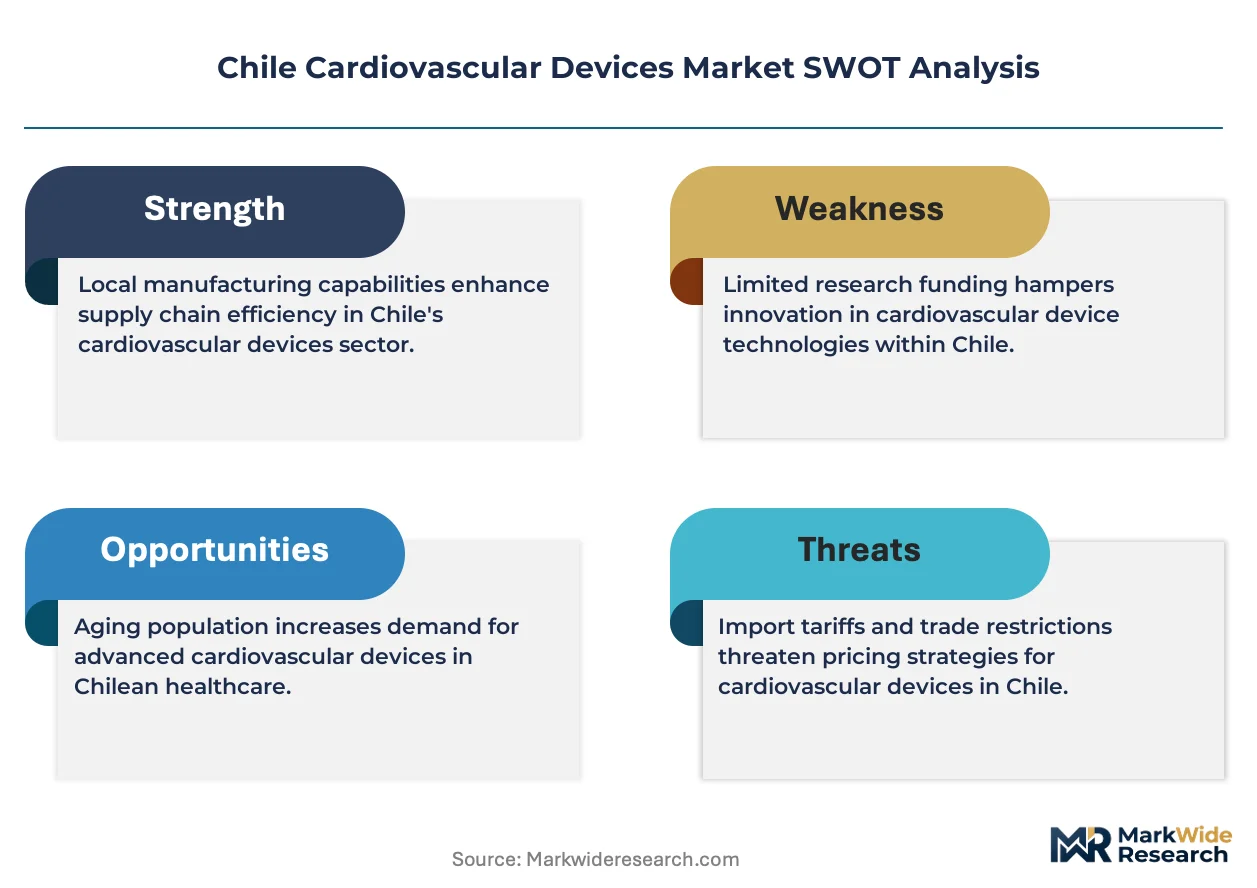
- Import Dependency:Chile lacks domestic cardiovascular device manufacturing, exposing procurement to currency fluctuation and extended supply lead times from US and European suppliers.
- ISP Registration Timelines:Instituto de Salud Pública stability testing requirements for novel drug-eluting platforms create 18-24 month market access delays.
- Specialized Workforce Scarcity:Interventional cardiologist training programs produce insufficient graduates to match catheterization laboratory expansion plans in regional provinces.
Strategic Opportunities
- Provincial Laboratory Expansion:Underpenetrated regions including Valparaíso and Biobío lack catheterization capacity, creating first-mover advantages for device vendors securing tender relationships.
- Electrophysiology Suite Buildouts:Ablation procedure growth in Chilean cardiac clinics outpaces current device availability, opening specialty catheter and mapping system demand.
- Mercosur Harmonization:Pending technical regulation updates will streamline conformity assessment for manufacturers already certified in Brazil or Argentina.
Industry Challenges
- Biomedical Engineer Recruitment:Public hospitals struggle to attract qualified personnel for catheterization laboratory maintenance and device inventory management.
- Legacy System Integration:Provincial cardiac centers deploying new hemodynamic monitoring systems face compatibility friction with existing imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Cardiovascular Devices Market |
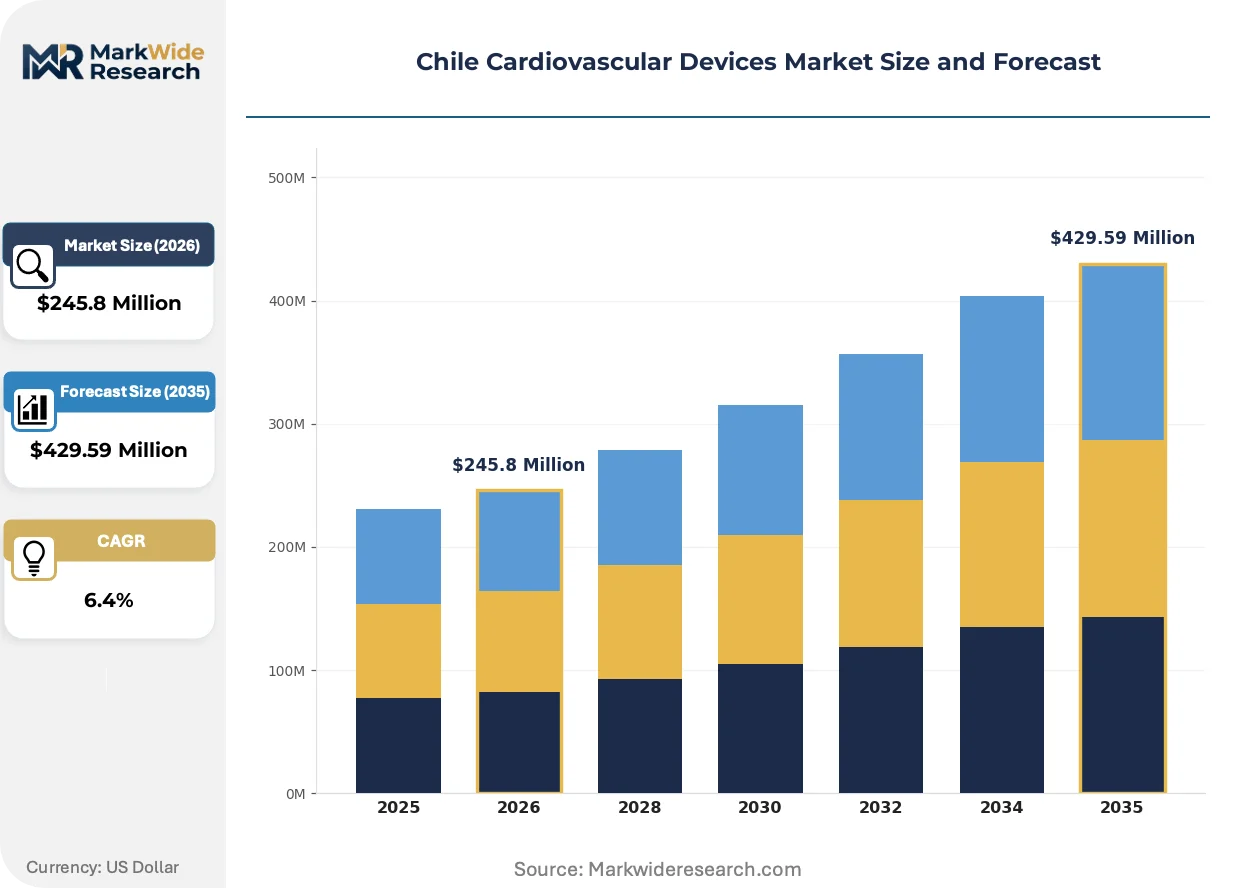
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $429.59 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Catheters, Electrophysiology Devices, Diagnostic Imaging End User: Hospitals, Cardiac Clinics, Research Centers, Outpatient Facilities Technology: Thermal Ablation, Mechanical Circulatory Support, Drug-Eluting Technology, Imaging Techniques Delivery Mode: Minimally Invasive, Open Surgery, Telehealth, Transcatheter |
| Companies Covered | Boston Scientific Corporation, Medtronic PLC, Abbott Laboratories, Siemens Healthineers AG, Philips Healthcare, Nihon Kohden Corporation, GE Healthcare, Edwards Lifesciences Corporation, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Cardiovascular Devices Market Strategic Shifts
Technological convergence between diagnostic imaging and interventional platforms is compressing procedure timelines and altering capital allocation priorities across Chile's cardiac care infrastructure.
Bioresorbable vascular scaffold technology is hybridizing metallic stent durability with temporary vessel support functionality. Santiago's Instituto Nacional de Enfermedades Cardiovasculares has initiated pilot programs evaluating magnesium-based platforms. This hybridization is compressing the traditional stent-to-surgery decision timeline for younger patients with complex lesions.
Chile's Superintendencia de Salud is tightening AUGE-GES compliance audits for high-cost cardiac intervention coverage. Device vendors must now submit real-world outcome data alongside traditional clinical trial evidence. Drug-eluting stent manufacturers face the steepest documentation requirements as reimbursement thresholds tighten.
Hospital consortium purchasing is consolidating tender participation around multi-year supply agreements. Regional service networks in Chile's public system are displacing single-facility procurement autonomy. The Metropolitan Region's Hospital Metropolitano consortium exemplifies this concentration, bundling stent and catheter volumes across twelve facilities.
Chile Cardiovascular Devices Market Segmentation
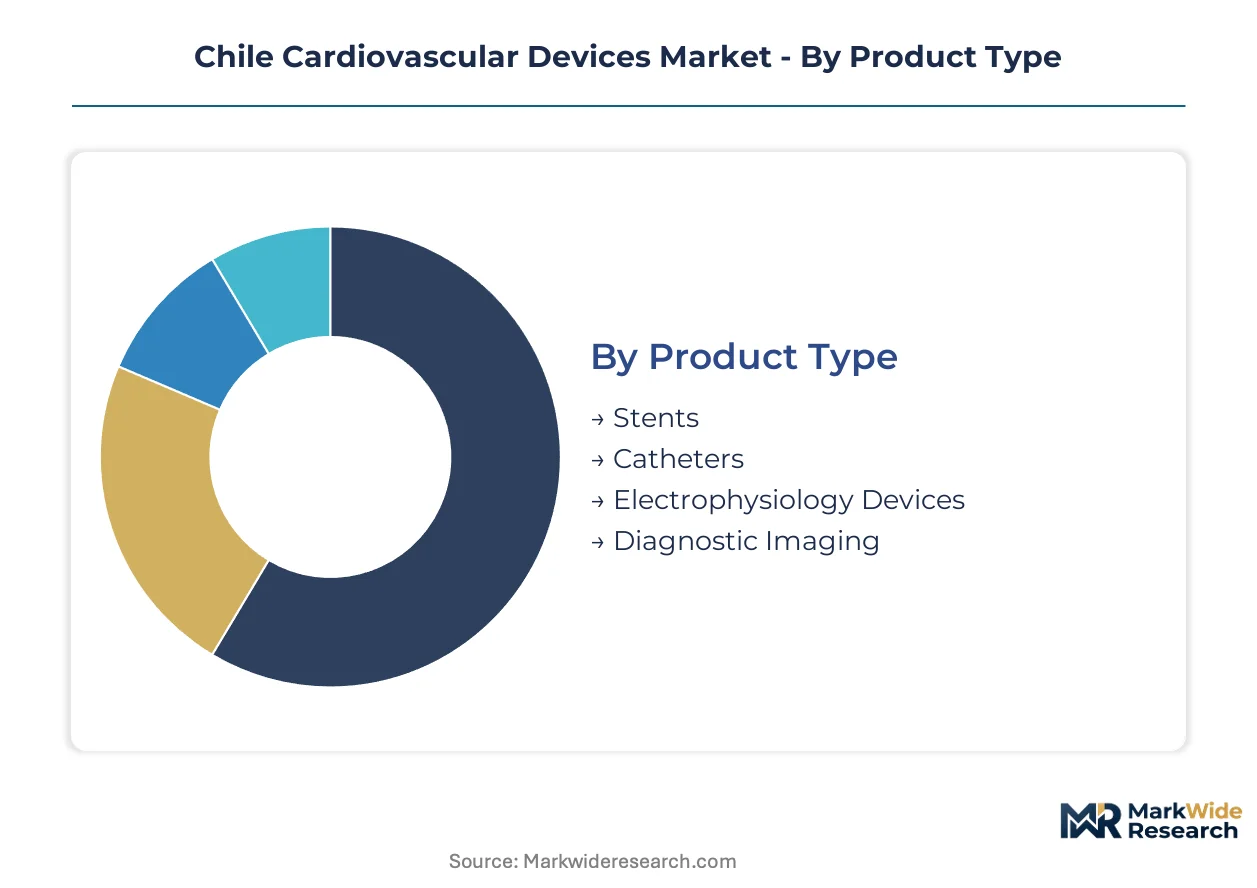
Device taxonomy in Chile's cardiovascular market determines procurement pathways, reimbursement eligibility, and competitive positioning across the AUGE-GES framework. Segmentation reveals where public hospital networks concentrate purchasing power and where private cardiac clinics capture margin.
Product Type:
Cost tier differentiation separates commodity devices from premium platforms in Chilean hospital tenders, with reimbursement thresholds directly mapping to product category.
- Stents:Cobalt-chromium and platinum-chromium alloy platforms incorporate sirolimus analogue coatings at 5-10 micrometer thicknesses. Metropolitan Region tertiary centers are displacing bare-metal inventory with drug-eluting variants as AUGE-GES coverage mandates expand PCI reimbursement.
- Electrophysiology Devices:Ablation catheters and 3D mapping systems address arrhythmia treatment pathways. Santiago's cardiac clinics are outpacing current device availability, creating supply gaps for specialized catheters and navigation platforms.
- Catheters:Diagnostic and interventional catheters serve coronary and peripheral vascular access procedures.
- Diagnostic Imaging:Echocardiography and angiography systems support pre-procedural planning and intraprocedural guidance.
Stents command the established base. The steepest expansion runs through Electrophysiology Devices.
End User:
Customer type determines procurement channel, with public system consolidation contrasting against private clinic autonomy.
- Hospitals:Public hospital procurement consortia under AUGE-GES now govern centralized stent and catheter allocations across regional service networks. The Metropolitan Region's Hospital Metropolitano consortium bundles volumes across twelve facilities, displacing single-facility purchasing autonomy.
- Cardiac Clinics:Specialized electrophysiology suites and catheterization laboratories in Santiago concentrate ablation procedure growth. These facilities operate outside public tender systems, enabling faster adoption of novel mapping and ablation technologies.
- Research Centers:Instituto Nacional de Enfermedades Cardiovasculares evaluates bioresorbable scaffolds and next-generation platforms.
- Outpatient Facilities:Limited catheterization capacity restricts device deployment to diagnostic rather than interventional applications.
Hospitals anchor volume concentration. Cardiac Clinics are gaining share fastest through specialty procedure expansion.
Technology:
Application focus distinguishes acute intervention platforms from chronic disease management and diagnostic modalities.
- Drug-Eluting Technology:Antiproliferative coating systems on metallic stent platforms reduce restenosis rates in coronary interventions. ISP registration timelines of 18-24 months for novel coating chemistries create market access friction for imported platforms.
- Thermal Ablation:Radiofrequency and cryoablation systems target atrial fibrillation and ventricular tachycardia pathways. Provincial cardiac centers lack trained electrophysiologists to match device deployment potential.
- Mechanical Circulatory Support:Impella and ECMO platforms serve high-risk PCI and cardiogenic shock populations.
- Imaging Techniques:Intravascular ultrasound and optical coherence tomography guide lesion assessment and stent optimization.
Drug-Eluting Technology commands the established base. Thermal Ablation is climbing the fastest as ablation volumes outpace specialist availability.
Delivery Mode:
Procedure invasiveness level shapes capital requirements, reimbursement coding, and workforce training intensity.
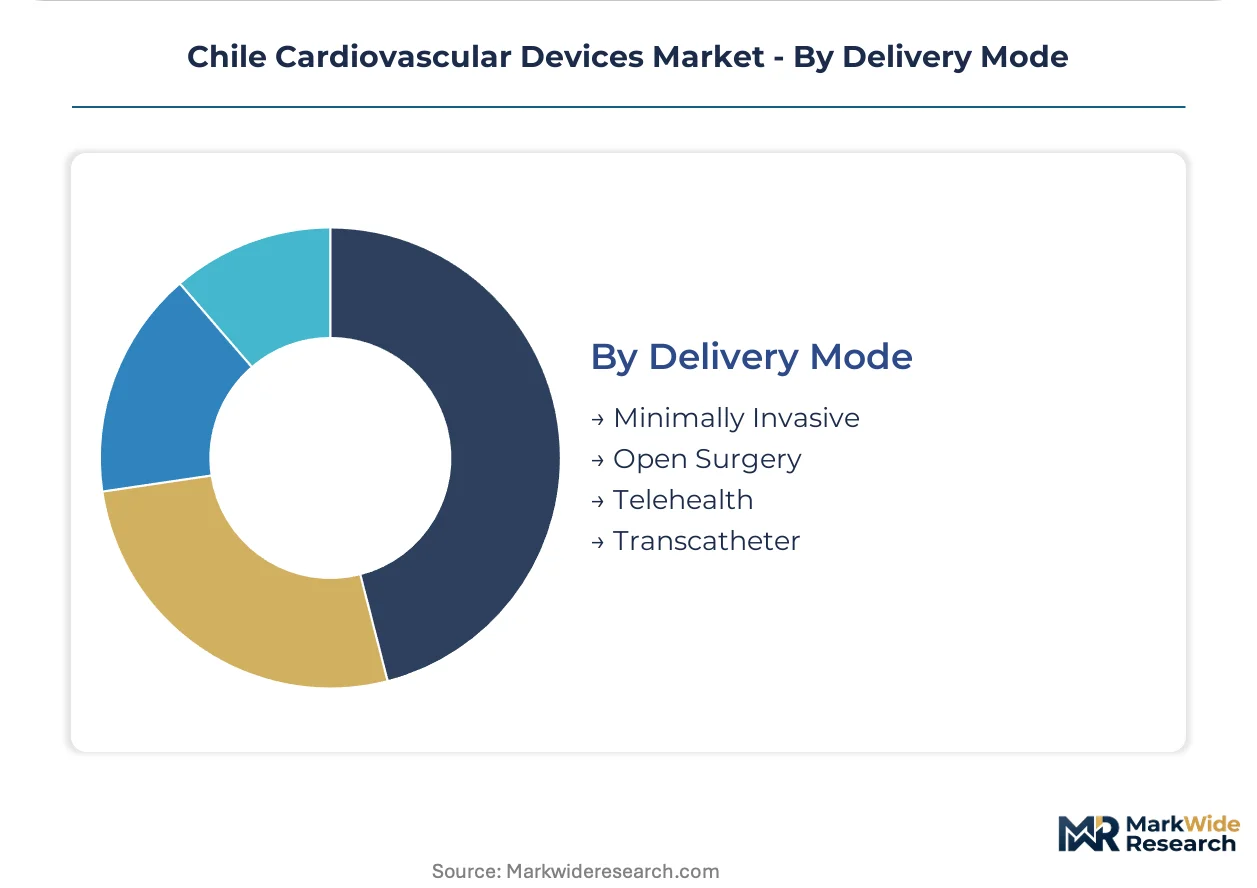
- Transcatheter:Percutaneous approaches via femoral or radial access displace open surgical revascularization in eligible coronary and structural heart populations. Interventional cardiologists in Santiago's catheterization laboratories capture margin concentration through volume density.
- Minimally Invasive:Hybrid procedures combining surgical and catheter-based techniques address complex multivessel disease.
- Open Surgery:Coronary artery bypass grafting retreats to patients with complex anatomy unsuitable for PCI.
- Telehealth:Remote monitoring and consultation platforms support post-procedural follow-up rather than acute intervention.
Transcatheter approaches command the established base. Minimally Invasive hybrid techniques are expanding most quickly as case complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AUGE-GES universal coverage mandates are redistributing cardiovascular device procurement across Chile's administrative regions, with public hospital consortia consolidating purchasing power in high-volume zones while provincial networks lag in catheterization infrastructure.
Metropolitan Region
Santiago's tertiary cardiac centers generate the densest procedure volumes nationally, with Hospital Metropolitano consortium bundling stent and catheter allocations across twelve facilities. The Instituto de Salud Pública maintains its headquarters here, streamlining registration pathways for importers. Clínica Alemana and Hospital Clínico Universidad de Chile anchor interventional cardiology training and device evaluation programs.
Valparaíso Region
Port city industrial corridors sustain manufacturing workforce cardiovascular risk profiles that drive diagnostic demand. Regional service networks under AUGE-GES lack dedicated catheterization laboratories, forcing patient transfers to Santiago. Hospital Carlos Van Buren in Viña del Mar operates the province's busiest emergency cardiac receiving center.
Biobío Region
Concepción's university hospital system trains interventional cardiologists but retains graduates inadequately. The Superintendencia de Salud audits AUGE-GES compliance unevenly across provincial facilities. Hospital Guillermo Grant Benavente manages complex cases with outdated hemodynamic monitoring platforms.
Araucanía Region
Rural indigenous populations present late-stage coronary disease requiring mechanical circulatory support. Regional procurement budgets concentrate on basic diagnostic imaging rather than interventional suites. Hospital Hernán Henríquez Aravena in Temuco triages patients for Santiago transfer.
Antofagasta Region
Mining sector occupational health programs fund preventive cardiac screening for remote workforce populations. Private clinic networks serving expatriate mining engineers deploy premium electrophysiology devices outside public tender systems. Clínica Antofagasta operates independent catheterization capacity.
Chile Cardiovascular Devices Market Competitive Environment
On the supply side, the industry is consolidating around multinational device manufacturers with established Mercosur regulatory pathways and localized distribution partnerships. Three strategic archetypes dominate: diversified cardiovascular portfolios spanning stents through imaging, specialized electrophysiology and structural heart platforms, and diagnostic imaging systems integrated with interventional workflows. Competitive moves center on multi-year tender participation in public hospital consortia and technology licensing agreements to bypass ISP registration delays.
Among US-based diversified manufacturers, Boston Scientific Corporation and Medtronic PLC occupy positions anchoring interventional portfolio breadth, while Abbott Laboratories exemplifies drug-eluting platform specialization aligned with AUGE-GES reimbursement expansion. Siemens Healthineers AG represents European imaging-to-intervention integration, competing through echocardiography and angiography installed base extensions into provincial cardiac centers.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic PLC |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Philips Healthcare |
| Nihon Kohden Corporation |
| GE Healthcare |
| Edwards Lifesciences Corporation |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Santiago's Metropolitan Region concentrates Chile's catheterization laboratory capacity, and this geographic density of tertiary cardiac centers grants procurement consortia substantial leverage over multinational device vendors. The Hospital Metropolitano consortium bundles stent and catheter volumes across twelve facilities, compressing margins for imported platforms while amplifying price transparency across AUGE-GES reimbursement tiers.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA-cleared and CE-marked drug-eluting stents commanding substantial premiums over bare-metal alternatives in public tenders. Three-tier pricing structure across premium, standard, and economy levels reflects ISP registration status, clinical evidence depth, and after-sales service bundling. Cost compression in the economy tier is intensifying because regional service networks prioritize volume commitments over feature differentiation. Public hospital procurement committees exhibit highest price sensitivity, while private cardiac clinics in Santiago absorb premiums for novel electrophysiology platforms.
Supply Chain Analysis
US export controls on advanced semiconductor components constrain electrophysiology mapping system availability, forcing Chilean importers to navigate dual-use technology licensing. Manufacturing concentrates in the United States, Ireland, and Costa Rica for finished devices, with cobalt-chromium alloy feedstock drawn from German and Japanese metallurgical suppliers. Single-source vulnerability pervades the drug-eluting coating chemistry segment, where proprietary polymer formulations remain captive to original developers. Distribution runs through authorized distributor networks holding ISP import licenses, with regional warehousing in Santiago serving provincial public hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device vendors should treat Chile as a service-attach market where training contracts and preventive maintenance agreements expand faster than hardware shipments. Electrophysiology suite technical support and catheterization laboratory biomedical engineering services represent the fastest-growing recurring revenue layers.
For Market Incumbents: Pre-empt provincial laboratory expansion by securing exclusive technical service contracts with emerging regional cardiac centers before competitors establish installed bases. Lock in multi-year stent supply agreements with Hospital Metropolitano consortium members to forestall Abbott's drug-eluting platform displacement. Vertical integration into Santiago-based biomedical engineering training programs addresses workforce scarcity while creating switching costs for public hospital clients.
For New Entrants and Emerging Players: Valparaíso Region's catheterization capacity gap offers first-mover positioning before AUGE-GES mandates force infrastructure investment. Target electrophysiology device distribution through private clinic networks operating outside consolidated tender systems, where faster procurement cycles reward novel ablation catheter platforms. Partner with Concepción's university hospital system to embed mapping systems within interventional cardiology training curricula.
For Investors and Strategic Acquirers: Long-term, this sits as a reimbursement-expansion play because AUGE-GES coverage mandates for percutaneous coronary intervention will compound procedure volumes regardless of macroeconomic cycles. Acquisition candidates include specialized electrophysiology distributors with established ISP regulatory pathways and relationships with Santiago's private cardiac clinic network. Monitor Superintendencia de Salud audit intensity as the signal for when real-world outcome data requirements will tighten reimbursement thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| ISP Registration Acceleration | Shortening 18-24 month approval timelines for novel drug-eluting platforms captures AUGE-GES reimbursement windows. |
| Provincial Laboratory Partnership | First-mover agreements with Valparaíso and Biobío regional networks secure volume before tender consolidation. |
| Biomedical Engineer Training Program | Captive workforce development addresses public hospital recruitment failures while creating service-attach revenue. |
| Electrophysiology Suite Buildout | Ablation procedure growth outpaces current device availability, opening specialty catheter and mapping system demand. |
| Mercosur Harmonization Preparation | Early alignment with pending technical regulation updates streamlines conformity assessment for Brazilian and Argentine certifications. |
Study Parameters
A spread of perspectives from interventional cardiologists, hospital procurement committee members, biomedical engineers, and ISP regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary interviews with catheterization laboratory directors and GPO contracts managers combined with secondary validation from hospital procurement databases, AUGE-GES coverage mandate documents, and Mercosur technical regulation filings. Bottom-up procedure volume estimates triangulated against top-down device shipment data from authorized distributor networks.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across product type, end user, technology, and delivery mode dimensions. CAGRs derived from fitted growth curves applied to historical procedure volumes and device replacement cycles. Industry-specific forecast inputs incorporated ISP registration pipeline status and AUGE-GES reimbursement expansion timelines.
Practitioners should monitor ISP stability testing requirement updates and Superintendencia de Salud audit protocols for early signals of regulatory friction. Forecasts reflect assumptions about continued AUGE-GES coverage expansion and Mercosur harmonization progress. Material shifts in Chilean peso volatility or import licensing delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Resuscitation Bags Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Cardiovascular Ultrasound Imaging Systems Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Atherectomy Devices Market