
 North America Ovarian Cancer Diagnostics Market | 2026-2036
North America Ovarian Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ovarian Cancer Diagnostics Market Analytics
The capital-intensity divergence between integrated platform developers and point-of-care test manufacturers is bifurcating competitive strategy across the North America ovarian cancer diagnostics landscape. F. Hoffmann-La Roche Ltd leverages its centralized laboratory automation infrastructure to sustain high-throughput CA-125 and HE4 testing workflows in hospital systems. Thermo Fisher Scientific Inc. anchors its position through next-generation sequencing panels that compete on breadth of genomic coverage for hereditary risk assessment.
Ovarian cancer diagnostics encompasses laboratory and imaging modalities designed to detect malignant neoplasms of the ovaries, fallopian tubes, and primary peritoneum, utilizing biomarker quantification, radiologic morphologic assessment, and histopathologic confirmation with sensitivity thresholds dictating clinical utility. Blood tests and genetic testing command expanding share as liquid biopsy technologies and multigene panel accessibility reshape frontline screening paradigms, while imaging tests retain structural importance in surgical staging and recurrence monitoring. The technology dimension shows computed tomography and magnetic resonance imaging maintaining established roles in metastasis detection, whereas ultrasound persists as the initial pelvic evaluation standard.
The FDA governs premarket approval and breakthrough device pathways for novel diagnostics, while CLIA certification requirements shape operational standards for diagnostic laboratories processing ovarian cancer specimens. Health Canada and the Canadian Agency for Drugs and Technologies in Health parallel this framework with evidence-based reimbursement assessments that condition provincial adoption. Stakeholders must monitor evolving biomarker qualification criteria and coverage determination shifts as proteomic and genomic signatures transition from research tools to standard-of-care instruments.
Market Dynamics
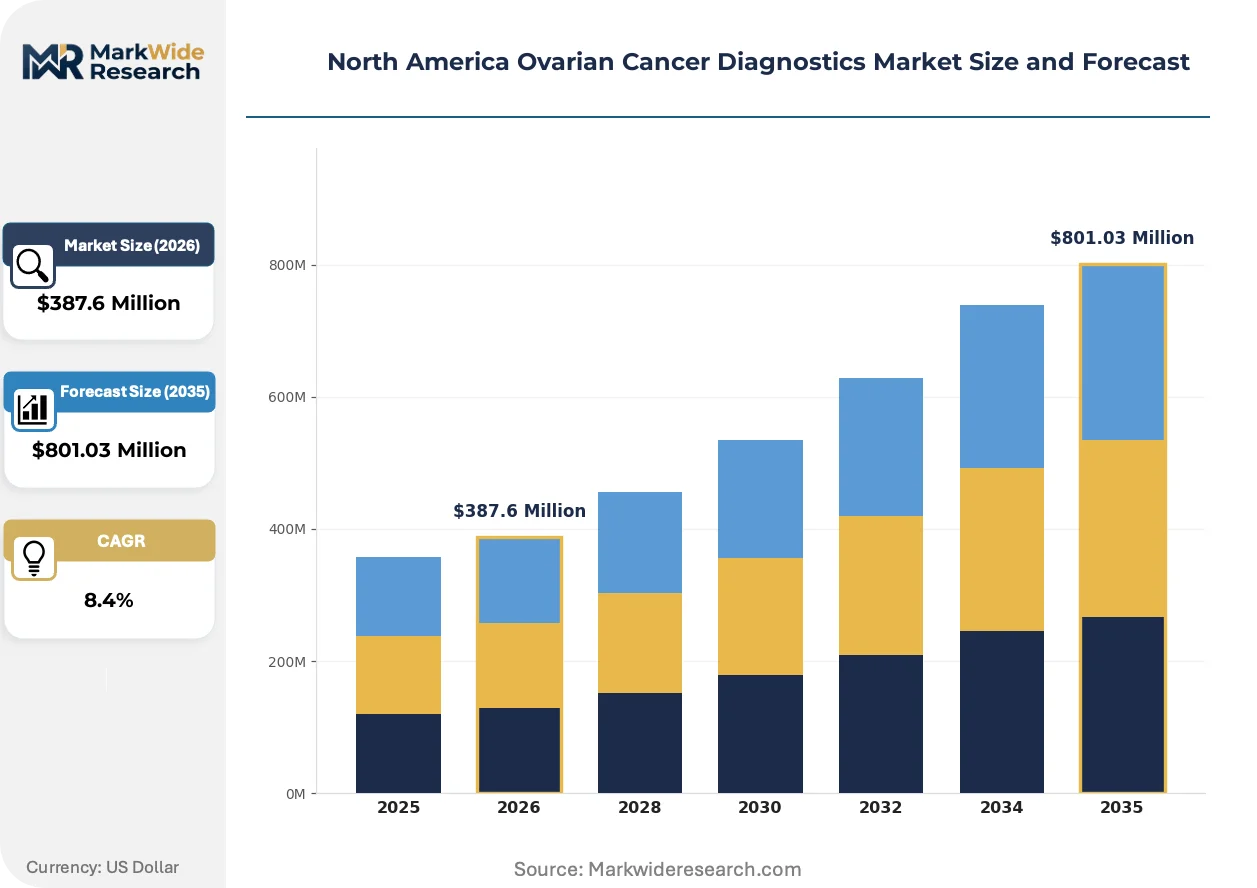
The FDA's breakthrough device designation pathway is compressing commercialization timelines for novel biomarker assays, while diagnostic laboratories accelerate molecular profiling platform adoption to capture high-margin hereditary risk assessment volumes.
Growth Catalysts
- CLIA-certified laboratory expansion:Diagnostic laboratories in Texas and California are scaling next-generation sequencing capacity to meet rising demand for BRCA1/2 and Lynch syndrome panel testing in oncology networks.
- Multi-cancer early detection integration:Blood-based liquid biopsy technologies are entering clinical workflows as adjunctive screening tools for high-risk patient populations in academic medical centers.
- Provincial reimbursement alignment:Health Canada's parallel evidence assessment frameworks with CADTH are accelerating provincial adoption of novel proteomic signatures in Ontario and British Columbia.
Market Restraints
- Reagent supply concentration:Polymerase chain reaction master mixes and targeted capture probes concentrate manufacturing in a limited supplier base, creating input cost volatility for regional laboratories.
- Technical specificity ceilings:CA-125 and HE4 biomarkers exhibit elevated false-positive rates in premenopausal populations, constraining frontline screening utility in primary care settings.
- Reimbursement code fragmentation:CPT coding complexity for multigene panels versus single-analyte tests creates claims adjudication friction that delays laboratory revenue recognition.
Strategic Opportunities
- Underpenetrated Canadian provinces:Alberta and Manitoba present whitespace for centralized reference laboratory partnerships given lower per-capita access to academic medical center pathology networks.
- Artificial intelligence-pathology convergence:Digital whole-slide imaging platforms integrated with machine learning algorithms are enabling automated morphometric assessment of fallopian tube lesions.
- Direct-to-consumer channel emergence:Telehealth-integrated genetic counseling services are creating new patient acquisition pathways for hereditary cancer risk assessment outside traditional oncology referrals.
Industry Challenges
- Bioinformatics talent scarcity:Variant interpretation and clinical genomics reporting functions face persistent recruitment gaps that constrain laboratory throughput scaling.
- IVD-RUO classification ambiguity:FDA enforcement discretion boundaries for laboratory-developed tests versus in vitro diagnostics create compliance timeline uncertainty for multianalyte algorithmic assays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ovarian Cancer Diagnostics Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Blood Tests, Imaging Tests, Biopsies, Genetic Testing Technology: Computed Tomography, Magnetic Resonance Imaging, Ultrasound, CA-125 Test End User: Hospitals, Diagnostic Laboratories, Research Institutes, Oncology Clinics Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Wholesalers |
| Companies Covered | F. Hoffmann-La Roche Ltd, Quest Diagnostics Incorporated, Thermo Fisher Scientific Inc., Abbott, Siemens Healthineers, Bio-Rad Laboratories Inc., Myriad Genetics Inc., Illumina Inc., Luminex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ovarian Cancer Diagnostics Market Evolving Landscape
Technological convergence between liquid biopsy platforms and artificial intelligence analytics is restructuring competitive advantage around data integration capabilities rather than discrete test performance.
Next-generation sequencing-based circulating tumor DNA assays are decomposing the traditional tissue-first diagnostic paradigm in platinum-resistant recurrence monitoring. Community oncology practices in Florida and Arizona are adopting these platforms faster than academic centers due to biopsy accessibility constraints. This shift is compressing pathology department revenue from repeat surgical procedures while elevating longitudinal monitoring contract values.
The FDA's breakthrough device designation pathway is streamlining premarket review for proteomic signature tests that combine multiple biomarkers into single risk scores. Manufacturers are restructuring clinical trial designs to align with real-world evidence requirements under this framework. High-complexity laboratories in major metropolitan cancer centers are the primary beneficiaries, gaining first-mover access to novel assays before broader commercial release.
Consolidated purchasing by integrated delivery networks is displacing independent laboratory selection autonomy in ovarian cancer diagnostics procurement. Hospital systems in the Northeast and Midwest are mandating exclusive contracts with single reference laboratories for molecular testing. This concentration is most visible in Pennsylvania and Ohio, where three health systems now control over half of high-complexity oncology specimen volume in their respective states.
North America Ovarian Cancer Diagnostics Market Segmentation
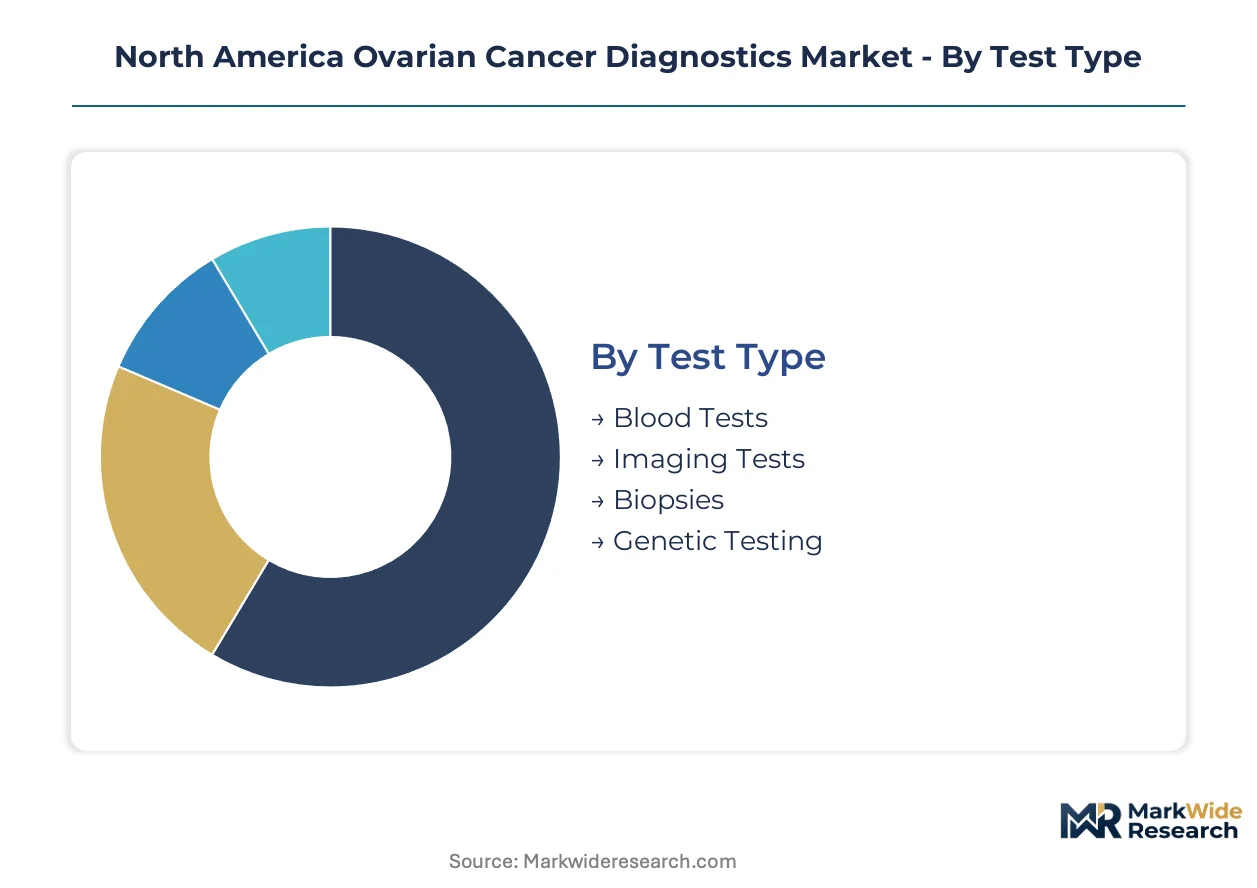
Segmentation in the North America ovarian cancer diagnostics market reveals how test modality, technology platform, and procurement channel determine where value concentrates. Each dimension carries distinct regulatory, reimbursement, and operational requirements that shape vendor strategy across the United States and Canada.
Test Type:
Blood tests and genetic panels dominate domestic laboratory volumes, while imaging and biopsy services concentrate in hospital-based cancer centers with surgical capacity. Export-oriented innovation flows from U.S. academic medical networks into Canadian provincial health systems.
- Blood Tests:CA-125 and HE4 quantification assays process through CLIA-certified laboratories in Texas and California. Demand clusters in major metropolitan cancer centers where longitudinal monitoring protocols require high-throughput automation.
- Genetic Testing:BRCA1/2 and Lynch syndrome multigene panels deploy next-generation sequencing workflows for hereditary risk assessment. Ontario and British Columbia health authorities are expanding provincial coverage for cascade testing in high-risk families.
- Imaging Tests:CT and MRI protocols for metastasis detection.
- Biopsies:Tissue acquisition for histopathologic confirmation.
Blood tests command the established base. The steepest expansion runs through genetic testing.
Technology:
Platform selection tracks capital intensity and reimbursement tier. High-field MRI and molecular assays occupy premium pricing bands, while ultrasound and conventional immunoassays serve cost-constrained community settings.
- CA-125 Test:Established immunoassay platforms from Roche and Abbott anchor routine monitoring in U.S. hospital laboratories. Elevated false-positive rates in premenopausal populations constrain frontline screening deployment in primary care networks.
- Magnetic Resonance Imaging:Pelvic MRI protocols deliver superior soft-tissue contrast for surgical staging in academic medical centers. Installation concentrates in Northeast and Midwest health systems with dedicated gynecologic oncology programs.
- Computed Tomography:Abdominopelvic CT for metastasis detection.
- Ultrasound:Transvaginal sonography for initial pelvic evaluation.
CA-125 testing commands the established base. The steepest expansion runs through MRI protocols.
End User:
Customer type determines contract structure and service intensity. Integrated delivery networks consolidate purchasing power, while independent laboratories compete on turnaround time and specialized assay menus.
- Diagnostic Laboratories:Quest Diagnostics and LabCorp scale molecular profiling capacity across multi-state networks. CLIA-certified facilities in Florida and Arizona are adopting circulating tumor DNA platforms faster than academic centers due to biopsy accessibility constraints.
- Hospitals:In-house pathology departments in Pennsylvania and Ohio health systems now process over half of high-complexity oncology specimens through exclusive reference laboratory contracts.
- Oncology Clinics:Community-based infusion centers in suburban markets.
- Research Institutes:Academic medical center laboratories conducting biomarker qualification studies.
Diagnostic laboratories command the established base. The steepest expansion runs through hospital consolidation.
Distribution Channel:
Channel selection reflects test complexity and regulatory classification. High-complexity molecular assays require direct field service support, while commoditized reagents flow through distributor networks.
- Direct Sales:Manufacturers of next-generation sequencing platforms and automated immunoassay systems deploy specialized field application scientists to hospital laboratories. Thermo Fisher and Roche maintain dedicated oncology diagnostics sales forces covering major U.S. metropolitan markets.
- Medical Distributors:McKesson and Cardinal Health route conventional imaging contrast agents and routine laboratory reagents to community hospitals and independent laboratories across the United States.
- Online Sales:Telehealth-integrated genetic counseling services enabling direct-to-consumer hereditary cancer risk assessment.
- Wholesalers:Bulk procurement intermediaries for standard laboratory consumables.
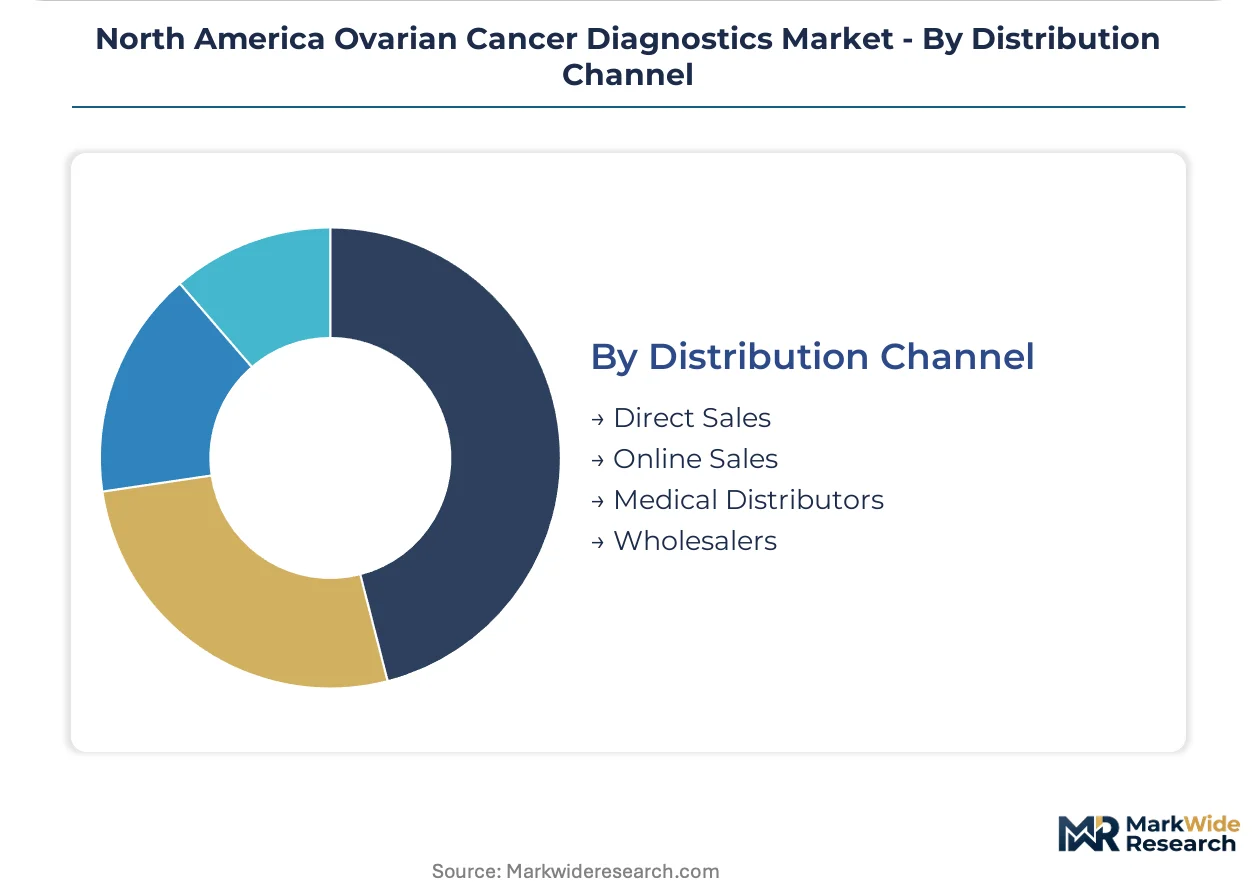
Direct sales command the established base. The steepest expansion runs through online channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates ovarian cancer diagnostics consumption in high-throughput hospital laboratories and academic medical centers, while Canada distributes testing across provincial reference networks with tighter reimbursement controls. Mexico operates a dual-tier system where private oncology clinics in Mexico City and Monterrey import advanced molecular assays, while public hospitals rely on conventional imaging and biomarker protocols.
United States
Texas and California laboratories scale next-generation sequencing capacity for BRCA1/2 hereditary risk panels. The FDA breakthrough device designation pathway accelerates commercialization timelines for novel proteomic signature tests. Major metropolitan cancer centers in Boston and New York anchor adoption of circulating tumor DNA platforms for platinum-resistant recurrence monitoring.
Canada
Ontario and British Columbia health authorities expand provincial coverage for multigene cascade testing in high-risk families. Health Canada and CADTH apply parallel evidence assessment frameworks that condition reimbursement decisions on real-world performance data. Centralized reference laboratories in Toronto and Vancouver process complex molecular profiling for Atlantic and Prairie provinces with limited pathology infrastructure.
Mexico
Private oncology networks in Mexico City and Monterrey drive demand for imported CA-125 and HE4 immunoassay platforms. The national pharmaceutical regulator oversees registration of in vitro diagnostics through a risk-based classification system. Guadalajara medical centers are establishing partnerships with U.S. reference laboratories to access next-generation sequencing hereditary cancer panels.
North America Ovarian Cancer Diagnostics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive structure in North American ovarian cancer diagnostics. The upper tier combines centralized laboratory automation with multi-platform biomarker portfolios, while specialists compete on turnaround velocity and niche assay menus. Three archetypes dominate: diversified life science conglomerates with diagnostics divisions, pure-play molecular testing laboratories, and precision medicine platform developers. Consolidation through exclusive reference laboratory contracts and technology licensing partnerships represents the primary competitive dynamic.
Among diversified diagnostics conglomerates, F. Hoffmann-La Roche Ltd and Abbott exemplify the integrated platform archetype, anchoring positions through established immunoassay infrastructure. Thermo Fisher Scientific Inc. occupies a position within the precision medicine tier, representing the convergence of next-generation sequencing hardware with oncology-focused content development. These three entities illustrate how scale-driven and specialization-driven strategies coexist within the same market structure.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Quest Diagnostics Incorporated |
| Thermo Fisher Scientific Inc. |
| Abbott |
| Siemens Healthineers |
| Bio-Rad Laboratories Inc. |
| Myriad Genetics Inc. |
| Illumina Inc. |
| Luminex Corporation |
| Others |
Value Network & Pricing Analysis
CLIA certification requirements and FDA breakthrough device designation pathways simultaneously gate supplier qualification and stratify price tiers across molecular diagnostic platforms. Buyers with integrated delivery network scale extract preferential terms from reference laboratories, while independent facilities absorb input cost volatility.
Pricing Analysis
Long-term exclusive contracts with integrated delivery networks dominate procurement for high-complexity molecular assays, while spot purchasing persists for routine reagents and consumables. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status, CLIA certification tier, and automation integration depth. Cost compression in economy-tier immunoassays is intensifying because of reagent supply concentration among limited polymerase chain reaction master mix manufacturers. Community oncology practices exhibit highest price sensitivity due to biopsy accessibility constraints, whereas academic medical centers prioritize assay breadth over unit economics.
Supply Chain Analysis
Polymerase chain reaction master mix manufacturing concentrates in the United States, Germany, and Japan, creating chokepoint vulnerability for regional laboratories scaling next-generation sequencing capacity. Targeted capture probes, sequencing reagents, and automated liquid handling consumables draw from this concentrated supplier base. Single-source vulnerability in proprietary probe chemistries exposes laboratories to input cost volatility and qualification timeline delays. Distribution runs through specialized field service teams for high-complexity platforms, while routine reagents flow through McKesson and Cardinal Health networks to community hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated purchasing by integrated delivery networks has shifted bargaining power toward hospital systems, fragmenting independent laboratory autonomy across Pennsylvania, Ohio, and the Northeast corridor.
For Market Incumbents: Fortify exclusive reference laboratory contracts with integrated delivery networks before provincial expansion in Alberta and Manitoba accelerates. Defensive consolidation through CLIA-certified facility acquisitions in Texas and California will offset emerging competition from telehealth-integrated genetic counseling platforms. Prioritize automation infrastructure investments that sustain high-throughput CA-125 and HE4 workflows against liquid biopsy substitution threats. For New Entrants and Emerging Players: Anchor in underpenetrated Canadian provinces where centralized reference laboratory partnerships remain whitespace for BRCA1/2 cascade testing expansion. Telehealth-integrated genetic counseling services represent the most penetrable channel for hereditary risk assessment outside traditional oncology referral pathways. Pursue provincial reimbursement alignment with Health Canada and CADTH evidence frameworks as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA breakthrough device designation reshapes the acquisition landscape by compressing commercialization timelines for proteomic signature developers and elevating platform valuations. Long-term viability across the analysis window favors precision medicine platform developers with integrated next-generation sequencing hardware and oncology content libraries. Monitor biomarker qualification criteria evolution as the primary signal for coverage determination shifts that would elevate multianalyte algorithmic assay valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates premarket review timelines for novel proteomic signature tests in high-complexity laboratories. |
| CLIA-Certified Laboratory Acquisition | Captures hereditary risk assessment volumes in Texas and California oncology networks. |
| Integrated Delivery Network Partnership | Locks in exclusive specimen processing contracts with Pennsylvania and Ohio health systems. |
| Liquid Biopsy Platform Integration | Enables circulating tumor DNA monitoring for platinum-resistant recurrence in community oncology settings. |
| Provincial Reimbursement Strategy | Aligns Health Canada evidence requirements with Ontario and British Columbia coverage expansion. |
Research Methodology
Operator-level perspectives from molecular diagnostics laboratory directors, gynecologic oncology clinicians, hospital procurement committee members, and Health Canada regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) and PMA filings, ClinicalTrials.gov biomarker qualification studies, CMS Medicare reimbursement databases, and provincial health authority coverage policies. Bottom-up laboratory capacity modeling and top-down market sizing triangulated volume estimates across test modality and technology platform dimensions.
Sensitivity analysis tested forecast robustness against alternative CLIA laboratory expansion scenarios and breakthrough device designation approval timelines. Segmentation dimensions modeled include test type, technology platform, end user category, and distribution channel across the projection horizon. CAGRs derived from laboratory throughput scaling curves, provincial reimbursement trajectory assumptions, and liquid biopsy adoption rate projections in community oncology versus academic medical center settings.
Decision-makers should treat outputs as directional under sustained FDA breakthrough pathway utilization and stable CLIA certification standards; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as Health Canada and CADTH evidence assessment frameworks evolve and as integrated delivery network consolidation patterns shift reference laboratory contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
In-Vitro Diagnostics Enzymes Market
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market