
 Mitral Valve Disease Market | 2026-2036
Mitral Valve Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Mitral Valve Disease Market Foresight
Transcatheter edge-to-edge repair is reconfiguring the treatment paradigm for degenerative mitral regurgitation, shifting eligible patients from open-heart surgery toward catheter-based interventions. Edwards Lifesciences Corporation leverages its SAPIEN platform expertise to extend capabilities into mitral applications. Medtronic Plc anchors its position through the Intrepid transcatheter mitral valve replacement program. Abbott Laboratories differentiates via the MitraClip system, which dominates commercial traction in edge-to-edge repair.
Mitral valve disease encompasses structural and functional disorders of the mitral apparatus—leaflets, annulus, chordae tendineae, and papillary muscles—that disrupt coaptation and generate regurgitant or stenotic flow patterns, with primary commercial purpose to restore hemodynamic competence and reduce heart failure progression. Transcatheter mitral valve replacement represents the fastest-growing product category as surgical-risk-ineligible patients drive addressable pool expansion. Catheter-based techniques command premium positioning within the technology dimension due to shorter recovery trajectories and expanding operator training programs. Surgical mitral valve repair retains volume leadership in younger patients with isolated degenerative disease and favorable anatomy.
FDA premarket approval pathways and the EU Medical Device Regulation shape trial design, post-market surveillance obligations, and market access timelines for transcatheter devices. The European Medicines Agency coordinates centralized assessments that influence reimbursement negotiations across member states. Stakeholders must monitor real-world evidence generation requirements and evolving health technology assessment criteria as payers tighten evidence standards for catheter-based therapies.
Market Dynamics
Transcatheter mitral valve replacement is collapsing the surgical-risk stratification that historically excluded high-risk patients from intervention, forcing manufacturers to reconfigure clinical trial design around real-world evidence endpoints rather than traditional surgical benchmarks.
Growth Catalysts
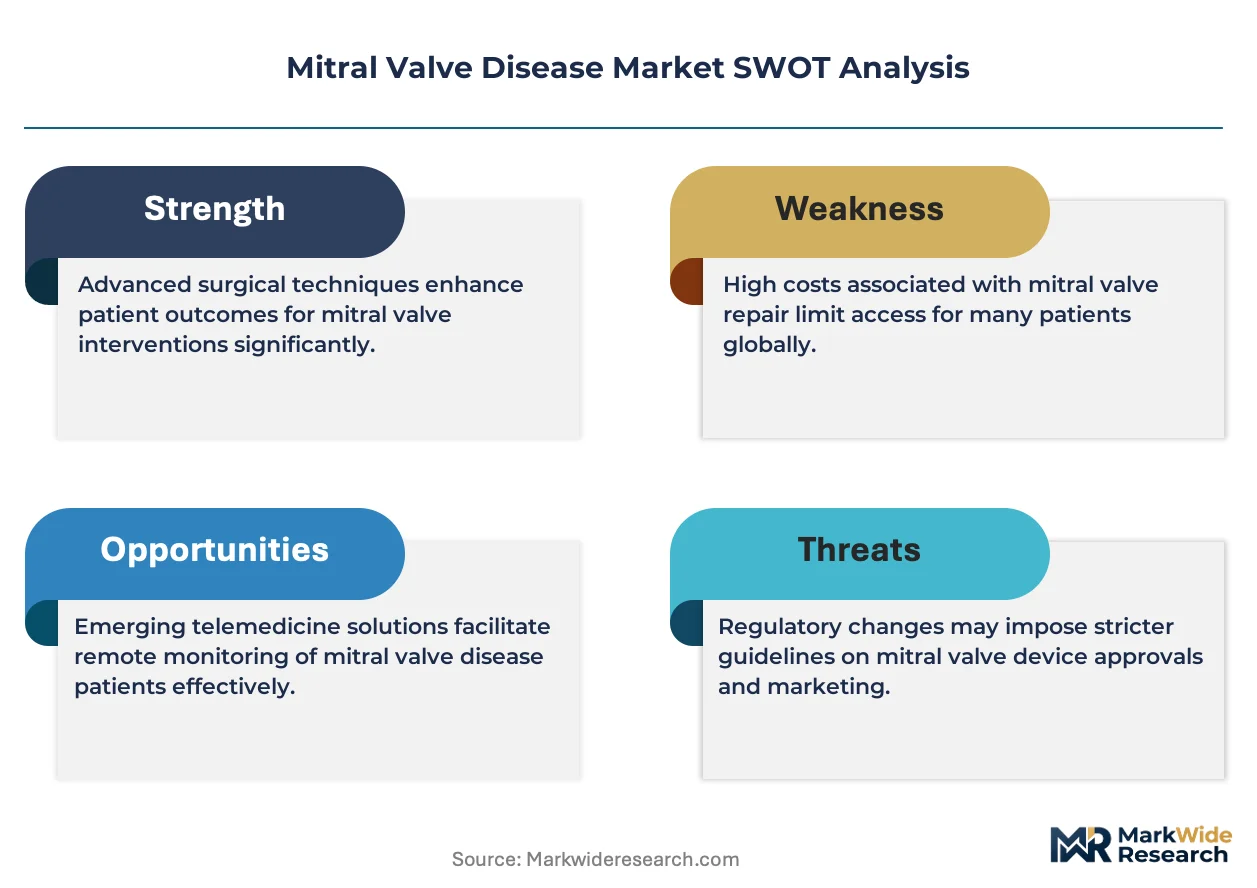
- FDA Breakthrough Device Designation:Accelerated review timelines compress development cycles for transcatheter systems, enabling earlier commercial entry for devices addressing unmet need in inoperable patient cohorts.
- Structural Heart Centers:Concentration of procedural expertise in dedicated cardiac hubs generates referral network effects that pull eligible patients toward catheter-based interventions over conventional surgery.
- Aging Demographics:Expanding populations over seventy-five with degenerative mitral regurgitation create addressable pools that surgical risk scores exclude, directly expanding transcatheter candidacy.
Market Restraints
- EU Medical Device Regulation:Enhanced post-market surveillance obligations and notified body capacity constraints extend CE marking timelines, compressing revenue recognition windows for European launches.
- Operator Training Bottlenecks:Procedural complexity demands extended proctoring programs that limit expansion velocity beyond established structural heart centers.
- Reimbursement Uncertainty:Health technology assessment bodies in Germany and Japan apply evolving evidence standards that delay positive coverage determinations for novel transcatheter indications.
Strategic Opportunities
- Functional Mitral Regurgitation Expansion:Underpenetrated secondary indications in heart failure populations represent white space beyond currently approved degenerative disease labels.
- Japan PMDA Priority Review:Sakigake designation pathway offers accelerated assessment for innovative devices, enabling earlier market entry relative to standard pharmaceutical and medical product review timelines.
- Annuloplasty-TAVR Convergence:Hybrid transcatheter approaches combining leaflet repair with annular remodeling technologies address complex anatomies that single-modality devices fail to treat.
Industry Challenges
- Imaging Integration Complexity:Real-time intraprocedural guidance demands seamless echocardiography-fluoroscopy fusion that existing catheter lab infrastructure often lacks, requiring capital-intensive upgrades.
- Long-Term Durability Data Gaps:Five and ten-year transcatheter valve performance remains undercharacterized relative to surgical benchmarks, complicating shared decision-making conversations with younger candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mitral Valve Disease Market |
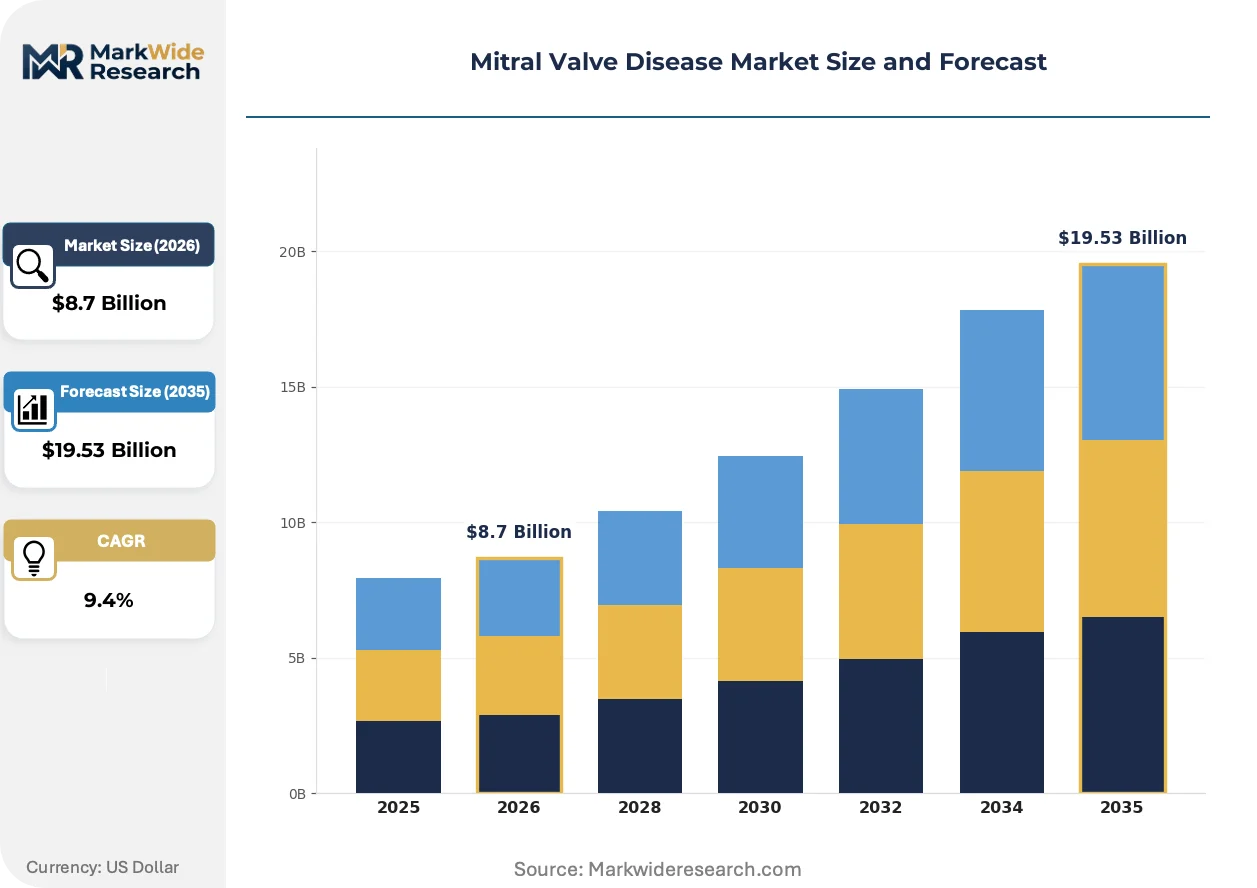
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mitral Valve Replacement, Mitral Valve Repair, Transcatheter Mitral Valve, Surgical Mitral Valve End User: Hospitals, Cardiac Clinics, Outpatient Centers, Specialty Cardiovascular Centers Technology: Minimally Invasive Surgery, Catheter-Based Techniques, Robotic Surgery, Conventional Surgery Treatment Approach: Medical Management, Surgical Intervention, Transcatheter Therapy, Combined Approach |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic Plc, Abbott Laboratories, Boston Scientific Corporation, LivaNova PLC, Corcym UK Limited, Artivion, Inc., ShockWave Medical, Inc., Valcare Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mitral Valve Disease Market Shifts & Advancements
Device miniaturization and computational modeling are converging to enable patient-specific procedural planning, compressing the gap between anatomical assessment and therapeutic execution while reducing complication rates.
Transcatheter mitral valve replacement is collapsing the historical surgical monopoly on definitive valve therapy. Cardiac surgeons at high-volume centers now refer anatomically complex patients to interventional cardiologists for catheter-based approaches. This shift compresses the traditional division of labor between surgical and interventional disciplines, forcing cross-training investments and shared ownership models.
CE marking under the EU Medical Device Regulation now demands extended clinical follow-up and proactive post-market clinical follow-up studies. Manufacturers must maintain robust quality management systems and vigilance reporting infrastructure. Transcatheter device portfolios face the steepest compliance burden given their novel risk classification and limited long-term track records.
Hospital procurement committees now bundle structural heart program investments across imaging, catheterization laboratory capacity, and operator credentialing. Integrated service contracts replace discrete device purchasing, tying vendor selection to training commitment and case volume guarantees. This consolidation concentrates purchasing power at academic medical centers in the United States and university hospitals in Germany.
Mitral Valve Disease Market Segmentation
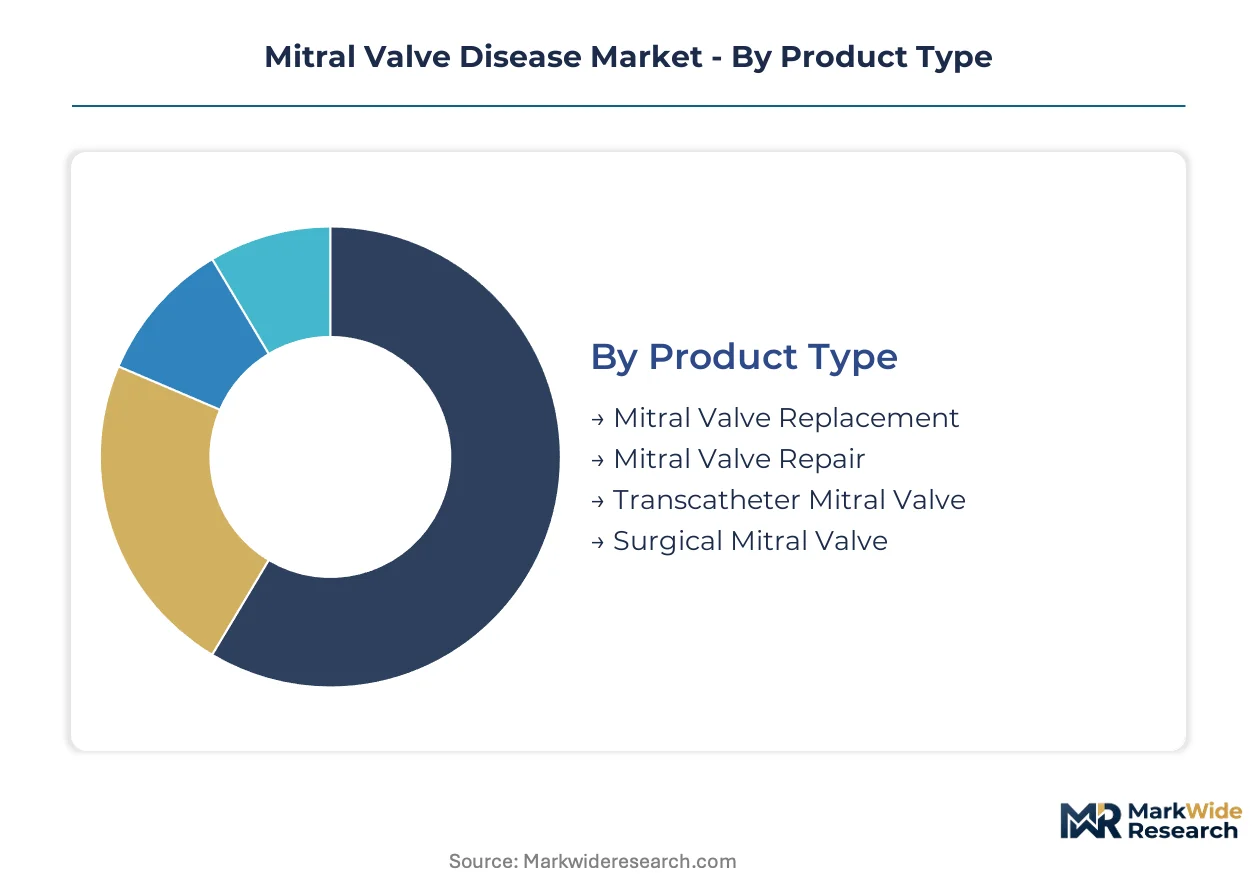
Segmentation in the mitral valve disease market reveals how procedural economics and clinical risk stratification allocate revenue across intervention modalities. Device manufacturers configure service contracts and training commitments differently for each category, directly influencing margin structures and customer lifetime value calculations.
Product Type:
After-sales service intensity varies sharply across product categories, with transcatheter systems demanding continuous imaging integration support and surgical valves requiring less intensive technical servicing.
- Transcatheter Mitral Valve:Self-expanding or balloon-expandable prostheses delivered via femoral or transapical access. Demand concentrates in United States academic medical centers and German university hospitals where structural heart programs absorb the steep learning curve and capital requirements.
- Mitral Valve Repair:Annuloplasty rings and bands that remodel the native valve apparatus. Cardiac surgeons at Cleveland Clinic and Mayo Clinic anchors drive volume for durable repair over replacement in younger patients with isolated degenerative disease.
- Mitral Valve Replacement:Mechanical and bioprosthetic substitutes for irreparable native valves. Demand persists in rheumatic disease corridors of India and sub-Saharan Africa where tissue repair options remain limited.
- Surgical Mitral Valve:Conventional sternotomy and minimally invasive approaches using standard cardiopulmonary bypass. Volume leadership sits with established cardiac surgery programs in Japan and South Korea.
Transcatheter mitral valve holds the largest share; momentum sits with mitral valve repair.
End User:
Capital deployment patterns distinguish customer types, with specialty cardiovascular centers amortizing equipment across high procedural volumes while outpatient centers struggle with fixed-cost absorption.
- Hospitals:Integrated health systems with emergency bypass capability and 24-hour cardiac surgery backup. United States hospital networks in Texas and Florida generate concentrated transcatheter volumes through hub-and-spoke referral models.
- Specialty Cardiovascular Centers:Dedicated structural heart facilities with hybrid operating rooms and multimodality imaging suites. German centers in Munich and Heidelberg anchor European transcatheter adoption through coordinated operator training pipelines.
- Cardiac Clinics:Diagnosis and longitudinal management sites that refer intervention-eligible patients to procedural centers. Japanese cardiology clinics in Tokyo and Osaka feed high-volume centers through standardized severity grading protocols.
- Outpatient Centers:Ambulatory facilities focused on diagnostic workup and post-procedural surveillance. Limited penetration in transcatheter delivery due to anesthesia and rescue surgery requirements.
Specialty cardiovascular centers capture the steepest expansion trajectory; hospitals retain volume dominance.
Technology:
Training infrastructure requirements stratify technology adoption, with robotic surgery demanding dedicated simulator programs and conventional surgery leveraging existing apprenticeship models.
- Catheter-Based Techniques:Transfemoral and transapical approaches without sternotomy or cardiopulmonary bypass. United States interventional cardiology fellowship programs at New York-Presbyterian and Cedars-Sinai produce qualified operators that expand addressable geography.
- Minimally Invasive Surgery:Right mini-thoracotomy and partial sternotomy approaches with direct visualization. German cardiac surgery departments prioritize these techniques for degenerative repair in low-to-intermediate surgical risk patients.
- Robotic Surgery:Da Vinci platform telemanipulation for mitral repair with enhanced dexterity and tremor filtration. Intuitive Surgical training commitments limit expansion to centers with guaranteed case volume thresholds.
- Conventional Surgery:Median sternotomy with standard cardiopulmonary bypass and direct visualization. Remains default for complex multivalve disease and reoperative scenarios across India and Southeast Asia.
Catheter-based techniques are expanding most quickly; conventional surgery anchors procedural volume.
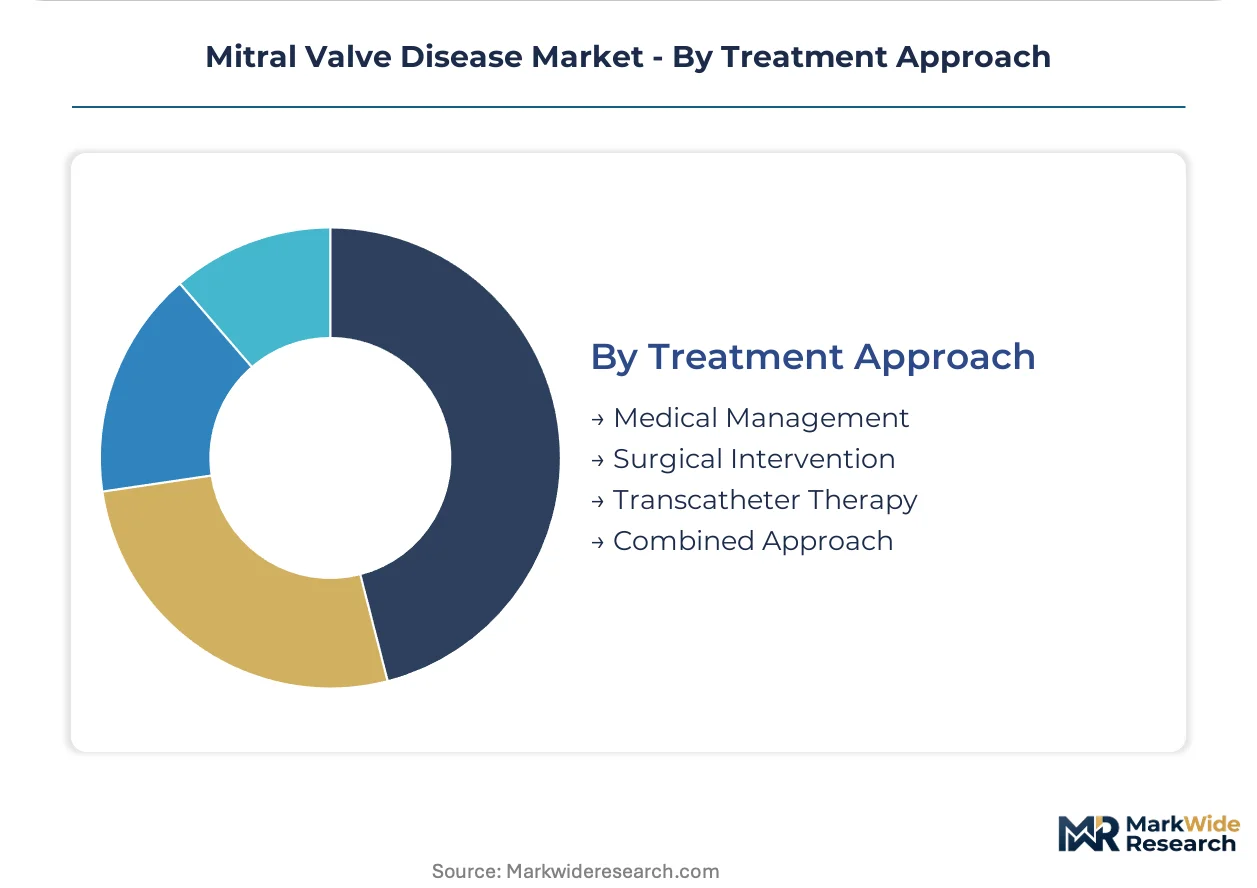
Treatment Approach:
Reimbursement pathway complexity segments treatment modalities, with transcatheter therapy navigating novel technology add-on payments while medical management relies on established pharmaceutical billing codes.
- Transcatheter Therapy:Catheter-based repair or replacement without surgical incision. United States Medicare new technology add-on payments and German DRG negotiations determine site profitability and expansion incentives.
- Surgical Intervention:Open or minimally invasive repair and replacement with direct visualization. Japanese J-ROAD and J-ROAD II registry data supports durability claims that sustain reimbursement for younger patient cohorts.
- Medical Management:Diuretics, afterload reduction, and guideline-directed medical therapy for heart failure. Serves as bridge to intervention or definitive therapy for inoperable candidates across all geographies.
- Combined Approach:Hybrid procedures integrating catheter-based and surgical techniques in single setting. German heart teams in Berlin and Hamburg pioneer these protocols for complex functional regurgitation with annular dilation.
Surgical intervention retains volume leadership; transcatheter therapy gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export transcatheter valve systems to United States academic medical centers, establishing the primary trade-flow corridor in structural heart devices.
United States
Medicare new technology add-on payments and commercial payer coverage expansion drive transcatheter procedure volumes. FDA breakthrough device designation accelerates premarket review timelines for mitral replacement systems. Cleveland Clinic and Mayo Clinic anchor structural heart referral networks that concentrate eligible patients in Ohio and Minnesota.
Germany
G-BA health technology assessment determinations and DRG reimbursement negotiations shape site-level profitability for catheter-based interventions. EU Medical Device Regulation mandates extended post-market surveillance that extends CE marking timelines. Munich and Heidelberg university hospitals coordinate operator training pipelines that feed European adoption.
Japan
PMDA Sakigake priority review designation offers accelerated assessment pathways for innovative transcatheter devices. Aging demographics above seventy-five expand the addressable pool for surgical-risk-ineligible candidates. Tokyo and Osaka cardiology clinics feed high-volume centers through standardized severity grading protocols.
United Kingdom
NICE technology appraisals and NHS England specialized commissioning frameworks determine patient access to novel mitral interventions. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for transcatheter systems. London teaching hospitals and the Oxford-Cambridge corridor concentrate structural heart expertise and procedural volume.
India
Rheumatic heart disease burden and growing private healthcare infrastructure create dual-market dynamics for surgical and transcatheter approaches. CDSCO medical device rules govern import licensing and clinical trial requirements for foreign manufacturers. Apollo and Fortis hospital networks in Delhi-NCR and Mumbai build structural heart capabilities through international training partnerships.
Mitral Valve Disease Market Competitive Landscape
On the supply side, the industry is consolidating around integrated cardiovascular platforms with dedicated structural heart divisions. Tier-one conglomerates with cardiac surgery heritage compete against interventional-focused specialists with catheter-lab expertise. Strategic archetypes span platform-integrated multinationals, pure-play transcatheter innovators, and surgical valve incumbents expanding into catheter-based modalities. Dominant competitive moves include technology licensing partnerships and vertical integration into imaging and procedural planning software.
Within the platform-integrated tier, Edwards Lifesciences Corporation, Medtronic Plc, and Abbott Laboratories exemplify archetypes that leverage SAPIEN franchise expertise, Intrepid program development, and MitraClip commercial traction respectively. These California-based, Ireland-domiciled, and Illinois-headquartered entities occupy positions that reflect divergent strategic bets on replacement versus repair modalities.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic Plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| LivaNova PLC |
| Corcym UK Limited |
| Artivion, Inc. |
| ShockWave Medical, Inc. |
| Valcare Medical |
| Others |
Supply & Pricing Matrix
Swiss precision machining clusters for nitinol frames and bovine pericardium sourcing from controlled Australian herds concentrate upstream margin capture, forcing transcatheter device manufacturers to absorb feedstock volatility while competing on bundled service contracts downstream.
Pricing Analysis
First-generation surgical valves, current-generation transcatheter repair systems, and next-generation replacement platforms occupy distinct pricing tiers. Three-tier pricing structure across premium transcatheter replacement, standard edge-to-edge repair, and economy surgical valves dominates procurement negotiations. Price differentiation hinges on FDA breakthrough designation status and procedural training bundling. Cost compression in the surgical tier is intensifying because hospital procurement committees consolidate purchasing power through integrated service contracts. Outpatient cardiac clinics exhibit highest price sensitivity; academic medical centers with guaranteed case volumes command steepest discounts.
Supply Chain Analysis
Bovine pericardium tissue banks in Australia, nitinol smelting operations in the United States, and cleanroom assembly facilities in Ireland anchor upstream feedstock security. Raw material dependencies encompass shape-memory alloys, biological tissue matrices, and fluoropolymer delivery sheaths. Single-source vulnerability for tissue processing creates exposure to veterinary health regulations in source countries. Distribution runs through GPO contracts with integrated health systems and direct-to-hospital agreements for specialty cardiovascular centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transcatheter mitral valve replacement is entering a cyclical recovery phase as aging demographics above seventy-five expand addressable pools beyond surgical-risk stratification limits.
For Market Incumbents: Pre-empt functional mitral regurgitation label expansion by accelerating real-world evidence generation before competitor devices secure secondary indication approvals. Secure backward integration into tissue processing capabilities to mitigate Australian feedstock regulatory exposure. Lock hospital system partnerships through guaranteed operator training commitments and hybrid OR capital co-investment.
For New Entrants and Emerging Players: Establish a beachhead in Indian rheumatic disease corridors where surgical valve replacement persists and transcatheter penetration remains minimal. Target private hospital networks in Delhi-NCR and Mumbai through international training partnerships that bypass established structural heart center oligopolies. Pursue CDSCO regulatory pathway optimization as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed transcatheter repair specialists possessing European CE marking but limited United States market access. Five-to-ten year viability hinges on durability data maturation and functional indication expansion. Monitor FDA pre-submission meeting outcomes for novel annuloplasty-TAVR convergence devices as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses development cycles for high-risk patient cohorts. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic referral networks concentrate eligible patient flows. |
| CE Marking Under EU MDR | Extended post-market surveillance obligations extend European launch timelines. |
| Operator Training Pipeline | New York-Presbyterian and Cedars-Sinai fellowship programs expand qualified geography. |
| Reimbursement Strategy | Medicare new technology add-on payments determine United States site profitability. |
Research Methodology
Cross-validation between primary interviews with interventional cardiologists, cardiac surgeons, hospital purchasing committee members, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EMA centralized assessment reports, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up procedure volume modeling triangulates with top-down market sizing across product type, technology, and treatment approach dimensions.
Calibration against historical adoption curves for transcatheter aortic valve replacement informs penetration rate assumptions across the projection horizon. Segmentation dimensions encompass product category, procedural technology, end-user facility type, and regional regulatory cluster. CAGRs derive from logistic diffusion modeling of eligible patient pools and operator capacity expansion. Forecast inputs incorporate PMDA Sakigake designation timelines and G-BA health technology assessment negotiation patterns.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles and medical device tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and reimbursement coverage expansion. Quarterly review of FDA pre-submission feedback letters and EMA notified body capacity indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Middle East and Africa Heart Valve Repair and Replacement Market
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Remote Endarterectomy Devices Market