
 Cardiovascular Catheter Market | 2026-2036
Cardiovascular Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Catheter Market Intelligence
The direct-to-hospital distribution channel for cardiovascular catheters is fragmenting as specialized interventional clinics gain purchasing autonomy. Medtronic leverages its extensive sales network to maintain relationships with large hospital systems. Boston Scientific Corporation differentiates through its focus on innovative electrophysiology and structural heart products. Meanwhile, Terumo Corporation competes on manufacturing excellence and supply chain reliability in high-volume catheter segments, particularly in the Asia-Pacific region.
A cardiovascular catheter is a thin, flexible tube, often constructed from materials like polyurethane and specified by its French size, designed for intravascular access. Its primary purpose is to deliver contrast agents for angiography, deploy stents, or perform ablations within the heart and peripheral vasculature. Interventional catheters for coronary angioplasty constitute a mature and high-volume segment of the market. In contrast, electrophysiology catheters for complex arrhythmia treatments command higher price points due to their advanced steerable tip technologies.
Market access hinges on stringent pre-market approvals from bodies like the US FDA and conformity assessments under the EU's Medical Device Regulation (MDR). In China, the NMPA's evolving requirements for clinical trial data are shaping market entry strategies for foreign manufacturers. Future investment decisions will depend on navigating these disparate regulatory pathways while managing the lifecycle of drug-eluting and polymer coating technologies.
Market Dynamics
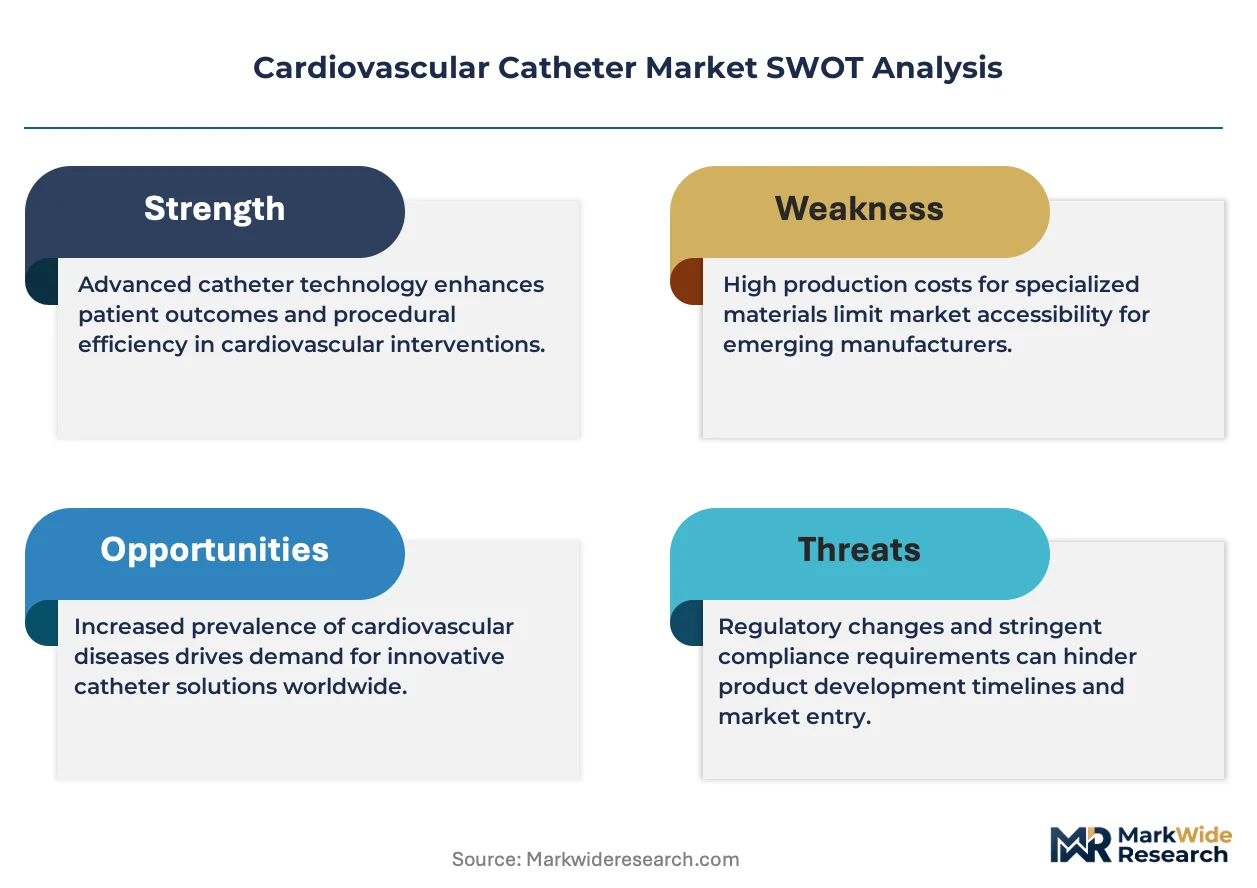
The cardiovascular catheter market is defined by a fundamental tension between the need for high-margin innovation in complex devices and the intense price competition in mature, high-volume segments. Stricter regulatory frameworks, particularly the EU's Medical Device Regulation, are raising development costs and timelines, forcing manufacturers to justify clinical and economic value more rigorously.
Growth Catalysts
- Advanced Catheter Technologies:The integration of miniaturized sensors, fiber optics, and advanced mapping capabilities into catheters enhances procedural accuracy for complex ablations and structural heart repairs, driving adoption in specialized centers.
- Demographic Shifts:Aging populations in developed countries like Germany and Japan, with high incidences of cardiovascular disease, sustain a high volume of diagnostic and interventional procedures requiring catheterization.
- Outpatient Procedure Expansion:Favorable reimbursement policies in markets like the United States are accelerating the shift of coronary and peripheral interventions from inpatient hospitals to more cost-effective ambulatory surgery centers and specialized clinics.
Market Restraints
- Stringent Regulatory Hurdles:The extensive clinical trial data requirements and prolonged review processes under China's NMPA create significant barriers and delays for foreign manufacturers seeking market entry.
- Raw Material Price Volatility:Fluctuations in the cost of medical-grade polymers like polyurethane and Pebax, critical for catheter construction, directly impact manufacturing margins and can lead to supply chain instability.
- Technical Miniaturization Limits:Developing smaller, more flexible catheters for pediatric or complex neurovascular applications poses significant engineering challenges in maintaining torque control, pushability, and lumen integrity.
Strategic Opportunities
- Emerging Market Penetration:Healthcare infrastructure investments in Southeast Asian nations present a significant opportunity for market expansion, particularly for diagnostic and basic interventional catheters, as access to care improves.
- Robotic-Assisted Interventions:The convergence of advanced robotics with steerable catheter technology creates an opportunity for developing systems that enable remote-controlled procedures, potentially expanding access to expert care.
- Neurovascular Applications:Adapting cardiovascular catheter technologies for thrombectomy and aneurysm coiling in the neurovascular space represents an adjacent market with high unmet needs and significant growth potential.
Industry Challenges
- Specialized Talent Scarcity:A shortage of highly trained interventional cardiologists, electrophysiologists, and cath lab technicians capable of utilizing the most advanced catheter systems limits the adoption rate of new, complex technologies.
- Post-Market Surveillance Burden:Complying with the rigorous post-market clinical follow-up and reporting requirements mandated by the EU's MDR places a substantial and ongoing operational and financial burden on device manufacturers.
- Intellectual Property Complexity:Navigating the dense landscape of patents related to steerable tip mechanisms, drug-eluting coatings, and sensor technologies often leads to costly licensing negotiations and litigation risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Catheter Market |
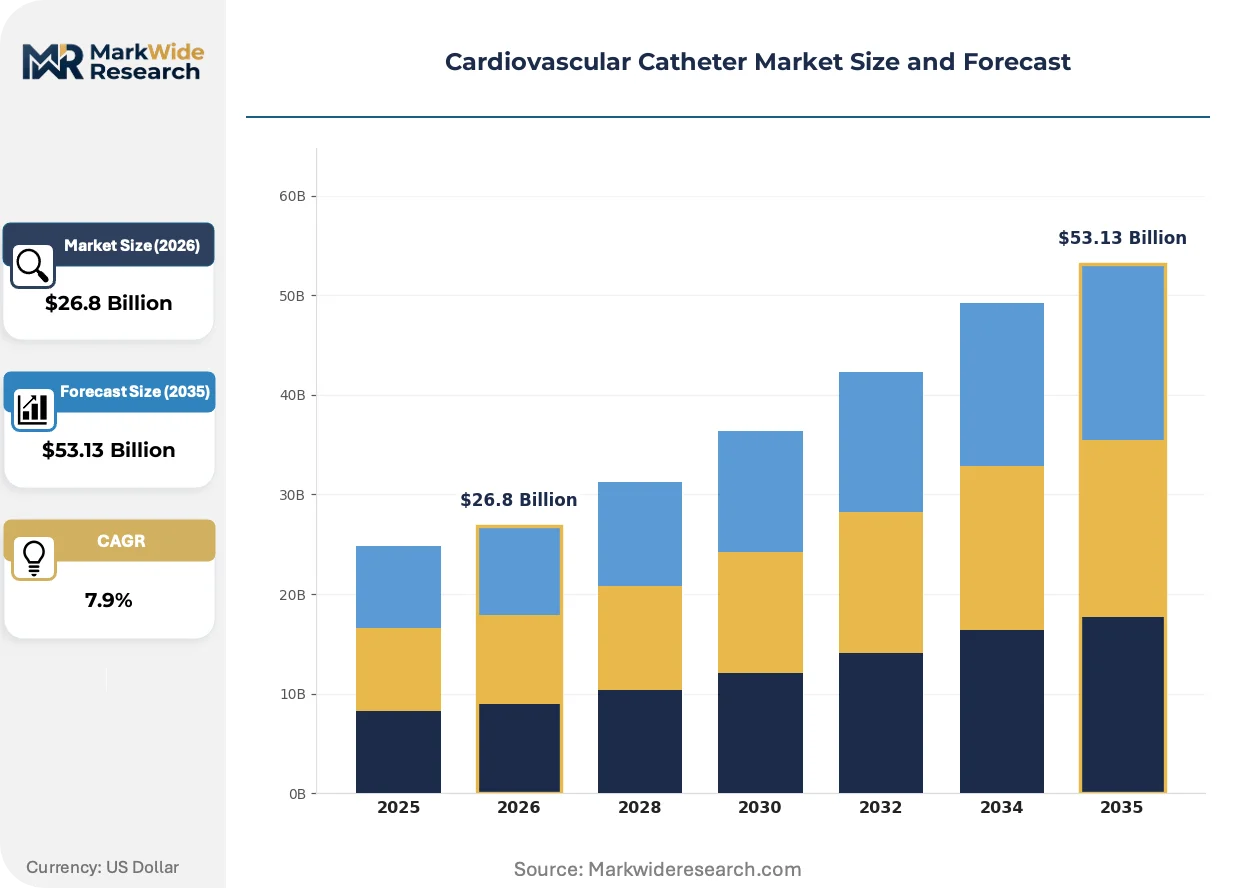
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $53.13 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Catheters, Interventional Catheters, Balloon Catheters, Electrophysiology Catheters, Ablation Catheters Technology: Hydrophilic Coating, Polymer Coating, Steerable Tip, Drug-Eluting, Radiofrequency Application: Coronary Angioplasty, Peripheral Vascular Interventions, Cardiac Electrophysiology, Structural Heart Procedures End User: Cardiac Surgery Centers, Diagnostic Labs, Interventional Clinics, Research Institutions |
| Companies Covered | Abbott Laboratories, Medtronic, Boston Scientific Corporation, Johnson & Johnson, Terumo Corporation, Teleflex Incorporated, B. Braun Melsungen, Cook Medical, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Catheter Market Strategic Shifts & Innovations
The evolution of cardiovascular catheters is marked by a transition from purely mechanical instruments to data-rich platforms. This shift is driven by the integration of sensing, imaging, and software, transforming procedural workflows and therapeutic decision-making. These intelligent devices are enabling more personalized and predictive approaches to treating cardiovascular disease.
Advanced fiber optic sensing and AI-powered image processing are being integrated directly into catheter tips. Electrophysiology labs and academic medical centers are the primary adopters of these sophisticated systems, which provide unparalleled real-time anatomical and functional data. This fusion of hardware and software is virtualizing the cardiac environment, enabling physicians to model tissue response and plan interventions with greater precision before delivering therapy.
The US FDA's full implementation of the Unique Device Identification (UDI) system is a significant regulatory trend. This rule mandates a unique identifier on each catheter, improving traceability throughout the healthcare supply chain from production to patient use. The primary impact is on hospital inventory management systems and electronic health records, which must be upgraded to scan, record, and track UDI data, thereby enhancing post-market surveillance and recall efficiency.
Purchasing authority for many catheter types is decentralizing from hospital-wide committees to individual clinical departments. Specialized service lines, such as structural heart or peripheral vascular programs, now exert greater influence over device selection, often bypassing traditional group purchasing organization contracts for technologically superior products. This shift is most prominent in the United States, where physician preference for specific catheter performance characteristics directly shapes procurement within their labs.
Cardiovascular Catheter Market Segmentation
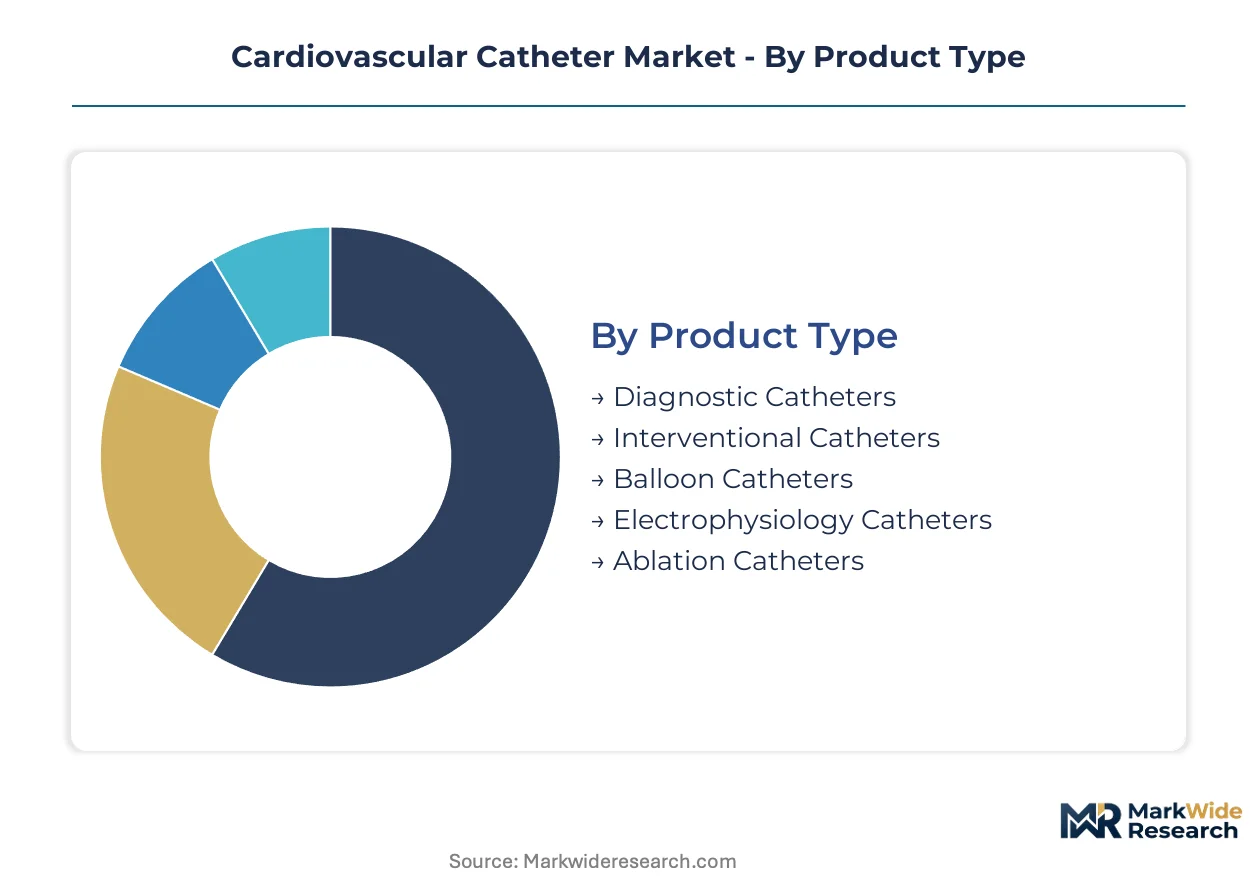
The cardiovascular catheter market fragments across diverse product specifications, technological advancements, application areas, and end-user requirements. Understanding these distinctions is critical for manufacturers to align product development with evolving clinical needs and regulatory demands. Each segment addresses specific patient populations and procedural complexities, influencing market dynamics.
Product Type:
The after-sales service intensity for cardiovascular catheters varies significantly across product types, reflecting diverse technical complexities and maintenance requirements.
- Interventional Catheters:These devices are primarily used for deploying stents, performing angioplasty, and other therapeutic procedures within vessels. Demand concentrates in interventional clinics across the United States, driven by the shift towards minimally invasive interventions.
- Electrophysiology Catheters:Designed for diagnosing and treating cardiac arrhythmias, these catheters feature advanced steerable tips and mapping capabilities. Academic medical centers in Germany drive demand due to their focus on complex arrhythmia management.
- Diagnostic Catheters:These thin tubes deliver contrast agents for imaging and measure pressures within the heart chambers.
- Balloon Catheters:Used primarily for vessel dilation during angioplasty procedures, these catheters inflate at the site of a blockage.
- Ablation Catheters:These devices deliver energy to destroy abnormal heart tissue responsible for arrhythmias.
By volume, Interventional Catheters leads. By growth pace, Electrophysiology Catheters is ahead.
Technology:
Functional differentiation drives technology adoption in cardiovascular catheters, with specific innovations addressing distinct clinical needs.
- Drug-Eluting:These catheters feature polymer coatings that release therapeutic agents to prevent restenosis after stent deployment or angioplasty. Demand concentrates in coronary interventions across Japan, aiming to improve long-term patient outcomes.
- Steerable Tip:Advanced steerable tip mechanisms provide precise navigation and control within complex anatomical structures during procedures. Electrophysiology labs in Germany adopt these technologies for enhanced procedural accuracy in arrhythmia treatments.
- Hydrophilic Coating:These coatings reduce friction, enabling smoother and safer insertion and navigation through blood vessels.
- Polymer Coating:Various polymer coatings enhance biocompatibility, durability, and deliverability of the catheter body.
- Radiofrequency:This technology delivers controlled heat energy for tissue ablation, primarily in electrophysiology procedures.
The pace of innovation in this segment is dictated by clinical evidence and regulatory acceptance.
Application:
The volume of cardiovascular catheter procedures is directly tied to the prevalence of specific cardiac conditions and treatment protocols.
- Coronary Angioplasty:This application involves using catheters to open blocked coronary arteries, often followed by stent placement. Interventional clinics in the United States perform a high volume of these procedures due to the prevalence of coronary artery disease.
- Cardiac Electrophysiology:Catheters are central to diagnosing and treating heart rhythm disorders through mapping and ablation. Specialized cardiac centers across Europe are key adopters for managing complex arrhythmias.
- Peripheral Vascular Interventions:This category includes procedures to treat blockages and narrowing in arteries outside the heart and brain.
- Structural Heart Procedures:Catheters facilitate minimally invasive repairs or replacements of heart valves and closure of congenital defects.
Clinical outcomes and procedural efficiency drive adoption across these application areas.
End User:
The customer type for cardiovascular catheters influences procurement patterns, with specialized facilities prioritizing specific device capabilities.
- Interventional Clinics:These outpatient facilities specialize in minimally invasive procedures, including coronary and peripheral interventions. They represent a significant purchasing segment in the US and Germany due to cost-effectiveness and patient preference for outpatient care.
- Cardiac Surgery Centers:Typically found within large hospital systems, these centers handle complex cardiac procedures requiring advanced infrastructure and specialized staff. Demand is strong in Japan, driven by an aging population and advanced healthcare.
- Diagnostic Labs:These facilities utilize catheters for various diagnostic imaging and physiological measurement purposes.
- Research Institutions:Academic and private research institutions employ catheters for preclinical studies, clinical trials, and device development.
The evolving healthcare delivery landscape is shifting procurement power towards specialized interventional settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced healthcare infrastructure underpins the varied regional dynamics within the cardiovascular catheter market. Specialized medical centers and robust regulatory frameworks facilitate device adoption and innovation across key geographies. These regional variations are critical for manufacturers navigating market entry and expansion strategies.
United States
The United States drives demand for interventional catheters, fueled by favorable reimbursement policies accelerating outpatient procedures and high coronary artery disease prevalence. The US FDA's stringent pre-market approvals shape product development and market access strategies. Boston's MedTech cluster continues to innovate in advanced catheter technologies, attracting significant investment.
Germany
Germany's aging population and focus on complex arrhythmia management sustain robust demand for electrophysiology catheters. The EU's Medical Device Regulation (MDR) imposes rigorous conformity assessments, influencing device approval pathways. Munich and Berlin's academic medical centers adopt advanced steerable tip technologies for enhanced procedural accuracy.
Japan
Japan's aging population and emphasis on improving long-term patient outcomes in coronary interventions drive significant demand for drug-eluting catheters. PMDA regulatory pathways influence market entry strategies for manufacturers. Tokyo's medical device industry focuses on manufacturing excellence and supply chain reliability for high-volume catheter segments.
China
China presents substantial opportunity for market expansion, particularly for diagnostic and basic interventional catheters, as access to care improves. The NMPA's evolving requirements for clinical trial data create significant barriers for foreign manufacturers. Shanghai and Shenzhen's emerging medical device hubs attract investment in local production capabilities.
France
France's specialized cardiac centers adopt catheters for diagnosing and treating heart rhythm disorders through mapping and ablation. The ANSM ensures strict device safety and efficacy, aligning with European regulatory standards. Paris and Lyon are centers for medical technology innovation, fostering development in advanced electrophysiology catheter systems.
Cardiovascular Catheter Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical materials and sub-assemblies. The cardiovascular catheter market exhibits a tiered structure, with established multinational corporations alongside specialized innovators. Archetypes include diversified medical device giants, focused interventional cardiology players, and niche electrophysiology specialists. Dominant competitive moves involve strategic partnerships for technology co-development and targeted portfolio diversification into high-growth application areas.
Within the diversified medical device giants archetype, Medtronic exemplifies the leverage of an extensive sales network to maintain robust relationships with large hospital systems, securing broad market penetration across various product lines. Boston Scientific Corporation occupies a strong position by consistently differentiating through its focus on innovative electrophysiology and structural heart products, targeting high-value, complex intervention segments. Terumo Corporation, a Japan-based company, anchors the high-volume catheter segments through manufacturing excellence and supply chain reliability, particularly in the Asia-Pacific region, competing effectively on operational efficiency and cost-effectiveness.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Terumo Corporation |
| Teleflex Incorporated |
| B. Braun Melsungen |
| Cook Medical |
| Cardinal Health |
| Others |
Cost & Logistics Intelligence
Underutilization across some specialized catheter manufacturing facilities in Asia-Pacific influences global pricing, driving supplier behavior towards competitive bids and impacting overall market posture. This dynamic balances innovation costs with volume-driven efficiency.
Pricing Analysis
Volume-discount contracting often dictates pricing for high-volume cardiovascular catheters, particularly for diagnostic and basic interventional types. Price differentiation stems from device complexity and the level of post-market surveillance required under regulations like the EU MDR. Pricing softness reflects intense competition in mature segments, especially for commodity products. Specialized interventional clinics demonstrate higher price sensitivity for routine devices compared to academic medical centers acquiring advanced electrophysiology systems.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices to manage liquidity for manufacturers sourcing critical components. Geographic supply concentration for medical-grade polymers like polyurethane and Pebax primarily occurs in East Asia and Europe. Raw material price volatility represents a structural supply chain risk for device manufacturers. Distribution runs through a fragmented network of direct sales forces and specialized medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiovascular catheter market faces a critical constraint: a persistent shortage of highly trained interventional cardiologists and electrophysiologists. This talent gap limits the adoption of advanced catheter systems and shapes strategic investment priorities.
For Market Incumbents: Insulate core product lines through continuous R&D investment in next-generation drug-eluting technologies and advanced steerable tip mechanisms. Consolidate market share by acquiring niche innovators in electrophysiology to counter emerging competition from specialized device companies. The EU MDR's rigorous post-market surveillance requirements serve as a lever to differentiate quality and compliance, countering price pressure in mature segments.
For New Entrants and Emerging Players: Underpenetration in Southeast Asian nations presents a significant white-space opportunity for diagnostic and basic interventional catheters. Focus on developing cost-effective, high-volume products tailored to local clinical needs and regulatory pathways, particularly for coronary angioplasty. A direct-to-clinic sales model, emphasizing product training and technical support, offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the electrophysiology catheter segment, driven by the need for advanced manufacturing and complex R&D. Long-term viability favors firms with robust intellectual property portfolios in steerable tip and sensor technologies. Target mid-sized, innovation-driven companies specializing in neurovascular applications for strategic acquisition. The signal to watch is the acceleration of robotic-assisted intervention adoption rates in major markets.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Securing US FDA approval opens access to the largest market for novel catheter technologies. |
| Hospital System Partnership | Collaborating with major hospital networks ensures broader adoption of advanced interventional devices. |
| Software Companion Development | Integrating AI-powered image processing enhances catheter functionality and procedural accuracy. |
| Reimbursement Strategy | Developing strong economic value propositions supports favorable coverage for high-cost devices. |
| Manufacturing Scale-Up | Expanding production capacity for polymer-based catheters addresses growing global demand. |
Research Approach
Desk research of academic publications, regulatory filings, and industry reports preceded interviews with interventional cardiologists, cath lab managers, hospital procurement committees, and device engineers. Secondary validation utilized hospital procurement databases, GPO contracts, CMS Medicare data, and US FDA filings. Bottom-up and top-down triangulation reconciled market size estimates and growth projections.
Assumptions regarding stable reimbursement policies and healthcare expenditure were held constant over the projection horizon. The analytical framework modeled segmentation by product type, technology, application, end-user, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected adoption, with aging population demographics and regulatory approval timelines as critical forecast inputs.
Practitioners should monitor raw material price volatility and evolving regulatory hurdles from bodies like China's NMPA for early signals. Forecasts reflect underlying assumptions about market dynamics and technological progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Lower Limb Arterial Stents Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Implantable Infusion Pumps Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Resuscitation Bags Market