
 Blood Fluid Warming System Market | 2026-2036
Blood Fluid Warming System Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Fluid Warming System Market Outlook
Trauma care is expanding as the dominant end-use vertical for blood fluid warming systems, displacing traditional general surgical applications. Stryker Corporation leverages its emergency care portfolio to anchor positions in military and civilian trauma settings. Belmont Medical Technologies specializes in high-flow warming platforms for massive transfusion protocols. Baxter International competes through integrated fluid management ecosystems that bundle warming with filtration and delivery.
A blood fluid warming system is an active thermal regulation device that heats blood, plasma, or intravenous solutions to normothermic range (typically 37°C) before patient infusion, using conductive, convective, or radiant energy transfer to prevent hypothermia-induced coagulopathy and metabolic acidosis. In-line warmers dominate current procurement due to their compatibility with standard infusion sets and minimal footprint in crowded operating theaters. Convection heating technology leads on warming speed and temperature uniformity, though microwave platforms are gaining traction in pre-hospital emergency settings where rapid activation matters.
The FDA enforces 21 CFR Part 820 quality system regulations and ISO 10993 biocompatibility standards for device materials contacting blood products, while the EU Medical Device Regulation mandates clinical evidence for Class IIa thermal devices entering European markets. These frameworks elevate compliance costs for new entrants but protect incumbent manufacturers with established regulatory dossiers. Stakeholders must monitor evolving premarket notification pathways and emerging consensus standards on warming accuracy validation as procurement criteria tighten across hospital systems.
Market Dynamics
Trauma care units in tertiary hospitals are driving demand concentration toward high-flow warming platforms capable of supporting massive transfusion protocols, compressing procurement cycles and elevating performance validation requirements.
Growth Catalysts
- FDA 21 CFR Part 820 enforcement:The updated quality system regulations for thermal regulation equipment are accelerating hospital replacement cycles as older devices fail premarket validation standards.
- Military medical installations:Forward surgical teams and combat support hospitals maintain standing procurement volumes for portable warming systems with battery-independent activation.
- Microwave warming platforms:Pre-hospital emergency settings are absorbing these devices for rapid field activation where convection heating infrastructure is unavailable.
Market Restraints
- Biocompatibility testing costs:ISO 10993 compliance for blood-contacting materials elevates R&D expenditure for new market entrants without established regulatory dossiers.
- EU MDR clinical evidence requirements:Class IIa thermal devices entering European markets face extended approval timelines and mandatory post-market surveillance obligations.
- Reusable component standardization:Dominance of in-line warmers compatible with standard infusion sets limits differentiation opportunities for proprietary connector systems.
Strategic Opportunities
- Pre-hospital emergency services:Ambulance fleets and air medical transport operators represent underpenetrated demand for battery-operated warming platforms with sub-60-second activation.
- Integrated fluid management ecosystems:Bundling warming with filtration and delivery functions creates value capture opportunities in academic medical centers consolidating vendor relationships.
- CE marking harmonization:Streamlined conformity assessment pathways under EU MDR reduce time-to-market for manufacturers with existing ISO 13485 quality management systems.
Industry Challenges
- Warming accuracy validation:Emerging consensus standards on temperature uniformity testing require capital investment in metrology infrastructure and specialized calibration protocols.
- Supply chain reconfiguration:Concentration of semiconductor components for temperature control modules creates vulnerability to foundry capacity constraints and extended lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Fluid Warming System Market |
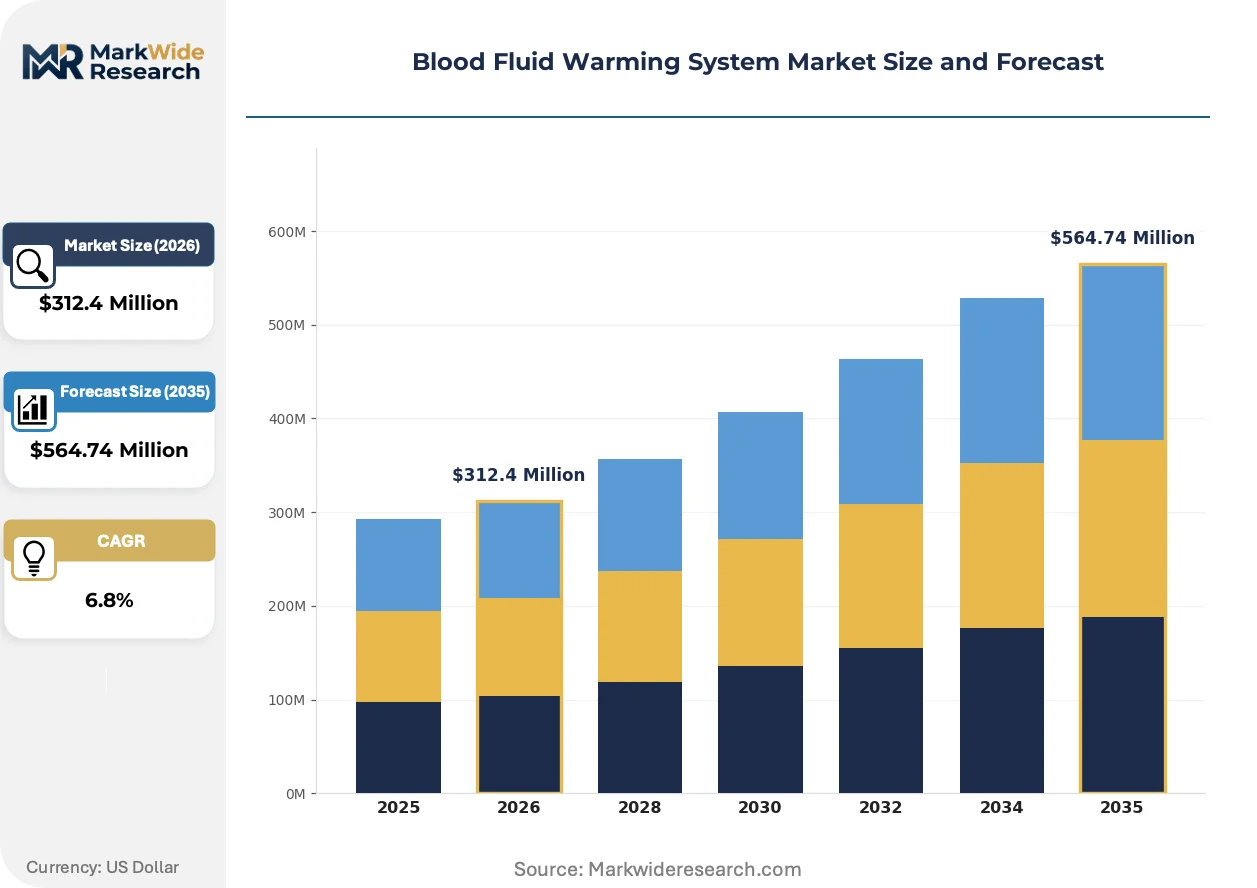
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Line Warmers, Dial-A-Flow Warmers, Mobile Warmers, Stationary Warmers End User: Hospitals, Blood Banks, Emergency Medical Services, Military Medical Units Technology: Conduction Heating, Convection Heating, Microwave Heating, Infrared Heating Application: Trauma Care, Surgical Procedures, Neonatal Care, Resuscitation |
| Companies Covered | Becton, Dickinson and Company, Belmont Medical Technologies, 3M Company, Stryker Corporation, GE Healthcare, Baxter International, ICU Medical, Barkey GmbH & Co. KG, Biegler GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Fluid Warming System Market Strategic Shifts
Technology convergence between thermal regulation and connected health infrastructure is redefining competitive positioning, while regulatory stringency and procurement consolidation reshape commercial pathways.
Convection heating technology dominates current installations through superior warming speed and temperature uniformity across high-flow scenarios. Trauma centers and operating theaters are standardizing on these platforms for massive transfusion protocols. Microwave-based alternatives are absorbing niche applications in pre-hospital settings where infrastructure weight and power requirements constrain equipment selection.
The EU Medical Device Regulation mandates clinical evidence for Class IIa thermal devices entering European markets, elevating documentation burdens for new entrants. Manufacturers with established regulatory dossiers gain protected positions as compliance costs rise. Hospital systems are tightening procurement criteria to include warming accuracy validation as a mandatory evaluation metric.
Academic medical centers are consolidating vendor relationships around integrated fluid management ecosystems that bundle warming with filtration and delivery. Single-source contracting is displacing discrete component purchasing in tertiary hospitals with centralized supply chain governance. This concentration is most visible in United States trauma centers where military-civilian procurement alignment creates volume leverage.
Blood Fluid Warming System Market Segmentation
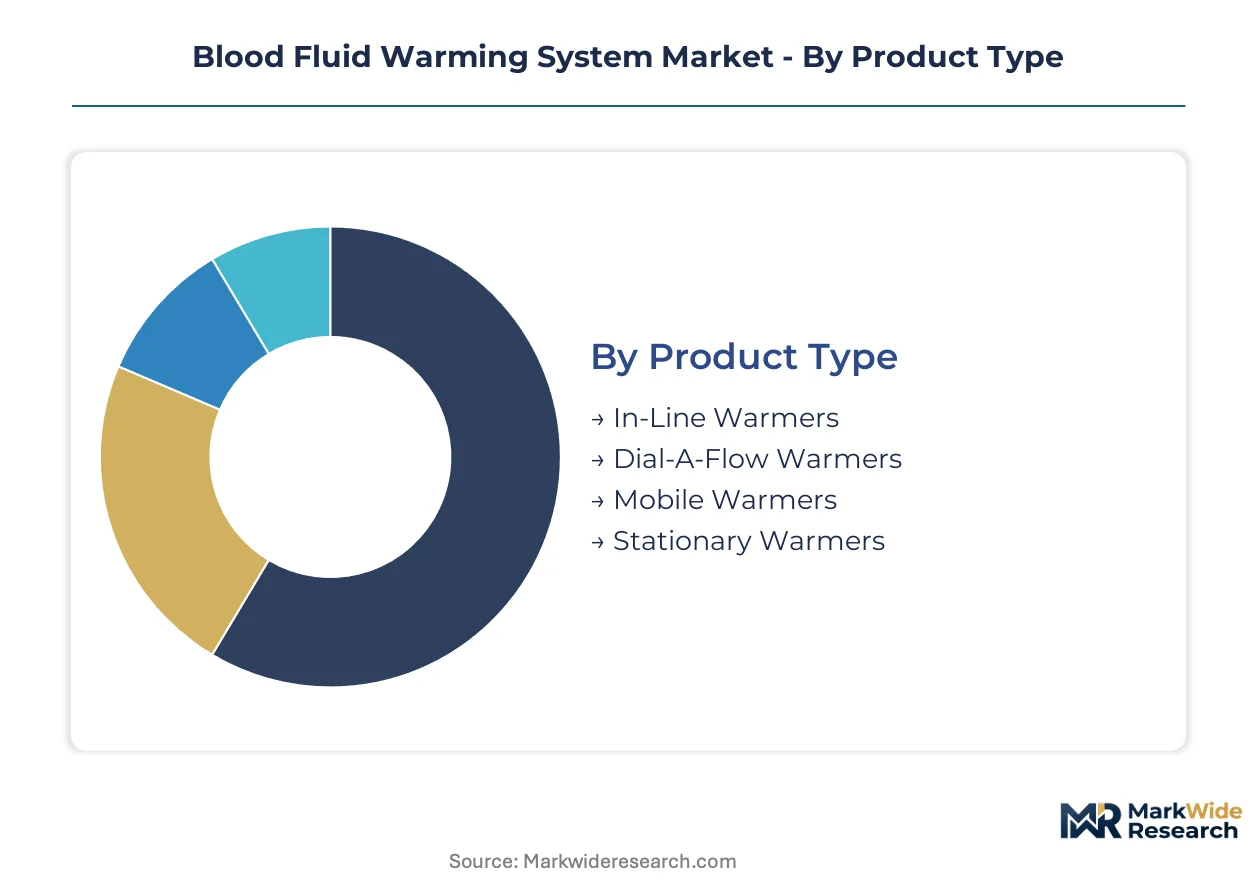
Blood fluid warming systems fragment across four distinct taxonomies that shape procurement patterns and R&D allocation. Product architecture determines capital deployment intensity, while end-user concentration and heating modality selection drive margin structures and regulatory pathway complexity.
Product Type:
Capital intensity varies sharply across warming platform architectures, with stationary installations demanding the heaviest upfront infrastructure investment.
- In-Line Warmers:Compact conductive heating modules integrate directly into standard IV infusion sets without dedicated power infrastructure. Trauma centers in the United States favor these devices for their minimal footprint in crowded operating theaters and compatibility with existing fluid delivery workflows.
- Mobile Warmers:Battery-capable convection units deploy across pre-hospital and forward military settings where grid independence determines operational viability. Emergency medical services in Texas and California are absorbing these platforms for air medical transport and ambulance fleet standardization.
- Dial-A-Flow Warmers:Precision-controlled warming stations with variable flow rate calibration serve neonatal and pediatric applications requiring tight temperature tolerance.
- Stationary Warmers:High-throughput cabinet systems anchor blood bank processing facilities with batch warming capacity for plasma and cryoprecipitate units.
In-Line warmers absorb the bulk of installed capacity; mobile warmers are expanding most quickly.
End User:
Procurement authority and reimbursement pathways diverge across institutional buyer categories, with military medical units operating under distinct acquisition frameworks.
- Hospitals:Tertiary trauma centers and academic medical centers drive specification standards through centralized value analysis committees. These institutions bundle warming systems into integrated fluid management contracts that span filtration, warming, and delivery functions.
- Emergency Medical Services:Ambulance operators and air medical fleets prioritize sub-60-second activation times and battery-independent operation. Pre-hospital adoption is climbing fastest in states with consolidated regional EMS authorities capable of fleet-wide standardization.
- Blood Banks:Plasma processing facilities deploy high-volume stationary warming for component thawing and preparation workflows.
- Military Medical Units:Forward surgical teams and combat support hospitals maintain standing procurement volumes through Defense Logistics Agency channels with ruggedization requirements exceeding civilian specifications.
Hospitals command the largest installed base; emergency medical services is gaining share fastest.
Technology:
Heating modality selection trades warming velocity against temperature uniformity, with convection platforms dominating high-flow trauma applications.
- Convection Heating:Forced-air thermal transfer delivers superior warming speed and temperature uniformity across massive transfusion protocols. Trauma centers in the United States have standardized on these platforms for operating theater deployment.
- Microwave Heating:Rapid electromagnetic warming enables sub-30-second activation without fluid contact heating elements. Pre-hospital emergency settings are adopting these devices where infrastructure weight and power constraints limit equipment selection.
- Conduction Heating:Direct surface contact warming maintains simplicity and reliability in low-flow neonatal and pediatric applications.
- Infrared Heating:Radiant energy transfer offers non-contact warming for specialized blood component processing with minimal shear stress.
Convection heating carries the dominant installed base; microwave platforms are climbing the fastest.
Application:
Clinical use case determines performance validation requirements and regulatory scrutiny intensity, with trauma protocols demanding the most rigorous warming accuracy standards.
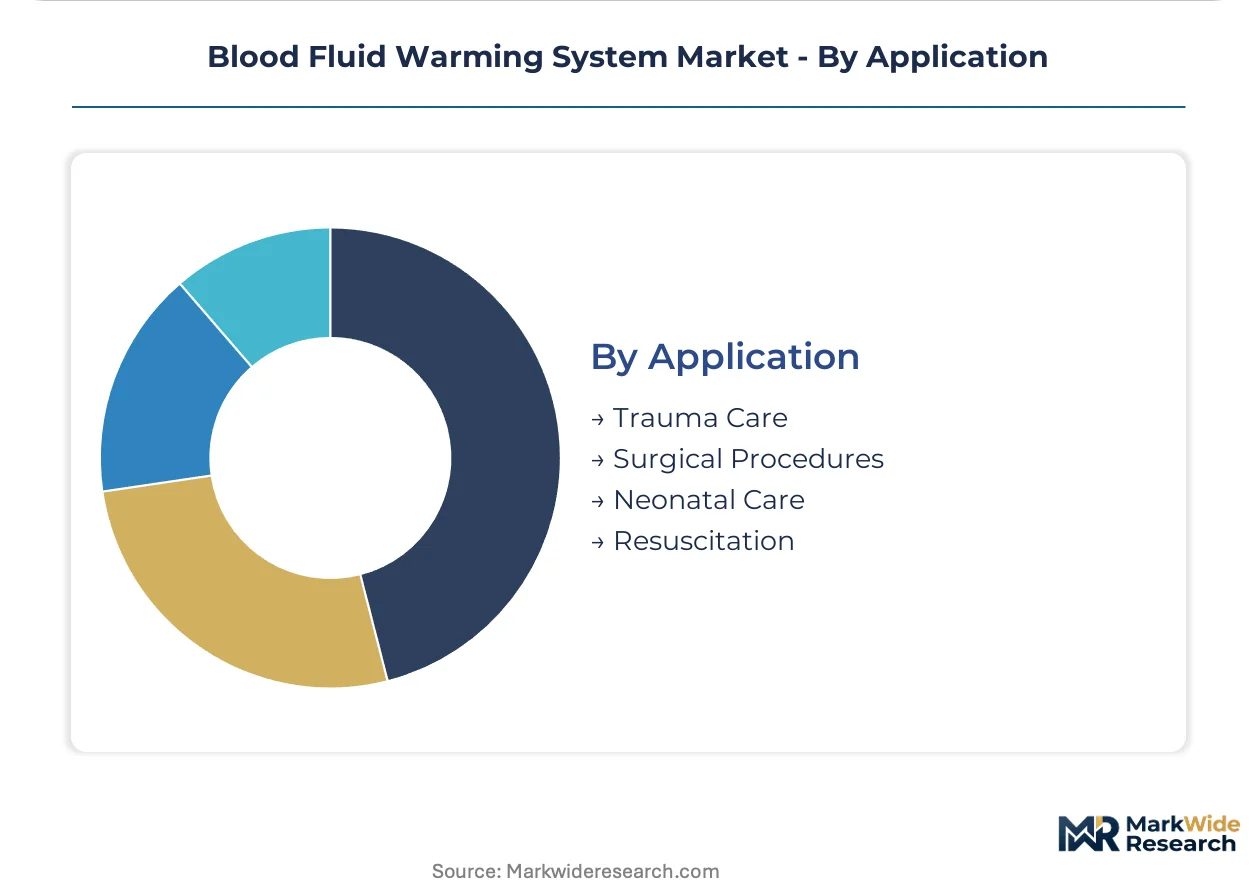
- Trauma Care:Massive transfusion protocols require high-flow warming capable of delivering normothermic blood products at rates exceeding 500 mL per minute. Tertiary hospitals in the United States are consolidating procurement around platforms validated for coagulopathy prevention.
- Surgical Procedures:Elective and emergency operating theater use spans general surgery, orthopedics, and cardiac procedures with moderate flow requirements and established temperature monitoring protocols.
- Neonatal Care:Low-volume precision warming serves incubator-adjacent applications with strict temperature tolerance and minimal fluid volume requirements.
- Resuscitation:Emergency department and field resuscitation protocols prioritize rapid deployment and intuitive operation under high-stress conditions.
Trauma care holds the dominant application share; neonatal care is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States, while demand tilts toward American trauma centers and military installations. European markets absorb high-end warming platforms through centralized hospital procurement, with Asia-Pacific emerging as the fastest-expanding consumption zone.
United States
Tertiary trauma centers in Texas and California drive procurement volumes for high-flow warming platforms capable of massive transfusion protocols. The FDA enforces 21 CFR Part 820 quality system regulations that accelerate hospital replacement cycles for older thermal devices. Military medical installations in San Antonio and Bethesda maintain standing demand through Defense Logistics Agency channels with ruggedization requirements exceeding civilian specifications.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia standardize on integrated fluid management ecosystems bundling warming with filtration functions. The EU Medical Device Regulation mandates clinical evidence for Class IIa thermal devices entering European markets, elevating documentation burdens for new entrants. Barkey GmbH & Co. KG and Biegler GmbH anchor industrial clusters around Stuttgart and Munich with established regulatory dossiers protecting incumbent positions.
United Kingdom
NHS trusts in London and the Midlands consolidate vendor relationships around single-source contracts for emergency care equipment. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines while maintaining distinct post-market surveillance protocols. Trauma networks in Greater Manchester and the West Midlands are absorbing microwave warming platforms for pre-hospital emergency services where rapid field activation matters.
Japan
Metropolitan hospital systems in Tokyo and Osaka prioritize precision-controlled warming stations for neonatal and pediatric applications with tight temperature tolerance. The Pharmaceuticals and Medical Devices Agency enforces JIS standards alongside ISO 13485 quality management requirements for device manufacturers. Chubu region medical device clusters around Nagoya are expanding export capacity for convection heating modules targeting Southeast Asian markets.
Australia
Air medical transport operators in New South Wales and Queensland represent underpenetrated demand for battery-operated warming platforms with sub-60-second activation. The Therapeutic Goods Administration maintains alignment with EU MDR while streamlining conformity assessment pathways for manufacturers with existing ISO certifications. Royal Flying Doctor Service deployments across the Northern Territory are validating microwave platforms in remote field conditions where infrastructure weight constrains equipment selection.
Blood Fluid Warming System Market Competitive Environment
Top-tier vendors anchor integrated fluid management ecosystems, while mid-tier specialists concentrate on thermal regulation components and regional service networks. The vendor base stratifies across three tiers: multinational health technology conglomerates with emergency care portfolios, dedicated warming platform manufacturers with regulatory specialization, and regional fabricators serving price-sensitive procurement channels. Strategic moves center on portfolio diversification into connected health infrastructure and geographic expansion through distributor partnerships in underpenetrated markets.
Within the dedicated warming platform tier, Belmont Medical Technologies and Barkey GmbH & Co. KG exemplify manufacturers with deep regulatory specialization and established thermal technology expertise. Stryker Corporation occupies a position among health technology conglomerates leveraging emergency care portfolio breadth to anchor military and civilian trauma settings. These three entities represent distinct competitive archetypes: pure-play warming specialists, diversified emergency care platforms, and integrated health technology ecosystems.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Belmont Medical Technologies |
| 3M Company |
| Stryker Corporation |
| GE Healthcare |
| Baxter International |
| ICU Medical |
| Barkey GmbH & Co. KG |
| Biegler GmbH |
| Others |
Value Chain & Pricing Dynamics
Backward integration into semiconductor temperature control module production anchors both supply security and pricing power for incumbent manufacturers, as foundry capacity constraints elevate component costs and compress margins for assemblers without captive sourcing. This structural positioning allows integrated vendors to command premium positioning while forcing price competition onto procurement-dependent competitors.
Pricing Analysis
Short lead-time premiums dominate pricing architecture, with hospitals paying elevated rates for rapid fulfillment of FDA-validated warming platforms against standard delivery schedules. Pricing stratifies across premium, standard, and economy tiers based on warming accuracy certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because EMS procurement consolidation enables volume leverage against vendors. Blood banks exhibit the highest price sensitivity due to capital budget constraints, while military medical units demonstrate the lowest sensitivity given mission-critical requirements and standing procurement channels.
Supply Chain Analysis
Workforce availability in precision electronics assembly constrains expansion in Germany and the United States, where skilled technician pools for medical device manufacturing face competition from broader industrial automation sectors. Component sourcing draws from Taiwan for semiconductors, Germany for precision heating elements, and the United States for biocompatible polymers. Single-source vulnerability concentrates in temperature sensor foundries, where limited qualified suppliers create chokepoint exposure. Distribution runs through hospital GPO contracts in the United States and centralized NHS procurement frameworks in the United Kingdom, with regional medical device distributors serving fragmented EMS markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence requirements and FDA validation tightening are forcing consolidation, eliminating undercapitalized entrants lacking established regulatory dossiers and quality management infrastructure.
For Market Incumbents: Deepen captive production of temperature control modules to insulate margins from semiconductor foundry pricing volatility. Anchor hospital system relationships through integrated fluid management contracts spanning warming, filtration, and delivery functions, displacing discrete component vendors. Prioritize ISO 13485 certification maintenance and warming accuracy validation infrastructure investment to defend against emerging microwave platform competitors. For New Entrants and Emerging Players: Enter via pre-hospital emergency services in Australian air medical transport and Texas ambulance fleet consolidation, where battery-operated microwave platforms face minimal incumbent saturation. Target microwave warming technology for rapid field activation scenarios where convection infrastructure is unavailable. Pursue distributor partnerships with regional EMS authorities capable of fleet-wide standardization rather than fragmented hospital procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by health technology conglomerates seeking emergency care portfolio expansion, with pure-play warming specialists commanding premium positioning due to regulatory dossier scarcity. Five-to-ten year viability favors manufacturers with established FDA 510(k) clearances and EU MDR technical documentation. Monitor FDA premarket notification pathway revisions and warming accuracy consensus standard finalization as inflection indicators for valuation compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Streamlined conformity assessment under EU MDR reduces time-to-market for ISO 13485-certified manufacturers. |
| Hospital System Partnership | Single-source integrated fluid management contracts displace discrete component purchasing in tertiary trauma centers. |
| FDA Submission | Premarket notification clearance under 21 CFR Part 820 protects market access against quality system enforcement actions. |
| Software Companion Development | Connected health infrastructure integration differentiates warming platforms in academic medical center procurement. |
| Reimbursement Strategy | Alignment with massive transfusion protocol reimbursement codes accelerates hospital adoption of high-flow warming systems. |
Study Parameters
FDA 510(k) premarket notification databases, EU MDR technical documentation registries, and hospital GPO contract filings formed the secondary backbone, cross-referenced with primary interviews with trauma surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Bottom-up installed base estimates triangulated against top-down market value projections derived from manufacturer revenue disclosures and procurement volume analysis.
Historical trendline analysis of thermal regulation equipment adoption across trauma care units established baseline penetration rates, with projection modeling incorporating product type segmentation across in-line, mobile, dial-a-flow, and stationary warming architectures; end-user concentration across hospitals, emergency medical services, blood banks, and military medical units; and technology modality selection between convection, microwave, conduction, and infrared heating. CAGRs were derived from weighted average growth trajectories across these segmentation dimensions, with specific inputs including Defense Logistics Agency procurement volumes and tertiary hospital capital expenditure cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA quality system enforcement acceleration or EU MDR clinical evidence requirement expansion. Forecasts reflect documented assumptions regarding military medical installation procurement continuity and trauma center capital budget availability. Material deviation in FDA premarket validation timeline compression or semiconductor foundry capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
Infusion Catheters Market
Cardiovascular Devices
Abdominal Aortic Aneurysm (AAA) Repair Devices Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Global External Ventricular Drain Market