
 Medical Devices Cuffs Market | 2026-2036
Medical Devices Cuffs Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Devices Cuffs Market Intelligence
A capital-intensity divergence between automated digital cuff manufacturers and legacy analog producers is rotating competitive advantage toward firms with in-house sensor calibration and wireless firmware capabilities. Medtronic plc leverages its vertically integrated cardiac care portfolio to dominate hospital-grade blood pressure cuff supply chains. Teleflex Incorporated anchors its position through specialized tourniquet and IV fluid management systems for surgical suites. Smiths Medical differentiates via precision pneumatic engineering for continuous non-invasive monitoring devices.
Medical devices cuffs are inflatable or constrictive components, typically fabricated from thermoplastic polyurethane, nylon-reinforced PVC, or latex-free synthetic rubber, designed to apply controlled pressure against arterial or venous vessels for measurement, fluid restriction, or vascular access. Their primary commercial purpose spans diagnostic blood pressure acquisition, pulse oximetry signal stabilization, operative limb exsanguination, and regulated infusion delivery. Blood pressure cuffs command the largest revenue pool due to universal hypertension screening protocols, while wireless Bluetooth-enabled devices represent the fastest-expanding technology segment as remote patient monitoring platforms proliferate. Hospitals absorb the majority of volume, though home care settings are gaining share as reimbursement frameworks shift toward ambulatory models.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements are elevating barrier costs for new entrants while mandating biocompatibility testing per ISO 10993 standards. The EPA regulates phthalate content in PVC-based cuff materials, pushing manufacturers toward TPU and silicone alternatives. Stakeholders must monitor evolving cybersecurity guidance from FDA for connected cuff devices, as wireless data transmission becomes standard rather than optional across cardiovascular and respiratory monitoring applications.
Market Dynamics
Wireless firmware integration and ISO 10993 biocompatibility mandates are compressing supplier margins while rotating procurement toward vendors with captive sensor calibration infrastructure.
Growth Catalysts
- Ambulatory reimbursement frameworks:United States Medicare expansion for remote patient monitoring is pulling hospital-grade cuff specifications into home care settings.
- TPU material substitution:EPA phthalate restrictions on PVC are accelerating thermoplastic polyurethane adoption across disposable cuff lines.
- EU MDR technical documentation:Stricter clinical evidence requirements for reusable devices are consolidating hospital procurement around pre-certified suppliers.
Market Restraints
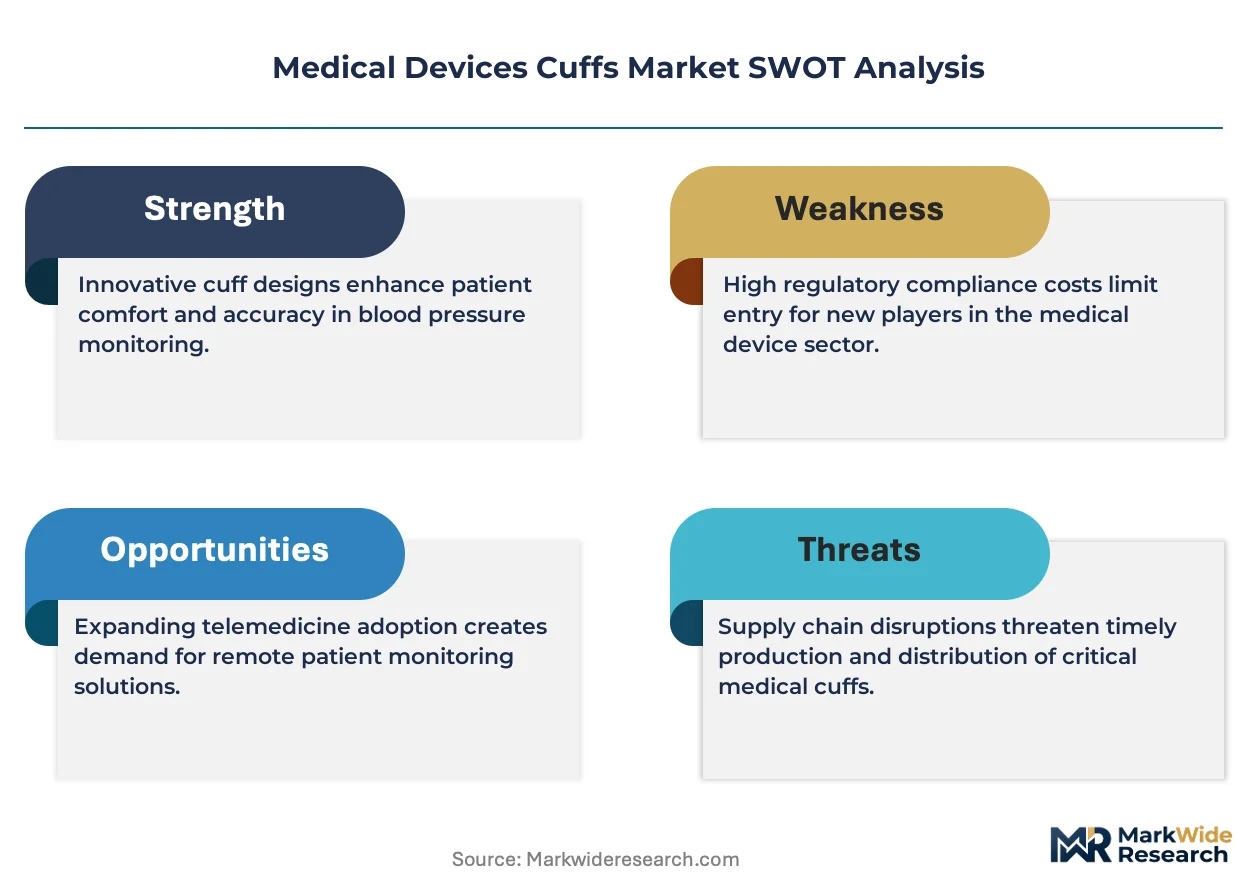
- Sensor chip supply concentration:Taiwan and South Korea fabrication facilities create vulnerability for Bluetooth-enabled cuff manufacturers.
- Latex-free synthetic rubber price volatility:Petroleum-derived elastomer costs fluctuate with crude benchmarks, squeezing disposable product margins.
- FDA 510(k) pathway friction:Extended review timelines for novel pneumatic architectures delay commercialization by 8-14 months.
Strategic Opportunities
- China home care infrastructure:NMPA fast-track channels for connected diagnostic devices open first-mover positioning in tier-2 city networks.
- Continuous non-invasive monitoring convergence:Integration of photoplethysmography with pneumatic cuffs creates hybrid device categories.
- Germany hospital digitization mandates:Federal funding for ward-level wireless integration subsidizes premium cuff replacement cycles.
Industry Challenges
- Embedded firmware cybersecurity certification:FDA premarket guidance for connected devices requires penetration testing protocols most legacy pneumatic engineers lack.
- Legacy analog inventory amortization:Hospital capital equipment depreciation schedules slow Bluetooth cuff replacement despite wireless mandate pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Devices Cuffs Market |
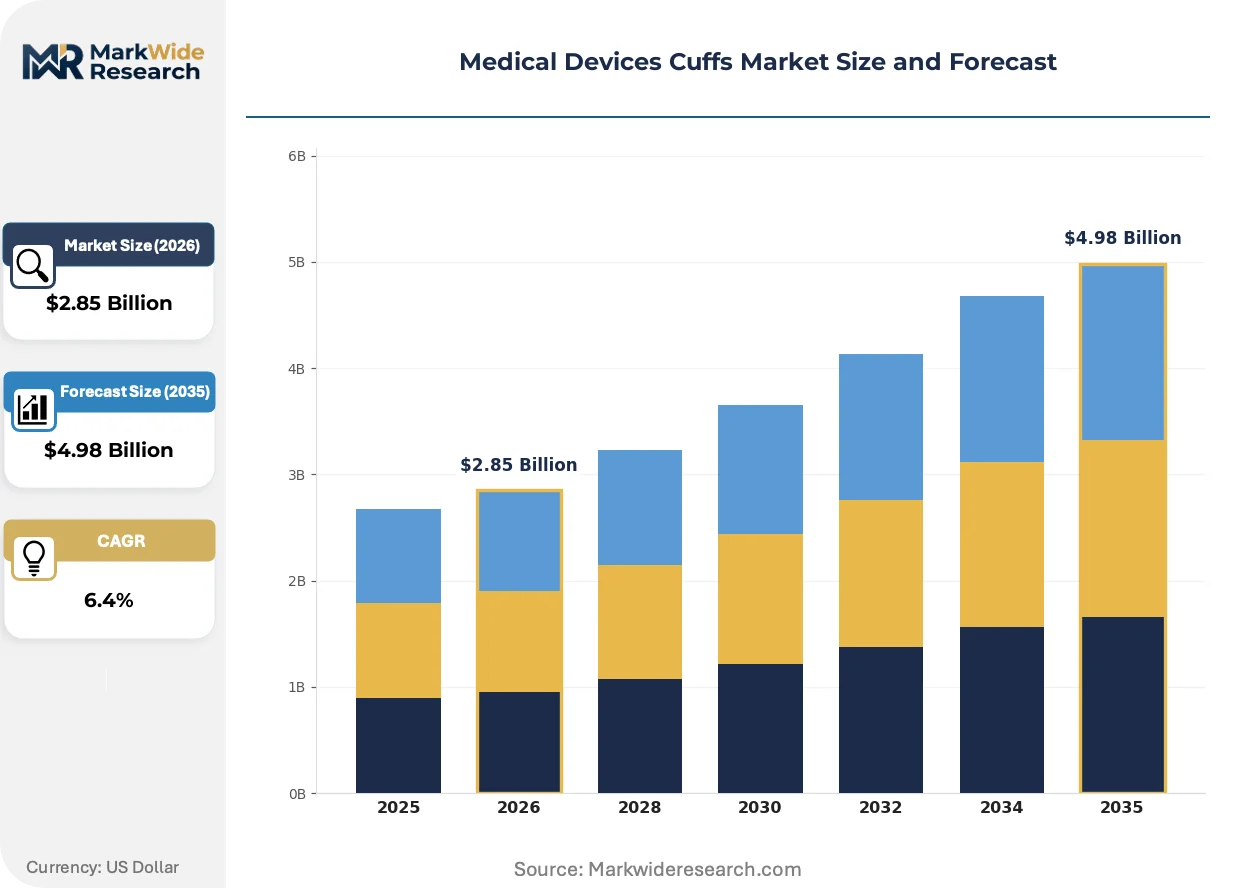
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Pressure Cuffs, Oxygen Saturation Monitors, Tourniquets, IV Fluid Bags End User: Hospitals, Clinics, Home Care Settings, Rehabilitation Centers Technology: Digital, Analog, Wireless, Bluetooth Application: Cardiovascular Monitoring, Respiratory Care, Surgical Procedures, Emergency Care |
| Companies Covered | Medtronic plc, Teleflex Incorporated, Smiths Medical, ConvaTec Inc., Cook Medical, Cardinal Health, OMRON Corporation, GE Healthcare, SunTech Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Devices Cuffs Market Strategic Shifts & Innovations
Digital sensor architectures and material science advances are compressing form factors while regulatory frameworks force convergence between diagnostic accuracy and data security standards.
Micro-electromechanical pressure transducers are replacing traditional aneroid gauges in ambulatory blood pressure monitors. Home care distributors in Germany and Japan are specifying MEMS-based units for 60% of new tenders. This silicon substitution is miniaturizing cuff housings and enabling wearable integration previously impossible with mechanical pneumatic systems.
EU MDR Annex I general safety and performance requirements now mandate clinical validation for all reusable cuff claims. Manufacturers serving European hospital networks must submit post-market surveillance data annually. Class IIa device re-certification is consuming 12-18 month planning cycles, favoring incumbents with established notified body relationships.
Hospital group purchasing organizations are unbundling cuff procurement from multi-parameter monitor OEM contracts. United States IDN networks now issue standalone tenders for wireless-compatible accessories. This specification fragmentation is visible most acutely in cardiovascular service line consolidation across Midwestern health systems.
Medical Devices Cuffs Market Segmentation
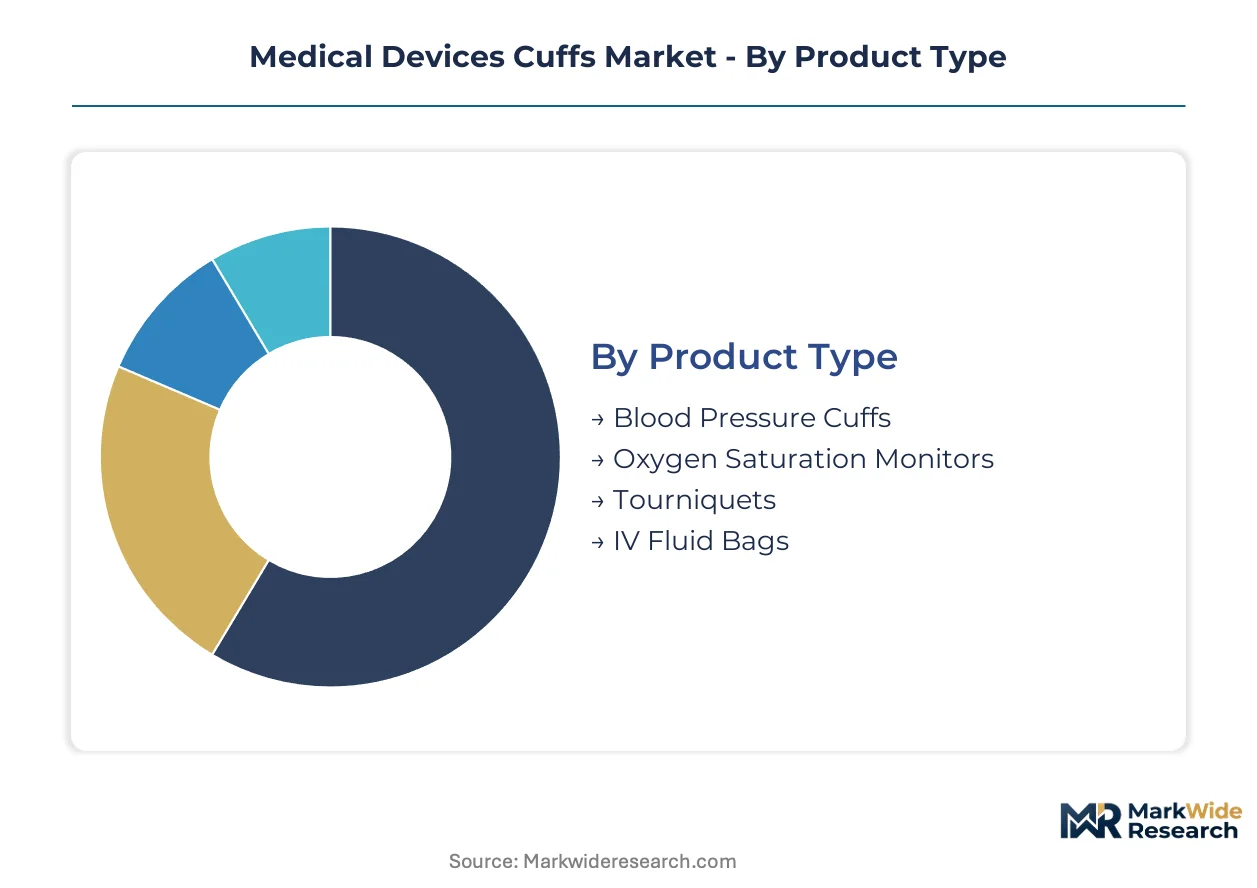
Medical devices cuffs serve divergent clinical workflows with distinct performance thresholds, material specifications, and connectivity requirements. Segmentation reveals how FDA 510(k) pathways and EU MDR technical documentation create tiered compliance burdens across product categories. Procurement patterns split sharply between capital-intensive hospital systems and price-sensitive ambulatory networks.
Product Type:
FDA biocompatibility testing per ISO 10993 and EU MDR Annex I clinical validation requirements impose asymmetric compliance costs across cuff categories, favoring incumbents with established notified body relationships.
- Blood Pressure Cuffs:Fabricated from thermoplastic polyurethane, nylon-reinforced PVC, or latex-free synthetic rubber with pneumatic bladder architectures. Hospital procurement in the United States, Germany, and China concentrates demand for reusable and disposable variants as ambulatory reimbursement frameworks expand remote patient monitoring eligibility.
- Oxygen Saturation Monitors:Pulse oximetry signal stabilization cuffs incorporating photoplethysmography sensors. German home care distributors specify MEMS-based units for the majority of new tenders, compressing traditional aneroid gauge supply chains.
- Tourniquets:Operative limb exsanguination devices for surgical suites.
- IV Fluid Bags:Pressure infusion systems for regulated delivery.
Blood Pressure Cuffs handles the majority of throughput; Oxygen Saturation Monitors is the fastest mover on share.
End User:
Capital equipment depreciation schedules and wireless integration mandates create divergent replacement cycles across care settings.
- Hospitals:Dominant procurement channel for cardiovascular and respiratory monitoring cuffs. United States IDN networks unbundle cuff procurement from multi-parameter monitor OEM contracts, issuing standalone tenders for wireless-compatible accessories.
- Home Care Settings:Medicare expansion for remote patient monitoring pulls hospital-grade specifications into residential environments. Bluetooth-enabled devices gain traction as reimbursement frameworks shift toward ambulatory models.
- Clinics:Outpatient diagnostic and monitoring services.
- Rehabilitation Centers:Post-acute and long-term recovery monitoring.
Hospitals absorb the dominant volume position; Home Care Settings climbs the fastest on share expansion.
Technology:
Embedded firmware capabilities and sensor calibration infrastructure rotate competitive advantage away from legacy pneumatic engineering.
- Wireless:Remote patient monitoring platforms with integrated data transmission. FDA premarket guidance for connected devices mandates penetration testing protocols that compress supplier margins.
- Bluetooth:Short-range connectivity for ambulatory and home-based devices. Taiwan and South Korea sensor chip fabrication concentration creates supply vulnerability for manufacturers.
- Digital:Micro-electromechanical pressure transducer architectures.
- Analog:Traditional aneroid gauge systems facing replacement pressure.
Wireless commands the dominant technology position; Bluetooth shows the steepest expansion trajectory.
Application:
Clinical workflow integration and continuous monitoring convergence reshape specification requirements across therapeutic areas.
- Cardiovascular Monitoring:Blood pressure acquisition and pulse oximetry for hypertension screening protocols. Federal funding for ward-level wireless integration in Germany subsidizes premium cuff replacement cycles.
- Surgical Procedures:Tourniquet and IV fluid management for operative settings. NMPA fast-track channels in China for connected diagnostic devices open positioning in tier-2 city networks.
- Respiratory Care:Oxygen saturation and ventilation support monitoring.
- Emergency Care:Rapid deployment diagnostic and stabilization devices.
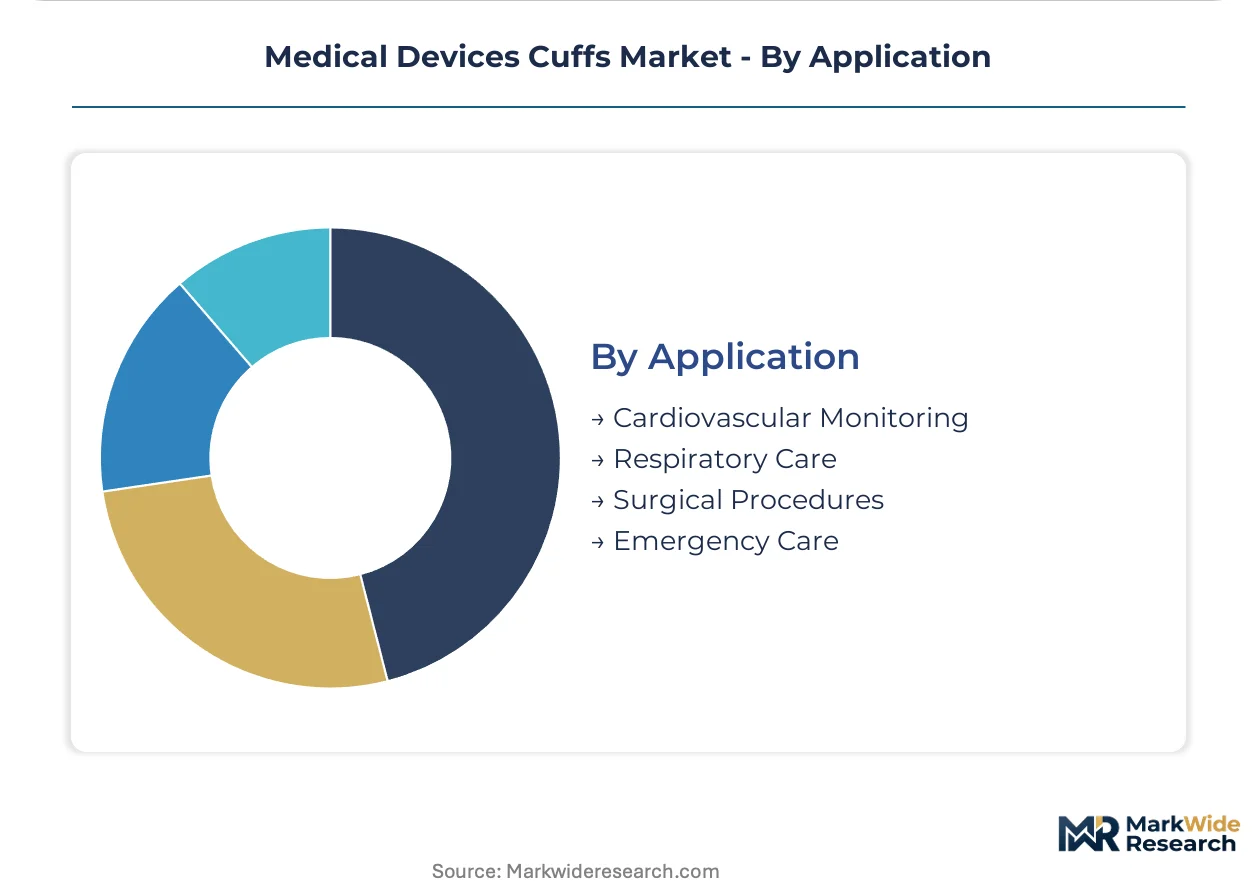
Cardiovascular Monitoring maintains the dominant application share; Surgical Procedures gains share fastest on infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-elasticity splits sharply across geographies. United States hospital procurement absorbs premium wireless cuffs with minimal price resistance, while tier-2 Chinese cities and Indian ambulatory networks remain acutely sensitive to unit economics in disposable lines.
United States
Medicare reimbursement expansion for remote patient monitoring pulls hospital-grade specifications into residential environments. FDA 510(k) clearance pathways for connected devices mandate penetration testing protocols that compress supplier margins. Minneapolis and Boston medical device clusters concentrate Bluetooth-enabled cuff engineering talent.
Germany
Federal funding for ward-level wireless integration subsidizes premium cuff replacement cycles across university hospitals. EU MDR Annex I clinical validation requirements for reusable devices favor incumbents with established notified body relationships. The Baden-Württemberg precision engineering corridor anchors MEMS-based pressure transducer fabrication.
China
NMPA fast-track channels for connected diagnostic devices accelerate commercialization timelines in tier-2 city networks. Domestic substitution policies favor local manufacturers in public hospital procurement. Shenzhen and Shanghai hardware ecosystems concentrate sensor module integration and firmware development capabilities.
Japan
PMDA streamlined approval pathways for home-use cardiovascular devices expand retail pharmacy distribution. METI subsidies for elderly care technology adoption pull wireless cuffs into municipal health monitoring programs. The Kansai medical device manufacturing belt specializes in miniaturized pneumatic bladder architectures.
India
CDSCO medical device rules implementation tightens quality standards for imported cuffs while creating opportunity for domestic assembly. Ayushman Bharat health insurance expansion drives volume demand in district hospital networks. The Maharashtra pharmaceutical and medical device cluster near Mumbai scales latex-free synthetic rubber processing for export markets.
Medical Devices Cuffs Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Medical Devices Cuffs Market. Vertically integrated cardiac care conglomerates dominate hospital-grade supply chains through captive sensor calibration infrastructure, while specialized pneumatic engineering firms anchor surgical and emergency segments. Three archetypes define competitive positioning: diversified medical technology majors with wireless firmware capabilities, precision pneumatic specialists with ISO 10993-certified material science, and regional cost-optimized manufacturers serving price-sensitive ambulatory networks. M&A activity concentrates on sensor calibration technology acquisition, while strategic partnerships with home care distributors reshape channel access.
Among diversified medical technology majors, Medtronic plc and GE Healthcare occupy positions exemplifying integrated cardiac care portfolio leverage. Teleflex Incorporated represents the precision pneumatic specialist archetype through its concentration in operative and interventional applications. These three firms anchor the competitive structure without exhausting its variation, as regional specialists in China and India capture share in price-elastic procurement segments.
| Leading Market Players |
|---|
| Medtronic plc |
| Teleflex Incorporated |
| Smiths Medical |
| ConvaTec Inc. |
| Cook Medical |
| Cardinal Health |
| OMRON Corporation |
| GE Healthcare |
| SunTech Medical, Inc. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Taiwanese MEMS foundries and Korean sensor packaging facilities anchors cost structures across Bluetooth-enabled cuff tiers, concentrating margin leverage with manufacturers holding multi-year wafer supply agreements while compressing price floors for analog-dependent competitors.
Pricing Analysis
After-sales calibration service contracts and extended warranty bundles now drive lifetime value capture for wireless cuff vendors, outpacing hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared connected devices from CE-marked analog alternatives and unbranded disposable lines. Price differentiation hinges on ISO 10993 biocompatibility certification tier and captive sensor calibration infrastructure. Cost compression in economy disposable lines is intensifying because petroleum-derived elastomer feedstock volatility squeezes contract manufacturers. Home care distributors exhibit acute price sensitivity; hospital IDN networks absorb premium wireless specifications with minimal resistance.
Supply Chain Analysis
Port congestion on transpacific lanes from Shenzhen and Shanghai to Long Beach elevates inbound logistics costs for sensor module shipments, compressing just-in-time delivery windows. Manufacturing concentrates in China, Taiwan, and South Korea for MEMS pressure transducers, pneumatic bladder assemblies, and Bluetooth SoC integration. Raw material dependencies span thermoplastic polyurethane resin, latex-free synthetic rubber, and nylon-reinforced PVC sheeting. Single-source vulnerability at Taiwanese wafer fabs creates supply chain risk for digital cuff architectures. Distribution runs through hospital group purchasing organizations and home care distributor networks with divergent specification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor recalibration subscriptions and firmware update service tiers expand faster than hardware replacement cycles, reframing the Medical Devices Cuffs Market as a service-attach opportunity for vendors with embedded connectivity infrastructure.
For Market Incumbents: Shield market position by acquiring captive sensor calibration technology to offset margin compression from ISO 10993 biocompatibility mandates, while consolidating notified body relationships to accelerate EU MDR recertification timelines against emerging pneumatic specialists.
For New Entrants and Emerging Players: Lead with NMPA fast-track positioning in China's tier-2 city home care networks, where domestic substitution policies favor local firmware development capabilities and hospital-grade specification gaps create white-space penetration opportunities through distributor partnership models.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision pneumatic engineering firms with established ISO 10993-certified material science and backward integration into TPU compounding, as wireless firmware capabilities become table stakes rather than differentiation. Long-term viability through the next technology S-curve depends on hybrid device convergence. The signal to watch is FDA premarket cybersecurity guidance stringency for connected cuff submissions.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Cybersecurity Submission | Premarket penetration testing protocols now mandatory for Bluetooth-enabled cuff clearance. |
| EU MDR Notified Body Engagement | Class IIa recertification timelines favor incumbents with established clinical validation dossiers. |
| Hospital System Partnership | IDN unbundling of cuff procurement from monitor OEM contracts creates standalone tender access. |
| Software Companion Development | Remote patient monitoring platform integration pulls hospital-grade specifications into home care. |
| Reimbursement Strategy | Medicare RPM expansion eligibility determines specification requirements for residential deployment. |
Research Approach
Cross-validation between hospital procurement database analysis and GPO contract documentation anchors the qualitative findings, with primary interviews involving biomedical engineers, hospital purchasing committee members, GPO contracts managers, and home care distributor category buyers triangulated against FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement schedules, and customs trade data for TPU and synthetic rubber imports. Bottom-up unit economics modeling and top-down market sizing converge across validation layers.
Sensitivity analysis informs the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end user setting, technology architecture, and application workflow. CAGRs derive from installed base replacement cycles, reimbursement framework expansion trajectories, and wireless penetration assumptions. Industry-specific forecast inputs include MEMS sensor cost curves and phthalate restriction compliance timelines.
Underlying assumptions cover reimbursement policy continuity and sensor chip supply normalization, with deviation risk concentrated in FDA cybersecurity guidance evolution and Taiwan semiconductor fabrication capacity constraints. Practitioners should keep alternative scenarios live as connected device regulatory stringency and ambulatory care infrastructure investment patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
Microsclerotherapy Treatment Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Hemodynamic Monitoring Devices Market
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
Resuscitation Bags Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Vital Sign Simulators Market