
 Cardiovascular CT Systems Market | 2026-2036
Cardiovascular CT Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular CT Systems Market Outlook
Software-defined spectral imaging packages is recalibrating how cardiovascular CT value gets captured, shifting revenue from hardware transactions to recurring clinical workflow subscriptions. Siemens Healthineers leverages its dual-source CT architecture to anchor premium service contracts across European hospital networks. GE Healthcare sustains R&D intensity in photon-counting detector arrays, competing on image resolution benchmarks for coronary angiography protocols.
Cardiovascular CT systems are X-ray computed tomography platforms engineered for cardiac imaging, typically achieving temporal resolution below 75 milliseconds to freeze coronary motion and employing ECG-gated acquisition protocols. Their primary purpose is non-invasive visualization of coronary arteries, cardiac valves, and aortic structures to guide intervention planning and risk stratification. The 256-slice category leads in throughput for high-volume centers, while dual-energy CT captures expanding margin pools through material decomposition for plaque characterization. Spectral CT technology is displacing standard CT in research institutions seeking quantitative iodine mapping for myocardial perfusion assessment.
The FDA governs 510(k) clearance pathways for new CT platforms in the United States, while the EU MDR imposes stricter clinical evidence requirements for cardiovascular indications under CE marking. Japan's PMDA enforces JIS standards for radiation dose reporting, shaping product development priorities for Asian market entry. Stakeholders must monitor how regulatory divergence between FDA and EU MDR affects platform launch sequencing and service localization strategies.
Market Dynamics
Software-defined spectral imaging is restructuring how cardiovascular CT value gets captured, shifting revenue from hardware transactions to recurring clinical workflow subscriptions anchored by dual-source CT architectures.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:Accelerated clearance timelines for iterative reconstruction algorithms reduce time-to-market for next-generation platforms targeting coronary angiography protocols.
- Dual-Energy CT Material Decomposition:Research institutions adopt quantitative iodine mapping for myocardial perfusion assessment, expanding addressable use cases beyond anatomical visualization.
- China Cardiac Imaging Infrastructure Buildout:Hospital procurement budgets prioritize 256-slice systems for high-volume centers in tier-one cities.
Market Restraints
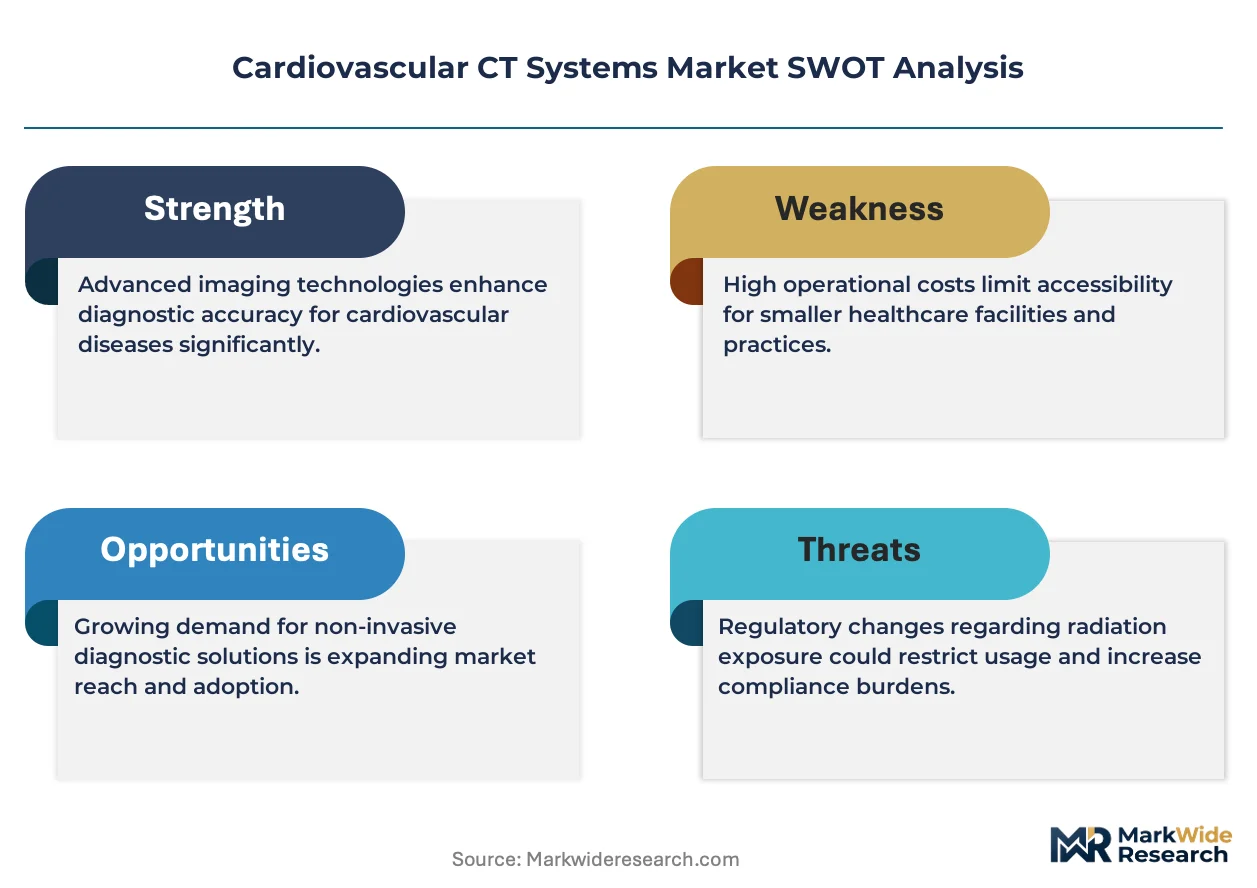
- Photon-Counting Detector Array Costs:Raw material and fabrication complexity for cadmium telluride sensors compress margins on premium system tiers.
- EU MDR Clinical Evidence Requirements:Stricter cardiovascular indication documentation under CE marking extends launch timelines and localization costs for European market entry.
- Radiation Dose Optimization Standards:JIS dose reporting mandates in Japan force hardware redesign cycles that delay product certification.
Strategic Opportunities
- India Diagnostic Center Network Expansion:Private imaging chains in Mumbai and Delhi seek refurbished 128-slice systems for cost-sensitive cardiac screening programs.
- AI-Assisted Plaque Characterization:Machine learning algorithms integrated with spectral CT data streams enable automated coronary risk scoring for asymptomatic patient populations.
- Outcome-Based Service Contracts:Siemens Healthineers pilots uptime-guaranteed subscriptions across German hospital networks, shifting revenue to recurring clinical workflow fees.
Industry Challenges
- ECG-Gated Acquisition Protocol Expertise Gap:Radiologic technologists require specialized training for sub-75-millisecond temporal resolution imaging, constraining deployment velocity.
- Legacy PACS Integration Complexity:New spectral CT platforms face interoperability friction with hospital information systems built on DICOM standards predating material decomposition workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular CT Systems Market |
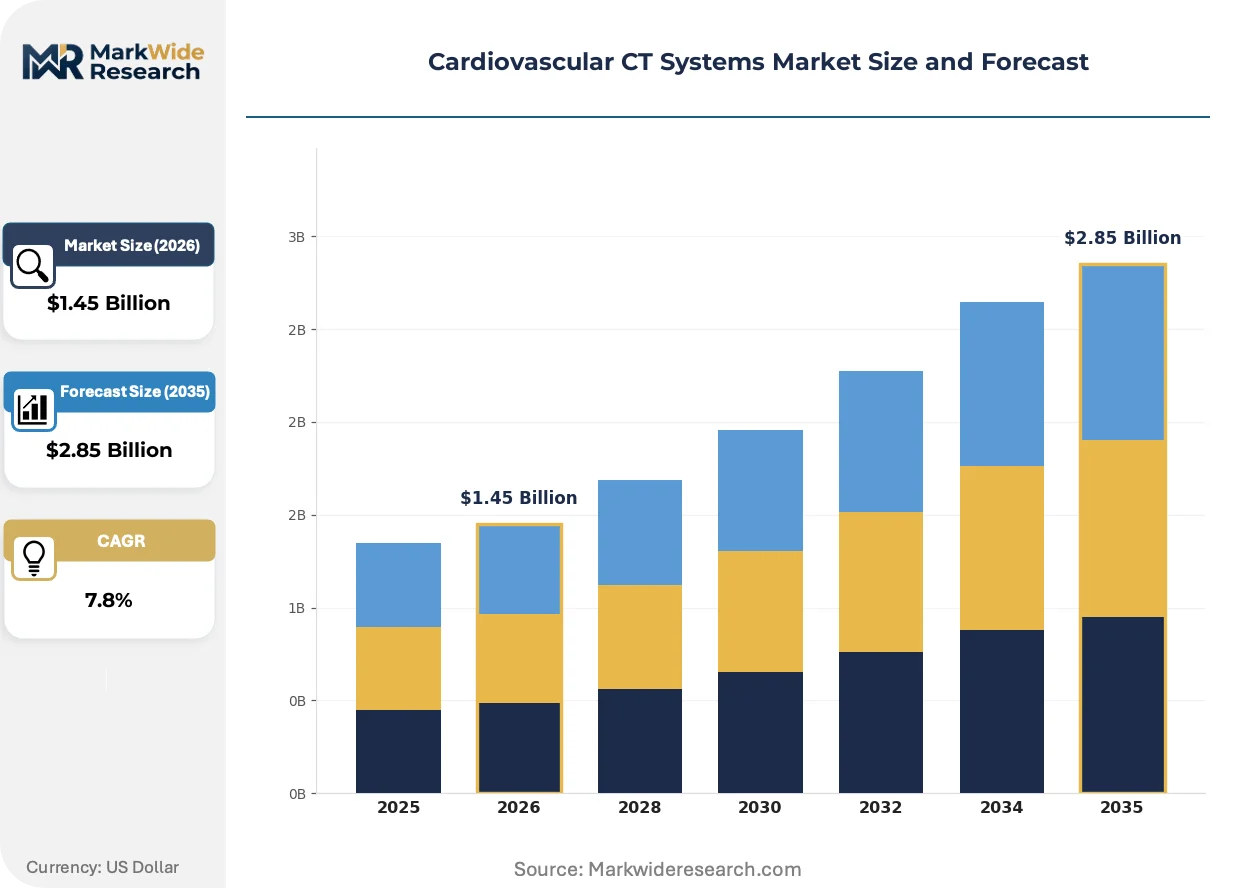
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.85 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 16-Slice, 64-Slice, 128-Slice, 256-Slice Technology: Standard CT, Dual-Energy CT, Spectral CT, Iterative Reconstruction End User: Hospitals, Imaging Centers, Research Institutions, Emergency Departments Application: Coronary Angiography, Heart Valve Assessment, Aortic Imaging, Congenital Defects |
| Companies Covered | Siemens Healthineers, GE Healthcare, Canon Medical Systems Corporation, Koninklijke Philips N.V., Fujifilm Holdings Corporation, United Imaging Healthcare, Neusoft Medical Systems Co. Ltd., NeuroLogica Corporation, Shenzhen Anke High-tech Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular CT Systems Market Strategic Shifts
Cardiovascular CT innovation vectors center on detector physics breakthroughs, regulatory evidence frameworks, and procurement model restructuring that together redefine how cardiac imaging value gets delivered.
Photon-counting detector technology is converging with spectral imaging pipelines to enable direct energy-resolved photon measurement without scintillator conversion layers. Academic medical centers in Germany and the United States pilot these arrays for ultra-low-dose coronary angiography. The technology is converging with iterative reconstruction algorithms to compress radiation exposure benchmarks while preserving spatial resolution for stent visualization.
The EU MDR imposes stricter clinical evidence requirements for cardiovascular indications under CE marking, mandating prospective outcome data for plaque characterization claims. Manufacturers must now fund multi-center registry studies to support material decomposition indications. High-volume European hospital networks delay procurement decisions until post-market surveillance data validates quantitative perfusion metrics.
Hospital procurement committees now unbundle hardware acquisition from service and software subscriptions, treating CT platforms as modular technology stacks. Original equipment manufacturers respond with tiered clinical workflow packages priced per study volume rather than capital expenditure. This behavioral shift is most visible in United States integrated delivery networks consolidating vendor relationships around enterprise imaging contracts.
Cardiovascular CT Systems Market Segmentation
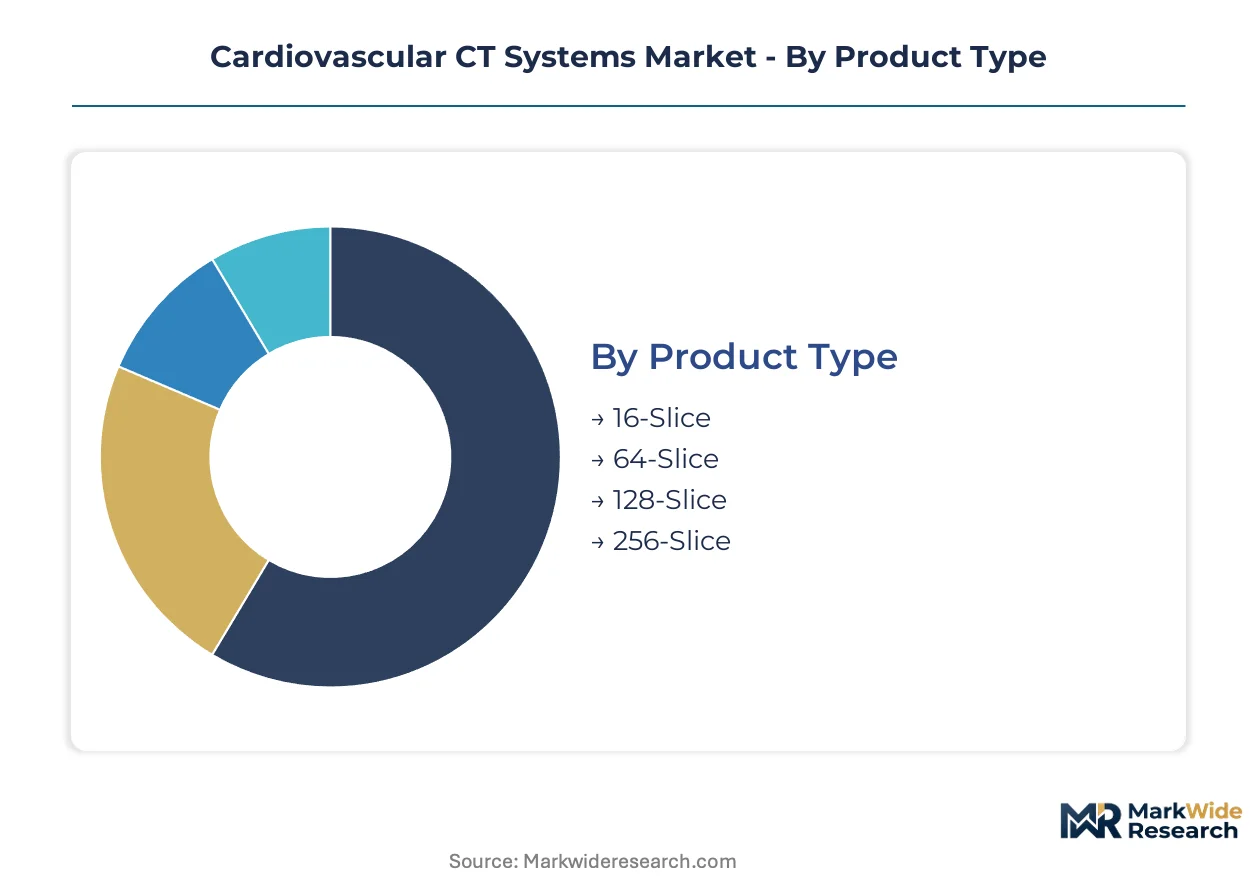
Segmentation in cardiovascular CT systems reveals how capital allocation, clinical workflow complexity, and reimbursement pathways concentrate purchasing power across distinct technology tiers and care settings. Understanding these fault lines helps vendors align R&D pipelines with where hospitals actually commit budget.
Product Type:
Capital intensity escalates sharply with slice count, as detector array width, gantry rotation mechanics, and computational backend requirements scale non-linearly.
- 256-Slice:These systems deploy wide-area detector arrays capable of whole-heart coverage in single cardiac cycles, eliminating stair-step artifacts from multi-segment reconstruction. High-volume centers in the United States and Germany absorb the premium pricing to maximize throughput for emergency coronary angiography protocols.
- 128-Slice:Mid-tier platforms balance temporal resolution against acquisition cost, serving tier-one Chinese hospitals expanding cardiac imaging infrastructure without photon-counting detector premiums.
- 64-Slice:Entry-level workhorses for cost-sensitive diagnostic chains in India.
- 16-Slice:Refurbished units dominate secondary market for basic screening programs.
Most installed capacity flows through 128-Slice configurations. Expansion is steepest in 256-Slice as high-volume centers prioritize throughput over capital efficiency.
Technology:
Margin architecture diverges between hardware-centric detector platforms and software-defined reconstruction pipelines that capture recurring revenue.
- Dual-Energy CT:Two X-ray spectra acquired simultaneously enable material decomposition for plaque characterization and myocardial perfusion quantification. Research institutions in Germany and the United States drive adoption for prospective outcome studies required under EU MDR.
- Iterative Reconstruction:Algorithmic noise reduction compresses radiation dose benchmarks while preserving spatial resolution for stent visualization. FDA 510(k) pathway streamlining accelerates clearance timelines for vendors competing on low-dose coronary angiography claims.
- Spectral CT:Energy-resolved photon measurement without scintillator conversion layers enables quantitative iodine mapping.
- Standard CT:Conventional single-energy acquisition remains prevalent in budget-constrained emergency departments.
Dual-Energy CT commands the highest service contract attach rates. Spectral CT is gaining share fastest as academic medical centers validate quantitative perfusion metrics.
End User:
Procurement authority and reimbursement access determine which settings can absorb premium system costs versus refurbished alternatives.
- Hospitals:Integrated delivery networks in the United States consolidate vendor relationships around enterprise imaging contracts, unbundling hardware from software subscriptions. These buyers prioritize 256-slice throughput for emergency coronary angiography and cardiac surgery planning.
- Imaging Centers:Private diagnostic chains in Mumbai and Delhi seek refurbished 128-slice systems for cost-sensitive cardiac screening programs, optimizing equipment utilization across high patient volumes.
- Research Institutions:Academic medical centers pilot photon-counting detector arrays for ultra-low-dose protocols.
- Emergency Departments:Time-critical settings demand rapid acquisition with minimal patient preparation.
Hospitals absorb the majority of new system shipments. Imaging centers are expanding most quickly as private capital flows into outpatient cardiac diagnostics.
Application:
Clinical indication complexity dictates temporal resolution requirements and contrast protocol sophistication.
- Coronary Angiography:Non-invasive visualization of coronary arteries demands sub-75-millisecond temporal resolution to freeze cardiac motion, driving specification requirements for dual-source CT architectures. United States hospitals prioritize this indication for emergency chest pain triage.
- Heart Valve Assessment:Functional imaging of valve dynamics requires ECG-gated acquisition with retrospective reconstruction phases. German hospital networks invest in dual-energy material decomposition to characterize calcification burden for transcatheter intervention planning.
- Aortic Imaging:Extended field-of-view coverage for thoracoabdominal assessment favors wide-detector 256-slice platforms.
- Congenital Defects:Pediatric protocols impose strict radiation dose constraints favoring iterative reconstruction algorithms.
Coronary angiography dominates procedure volume. Heart valve assessment shows the steepest technology upgrade trajectory as transcatheter interventions expand eligibility criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs premium system pricing for dual-source architectures while China scales procurement through hospital infrastructure buildouts in tier-one cities. The United States concentrates emergency coronary angiography demand across integrated delivery networks. Japan enforces radiation dose optimization through PMDA standards. India expands cost-sensitive diagnostic capacity through private imaging chains.
United States
Emergency chest pain triage protocols drive 256-slice system deployment across high-volume centers. FDA 510(k) clearance streamlines iterative reconstruction algorithm approvals for vendors competing on low-dose claims. Cleveland Clinic and Mayo Clinic anchor photon-counting detector pilots for ultra-low-dose coronary angiography research.
Germany
Academic medical centers validate quantitative perfusion metrics for EU MDR compliance on material decomposition claims. The national regulator mandates prospective outcome data for plaque characterization indications under CE marking. Siemens Healthineers anchors premium service contracts across hospital networks in Bavaria and North Rhine-Westphalia.
China
Hospital procurement budgets prioritize 256-slice throughput for cardiac imaging infrastructure in Beijing and Shanghai. NMPA governs medical device registration pathways for spectral CT platforms entering the domestic market. United Imaging Healthcare and Neusoft Medical Systems occupy positions within the domestic equipment supply chain.
Japan
Cardiac surgery planning workflows demand sub-75-millisecond temporal resolution for valve assessment protocols. PMDA enforces JIS standards for radiation dose reporting that reshape product development priorities. Tokyo and Osaka medical centers pilot dual-energy CT for myocardial perfusion quantification studies.
India
Private diagnostic chains in Mumbai and Delhi seek refurbished 128-slice systems for cost-sensitive cardiac screening programs. CDSCO regulates medical device imports and domestic manufacturing quality standards. Apollo Hospitals and Max Healthcare expand outpatient cardiac imaging capacity across metropolitan clusters.
Cardiovascular CT Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated imaging conglomerates commanding premium tier positioning while regional fabricators compete on acquisition cost. The vendor base concentrates around detector architecture differentiation and software-defined workflow subscriptions. Three archetypes dominate: full-stack imaging conglomerates with dual-source CT platforms, mid-tier regional equipment suppliers, and refurbished system distributors serving cost-sensitive markets. M&A activity targets AI-assisted reconstruction algorithm developers, while capacity expansion concentrates on photon-counting detector fabrication facilities.
Among Germany-based conglomerates, Siemens Healthineers exemplifies the full-stack archetype through dual-source CT architectures and outcome-based service contracts. GE Healthcare represents North American R&D intensity in detector physics and iterative reconstruction pipelines. Canon Medical Systems Corporation occupies a position within the Japanese imaging equipment tier, while Koninklijke Philips N.V. anchors European hospital network relationships through enterprise imaging contracts. Chinese manufacturers United Imaging Healthcare and Neusoft Medical Systems sit within the domestic market supply chain, competing on cost-adjusted specifications for hospital procurement tenders.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Canon Medical Systems Corporation |
| Koninklijke Philips N.V. |
| Fujifilm Holdings Corporation |
| United Imaging Healthcare |
| Neusoft Medical Systems Co. Ltd. |
| NeuroLogica Corporation |
| Shenzhen Anke High-tech Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States consolidate procurement authority around enterprise imaging contracts, anchoring a subscription-based pricing model that unbundles hardware from recurring clinical workflow fees. This buyer concentration shifts margin capture toward software-defined service tiers and away from capital equipment transactions.
Pricing Analysis
Capacity additions in China are reshaping price floors for mid-tier 128-slice systems as domestic manufacturers compete on cost-adjusted specifications. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting detector arrays from dual-energy CT platforms and refurbished legacy units. Pricing pressure stems from EU MDR compliance costs extending European launch timelines. Imaging centers in India exhibit highest price sensitivity, while academic medical centers in Germany absorb premium tiers for research-validated quantitative perfusion metrics.
Supply Chain Analysis
FDA 510(k) and EU MDR CE marking pathways gate market access, forcing manufacturers to maintain parallel regulatory documentation systems. Detector array fabrication concentrates in Germany, Japan, and the United States, with cadmium telluride sensor production anchored in specialized semiconductor foundries. Supply chains draw from rare earth elements for scintillator materials, precision-machined gantry components, and computational backend hardware. Single-source vulnerability runs through photon-counting detector substrate suppliers. Distribution runs through direct OEM sales teams for hospital networks and third-party refurbished equipment brokers for cost-sensitive diagnostic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiovascular CT systems function as a regulatory compounder where EU MDR clinical evidence requirements for plaque characterization claims accelerate R&D consolidation and raise competitive barriers for new platform entrants.
For Market Incumbents: Deploy outcome-based service contracts to lock hospital network relationships before photon-counting detector technology commoditizes. Siemens Healthineers pilots uptime-guaranteed subscriptions across German hospital networks, establishing recurring revenue anchors. Defend against Chinese domestic manufacturers by accelerating FDA 510(k) clearances for iterative reconstruction algorithms that compress radiation dose benchmarks. For New Entrants and Emerging Players: Capture refurbished 128-slice system distribution for private diagnostic chains in Mumbai and Delhi, where CDSCO import regulations create arbitrage opportunities for cost-optimized equipment sourcing. India's outpatient cardiac imaging expansion offers the most penetrable geography. Partner with local biomedical engineering firms for installation and maintenance capacity rather than building captive service infrastructure. For Investors and Strategic Acquirers: Full-stack imaging conglomerates are the most active acquirer in this space, targeting AI-assisted reconstruction algorithm developers to differentiate spectral CT platforms. Long-term viability rests on software subscription attach rates outpacing hardware replacement cycles. Watch for NMPA registration pathway streamlining in China as an inflection indicator for domestic manufacturer competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Fabrication Scale-Up | Cadmium telluride sensor capacity expansion in Germany and Japan secures premium tier supply. |
| EU MDR Multi-Center Registry Funding | Prospective outcome data investment validates material decomposition claims for CE marking. |
| AI-Assisted Plaque Characterization Acquisition | Machine learning algorithm integration automates coronary risk scoring for asymptomatic populations. |
| Hospital System Partnership Expansion | Enterprise imaging contracts with United States integrated delivery networks consolidate vendor relationships. |
| Refurbished Equipment Channel Development | Cost-sensitive diagnostic chains in India access cardiac screening capacity without capital expenditure burden. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EU MDR submission databases, NMPA registration records, and hospital procurement tender databases. Bottom-up system shipment estimates triangulated against top-down addressable market calculations.
Comparable historical periods anchored the projection horizon across product type, technology tier, end-user setting, clinical application, and regional regulatory cluster dimensions. CAGRs derived from segmented growth rate modeling incorporating replacement cycle timing, infrastructure buildout trajectories, and reimbursement pathway evolution. Forecast inputs included iterative reconstruction algorithm adoption curves and photon-counting detector pilot program expansion.
Regulatory pathway divergence, supply chain disruption, and reimbursement rate compression are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in EU MDR clinical evidence requirements or NMPA domestic preference policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Cardiovascular Needle Market
Cardiovascular Devices
Infusion Catheters Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Global Artificial Heart Market