
 Global Critical Limb Ischemia Treatment Market | 2026-2036
Global Critical Limb Ischemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Critical Limb Ischemia Treatment Market Foresight
Drug-eluting balloon technology is rewriting the revascularization paradigm for below-the-knee lesions, shifting procedural economics toward outpatient settings. Medtronic leverages its integrated endovascular portfolio to sustain leadership in catheter-based platforms across multiple geographies. Boston Scientific Corporation anchors its position through specialized drug-coated balloon platforms designed for complex tibial anatomy. Abbott Laboratories differentiates via its focus on bioresorbable scaffold technologies for small-vessel applications.
Critical limb ischemia denotes advanced peripheral artery disease characterized by chronic rest pain, non-healing ulcers, or gangrene resulting from severe obstruction of arterial blood flow to the lower extremities, typically defined by ankle-brachial index measurements below 0.4 or absolute ankle pressure below 50 mmHg. The condition demands urgent intervention to prevent limb loss, with treatment selection governed by lesion morphology, runoff status, and patient comorbidity burden. Angioplasty and catheter-based delivery modes command the largest current revenue share due to established reimbursement and minimally invasive recovery profiles, while cell therapy represents the fastest-expanding segment as pluripotent stem cell platforms advance through late-stage clinical validation. End user concentration tilts toward vascular surgery centers where hybrid operating capabilities enable simultaneous endovascular and open surgical approaches.
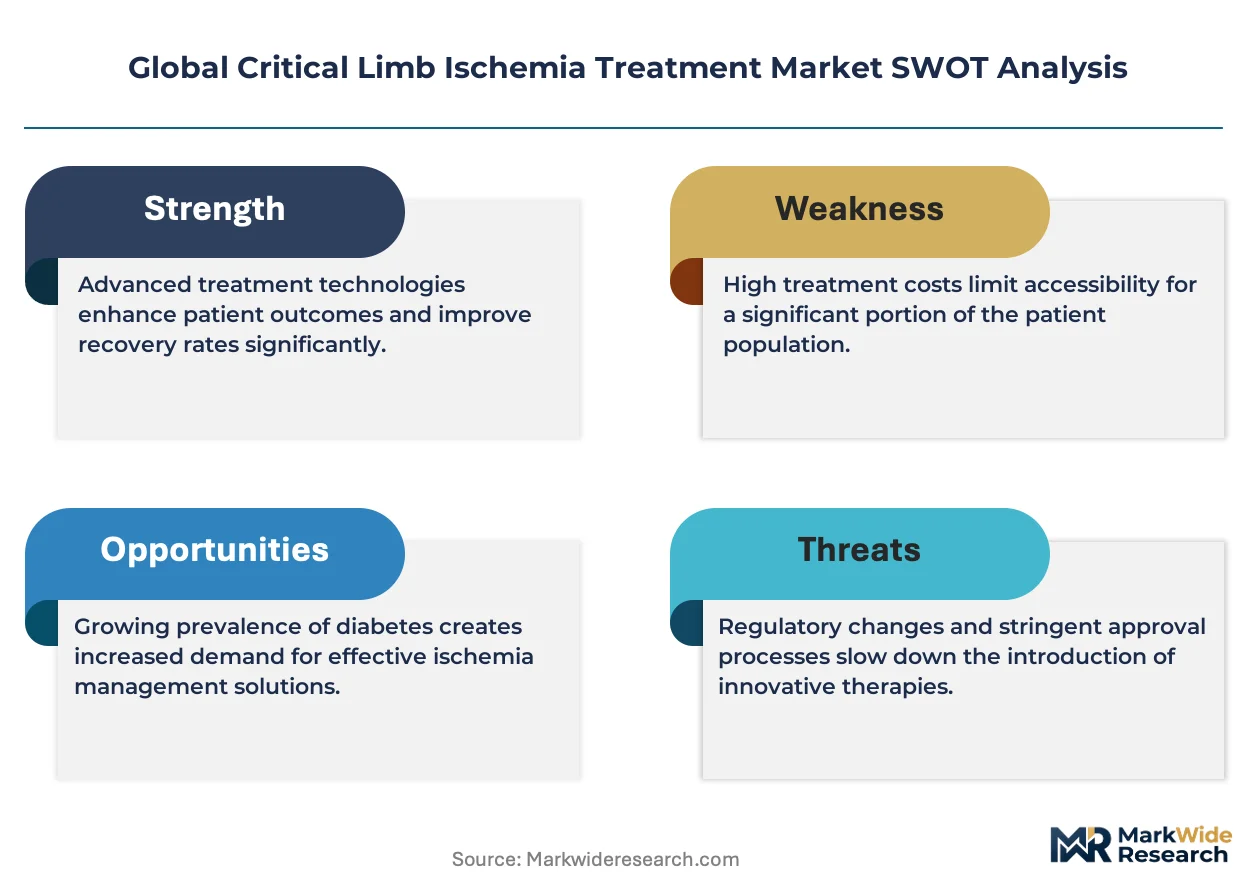
The FDA regulates device-based interventions through the premarket approval and de novo pathways, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements for peripheral vascular devices across European markets. Japan's PMDA maintains distinct reimbursement listing processes that shape product launch sequencing and commercial investment priorities. Stakeholders must monitor evolving health technology assessment methodologies in major markets, as payer scrutiny of cost-effectiveness evidence intensifies for premium-priced limb salvage technologies.
Market Dynamics
Catheter-based revascularization is consolidating procedural volume around outpatient settings, compressing hospital inpatient economics while elevating reimbursement complexity for device manufacturers across major markets.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway compresses commercialization timelines for novel limb salvage technologies, accelerating patient access to first-in-class therapies.
- Japan's Super-Aged Society:Demographic concentration above age 75 sustains procedure demand for below-the-knee interventions in Tokyo and Osaka metropolitan clusters.
- Drug-Eluting Balloon Platforms:These catheter-based systems reduce restenosis rates in tibial lesions, shifting clinical preference toward endovascular first-line therapy.
Market Restraints
- Platinum-Iridium Alloy Supply:Concentrated mining operations in South Africa and Russia create input volatility for electrode and guidewire manufacturing.
- EMA MDR Clinical Evidence Requirements:Stricter post-market surveillance mandates extend certification timelines and elevate documentation costs for peripheral vascular devices.
- Primary Patency Limitations:Bare-metal stents in small-caliber tibial vessels demonstrate inferior durability versus surgical bypass, constraining indication expansion.
Strategic Opportunities
- German Ambulatory Surgery Centers:Regulatory reforms enabling same-day discharge for complex endovascular procedures create channel expansion potential outside traditional hospital systems.
- Autologous Cell Therapy:Pluripotent stem cell platforms targeting angiogenesis represent white-space indications beyond mechanical revascularization.
- India's PLI Scheme for Medical Devices:Domestic manufacturing incentives attract catheter production investment to serve South Asian price-sensitive segments.
Industry Challenges
- Vascular Surgeon Training Bottlenecks:Hybrid operating capability requires dual endovascular and open-surgical proficiency, constraining eligible operator supply.
- PMDA Reimbursement Listing Sequencing:Japan's distinct pricing negotiation timelines delay commercial launch returns relative to FDA-cleared markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Critical Limb Ischemia Treatment Market |
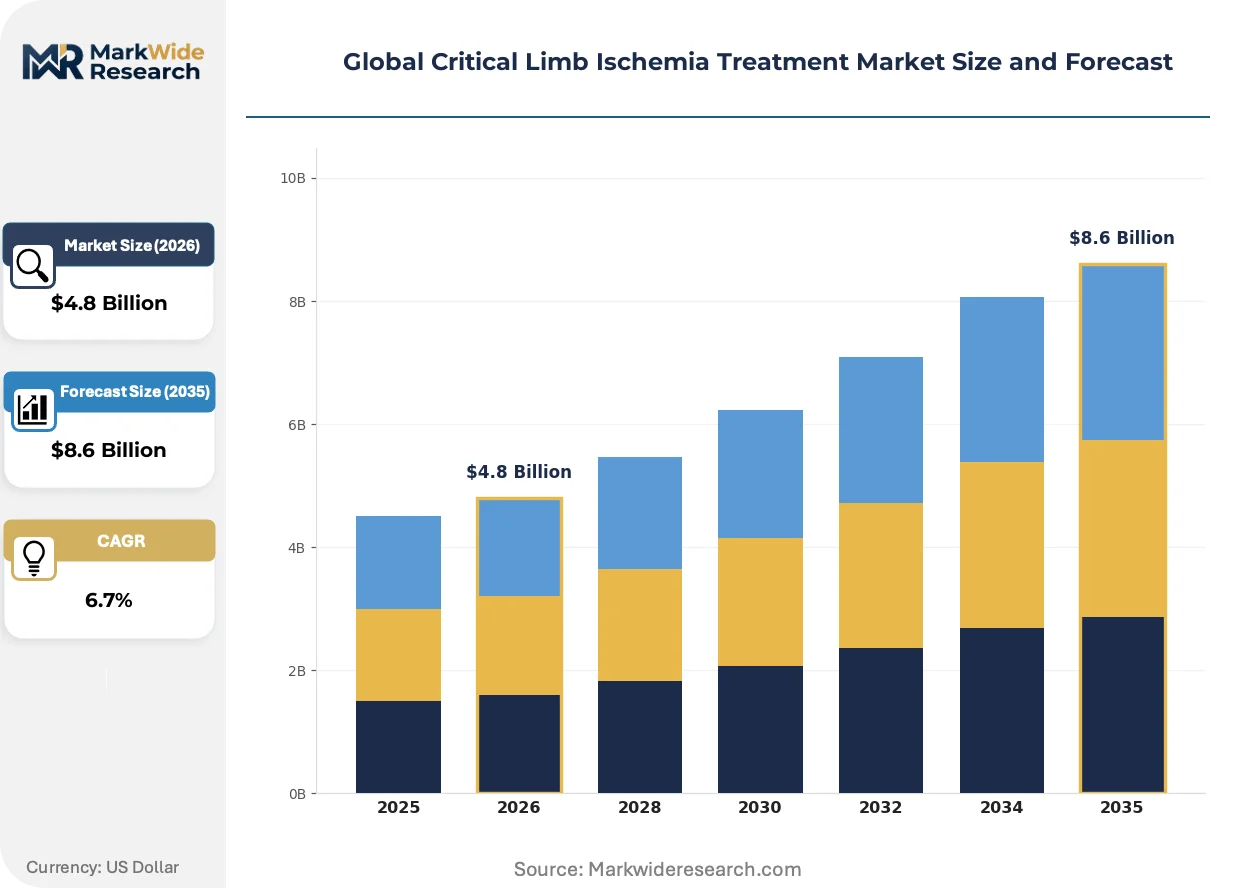
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Angioplasty, Bypass Surgery, Thrombolytic Therapy, Cell Therapy, Endarterectomy Indication: Rest Pain, Tissue Loss, Ulceration, Gangrene, Non-Healing Wounds End User: Vascular Surgery Centers, Specialty Clinics, Home Healthcare Providers, Rehabilitation Facilities, Diagnostic Labs Delivery Mode: Catheter-Based, Surgical, Pharmacological, Cell-Based, Hybrid Procedures |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, LimFlow SA, Pluristem Therapeutics, Cesca Therapeutics, Cardiovascular Systems, Inc., Cook Medical, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Critical Limb Ischemia Treatment Market Shifts & Advancements
Bioresorbable scaffold engineering and real-world evidence generation are reconfiguring competitive advantage in small-vessel intervention, favoring manufacturers with integrated clinical trial infrastructure.
Drug-eluting balloon technology is rendering obsolete bare-metal stent deployment in below-the-knee lesions. Vascular surgery centers in Germany and the United States are adopting these platforms at accelerating pace for complex tibial anatomy. The shift is compressing stent manufacturer revenue while elevating catheter-based platform economics.
EMA's Medical Device Regulation imposes stricter clinical evidence requirements for peripheral vascular devices across European markets. Manufacturers must now submit extended post-market surveillance data before maintaining CE marking. High-complexity scaffold and balloon catheter segments face the steepest compliance cost escalation.
Hospital procurement committees are consolidating vendor relationships around full-portfolio suppliers capable of hybrid procedure support. Independent catheter manufacturers face exclusion from integrated delivery networks in the United States and Western Europe. This concentration is most visible in multi-hospital systems across Texas and Bavaria where single-source contracts dominate.
Global Critical Limb Ischemia Treatment Market Segmentation
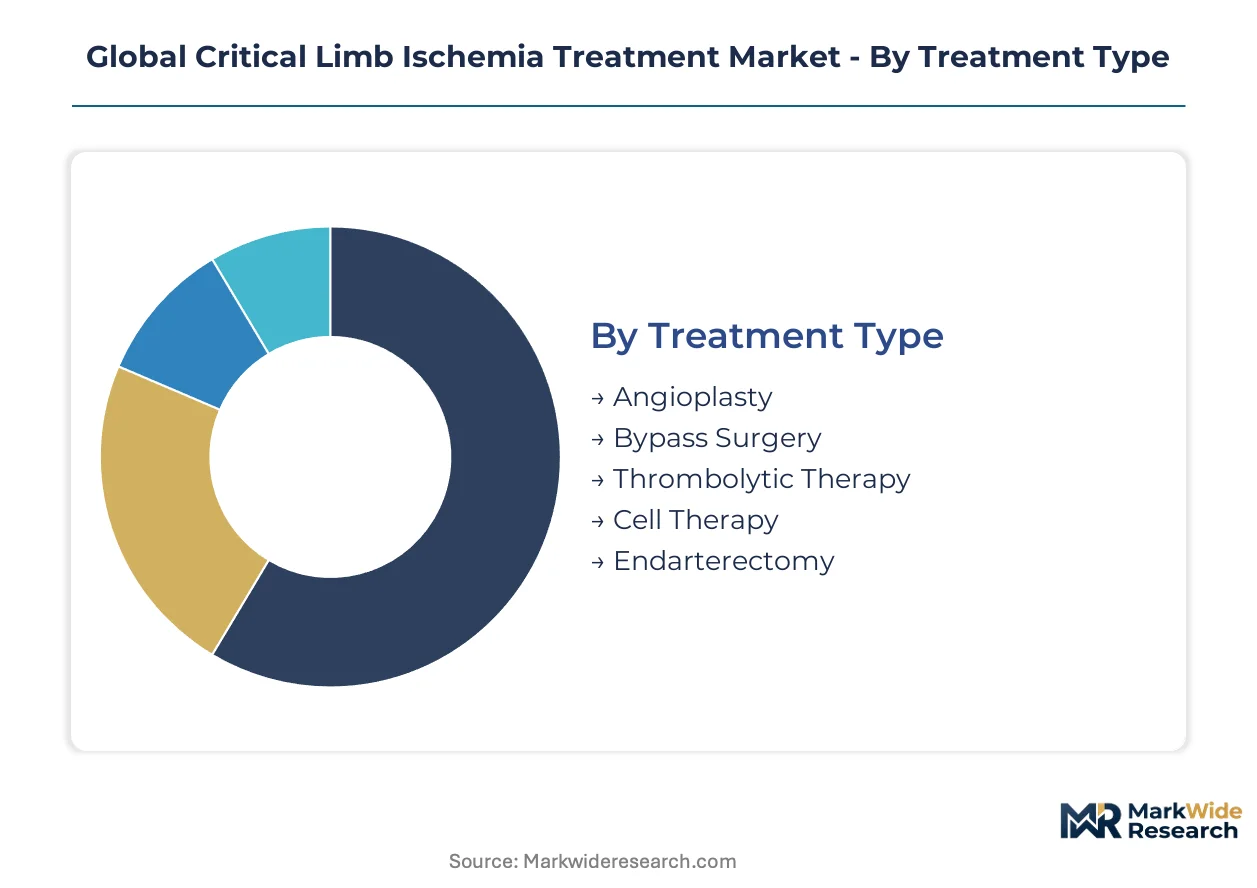
Critical limb ischemia treatment selection hinges on lesion complexity, patient comorbidity burden, and institutional capability. Segmentation reveals how reimbursement frameworks and technological maturity channel demand across intervention modalities and care settings.
Treatment Type:
The use-case spectrum spans mechanical revascularization through biological regeneration, with procedure economics shifting toward outpatient-compatible modalities.
- Angioplasty:Balloon catheter dilation of stenotic arterial segments, often augmented with drug-eluting or cutting balloon platforms. Demand concentrates in hospital outpatient departments across the United States and Germany where same-day discharge protocols maximize facility throughput.
- Cell Therapy:Autologous or allogeneic stem cell delivery targeting therapeutic angiogenesis in no-option patients. Clinical validation efforts in Japan's super-aged metropolitan clusters are accelerating regulatory pathway refinement for pluripotent platforms.
- Bypass Surgery:Autologous vein or prosthetic graft construction for durable revascularization in favorable anatomy.
- Thrombolytic Therapy:Catheter-directed thrombolysis for acute limb ischemia superimposed on chronic disease.
- Endarterectomy:Open surgical removal of atherosclerotic plaque, reserved for focal common femoral disease.
The dominant share belongs to angioplasty, while cell therapy is closing the gap fastest.
Indication:
Clinical presentation severity dictates urgency, reimbursement tier, and likelihood of limb salvage versus primary amputation.
- Tissue Loss:Digital or forefoot necrosis with intact heel and ankle perfusion. Vascular surgery centers in Texas and Bavaria report highest procedure volumes for this indication due to integrated wound care protocols.
- Rest Pain:Ischemic discomfort at rest without tissue breakdown, representing the earliest surgical indication threshold. German ambulatory surgery centers are expanding endovascular capacity to capture this less complex caseload.
- Ulceration:Full-thickness skin defect without gangrene, often requiring concurrent infection management.
- Gangrene:Tissue necrosis with demarcation, frequently necessitating partial foot amputation despite revascularization.
- Non-Healing Wounds:Chronic ulceration beyond six weeks with documented perfusion deficit.
Tissue loss commands the largest addressable population, though rest pain shows the steepest expansion trajectory as screening programs widen diagnostic capture.
End User:
Site-of-care migration toward lower-acuity settings is redistributing revenue across institutional categories with varying capital requirements.
- Vascular Surgery Centers:Hybrid operating suites enabling simultaneous endovascular and open surgical capability. These facilities in Tokyo and Osaka metropolitan clusters maintain highest tibial intervention volumes through dedicated limb salvage programs.
- Specialty Clinics:Office-based labs and standalone endovascular centers focused on diagnostic angiography and percutaneous intervention. Regulatory reforms in Germany are licensing these sites for same-day complex procedures previously restricted to hospitals.
- Home Healthcare Providers:Wound care and post-revascularization monitoring services.
- Rehabilitation Facilities:Gait training and functional recovery after limb salvage or amputation.
- Diagnostic Labs:Non-invasive vascular testing and ankle-brachial index screening.
Vascular surgery centers retain the dominant procedural share, while specialty clinics are gaining volume fastest through regulatory-enabled site-of-care expansion.
Delivery Mode:
Technical approach selection reflects lesion morphology, operator training, and device availability within specific markets.
- Catheter-Based:Percutaneous transluminal angioplasty with or without adjunctive stenting or atherectomy. Hospital systems across the United States are consolidating procurement around full-portfolio suppliers capable of supporting these procedures.
- Hybrid Procedures:Combined endovascular and open surgical intervention in single operative session. German vascular surgery centers pioneered this approach for multilevel disease and now export training protocols to Japanese institutions.
- Surgical:Open bypass or endarterectomy without endovascular component.
- Pharmacological:Systemic antiplatelet, anticoagulant, and vasoactive drug regimens.
- Cell-Based:Direct intramuscular or intra-arterial stem cell delivery.
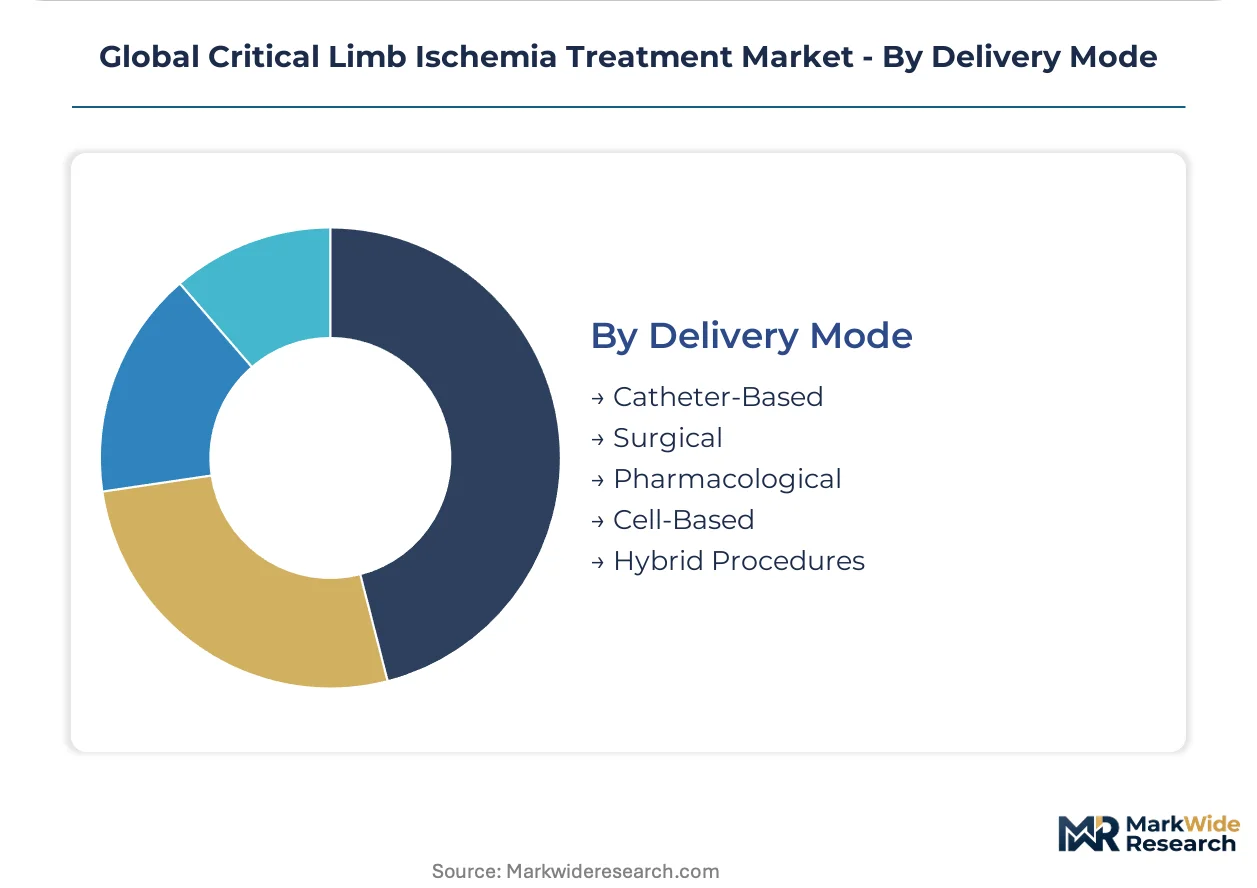
Catheter-based delivery holds the dominant position, with hybrid procedures climbing fastest as operator training bottlenecks gradually resolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports catheter-based revascularization platforms to Japanese vascular surgery centers, while the United States supplies drug-eluting balloon technologies to German ambulatory networks. This tripartite trade corridor concentrates procurement decisions in Tokyo, Munich, and Dallas metropolitan clusters.
United States
Hospital outpatient departments in Texas and Florida drive catheter-based procedure volumes through same-day discharge protocols. The FDA's breakthrough device designation pathway accelerates commercialization timelines for novel limb salvage technologies. Dallas-Fort Worth vascular surgery centers maintain the highest tibial intervention volumes through integrated wound care protocols.
Germany
Ambulatory surgery centers in Bavaria and North Rhine-Westphalia expand endovascular capacity for complex below-the-knee lesions. The EMA's Medical Device Regulation imposes stricter clinical evidence requirements for peripheral vascular devices across European markets. Munich metropolitan clusters pioneer hybrid procedure training protocols now exported to Japanese institutions.
Japan
Super-aged demographics above age 75 sustain demand for below-the-knee interventions in Tokyo and Osaka metropolitan areas. The PMDA maintains distinct reimbursement listing processes that shape product launch sequencing and commercial investment priorities. Osaka vascular surgery centers report highest procedure volumes through dedicated limb salvage programs.
India
Domestic manufacturing incentives under the PLI scheme attract catheter production investment to serve South Asian price-sensitive segments. The CDSCO regulates device-based interventions through premarket approval pathways for imported technologies. Maharashtra and Gujarat industrial corridors concentrate contract manufacturing for guidewire and balloon catheter components.
Switzerland
Swissmedic oversees clinical trial infrastructure for bioresorbable scaffold technologies targeting small-vessel applications. Precision manufacturing clusters in Basel and Zurich supply platinum-iridium alloy components for electrode and guidewire production. Geneva-based health technology assessment bodies influence payer scrutiny of cost-effectiveness evidence across European markets.
Global Critical Limb Ischemia Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement committees that consolidate vendor relationships around full-portfolio suppliers. The market structure tilts toward integrated medical technology conglomerates capable of hybrid procedure support, while independent catheter manufacturers face exclusion from multi-hospital systems. Three archetypes dominate: diversified conglomerates with endovascular portfolios, drug-device combination specialists, and cell therapy platform developers. M&A activity targets catheter-based platform capabilities, while strategic partnerships secure platinum-iridium alloy supply chains.
Within the diversified conglomerate tier, Medtronic and Boston Scientific Corporation exemplify channel-controlling positioning through integrated endovascular portfolios. Abbott Laboratories occupies a specialist position in bioresorbable scaffold technologies for small-vessel applications. These three anchors represent distinct competitive vectors: scale-driven procurement consolidation, drug-coated balloon specialization, and biodegradable implant innovation.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| LimFlow SA |
| Pluristem Therapeutics |
| Cesca Therapeutics |
| Cardiovascular Systems, Inc. |
| Cook Medical |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Platinum-iridium alloy supply volatility from South African and Russian mining operations compresses margin buffers across electrode and guidewire tiers while forcing catheter manufacturers toward dual-source qualification programs and regional buffer inventory strategies.
Pricing Analysis
Drug-eluting balloon platforms command substantial premiums over bare-metal stent equivalents and cutting balloon prior-generation alternatives, with price differentiation anchored in FDA breakthrough designation tiering and CE marking complexity under EMA MDR. Pricing pressure stems from German ambulatory surgery center procurement consolidation around full-portfolio suppliers capable of hybrid procedure support. Hospital systems in Texas and Florida demonstrate lowest price sensitivity due to integrated wound care reimbursement protocols, while Indian contract manufacturers face acute cost compression serving South Asian price-sensitive segments.
Supply Chain Analysis
Contract manufacturing for balloon catheter assemblies concentrates in Maharashtra and Gujarat industrial corridors, with precision guidewire production anchored in Swiss Basel and Zurich manufacturing clusters. Raw material dependencies span platinum-iridium alloys for electrodes, nitinol for superelastic guidewires, and paclitaxel coating substrates for drug-eluting platforms. Single-source vulnerability in South African platinum group metal extraction elevates supply chain risk exposure. Distribution runs through hospital procurement committees in the United States and integrated delivery networks in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catheter-based platform manufacturers increasingly attach clinical training and wound care protocol services to device contracts, with post-revascularization monitoring service layers expanding faster than hardware unit economics across vascular surgery centers.
For Market Incumbents: Insulate catheter-based revenue streams by deepening backward integration into platinum-iridium alloy supply through Swiss precision manufacturing partnerships, while securing exclusive GPO contracts with Texas and Bavarian multi-hospital systems before EMA MDR compliance costs escalate for smaller competitors. For New Entrants and Emerging Players: Pursue white-space positioning in autologous cell therapy platforms for no-option CLI patients, targeting Japan's super-aged metropolitan clusters where PMDA reimbursement pathway refinement creates regulatory clarity advantages unavailable in FDA-cleared markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified conglomerates with hybrid procedure capabilities; acquisition targets should demonstrate integrated endovascular portfolios or bioresorbable scaffold manufacturing infrastructure. Long-term viability through the next decade hinges on reimbursement strategy execution. The signal to watch is FDA breakthrough designation grant velocity as an indicator of competitive access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses commercialization timelines for novel limb salvage technologies entering United States markets. |
| EMA MDR Compliance Pathway | Extends certification timelines for peripheral vascular devices across European markets with elevated documentation costs. |
| Hospital System Partnership | Secures procurement committee inclusion through full-portfolio supplier positioning in Texas integrated delivery networks. |
| Reimbursement Strategy | Shapes PMDA listing sequencing decisions and commercial investment priorities for Japanese market entry. |
| Software Companion Development | Enables real-world evidence generation for bioresorbable scaffold platforms targeting small-vessel applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vascular surgeons, hospital procurement managers, GPO contracts specialists, and biomedical engineers at catheter manufacturing facilities. Secondary validation drew from FDA premarket approval filings, EMA MDR submission databases, PMDA reimbursement listing records, and hospital procurement databases across the United States, Germany, and Japan. Bottom-up procedure volume estimates and top-down market sizing were triangulated to reconcile segmentation outputs.
Calibration against historical procedure adoption curves and reimbursement expansion patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include treatment type, indication severity, end-user facility category, and delivery mode complexity. CAGRs were derived from slope analysis of technology diffusion curves and payer coverage expansion timelines. Forecast inputs incorporated PMDA pricing negotiation timelines and EMA MDR implementation phase transitions.
Macroeconomic conditions sit as an overlay; deviation in platinum group metal commodity indices, healthcare reimbursement policy shifts, or regulatory approval velocity would shift the trajectory. Forecasts reflect documented assumptions regarding procedure migration to outpatient settings and cell therapy clinical validation progress. Quarterly review of FDA breakthrough designation grants, EMA MDR certification timelines, and PMDA reimbursement listing decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market