
 Global Skin Grafting Device Market | 2026-2036
Global Skin Grafting Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Skin Grafting Device Market Foresight
Multi-source procurement for precision cutting blades is shifting toward captive in-house production among top-tier manufacturers. Zimmer Biomet leverages its orthopedic supply chain infrastructure to control dermatome blade fabrication costs. Integra LifeSciences anchors its position through regenerative tissue portfolios adjacent to grafting hardware. AVITA Medical specializes in autologous spray devices that compete with conventional mesh grafting workflows.
Skin grafting devices are surgical instruments designed to harvest and transfer epidermal or dermal tissue layers, typically operating at blade speeds between 3,500 and 15,000 oscillations per minute to achieve consistent split-thickness grafts of 0.15 to 0.40 millimeters. These systems serve primarily to restore integumentary function following thermal injury, chronic ulceration, or surgical excision of malignancy. Electric and battery-operated technologies command expanding share as operating room ergonomics and portability requirements intensify, while manual instruments retain cost-driven demand in resource-constrained settings. Burn treatment applications generate the deepest revenue pools due to repeat procedure volumes and specialized center concentration, though chronic wound care segments are gaining traction with aging patient demographics.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) establish divergent compliance burdens that shape product development timelines and geographic launch sequencing. The FDA's surgical instrument quality system regulation and MDR's enhanced clinical evidence mandates for Class IIa devices elevate barriers for smaller manufacturers seeking transatlantic market access. Stakeholders must monitor evolving reimbursement coding for autologous cell harvesting versus traditional grafting to anticipate shifts in hospital capital allocation and device preference.
Market Dynamics
Powered dermatomes are displacing manual instruments across burn centers and reconstructive surgery clusters, driven by blade speed precision requirements and operating room throughput pressures. This technology transition concentrates procurement decisions among specialized purchasing consortia in Germany, the United States, and Japan.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined premarket notification for surgical dermatome devices reduces time-to-market for powered instrument innovations. Burn centers in the United States are expanding capital equipment budgets accordingly.
- Chronic Wound Demographics:Aging patient populations in Japan and Italy are generating repeat procedure volumes for diabetic ulcer management. Autologous grafting protocols are standardizing in tertiary care networks.
- Battery-Operated Portability:Lithium-ion power systems enable field-deployable graft harvesting in mass casualty scenarios. Military medical corps and disaster response units are driving specification requirements.
Market Restraints
- Stainless Steel Input Volatility:Surgical-grade blade material costs fluctuate with nickel and chromium spot markets. German and Japanese precision forgers pass through price adjustments on quarterly contracts.
- EU MDR Clinical Evidence Burden:Enhanced post-market surveillance requirements for Class IIa devices extend certification timelines. Smaller manufacturers face capital constraints for notified body engagements.
- Cellular Spray Substitution:Autologous suspension technologies compete for burn center capital allocation against conventional mesh grafting workflows. Reimbursement coding disparities favor established procedures in several national health systems.
Strategic Opportunities
- India Tier-2 Hospital Expansion:Government health infrastructure programs are equipping district hospitals with basic dermatome capabilities. Domestic manufacturing incentives reduce import duty exposure for local assembly operations.
- Regenerative Adjacent Portfolios:Tissue-engineered dermal scaffolds create bundled procurement opportunities with harvesting hardware. Hospital value analysis committees prefer integrated vendor relationships.
- Telemedicine-Enabled Pre-Surgical Planning:Digital wound assessment platforms are integrating with graft dimensioning software. Remote consultation networks in Australia and Canada are piloting automated thickness recommendation algorithms.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Specialized training for oscillating blade calibration and maintenance is concentrated in legacy manufacturing regions. Recruitment competition from orthopedic and cardiovascular device sectors intensifies.
- Legacy System Integration Friction:Electronic health record connectivity for graft tracking and inventory management requires custom API development. Hospital IT departments prioritize larger capital equipment categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Skin Grafting Device Market |
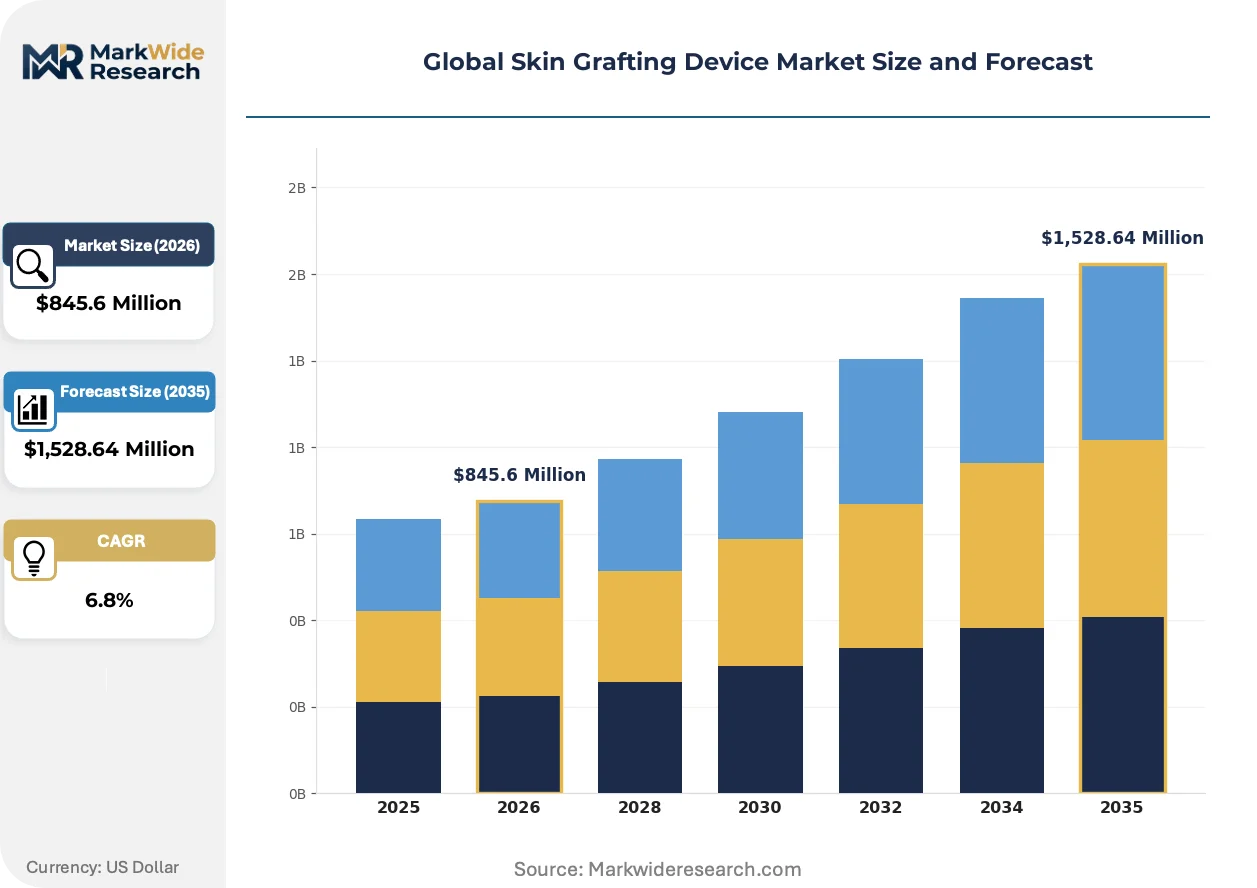
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,528.64 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dermatome, Skin Mesher, Split-Thickness Grafting Device, Full-Thickness Grafting Device, Autograft Instrument Technology: Manual, Electric, Hydraulic, Pneumatic, Battery Operated Application: Burn Treatment, Chronic Wound Care, Reconstructive Surgery, Cosmetic Surgery, Trauma Repair End User: Plastic Surgery Clinics, Burn Centers, Outpatient Facilities, Ambulatory Surgical Centers |
| Companies Covered | Zimmer Biomet, B. Braun, Integra LifeSciences, Exsurco Medical, Rudolf Storz GmbH, De Soutter Medical Limited, AVITA Medical, Humeca BV, Aygun Surgical Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Skin Grafting Device Market Shifts & Advancements
Digital blade control systems and connected device architectures are redefining precision parameters in graft harvesting workflows. These advances compress operator learning curves while generating procedural data assets.
Continuous depth-sensing dermatomes with real-time feedback displays are overtaking fixed-setting instruments in academic medical centers. Burn unit directors in the United States and Germany specify these systems for resident training programs. The technology is compressing variation in split-thickness graft outcomes and reducing revision procedure rates.
The EU Medical Device Regulation's unique device identification mandates are forcing serialization investments across surgical instrument supply chains. German and Italian manufacturers are retrofitting production lines with laser marking and database integration capabilities. Class IIa device importers into the European Union face extended customs clearance protocols until traceability systems achieve full compliance.
Hospital purchasing cooperatives are consolidating dermatome procurement through multi-year managed service agreements. Independent distributors in France and Spain are losing direct access to burn center accounts as equipment vendors internalize field service operations. This channel compression is most visible in national health systems with centralized capital budgeting authority.
Global Skin Grafting Device Market Segmentation
Segmentation in the skin grafting device market reveals divergent capital requirements across hardware categories. Procurement patterns vary sharply between high-volume burn centers and distributed outpatient settings, with technology choices directly tied to procedure throughput and reimbursement economics.
Product Type:
Capital intensity peaks with powered harvesting systems requiring precision motor assemblies and oscillating blade mechanisms.
- Dermatome:Oscillating blade instruments generate split-thickness grafts through motorized or manual operation at 3,500 to 15,000 RPM. German reconstructive surgery clusters and North American burn centers drive specification requirements for continuous depth-sensing variants.
- Skin Mesher:Expansion ratio instruments perforate harvested tissue to increase surface coverage, with 1.5:1 to 6:1 expansion settings. Demand concentrates in trauma repair protocols across United States academic medical centers where mesh grafting remains the cost-standard for large-area coverage.
- Split-Thickness Grafting Device:Epidermal-dermal harvesting systems dominate high-volume thermal injury treatment.
- Full-Thickness Grafting Device:Complete dermal excision instruments serve specialized reconstructive applications.
- Autograft Instrument:Patient-derived tissue processing tools support cellular spray workflows.
Dermatome hardware absorbs the bulk of installed capacity; skin meshers are expanding most quickly through trauma protocol standardization.
Technology:
Power source selection determines field deployability, maintenance burden, and per-procedure operating cost structure.
- Manual:Hand-cranked instruments with zero electrical dependency serve resource-constrained settings and backup scenarios. District hospitals in India and field military units specify these for reliability under infrastructure failure conditions.
- Electric:Corded motor systems deliver consistent blade speed for precision graft thickness control. United States burn centers prioritize these for resident training programs where outcome consistency outweighs portability requirements.
- Hydraulic:Fluid-pressure actuation provides smooth cutting force for dense tissue harvesting.
- Pneumatic:Compressed air systems offer sterilization compatibility in specific operating room configurations.
- Battery Operated:Lithium-ion power enables mass casualty deployment and ambulatory surgical center adoption.
Electric systems anchor current procurement volumes; battery operated configurations are climbing the fastest as lithium-ion energy density improves.
Application:
Procedure reimbursement codes and repeat visit frequency shape device utilization rates across clinical settings.
- Burn Treatment:Thermal injury protocols require staged grafting procedures with high repeat volumes. Specialized centers in Germany and Japan generate concentrated demand for powered harvesting systems due to procedure density and severity grading complexity.
- Chronic Wound Care:Diabetic ulcer and venous stasis management drives outpatient grafting adoption. Aging demographics in Italy and Japan are expanding autologous protocol standardization in tertiary care networks.
- Reconstructive Surgery:Post-oncologic and congenital defect restoration employs full-thickness techniques.
- Cosmetic Surgery:Aesthetic applications utilize precision harvesting for scar revision and texture matching.
- Trauma Repair:Acute injury grafting combines mesh expansion with rapid coverage objectives.
Burn treatment commands the deepest revenue pools; chronic wound care is gaining share fastest through demographic tailwinds.
End User:
Facility scale and capital budgeting authority determine procurement channel access and service contract structure.
- Plastic Surgery Clinics:Private practice settings prioritize compact footprint and premium aesthetic outcomes. German specialized reconstructive clusters specify high-precision instruments for cosmetic-adjacent procedures.
- Burn Centers:Dedicated thermal injury facilities generate the highest procedure volumes and capital equipment refresh cycles. United States centers are expanding powered dermatome procurement through managed service agreements with direct vendor relationships.
- Outpatient Facilities:Distributed wound care sites drive portable and lower-capital configurations.
- Ambulatory Surgical Centers:Same-day discharge protocols favor battery-operated and rapid-setup systems.
Burn centers concentrate the majority of capital deployment; ambulatory surgical centers are expanding most quickly through site-of-service migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical-grade stainless steel forgers in Solingen, Germany supply precision blade blanks to reconstructive surgery clusters worldwide. Nickel and chromium spot volatility propagates through quarterly contract adjustments from Japanese and German metallurgical suppliers. Device procurement concentrates where burn center density intersects with specialized reimbursement pathways.
United States
FDA 510(k) pathway streamlining accelerates powered dermatome introductions for burn center capital budgets. The agency's quality system regulation for surgical instruments shapes domestic manufacturing compliance investments. Texas and California thermal injury centers drive specification requirements for continuous depth-sensing systems in resident training protocols.
Germany
Specialized reconstructive surgery clusters in North Rhine-Westphalia and Bavaria generate premium instrument adoption for precision graft harvesting. EU MDR unique device identification mandates force laser marking and serialization investments across Baden-Württemberg production lines. Solingen blade forgers pass through nickel alloy cost adjustments on quarterly supply contracts.
Japan
Aging demographics expand chronic wound care volumes for diabetic ulcer management in tertiary networks. METI medical device reimbursement frameworks favor established grafting procedures over cellular spray alternatives. Osaka and Tokyo academic medical centers standardize autologous protocols with repeat procedure density.
India
Government district hospital equipping programs extend basic dermatome capabilities to Tier-2 cities under health infrastructure expansion. CDSCO medical device rules and PLI scheme incentives reduce import duty exposure for domestic assembly operations. Maharashtra and Karnataka manufacturing zones attract component sourcing for regional supply chains.
United Kingdom
NHS specialized commissioning for burn services concentrates procurement decisions through managed service agreements. MHRA post-Brexit device regulations create parallel compliance tracks to EU MDR for London and Manchester trauma centers. Academic medical partnerships in the Midlands pilot telemedicine-integrated pre-surgical planning platforms.
Global Skin Grafting Device Market Competitive Landscape
Strategic portfolio diversification dominates the current landscape as orthopedic and wound care conglomerates extend into adjacent grafting hardware. The vendor base organizes around three tiers: diversified medical technology conglomerates with orthopedic supply chain leverage, specialized surgical instrument manufacturers with precision forging heritage, and regenerative medicine specialists with cellular processing capabilities. M&A activity and backward integration into blade fabrication represent the principal competitive vectors reshaping procurement relationships.
Within the diversified conglomerate tier, Zimmer Biomet and B. Braun exemplify players leveraging orthopedic infrastructure for dermatome blade cost control. Integra LifeSciences occupies a position bridging regenerative tissue portfolios with harvesting hardware bundling. Specialized instrument heritage is represented by Rudolf Storz GmbH and De Soutter Medical Limited, while AVITA Medical anchors the cellular spray alternative segment competing with conventional mesh workflows.
| Leading Market Players |
|---|
| Zimmer Biomet |
| B. Braun |
| Integra LifeSciences |
| Exsurco Medical |
| Rudolf Storz GmbH |
| De Soutter Medical Limited |
| AVITA Medical |
| Humeca BV |
| Aygun Surgical Instruments |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA-cleared powered dermatomes and unregulated manual instruments manifests in both procurement premiums and supply chain sourcing strategies. German and Japanese precision forgers command blade blank premiums for CE-marked and FDA-registered device tiers, while Indian and Chinese assembly operations serve cost-driven district hospital segments through reduced regulatory documentation burdens.
Pricing Analysis
Warranty and field service bundling separates premium powered dermatome contracts from unbundled manual instrument transactions. Three-tier pricing structure across premium continuous depth-sensing systems, standard electric dermatomes, and economy manual instruments reflects certification tier and blade precision grade. Pricing pressure stems from nickel and chromium spot volatility propagating through quarterly stainless steel supply contracts. Burn centers in the United States and Germany exhibit lowest price sensitivity due to outcome-based procurement mandates, while Indian Tier-2 hospitals prioritize capital cost minimization.
Supply Chain Analysis
Specialized biomedical engineer scarcity in Solingen, Tuttlingen, and Osaka precision manufacturing zones constrains oscillating blade calibration capacity expansion. Germany, Japan, and the United States concentrate high-grade dermatome production, while India and China scale domestic assembly for regional markets. Supply chains draw from surgical-grade stainless steel forgers, lithium-ion cell manufacturers, and precision motor suppliers. Single-source vulnerability concentrates in Solingen blade blank sourcing for premium instrument tiers. Distribution runs through hospital purchasing cooperatives and direct vendor relationships with burn center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive blade fabrication and regenerative tissue portfolio bundling determine margin sustainability. Players are pursuing upstream control over precision forging capacity to secure cost position and supply continuity.
For Market Incumbents: Cement procurement relationships through multi-year managed service agreements with burn center networks. Deepen backward integration into dermatome blade fabrication to offset nickel alloy cost volatility. Cellular spray substitution from AVITA Medical and regenerative medicine specialists threatens conventional mesh grafting capital allocation. FDA 510(k) pathway acceleration favors incumbents with established quality system infrastructure. For New Entrants and Emerging Players: Begin with battery-operated portable configurations for ambulatory surgical centers and military medical corps procurement channels. Target chronic wound care segments in Japan and Italy where demographic tailwinds expand repeat procedure volumes. Unbundled software companion development for telemedicine-integrated pre-surgical planning offers white-space entry with lower capital barriers than hardware manufacturing. For Investors and Strategic Acquirers: Re-rating potential sits with specialized surgical instrument manufacturers possessing precision forging heritage given EU MDR compliance consolidation pressure. Long-term viability favors players bridging harvesting hardware with regenerative tissue portfolios. Watch reimbursement coding shifts for autologous cell harvesting versus traditional grafting as inflection signal for hospital capital allocation preference.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates powered dermatome introductions for United States burn centers. |
| CE Marking Pathway | EU MDR unique device identification mandates force serialization investments across German production lines. |
| Hospital System Partnership | Managed service agreements consolidate procurement decisions through direct vendor relationships with burn centers. |
| Software Companion Development | Telemedicine-integrated pre-surgical planning platforms differentiate precision harvesting workflows in academic medical centers. |
| Reimbursement Strategy | Coding alignment for autologous protocols versus conventional mesh grafting shapes capital equipment preference. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and FDA 510(k) clearance records underwrites the qualitative findings. Primary interviews with burn center directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers combined with secondary validation from CMS Medicare reimbursement data, EU MDR notified body registration databases, and customs import records. Bottom-up installed base modeling and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition across product type, technology, application, and end user dimensions structures the analytical framework. Segmentation modeling incorporates powered versus manual instrument mix, electric versus battery-operated technology share, burn treatment versus chronic wound care application split, and burn center versus ambulatory surgical center end user distribution. CAGRs derive from procedure volume forecasting cross-referenced with capital equipment replacement cycles and reimbursement pathway evolution. Nickel alloy spot price trajectories and lithium-ion energy density improvement curves inform cost structure projections.
Underlying measurement precision varies by segment; burn center procurement data carries tighter precision than distributed outpatient facility estimates. Forecasts reflect assumptions regarding FDA pathway streamlining continuity, EU MDR compliance timeline adherence, and reimbursement coding stability. Material deviation in nickel and chromium spot markets, cellular spray technology adoption rates, or district hospital equipping program funding warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Oxygenator Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Ovulation Microscope Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Extremity Reconstruction Market