
 Senior Care Technologies Market | 2026-2036
Senior Care Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Senior Care Technologies Market Outlook
Home health agency procurement channels are rewriting how senior care technologies reach end users, with platform vendors now competing directly for multi-year enterprise contracts. WellSky leverages its post-acute software footprint to anchor hospital-to-home transitions. PointClickCare sustains dominance in skilled nursing facility electronic health records, while AlayaCare specializes in cloud-based scheduling and billing for home care operators.
Senior care technologies encompass hardware and software systems engineered to monitor health status, automate medication adherence, detect falls, and facilitate remote clinical interactions for aging populations; core functional parameters include continuous biometric sampling rates, FDA 510(k) clearance thresholds for software-as-medical-device claims, and interoperability with HL7 FHIR standards for health information exchange. Wearable devices and home monitoring systems occupy the largest addressable revenue pools, reflecting recurring device replacement cycles and subscription-based data analytics revenue. Telehealth solutions and IoT solutions represent the fastest-expanding technology categories, driven by cellular-enabled sensors and edge-computing architectures that reduce latency for emergency response triggers.
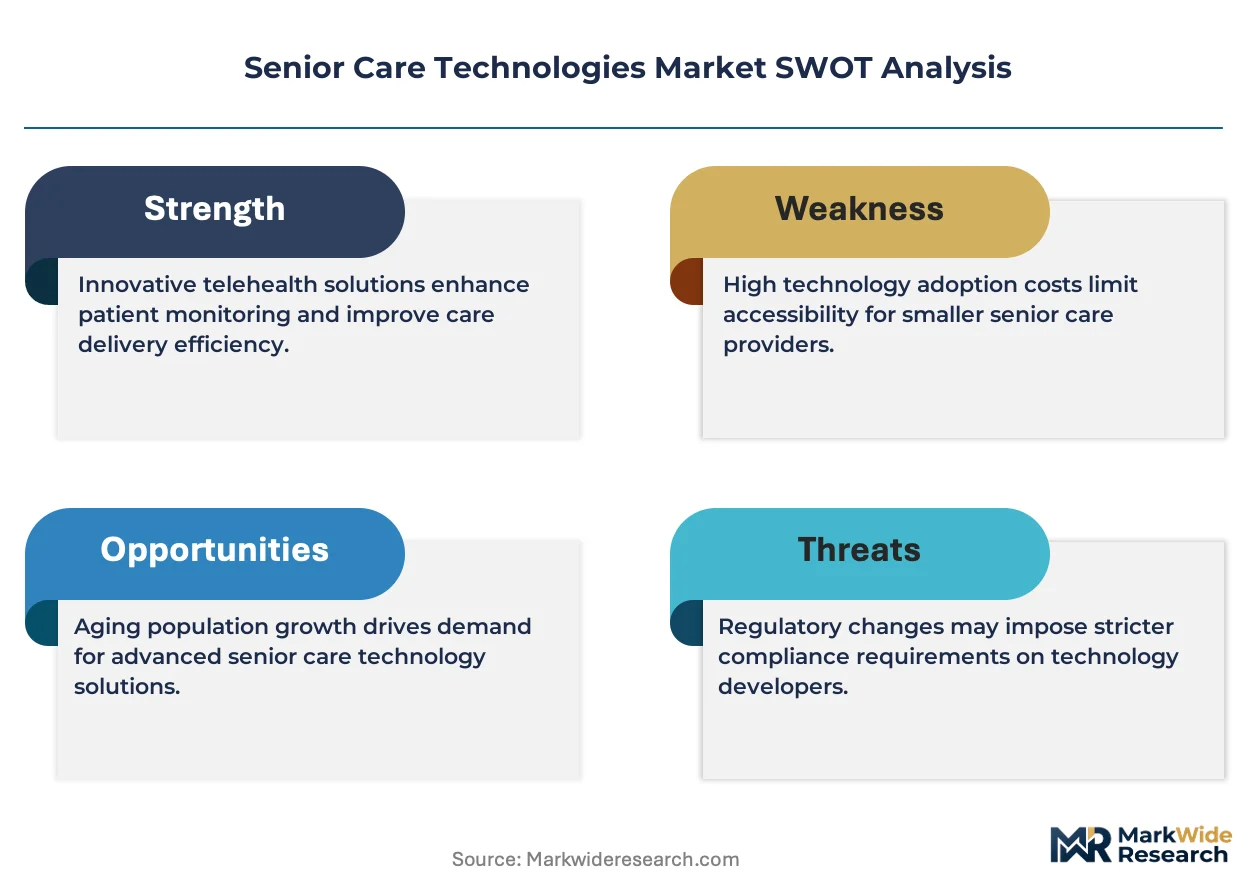
FDA digital health guidance and HIPAA security rule enforcement shape product development roadmaps, with pre-certification requirements forcing vendors to embed quality management systems earlier in design cycles. The EU MDR and GDPR impose parallel compliance burdens for wearable devices collecting biometric data from European seniors. Stakeholders must monitor evolving CMS reimbursement codes for remote therapeutic monitoring, as coverage determinations directly dictate provider willingness to deploy capital-intensive monitoring infrastructure.
Market Dynamics
Home health agencies now drive procurement decisions for connected monitoring platforms, shifting vendor relationships from device sales toward multi-year enterprise service agreements anchored by data analytics subscriptions.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare coverage for remote therapeutic monitoring services creates direct revenue pathways for providers deploying cellular-enabled sensors in patient homes.
- Edge Computing Architectures:Cellular-enabled sensors with localized processing reduce emergency response latency, making fall detection and cardiac event triggers clinically viable for home settings.
- FDA Pre-Certification Pathway:Software-based medical device approvals accelerate as quality management systems embed earlier in vendor design cycles.
Market Restraints
- Semiconductor Supply Concentration:Biometric sensor chip fabrication concentrates in East Asian foundries, exposing hardware vendors to input volatility and extended lead times.
- Interoperability Friction:HL7 FHIR standard implementation gaps between skilled nursing facilities and home health platforms force costly custom integration work.
- Cellular Infrastructure Dependency:Rural broadband and 5G coverage gaps limit platform deployment in geographically dispersed senior populations.
Strategic Opportunities
- Behavioral Health Integration:Depression and anxiety monitoring modules represent underpenetrated clinical applications within existing wearable form factors.
- Social Determinant Data Layers:Platforms incorporating transportation access and food security metrics qualify for enhanced value-based care contracts with Medicare Advantage plans.
- Caregiver Marketplace Features:Scheduling algorithms connecting family caregivers with professional home health aides create new subscription revenue streams.
Industry Challenges
- Clinical Workflow Integration:Home health nurses resist dashboard fatigue from multiple monitoring platforms lacking unified alert prioritization.
- Biometric Data Governance:HIPAA security rule enforcement creates liability exposure for vendors handling continuous glucose and blood pressure streams across state lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Senior Care Technologies Market |
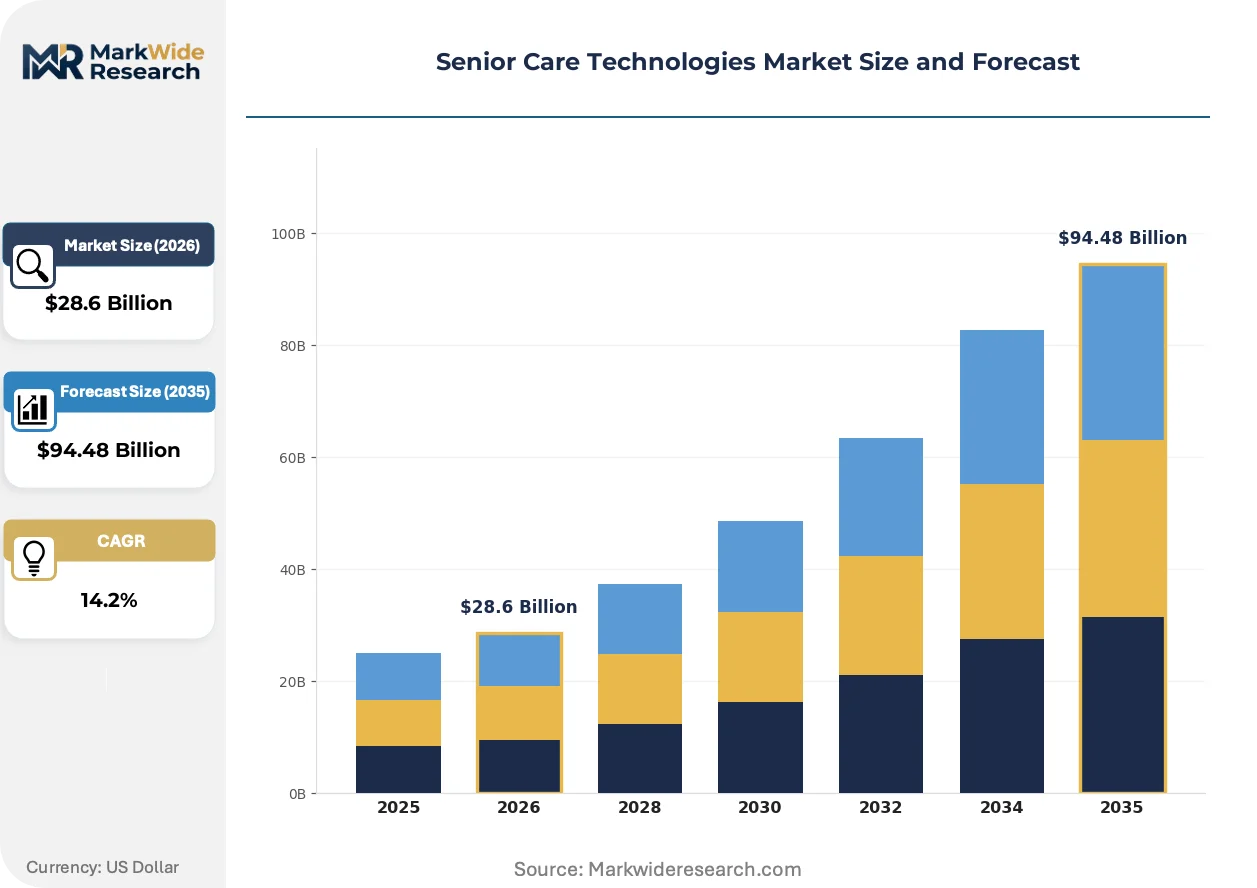
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Home Monitoring Systems, Medication Management Tools, Emergency Response Systems Technology: Telehealth Solutions, Smart Home Technology, Artificial Intelligence, IoT Solutions End User: Seniors Living Communities, Home Health Agencies, Family Caregivers, Health Insurance Providers Service Type: Consultative Services, Training Programs, Maintenance Services, Integration Support |
| Companies Covered | Eldermark, WellSky, DosePacker, PointClickCare, CareSmartz360, MatrixCare, Yardi, AlayaCare, ALIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Senior Care Technologies Market Strategic Shifts
Sensor miniaturization and cellular module cost reductions are compressing hardware replacement cycles while software subscriptions capture recurring value from aging-in-place infrastructure investments.
Passive radar monitoring is collapsing the distinction between wearable and ambient sensing modalities. These systems track respiration and gait through radio frequency signals without body-worn devices. Home health agencies in Medicare Advantage networks are piloting installations at scale. The technology is collapsing capital expenditure requirements for continuous monitoring by eliminating device procurement and replacement logistics.
The EU MDR imposes parallel compliance burdens for wearable devices collecting biometric data from European seniors, forcing vendors to maintain dual quality management systems. Hardware manufacturers must demonstrate clinical evidence for software updates that alter diagnostic algorithms. Vendors serving transatlantic markets are responding by segregating European product lines with localized data residency architectures.
Hospital-at-home programs are consolidating purchasing authority for post-acute monitoring equipment under health system supply chain officers. Traditional durable medical equipment distributors face disintermediation as direct vendor-to-health-system contracts proliferate. This pattern is most visible in United States markets where CMS waiver programs expand eligible diagnoses for acute-level care in residential settings.
Senior Care Technologies Market Segmentation
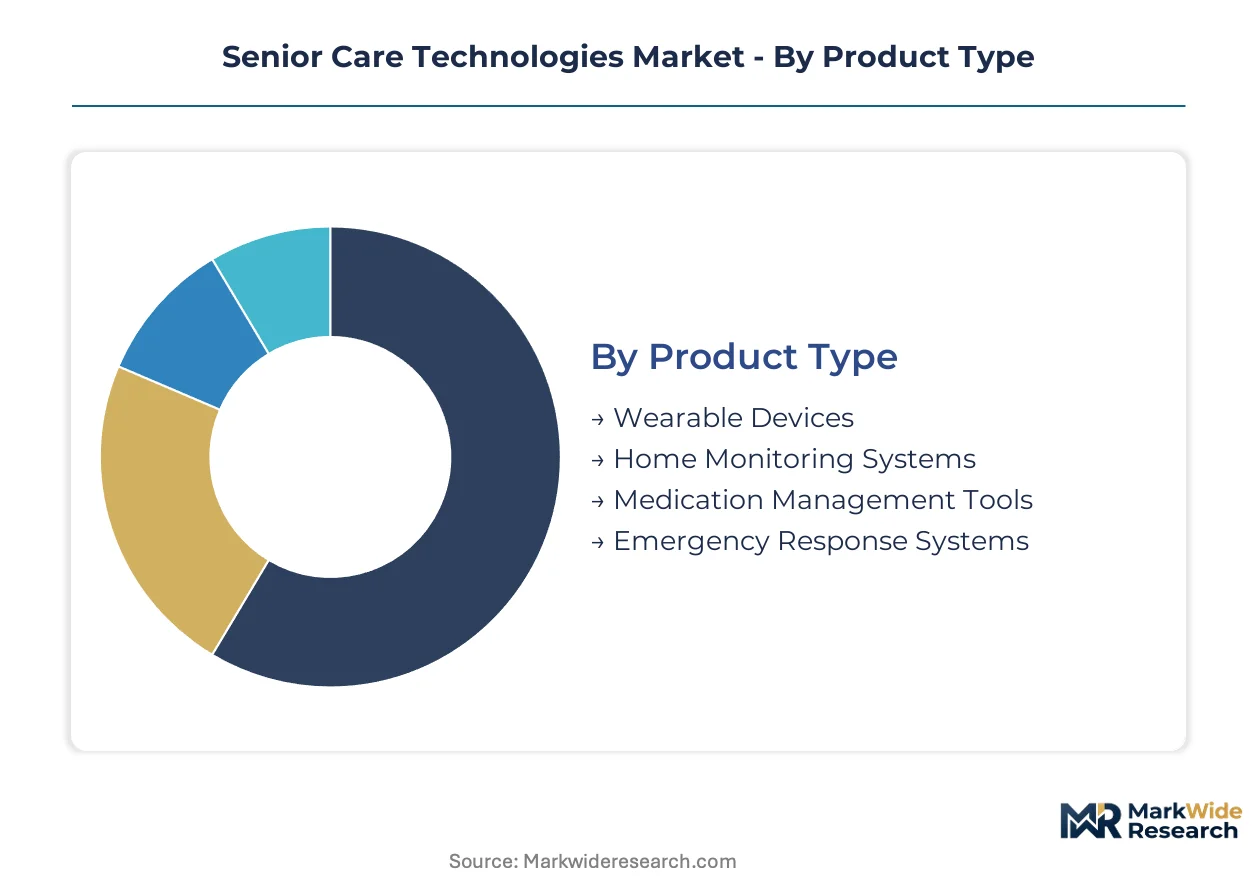
Segmentation in senior care technologies reveals divergent hardware replacement cycles, software subscription models, and procurement authority structures across product categories. Understanding these divisions clarifies where enterprise contracts concentrate versus where direct-to-consumer channels dominate.
Product Type:
Mature hardware segments with established reimbursement codes coexist alongside emerging ambient sensing platforms that eliminate device logistics entirely.
- Wearable Devices:Body-worn sensors capture continuous biometrics through accelerometers, optical heart rate monitors, and skin temperature sensors. Medicare Advantage networks in Florida and Arizona drive procurement volume for cellular-enabled fall detection pendants. CMS reimbursement codes for remote therapeutic monitoring accelerate provider willingness to subsidize device costs for enrolled seniors.
- Home Monitoring Systems:Fixed environmental sensors track motion patterns, sleep quality, and bathroom utilization through passive infrared and pressure mat arrays. Skilled nursing facility discharge planners in Texas and California specify these systems for hospital-to-home transitions. Installation complexity and WiFi dependency create friction in rural service territories.
- Medication Management Tools:Smart pill dispensers with cellular connectivity and adherence logging.
- Emergency Response Systems:Voice-activated wall units and mobile personal emergency response systems with GPS triangulation.
Wearable devices retain volume leadership; home monitoring systems hold the steepest expansion curve.
Technology:
Application intensity varies sharply across clinical versus wellness use cases, with regulatory clearance thresholds determining viable deployment settings.
- Telehealth Solutions:Synchronous video platforms and asynchronous store-and-forward systems enable remote clinical encounters between homebound seniors and specialty providers. Rural health clinics in Montana and North Dakota rely on these systems to extend geriatric psychiatry and cardiology access. Reimbursement parity laws in multiple states mandate equivalent payment for telehealth-delivered services.
- IoT Solutions:Cellular-enabled sensor networks transmit biometric and environmental data through low-power wide-area protocols. Home health agencies in Illinois and Ohio deploy these architectures to reduce emergency response latency for cardiac event detection. Edge computing modules process alerts locally before cloud transmission.
- Smart Home Technology:Voice assistants, automated lighting, and door lock systems adapted for aging-in-place safety.
- Artificial Intelligence:Predictive algorithms for fall risk stratification and medication interaction detection.
Telehealth solutions command the largest installed base; IoT solutions are climbing the fastest.
End User:
Procurement authority has migrated from individual consumers toward institutional purchasers with value-based care contracts.
- Home Health Agencies:Licensed Medicare-certified providers deploy connected monitoring platforms under multi-year enterprise agreements with data analytics subscriptions. These organizations in Pennsylvania and Michigan now specify interoperability requirements with existing electronic health record systems. Staffing shortages drive demand for automated alert triage to reduce nurse dashboard burden.
- Seniors Living Communities:Independent living and assisted living operators install ambient monitoring infrastructure across residential units. Large multi-state operators in the Sun Belt region negotiate direct vendor contracts that bypass traditional durable medical equipment distributors. Capital expenditure models shift toward subscription-based operational expenses.
- Family Caregivers:Adult children purchasing direct-to-consumer devices for remote monitoring of aging parents.
- Health Insurance Providers:Medicare Advantage plans and supplemental insurers subsidizing monitoring technology to reduce acute care utilization.
Home health agencies dominate contract value; seniors living communities are gaining share fastest.
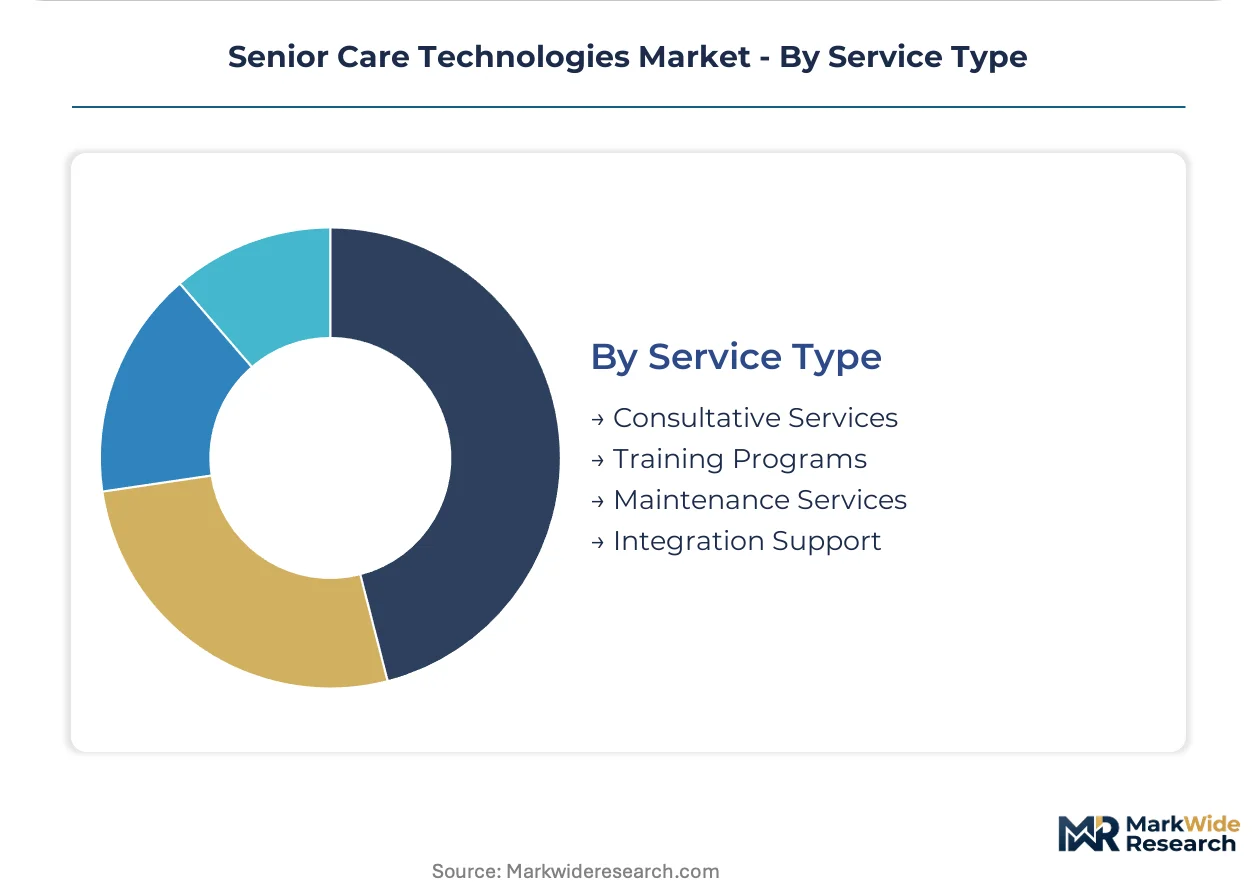
Service Type:
Revenue mix shifts from one-time implementation fees toward recurring support relationships as platform complexity increases.
- Integration Support:Technical services connecting monitoring platforms with health system electronic health records and health information exchanges. Hospital-at-home programs in New York and Massachusetts require these services for FDA 510(k)-cleared device validation. HL7 FHIR standard implementation gaps force custom interface development.
- Maintenance Services:Hardware replacement logistics, sensor calibration, and cellular connectivity troubleshooting. Home health agencies prioritize vendors with same-day device swap capabilities in metropolitan service areas. Subscription pricing bundles these services with software updates.
- Consultative Services:Workflow redesign and clinical protocol development for remote monitoring deployment.
- Training Programs:Staff education on alert response protocols and platform utilization.
Integration support captures the highest margin profile; maintenance services represent the largest revenue pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where Medicare reimbursement codes command premium subscription rates, while German vendors absorb EU MDR compliance costs that compress margins across continental Europe.
United States
Home health agencies in Florida and Arizona drive procurement volume for cellular-enabled fall detection systems. The FDA's digital health pre-certification pathway accelerates software-based medical device approvals for remote patient monitoring platforms. Hospital-at-home programs in New York and Massachusetts consolidate purchasing authority under health system supply chain officers, disintermediating traditional durable medical equipment distributors.
Germany
Skilled nursing facility operators in Bavaria and North Rhine-Westphalia specify ambient monitoring infrastructure for hospital-to-home transitions. The EU MDR imposes clinical evidence requirements for software updates that alter diagnostic algorithms in wearable devices. Berlin-based technology clusters develop dual quality management systems to serve transatlantic markets with segregated European product lines.
Japan
Metropolitan Tokyo and Osaka prefectures deploy passive radar monitoring systems that track respiration and gait without body-worn devices. METI guidelines on aging-in-place technology subsidies reduce capital expenditure barriers for seniors living communities. Kansai region health systems pilot edge-computing architectures that process cardiac event alerts locally before cloud transmission.
United Kingdom
NHS Integrated Care Systems in Greater London and the Midlands negotiate enterprise contracts for connected monitoring platforms with embedded HL7 FHIR interoperability. MHRA recognition of FDA 510(k) clearances streamlines market entry for US-based platform vendors. Manchester and Birmingham clusters focus on behavioral health integration modules for depression and anxiety monitoring within existing wearable form factors.
Canada
Provincial health authorities in Ontario and Quebec expand hospital-at-home waiver programs for acute-level care in residential settings. Health Canada's digital health guidance aligns with FDA pre-certification frameworks for software-as-medical-device claims. Toronto-based procurement consortia aggregate demand from home health agencies to secure multi-year enterprise service agreements with data analytics subscriptions.
Senior Care Technologies Market Competitive Environment
Post-acute software specialists and cloud-native platform vendors split the market along legacy integration versus modular agility lines. The vendor base concentrates around three strategic archetypes: electronic health record incumbents with skilled nursing facility dominance, home care scheduling specialists with cellular-enabled field operations, and hospital-to-home transition platforms with health system EHR interoperability. M&A activity targets workflow automation capabilities, while strategic partnerships with Medicare Advantage plans secure preferred vendor status for value-based care contracts.
Among North American platform vendors, WellSky leverages its post-acute software footprint to anchor hospital-to-home transitions, while PointClickCare exemplifies the EHR-incumbent archetype with skilled nursing facility market presence. AlayaCare occupies a position within the cloud-native tier, representing specialists in home care workforce management with cellular-enabled scheduling architectures.
| Leading Market Players |
|---|
| Eldermark |
| WellSky |
| DosePacker |
| PointClickCare |
| CareSmartz360 |
| MatrixCare |
| Yardi |
| AlayaCare |
| ALIS |
| Others |
Value Chain & Pricing Dynamics
Semiconductor supply concentration in East Asian foundries determines both tiered hardware pricing spreads and the contract-manufacturing footprint that senior care technology vendors must navigate. FDA pre-certification requirements and CMS reimbursement volatility amplify procurement risk for hardware-dependent monitoring platforms.
Pricing Analysis
Configured-to-order pricing for FDA 510(k)-cleared wearables commands substantial premiums over standard cellular-enabled pendants lacking clinical-grade certification. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native analytics subscriptions from basic device-only transactions. Cost compression in economy-tier hardware is intensifying because biometric sensor chip lead times stretch procurement cycles. Home health agencies exhibit lowest price sensitivity due to Medicare reimbursement coverage, while family caregivers in direct-to-consumer channels face full unsubsidized device costs.
Supply Chain Analysis
Contract manufacturing capacity for cellular-enabled sensors concentrates with Foxconn, Jabil, and Pegatron facilities across Taiwan, China, and Vietnam. Biometric chip fabrication draws from TSMC and Samsung foundries in Taiwan and South Korea, while lithium-ion battery cells source predominantly from CATL and LG Energy Solution plants in China and South Korea. Single-source vulnerability in advanced node semiconductor production exposes vendors to export control disruptions. Distribution runs through health system supply chain officers consolidating hospital-at-home procurement authority, disintermediating traditional durable medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The senior care technologies market functions as a service-attach opportunity where data analytics subscriptions expand faster than hardware replacement cycles. Recurring revenue from integration support and maintenance services now exceeds one-time device margins for platform vendors.
For Market Incumbents: Insulate installed base relationships by embedding quality management systems early in design cycles to accelerate FDA pre-certification timelines. Defend against cloud-native scheduling specialists by anchoring hospital-to-home transitions through EHR interoperability investments with health system supply chain officers. Deepen backward integration into cellular module sourcing to reduce exposure to East Asian foundry concentration. For New Entrants and Emerging Players: Establish a beachhead in behavioral health integration modules for depression and anxiety monitoring, the most penetrable clinical application within existing wearable form factors. Target rural health clinic telehealth extensions in Montana and North Dakota where reimbursement parity laws mandate equivalent payment for remote geriatric psychiatry access. Lead with caregiver marketplace features connecting family caregivers with professional home health aides as a differentiated go-to-market angle. For Investors and Strategic Acquirers: FDA digital health pre-certification pathway expansion reshapes the acquisition landscape toward vendors with embedded quality management systems and existing 510(k) clearances. Long-term viability centers on platforms capable of serving both Medicare fee-for-service and Medicare Advantage value-based care contracts. Target acquisition archetypes include workflow automation specialists with cellular-enabled field operations. The signal to monitor is CMS reimbursement code expansion for remote therapeutic monitoring services beyond current cardiopulmonary and musculoskeletal indications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates software-as-medical-device claims for remote patient monitoring platforms. |
| Hospital System Partnership | Secures preferred vendor status under health system supply chain consolidation for hospital-at-home programs. |
| Software Companion Development | Enables behavioral health integration modules for depression monitoring within wearable form factors. |
| Reimbursement Strategy | Aligns platform deployment with CMS remote therapeutic monitoring coverage determinations. |
| Platform Integration | Resolves HL7 FHIR interoperability gaps between skilled nursing facilities and home health platforms. |
Study Parameters
Operator-level perspectives from home health agency supply chain officers, skilled nursing facility discharge planners, Medicare Advantage plan contracting leads, and biomedical engineers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) clearance databases, CMS Medicare reimbursement code filings, hospital procurement contract registries, and health system EHR interoperability documentation. Bottom-up and top-down triangulation cross-checked vendor shipment data against institutional purchasing authority migration patterns.
Scenario-bracketing framed analytical outputs across the projection horizon, modeling baseline, upside, and stress trajectories for reimbursement policy shifts and semiconductor supply disruptions. Segmentation dimensions included product type, technology category, end-user procurement authority, and service revenue model. CAGRs derived from fitted growth curves applied to hardware replacement cycles and software subscription attach rates. Edge computing adoption curves and passive radar monitoring penetration served as technology-specific forecast inputs.
Stress conditions across CMS reimbursement code expansions, FDA pre-certification timeline variability, and East Asian foundry capacity utilization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Medicare Advantage value-based care contract proliferation and cellular infrastructure coverage gaps. Quarterly review of FDA digital health guidance updates and CMS national coverage determinations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
Clinical Perinatal Software Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Wearable Biosensors Market