
 Italy Cardiovascular Devices Market | 2026-2036
Italy Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Cardiovascular Devices Market Foresight
CE marking under the EU Medical Device Regulation (MDR) is bifurcating the competitive landscape between established manufacturers with notified body relationships and entrants facing extended conformity timelines. Medtronic PLC leverages its deep regulatory infrastructure and broad cath-lab installed base to sustain premium positioning across stent and pacemaker lines. Edwards Lifesciences differentiates through transcatheter valve specialization, anchoring high-acuity cardiac centers in Milan and Bologna. Abbott Laboratories competes on integrated diagnostic-interventional platforms, controlling workflow economics in major university hospitals.
Cardiovascular devices encompass implantable and interventional instruments designed to diagnose, monitor, or treat pathologies of the heart and vasculature, typically manufactured from biocompatible alloys, polymers, or biological tissues and subject to stringent sterility and fatigue-resistance specifications. Drug-eluting stents command the largest revenue pool within product type segments due to repeat intervention rates and premium pricing, while remote monitoring tools represent the fastest-expanding technology category as home-based cardiac surveillance gains reimbursement traction. Coronary artery disease applications dominate procedural volumes, though heart failure segments are attracting accelerated R&D investment from device developers seeking indication expansion.
Italy's Agenzia Italiana del Farmaco (AIFA) governs reimbursement and pricing negotiations for cardiovascular implants, while the EU MDR and CE marking framework administered through notified bodies determine market access eligibility for manufacturers. These regulatory layers shape product launch sequencing, with MDR transition deadlines compressing certification pipelines and AIFA regional tender processes concentrating purchasing power within large hospital consortia. Stakeholders must monitor evolving MDR guidance on legacy device recertification and AIFA real-world evidence requirements to anticipate competitive repositioning.
Market Dynamics
EU MDR recertification deadlines are compressing conformity assessment pipelines for legacy cardiovascular implants, forcing manufacturers to prioritize notified body capacity allocation and accelerating competitive consolidation among CE-marked device portfolios.
Growth Catalysts
- AIFA Reimbursement Acceleration:Italy's national pharmaceutical agency has streamlined coverage pathways for transcatheter valve therapies, expanding procedural volumes in high-acuity cardiac centers across Lombardy and Emilia-Romagna.
- Remote Monitoring Infrastructure:Home-based cardiac surveillance platforms are gaining traction as regional health authorities integrate telecardiology into chronic disease management protocols.
- Interventional Cardiology Expansion:Cath-lab networks in northern Italy hospital consortia are upgrading hemodynamic monitoring and imaging capabilities to support complex percutaneous coronary interventions.
Market Restraints
- Notified Body Bottleneck:EU MDR transition has concentrated conformity assessment capacity among a shrinking pool of designated bodies, extending certification timelines for novel stent and pacemaker submissions.
- Biocompatible Alloy Supply Concentration:Nitinol and cobalt-chromium feedstock for stent manufacturing depends on a limited supplier base in Germany and Switzerland, exposing device makers to input cost volatility.
- Structural Substitution Threat:Optimized medical therapy protocols for heart failure are displacing implantable cardioverter-defibrillator indications in selected patient cohorts.
Strategic Opportunities
- Underpenetrated Southern Regions:Cardiovascular device utilization in Calabria, Sicily, and Apulia lags northern benchmarks by procedural density, creating whitespace for cath-lab network development.
- Structural Heart Convergence:Integration of transcatheter mitral repair with advanced intracardiac echocardiography is opening hybrid procedure suites in Milan and Rome university hospitals.
- Regional Tender Consolidation:Large hospital purchasing consortia in Veneto and Tuscany are centralizing procurement, favoring integrated diagnostic-interventional platform vendors with comprehensive service contracts.
Industry Challenges
- Specialized Electrophysiology Talent Scarcity:Complex ablation and lead extraction procedures require operators with advanced fellowship training, constraining expansion of arrhythmia service lines outside major metropolitan centers.
- Legacy System Integration Friction:Next-generation hemodynamic monitoring platforms face interoperability barriers with existing cath-lab informatics architectures in aging hospital infrastructure.
- MDR Clinical Evidence Burden:Legacy device recertification demands expanded post-market surveillance data, straining regulatory affairs capacity and documentation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Cardiovascular Devices Market |
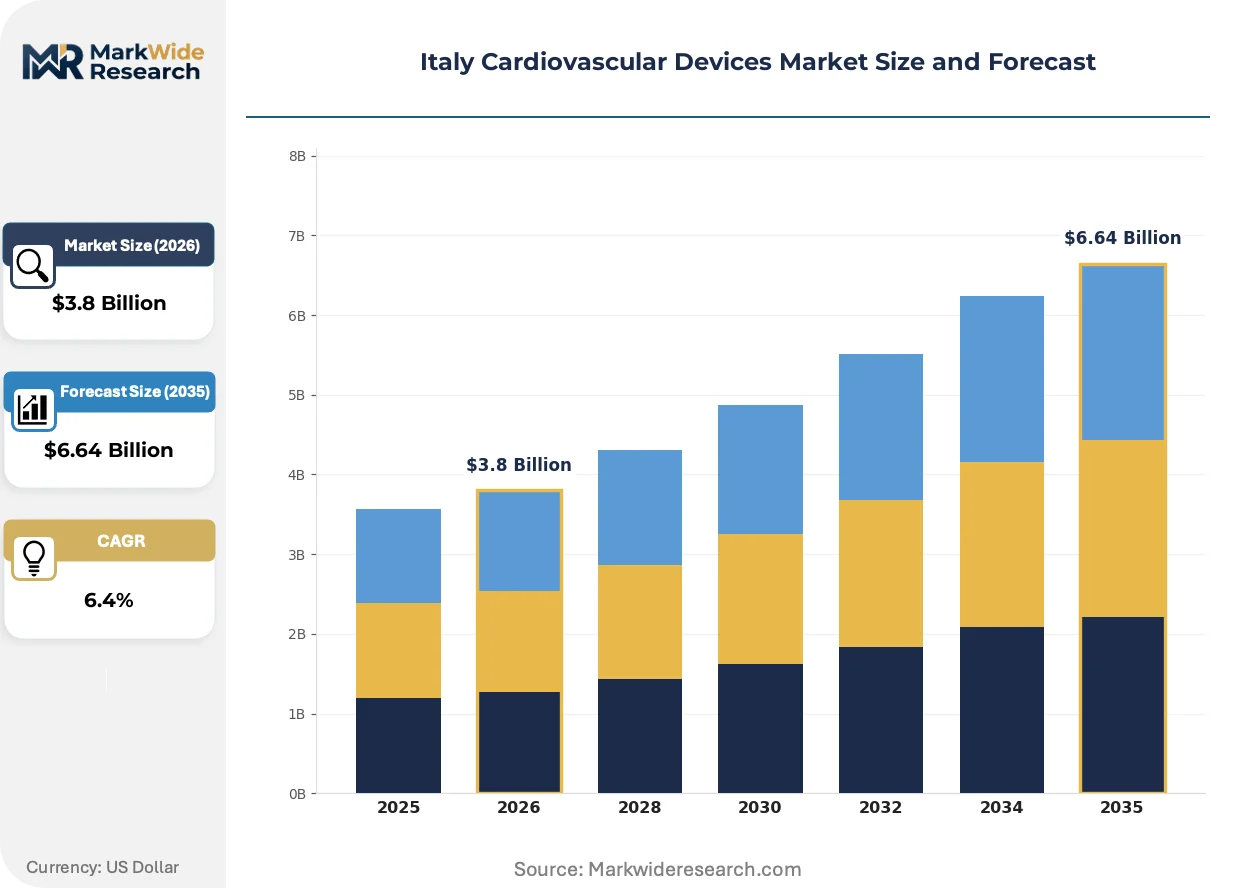
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Bypass Grafts Technology: Biodegradable Devices, Drug-Eluting Stents, MRI-Compatible Devices, Remote Monitoring Tools End User: Cardiology Clinics, Hospitals, Research Institutions, Home Care Settings Application: Coronary Artery Disease, Heart Failure, Arrhythmias, Valvular Heart Disease |
| Companies Covered | Medtronic PLC, Edwards Lifesciences, Abbott Laboratories, B. Braun Melsungen, Johnson & Johnson Services, Boston Scientific Corporation, Siemens Healthineers AG, Philips, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Cardiovascular Devices Market Shifts & Advancements
Digital catheterization laboratory ecosystems are reconfiguring workflow economics in Italian cardiac centers, while regulatory compression and procurement consolidation reshape how device manufacturers capture value across the interventional cardiology stack.
Bioresorbable vascular scaffolds are re-emerging as a focal technology for coronary intervention, with second-generation magnesium and polymer platforms demonstrating improved strut thickness and radial strength profiles. Academic medical centers in Bologna and Padua are piloting these devices in selected lesion subsets. The technology is bifurcating the stent market between durable polymer drug-eluting platforms and resorbable alternatives, with reimbursement uncertainty compressing near-term commercial traction for the latter category.
EU MDR recertification mandates are imposing stepped clinical evidence requirements on legacy implantable devices, forcing manufacturers to restructure post-market surveillance systems and notified body engagement strategies. The regulation is extending time-to-market for iterative product modifications and concentrating commercial resources on highest-revenue device families. Pacemaker and defibrillator portfolios face the most acute compliance timeline pressure, with MDR certificates of conformity expiring in staggered waves through 2027 and 2028.
Regional health authority tender processes are consolidating purchasing power within multi-hospital consortia, displacing single-site procurement autonomy. Device vendors are responding with outcome-guarantee frameworks and utilization-based pricing structures. This behavioral shift is most pronounced in Lombardy and Piedmont, where ATS (Aziende di Tutela della Salute) entities aggregate demand across provincial networks and negotiate multi-year supply agreements with performance metrics.
Italy Cardiovascular Devices Market Segmentation
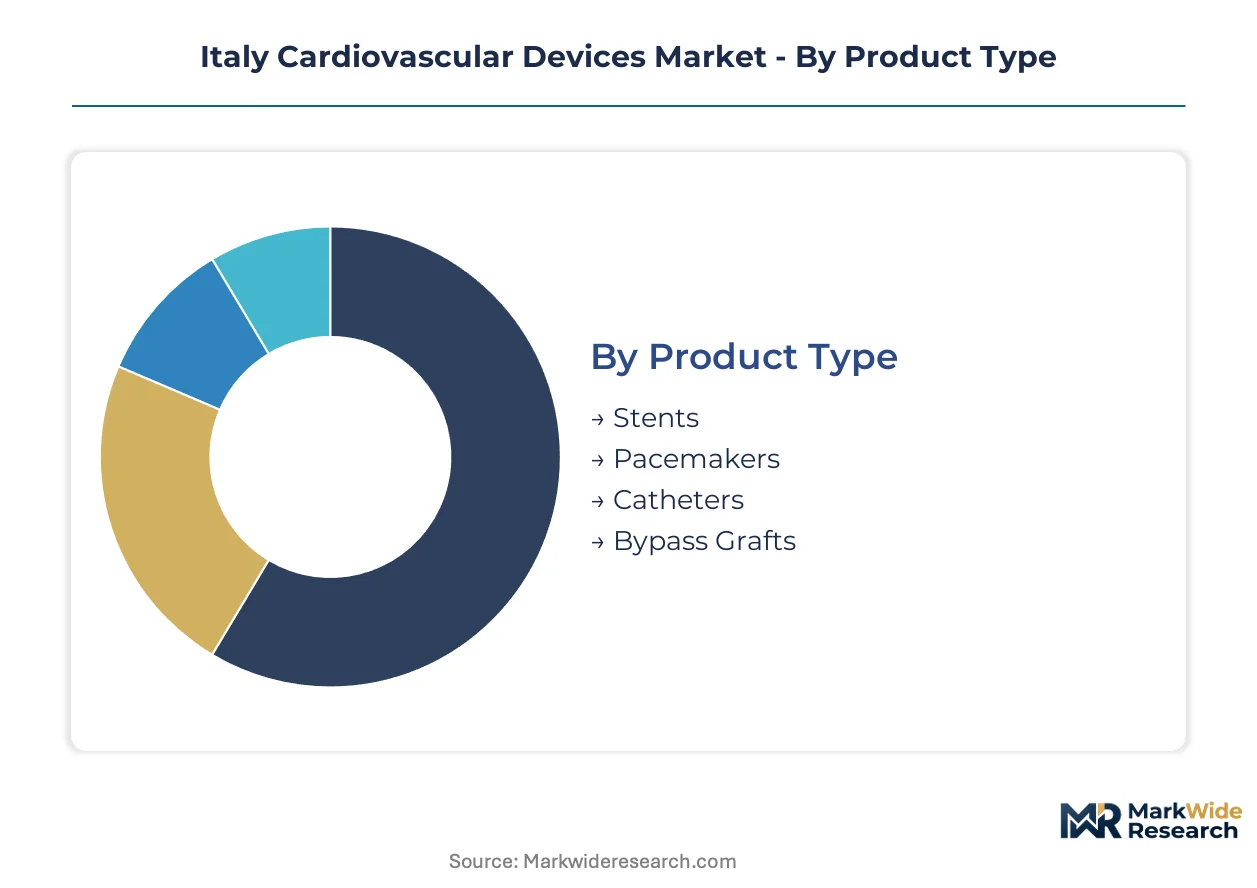
Segmentation in Italy's cardiovascular devices market reveals distinct margin architectures across product types and technologies, with reimbursement pathways and procedural complexity determining where manufacturers capture sustainable value. Understanding these segment boundaries enables targeted portfolio allocation and regional tender positioning.
Product Type:
Margin pools concentrate in implantable electrophysiology devices and coronary intervention platforms, where AIFA reimbursement premiums attach to innovation categories and procedural volume thresholds.
- Stents:Metallic or polymeric tubular scaffolds deployed percutaneously to restore coronary lumen patency, manufactured from cobalt-chromium or platinum-iridium alloys with polymer drug reservoirs. Demand clusters in Lombardy's high-volume cath-lab networks, where regional tender consolidation favors vendors with comprehensive DES portfolios and service infrastructure.
- Pacemakers:Battery-powered implantable pulse generators with transvenous leads for bradycardia management, increasingly specified with MRI-conditional shielding and wireless telemetry. Northern Italy hospital consortia drive procurement volumes as aging demographics expand device indication pools.
- Catheters:Diagnostic and interventional delivery systems for angiography, ablation, and hemodynamic monitoring.
- Bypass Grafts:Autologous vessel or synthetic conduit alternatives for coronary artery bypass procedures.
The dominant share belongs to Stents, while Pacemakers is closing the gap fastest.
Technology:
Technology differentiation separates premium reimbursement tiers from commodity positioning, with regulatory complexity and clinical evidence requirements scaling with innovation novelty.
- Biodegradable Devices:Magnesium-alloy or polymer-based vascular scaffolds engineered for complete metabolic resorption within 12-24 months post-implantation, eliminating long-term endothelial dysfunction risks. Academic medical centers in Bologna and Padua pilot these platforms in selected lesion subsets, though AIFA coverage uncertainty constrains commercial traction.
- Drug-Eluting Stents:Polymer-coated metallic platforms delivering antiproliferative agents to inhibit neointimal hyperplasia, commanding the largest revenue pool within coronary intervention. Milan and Turin cardiac centers sustain utilization volumes through established operator familiarity and supply chain integration.
- MRI-Compatible Devices:Ferromagnetic-shielded pacemakers and ICDs enabling safe magnetic resonance imaging post-implantation.
- Remote Monitoring Tools:Cloud-connected implantable sensors and external wearables for ambulatory cardiac surveillance.
Drug-Eluting Stents retains volume leadership, though Remote Monitoring Tools is expanding most quickly as regional health authorities integrate telecardiology protocols.
End User:
Procurement authority and technical sophistication vary sharply across care settings, with university-affiliated centers driving technology adoption curves.
- Cardiology Clinics:Outpatient facilities performing diagnostic catheterization and device follow-up, concentrated in Emilia-Romagna's dense specialist networks. These settings prioritize workflow efficiency and integrated diagnostic platforms.
- Hospitals:Acute care institutions with full interventional capabilities and hybrid operating suites. Lombardy's ATS consortia aggregate demand across provincial networks, concentrating purchasing power and favoring vendors with multi-year service contracts.
- Research Institutions:Academic medical centers conducting clinical trials and first-in-human device evaluations.
- Home Care Settings:Ambulatory environments for post-acute monitoring and chronic disease management.
Hospitals command the dominant procurement volume, while Home Care Settings is gaining share fastest through telecardiology reimbursement expansion.
Application:
Indication severity and intervention invasiveness shape device selection criteria, with structural heart procedures attracting accelerated manufacturer investment.
- Coronary Artery Disease:Atherosclerotic luminal narrowing requiring revascularization through stent deployment or bypass grafting, representing the foundational procedural volume for Italian interventional cardiology. Northern regional health authorities sustain high per-capita intervention rates through established cath-lab infrastructure.
- Heart Failure:Progressive ventricular dysfunction managed through CRT devices, LVADs, or transcatheter mitral interventions. Milan and Rome university hospitals anchor specialist referral networks for advanced device therapy.
- Arrhythmias:Electrical conduction disorders treated through ablation or implantable rhythm management devices.
- Valvular Heart Disease:Structural valve dysfunction addressed through surgical replacement or transcatheter repair.
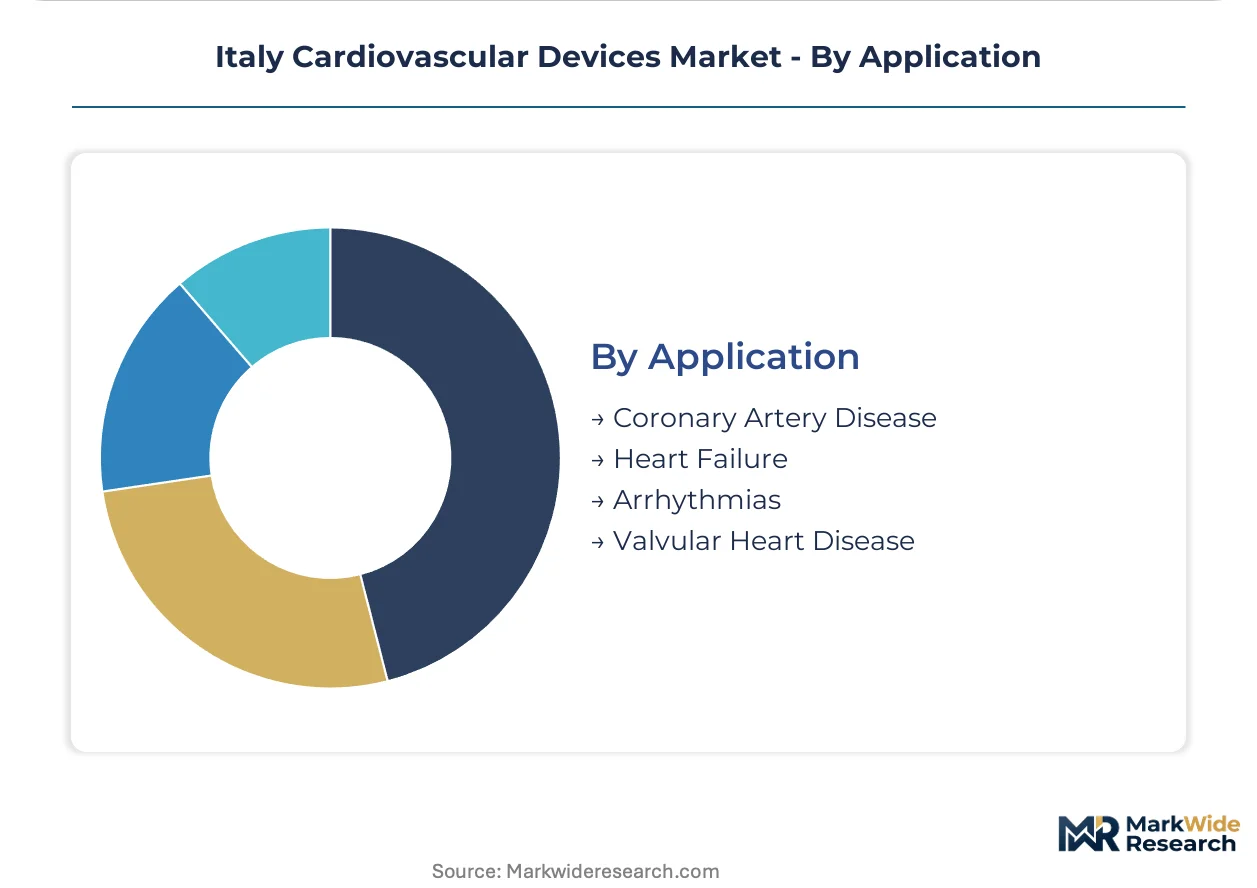
Coronary Artery Disease maintains the largest procedural base, while Heart Failure is climbing the fastest as transcatheter therapies expand indication boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital purchasing consortia and cath-lab network density concentrate device procurement across northern Italian regions, with AIFA regional tender frameworks amplifying buyer leverage in high-volume provinces.
Lombardy
Milan's ATS consortia aggregate demand across provincial hospital networks, driving multi-year supply agreements for drug-eluting stents and pacemaker portfolios. AIFA regional tender processes concentrate purchasing authority within large consortia, compressing vendor margins. The city's university hospitals anchor specialist referral networks for transcatheter valve therapies, sustaining premium device utilization.
Emilia-Romagna
Bologna and Modena cardiac centers sustain high procedural volumes for coronary interventions, with regional health authorities integrating telecardiology into chronic disease protocols. EU MDR recertification deadlines shape device launch sequencing for manufacturers serving this cluster. Academic medical centers in Padua pilot bioresorbable vascular scaffolds in selected lesion subsets.
Veneto
Verona and Vicenza hospital networks upgrade hemodynamic monitoring capabilities to support complex percutaneous coronary interventions. Regional tender consolidation favors integrated diagnostic-interventional platform vendors with comprehensive service contracts. The province's aging demographics expand indication pools for implantable rhythm management devices.
Piedmont
Turin anchors northwestern Italy's interventional cardiology infrastructure, with ATS entities negotiating outcome-guarantee frameworks and utilization-based pricing structures. Biocompatible alloy supply concentration from German and Swiss feedstock sources exposes device makers to input cost volatility. Cath-lab networks prioritize workflow efficiency and integrated diagnostic platforms.
Lazio
Rome university hospitals develop hybrid procedure suites combining transcatheter mitral repair with advanced intracardiac echocardiography. Specialized electrophysiology talent scarcity constrains arrhythmia service line expansion outside the metropolitan center. Legacy system integration friction challenges next-generation hemodynamic monitoring platform deployment in aging hospital infrastructure.
Italy Cardiovascular Devices Market Competitive Landscape
Player mix skews toward diversified multinationals with deep regulatory infrastructure and integrated platform capabilities. CE marking under EU MDR bifurcates the competitive landscape between established manufacturers with notified body relationships and entrants facing extended conformity timelines. Strategic archetypes include full-stack platform vendors controlling workflow economics, transcatheter valve specialists anchoring high-acuity centers, and diagnostic-imaging integrators capturing cath-lab informatics spend. Dominant competitive moves center on MDR recertification capacity allocation and multi-year service contract negotiation with regional purchasing consortia.
Among diversified medical technology conglomerates, Medtronic PLC, Abbott Laboratories, and Edwards Lifesciences occupy positions reflecting distinct competitive vectors. Medtronic exemplifies the full-stack platform archetype with broad cath-lab installed base penetration. Abbott represents the diagnostic-interventional integration model favored by university hospital procurement committees. Edwards occupies a specialization position in structural heart therapies, anchoring high-acuity cardiac centers in Milan and Bologna through transcatheter valve expertise.
| Leading Market Players |
|---|
| Medtronic PLC |
| Edwards Lifesciences |
| Abbott Laboratories |
| B. Braun Melsungen |
| Johnson & Johnson Services |
| Boston Scientific Corporation |
| Siemens Healthineers AG |
| Philips |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Cath-lab network scale economies in Lombardy and Emilia-Romagna compress unit procurement costs while elevating minimum viable service thresholds for device vendors, concentrating price-setting power within ATS purchasing consortia and tethering margin sustainability to multi-year contract performance guarantees.
Pricing Analysis
Cost-plus contracts with German and Swiss nitinol indexation dominate stent procurement, with AIFA regional tenders imposing utilization-based pricing floors. Three-tier pricing structure across premium DES, standard bare-metal, and economy catheter platforms separates Milan university hospitals from provincial facilities. Price erosion runs through economy tiers as ATS consortia consolidate volumes, while premium transcatheter valve segments resist compression due to operator training scarcity. Cardiology clinics in Emilia-Romagna exhibit highest price sensitivity; Milan cardiac centers least.
Supply Chain Analysis
Germany and Switzerland anchor cobalt-chromium and nitinol feedstock production for Italian stent manufacturing, with polymer drug reservoirs sourced from Netherlands specialty chemical producers. Raw material dependencies center on ferromagnetic alloys, antiproliferative pharmaceutical coatings, and sterile packaging films. Single-source vulnerability concentrates in German nitinol suppliers serving Medtronic and Abbott production lines. Distribution runs through regional hospital consortia with just-in-time cath-lab inventory systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
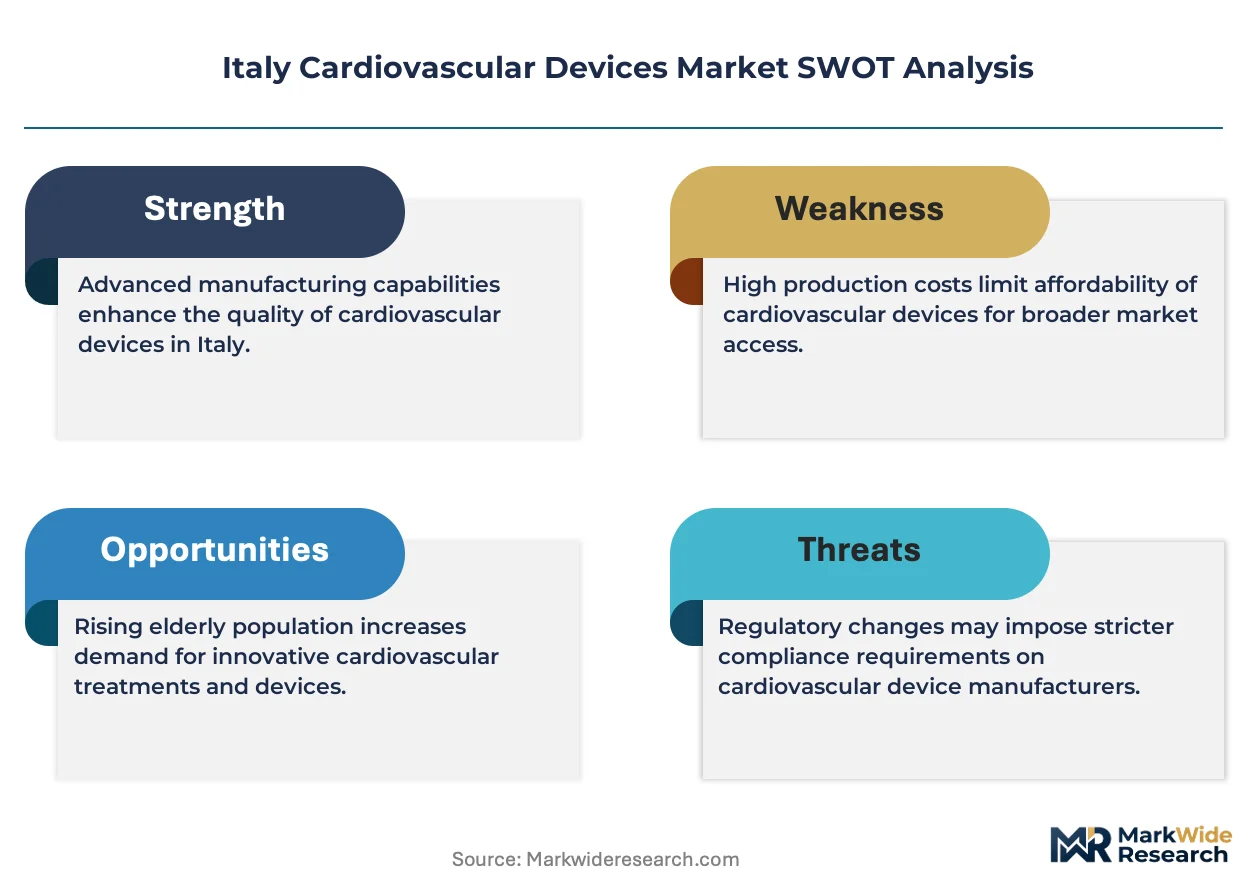
Device incumbents face structural substitution from optimized medical therapy protocols displacing ICD indications in heart failure cohorts, requiring defensive portfolio repositioning around irreplaceable interventional procedures.
For Market Incumbents: Shield pacemaker and defibrillator revenue pools through accelerated MRI-conditional platform transitions ahead of MDR recertification waves. Secure notified body capacity allocation for legacy device recertification to block entrant certification timelines. Vertical integration into cobalt-chromium feedstock through Swiss supplier partnerships mitigates input cost volatility threatening DES margins. For New Entrants and Emerging Players: Differentiate on remote monitoring platform integration with AIFA telecardiology reimbursement pathways. Target underpenetrated cath-lab development in Calabria and Sicily where procedural density lags northern benchmarks by forty percent. Anchor initial commercial traction through university hospital pilot contracts in Rome hybrid suite environments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors transcatheter valve specialists with established Milan-Bologna clinical anchoring over diversified commodity device portfolios. Long-term viability hinges on MDR regulatory infrastructure depth and AIFA real-world evidence generation capabilities. Watch for notified body designation expansions as inflection signal for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR recertification capacity allocation determines competitive access timelines for legacy portfolios. |
| Hospital System Partnership | Multi-year ATS consortia agreements in Lombardy lock in cath-lab installed base positions. |
| Reimbursement Strategy | AIFA transcatheter valve coverage expansion directly enables procedural volume growth in high-acuity centers. |
| Software Companion Development | Remote monitoring platform integration captures telecardiology infrastructure spend across regional health authorities. |
| Backward Integration | Cobalt-chromium feedstock control through Swiss supplier relationships insulates DES manufacturing from alloy price volatility. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with cath-lab directors, AIFA reimbursement specialists, biomedical engineers, and GPO contracts managers; and secondary validation against EU MDR guidance documents, AIFA pricing bulletins, hospital procurement databases, and notified body designation records. Bottom-up device shipment estimates triangulated against top-down AIFA expenditure flows.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, technology tier, end-user setting, and application severity. CAGRs derived from procedural volume trajectories indexed to regional demographic aging patterns and cath-lab network expansion plans. Forecast inputs incorporated MDR recertification timeline assumptions and AIFA real-world evidence requirement evolution.
The analysis sits within stated boundaries; outcomes outside sustained AIFA reimbursement acceleration or notified body capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding procedural adoption curves and supply chain input cost stability. Recalibration cycles align with material shifts in MDR implementation guidance and regional tender consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Umbilical Vessel Catheters Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Wearable Artificial Organs Market