
 Umbilical Vessel Catheters Market | 2026-2036
Umbilical Vessel Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Umbilical Vessel Catheters Market Analytics
Hospital procurement of umbilical vessel catheters is tilting toward consolidated group purchasing organizations and direct manufacturer contracts. Cardinal Health leverages its distribution scale to secure multi-year supply agreements with integrated health networks. Utah Medical Products anchors its position through specialized neonatal device manufacturing and stringent quality protocols. Teleflex competes by extending its vascular access portfolio into low-birth-weight infant applications.
Umbilical vessel catheters are sterile, flexible tubes inserted into the umbilical artery or vein of neonates to provide vascular access, typically manufactured from polyurethane or silicone with French sizes ranging from 3.5F to 5.0F depending on infant weight. Double-lumen configurations dominate current procurement as they permit simultaneous blood sampling and fluid infusion, reducing the need for multiple access points. Neonatal intensive care units represent the deepest margin pool given their high acuity, standardized protocols, and recurring replacement cycles driven by infection control mandates. Fluid therapy and medication administration applications are expanding fastest as premature birth rates sustain demand for parenteral nutrition and inotropic support in critical early hours.
FDA premarket notification requirements and CE marking under the EU MDR shape product development timelines, material biocompatibility testing, and clinical evidence thresholds for market entry. ISO 80369 small-bore connector standards and Joint Commission neonatal care guidelines further constrain design choices and interoperability requirements. Stakeholders must monitor regulatory divergence between FDA and notified body interpretations of neonatal device risk classification to anticipate submission burdens and competitive entry timing.
Market Dynamics
Hospital procurement consolidation through group purchasing organizations is compressing margins and forcing manufacturers toward direct contracting models with integrated delivery networks.
Growth Catalysts
- Level IV NICU expansion:Academic medical centers in the United States are building specialized neonatal units that standardize umbilical catheter protocols and drive recurring replacement volume through infection control mandates.
- EU MDR implementation:Stricter clinical evidence requirements for neonatal vascular devices under the Medical Device Regulation are filtering out marginal competitors and concentrating procurement among qualified suppliers.
- Polyurethane material advances:Improved biocompatibility and kink resistance in catheter polymers are extending dwell times and reducing complication rates in premature infant populations.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply chains cluster among specialty chemical producers in Germany and Japan, exposing manufacturers to input volatility and qualification delays.
- FDA premarket notification burden:The 510(k) pathway for neonatal vascular devices demands extensive biocompatibility testing and predicate device comparisons that extend development timelines by 12-18 months.
- Peripheral catheter substitution:Advances in peripherally inserted central catheters for neonates are capturing low-acuity cases that previously defaulted to umbilical access.
Strategic Opportunities
- India NICU infrastructure buildout:Government-funded neonatal care expansion under the National Health Mission is creating first-mover advantages for catheter suppliers establishing local distribution.
- Antimicrobial coating convergence:Integration of silver-ion and chlorhexidine technologies with standard polyurethane substrates offers premium positioning against commodity catheters.
- Direct-to-hospital e-procurement:Specialized medical device marketplaces are bypassing traditional distributor markups and capturing preference share among independent community hospitals.
Industry Challenges
- Neonatal device specialization gap:Clinical engineering teams lack dedicated training in umbilical catheter placement and maintenance, increasing facility reliance on manufacturer field support.
- ISO 80369-3 compliance complexity:Small-bore connector standardization requires redesign of legacy catheter hubs and mating infusion sets, forcing parallel inventory management during transition periods.
- Joint Commission survey readiness:Unannounced accreditation inspections demand continuous documentation of catheter insertion protocols and complication tracking that strains quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Umbilical Vessel Catheters Market |
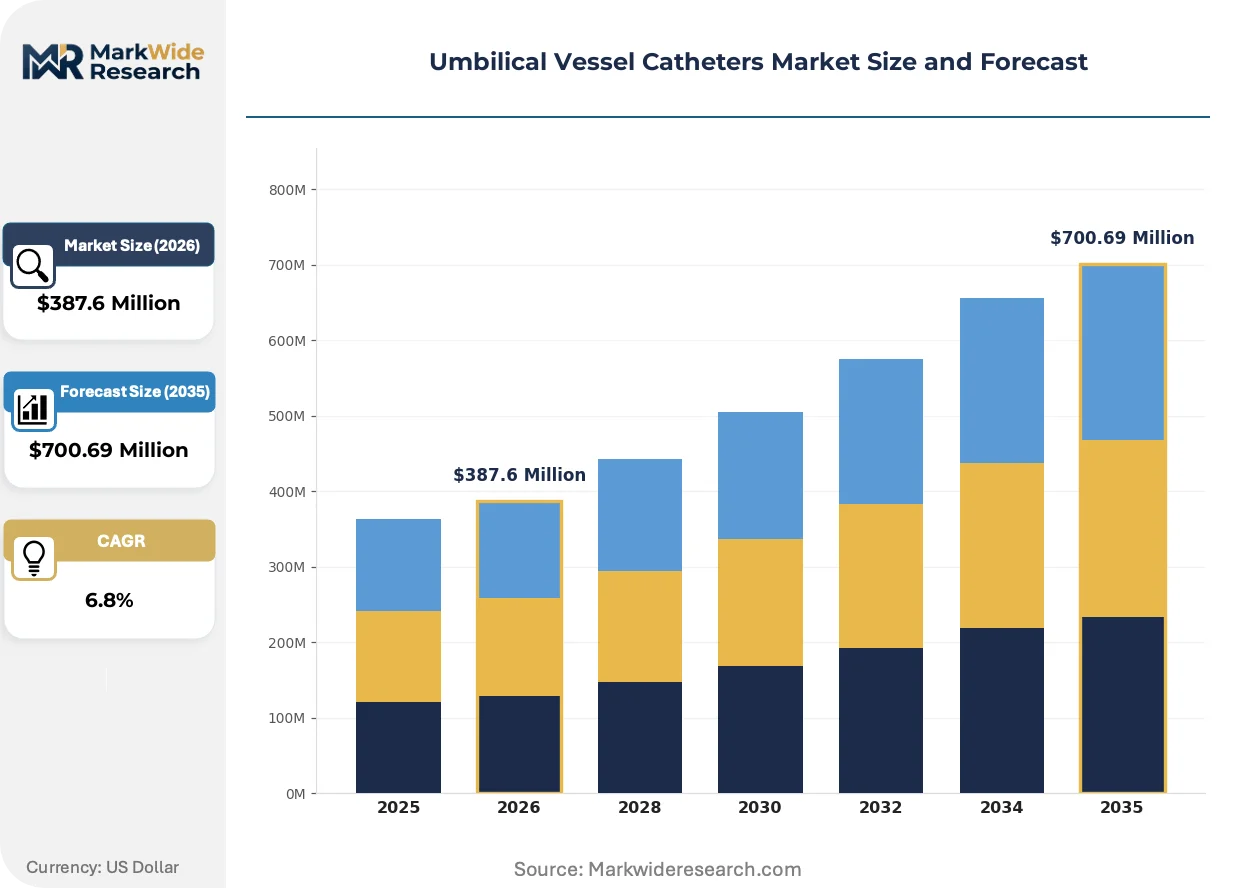
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen, Double-Lumen, Triple-Lumen, Microcatheters End User: Neonatal Intensive Care Units, Pediatric Hospitals, Home Care Settings, Ambulatory Surgical Centers Material: Polyvinyl Chloride, Polyurethane, Silicone, Biocompatible Polymers Application: Fluid Therapy, Blood Sampling, Medication Administration, Vascular Access |
| Companies Covered | Cardinal Health, Vygon SA, Utah Medical Products, Sterimed Group, Angiplast Pvt Ltd, Medline Industries, Teleflex, GPC Medical Ltd, Neotech Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Umbilical Vessel Catheters Market Evolving Landscape
Catheter technology is converging with antimicrobial surface engineering and digital placement guidance systems that reshape clinical workflows and procurement criteria simultaneously.
Silicone-polyurethane composite catheter construction is hybridizing material properties to balance flexibility with tensile strength for low-birth-weight infants. Level IV NICU specialists are adopting these dual-material designs fastest, replacing single-polymer legacy stock. The hybridization is compressing the premium tier by collapsing the performance gap between specialty and standard catheters.
CE marking under the EU MDR now requires post-market clinical follow-up studies for all neonatal vascular access devices. Manufacturers must maintain active surveillance registries tracking thrombosis and infection outcomes. European notified bodies are interpreting risk classification more stringently than FDA, delaying market entry for novel catheter designs by six to nine months.
Consolidated buying committees are displacing individual clinician preference in catheter selection across US health systems. Standardized formulary decisions now flow through value analysis committees that weigh total cost of care against device price. This behavioral shift is most visible in the Northeast, where Catholic health networks and academic consortia have centralized neonatal supply contracts.
Umbilical Vessel Catheters Market Segmentation
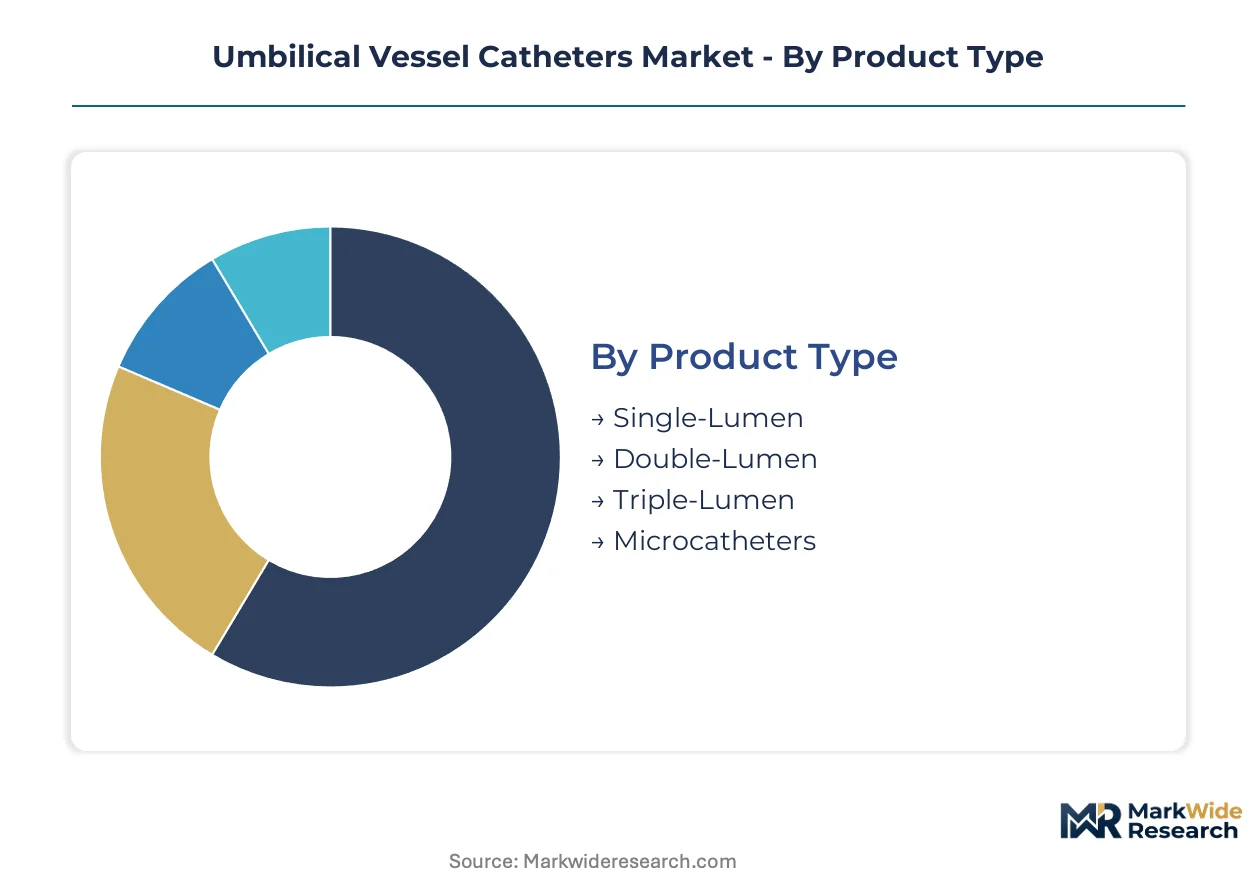
Segmentation in umbilical vessel catheters reveals how procurement priorities diverge between high-acuity NICU environments and lower-intensity care settings. Replacement cycles, material qualification burdens, and application-specific performance requirements create distinct margin pools across each dimension.
Product Type:
Double-lumen configurations turn over fastest due to infection control mandates and thrombosis protocols, while microcatheters for extremely low birth weight infants cycle slowest given specialized inventory management.
- Double-Lumen:Simultaneous blood sampling and fluid infusion capability reduces multiple access points in critical neonates. Demand concentrates in United States Level IV NICUs where standardized protocols mandate replacement every 5-7 days. FDA 510(k) predicates for dual-lumen designs are well-established, accelerating supplier qualification.
- Single-Lumen:Lower cost position suits shorter-dwell applications and resource-constrained settings. Procurement in Indian government hospitals under National Health Mission expansion favors this tier for initial NICU stocking.
- Triple-Lumen:Reserved for the most complex neonatal cases requiring simultaneous medication, nutrition, and monitoring access. Limited adoption outside academic medical centers due to insertion complexity.
- Microcatheters:Sub-3.0 French designs for infants under 800 grams. Japanese and German neonatal specialists drive specification development through ISO 80369-3 small-bore connector working groups.
Double-lumen designs dominate installed base. Microcatheters are where expansion concentrates.
End User:
Procurement authority and volume scale separate institutional buyers from distributed channels, with cost tier becoming the decisive structural angle.
- Neonatal Intensive Care Units:Deep acuity and standardized protocols generate recurring replacement demand. United States academic medical centers anchor premium pricing through value analysis committees that weigh total cost of care against device acquisition cost.
- Pediatric Hospitals:Broader service mix dilutes catheter specialization. European pediatric networks under EU MDR clinical evidence requirements are consolidating supplier lists to reduce notified body audit burden.
- Home Care Settings:Emerging segment for stable neonates transitioning from hospital. Reimbursement complexity and caregiver training gaps constrain near-term volume.
- Ambulatory Surgical Centers:Minimal penetration given procedural focus and lack of overnight neonatal monitoring capability.
NICUs command pricing power through volume concentration. Pediatric hospitals are where supplier consolidation accelerates.
Material:
Volume and supply concentration define competitive dynamics, with polyurethane outpacing alternatives in procurement velocity.
- Polyurethane:Kink resistance and tensile strength balance suits premature infant vascular fragility. German specialty chemical producers supply medical-grade feedstock, creating qualification delays for new catheter manufacturers.
- Silicone:Superior biocompatibility and flexibility for extended dwell applications. Raw material concentration among Japanese and German producers exposes supply chains to input volatility.
- Polyvinyl Chloride:Cost-driven selection in emerging market procurement. Phthalate plasticizer concerns under EU REACH regulations are displacing this material in European neonatal devices.
- Biocompatible Polymers:Antimicrobial-integrated and drug-eluting surfaces under development. FDA premarket notification timelines of 12-18 months slow commercialization.
Polyurethane holds installed base leadership. Biocompatible polymers are climbing the fastest.
Application:
Customer type and clinical workflow integration determine which applications capture procurement preference.
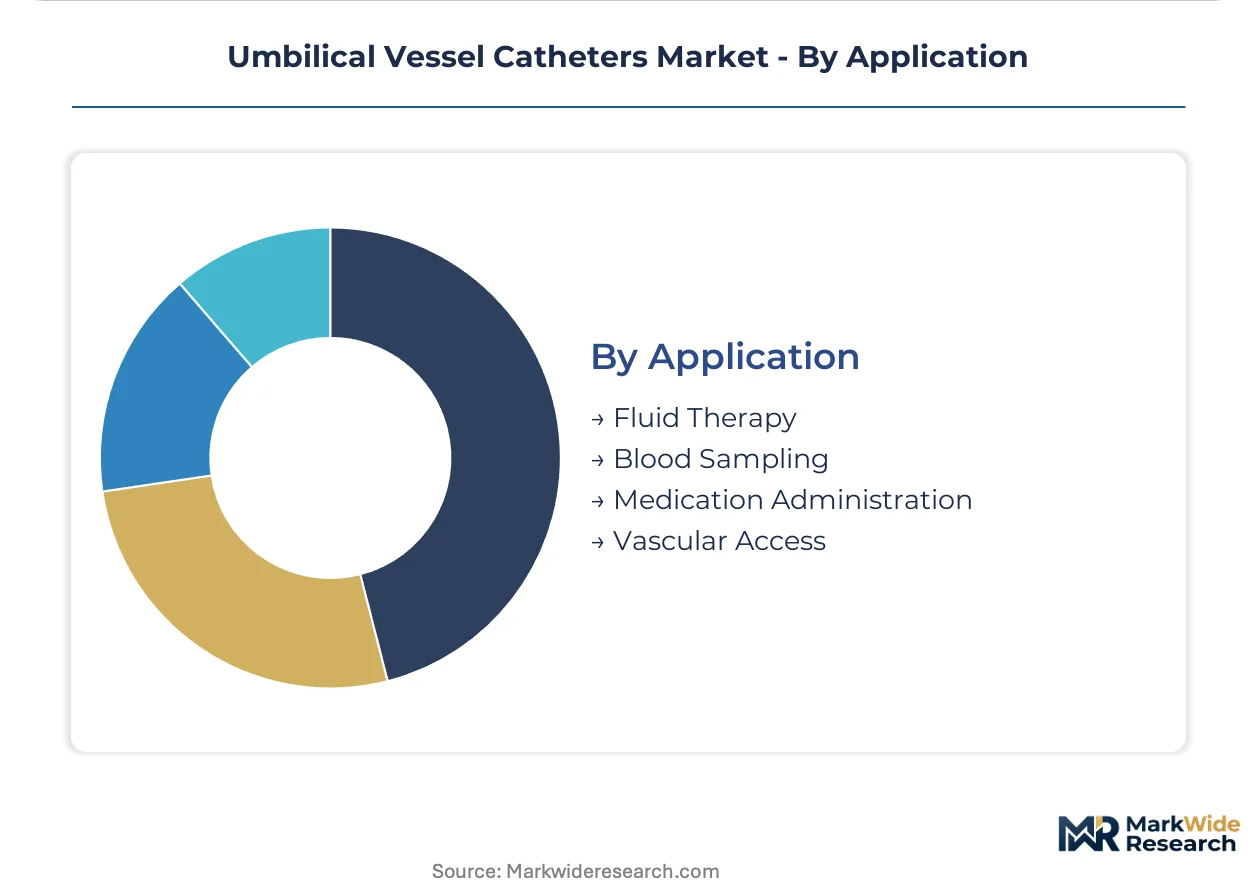
- Medication Administration:Inotropic support and parenteral nutrition in critical early hours demand reliable vascular access. United States Level IV NICUs standardize double-lumen protocols for this application.
- Fluid Therapy:Volume resuscitation and electrolyte management in premature infants. Expansion tracks premature birth rate sustainment across developed healthcare systems.
- Blood Sampling:Repeated arterial access for blood gas monitoring reduces peripheral puncture trauma. Integration with closed-system sampling devices is displacing open-collection methods.
- Vascular Access:General-purpose category capturing mixed-use catheters. Peripheral catheter substitution in low-acuity cases is compressing this segment's expansion trajectory.
Medication administration anchors current procurement volume. Fluid therapy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification requirements anchor the United States as the dominant geography, while EU MDR implementation and National Health Mission expansion in India reshape competitive entry patterns across developed and emerging healthcare systems.
United States
Level IV NICU networks at academic medical centers in Boston, Philadelphia, and Houston drive standardized procurement protocols with 5-7 day replacement cycles. FDA 510(k) pathways for neonatal vascular devices demand extensive biocompatibility testing that extends development timelines. The Northeast corridor concentrates Catholic health networks and academic consortia that have centralized neonatal supply contracts through value analysis committees.
Germany
Specialty chemical producers in the Rhine-Ruhr and Bavaria regions supply medical-grade polyurethane and silicone feedstock, creating qualification bottlenecks for new catheter manufacturers. EU MDR notified bodies in Berlin and Munich interpret neonatal device risk classification more stringently than FDA counterparts. ISO 80369-3 small-bore connector standardization working groups operate from Frankfurt, shaping interoperability requirements for European procurement.
India
Government-funded NICU infrastructure buildout under the National Health Mission creates first-mover advantages for suppliers establishing local distribution in Maharashtra and Karnataka. CDSCO medical device regulations are converging with international standards, though state-level implementation varies. Delhi-NCR and Chennai anchor private hospital chains that are adopting double-lumen protocols faster than government facilities.
Japan
PMDA post-market surveillance requirements for neonatal devices maintain high clinical evidence thresholds that filter marginal competitors. Medical-grade silicone supply chains cluster among specialty producers in Osaka and Nagoya, exposing manufacturers to input volatility. Tokyo metropolitan hospitals lead specification development for sub-3.0 French microcatheters through METI-funded research consortia.
United Kingdom
NHS England specialized neonatal care networks standardize catheter protocols across 44 operational delivery networks, concentrating procurement volume. MHRA convergence with EU MDR technical standards maintains regulatory alignment post-Brexit. London and Manchester academic medical centers drive adoption of antimicrobial-integrated catheter surfaces through NICE technology appraisal pathways.
Umbilical Vessel Catheters Market Competitive Landscape
Integrated health network suppliers and specialized neonatal device manufacturers split the market along procurement channel lines. Hospital consolidation through group purchasing organizations compresses margins and forces direct contracting models. Three archetypes dominate: distribution-scale incumbents securing multi-year supply agreements, specialized manufacturers anchoring positions through quality protocols, and vascular access portfolio extenders targeting low-birth-weight applications. Competitive moves concentrate on antimicrobial coating integration and e-procurement platform development.
Among distribution-scale incumbents, Cardinal Health exemplifies the archetype of consolidated supply agreements with integrated delivery networks. Utah Medical Products occupies a specialist position within neonatal device manufacturing, while Teleflex sits within the vascular access portfolio extension tier. Vygon SA and Medline Industries represent European and North American mid-scale fabricators respectively. Sterimed Group, Angiplast Pvt Ltd, GPC Medical Ltd, and Neotech Products anchor emerging market and regional specialist positions.
| Leading Market Players |
|---|
| Cardinal Health |
| Vygon SA |
| Utah Medical Products |
| Sterimed Group |
| Angiplast Pvt Ltd |
| Medline Industries |
| Teleflex |
| GPC Medical Ltd |
| Neotech Products |
| Others |
Value Network & Pricing Analysis
Rhine-Ruhr specialty chemical clusters in Germany anchor medical-grade polyurethane feedstock capacity, concentrating pricing leverage among qualified catheter manufacturers while downstream hospital procurement consolidation squeezes margin capture. FDA 510(k) biocompatibility testing burdens and EU MDR clinical evidence requirements stratify pricing tiers by certification investment depth, with antimicrobial-coated configurations commanding premium positioning against commodity single-lumen alternatives.
Pricing Analysis
United States academic medical centers pay 15-25% premiums over Indian government hospital procurement for identical double-lumen configurations, reflecting value analysis committee total-cost-of-care weighting against device acquisition price. Three-tier pricing structure across antimicrobial-integrated premium, standard polyurethane, and economy PVC levels segments buyer archetypes by infection control protocol stringency. Cost compression in the economy tier intensifies as National Health Mission expansion in India concentrates volume tenders on single-lumen specifications. Community hospitals and independent NICUs exhibit highest price sensitivity, while Level IV academic centers prioritize dwell-time performance and complication reduction over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk planning for polyurethane feedstock-dependent manufacturers. Medical-grade silicone concentrates among Osaka and Nagoya specialty producers in Japan, while polyurethane resin production clusters in the Rhine-Ruhr and Bavaria regions of Germany. Raw material qualification timelines for new catheter entrants hinge on ISO 10993 biocompatibility testing and FDA master file cross-referencing. Single-source vulnerability in silicone supply exposes manufacturers to input volatility during pharmaceutical-grade chemical allocation periods. Distribution runs through Cardinal Health and Medline Industries warehouse networks to integrated delivery networks, with direct manufacturer contracting displacing traditional distributor markups in consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peripherally inserted central catheters for neonates threaten umbilical vessel catheter incumbents by capturing low-acuity cases that previously defaulted to umbilical access, forcing defensive innovation in antimicrobial surface engineering and placement guidance integration.
For Market Incumbents: Insulate premium positioning by backward integration into medical-grade polyurethane compounding and captive supply of antimicrobial coating substrates. Secure multi-year sole-source agreements with Level IV NICU networks before EU MDR post-market surveillance registries consolidate supplier lists. Peripheral catheter substitution in sub-1,500 gram infants represents the most acute substitution threat requiring dwell-time performance differentiation. For New Entrants and Emerging Players: Pursue Maharashtra and Karnataka state-level NICU infrastructure buildout under India's National Health Mission, where CDSCO registration pathways offer faster qualification than FDA 510(k) timelines. Target single-lumen catheter procurement for initial government hospital stocking, leveraging cost position against established premium suppliers. Direct-to-hospital e-procurement platforms offer the most penetrable channel for bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU MDR clinical evidence requirements and FDA biocompatibility testing burdens filter marginal competitors toward qualified supplier concentration. Acquisition targets should display antimicrobial coating R&D pipelines and established notified body relationships in Berlin or Munich. Watch FDA premarket notification submission volumes for novel catheter designs as the inflection signal for competitive entry timing compression.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Integration | Silver-ion and chlorhexidine surface engineering differentiates premium catheters against commodity alternatives in Level IV NICU procurement. |
| EU MDR CE Marking Pathway | Notified body relationships in Berlin and Munich accelerate market entry for novel catheter designs under stricter risk classification. |
| Hospital System Partnership | Multi-year supply agreements with Catholic health networks and academic consortia secure recurring replacement volume through infection control mandates. |
| Software Companion Development | Digital placement guidance systems reshape clinical workflows and procurement criteria toward integrated device-platform bundles. |
| Reimbursement Strategy | NICE technology appraisal pathways in the United Kingdom drive adoption of antimicrobial-integrated surfaces through total cost of care justification. |
Research Methodology
Initial hypotheses were tested against primary input from neonatologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up catheter unit demand estimates were triangulated with top-down healthcare expenditure allocation models across the analysis window.
Demand-supply-balance framing anchored the quantitative model, with segmentation across product type, material composition, end-user facility tier, and application workflow integrated throughout the projection horizon. CAGRs were derived from installed base replacement cycle analysis and premature birth rate sustainment patterns. ISO 80369-3 small-bore connector standardization timelines and Joint Commission accreditation survey frequencies served as industry-specific forecast inputs.
Sensitivities concentrate around FDA predicate device availability for 510(k) pathway navigation and EU MDR notified body capacity constraints extending CE marking timelines. Forecasts reflect assumptions regarding Level IV NICU expansion rates and antimicrobial coating technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Transcatheter Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Hypertension Management Devices Market