
 Aortic Stents Grafts Market | 2026-2036
Aortic Stents Grafts Market Size, Share, and Industry Trends Forecast 2026-2036
Aortic Stents Grafts Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD), which mandates comprehensive ESG disclosures, is repositioning material selection and supply chain transparency for aortic stent graft manufacturers. Medtronic leverages its extensive global distribution network and clinical trial infrastructure to maintain a significant market presence. W. L. Gore & Associates differentiates through its proprietary ePTFE material science and focus on long-term device durability. Cook Medical specializes in a broad portfolio of both thoracic and abdominal grafts, catering to diverse patient anatomies.
Aortic stent grafts are medical implants combining a fabric liner, typically polyester or ePTFE, with a metallic stent framework. These devices are delivered endovascularly to reinforce a weakened aortic wall, primarily treating conditions like aortic aneurysms by creating a new channel for blood flow. Abdominal stent grafts constitute the largest product segment due to the higher prevalence of abdominal aortic aneurysms. Fenestrated stent grafts represent the fastest-growing category, enabling treatment of more complex juxtarenal aneurysms that were previously difficult to manage endovascularly.
Regulatory oversight from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA dictates stringent pre-market approval pathways for new devices. These agencies' requirements for extensive clinical trial data and post-market surveillance directly influence development timelines and market access. Decisions on investment in next-generation branched and fenestrated device technologies will determine competitive leadership.
Market Dynamics
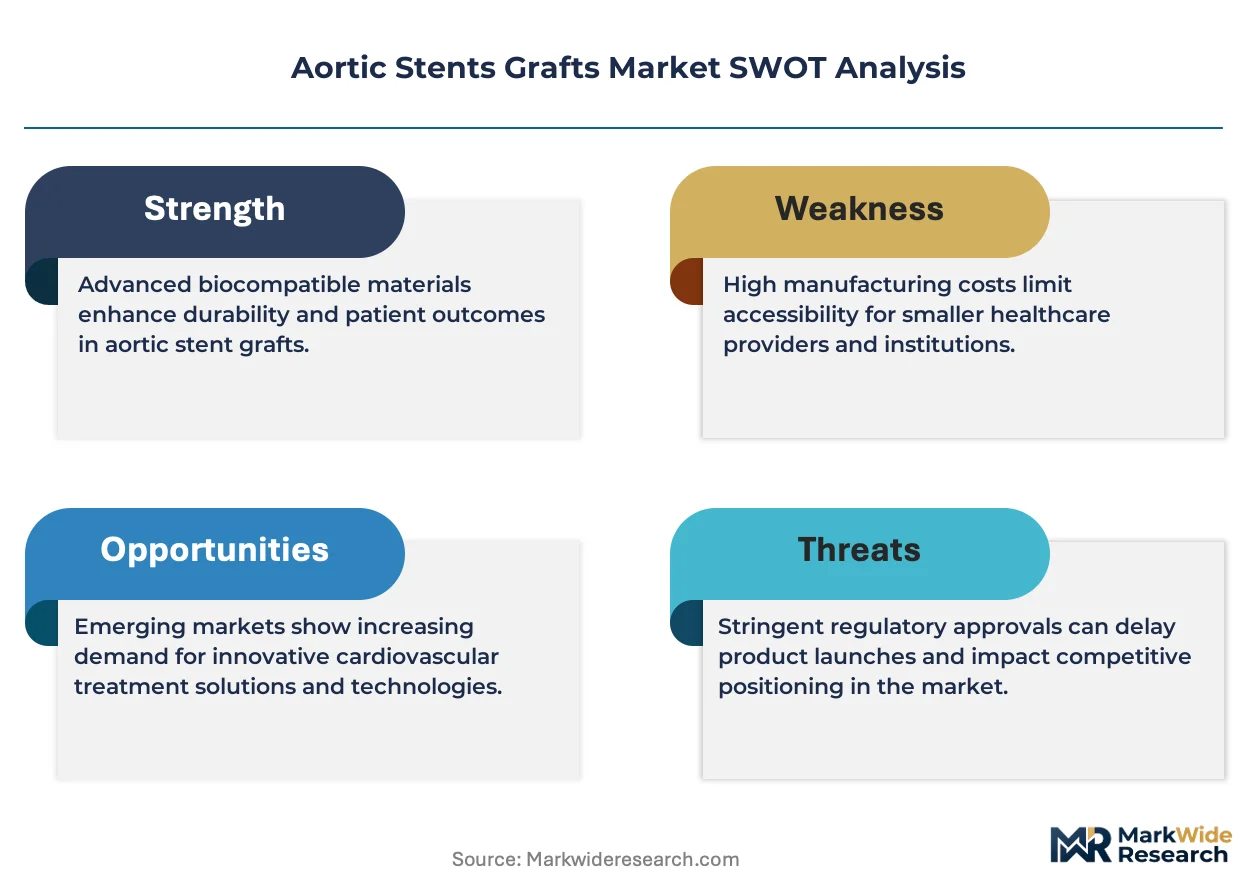
The convergence of advanced material science and stringent regulatory frameworks for medical devices is the central force shaping the aortic stent graft market. Compliance with standards like the EU's MDR is compelling manufacturers to re-evaluate material sourcing and long-term biocompatibility data.
Growth Catalysts
- Next-Generation Devices:The development of fenestrated and branched stent grafts enables the endovascular treatment of complex juxtarenal and thoracoabdominal aneurysms, expanding the addressable patient population beyond what was possible with simpler devices.
- Aging Global Population:Demographic shifts, particularly in developed nations such as Germany and Japan, are leading to a higher incidence of aortic aneurysms, directly increasing procedural volumes for both elective and emergency repairs.
- Minimally Invasive Focus:Healthcare systems are prioritizing minimally invasive procedures like EVAR due to benefits such as shorter hospital stays and faster patient recovery, a trend supported by favorable reimbursement policies in many regions.
Market Restraints
- High Device and Procedure Cost:The significant expense associated with aortic stent grafts and the corresponding endovascular procedures can restrict patient access in healthcare systems with tight budgets or in regions with limited insurance coverage.
- Risk of Endoleaks:A persistent technical limitation is the potential for endoleaks, where blood flows into the aneurysm sac outside the graft, necessitating costly and complex long-term patient surveillance and potential re-interventions.
- Stringent Regulatory Pathways:Extensive pre-market approval processes mandated by bodies like the US FDA and China's NMPA require substantial investment in clinical trials and data collection, creating high barriers to entry and slowing innovation cycles.
Strategic Opportunities
- Emerging Market Penetration:Increasing healthcare expenditure and the development of specialized cardiac and vascular centers in countries like Brazil and India present significant growth opportunities for established stent graft manufacturers.
- AI in Procedural Planning:Integrating artificial intelligence and machine learning algorithms with medical imaging data offers the potential to automate graft sizing and optimize deployment strategies, improving surgical precision and patient outcomes.
- Patient-Specific Implants:Advances in 3D printing and advanced manufacturing create an opportunity to produce custom-made stent grafts tailored to individual patient anatomy, especially for cases that cannot be treated with off-the-shelf devices.
Industry Challenges
- Specialized Physician Shortage:A critical challenge is the lack of a sufficient number of vascular surgeons and interventional radiologists with the advanced training required to perform complex fenestrated and branched endovascular aortic repairs.
- Material Traceability Compliance:The operational burden of meeting new material traceability and supply chain transparency requirements, as mandated by regulations like the EU's Medical Device Regulation, adds complexity and cost.
- Data Interoperability:Ensuring seamless integration of new device planning software with legacy hospital picture archiving and communication systems (PACS) and electronic health records remains a significant technical hurdle for providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aortic Stents Grafts Market |
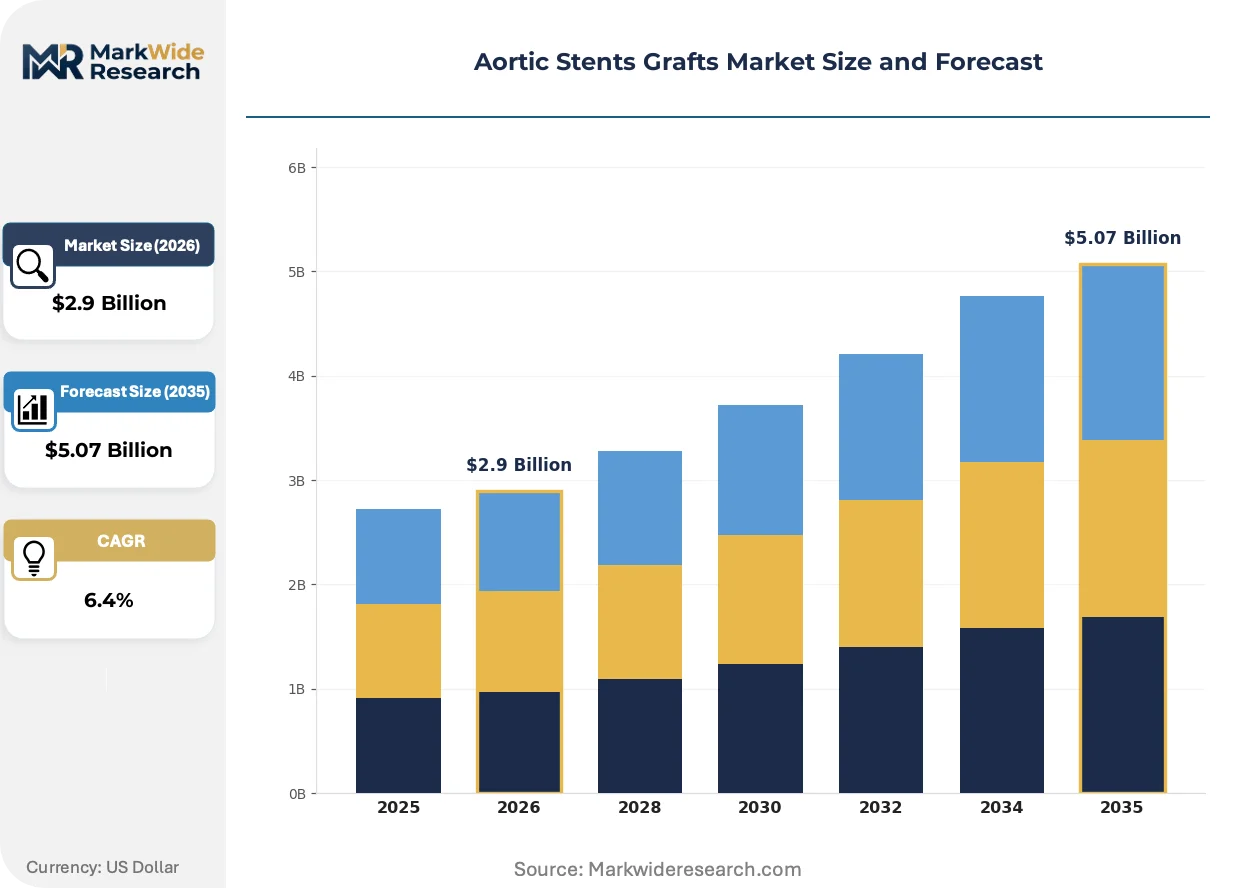
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.07 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thoracic Stent Grafts, Abdominal Stent Grafts, Fenestrated Stent Grafts, Branched Stent Grafts Therapy Area: Aortic Aneurysm, Aortic Dissection, Aortic Rupture, Aortic Coarctation End User: Cardiology Clinics, Vascular Surgery Centers, Diagnostic Laboratories, Specialty Care Units Delivery Mode: Endovascular, Open Surgical, Hybrid Procedures, Minimally Invasive Techniques |
| Companies Covered | Medtronic, W. L. Gore & Associates, Cook Medical, Terumo Aortic, Endologix, Artivion, MicroPort Scientific Corporation, Becton Dickinson, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aortic Stents Grafts Market Strategic Shifts & Innovations
Innovation in the aortic stent graft market is driven by the pursuit of enhanced long-term durability and the integration of digital tools for procedural precision. Material science advancements are focused on improving biocompatibility, while software evolution aims to de-risk complex implantations.
Bioresorbable polymers are being investigated for use in stent graft components, designed to provide temporary structural support before safely degrading within the body. These materials are being explored primarily by academic research centers and specialized device developers for next-generation implants. The potential for a fully resorbable scaffold that obviates the risks associated with a permanent implant is electrifying the field of regenerative vascular medicine.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is compelling manufacturers to provide detailed disclosures on their environmental, social, and governance performance. This regulation forces a comprehensive accounting of the lifecycle impact of device materials, from the sourcing of nitinol to the disposal of polyester fabrics. The abdominal stent graft segment, due to its high production volume, is most affected, prompting a re-evaluation of supplier sustainability credentials.
A notable behavioral shift is occurring in hospital purchasing, moving from unit-based transactions to value-based agreements tied to clinical outcomes. This model disrupts traditional sales channels by rewarding devices that demonstrate lower rates of re-intervention and complications in post-market studies. This change is most pronounced in large, integrated health systems in the United States and public hospital networks in Western Europe.
Aortic Stents Grafts Market Segmentation
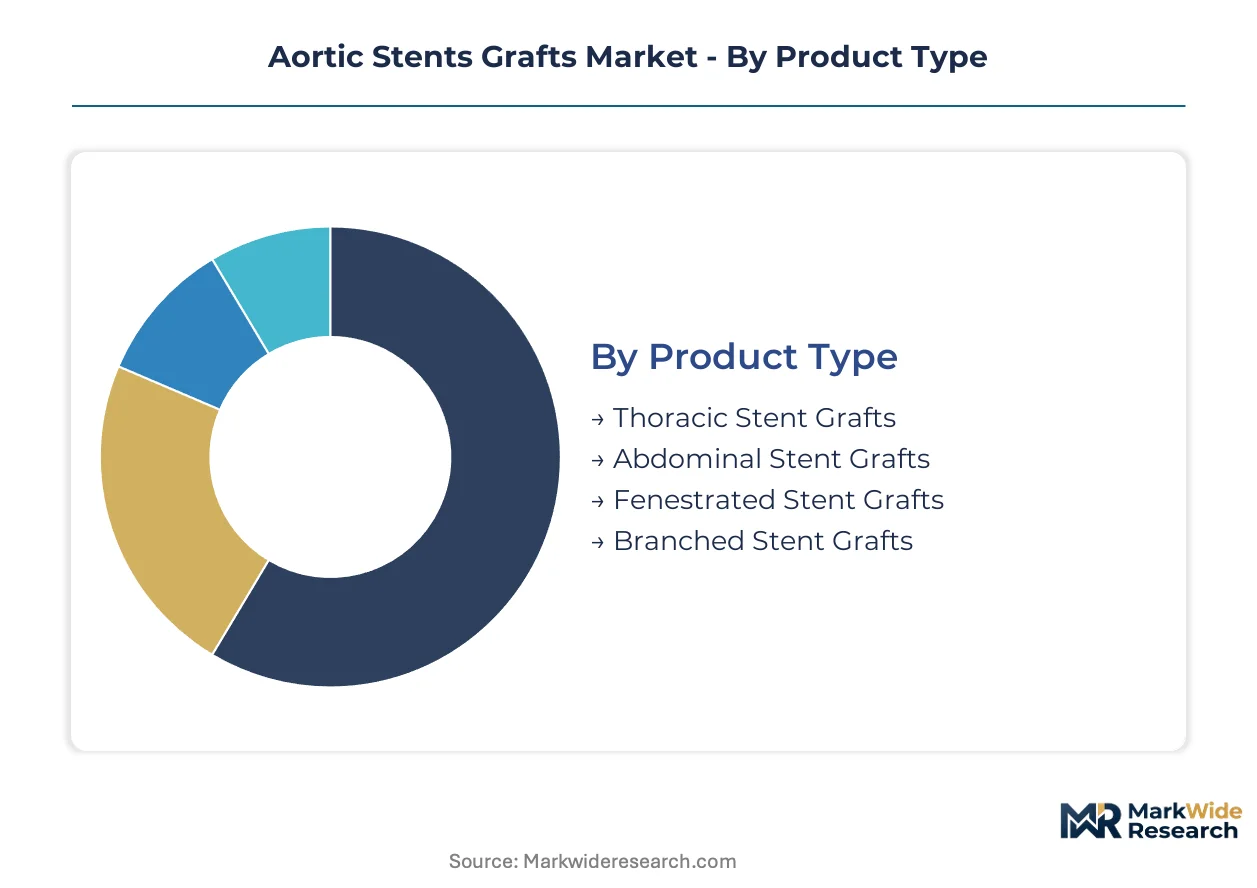
The aortic stent grafts market is segmented based on the critical characteristics of these medical devices, reflecting their diverse applications and the evolving landscape of endovascular repair. Understanding these segments is crucial for manufacturers to align product development with clinical needs and for healthcare providers to optimize patient care pathways.
Product Type:
Aortic stent graft product types are differentiated by their anatomical placement and design complexity.
- Abdominal Stent Grafts:These devices are designed for endovascular repair of aneurysms located in the infrarenal aorta, typically featuring a bifurcated design to accommodate iliac arteries. Demand concentrates in developed nations like Germany due to the high incidence of abdominal aortic aneurysms and established screening programs.
- Fenestrated Stent Grafts:These advanced implants incorporate custom-designed openings that allow perfusion of critical branch vessels, enabling endovascular treatment of complex juxtarenal and pararenal aneurysms. Demand is expanding rapidly in specialized vascular centers seeking to offer minimally invasive solutions for challenging anatomies.
- Thoracic Stent Grafts:These devices are specifically engineered for the descending thoracic aorta, addressing aneurysms and dissections in the chest cavity.
- Branched Stent Grafts:These highly customized devices feature integrated branches for multiple aortic side vessels, extending endovascular repair capabilities to thoracoabdominal aneurysms.
Abdominal Stent Grafts lead on scale; Fenestrated Stent Grafts lead on momentum.
Therapy Area:
Therapy areas delineate the specific aortic pathologies addressed by stent graft interventions.
- Aortic Aneurysm:This primary indication involves the repair of localized dilations in the aortic wall, preventing rupture through endovascular exclusion. Demand is driven by an aging global population and the preference for less invasive surgical alternatives.
- Aortic Dissection:Stent grafts stabilize the aorta by sealing entry tears and promoting false lumen thrombosis, managing acute and chronic dissections. Procedural volumes are increasing in emergency settings where rapid intervention is crucial for patient survival.
- Aortic Rupture:This life-threatening emergency requires immediate intervention, where stent grafts offer a rapid and effective method for hemorrhage control.
- Aortic Coarctation:While less common for stent grafts, severe narrowing of the aorta can be managed endovascularly to restore normal blood flow.
Aortic Aneurysm remains the primary driver of stent graft procedures; Aortic Dissection represents an emerging critical need.
End User:
End-user segments reflect the diverse healthcare facilities where aortic stent graft procedures are performed and managed.
- Vascular Surgery Centers:These specialized facilities are equipped with the necessary hybrid operating rooms and skilled personnel for complex endovascular aortic repair procedures. Demand is concentrated in regions with sophisticated hospital infrastructure and high procedural volumes, such as Germany.
- Cardiology Clinics:These outpatient settings play a vital role in patient referral, pre-procedural assessment, and long-term post-implantation surveillance for aortic stent graft recipients. Their influence on device selection is growing through integrated care pathways.
- Diagnostic Laboratories:These facilities provide critical imaging and diagnostic services essential for patient selection, device sizing, and post-operative monitoring of stent graft patients.
- Specialty Care Units:These units, often within larger hospitals, manage patients with complex cardiovascular conditions requiring multidisciplinary care, including those undergoing aortic interventions.
Vascular Surgery Centers are central to device deployment; Cardiology Clinics focus on comprehensive patient management.
Delivery Mode:
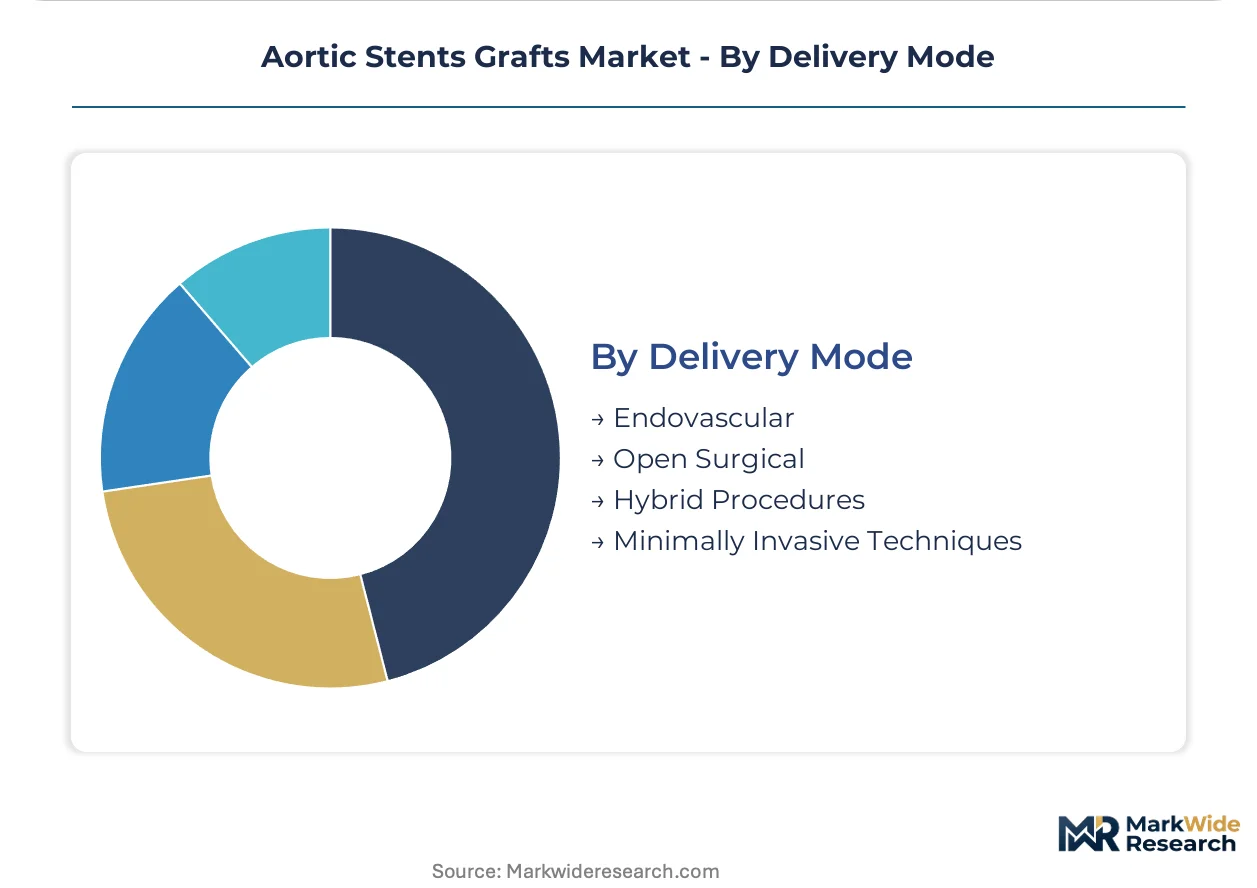
Delivery modes categorize the primary surgical or interventional techniques employed for aortic stent graft implantation.
- Endovascular:This dominant approach involves percutaneous access and catheter-based delivery of the stent graft, offering reduced patient trauma and faster recovery compared to traditional open surgery. Demand is bolstered by favorable reimbursement policies and patient preference for less invasive options across Europe and the US.
- Minimally Invasive Techniques:This category emphasizes approaches that utilize smaller incisions or percutaneous access points for device delivery, often overlapping with endovascular methods but focusing on reduced surgical footprint. These techniques are gaining traction due to benefits like decreased hospital stays and lower complication rates.
- Open Surgical:While declining for many aortic conditions, traditional open repair remains an option for highly complex cases or when endovascular options are unsuitable.
- Hybrid Procedures:These combine elements of open surgical exposure with endovascular repair, allowing for complex reconstructions that leverage the benefits of both approaches.
Endovascular delivery has become the standard; Minimally Invasive Techniques represent its ongoing evolution towards less invasiveness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aortic stent graft industry was significantly scaled in Western economies, where advanced medical infrastructure and an aging demographic first converged to create substantial demand for endovascular aortic repair. Regions with established healthcare systems and high rates of cardiovascular disease continue to drive innovation and adoption of advanced stent graft technologies. This market expansion is supported by ongoing clinical research and favorable reimbursement landscapes across developed nations.
Germany
Demand for aortic stent grafts in Germany is driven by a high incidence of abdominal aortic aneurysms and established screening programs. Compliance with the European Union's Medical Device Regulation (MDR) is compelling manufacturers to re-evaluate material sourcing and long-term biocompatibility data. Specialized vascular centers in cities like Munich and Berlin are at the forefront of adopting fenestrated and branched stent grafts.
United States
The United States market benefits from favorable reimbursement policies and patient preference for less invasive options in aortic repair. The US FDA mandates stringent pre-market approval pathways, influencing development timelines for new devices. Integrated health systems across major metropolitan areas, including New York and Los Angeles, prioritize outcomes-based care and advanced endovascular solutions.
Japan
Japan's aging population contributes to a higher incidence of aortic aneurysms, increasing procedural volumes for endovascular repairs. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates market access, requiring extensive clinical trial data for novel devices. Advanced medical technology hubs in Tokyo and Osaka are actively involved in research and development for next-generation implants.
China
China presents significant growth opportunities due to increasing healthcare expenditure and the development of specialized cardiac and vascular centers. The National Medical Products Administration (NMPA) dictates stringent pre-market approval processes for new devices entering the market. Major cities like Shanghai and Beijing are seeing rapid expansion of endovascular capabilities and procedural volumes.
Brazil
Increasing healthcare expenditure and the development of specialized cardiac and vascular centers in Brazil drive demand for aortic stent grafts. ANVISA, Brazil's health regulatory agency, oversees the approval and market entry of medical devices. Major urban centers such as São Paulo and Rio de Janeiro are becoming key hubs for complex endovascular interventions.
Aortic Stents Grafts Market Key Industry Players
Premium-margin players sit above commodity-margin players across the aortic stent graft market, primarily differentiated by technological sophistication and long-term clinical data. The market structure features a mix of large, diversified medical device companies and specialized firms focusing on niche aortic repair solutions. Strategic archetypes include innovation-driven leaders, broad portfolio providers, and material science specialists. Dominant competitive moves involve significant investment in research and development for next-generation devices and strategic partnerships to expand market reach.
Within the innovation-driven tier, Medtronic leverages its extensive global distribution network and clinical trial infrastructure to maintain a significant market presence. W. L. Gore & Associates exemplifies differentiation through its proprietary ePTFE material science and focus on long-term device durability. Cook Medical occupies a strong position with a broad portfolio of both thoracic and abdominal grafts, catering to diverse patient anatomies and complex cases.
| Leading Market Players |
|---|
| Medtronic |
| W. L. Gore & Associates |
| Cook Medical |
| Terumo Aortic |
| Endologix |
| Artivion |
| MicroPort Scientific Corporation |
| Becton Dickinson |
| Cardinal Health |
Cost & Logistics Intelligence
Vertical integration by leading manufacturers like Medtronic and W. L. Gore & Associates anchors both supply position and pricing power in the aortic stent graft market. This strategic control over proprietary materials and complex device manufacturing enables premium pricing for advanced endovascular solutions.
Pricing Analysis
Value-based agreements are increasingly influencing pricing in the aortic stent graft market, shifting from unit-based transactions to models tied to clinical outcomes. Price differentiation is primarily driven by technological sophistication of devices, such as fenestrated and branched grafts, and robust long-term clinical data demonstrating device durability. Pricing softness stems from healthcare systems prioritizing cost-effectiveness and favorable reimbursement policies in many regions. Public hospital networks in Western Europe often exhibit higher price sensitivity, while specialized vascular surgery centers prioritize advanced, clinically proven solutions for complex patient anatomies.
Supply Chain Analysis
Direct-to-hospital distribution through extensive global networks characterizes the aortic stent graft market, ensuring specialized devices reach vascular surgery centers. Supply chain concentration for key raw materials draws from specific geographies, with nitinol primarily sourced from North America and China, and ePTFE/polyester fabrics from specialized chemical manufacturers. Stringent regulatory frameworks like the EU's MDR and China's NMPA pose a structural risk, demanding rigorous material traceability and long-term biocompatibility data. Manufacturers must navigate complex logistics to deliver custom-made and off-the-shelf grafts to diverse healthcare systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aortic stent graft market offers a compelling margin-expansion story driven by the increasing adoption of next-generation branched and fenestrated device technologies. These advanced implants command premium pricing due to their complexity and expanded addressable patient populations.
For Market Incumbents:Deepen investment in research and development for next-generation branched and fenestrated devices to maintain technological leadership against emerging solutions. Expand clinical trial infrastructure to meet stringent regulatory pathways from bodies like the US FDA, mitigating market access delays. Consolidate market share by leveraging established global distribution networks, particularly in regions with high procedural volumes like Germany. Focusing on long-term device durability and reducing endoleak risks will reinforce competitive positioning.
For New Entrants and Emerging Players:Online clinical education platforms offer a strategic digital channel to build credibility and disseminate expertise for novel aortic stent graft technologies. Target underpenetrated emerging markets like Brazil and India, where healthcare expenditure is increasing, by offering cost-effective solutions. Specialize in patient-specific implants using advanced 3D printing, addressing complex anatomies not served by off-the-shelf devices. Partnering with AI imaging companies for optimized procedural planning provides a compelling go-to-market angle.
For Investors and Strategic Acquirers:Roll-up economics work for established medical device conglomerates because of the fragmented innovation landscape and high R&D costs associated with regulatory approvals. The market offers sustained long-term viability over the next decade, driven by an aging global population and preference for minimally invasive endovascular repair. Target acquisition archetypes include specialized device developers with proprietary material science, such as ePTFE, or advanced AI-driven procedural planning software. Accelerated regulatory approvals for bioresorbable polymers will be a key inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for next-generation fenestrated and branched stent grafts within stringent regulatory frameworks. |
| Hospital System Partnership | Secures preferred vendor status and integrates advanced devices into established vascular surgery center care pathways. |
| Software Companion Development | Enhances procedural precision and reduces complication rates for complex aortic stent graft implantations. |
| Material Science Innovation | Improves long-term device durability and biocompatibility, addressing endoleak risks for patients. |
| Emerging Market Entry | Expands addressable patient populations and diversifies revenue streams in high-growth regions like Brazil and India. |
Research Approach
Bottom-up vascular surgery center modeling reconciled against top-down stent graft manufacturer tracking forms the analytical core of this study. Primary interviews with vascular surgeons, interventional radiologists, and hospital procurement managers provided granular insights into device adoption and clinical needs. This qualitative data was validated against extensive secondary sources including US FDA filings, European Medicines Agency (EMA) submissions, and medical journal databases. The approach ensures comprehensive data triangulation.
The input-output matrix framework integrates historical market performance with projected dynamics across the analysis window. Segmentation dimensions modeled include product type, therapy area, end user, delivery mode, and regional adoption patterns. Compound annual growth rates were derived from a synthesis of historical trends and anticipated market shifts. Key industry-specific forecast inputs include global aortic aneurysm incidence rates.
Regulatory changes, technological breakthroughs, and shifts in healthcare spending are the dominant revision risks to market forecasts. All projections reflect underlying assumptions regarding clinical practice evolution and material science advancements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Renal Denervation Devices Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Cardiovascular Prosthetic Devices Market