
 Canada Cardiovascular Devices Market | 2026-2036
Canada Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Cardiovascular Devices Market Outlook
Health Canada's evolving post-market surveillance framework for implantable devices is shifting procurement criteria toward long-term reliability data. Medtronic leverages its integrated cath lab-to-home monitoring ecosystem to sustain recurring revenue streams. Abbott Laboratories anchors its position through structural heart innovations that reduce open-heart dependency. Boston Scientific Corporation competes aggressively in interventional cardiology with specialized drug-eluting stent portfolios.
Canada cardiovascular devices encompass implantable and interventional instruments engineered from biocompatible alloys, polymer matrices, and biological tissues, typically requiring precision machining, laser welding, and sterile packaging to achieve hemodynamic compatibility and thromboresistance; these devices restore or monitor cardiac and vascular function in clinical settings. Stent platforms generate substantial recurring revenue through repeat intervention cycles, while transcatheter heart valves capture expanding margin pools as surgical-eligible populations age. Minimally invasive technology segments attract capital investment from ambulatory surgical centers seeking reduced recovery protocols.
Health Canada's Medical Devices Bureau, the Canadian Standards Association, and ISO 13485 quality management standards collectively govern pre-market licensing, clinical evidence requirements, and manufacturing audits for cardiovascular device commercialization. These frameworks elevate barriers for new entrants while mandating real-world performance tracking that shapes hospital purchasing committees. Stakeholders must monitor evolving evidence requirements for breakthrough device designations and anticipate how provincial formularies will reconcile cost-effectiveness thresholds against patient access mandates.
Market Dynamics
Health Canada's tightened post-market surveillance mandates for implantable cardiac devices are forcing manufacturers to restructure clinical evidence portfolios and hospital contracting terms around longitudinal performance guarantees rather than upfront device costs.
Growth Catalysts
- Ontario catheterization lab expansion:Provincial hospital infrastructure investments in Toronto and Ottawa cardiac centers are creating concentrated demand corridors for interventional cardiology suites and associated consumables.
- ISO 13485 quality certification:Mandatory manufacturing audits under harmonized international standards are elevating compliance barriers that favor established suppliers with captive sterile packaging and precision machining capabilities.
- Bioresorbable polymer stents:Next-generation scaffold materials eliminating permanent metal implants are capturing preference share among interventional cardiologists at Quebec's major academic medical centers.
Market Restraints
- Noble metal input volatility:Platinum and palladium price swings embedded in coronary stent manufacturing costs compress margin predictability for device suppliers serving Canadian provincial formularies.
- Single-source laser welding equipment:Concentrated supply of precision joining systems from German and Swiss OEMs creates vulnerability in domestic device manufacturing scale-up timelines.
- Health Canada licensing friction:Extended pre-market review cycles for novel transcatheter valve designs delay revenue recognition against R&D amortization schedules.
Strategic Opportunities
- Remote patient monitoring convergence:Integration of implantable cardiac devices with home-based telemetry platforms opens recurring revenue streams beyond the index procedure in British Columbia's distributed rural populations.
- Ambulatory surgical center channel:Standalone cardiac catheterization facilities in Alberta and Saskatchewan are procuring turnkey device-procedure bundles that bypass traditional hospital supply chains.
- Provincial value-based procurement:Ontario Health's outcomes-linked tendering creates first-mover advantage for suppliers demonstrating readmission reduction through device-integrated care pathways.
Industry Challenges
- Specialized interventional cardiologist scarcity:Transcatheter structural heart procedures require fellowship-trained operators whose limited supply in Atlantic Canada constrains procedural volume growth.
- Legacy electronic health record integration:Device-generated hemodynamic data streams face interoperability barriers with provincial hospital information systems, complicating real-world evidence capture for post-market surveillance.
- Capital equipment refresh cycles:Cath lab imaging system replacement timelines at Quebec institutions lag procedural volume growth, creating bottlenecks for complex transcatheter interventions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Cardiovascular Devices Market |
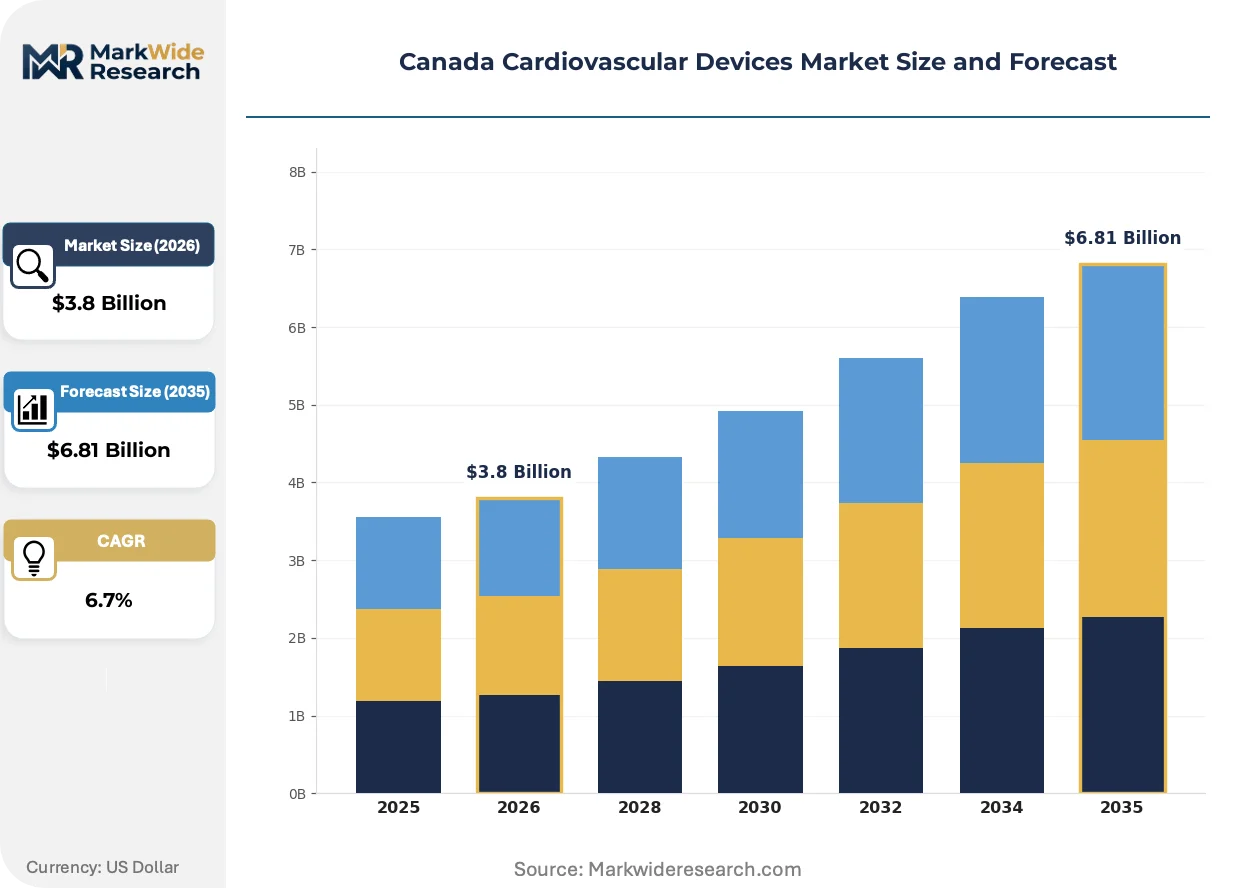
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Heart Valves End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Technology: Minimally Invasive, Implantable, Diagnostic Imaging, Intravascular Application: Coronary Artery Disease, Heart Failure, Arrhythmia, Peripheral Vascular Disease |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Edwards Lifesciences Corporation, Biotronik, Cardinal Health, Siemens Healthineers, GE Healthcare, W. L. Gore & Associates, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Cardiovascular Devices Market Strategic Shifts
Computational integration across device design, manufacturing, and post-implant monitoring is compressing development cycles while expanding the addressable patient population beyond surgical-eligible candidates.
Artificial intelligence-enabled electrophysiology mapping systems are automating arrhythmia source localization during catheter ablation procedures. Cardiac electrophysiology teams at Toronto's University Health Network and Montreal's McGill University Health Centre are deploying these platforms to reduce fluoroscopy exposure and procedure duration. This automation is compressing training curves for new operators while enabling higher-throughput lab scheduling.
Health Canada's Medical Devices Bureau has aligned pre-market clinical evidence requirements with the International Medical Device Regulators Forum (IMDRF) framework for machine-learning-enabled diagnostic functions. Device manufacturers must now submit algorithm performance validation across Canadian demographic subpopulations as a condition of licensing. Transcatheter imaging and navigation systems with embedded AI classifiers face the steepest compliance adjustment.
Provincial health authorities are consolidating cardiovascular device procurement through centralized tendering vehicles that unbundle capital equipment from disposable contracts. Ontario Health's cardiac devices category management program now mandates five-year total cost of ownership modeling, forcing suppliers to price monitoring, training, and revision procedure likelihood into upfront bids. This purchasing model is most advanced in coronary stent and pacemaker categories.
Canada Cardiovascular Devices Market Segmentation
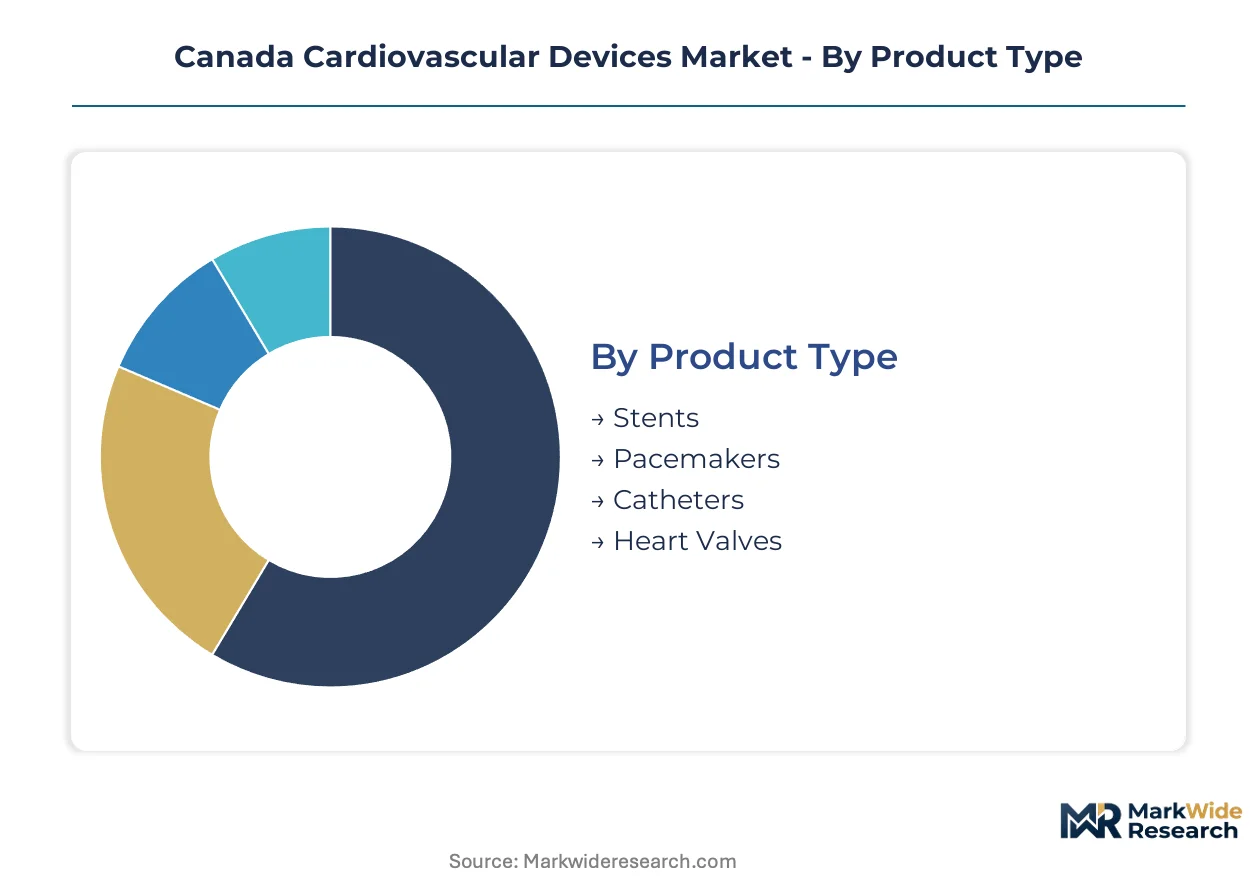
Segmentation in Canada's cardiovascular device market reveals how provincial procurement patterns, cath lab infrastructure maturity, and patient risk stratification reshape demand across product categories. Understanding these divides exposes where Health Canada licensing friction and Ontario Health tendering rules concentrate commercial opportunity.
Product Type:
Device selection hinges on reimbursement tier placement within provincial formularies and the procedural complexity each product enables.
- Stents:Drug-eluting and bioresorbable polymer platforms dominate interventional cardiology spend. Quebec's major academic centers drive preference for next-generation scaffolds that eliminate permanent metal implants, though platinum and palladium input costs compress margin predictability.
- Heart Valves:Transcatheter aortic and mitral replacements capture expanding procedure volumes as surgical-eligible populations age. Ontario catheterization lab expansions in Toronto and Ottawa create concentrated demand corridors for these high-acuity interventions.
- Pacemakers:Conduction system pacing and leadless devices address bradyarrhythmia through miniaturized energy delivery systems.
- Catheters:Diagnostic and interventional catheters enable coronary and peripheral vascular access across acute and elective settings.
Stents lead volumes today; heart valves are gaining share fastest.
End User:
Procurement authority and patient acuity levels fragment the customer base across institutional types with diverging capital allocation timelines.
- Hospitals:Tertiary cardiac centers in Ontario and Quebec anchor device demand through high-volume catheterization labs and structural heart programs. Health Canada's tightened post-market surveillance mandates force these institutions to restructure purchasing committees around longitudinal reliability data rather than upfront device costs.
- Ambulatory Surgical Centers:Standalone cardiac catheterization facilities in Alberta and Saskatchewan procure turnkey device-procedure bundles that bypass traditional hospital supply chains entirely. These centers prioritize rapid patient turnover and reduced recovery protocols.
- Cardiology Clinics:Outpatient diagnostic and follow-up settings manage chronic cardiovascular conditions through non-invasive monitoring.
- Rehabilitation Centers:Post-acute facilities integrate device-generated telemetry into cardiac recovery protocols.
Hospitals absorb the majority of device procurement spend; ambulatory surgical centers are expanding most quickly.
Technology:
Technical sophistication determines regulatory pathway length and the capital intensity required for commercial deployment.
- Minimally Invasive:Transcatheter delivery systems and percutaneous approaches reduce open-heart dependency. Toronto's University Health Network and Montreal's McGill University Health Centre deploy AI-enabled electrophysiology mapping platforms to compress procedure duration and fluoroscopy exposure.
- Implantable:Permanent and bioresorbable devices require ISO 13485-certified manufacturing with precision machining and sterile packaging capabilities. Health Canada's Medical Devices Bureau mandates real-world performance tracking that shapes hospital purchasing criteria.
- Diagnostic Imaging:Intravascular ultrasound and optical coherence tomography guide interventional decision-making.
- Intravascular:Catheter-based therapeutic delivery encompasses angioplasty, atherectomy, and thrombectomy systems.
Implantable technology commands premium pricing today; minimally invasive platforms show the steepest expansion trajectory.
Application:
Clinical indication severity and prevalence rates concentrate procedure volumes within specific provincial health authority catchments.
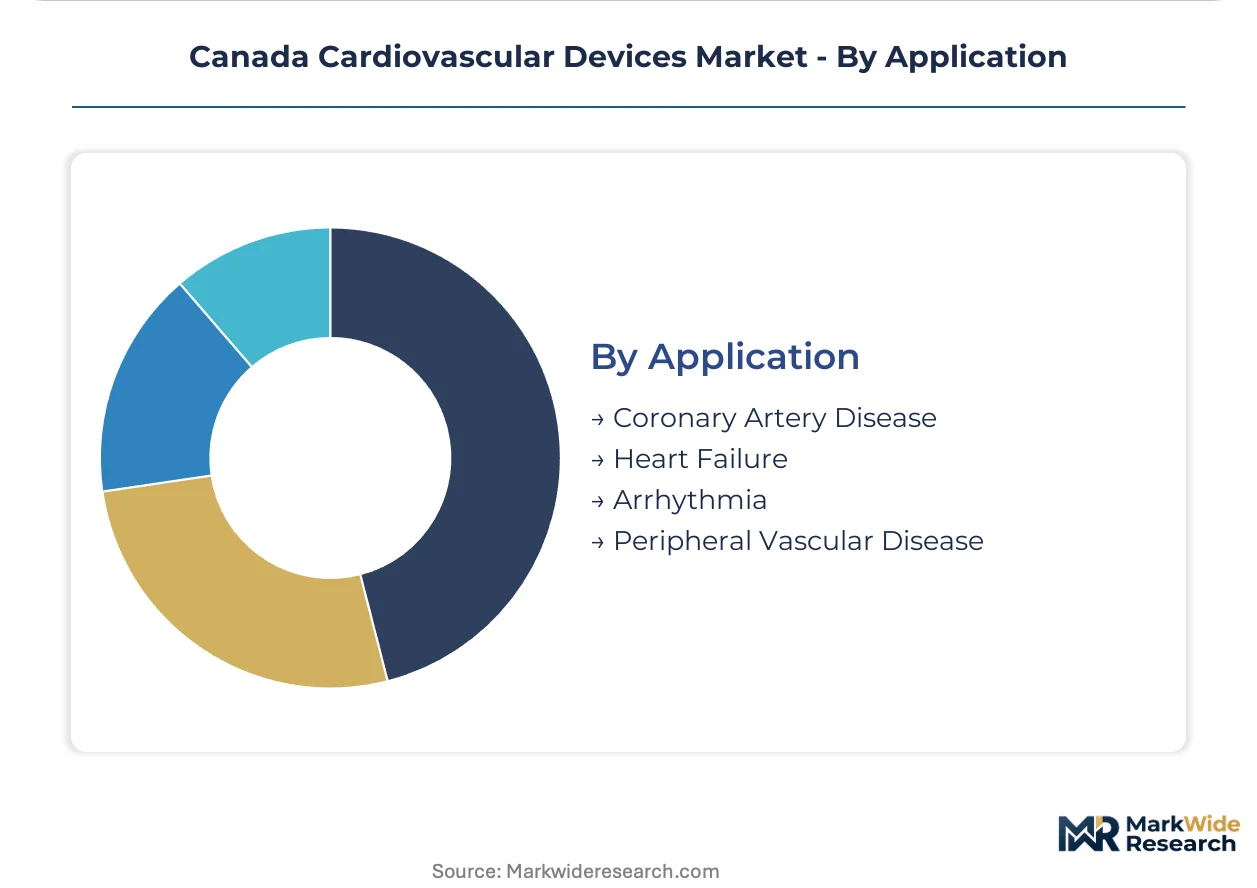
- Coronary Artery Disease:Percutaneous coronary intervention with stent deployment represents the foundational revenue stream. Ontario Health's outcomes-linked tendering now mandates five-year total cost of ownership modeling that forces suppliers to price revision procedure likelihood into upfront bids.
- Arrhythmia:Electrophysiology ablation and device-based rhythm management address atrial fibrillation and ventricular tachycardia. Fellowship-trained operator scarcity in Atlantic Canada constrains procedural volume growth despite underlying disease prevalence.
- Heart Failure:Resynchronization therapy and mechanical circulatory support address declining ejection fraction.
- Peripheral Vascular Disease:Endovascular intervention targets lower extremity and renal artery stenosis.
Coronary artery disease procedures generate the largest installed base; arrhythmia interventions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained interventional cardiologists concentrate in Ontario and Quebec, anchoring procedural capacity for transcatheter interventions across the Canadian market.
Ontario
Toronto and Ottawa cardiac centers drive catheterization lab expansion with provincial infrastructure investments. Health Canada's Medical Devices Bureau mandates longitudinal performance tracking for implantable devices procured through Ontario Health's centralized tendering. University Health Network deploys AI-enabled electrophysiology mapping to compress procedure duration.
Quebec
McGill University Health Centre and major academic medical centers generate preference for bioresorbable polymer stents eliminating permanent metal implants. ISO 13485 quality certification requirements elevate compliance barriers favoring established suppliers with captive sterile packaging capabilities. Montreal clusters concentrate demand for next-generation scaffold materials.
Alberta
Standalone cardiac catheterization facilities in Calgary and Edmonton procure turnkey device-procedure bundles bypassing traditional hospital supply chains. Provincial procurement frameworks prioritize rapid patient turnover and reduced recovery protocols. Ambulatory surgical center channel expansion creates alternative demand corridors outside tertiary hospital networks.
British Columbia
Distributed rural populations drive integration of implantable cardiac devices with home-based telemetry platforms. Remote patient monitoring convergence opens recurring revenue streams beyond index procedures for device suppliers. Vancouver anchors coastal demand while interior regions expand telemedicine-linked cardiac care.
Atlantic Canada
Fellowship-trained operator scarcity constrains transcatheter structural heart procedure growth despite underlying disease prevalence. Provincial health authorities face recruitment challenges for specialized interventional cardiologists. Halifax and St. John's cardiac centers concentrate limited procedural capacity.
Canada Cardiovascular Devices Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Canadian cardiovascular device market. Vertically integrated multinational suppliers with captive manufacturing capabilities dominate hospital procurement committees. Three archetypes anchor competitive positioning: integrated cath lab-to-home monitoring ecosystems, structural heart innovation specialists, and interventional cardiology portfolio aggregators. M&A activity concentrates around remote patient monitoring convergence and bioresorbable scaffold technology licensing.
Among integrated ecosystem providers, Medtronic and Abbott Laboratories exemplify the cath lab-to-home monitoring archetype. Boston Scientific Corporation occupies a position within the interventional cardiology tier. These three anchors represent distinct strategic vectors: longitudinal patient data capture, structural heart minimally invasive alternatives, and specialized drug-eluting stent portfolios.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| Biotronik |
| Cardinal Health |
| Siemens Healthineers |
| GE Healthcare |
| W. L. Gore & Associates |
| Others |
Value Chain & Pricing Dynamics
Platinum and palladium price swings embedded in coronary stent manufacturing trace through three distinct procurement tiers across Canadian provincial formularies. Ontario Health's outcomes-linked tendering compresses margin predictability for device suppliers while elevating long-term performance guarantees over upfront device costs.
Pricing Analysis
Bundled device-procedure packages dominate ambulatory surgical center procurement in Alberta and Saskatchewan, while unbundled capital equipment and disposable contracts persist in Ontario and Quebec hospital systems. Price differentiation hinges on ISO 13485 certification tier and five-year total cost of ownership modeling mandated by centralized tendering vehicles. Cost compression in drug-eluting stent categories intensifies as provincial formularies consolidate procurement authority. Community hospitals and standalone catheterization facilities exhibit highest price sensitivity; tertiary cardiac centers with fellowship-trained operator density prioritize longitudinal reliability data over per-unit acquisition costs.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss OEMs supplying precision laser welding systems essential for bioresorbable polymer scaffold production. Manufacturing draws from platinum and palladium feedstocks anchored in South Africa and Russia, polymer matrix precursors from Germany and Japan, and biological tissue processing capabilities concentrated in the United States. Tariff exposure on noble metal inputs creates margin unpredictability for domestic device manufacturing scale-up timelines. Distribution runs through provincial health authority centralized tendering vehicles that unbundle capital equipment from disposable consumable contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's tightened post-market surveillance mandates create regulatory arbitrage against the FDA's breakthrough device pathway, rewarding suppliers with Canadian clinical evidence portfolios that accelerate provincial formulary access.
For Market Incumbents: Acquire remote patient monitoring telemetry platforms to complete cath lab-to-home ecosystem integration. Bioresorbable polymer stent technology licensing addresses Quebec academic center preference shifts away from permanent metal implants. Backward integration into captive sterile packaging capabilities defends margin position against ISO 13485 compliance barriers that favor established suppliers with precision machining infrastructure. For New Entrants and Emerging Players: Health Canada's alignment with IMDRF machine-learning framework in pre-market clinical evidence requirements opens a window for AI-enabled electrophysiology mapping systems targeting Toronto and Montreal academic medical centers. Atlantic Canada's fellowship-trained operator scarcity represents the most penetrable geography for remote proctoring and training-enabled platform entry. Partnership with provincial GPO contracts managers secures hospital system pilot access bypassing traditional three-year incumbent lock-in periods. For Investors and Strategic Acquirers: Consolidation pressure builds where remote patient monitoring convergence fragments across standalone telemetry vendors lacking implantable device integration. Long-term viability centers on suppliers demonstrating readmission reduction through device-integrated care pathways that satisfy Ontario Health's outcomes-linked tendering. Acquisition targets include mid-cap specialists with Health Canada licensing momentum in transcatheter structural heart categories. Watch for Health Canada breakthrough device designation announcements as inflection indicators for provincial formulary fast-track eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Licensing Pathway Optimization | Accelerated pre-market review compresses revenue recognition timelines against R&D amortization schedules. |
| Provincial GPO Contracts Partnership | Ontario Health's centralized tendering creates first-mover advantage for outcomes-linked device-procedure bundles. |
| Bioresorbable Scaffold Technology Licensing | Quebec academic medical centers drive preference for next-generation polymer platforms eliminating permanent implants. |
| Remote Patient Monitoring Integration | British Columbia's distributed rural populations open recurring revenue streams beyond index procedures. |
| Ambulatory Surgical Center Channel Development | Alberta and Saskatchewan standalone facilities procure turnkey bundles bypassing traditional hospital supply chains. |
Study Parameters
Bottom-up catheterization lab procedure volume modeling reconciled against top-down device shipment tracking forms the analytical core of this study. Primary interviews with interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation against Health Canada Medical Devices Bureau licensing databases, provincial procurement tender records, and ISO 13485 audit registries. Top-down triangulation cross-checks manufacturer-reported device placements against provincial health authority reimbursement claims.
Historical trendline analysis of coronary stent and transcatheter valve procedure volumes across Ontario, Quebec, Alberta, and British Columbia establishes baseline growth trajectories. Segmentation dimensions span product type, end user institution class, technology sophistication tier, and clinical application severity. CAGRs derive from procedure volume elasticity to cath lab infrastructure expansion, demographic aging patterns, and regulatory pathway efficiency variations across provincial jurisdictions. Forecast inputs incorporate Health Canada licensing cycle duration and provincial formulary reconciliation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended pre-market review cycles for novel transcatheter valve designs or acute noble metal price volatility. Forecasts reflect assumptions regarding fellowship-trained operator supply expansion and provincial health authority procurement consolidation momentum. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
India Cardiovascular Devices Market