
 Global External Ventricular Drain Market | 2026-2036
Global External Ventricular Drain Market Size, Share, and Industry Trends Forecast 2026-2036
Global External Ventricular Drain Market Foresight
CE marking under the EU Medical Device Regulation is redrawing competitive access across Europe. Medtronic leverages its neurosurgery portfolio depth to sustain catheter supply contracts with major European hospital networks. B. Braun SE anchors its position through integrated manufacturing of silicone drainage tubing and proprietary valve assemblies. Sophysa differentiates via specialized programmable pressure valves that compete directly against larger diversified suppliers.
An external ventricular drain is a sterile catheter system inserted through the skull into the lateral ventricle to divert cerebrospinal fluid and monitor intracranial pressure, typically constructed from radiopaque silicone tubing with a proximal depth marker and a distal collection chamber. The device serves acute neurocritical care by preventing herniation and enabling therapeutic CSF evacuation in elevated pressure states. Antibiotic-impregnated drains command premium positioning due to documented reductions in ventriculitis incidence, while standard drains occupy cost-sensitive procurement tiers in emerging hospital systems. Closed system technology with digital monitoring interfaces is displacing open gravity-dependent setups in tertiary neurosurgical centers where infection control protocols are most stringent.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and material selection criteria for manufacturers seeking multi-region commercialization. ISO 13485 quality management certification operates as a baseline qualifier rather than a differentiator among established neurosurgical device suppliers. The central bank of regulatory risk sits with post-market surveillance obligations under FDA's Medical Device Reporting and EUDAMED vigilance modules. Stakeholders must weigh catheter material innovation against the documentation burden of expanded biocompatibility testing as both jurisdictions tighten evidence requirements for implantable neurological devices.
Market Dynamics
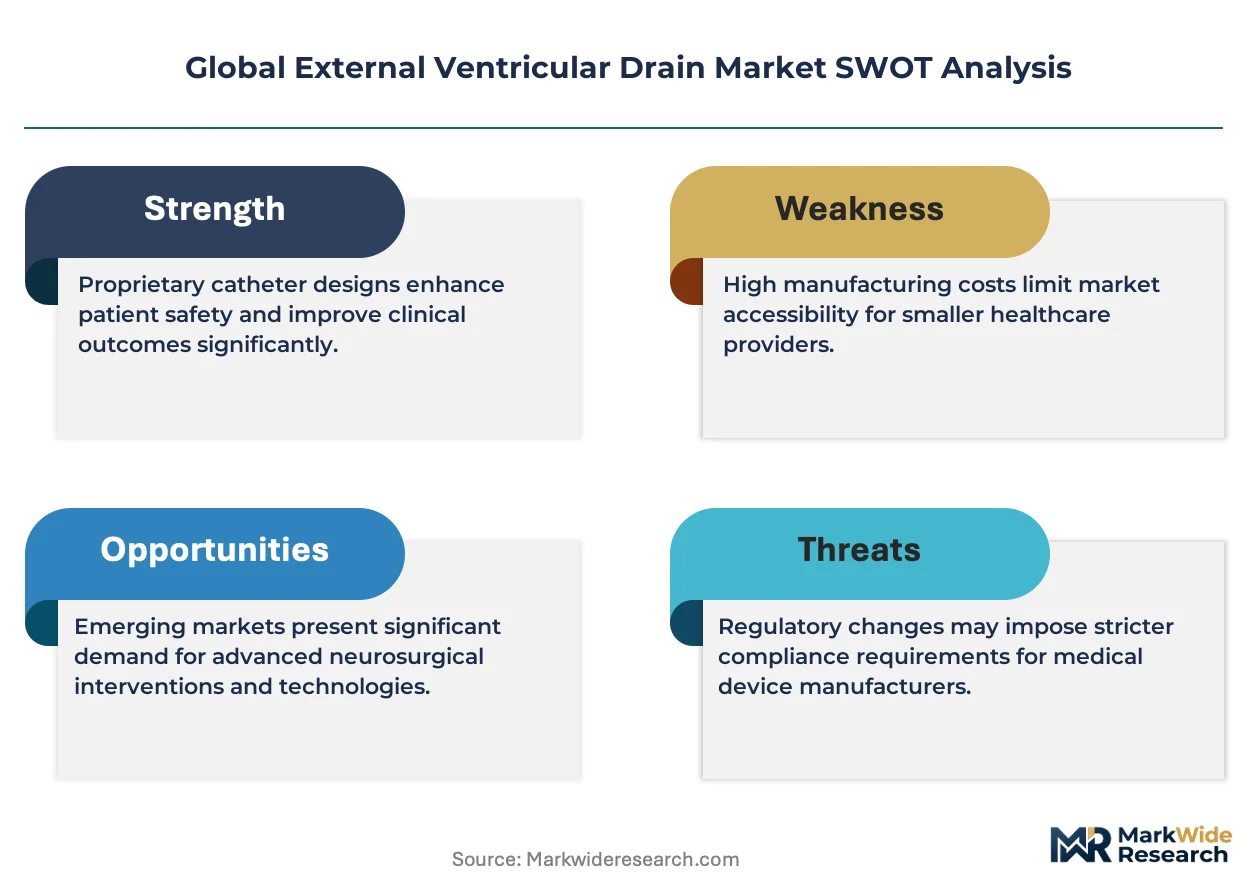
Antibiotic-impregnated catheter technology is compressing standard drain margins while EU MDR conformity costs filter smaller manufacturers from European hospital procurement networks.
Growth Catalysts
- Traumatic brain injury protocol expansion:Neurosurgical centers in the United States are embedding catheter placement into standardized critical care pathways for elevated intracranial pressure management.
- EU MDR implementation:CE marking requirements under the Medical Device Regulation are consolidating procurement authority around established suppliers with notified body relationships.
- Silicone biocompatibility advances:Radiopaque tubing formulations with enhanced infection resistance profiles are penetrating German university hospital networks.
Market Restraints
- Medical-grade silicone supply concentration:Specialty polymer feedstock production clusters in Germany and the United States create vulnerability to petrochemical price volatility.
- 510(k) documentation burden:FDA premarket notification pathways are extending development timelines for novel catheter materials requiring expanded biocompatibility evidence.
- External drain substitution:Lumbar drainage systems and non-invasive intracranial pressure monitors are capturing select hydrocephalus management cases.
Strategic Opportunities
- Brazilian hospital system modernization:ANVISA regulatory alignment with international standards is opening procurement channels for antibiotic-impregnated portfolios in São Paulo and Rio de Janeiro neurosurgical centers.
- Digital monitoring convergence:Closed EVD systems with integrated pressure transducers and wireless data transmission are creating premium positioning in tertiary care networks.
- Japanese super-aging infrastructure:PMDA fast-track pathways for neurological devices are accelerating market access for programmable valve technologies in stroke and dementia-related hydrocephalus cases.
Industry Challenges
- Neurocritical care specialist scarcity:Trained intensivists capable of EVD insertion and monitoring protocol management are concentrated in urban academic medical centers.
- EUDAMED vigilance compliance:Post-market surveillance documentation requirements for implantable neurological devices are consuming quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global External Ventricular Drain Market |
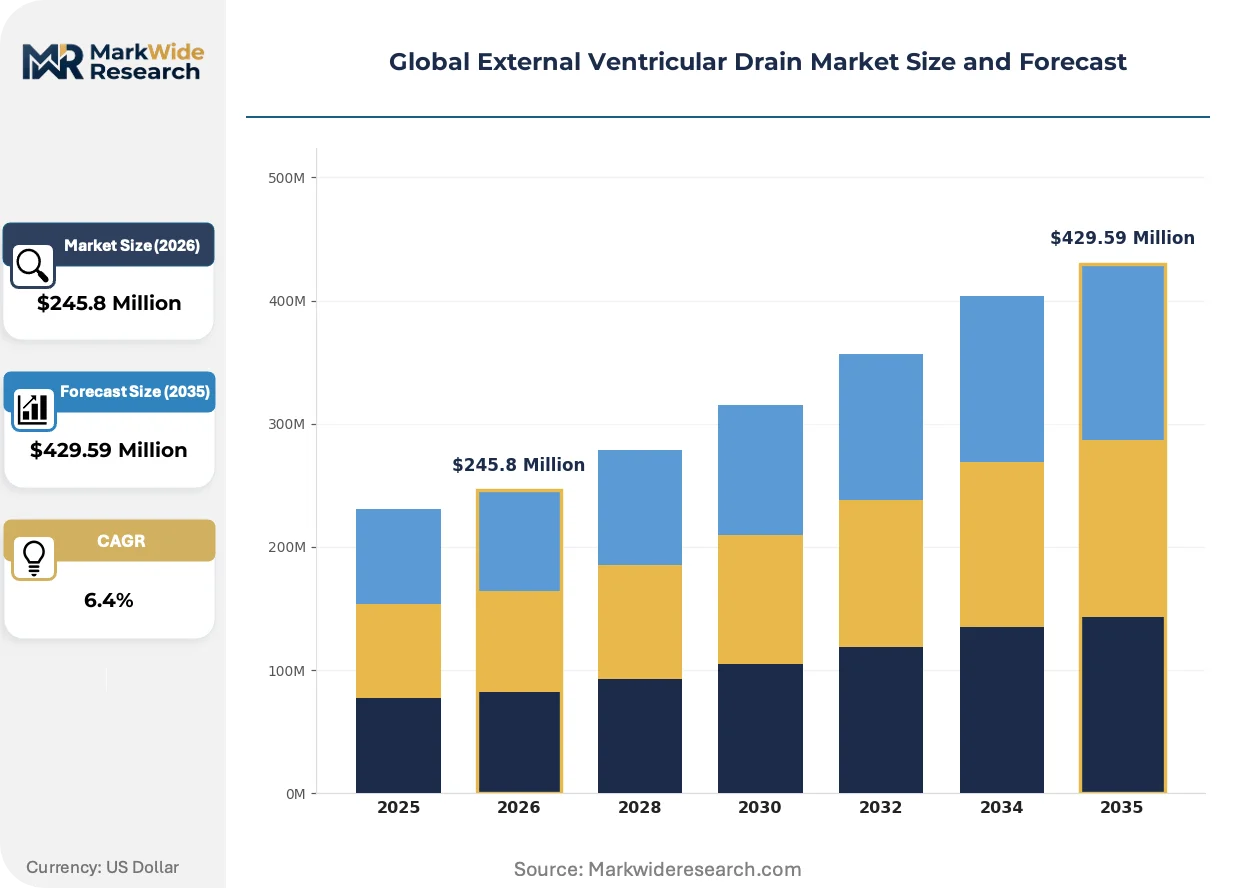
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $429.59 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Drain, Antibiotic-Impregnated Drain, Silver-Coated Drain, Programmable Valve Drain Application: Hydrocephalus Management, Traumatic Brain Injury, Intracranial Hemorrhage, Brain Tumor Treatment, Neurosurgical Procedures End User: Neurosurgical Centers, Specialty Clinics, Critical Care Units, Research Hospitals Technology: Open System, Closed System, Digital Monitoring, Wireless Connectivity |
| Companies Covered | Sophysa, Fuji Systems, Medtronic, B. Braun SE, Neuromedex GmbH, Spiegelberg GmbH & Co. KG, Möller Medical GmbH, Natus Medical Incorporated, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global External Ventricular Drain Market Shifts & Advancements
Digital integration and material science advances are redefining catheter system architecture, with infection control protocols and regulatory evidence requirements determining competitive survival.
Smart pressure-sensing EVD systems with continuous intracranial pressure waveform transmission are miniaturizing traditional gravity-dependent drainage setups. Tertiary neurosurgical centers in Germany and the United States are piloting these integrated platforms for automated alarm integration with electronic health records. The technology is compressing demand for standalone monitoring catheters while elevating software validation requirements.
EU MDR Article 117 and associated implementing acts are mandating clinical evidence standards previously reserved for higher-risk device classes. Manufacturers seeking CE marking for silicone-based drainage systems must now submit post-market clinical follow-up protocols alongside technical documentation. German notified bodies are applying these requirements most stringently, extending conformity assessment timelines for catheter portfolios.
Hospital procurement consortia are consolidating vendor relationships around full neurological critical care portfolios rather than single-product contracts. Integrated device suppliers with catheter, shunt, and monitoring capabilities are displacing standalone EVD manufacturers in European and North American purchasing decisions. This concentration is most visible in German university hospital networks and United States academic medical center systems.
Global External Ventricular Drain Market Segmentation
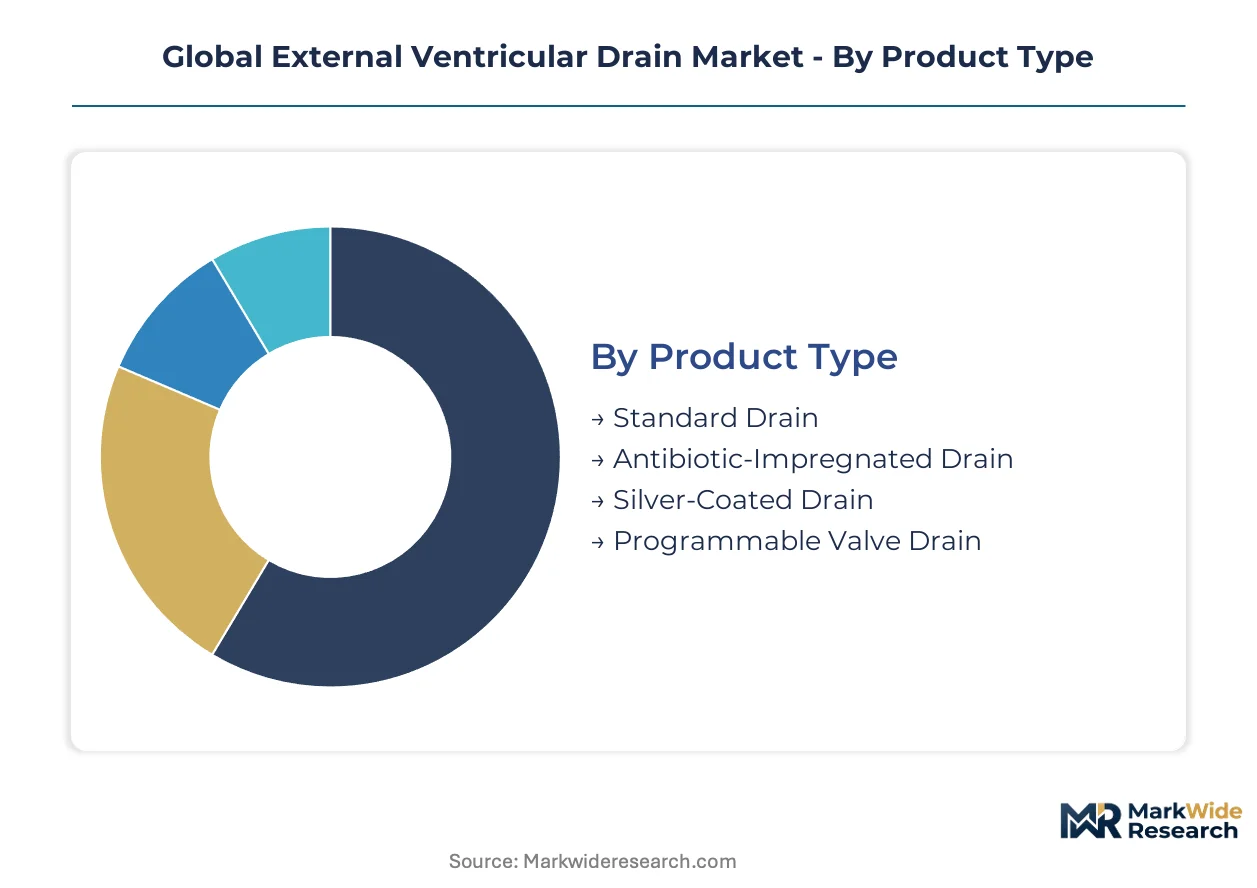
Catheter system architecture varies sharply by clinical setting and infection risk profile. Procurement channels favor integrated suppliers for high-complexity segments while standard drains flow through distributor networks.
Product Type:
Channel mix splits between direct hospital contracting for premium impregnated lines and distributor-mediated procurement for standard silicone drains.
- Antibiotic-Impregnated Drain:Silicone tubing infused with rifampin and minocycline reduces ventriculitis incidence in extended placement scenarios. German university hospital networks and United States academic medical centers concentrate procurement through sole-source agreements with integrated neurosurgical suppliers.
- Standard Drain:Radiopaque silicone construction with proximal depth markers serves cost-sensitive procurement tiers. Emerging hospital systems in Brazil and India route volume through regional medical device distributors lacking notified body relationships for premium portfolios.
- Silver-Coated Drain:Ionic silver surface treatment targets biofilm inhibition with alternative antimicrobial mechanism to antibiotic matrices.
- Programmable Valve Drain:Pressure-adjustable mechanisms enable titrated CSF diversion without surgical revision.
By volume, Standard Drain leads. By growth pace, Antibiotic-Impregnated Drain is climbing the fastest.
Application:
Cost tier stratification separates premium monitoring-integrated systems for trauma protocols from economy gravity-dependent setups for routine hydrocephalus.
- Traumatic Brain Injury:Elevated intracranial pressure management demands continuous waveform monitoring capability. Neurosurgical centers in the United States embed catheter placement into standardized critical care pathways, driving specification for digital pressure transducer integration.
- Hydrocephalus Management:Cerebrospinal fluid diversion for congenital or acquired ventriculomegaly represents the historical volume base. Pediatric and geriatric patient flows concentrate in specialty clinics across Japan and Germany with preference for programmable valve technology.
- Intracranial Hemorrhage:Emergency ventricular access for blood evacuation requires rapid deployment sterile packaging.
- Brain Tumor Treatment:Perioperative pressure management during posterior fossa surgery creates intermittent demand spikes.
- Neurosurgical Procedures:General craniotomy support applications favor disposable standard drain economics.
By procedure volume, Hydrocephalus Management dominates. By technology upgrade intensity, Traumatic Brain Injury is gaining share fastest.
End User:
Customer type determines service bandwidth requirements and training intensity for insertion protocol compliance.
- Neurosurgical Centers:Tertiary referral institutions with 24-hour neurocritical care coverage specify closed system technology with digital monitoring interfaces. These centers in Germany and the United States consolidate procurement around full neurological critical care portfolios rather than single-product contracts.
- Critical Care Units:General intensive care settings with neurosurgical consultation availability require rapid deployment capability and standardized insertion training protocols. Academic medical center networks concentrate demand for integrated pressure monitoring systems.
- Specialty Clinics:Outpatient hydrocephalus management facilities favor programmable valve technology for ambulatory pressure adjustment.
- Research Hospitals:Clinical trial infrastructure creates demand for novel material formulations and wireless data transmission platforms.
By installed base, Neurosurgical Centers lead. By capability expansion, Critical Care Units show steepest demand trajectory.
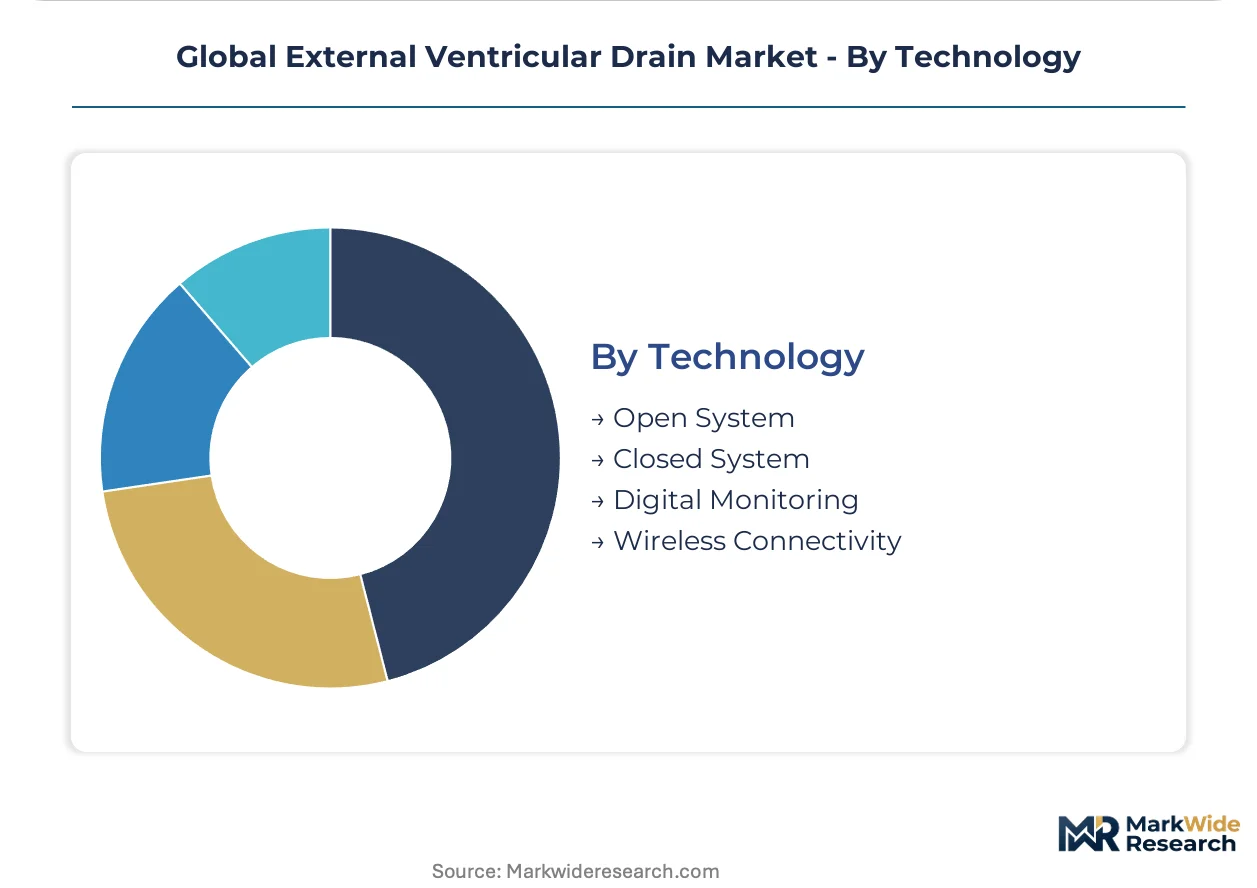
Technology:
Supply concentration for sensor components and wireless modules shapes competitive access to integrated system segments.
- Closed System:Sealed sterile circuits with integrated collection chambers minimize infection risk in extended placement. German university hospital networks and United States tertiary centers mandate closed architecture for neurocritical care protocol compliance.
- Digital Monitoring:Continuous intracranial pressure waveform transmission with automated alarm integration enables electronic health record connectivity. Pilot deployments in German and United States academic medical centers are compressing demand for standalone monitoring catheters.
- Open System:Gravity-dependent drainage with manual drip chamber observation occupies cost-sensitive procurement tiers.
- Wireless Connectivity:Bluetooth or proprietary protocols for remote pressure data transmission reduce bedside clutter.
By current deployment, Open System leads. By substitution pace, Digital Monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and university hospital networks concentrate procurement authority in the United States, Germany, and Japan, while emerging neurosurgical infrastructure in Brazil and India creates secondary demand nodes for standard drain systems.
United States
Traumatic brain injury protocol standardization and neurocritical care fellowship expansion drive catheter placement volumes. FDA 510(k) premarket notification pathways enforce biocompatibility documentation for silicone-based systems. Major academic medical centers in Boston, Baltimore, and Houston consolidate procurement around integrated neurological critical care portfolios.
Germany
University hospital networks prioritize antibiotic-impregnated catheter portfolios for extended placement scenarios. EU MDR Article 117 and notified body conformity assessments extend technical documentation timelines for silicone drainage systems. The Rhine-Ruhr and Baden-Württemberg clusters concentrate manufacturing of medical-grade silicone feedstock and valve assembly production.
Japan
Super-aging demographics and stroke-related hydrocephalus incidence elevate demand for programmable valve technologies. PMDA fast-track pathways for neurological devices accelerate regulatory timelines for digital monitoring integration. The Kanto region around Tokyo anchors neurosurgical device distribution networks serving tertiary referral institutions.
Brazil
ANVISA regulatory alignment with international standards opens procurement channels for premium catheter portfolios in São Paulo and Rio de Janeiro. Hospital system modernization programs expand neurosurgical service lines beyond historical concentration in southeastern states. Public-private partnerships in Minas Gerais and Paraná build critical care infrastructure for trauma referral networks.
India
Trauma center designation expansion and medical tourism infrastructure create demand for cost-sensitive standard drain systems. CDSCO medical device rules implement risk-based classification for neurological implantables. Metropolitan hospital networks in Delhi-NCR, Maharashtra, and Karnataka concentrate neurosurgical procedure volumes and distributor relationships.
Global External Ventricular Drain Market Competitive Landscape
Player mix skews toward diversified neurosurgical device conglomerates with catheter manufacturing capabilities and specialized valve engineering boutiques. Tiered competitive structure separates integrated portfolio suppliers from standalone drain manufacturers. Strategic archetypes include full neurological critical care suite providers, programmable valve specialists, and regional silicone component fabricators. Dominant competitive moves center on notified body relationship consolidation under EU MDR and backward integration into medical-grade silicone compounding.
Within the diversified conglomerate tier, Medtronic and B. Braun SE exemplify integrated supply positions spanning catheter systems, shunt technologies, and monitoring platforms. Sophysa occupies a specialist position focused on programmable pressure valve engineering. Among German-based component fabricators, Spiegelberg GmbH & Co. KG and Möller Medical GmbH represent regional manufacturing depth in silicone tubing and precision valve assemblies. These named entities anchor competitive archetypes rather than exhaust market participation.
| Leading Market Players |
|---|
| Sophysa |
| Fuji Systems |
| Medtronic |
| B. Braun SE |
| Neuromedex GmbH |
| Spiegelberg GmbH & Co. KG |
| Möller Medical GmbH |
| Natus Medical Incorporated |
| Integra LifeSciences |
| Others |
Supply & Pricing Matrix
Medical-grade silicone compounding scale economies in Germany and the United States anchor both supply concentration and price floors for catheter systems, with multi-year hospital procurement contracts indexing raw material costs to petrochemical benchmarks.
Pricing Analysis
Cost-plus contracts with silicone feedstock indexation dominate procurement between German manufacturers and university hospital networks. Pricing stratifies across antibiotic-impregnated premium tiers, standard radiopaque mid-market lines, and economy drains for emerging systems, with differentiation driven by FDA 510(k) clearance status and infection control certification. Pricing pressure stems from EU MDR conformity cost absorption as notified body fees compress margins on legacy portfolios. Emerging hospital systems in Brazil and India exhibit highest price sensitivity, while United States academic medical centers prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Six-to-nine month lead times for medical-grade silicone tubing constrain inventory flexibility across catheter assembly lines in Germany, the United States, and Japan. Feedstock production draws from Rhineland petrochemical clusters and Texas Gulf Coast specialty polymer facilities, with precision valve components sourced from Baden-Württemberg machining centers. Single-source vulnerability concentrates in rifampin-minocycline matrix suppliers for antibiotic-impregnated lines. Distribution runs through regional medical device distributors in emerging markets and direct hospital contracting networks in established neurosurgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consortium consolidation in Germany and the United States has shifted negotiating leverage toward integrated device suppliers, fragmenting standalone EVD manufacturers into price-taker positions.
For Market Incumbents: Secure notified body relationships under EU MDR Article 117 to defend CE marking timelines against emerging entrants lacking technical documentation bandwidth. Anchor backward integration into medical-grade silicone compounding to offset petrochemical price volatility threatening standard drain margins. Prioritize software validation investments for digital monitoring platforms as smart EVD systems displace standalone catheter demand in tertiary centers. For New Entrants and Emerging Players: Anchor in Brazilian neurosurgical center modernization programs where ANVISA alignment with international standards creates procurement access without legacy EU MDR compliance burdens. Target cost-sensitive standard drain segments in Indian trauma center expansion markets through regional distributor partnerships. Differentiate via silver-coated antimicrobial alternatives to antibiotic-impregnated portfolios facing rifampin supply constraints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among programmable valve specialists with hospital service contracts for pressure adjustment protocols. Five-to-ten year viability favors integrated neurological critical care portfolio suppliers over standalone drain manufacturers facing procurement exclusion. Monitor FDA Medical Device Reporting volume trends for infection-related adverse events as signal for antibiotic-impregnated portfolio acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Consolidation | CE marking timelines for silicone drainage systems extend as German notified bodies apply Article 117 most stringently. |
| Digital Monitoring Platform Integration | Closed EVD systems with wireless pressure transmission capture premium positioning in United States academic medical centers. |
| Antibiotic-Impregnated Portfolio Expansion | Rifampin-minocycline matrix supply agreements secure ventriculitis reduction claims for extended placement scenarios. |
| Brazilian Hospital System Partnership | ANVISA regulatory alignment opens procurement channels in São Paulo neurosurgical centers without EU conformity costs. |
| Medical-Grade Silicone Backward Integration | In-house compounding of radiopaque tubing formulations insulates margin from petrochemical benchmark volatility. |
Research Methodology
A spread of perspectives from neurocritical care intensivists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions, validated against FDA 510(k) filings, EUDAMED vigilance modules, hospital procurement databases, and German notified body technical documentation requirements. Bottom-up catheter placement volume estimates triangulated with top-down neurological device market sizing.
Segmentation dimensions modeled span product architecture, clinical application, end-user facility type, and technology integration level across the analysis window. CAGRs derived from procedure volume trajectories, technology substitution curves, and procurement contract renewal patterns. Forecast inputs incorporated EU MDR implementation timelines and PMDA fast-track pathway utilization for programmable valve technologies.
Material uncertainties — regulatory evidence requirement expansion, neurocritical care specialist availability constraints, and antimicrobial resistance profiles — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Cardiovascular Repair and Reconstruction Devices Market