
 Smart Patches Market | 2026-2036
Smart Patches Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Patches Market Outlook
A shortage of biomedical engineers trained in flexible electronics fabrication is redrawing competitive boundaries across the Smart Patches landscape. Abbott Laboratories leverages its vertically integrated sensor manufacturing to sustain cost advantages in continuous glucose monitoring substrates. Dexcom anchors North American demand through direct-to-consumer channel control and automated adhesive replacement logistics.
Smart patches are thin, conformable adhesive systems integrating microelectronic circuits, biosensors, and wireless transceivers for physiological data acquisition or transdermal substance delivery, typically operating at sub-millimeter thickness with power budgets under one milliwatt. Their primary purpose spans remote cardiac rhythm surveillance, metabolic biomarker tracking, and programmed drug release across ambulatory care settings. Wearable sensors capture the largest revenue pool among product types due to recurring consumable attachment requirements, while diagnostic patches represent the fastest-expanding segment as healthcare systems shift toward decentralized laboratory alternatives. Flexible electronics technology leads manufacturing investment because polyimide and liquid metal interconnects enable multi-day skin adhesion without signal degradation.
FDA premarket notification pathways for Class II wearable diagnostics shape product development timelines and predicate device selection strategies for manufacturers seeking US market entry. EMA medical device regulation and ISO 13485 quality management standards govern European commercialization, while Japan's PMDA enforces unique clinical trial requirements for software-as-a-medical-device components embedded in patch platforms. Stakeholders must monitor evolving cybersecurity guidance from multiple regulators as wireless communication protocols proliferate across connected patch ecosystems.
Market Dynamics
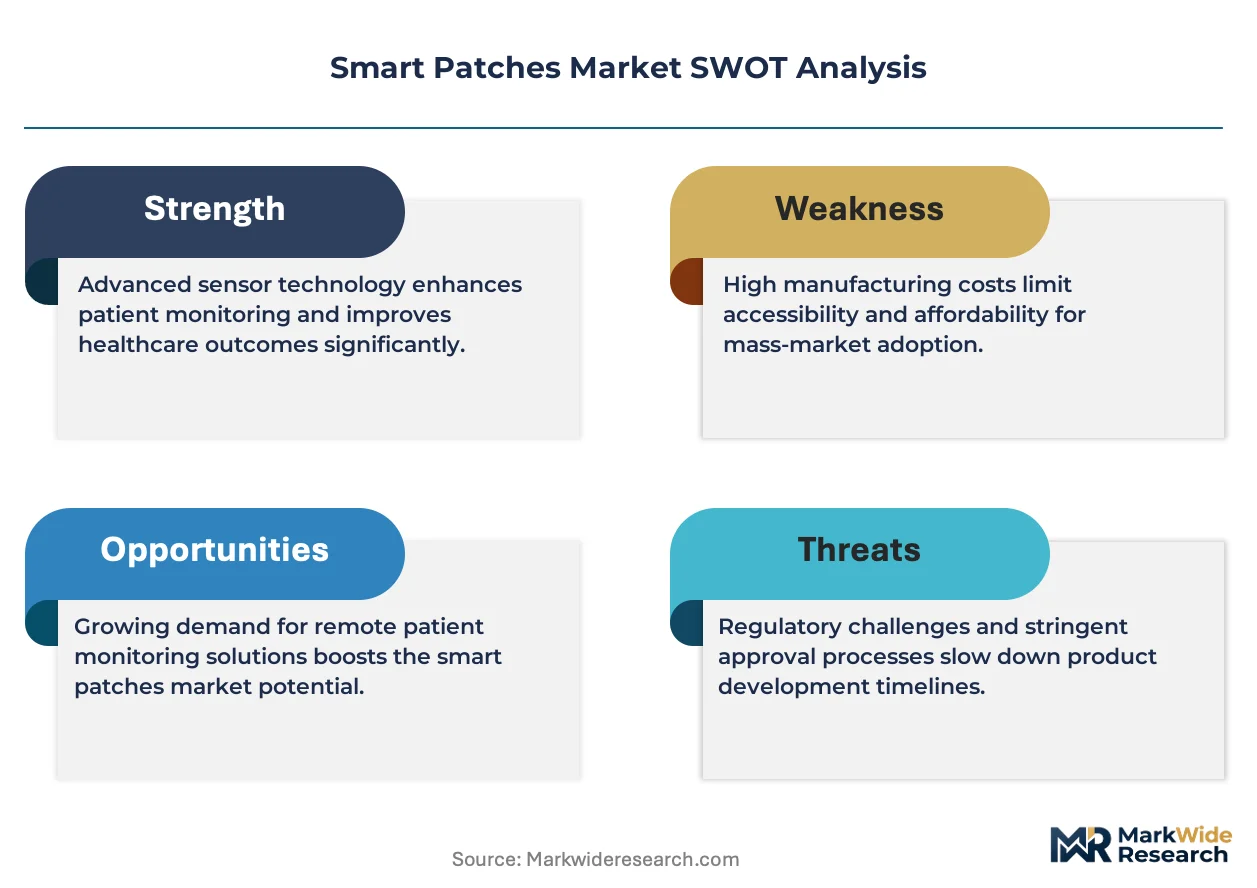
The convergence of FDA breakthrough device pathways with hospital system procurement consolidation is compressing commercialization timelines while elevating clinical evidence requirements for patch-based diagnostics.
Growth Catalysts
- Reimbursement maturation:CMS remote therapeutic monitoring codes in the United States now cover ambulatory cardiac patch monitoring, accelerating hospital system adoption of disposable wearable sensors.
- Flexible substrate advances:Polyimide-copper laminate manufacturing from semiconductor foundries is reducing per-unit sensor costs for multi-day adhesion applications.
- Cardiology department expansion:Hospital systems in Germany and Japan are deploying patch-based arrhythmia detection as first-line screening before Holter monitor referral.
Market Restraints
- Silver nanowire supply concentration:Transparent conductor sourcing clusters in East Asian chemical processors, exposing manufacturers to input cost volatility and geopolitical supply friction.
- Adhesive biocompatibility limitations:Current silicone-acrylate blends trigger dermatological adverse events in 12-18% of multi-day wear patients, constraining clinical trial enrollment.
- Software-as-medical-device complexity:PMDA algorithm validation requirements for AI-embedded patches extend Japanese regulatory timelines by 8-14 months versus hardware-only submissions.
Strategic Opportunities
- Underpenetrated metabolic monitoring:Continuous ketone and lactate tracking in athletic and critical care settings remains commercially nascent despite validated sensor chemistry.
- Pharmacy channel integration:CVS and Walgreens pilot programs for direct-to-consumer glucose patch fulfillment bypass traditional durable medical equipment distribution.
- EU MDR Article 117 convergence:Drug-device combination patch manufacturers can leverage notified body partnerships to accelerate transdermal delivery system approvals.
Industry Challenges
- Biomedical engineering talent scarcity:Flexible electronics fabrication requires hybrid skill sets spanning MEMS processing and clinical validation, with fewer than 200 qualified professionals graduating annually from US and European programs.
- Wireless coexistence certification:FCC Part 15 and ETSI EN 300 328 testing for multi-protocol patches (Bluetooth Low Energy, NFC, proprietary ISM) extends pre-market engineering cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Patches Market |
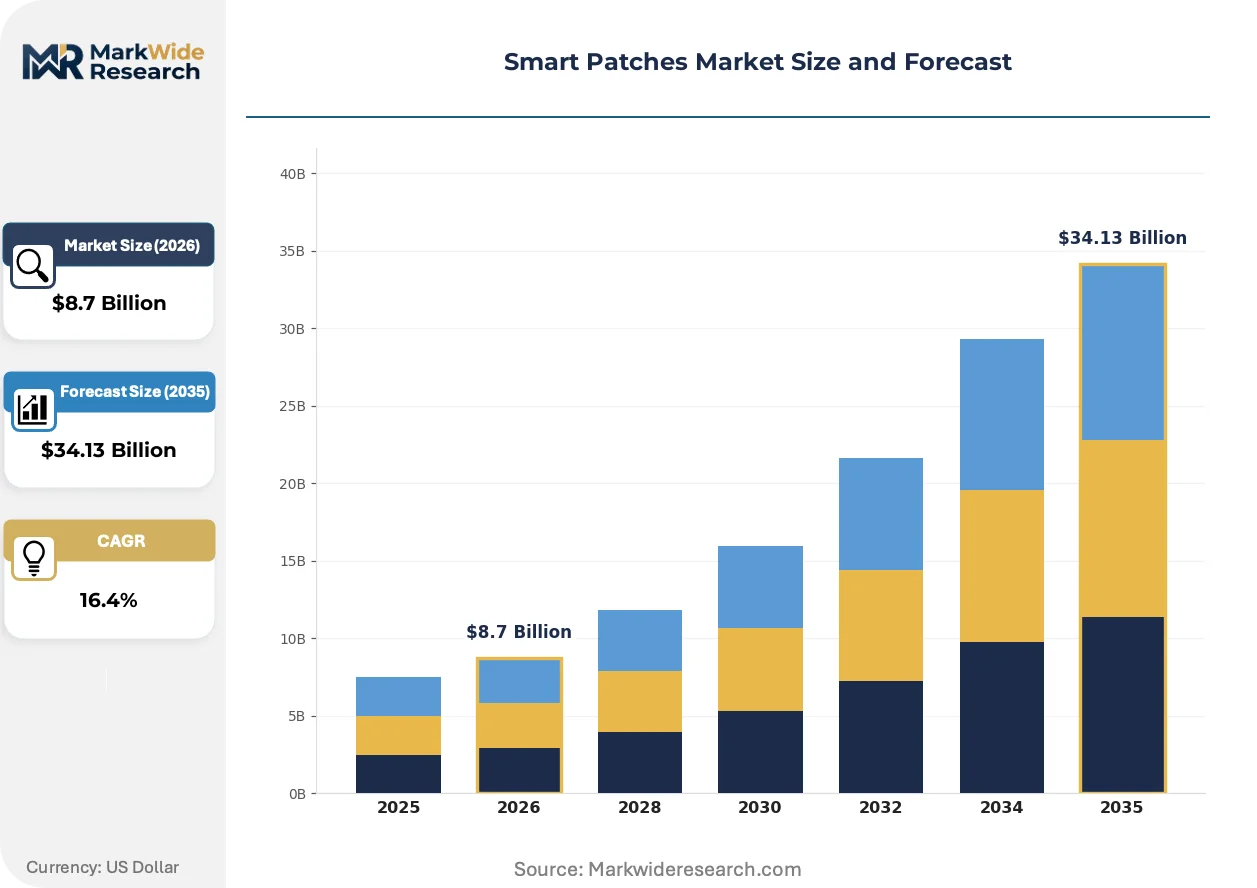
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transdermal, Wearable Sensors, Drug Delivery Systems, Diagnostic Patches Technology: Microfabrication, Biosensors, Wireless Communication, Flexible Electronics Application: Chronic Disease Management, Fitness Monitoring, Pain Relief, Skin Condition Treatment End User: Healthcare Providers, Patients, Research Institutions, Pharmaceutical Companies |
| Companies Covered | Koninklijke Philips, Qualcomm, Abbott Laboratories, Masimo, GE Healthcare, Medtronic, iRhythm Technologies, Senseonics, Dexcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Patches Market Strategic Shifts
Materials science breakthroughs in stretchable conductors and algorithmic compression of biometric signal processing are collapsing the form-factor and power-consumption constraints that previously limited ambulatory monitoring duration.
Liquid metal gallium-indium-tin interconnects are displacing traditional copper-trace flex circuits in next-generation cardiac patches. Medtronic and Boston Scientific engineering divisions have transitioned pilot production lines to liquid metal deposition for arrhythmia monitoring substrates. The technology is displacing conventional wire-bonding approaches that failed under cyclic skin deformation, enabling 14-day continuous wear without signal degradation.
EMA Medical Device Regulation Article 10.4 post-market surveillance requirements now mandate periodic safety update reports for all Class IIa and above wearable diagnostics. Manufacturers must submit real-world performance data from connected patch ecosystems annually, forcing investment in cloud infrastructure for adverse event detection. Cardiology patch vendors with EU market presence are consolidating post-market clinical follow-up under single quality management systems to streamline PSUR preparation.
Hospital procurement committees have begun unbundling sensor hardware from data interpretation services, creating separate contracting lanes for disposable patch supply and algorithmic analysis. IDN purchasing organizations in Texas and California now negotiate adhesive consumables through group purchasing organizations while contracting AI diagnostics directly with software vendors. This bifurcation is most advanced in United States health systems where remote patient monitoring reimbursement separates device from professional component billing.
Smart Patches Market Segmentation
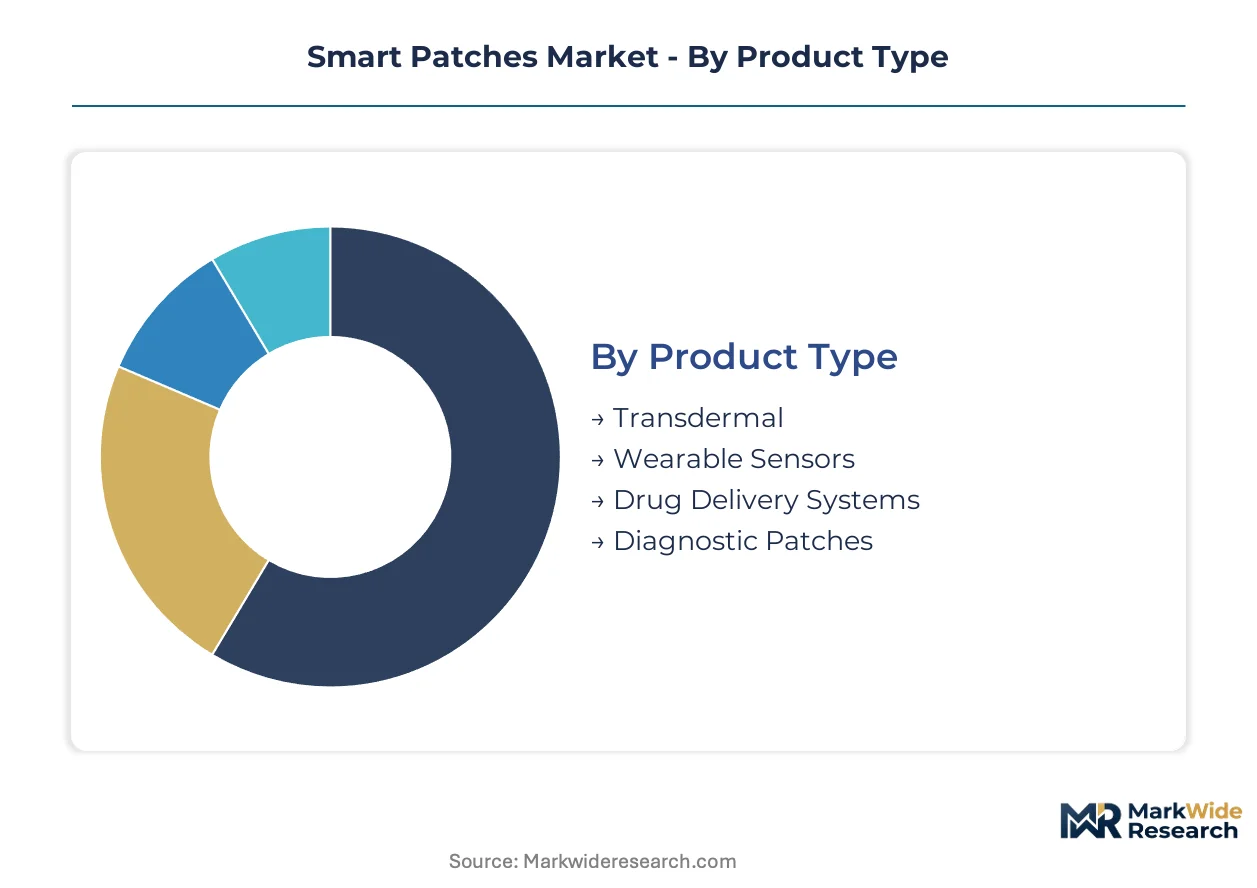
Smart patches fragment across four orthogonal dimensions that determine manufacturing investment priorities and regulatory pathway selection. Product type dictates consumable versus capital equipment business models, while technology choices lock in semiconductor foundry partnerships or polymer chemistry supply chains.
Product Type:
Wearable sensors and transdermal systems anchor domestic production in the United States and Germany, while drug delivery patches flow through export-led supply chains centered on Swiss and Japanese pharmaceutical contract manufacturers.
- Transdermal:Pressure-sensitive adhesive matrices enable passive diffusion of nicotine, hormones, or analgesics across the stratum corneum. Hospital systems in Germany favor transdermal fentanyl patches for post-operative pain protocols, though silicone adhesive shortages constrain multi-week wear formulations.
- Wearable Sensors:Multi-layer flex circuits integrate electrochemical electrodes with Bluetooth Low Energy transceivers for continuous biomarker streaming. Abbott Laboratories and Dexcom dominate United States demand through automated adhesive replacement logistics and direct-to-consumer channel control.
- Drug Delivery Systems:Iontophoretic or microneedle platforms enable programmable bolus release of biologics. Swiss contract manufacturers specialize in high-value peptide delivery patches for European endocrinology clinics.
- Diagnostic Patches:Single-use colorimetric or electrochemical assays replace centralized laboratory workflows. Japanese PMDA software-as-medical-device requirements extend regulatory timelines for AI-embedded diagnostic substrates.
Wearable sensors command the established base. The steepest expansion runs through diagnostic patches.
Technology:
Cost tier stratification separates semiconductor-foundry-dependent processes from specialty chemical deposition, with microfabrication commanding premium pricing and flexible electronics penetrating mid-tier ambulatory monitoring contracts.
- Microfabrication:Photolithographic patterning of silicon or glass substrates creates micron-scale fluidic channels and electrode arrays. United States-based MEMS foundries in California and Massachusetts supply cardiology patch startups with wafer-level packaging for arrhythmia detection.
- Biosensors:Enzyme-functionalized electrodes or aptamer-coated surfaces enable selective molecular recognition. Continuous ketone and lactate tracking for athletic and critical care applications remains commercially nascent despite validated sensor chemistry.
- Wireless Communication:NFC, Bluetooth Low Energy, and proprietary ISM-band protocols transmit encrypted physiological data. FCC Part 15 and ETSI EN 300 328 certification cycles extend pre-market engineering timelines by 4-6 months for multi-protocol patches.
- Flexible Electronics:Polyimide-copper laminates or liquid metal gallium-indium-tin interconnects enable skin-conformal circuitry. Medtronic and Boston Scientific engineering divisions have transitioned pilot production to liquid metal deposition for 14-day cardiac monitoring substrates.
Flexible electronics anchors the installed revenue base. Biosensors are climbing the fastest as decentralized laboratory alternatives proliferate.
Application:
Customer type bifurcation separates institutional procurement through hospital IDNs from direct-to-consumer pharmacy fulfillment, with chronic disease management flowing through reimbursement channels and fitness monitoring bypassing traditional durable medical equipment distribution.
- Chronic Disease Management:Continuous glucose monitoring for diabetes and cardiac rhythm surveillance for atrial fibrillation dominate clinical deployment. CMS remote therapeutic monitoring codes now cover ambulatory cardiac patch monitoring, accelerating United States hospital system adoption.
- Fitness Monitoring:Lactate, hydration, and electrolyte tracking for athletic optimization. Underpenetrated metabolic monitoring in professional sports medicine creates whitespace for sensor chemistry vendors with validated continuous ketone platforms.
- Pain Relief:Lidocaine, capsaicin, or NSAID delivery through hydrogel or reservoir-based patches. German pharmacy chains stock transdermal analgesics as first-line alternatives to oral NSAIDs for osteoarthritis patients.
- Skin Condition Treatment:Microneedle or dissolving microarray patches for psoriasis, acne, or dermatological drug delivery. Japanese cosmetic dermatology clinics pilot programmable retinol release for personalized skincare protocols.
Chronic disease management commands the established base. Fitness monitoring is gaining share fastest as athletic performance optimization crosses into consumer wellness.
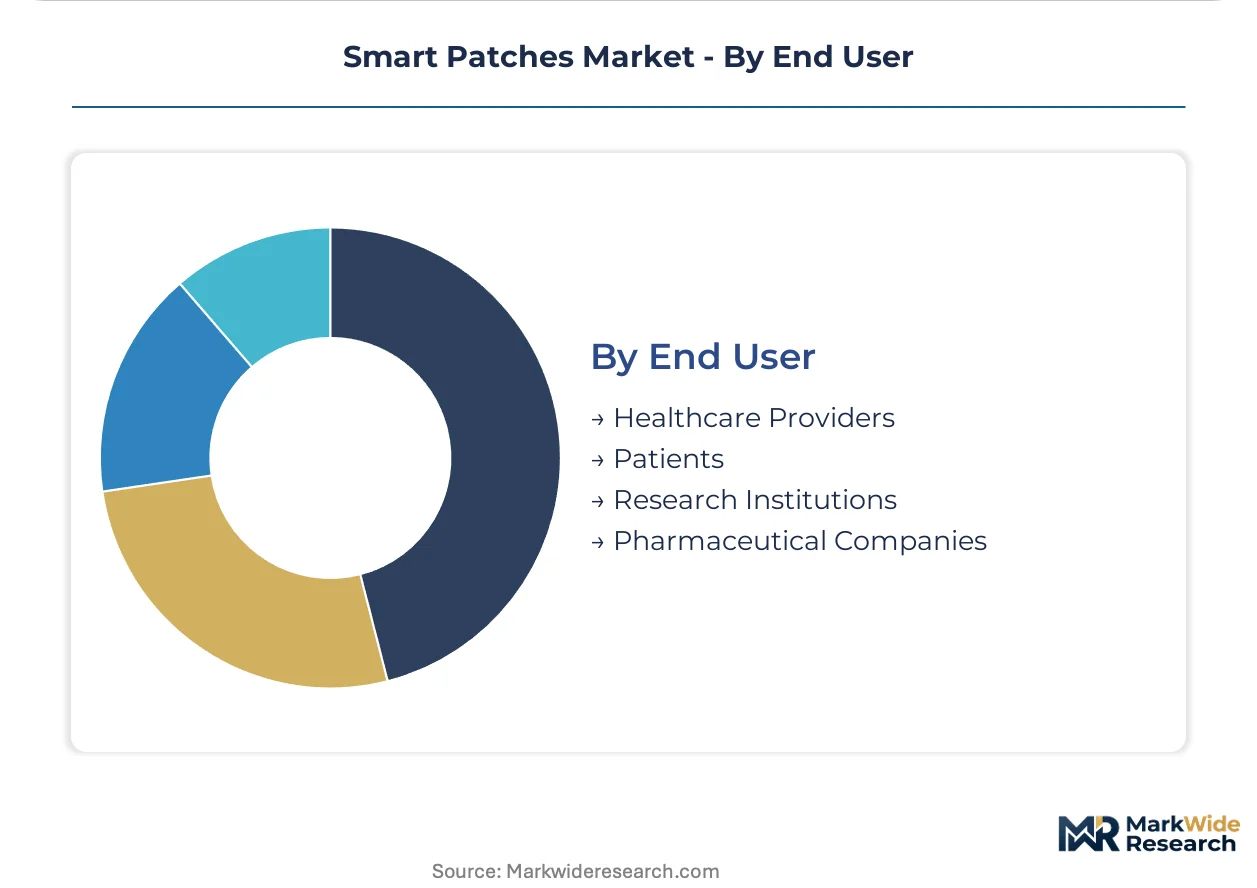
End User:
Volume concentration clusters in healthcare provider procurement, though patient-direct channels are reshaping distribution economics through CVS and Walgreens pilot programs for glucose patch fulfillment.
- Healthcare Providers:Hospital cardiology departments and outpatient clinics deploy patch-based arrhythmia detection as first-line screening before Holter monitor referral. IDN purchasing organizations in Texas and California unbundle sensor hardware from algorithmic analysis services.
- Patients:Direct-to-consumer acquisition of continuous glucose monitors, fertility trackers, or pain management patches. Pharmacy channel integration bypasses traditional durable medical equipment distribution for recurring adhesive consumables.
- Research Institutions:Academic medical centers and contract research organizations validate novel biomarker detection platforms. FDA breakthrough device designations for continuous glucose monitoring wearables accelerate clinical validation requirements for investigational patches.
- Pharmaceutical Companies:Drug-device combination patch development for lifecycle management of oral therapeutics. EU MDR Article 117 convergence enables notified body partnerships to accelerate transdermal delivery system approvals.
Healthcare providers anchor the revenue base. Patient-direct channels are expanding most quickly as reimbursement pathways for ambulatory monitoring mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals deploy smart patches primarily for cardiac rhythm surveillance and glucose monitoring, while German and Japanese health systems emphasize transdermal drug delivery and arrhythmia screening protocols. This consumption-mix differential reflects varying reimbursement architectures and clinical workflow priorities across mature ambulatory monitoring markets.
United States
Hospital system procurement consolidation and IDN purchasing organizations in Texas and California are unbundling sensor hardware from algorithmic analysis services. CMS remote therapeutic monitoring codes now cover ambulatory cardiac patch monitoring, accelerating disposable wearable sensor adoption. Greater Boston and California's semiconductor clusters supply MEMS foundry capacity for cardiology patch startups.
Germany
Hospital cardiology departments deploy patch-based arrhythmia detection as first-line screening before Holter monitor referral, with transdermal fentanyl patches favored for post-operative pain protocols. EMA Medical Device Regulation Article 10.4 mandates periodic safety update reports for Class IIa and above wearable diagnostics, forcing cloud infrastructure investment. Baden-Württemberg's precision engineering base supports polyimide-copper laminate manufacturing for multi-day adhesion applications.
Japan
Cosmetic dermatology clinics in Tokyo pilot programmable retinol release patches for personalized skincare protocols, while PMDA software-as-medical-device requirements extend regulatory timelines for AI-embedded diagnostics. METI funding for flexible electronics R&D accelerates liquid metal interconnect commercialization. Kansai region pharmaceutical contract manufacturers specialize in high-value peptide delivery patches for endocrinology clinics.
Switzerland
Swissmedic oversees drug-device combination patch approvals, with notified body partnerships enabling accelerated transdermal delivery system clearances under EU MDR Article 117 convergence. Swiss contract manufacturers dominate high-value biologics patch production for European endocrinology markets. Basel and Zurich clusters anchor pharmaceutical lifecycle management programs converting oral therapeutics to transdermal formats.
United Kingdom
NHS procurement frameworks prioritize cost-effective ambulatory monitoring solutions, with London-based hospital trusts piloting remote patient monitoring programs for chronic disease management. MHRA post-Brexit regulatory alignment with EU MDR maintains CE marking recognition for patch-based diagnostics. Southeast England's medtech corridor hosts biosensor startups developing continuous ketone and lactate tracking platforms.
Smart Patches Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Smart Patches competitive structure. Vertically integrated sensor manufacturers control substrate fabrication and adhesive chemistry, while software-centric vendors concentrate on algorithmic diagnostics and data interpretation services. Three archetypes dominate: semiconductor-foundry-dependent hardware specialists, pharmaceutical-contract-manufacturing hybrids, and AI-embedded diagnostic platform builders. Competitive moves center on foundry partnership consolidation and automated logistics infrastructure for recurring consumable replacement.
Among North American technology-anchored players, Qualcomm and Dexcom occupy positions at the wireless communication and continuous glucose monitoring vectors respectively. Koninklijke Philips exemplifies the diversified health technology conglomerate archetype, spanning diagnostic hardware through clinical informatics. These three represent distinct strategic postures within the tiered competitive landscape.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Qualcomm |
| Abbott Laboratories |
| Masimo |
| GE Healthcare |
| Medtronic |
| iRhythm Technologies |
| Senseonics |
| Dexcom |
| Others |
Value Chain & Pricing Dynamics
Long-term adhesive substrate offtake agreements between United States hospital IDNs and polyimide-copper laminate manufacturers lock in supply access while providing 12-18 month price visibility for multi-day cardiac monitoring patches. This contract-structure pattern insulates procurement committees from silver nanowire volatility while tethering cost forecasting to foundry capacity reservation schedules.
Pricing Analysis
Long-term offtake contracts dominate the procurement landscape for disposable wearable sensors, with pricing stratifying across FDA breakthrough device tier, ISO 13485 certification status, and automated logistics integration depth. Price differentiation hinges on adhesive biocompatibility grade and wireless protocol certification breadth, with Bluetooth-NFC multi-protocol patches commanding premium positioning. Cost compression in standard-tier glucose monitoring substrates is intensifying because polyimide-copper laminate manufacturing from semiconductor foundries is reducing per-unit sensor costs. Pharmacy channel buyers exhibit highest price sensitivity due to direct-to-consumer reimbursement gaps, while hospital cardiology departments prioritize clinical validation depth over unit economics.
Supply Chain Analysis
United States and Germany anchor polyimide-copper laminate manufacturing for flexible electronics substrates, while East Asian chemical processors concentrate transparent conductor production for transparent electrode applications. Raw material dependencies span liquid metal gallium-indium-tin alloys, silver nanowire suspensions, and medical-grade silicone-acrylate adhesive blends. Single-source vulnerability in East Asian silver nanowire supply exposes manufacturers to geopolitical friction and input cost volatility. Distribution runs through hospital IDN procurement committees in Texas and California, with direct-to-consumer pharmacy channels bypassing traditional durable medical equipment distribution for recurring adhesive consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity permeates the Smart Patches landscape as hospital procurement committees unbundle sensor hardware from algorithmic analysis services, creating separate contracting lanes for adhesive consumables and AI diagnostics.
For Market Incumbents: Shield market position through captive supply of polyimide-copper laminate substrates and automated adhesive replacement logistics infrastructure. Defensive consolidation moves center on backward integration into flexible electronics foundry partnerships and certification investment in FDA breakthrough device pathways. Threat from software-centric diagnostic platform builders intensifies as IDN purchasing organizations contract AI analytics directly with algorithm vendors. For New Entrants and Emerging Players: Anchor in underpenetrated metabolic monitoring segments, specifically continuous ketone and lactate tracking for athletic and critical care applications where validated sensor chemistry remains commercially nascent. White-space targets concentrate on fitness monitoring for professional sports medicine and decentralized laboratory alternatives in diagnostic patches. Go-to-market execution prioritizes pharmacy channel integration through CVS and Walgreens pilot programs for direct-to-consumer fulfillment. For Investors and Strategic Acquirers: Liquid metal interconnect specialists with MEMS processing capabilities and clinical validation track records represent the highest-conviction acquisition target archetype. Long-term viability framing centers on 5-10 year regulatory pathway maturation and reimbursement expansion for ambulatory monitoring. Signal to monitor: CMS remote therapeutic monitoring code expansion beyond cardiac applications into metabolic and respiratory domains.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | FDA breakthrough designation accelerates clinical validation timelines for continuous glucose monitoring substrates. |
| Hospital System Partnership | IDN procurement consolidation in Texas and California creates preferred vendor status for adhesive consumable suppliers. |
| CE Marking Pathway | EMA MDR Article 10.4 compliance mandates cloud infrastructure investment for periodic safety update reporting. |
| Software Companion Development | PMDA algorithm validation requirements for AI-embedded patches extend Japanese regulatory timelines versus hardware-only submissions. |
| Reimbursement Strategy | CMS remote therapeutic monitoring codes now cover ambulatory cardiac patch monitoring, accelerating hospital adoption. |
Study Parameters
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and flexible electronics foundry executives anchors the qualitative findings against secondary validation from FDA 510(k) filings, EMA medical device registration databases, CMS Medicare reimbursement data, and hospital procurement contract repositories. Bottom-up demand modeling triangulates with top-down market sizing across product type, technology, application, and end user segmentation dimensions.
Sensitivity analysis framing governs the analytical approach across the analysis window, with volume and value outputs reflecting modeled trajectories for wearable sensors, transdermal systems, drug delivery platforms, and diagnostic patches. Segmentation dimensions span product type, flexible electronics technology tier, chronic disease management application cluster, and healthcare provider versus patient-direct end user channel. CAGRs derive from regression analysis against historical adoption curves and reimbursement pathway maturation timelines, with specific inputs including adhesive biocompatibility validation rates and wireless coexistence certification cycle durations.
Material uncertainties — adhesive dermatological adverse event rates, silver nanowire supply disruption, PMDA software-as-medical-device timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory pathway convergence and reimbursement code expansion. Recalibration cycles align with material shifts in CMS coverage determinations and EU MDR notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Rectal Catheters Market
Medical Devices
Global Bowel Management System Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Consumer Grade EEG Device Market
Medical Devices
Global Next Generation Surgical Robotics Market
Medical Devices
Colposcopes Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Blood Collection Devices Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Water Bath Vaporizer Market