
 Cystic Fibrosis Devices Market | 2026-2036
Cystic Fibrosis Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cystic Fibrosis Devices Market Analytics
Smart nebulizer connectivity is fragmenting traditional device categories into app-integrated, data-generating platforms. Vertex Pharmaceuticals Incorporated leverages its cystic fibrosis therapeutic franchise to anchor adjacent device ecosystems. Smiths Medical, Inc. dominates airway clearance hardware through hospital procurement channels. Teva Pharmaceutical Industries Ltd. competes in mesh nebulizer generics across European reimbursement markets.
Cystic fibrosis devices encompass mechanical and electronic systems designed to clear thickened mucus from airways, deliver aerosolized medications to the lungs, and monitor respiratory function through spirometry and oscillometry parameters. These systems employ piezoelectric mesh vibration, positive expiratory pressure valves, or high-frequency chest wall oscillation to achieve therapeutic endpoints in patients with defective CFTR protein function. Inhalers and nebulizers capture the largest revenue pool due to chronic daily medication requirements, while diagnostic equipment represents the fastest-growing segment as newborn screening expands and biomarker-based monitoring protocols proliferate. Chest physiotherapy devices retain stable demand in acute care settings where manual percussion remains standard protocol.
The FDA regulates these products under combination product rules when paired with specific drug formulations, while the EMA's Medical Device Regulation imposes clinical evidence requirements on higher-class respiratory devices. The EU F-Gas Regulation restricts propellant choices in metered-dose inhalers, forcing reformulation investments across European supply chains. Stakeholders must monitor how real-world evidence requirements from CMS and private payors reshape the economic viability of connected device features versus basic mechanical alternatives.
Market Dynamics
The cystic fibrosis devices market is being fundamentally reshaped by the FDA's breakthrough device designation pathway, which compresses regulatory timelines and incentivizes manufacturers to develop connected, data-generating respiratory platforms rather than standalone mechanical hardware.
Growth Catalysts
- Newborn screening mandates:State-level expansion of heel-prick testing protocols in the United States and comparable programs across European health systems are expanding the addressable patient base for diagnostic spirometry and monitoring equipment.
- EU F-Gas Regulation:Propellant restrictions on hydrofluorocarbons in metered-dose inhalers are forcing manufacturers to invest in dry powder and mesh nebulizer alternatives, accelerating device portfolio modernization.
- Homecare reimbursement codes:CMS and private payors in the United States have established specific billing categories for portable airway clearance systems, shifting treatment volume from acute care settings to residential environments.
Market Restraints
- Piezoelectric component concentration:Mesh nebulizer manufacturing depends on precision ceramic suppliers concentrated in East Asian electronics clusters, creating input vulnerability for European and North American device assemblers.
- EMA MDR clinical evidence requirements:Higher-class respiratory devices now require substantial clinical validation dossiers, extending time-to-market and elevating development costs for mid-cap manufacturers without existing therapeutic franchises.
- Manual percussion substitution:Acute care protocols in cost-constrained hospital systems continue to favor trained respiratory therapists over capital equipment, limiting chest physiotherapy device penetration in emergency departments.
Strategic Opportunities
- App-integrated adherence platforms:Bluetooth-enabled nebulizers paired with patient-facing applications create recurring revenue streams through subscription monitoring services and pharmacy integration partnerships.
- Pediatric homecare expansion:Underpenetrated markets in Australia and Canada present white space for portable oscillating positive expiratory pressure devices designed specifically for adolescent CF patients managing school and travel schedules.
- Real-world evidence mandates:CMS reimbursement policies increasingly reward connected devices that generate longitudinal adherence data, creating competitive differentiation for manufacturers investing in cloud infrastructure.
Industry Challenges
- CFTR biomarker assay integration:Device manufacturers lack in-house proteomics expertise to validate sweat chloride sensors and genetic testing interfaces, requiring complex partnerships with diagnostic laboratories.
- Legacy hospital procurement inertia:Established vendor relationships in integrated delivery networks create switching friction for novel connected device entrants despite superior clinical outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cystic Fibrosis Devices Market |
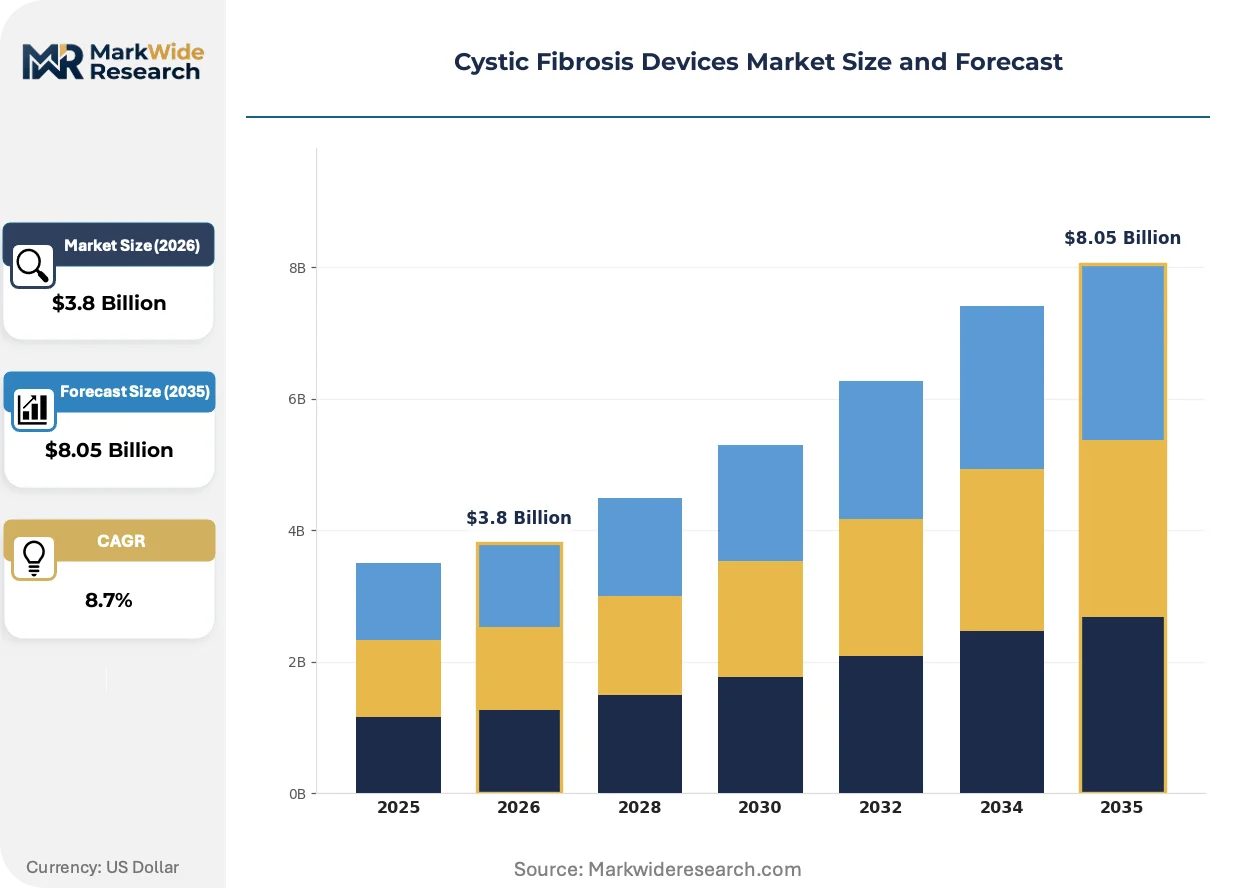
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Chest Physiotherapy Devices, Diagnostic Equipment Technology: Ultrasonic, Mesh, PEP, Oscillating Application: Airway Clearance, Drug Delivery, Monitoring, Diagnostics End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Vertex Pharmaceuticals Incorporated, AbbVie Inc., Viatris Inc, Teva Pharmaceutical Industries Ltd., Smiths Medical, Inc., Baxter International plc, AstraZeneca plc, Thayer Medical Corporation, AlgiPharma AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cystic Fibrosis Devices Market Evolving Landscape
Device architectures are converging around data-generating platforms that transform chronic respiratory management from episodic intervention to continuous monitoring, with hardware margins increasingly supplemented by software and service revenue streams.
Mesh nebulizer technology is migrating from hospital-grade stationary units to pocket-sized, battery-operated systems suitable for school and workplace administration. Adolescent and young adult patient segments in the United States and Germany are adopting these portable alternatives at accelerating rates. The transition is compressing the traditional distinction between acute and maintenance care settings, forcing manufacturers to redesign form factors around lifestyle integration rather than clinical environment optimization.
The EU F-Gas Regulation is eliminating hydrofluorocarbon propellants from metered-dose inhaler supply chains by 2030. European pharmaceutical-device combination product manufacturers are reformulating around dry powder and soft mist alternatives, with device redesign costs flowing through to pricing structures. German and French markets are experiencing the most acute transition pressure due to their historical reliance on chlorofluorocarbon successor propellants.
Hospital purchasing cooperatives in the United States are consolidating vendor panels for airway clearance equipment, favoring suppliers offering bundled device-drug-service contracts over standalone hardware procurement. Integrated delivery networks in Texas and California are piloting outcome-based agreements where device manufacturers share financial risk for patient exacerbation reduction. This behavioral shift is most visible in Medicare Advantage populations where capitated reimbursement aligns provider and supplier incentives around prevention.
Cystic Fibrosis Devices Market Segmentation
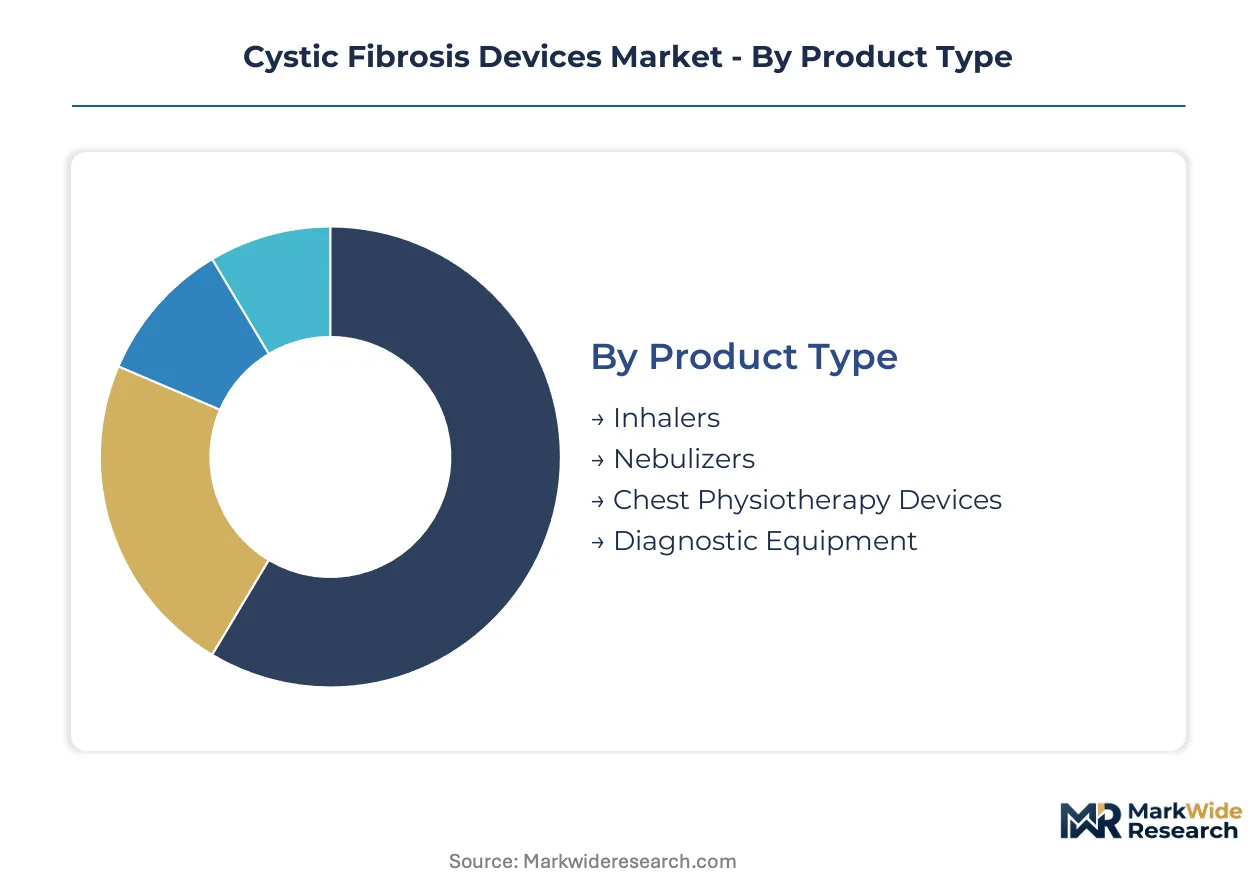
Cystic fibrosis device portfolios stratify across therapeutic function, delivery mechanism, and care setting. Each segment carries distinct regulatory pathways, reimbursement codes, and patient adherence profiles that determine commercial viability.
Product Type:
The maturity spectrum spans from decades-old mechanical systems to emerging connected platforms generating real-world evidence.
- Inhalers:Metered-dose and dry powder systems dominate chronic medication administration through compact, patient-operated formats. Demand concentrates in the United States where CFTR modulator co-therapies require precise bronchodilator timing; the EPA's hydrofluorocarbon restrictions are forcing propellant reformulation investments.
- Nebulizers:Piezoelectric mesh and ultrasonic systems aerosolize hypertonic saline, dornase alfa, and antibiotic suspensions for deep lung deposition. German and French markets are absorbing the steepest device redesign costs under the EU F-Gas Regulation's hydrofluorocarbon phaseout.
- Chest Physiotherapy Devices:High-frequency chest wall oscillation vests and positive expiratory pressure valves mechanically dislodge mucus plugs. Manual percussion protocols in cost-constrained hospital systems limit capital equipment penetration.
- Diagnostic Equipment:Spirometers, plethysmographs, and sweat chloride analyzers monitor disease progression and treatment response. Newborn screening mandates across U.S. states and European health systems are expanding the installed base.
Inhalers and nebulizers together handle the majority of throughput; diagnostic equipment is gaining share fastest as biomarker-based protocols proliferate.
Technology:
Cost tier differentiation separates premium connected platforms from basic mechanical alternatives with minimal electronic content.
- Ultrasonic:Piezoelectric crystal vibration generates aerosol without propellants, enabling silent operation suitable for nocturnal administration. Homecare reimbursement codes in the United States favor these systems over compressed-air alternatives for pediatric patients.
- Mesh:Micron-scale apertures in vibrating membranes produce consistent particle size distributions for distal airway targeting. Precision ceramic suppliers concentrated in East Asian electronics clusters create input vulnerability for Western device assemblers.
- PEP:Positive expiratory pressure valves create backpressure to splint airways during exhalation, facilitating mucus mobilization. Low manufacturing complexity supports broad accessibility in resource-limited settings.
- Oscillating:High-frequency chest wall oscillation and oscillating positive expiratory pressure generate intrapulmonary percussive effects. Portable battery-operated variants are capturing adolescent patient segments managing school and travel schedules.
Mesh technology commands premium pricing; oscillating systems are expanding most quickly into homecare environments.
Application:
Volume concentration follows the chronic daily therapy burden, with acute interventions representing smaller but higher-margin opportunities.
- Airway Clearance:Mechanical and oscillatory systems physically mobilize thickened secretions characteristic of defective CFTR function. Integrated delivery networks in Texas and California are piloting outcome-based agreements linking device provision to exacerbation reduction.
- Drug Delivery:Nebulized and inhaled formulations require device-drug pairing under FDA combination product rules. The EMA's Medical Device Regulation imposes clinical evidence requirements on higher-class respiratory delivery systems.
- Monitoring:Connected spirometers and adherence sensors generate longitudinal data for care optimization. CMS reimbursement policies increasingly reward devices producing real-world evidence for value-based contracting.
- Diagnostics:Newborn screening and confirmatory testing protocols drive equipment placement in hospital laboratories and specialized CF centers.
Drug delivery applications absorb the largest device volume; monitoring is climbing the fastest as digital infrastructure matures.
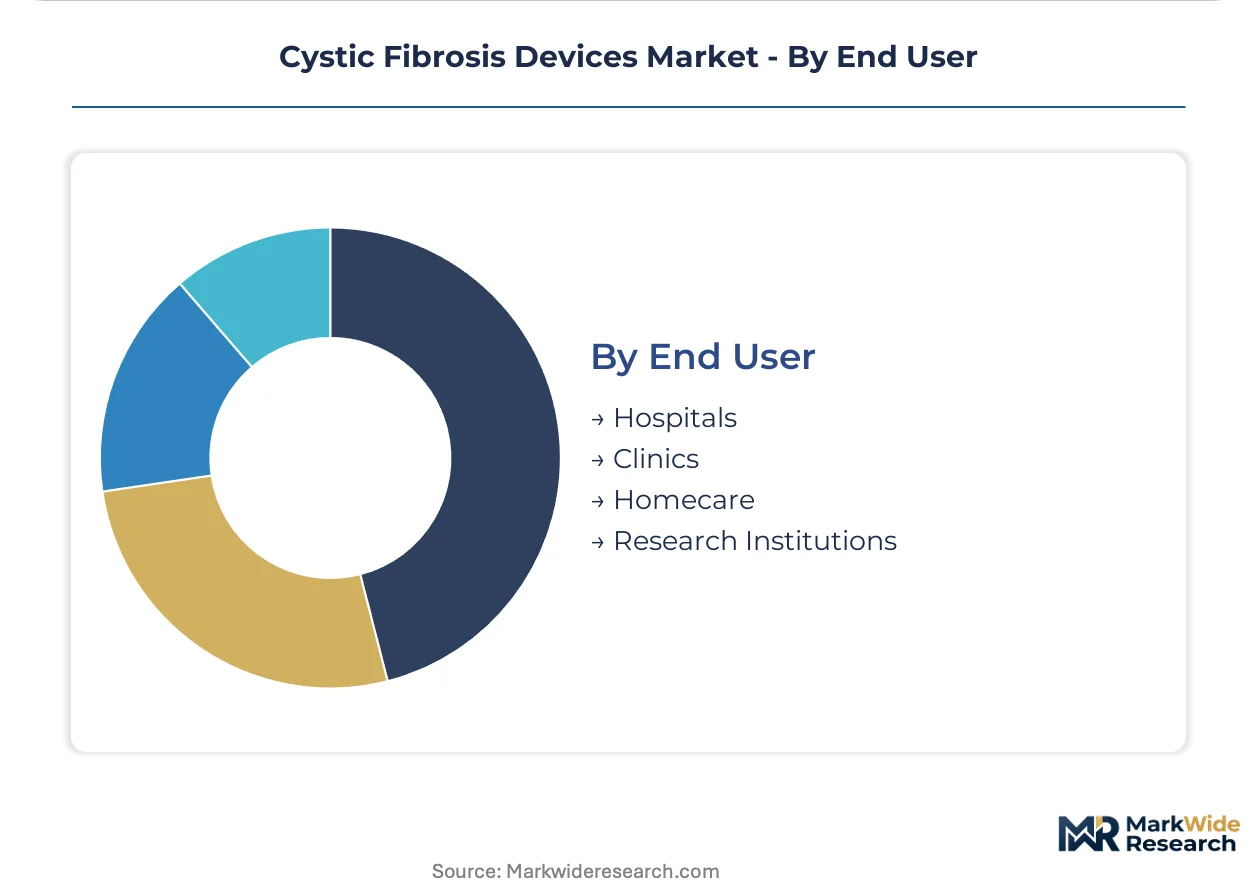
End User:
Customer type determines procurement channel, with institutional buyers favoring bundled contracts and individual patients prioritizing portability.
- Hospitals:Acute care settings deploy stationary high-frequency chest wall oscillation systems and diagnostic suites for exacerbation management. Established vendor relationships in integrated delivery networks create switching friction for novel connected device entrants.
- Clinics:Outpatient CF centers coordinate multidisciplinary care with spirometry and adherence monitoring equipment. Capitated reimbursement in Medicare Advantage populations aligns provider and supplier incentives around prevention.
- Homecare:Residential environments favor portable nebulizers and oscillating PEP devices for daily maintenance therapy. CMS-established billing categories for portable airway clearance systems are shifting treatment volume from acute to residential settings.
- Research Institutions:Academic medical centers validate novel device-drug combinations and connected platform efficacy for regulatory submission.
Homecare settings are capturing the fastest share expansion; hospitals retain the largest installed base of capital equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital purchasing cooperatives and homecare reimbursement infrastructure concentrate device procurement in markets with established CF treatment protocols. Regulatory pathways and newborn screening mandates determine addressable patient bases across jurisdictions.
United States
Integrated delivery networks in Texas and California pilot outcome-based agreements linking device provision to exacerbation reduction. CMS-established billing categories for portable airway clearance systems shift treatment volume from acute care to residential settings. Vertex Pharmaceuticals Incorporated anchors device-drug ecosystems from Boston while Smiths Medical, Inc. dominates hospital procurement channels.
Germany
The EU F-Gas Regulation's hydrofluorocarbon phaseout forces steepest device redesign costs in German metered-dose inhaler supply chains. EMA MDR clinical evidence requirements extend time-to-market for higher-class respiratory devices. Precision ceramics for mesh nebulizers flow through East Asian electronics clusters before final assembly.
United Kingdom
NHS procurement frameworks favor bundled device-service contracts over standalone hardware for cystic fibrosis centers. The Medicines and Healthcare products Regulatory Agency enforces combination product rules when nebulizers pair with specific drug formulations. London-based CF centers coordinate multidisciplinary care with adherence monitoring equipment.
France
ANSM oversight of medical device vigilance creates stringent post-market surveillance obligations for connected respiratory platforms. French markets absorb acute transition pressure from chlorofluorocarbon successor propellant elimination. Parisian hospital systems maintain manual percussion protocols in cost-constrained emergency departments.
Australia
The Therapeutic Goods Administration's priority review pathway accelerates approval timelines for novel airway clearance innovations. Underpenetrated pediatric homecare markets present white space for portable oscillating positive expiratory pressure devices. Sydney and Melbourne CF centers expand newborn screening protocol coverage.
Cystic Fibrosis Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. Hospital purchasing cooperatives consolidate vendor panels, favoring suppliers offering bundled device-drug-service contracts. Three archetypes dominate: therapeutic franchise holders extending into adjacent device ecosystems, dedicated respiratory hardware manufacturers, and pharmaceutical firms competing in nebulizer generics. Competitive moves center on outcome-based contracting partnerships and cloud infrastructure investments for real-world evidence generation.
Within the therapeutic franchise tier, Vertex Pharmaceuticals Incorporated exemplifies anchor positioning through cystic fibrosis drug-device ecosystem integration. Among dedicated device manufacturers, Smiths Medical, Inc. and Thayer Medical Corporation occupy positions shaped by hospital procurement channel relationships. Teva Pharmaceutical Industries Ltd. represents the pharmaceutical-generic archetype competing across European reimbursement markets.
| Leading Market Players |
|---|
| Vertex Pharmaceuticals Incorporated |
| AbbVie Inc. |
| Viatris Inc |
| Teva Pharmaceutical Industries Ltd. |
| Smiths Medical, Inc. |
| Baxter International plc |
| AstraZeneca plc |
| Thayer Medical Corporation |
| AlgiPharma AS |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors linking East Asian electronics clusters to North American device assemblers transmit ceramic component cost volatility into final nebulizer pricing, concentrating margin pressure on mesh technology tiers while rewarding suppliers with captive piezoelectric sourcing.
Pricing Analysis
Cost-plus contracts with ceramic supplier indexation dominate mesh nebulizer procurement, embedding raw material volatility into manufacturer margins. Three-tier pricing structure across connected platforms, standard electronic units, and mechanical alternatives reflects certification grade differentiation and after-sales service bundling. Cost compression in the standard electronic tier is intensifying because hospital purchasing cooperatives consolidate vendor panels around bundled contracts. Pediatric homecare segments demonstrate highest price sensitivity due to out-of-pocket exposure, while integrated delivery networks in Medicare Advantage populations exhibit lowest sensitivity under capitated reimbursement.
Supply Chain Analysis
Contract manufacturing capacity for precision piezoelectric assemblies concentrates with East Asian electronics foundries serving medical device OEMs. Mesh nebulizer production draws from ceramic substrate suppliers in Japan, South Korea, and Taiwan, with final device assembly occurring in the United States and Germany. Single-source vulnerability in micron-scale aperture membrane fabrication creates chokepoint exposure for Western device assemblers. Distribution runs through hospital purchasing cooperatives and specialized durable medical equipment suppliers to end-user facilities and homecare patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cystic fibrosis devices market sits in early-cycle expansion as newborn screening mandates and homecare reimbursement codes extend addressable patient bases beyond traditional acute care boundaries.
For Market Incumbents: Harden supply chain resilience through backward integration into precision ceramic sourcing or exclusive partnerships with Japanese substrate suppliers, insulating against East Asian logistics disruption. Deepen cloud infrastructure investments to capture CMS real-world evidence reimbursement premiums before mid-cap competitors achieve connectivity parity. Consolidate hospital procurement channel control through outcome-based contracting pilots in Texas and California integrated delivery networks. For New Entrants and Emerging Players: Build out portable oscillating positive expiratory pressure device portfolios targeting underpenetrated pediatric homecare markets in Australia and Canada, where established vendor relationships remain weakest. Pursue regulatory prioritization through the FDA's breakthrough device designation pathway to compress approval timelines against entrenched competitors. Anchor go-to-market strategy around pharmacy integration partnerships for adherence monitoring subscription revenue. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting non-core respiratory device divisions amid portfolio rationalization. Long-term viability favors manufacturers with demonstrated cloud infrastructure and real-world evidence generation capabilities over pure hardware plays. Monitor FDA breakthrough designation awards and CMS reimbursement code expansions as inflection signals for connected platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Compresses regulatory timelines for novel connected respiratory platforms against standard 510(k) pathways. |
| Cloud Infrastructure Investment | Captures CMS reimbursement premiums for real-world evidence generation in Medicare Advantage populations. |
| Precision Ceramic Supply Agreement | Secures piezoelectric membrane sourcing against East Asian supplier concentration risk. |
| Hospital System Partnership | Unlocks integrated delivery network procurement panels through outcome-based risk-sharing contracts. |
| Software Companion Development | Transforms hardware margins into recurring subscription revenue through adherence monitoring platforms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across cystic fibrosis treatment protocols, including respiratory therapists, hospital GPO contracts managers, biomedical engineers, and homecare durable medical equipment suppliers. Secondary validation drew from FDA 510(k) filings, EMA Medical Device Regulation guidance documents, CMS Medicare reimbursement databases, and EU F-Gas Regulation implementation reports. Bottom-up patient population modeling triangulated against top-down manufacturer revenue estimates across the analysis window.
Calibration against historical newborn screening expansion rates and homecare reimbursement code adoption curves anchored the projection framework. Segmentation dimensions spanned product type, technology platform, application function, and end-user setting, with regional regulatory clusters modeled separately. CAGRs derived from fitted adoption curves incorporating EU F-Gas Regulation phaseout timelines and FDA breakthrough designation velocity. Forecast inputs included state-level screening mandate rollouts and Medicare Advantage penetration trajectories.
Stress conditions across ceramic supply disruption severity, CMS reimbursement policy reversal, and EU MDR clinical evidence requirement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding screening expansion continuity and connected platform interoperability standards. Quarterly review of FDA breakthrough designation awards and CMS billing code expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Toe Fixation System Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Snare Devices Market
Medical Devices
Recanalization System Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market