
 Global Cardiac Output Monitoring Devices Market | 2026-2036
Global Cardiac Output Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Output Monitoring Devices Market Foresight
The EU Green Deal and associated healthcare sustainability mandates are shifting procurement criteria toward devices with reduced environmental footprints across European hospital networks. Edwards Lifesciences Corporation dominates the pulmonary artery catheter segment through its Swan-Ganz heritage and specialized catheter manufacturing. Baxter International leverages its broader critical care portfolio to bundle hemodynamic monitors with consumables and infusion systems. Getinge AB anchors its position in cardiac surgery centers through integrated perfusion and monitoring workflows.
Cardiac output monitoring devices measure blood volume pumped by the heart per minute using thermodilution, lithium dilution, or bioreactance methods with typical measurement ranges of 4 to 8 liters per minute in adult patients. These instruments guide fluid therapy, vasopressor titration, and inotropic support in hemodynamically unstable patients across operating rooms and intensive care settings. Pulmonary artery catheters remain the established revenue base despite declining procedural growth, while pulse contour analysis systems capture the fastest expansion as anesthesiologists favor less invasive arterial line integration. Bioreactance technology occupies a niche in emergency departments where rapid noninvasive screening outweighs absolute precision requirements.
FDA premarket approval pathways and EU MDR conformity assessments shape device development timelines and clinical trial obligations for manufacturers seeking dual-market access. ISO 81060 standards for noninvasive blood pressure monitoring and IEC 60601 electrical safety requirements constrain hardware design choices across all product categories. Stakeholders must monitor evolving reimbursement codes for minimally invasive hemodynamic monitoring in US outpatient surgical settings and track NMPA registration progress for market entry into China.
Market Dynamics
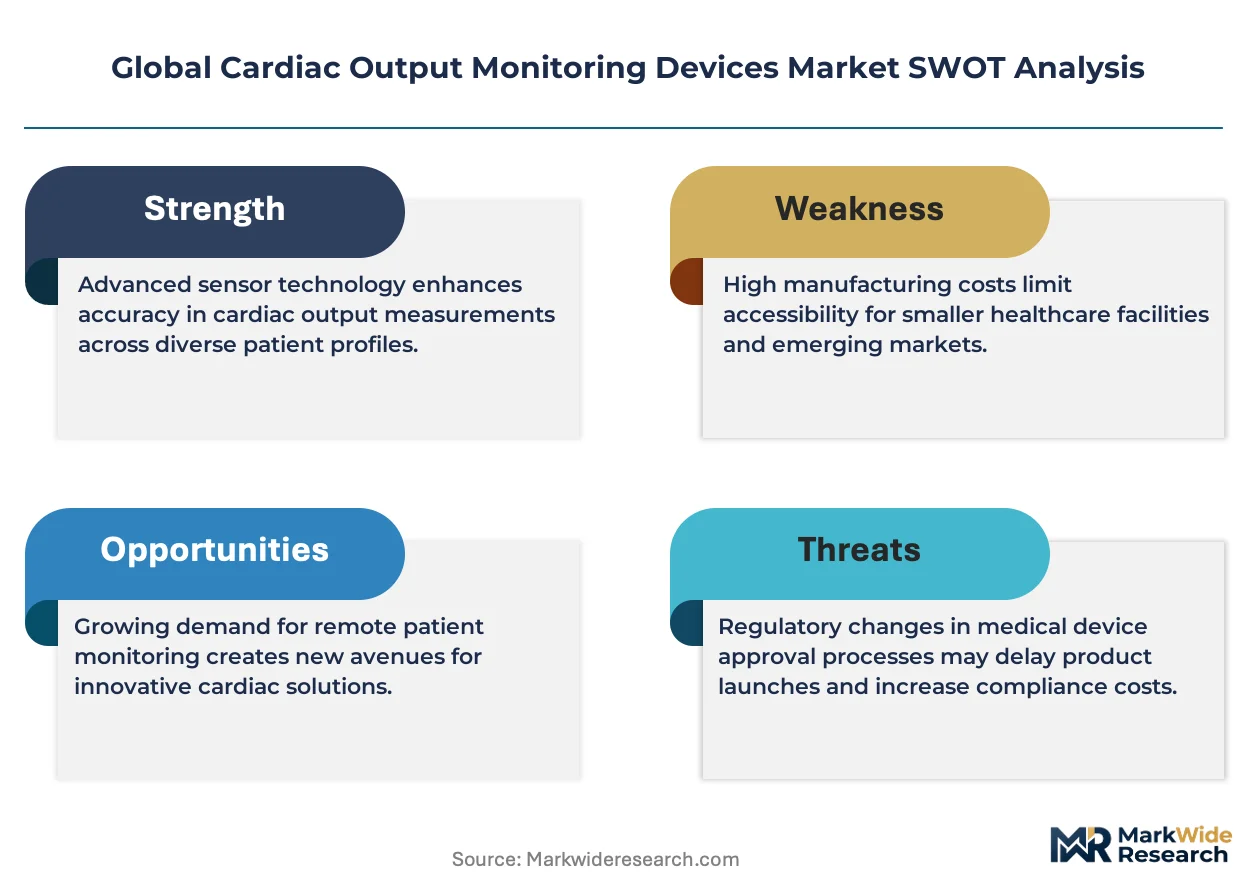
EU MDR clinical evidence requirements for Class III cardiovascular devices are compressing product development timelines and forcing manufacturers to front-load clinical trial investments before market entry.
Growth Catalysts
- Pulmonary artery catheter procedural volume:Cardiac surgery centers in Germany maintain elevated utilization rates for invasive monitoring during complex valve replacements and coronary revascularization procedures.
- FDA breakthrough device designation:Expedited review pathways for novel hemodynamic monitoring algorithms accelerate commercialization timelines for bioreactance and pulse contour analysis systems.
- ICU infrastructure investment:Hospital systems across the United States deploy integrated hemodynamic workstations combining cardiac output monitors with mechanical ventilation and renal replacement platforms.
Market Restraints
- Single-source sensor dependency:Specialized pressure transducers and arterial catheter components concentrate manufacturing in discrete supplier clusters, exposing procurement to disruption risk.
- EU MDR technical documentation burden:Class III device conformity assessments require extensive clinical performance data and post-market surveillance infrastructure, extending time-to-revenue for new entrants.
- Noninvasive monitoring substitution:Echocardiography and impedance cardiography systems capture screening applications where absolute precision is secondary to speed and cost.
Strategic Opportunities
- China NMPA registration pathway:Domestic manufacturing partnerships and clinical trial localization unlock access to hospital procurement networks in tier-one cities.
- Perioperative fluid optimization protocols:Enhanced recovery after surgery programs create standardized demand for goal-directed hemodynamic therapy in colorectal and orthopedic procedures.
- AI-enabled waveform analysis:Machine learning algorithms applied to arterial pressure waveforms enable predictive hemodynamic instability alerts before clinical decompensation.
Industry Challenges
- ISO 81060 validation requirements:Noninvasive blood pressure monitoring standards demand extensive accuracy testing across patient populations and hemodynamic states, prolonging development cycles.
- Legacy device interoperability:Integration of new monitoring platforms with existing hospital information systems and electronic health records requires customized interface engineering.
- Specialized perfusionist training pipelines:Cardiac surgery workforce constraints limit deployment of advanced invasive monitoring in community hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Output Monitoring Devices Market |
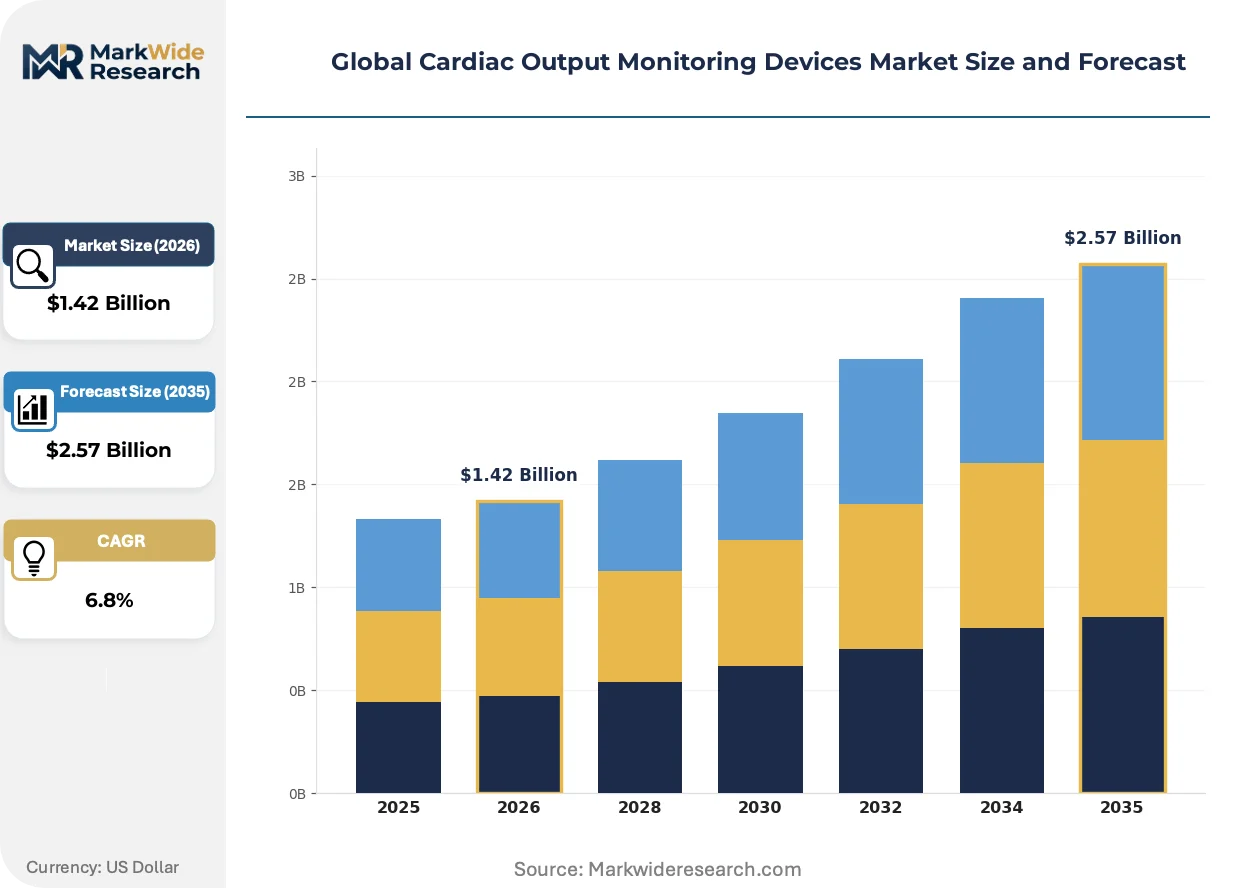
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulmonary Artery Catheters, Pulse Contour Analysis, Doppler Ultrasound Devices, Bioimpedance Monitors, Fick Principle Systems Technology: Thermodilution, Lithium Dilution, Transpulmonary Thermodilution, Bioreactance, Electromagnetic Flowmetry Application: Critical Care, Perioperative Monitoring, Emergency Medicine, Neonatal Care, Cardiac Rehabilitation End User: Intensive Care Units, Cardiac Surgery Centers, Emergency Departments, Neonatal Intensive Care Units, Specialized Clinics |
| Companies Covered | Edwards Lifesciences Corporation, GE Healthcare, Getinge AB, Baxter International, LiDCO Group plc, Deltex Medical Group plc, ICU Medical, Philips, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Output Monitoring Devices Market Shifts & Advancements
Sensor miniaturization and algorithmic signal processing are collapsing the invasiveness-precision tradeoff that historically segmented the cardiac output monitoring landscape.
Bioreactance technology is integrating thoracic electrical bioimpedance with machine learning pattern recognition to filter motion artifact and improve measurement stability in ambulatory and emergency settings. Anesthesiology departments in academic medical centers pilot these systems for intraoperative fluid management. The technology is integrating noninvasive screening workflows into perioperative pathways previously reserved for arterial catheterization.
EU MDR post-market clinical follow-up obligations now mandate systematic collection of real-world performance data across all Class III cardiovascular devices. Manufacturers must establish prospective registry infrastructure and adverse event reporting protocols. The regulation most acutely affects pulmonary artery catheter producers, who face expanded surveillance costs for legacy product lines.
Hospital procurement committees now unbundle hemodynamic monitoring hardware from disposable contracts, reversing historical vendor lock-in arrangements. Anesthesia groups and critical care departments negotiate separate pricing for arterial catheters, pressure transducers, and monitoring platforms. This behavior is most visible in United States integrated delivery networks consolidating purchasing across multiple surgical facilities.
Global Cardiac Output Monitoring Devices Market Segmentation
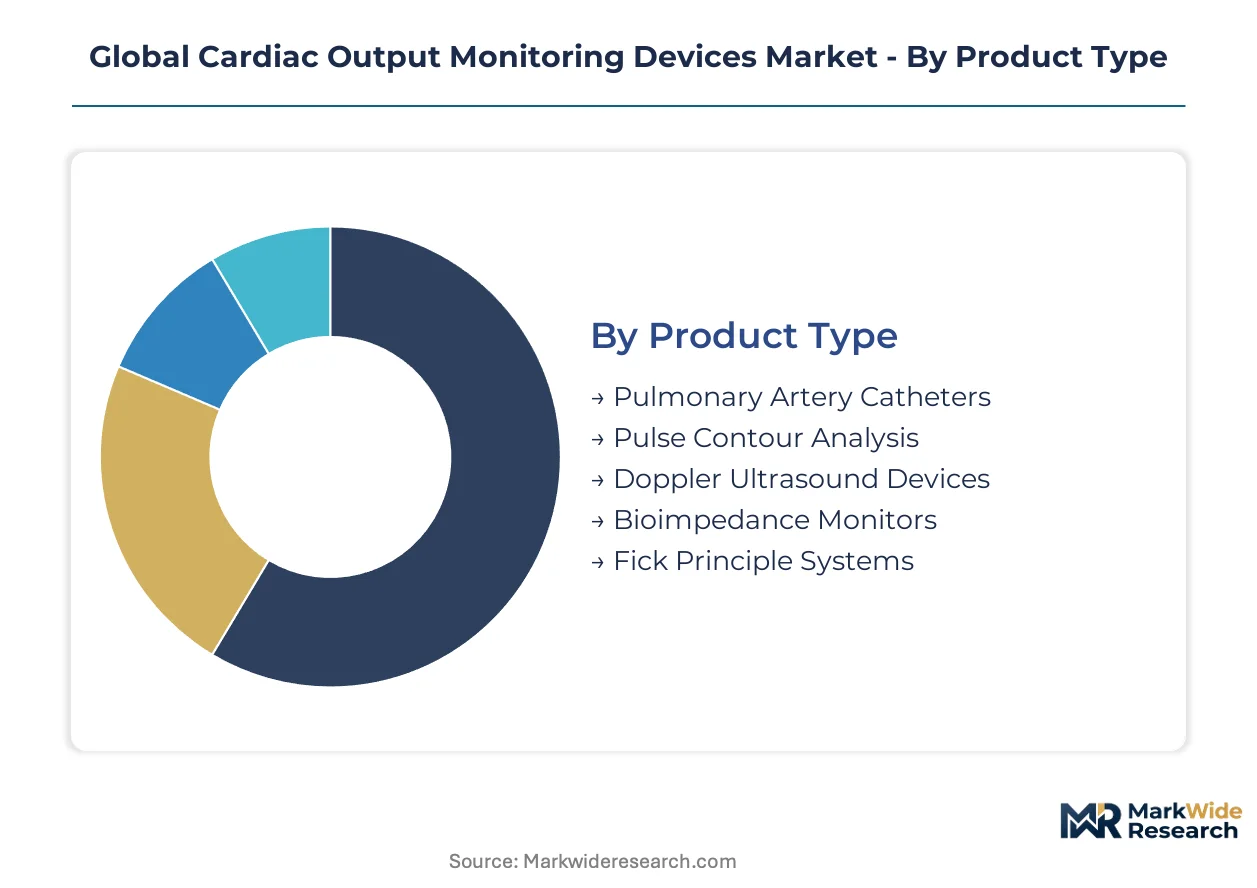
Cardiac output monitoring devices fragment across invasive-to-noninvasive technology spectra, with procurement decisions balancing measurement precision against procedural risk. Hospital capital committees and anesthesia departments evaluate segments through distinct clinical workflows and reimbursement pathways.
Product Type:
Hospital procurement committees weight catheterization risk against hemodynamic data fidelity when selecting among invasive and noninvasive modalities.
- Pulmonary Artery Catheters:Thermodilution-based catheters deliver gold-standard cardiac output measurements through right heart catheterization. Cardiac surgery centers in Germany maintain elevated utilization for complex valve replacements and coronary revascularization, though procedural volumes face pressure from less invasive alternatives.
- Pulse Contour Analysis:Arterial waveform interpretation systems integrate with existing radial or femoral lines, eliminating right heart catheterization. Anesthesiologists in United States academic medical centers favor this modality for goal-directed fluid therapy in major abdominal and orthopedic surgery.
- Doppler Ultrasound Devices:Esophageal or transthoracic Doppler systems measure aortic blood velocity for beat-to-beat output estimation. Cardiac surgery suites deploy these for rapid intraoperative assessment without additional vascular access.
- Bioimpedance Monitors:Thoracic electrical bioimpedance devices estimate stroke volume through chest electrode arrays. Emergency departments in tier-one Chinese cities adopt these for triage screening where speed outweighs absolute precision.
- Fick Principle Systems:Oxygen consumption-based calculations require mixed venous and arterial blood sampling. Specialized pulmonary hypertension clinics retain these for research protocols and complex diagnostic workups.
Volume sits with pulmonary artery catheters; growth tilts toward pulse contour analysis systems.
Technology:
Measurement methodology determines calibration requirements, operator skill demands, and integration complexity with hospital information systems.
- Thermodilution:Cold saline injectate or heating filament techniques measure temperature change curves for cardiac output calculation. Established ICU protocols in United States hospitals standardize around this reference method despite intermittent measurement limitations.
- Lithium Dilution:Peripheral venous lithium injection with arterial sampling enables less invasive calibration of pulse contour systems. United Kingdom anesthesia departments favor this for patients with contraindications to central venous catheterization.
- Transpulmonary Thermodilution:Central venous cold injectate with femoral arterial temperature detection provides global end-diastolic volume measurements. German cardiac surgery centers integrate these parameters into comprehensive preload assessment protocols.
- Bioreactance:Phase shift analysis of thoracic electrical signals tracks stroke volume variation without vascular access. Emergency medicine residency programs in Australia pilot these for undifferentiated shock evaluation.
- Electromagnetic Flowmetry:Perivascular probe placement around ascending aorta delivers continuous direct flow measurement. Extracorporeal membrane oxygenation circuits in Japanese cardiovascular centers incorporate these for precise perfusion monitoring.
Installed base concentrates in thermodilution; bioreactance systems are gaining share fastest.
Application:
Clinical setting dictates acceptable invasiveness levels, measurement frequency requirements, and integration with therapeutic decision support.
- Critical Care:Continuous hemodynamic monitoring guides vasopressor titration and fluid resuscitation in septic shock and acute respiratory distress syndrome. United States medical ICUs generate sustained demand for multi-parameter platforms integrating cardiac output with tissue oxygenation indices.
- Perioperative Monitoring:Goal-directed therapy protocols optimize stroke volume and oxygen delivery during major surgery. Enhanced recovery after surgery programs in French university hospitals mandate standardized hemodynamic algorithms for colorectal and hepatic resections.
- Emergency Medicine:Rapid noninvasive screening differentiates cardiogenic from distributive shock in undifferentiated hypotension. Spanish emergency departments deploy bioreactance systems for early sepsis recognition and fluid responsiveness assessment.
- Neonatal Care:Specialized low-flow measurement adaptions serve hemodynamically unstable preterm infants. Neonatal intensive care units in the Netherlands utilize ultrasonic cardiac output monitors for patent ductus arteriosus management.
- Cardiac Rehabilitation:Ambulatory impedance cardiography tracks exercise hemodynamics and training response. Outpatient clinics in Italy integrate these assessments into post-infarction functional capacity programs.
Critical care commands the largest installed footprint; perioperative monitoring shows the steepest expansion trajectory.
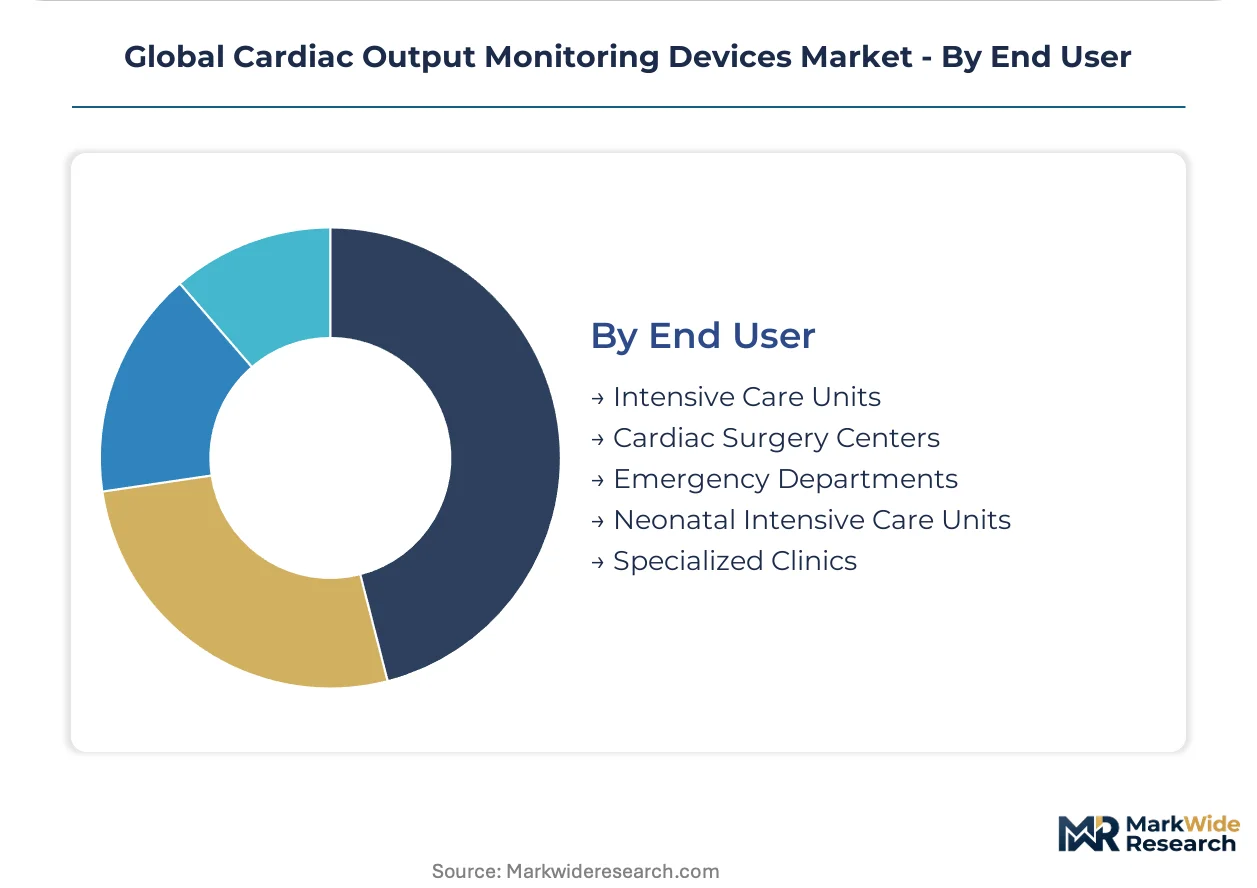
End User:
Facility type determines capital budget scale, specialist staffing availability, and procedural case mix driving device selection.
- Intensive Care Units:Medical and surgical ICUs require continuous multi-patient monitoring with centralized alarm management. United States health systems consolidate hemodynamic platform purchasing across mixed ICU portfolios to standardize training and consumable contracts.
- Cardiac Surgery Centers:Dedicated cardiothoracic units demand highest-fidelity invasive monitoring for cardiopulmonary bypass and postoperative support. German heart centers maintain differentiated procurement specifications exceeding general hospital standards.
- Emergency Departments:High-acuity resuscitation bays prioritize rapid deployment and minimal setup complexity. Australian metropolitan emergency departments evaluate noninvasive technologies for shock protocol standardization.
- Neonatal Intensive Care Units:Specialized low-birth-weight patient populations require miniaturized sensors and adapted measurement algorithms. Scandinavian neonatal networks share best practices for hemodynamic monitoring in extreme prematurity.
- Specialized Clinics:Outpatient heart failure and pulmonary hypertension programs utilize ambulatory monitoring for therapy optimization. Swiss cardiovascular centers combine impedance cardiography with six-minute walk testing for longitudinal functional assessment.
Intensive care units anchor procurement volume; cardiac surgery centers concentrate premium system deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors hemodynamic monitoring innovation through partnerships between Massachusetts General Hospital and device developers. The city's perioperative research infrastructure shapes protocol adoption across United States hospital systems.
United States
FDA breakthrough device designations accelerate commercialization timelines for novel hemodynamic algorithms in academic medical centers. The Centers for Medicare & Medicaid Services maintains reimbursement codes for goal-directed therapy in surgical settings. Texas Medical Center in Houston deploys integrated hemodynamic workstations across its cardiac surgery suites.
Germany
Cardiac surgery volumes in Bavaria and Baden-Württemberg sustain elevated pulmonary artery catheter utilization for complex procedures. The EU MDR tightens clinical evidence requirements for Class III cardiovascular devices through notified body assessments. Heidelberg University Hospital anchors multi-center trials for transpulmonary thermodilution protocols.
China
Tier-one cities including Shanghai and Beijing expand ICU infrastructure investment with standardized hemodynamic monitoring procurement. NMPA registration pathways require domestic clinical trial localization for market authorization. The Yangtze River Delta medical device cluster concentrates manufacturing partnerships for pulse contour analysis systems.
Japan
PMDA consultation procedures streamline approval for electromagnetic flowmetry integration with extracorporeal circuits. METI funding programs support sensor miniaturization research in cardiovascular applications. The Kansai region's cardiovascular centers pilot bioreactance technology for emergency department shock protocols.
United Kingdom
NHS England's perioperative care improvement programs mandate hemodynamic optimization in major surgery pathways. The MHRA maintains post-market surveillance alignment with EU MDR requirements post-Brexit. London's academic anesthesia departments favor lithium dilution calibration for patients with central venous access contraindications.
Global Cardiac Output Monitoring Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the invasiveness-precision spectrum, with specialized catheter manufacturers commanding pricing power over generic monitor assemblers. The vendor base concentrates among diversified critical care conglomerates and focused hemodynamic specialists. Three archetypes dominate: integrated critical care platform providers, standalone hemodynamic technology developers, and surgical workflow integrators. Competitive moves center on unbundling hardware from disposable contracts and establishing AI-enabled predictive algorithm partnerships.
Within the integrated platform tier, Edwards Lifesciences Corporation and Getinge AB exemplify divergent strategic positions. Edwards Lifesciences occupies the specialized catheter manufacturing archetype through its historical pulmonary artery catheter heritage. Getinge AB anchors the surgical workflow integration archetype by bundling perfusion systems with monitoring infrastructure. Baxter International sits between these positions, leveraging critical care portfolio breadth to bundle hemodynamic monitors with infusion and renal replacement platforms.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| GE Healthcare |
| Getinge AB |
| Baxter International |
| LiDCO Group plc |
| Deltex Medical Group plc |
| ICU Medical |
| Philips |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
EU MDR unbundling mandates are forcing hospital procurement committees to separate hemodynamic monitoring hardware from disposable catheter contracts, compelling manufacturers to restructure pricing around standalone platform value and per-procedure consumable economics.
Pricing Analysis
Value-based pricing anchored to clinical throughput and patient outcome metrics dominates hemodynamic monitoring procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status, ISO 81060 validation tier, and bundled service commitments. Cost compression in economy-tier noninvasive systems is intensifying because bioreactance alternatives commoditize screening applications. Emergency departments exhibit highest price sensitivity due to capital budget constraints, while German cardiac surgery centers show lowest sensitivity given reimbursement coverage for invasive monitoring in complex procedures.
Supply Chain Analysis
Specialized perfusionist and biomedical engineering workforce availability in Germany, the United States, and Japan constrains manufacturing scale-up for Class III cardiovascular device assembly. Production draws from precision pressure transducer suppliers in the United States, lithium sensor component manufacturers in Japan, and thermodilution catheter tubing facilities in Germany. Single-source vulnerability concentrates in specialized arterial pressure sensor modules. Distribution runs through integrated delivery networks in the United States, university hospital procurement consortia in Germany, and tier-one city hospital systems in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized catheter manufacturing capacity serves as the binding constraint propping premium pricing for invasive hemodynamic platforms, as EU MDR clinical evidence requirements extend development timelines and limit qualified supplier pools.
For Market Incumbents: Acquire predictive algorithm development capabilities to counter AI-enabled waveform analysis entrants threatening platform differentiation. Secure backward integration into pressure transducer manufacturing to mitigate single-source sensor dependency. Lock in long-term GPO contracts with United States integrated delivery networks before unbundling trends accelerate.
For New Entrants and Emerging Players: The mid-tier pricing gap between Edwards Lifesciences premium platforms and economy-tier bioimpedance systems offers entry space for calibrated pulse contour systems. Target Chinese tier-two cities where ICU infrastructure investment outpaces established vendor penetration. Pursue NMPA registration partnerships with Yangtze River Delta manufacturers to bypass clinical trial localization barriers.
For Investors and Strategic Acquirers: The window for entry favors standalone hemodynamic technology developers with FDA breakthrough device designations and established hospital pilot programs. Long-term viability rests on software-enabled recurring revenue models displacing transactional hardware sales. Monitor EU MDR notified body backlog resolution as inflection signal for Class III cardiovascular device approval velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review accelerates commercialization timelines for novel hemodynamic algorithms in academic centers. |
| CE Marking Under EU MDR | Notified body assessments for Class III devices compress development timelines and front-load clinical investments. |
| Hospital System Partnership | Integrated delivery network contracts standardize training and consumable purchasing across surgical facilities. |
| Software Companion Development | AI-enabled waveform analysis enables predictive instability alerts before clinical decompensation events. |
| Reimbursement Strategy | CMS coding for goal-directed therapy in surgical settings determines addressable market expansion. |
Research Methodology
Multi-period observation of ICU infrastructure investment, cardiac surgery procedural volumes, and regulatory approval timelines anchored the trend analysis, supplemented by interviews with perfusionists, anesthesiology department heads, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body assessment records, NMPA registration databases, and hospital procurement contract disclosures. Bottom-up facility-level demand estimation triangulated against top-down manufacturer revenue segmentation.
Input-output matrix modeling connected technology adoption curves, reimbursement pathway maturation, and regional regulatory cluster dynamics across the projection horizon. Segmentation dimensions spanned invasiveness tier, measurement methodology, clinical application setting, end-user facility type, and regional procurement structure. CAGRs were derived from fitted adoption curves weighted by installed base replacement cycles and expansion capital deployment patterns. Forecast inputs incorporated EU MDR implementation friction and China NMPA localization requirements.
Inputs from FDA filing databases and EU notified body registries were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions regarding regulatory approval velocity and reimbursement code stability. Material deviation in EU MDR backlog resolution or CMS goal-directed therapy reimbursement decisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Perfusion Systems Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market