
 Global Vascular Plugs Market | 2026-2036
Global Vascular Plugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vascular Plugs Market Foresight
Image-guided catheter delivery systems are reshaping how vascular plugs are deployed, shifting procedures from open surgical ligation to percutaneous occlusion in outpatient settings. Abbott leverages its structural heart portfolio to anchor positions in large-bore venous closure, while Medtronic sustains R&D intensity across its neurovascular franchise to compete in flow diversion. Terumo Corporation specializes in microcatheter-compatible plug designs that navigate tortuous anatomy in peripheral territories.
Vascular plugs are implantable occlusion devices, typically constructed from nitinol wire mesh or platinum-iridium coils, designed to achieve mechanical thrombosis within target vessels through controlled blood flow disruption. These devices serve the primary purpose of eliminating abnormal vascular communications, reducing aneurysm perfusion, or redirecting hemodynamics prior to surgical resection. Occluders and flow diverters command the deepest margin pools due to complex manufacturing and extended regulatory pathways, while embolization particles face commoditization pressure from multiple polymer suppliers. Peripheral embolization applications lead procedural volumes, though neurovascular procedures represent the fastest-growing demand segment as stroke networks expand.
FDA breakthrough device designations and MDR conformity assessments under the EU Medical Device Regulation shape product development timelines and market access costs for manufacturers. Japan's PMDA requires localized clinical data for novel plug geometries, creating additional barriers for foreign entrants. Stakeholders must monitor evolving reimbursement thresholds for outpatient-based vascular occlusion procedures across Medicare, Germany's G-DRG system, and Japan's fee schedule revisions.
Market Dynamics
Nitinol shape-memory alloy manufacturing constraints and FDA breakthrough device designations are compressing product development cycles while concentrating supply among metallurgical specialists with validated wire-drawing capabilities.
Growth Catalysts
- Stroke network expansion:Regional stroke centers in the United States are establishing catheterization capabilities for neurovascular embolization, creating procedural demand for flow diverters and occluders.
- MDR conformity assessments:The EU Medical Device Regulation is accelerating consolidation among manufacturers with notified body relationships, favoring scaled players with quality management systems.
- Outpatient procedural migration:Ambulatory surgical centers are adopting image-guided delivery systems that enable same-day discharge for peripheral vascular occlusion.
Market Restraints
- Nitinol wire supply concentration:Superelastic alloy production centers on a limited set of vacuum arc remelting facilities in Germany and the United States.
- PMDA localization requirements:Japan's pharmaceutical and medical device agency mandates domestic clinical data for novel plug geometries, extending market entry timelines.
- Polymer particle substitution:Embolization coils face pricing pressure from calibrated microspheres in non-neurovascular applications.
Strategic Opportunities
- India's catheterization infrastructure:Greenfield hospital construction in tier-two cities is creating first-mover positions for plug-compatible delivery system suppliers.
- Flow diversion in unruptured aneurysms:Expanded indications for intrasaccular flow disruption are opening addressable procedure categories previously managed surgically.
- Telemedicine-integrated follow-up:Remote monitoring protocols are enabling post-procedural surveillance without tertiary center dependence.
Industry Challenges
- Interventionalist training pipelines:Fellowship programs in neurointerventional surgery are not expanding at rates matching device innovation cycles.
- Biocompatibility validation timelines:ISO 10993 testing sequences for novel surface coatings extend regulatory submission preparation.
- Legacy inventory harmonization:Hospitals are managing parallel stocking of multiple plug generations during platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vascular Plugs Market |
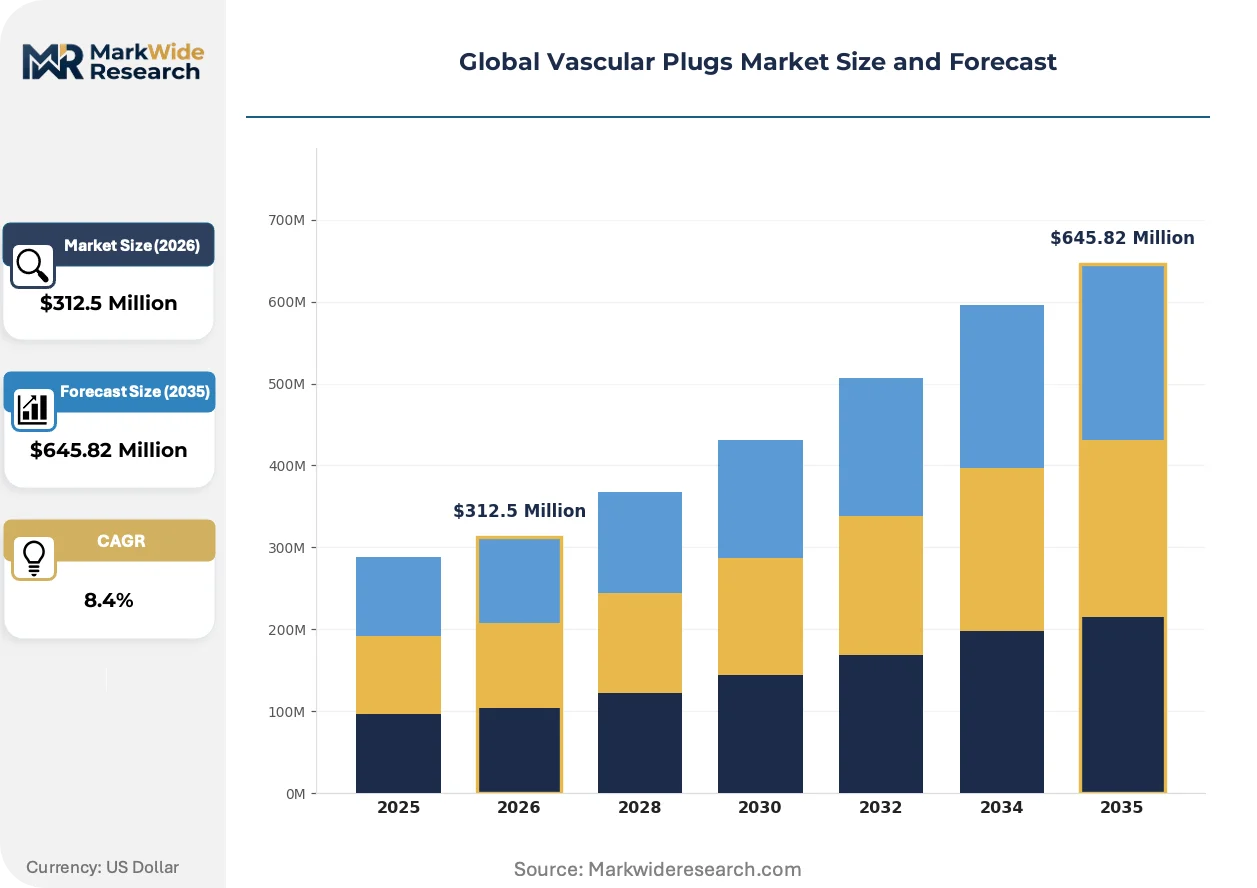
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coils, Occluders, Covered Stents, Embolization Particles, Flow Diverters Application: Peripheral Embolization, Cardiovascular Interventions, Neurovascular Procedures, Uterine Artery Embolization, Portal Vein Embolization End User: Specialty Clinics, Ambulatory Surgery Centers, Diagnostic Centers, Cardiac Institutes, Research Institutes Deployment: Hospital-based, Outpatient Facilities, Academic Medical Centers, Private Practices, Government Health Agencies |
| Companies Covered | Abbott, Medtronic, Terumo Corporation, Boston Scientific, Stryker Corporation, Lifetech Scientific, BD, Cook Medical, Penumbra Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vascular Plugs Market Shifts & Advancements
Device miniaturization and delivery system flexibility are converging to expand treatable anatomy, while regulatory data requirements are reshaping how manufacturers structure clinical evidence packages across jurisdictions.
Braided nitinol mesh technology is collapsing the distinction between mechanical occlusion and flow diversion in a single implantable platform. Interventional cardiologists in high-volume catheterization labs are adopting these hybrid devices for complex peripheral procedures previously staged with sequential coil deployments. The structural consequence is compressing average procedure times and reducing fluoroscopy exposure.
The EU Medical Device Regulation's enhanced clinical evidence requirements are elevating post-market surveillance obligations for neurovascular plug manufacturers. Notified bodies are demanding extended follow-up data for flow diverters, extending conformity assessment durations. Small-cap manufacturers without established quality management systems are exiting the European market rather than absorbing compliance costs.
Hospital procurement committees are consolidating vendor relationships around full-line structural heart suppliers capable of delivering plugs, delivery systems, and closure devices under single-source agreements. Independent distributors are losing shelf space to direct manufacturer contracts. This concentration is most visible in United States integrated delivery networks where standardization protocols override physician preference item autonomy.
Global Vascular Plugs Market Segmentation
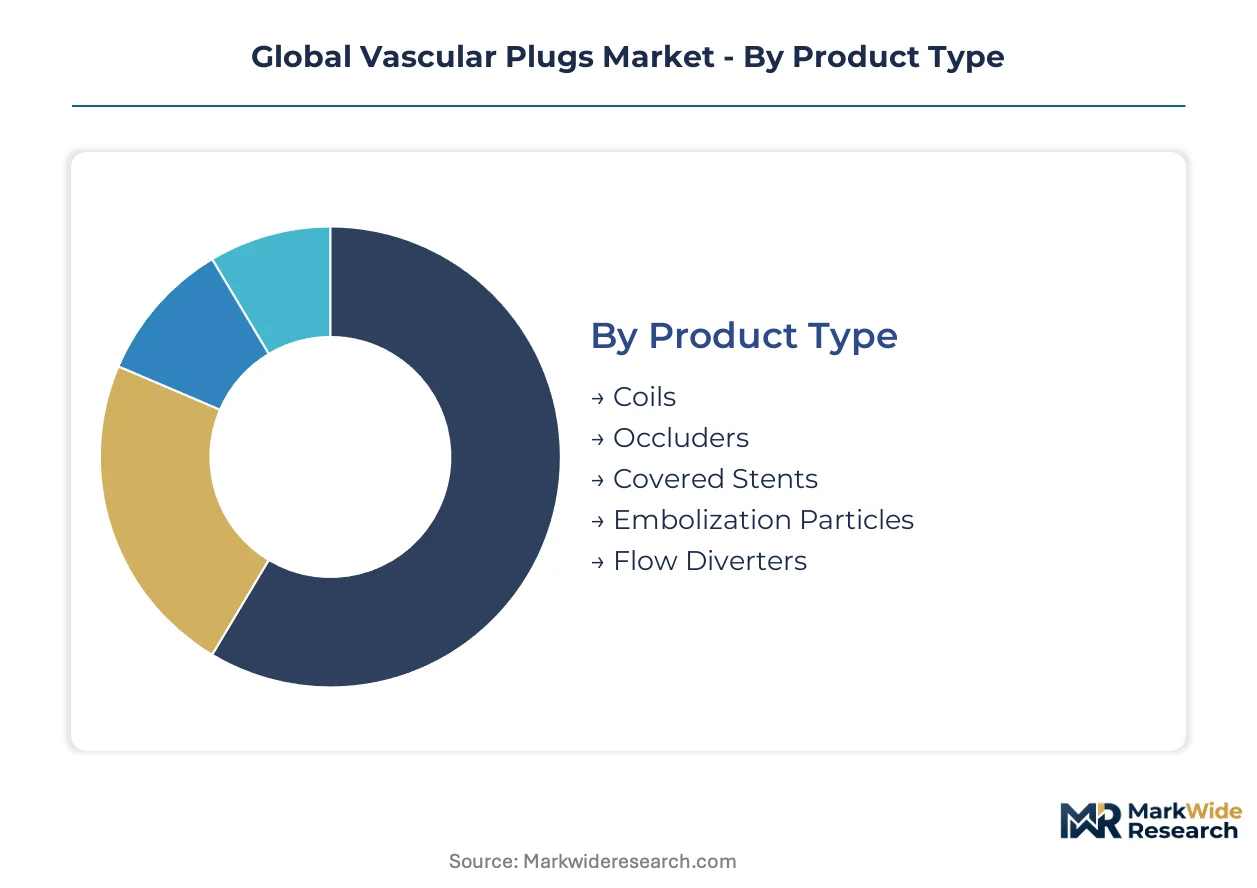
Vascular plug segmentation reveals distinct service intensity profiles across product categories. After-sales requirements vary sharply between permanent implants requiring long-term surveillance and consumable embolization agents. Procurement committees weigh these obligations against total cost-of-ownership models when standardizing vendor relationships.
Product Type:
After-sales service intensity peaks with flow diverters and occluders, where manufacturers must support multi-year implant tracking and adverse event reporting across regulatory jurisdictions.
- Flow Diverters:Braided nitinol mesh constructs redirect blood flow away from aneurysm sacs while preserving parent vessel patency. Demand concentrates in United States stroke centers where FDA breakthrough designations have accelerated adoption for unruptured intracranial aneurysms.
- Occluders:Self-expanding nitinol devices achieve mechanical occlusion through controlled thrombosis within target vessels. German catheterization labs are expanding utilization for complex peripheral arteriovenous malformations, driven by BfArM reimbursement alignment with minimally invasive outcomes.
- Coils:Platinum-iridium embolization coils deliver targeted vessel occlusion through controlled deployment.
- Covered Stents:Stent-graft hybrids exclude aneurysms while maintaining luminal flow.
- Embolization Particles:Calibrated polymer microspheres provide distal vessel occlusion without permanent implantation.
By volume, coils lead procedural deployment. By growth pace, flow diverters are expanding most quickly.
Application:
Application segmentation tracks how procedure site determines device specification requirements, with neurovascular interventions demanding the highest precision tolerances.
- Neurovascular Procedures:Intracranial aneurysm treatment and arteriovenous malformation embolization require sub-millimeter delivery accuracy. Japanese stroke networks under PMDA oversight are driving procedural volume expansion as regional centers achieve certification for mechanical thrombectomy and adjunctive flow diversion.
- Peripheral Embolization:Lower extremity and visceral vessel occlusion addresses trauma, tumors, and vascular malformations. United States outpatient migration is shifting volume toward ambulatory surgical centers with image-guided capabilities.
- Cardiovascular Interventions:Structural heart procedures including paravalvular leak closure and left atrial appendage exclusion.
- Uterine Artery Embolization:Fibroid treatment through targeted vascular occlusion preserves fertility.
- Portal Vein Embolization:Pre-surgical liver hypertrophy induction through ipsilateral portal branch occlusion.
Peripheral embolization dominates current procedural counts. Neurovascular applications show the steepest expansion trajectory.
End User:
End user structure reflects capital equipment requirements and case volume thresholds that determine viable plug deployment settings.
- Cardiac Institutes:Dedicated cardiovascular centers maintain hybrid operating suites combining surgical and interventional capabilities. Germany's university hospital networks are consolidating plug procurement through centralized G-DRG contracting.
- Ambulatory Surgery Centers:Same-day discharge facilities require streamlined inventory and rapid turnaround protocols. United States Medicare reimbursement expansion for outpatient vascular occlusion is accelerating site-of-service migration.
- Specialty Clinics:Focused interventional practices concentrate on specific anatomical territories.
- Diagnostic Centers:Imaging-equipped facilities provide procedural planning and follow-up surveillance.
- Research Institutes:Academic centers generate clinical evidence for novel indications and device iterations.
Cardiac institutes command the highest per-procedure device values. Ambulatory surgery centers are gaining share fastest.
Deployment:
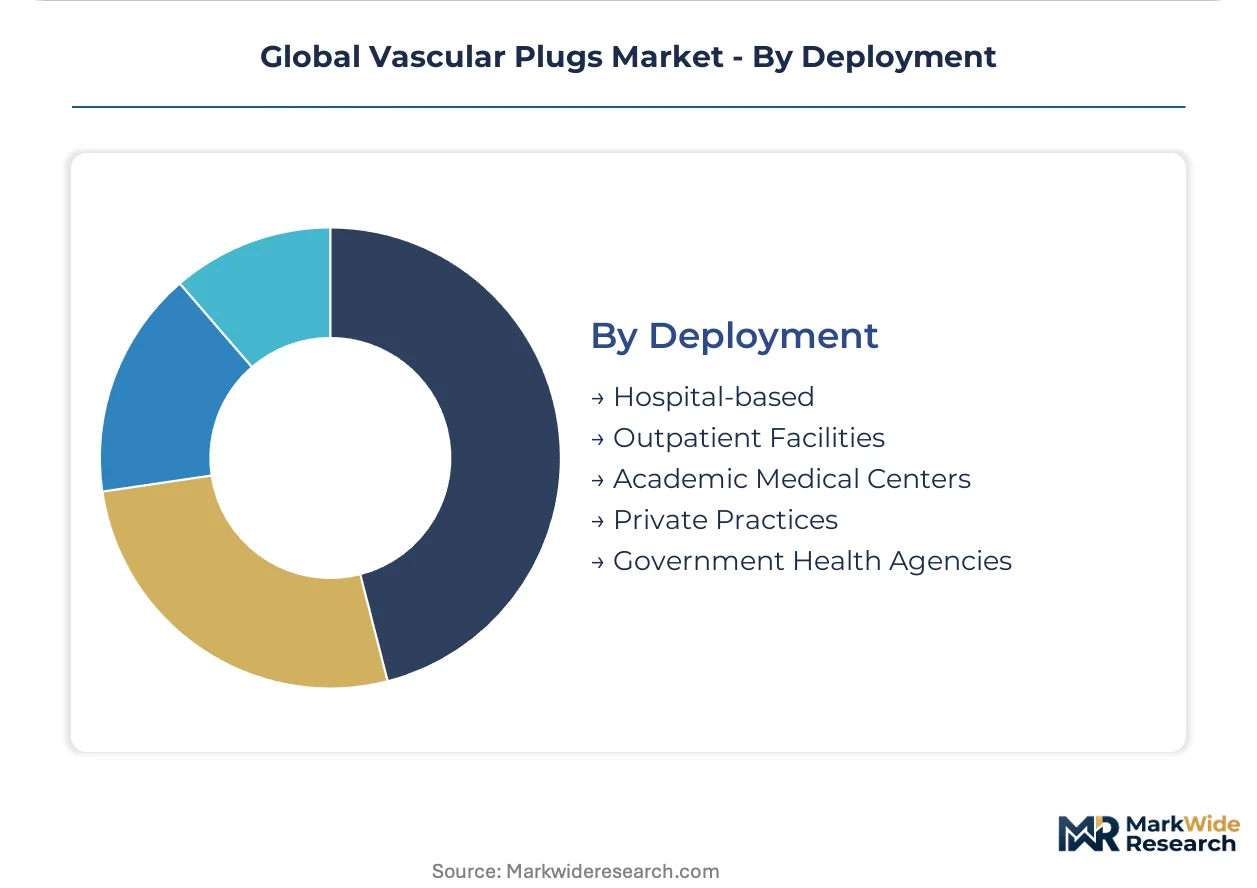
Deployment setting determines regulatory oversight intensity and reimbursement pathway structure for vascular occlusion procedures.
- Hospital-based:Tertiary medical centers manage complex multi-territory embolization with full surgical backup. Japan's designated stroke centers under PMDA certification requirements maintain exclusive access to neurovascular flow diversion procedures.
- Academic Medical Centers:Teaching hospitals combine clinical service with fellowship training and device evaluation. United States institutions are negotiating preferred vendor agreements spanning plugs, delivery systems, and closure devices.
- Outpatient Facilities:Standalone interventional suites focus on elective peripheral procedures.
- Private Practices:Physician-owned entities concentrate on high-volume routine applications.
- Government Health Agencies:Public systems manage population-level procurement and standardization.
Hospital-based deployment retains the largest installed base. Outpatient facilities are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision nitinol wire and finished vascular plugs to United States stroke centers, while Japan imports delivery system components from German metallurgical suppliers to serve its expanding neurovascular networks.
United States
Regional stroke center certification and Medicare reimbursement expansion for outpatient peripheral embolization drive procedural volumes. FDA breakthrough device designations compress approval timelines for flow diverters in unruptured aneurysm indications. The Cleveland Clinic and Mayo Clinic catheterization networks anchor multi-state procurement standardization for plug-compatible delivery systems.
Germany
BfArM reimbursement alignment with minimally invasive outcomes accelerates complex peripheral arteriovenous malformation procedures in university hospital networks. EU MDR conformity assessments favor scaled manufacturers with established notified body relationships. The Rhine-Ruhr medical technology cluster concentrates vacuum arc remelting facilities supplying superelastic nitinol wire to global device fabricators.
Japan
PMDA-mandated domestic clinical data requirements for novel plug geometries extend market entry timelines while protecting incumbent positions. Regional stroke center certification under PMDA oversight expands mechanical thrombectomy and flow diversion capabilities beyond Tokyo. The Kansai region's Osaka-based interventional cardiology training institutes generate specialist pipelines for neurovascular procedures.
China
Tier-two city hospital construction and catheterization infrastructure investment create first-mover positions for plug-compatible delivery system suppliers. NMPA regulatory pathways for Class III implantable devices require localized clinical trials extending product registration cycles. The Yangtze River Delta's Shanghai-Suzhou medical device manufacturing corridor concentrates domestic embolization coil production capacity.
India
Greenfield hospital construction in tier-two cities and medical tourism infrastructure investment expand addressable procedural volumes for peripheral embolization. CDSCO import licensing requirements for nitinol-based implants create regulatory friction for foreign device manufacturers. Hyderabad's medical technology cluster hosts catheter manufacturing operations serving domestic and export markets across South Asia.
Global Vascular Plugs Market Competitive Landscape
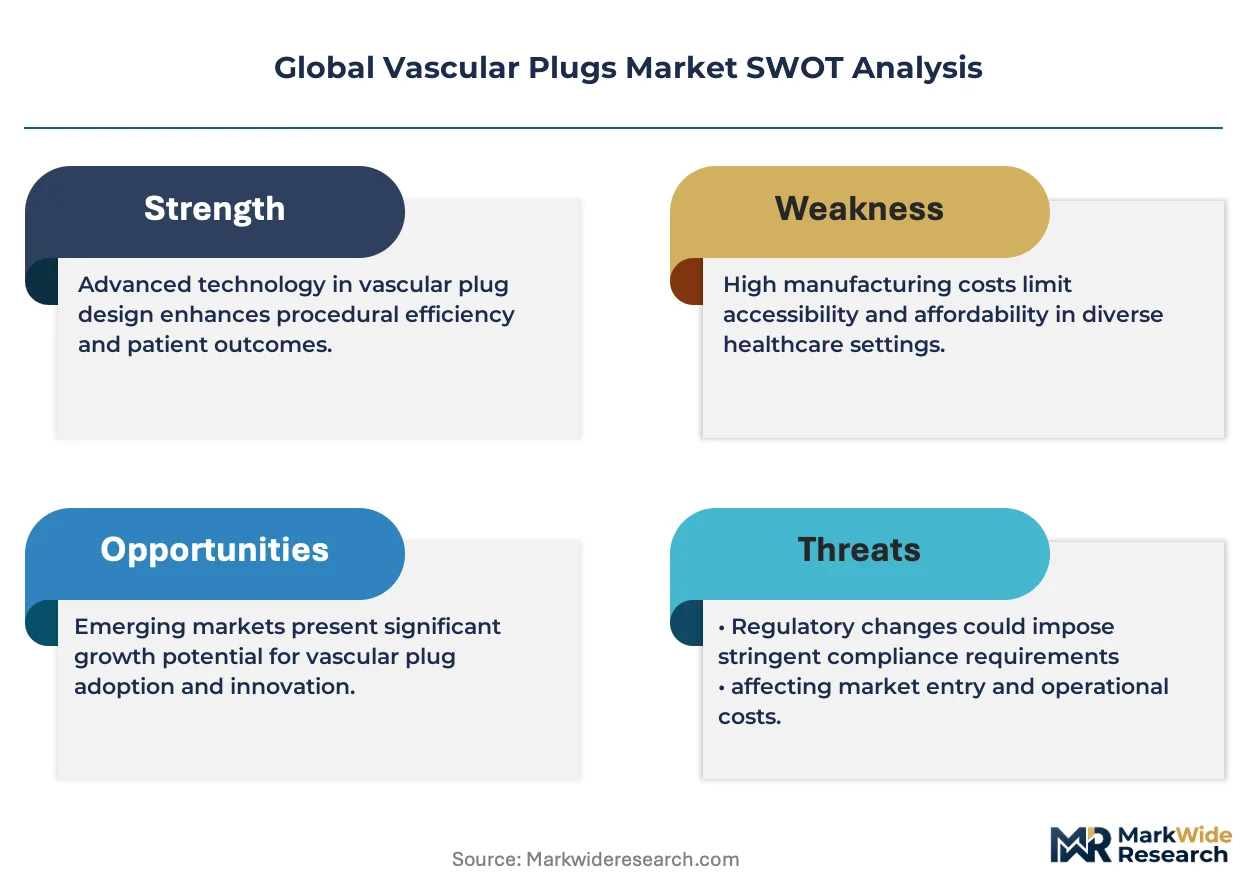
Channel-controlling players compete with product-specialist players across procurement committee relationships and interventionalist training networks. The market structures around three tiers: diversified structural heart portfolios anchoring integrated delivery network contracts, neurovascular franchises sustaining R&D intensity for flow diversion, and microcatheter-compatible specialists navigating tortuous peripheral anatomy. Consolidation accelerates through preferred vendor agreements spanning plugs, delivery systems, and closure devices, while strategic partnerships address nitinol wire supply concentration.
Among diversified structural heart portfolios, Abbott and Medtronic occupy positions anchoring large-bore venous closure and neurovascular flow diversion respectively. Terumo Corporation exemplifies the microcatheter-compatible specialist archetype with delivery system designs addressing tortuous anatomy. These three entities represent distinct competitive vectors: full-line structural heart integration, neurovascular R&D intensity, and peripheral navigation specialization.
| Leading Market Players |
|---|
| Abbott |
| Medtronic |
| Terumo Corporation |
| Boston Scientific |
| Stryker Corporation |
| Lifetech Scientific |
| BD |
| Cook Medical |
| Penumbra Inc. |
| Others |
Supply & Pricing Matrix
Vacuum arc remelting facility utilization rates in Germany's Rhine-Ruhr cluster and the United States determine nitinol wire availability, compressing supplier margins during demand surges while amplifying pricing power for metallurgical specialists with validated wire-drawing capabilities. FDA breakthrough device designations accelerate product development cycles, forcing manufacturers to absorb premium alloy costs upfront before reimbursement pathways stabilize.
Pricing Analysis
Cost-plus contracts indexed to nickel commodity benchmarks dominate nitinol alloy procurement, with superelastic wire pricing tethered to London Metal Exchange fluctuations and vacuum arc remelting facility queue positions. Three-tier pricing structure across premium, standard, and economy levels separates flow diverters with extended implant tracking from commoditized embolization coils and polymer microspheres. Cost compression in peripheral embolization coils is intensifying because calibrated microspheres substitute for mechanical occlusion in non-neurovascular applications. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare reimbursement caps, while academic medical centers prioritize device performance over unit economics.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supply-chain finance facilities extended by German metallurgical suppliers to United States device fabricators, straining working capital for mid-cap manufacturers without captive alloy production. Nitinol wire supply concentrates in Germany, the United States, and Japan, with vacuum arc remelting capacity anchored in the Rhine-Ruhr and Pittsburgh industrial corridors. Raw material dependencies span nickel ore from Indonesia, titanium sponge from Japan, and platinum group metals from South Africa. Single-source vulnerability pervades superelastic alloy feedstock, where qualified wire-drawing facilities number fewer than ten globally. Distribution runs through direct manufacturer contracts with integrated delivery networks, displacing independent distributors in United States hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device miniaturization and delivery system flexibility fragment competitive positioning, creating specialist niches as stroke network expansion outpaces interventionalist training pipelines. Outpatient procedural migration generates demand for plug-compatible systems beyond incumbent full-line portfolios.
For Market Incumbents: Harden quality management systems against EU MDR conformity assessment elevation, extending notified body relationships before small-cap exits concentrate procurement leverage among scaled players. Acquire microcatheter-compatible delivery system capabilities to defend against Terumo Corporation's tortuous anatomy specialization. Backward integration into vacuum arc remelting capacity secures nitinol wire supply during demand surges from neurovascular flow diversion adoption. For New Entrants and Emerging Players: Build out telemedicine-integrated follow-up protocols for post-procedural surveillance, exploiting tertiary center dependence reduction as stroke networks decentralize. Target India's tier-two city catheterization infrastructure, where greenfield hospital construction lacks established vendor relationships. Pursue CDSCO import licensing partnerships with domestic catheter manufacturers to navigate nitinol-based implant regulatory friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among flow diverter manufacturers with multi-year implant tracking obligations and adverse event reporting infrastructure. Five-to-ten year viability favors neurovascular franchises sustaining R&D intensity against peripheral embolization commoditization. Monitor PMDA regional stroke center certification velocity as inflection indicator for Japanese procedural volume expansion beyond Tokyo.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates approval timelines for unruptured aneurysm flow diversion indications in United States stroke centers. |
| EU MDR Conformity Assessment | Elevates post-market surveillance obligations, favoring scaled manufacturers with established notified body relationships. |
| Hospital System Partnership | Enables single-source agreements spanning plugs, delivery systems, and closure devices across integrated delivery networks. |
| Reimbursement Strategy | Aligns outpatient peripheral embolization with Medicare expansion and Germany's G-DRG minimally invasive outcome incentives. |
| Software Companion Development | Supports telemedicine-integrated follow-up protocols reducing tertiary center dependence for post-procedural surveillance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with interventional cardiologists, neurointerventional surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA filings, PMDA approval databases, CMS Medicare reimbursement schedules, and EU MDR notified body assessment records. Bottom-up procedure volume modeling triangulates with top-down manufacturer revenue aggregation across the analysis window.
Calibration against historical approval velocity and reimbursement expansion patterns anchors the analytical framework across product type, application, end user, and deployment setting segmentation dimensions. CAGRs derive from procedure volume trajectories modulated by regulatory pathway acceleration and training pipeline expansion constraints. Forecast inputs incorporate stroke network certification rates, nitinol wire capacity utilization signals, and outpatient migration elasticity to site-of-service reimbursement thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified structural heart portfolios or microcatheter-compatible specialists would shift outcomes beyond modeled ranges. Macroeconomic deviation in nickel commodity pricing, regulatory restriction from PMDA localization mandates, or technological displacement from polymer particle substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Pulmonary Artery Catheter Market