
 Abdominal Stent Graft System Market | 2026-2036
Abdominal Stent Graft System Market Size, Share, and Industry Trends Forecast 2026-2036
Abdominal Stent Graft System Market Analysis
Hospital procurement for abdominal stent graft systems is pivoting toward consolidated purchasing networks and value-based contracting frameworks. Medtronic leverages its integrated vascular platform to sustain premium positioning across integrated delivery networks. W. L. Gore & Associates anchors its competitive stance through proprietary expanded polytetrafluoroethylene graft materials and specialized thoracoabdominal portfolios.
An abdominal stent graft system comprises a fabric-covered metal scaffold deployed endovascularly to exclude abdominal aortic aneurysms from systemic circulation, typically constructed from nitinol or cobalt-chromium alloys with woven polyester or ePTFE graft coverings and delivered via catheter-based introducer sheaths ranging 14-24 French. Self-expanding configurations dominate procedural volume due to conformability in tortuous anatomy, while balloon-expandable variants occupy precise landing zone applications requiring radial force control. Composite material platforms represent the fastest-growing segment as manufacturers integrate bioabsorbable polymers to enable future surgical conversion pathways.
FDA premarket approval and EMA CE marking under the Medical Device Regulation govern clinical evidence thresholds for stent graft durability claims, directly shaping trial design costs and commercialization timelines. The EU AI Act and FDA software-as-medical-device guidance increasingly scrutinize AI-augmented sizing and planning tools bundled with delivery systems. Stakeholders must monitor evolving reimbursement benchmarks for fenestrated and branched graft procedures against standard endovascular repair codes.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing manufacturers to bundle planning software with delivery systems, fundamentally restructuring how abdominal stent graft systems reach end-users.
Growth Catalysts
- Aging demographics:Germany's 65-plus population expansion drives procedural volume for minimally invasive aneurysm repair. Reimbursement alignment with endovascular techniques accelerates hospital conversion from open surgery.
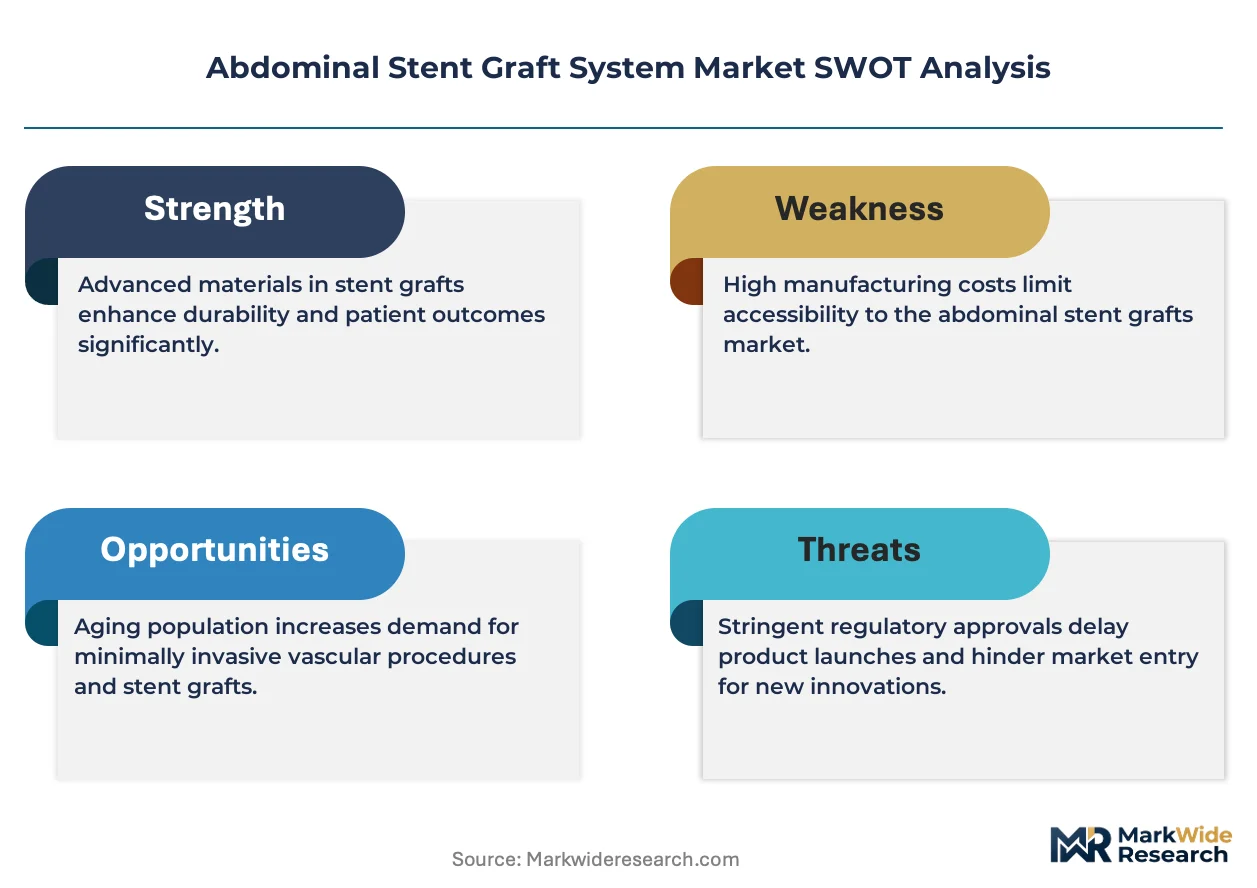
- MDR compliance pathways:EMA's tightened biocompatibility requirements for polymer-based stent grafts are elevating clinical evidence standards, filtering out marginal competitors and concentrating procurement among validated suppliers.
- ePTFE material platforms:Proprietary expanded polytetrafluoroethylene graft coverings deliver superior thromboresistance and durability profiles, commanding preference in thoracoabdominal applications across integrated delivery networks.
Market Restraints
- Nitinol price volatility:Superelastic alloy supply concentrates among specialty metal processors in Germany and Japan, exposing manufacturers to raw material cost swings and long-term contracting inflexibility.
- Fenestrated graft technical ceiling:Custom-manufactured branch vessel alignment requires 4-6 week production cycles, limiting emergency case applicability and constraining addressable procedural segments.
- FDA premarket approval friction:Durability claims for composite material platforms demand 5-year follow-up data, extending commercialization timelines and inflating trial expenditures for novel graft architectures.
Strategic Opportunities
- China's tier-2 hospital expansion:Provincial cardiovascular centers in Sichuan and Shandong provinces remain underpenetrated for endovascular aneurysm repair, offering volume expansion as catheterization lab infrastructure proliferates.
- AI-augmented sizing tools:Machine learning planning software bundled with delivery systems is unifying preoperative measurement workflows with inventory forecasting, creating service revenue streams distinct from device margins.
- EU Green Deal material mandates:Bioabsorbable polymer integration positions manufacturers for future regulatory preference as sustainability criteria penetrate medical device procurement frameworks.
Industry Challenges
- Interventional radiologist training pipelines:Fenestrated and branched graft deployment demands 100-plus case experience curves, creating procedural bottlenecks as experienced operators concentrate at academic medical centers.
- Legacy inventory reconciliation:Self-expanding and balloon-expandable variant proliferation strains hospital consignment management systems, forcing manufacturers to absorb working capital burdens for field-stocked devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abdominal Stent Graft System Market |
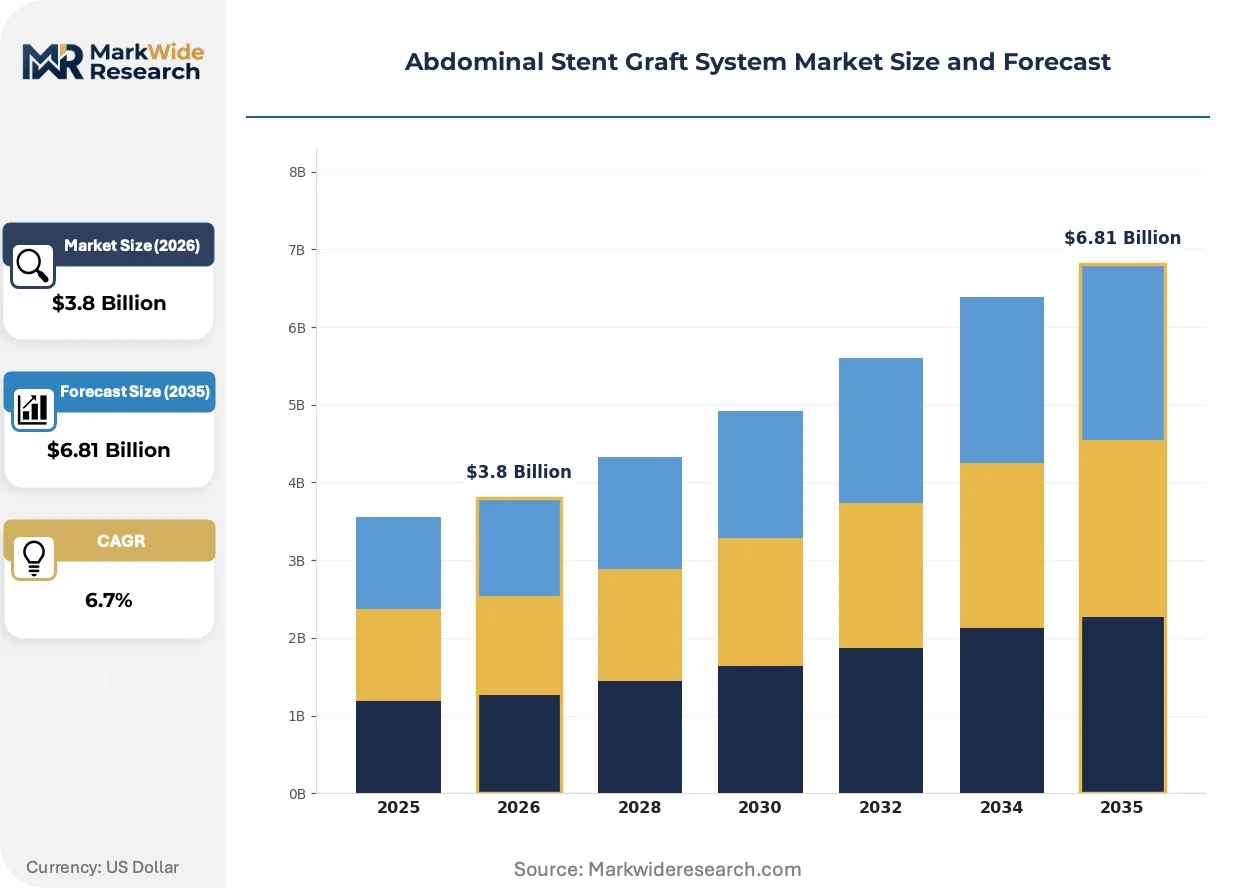
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding, Balloon-Expandable, Covered, Uncovered Delivery System: Standard Delivery, Mini-Invasive Delivery, Open Surgery Delivery, Hybrid Delivery End User: Hospitals, Surgical Centers, Outpatient Clinics, Academic Institutions Material Type: Polymer, Metal, Bio-absorbable, Composite |
| Companies Covered | W. L. Gore & Associates, Cardinal Health, Medtronic, MicroPort Scientific Corporation, Artivion, Cook Medical, Terumo Corporation, Lombard Medical, Endologix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abdominal Stent Graft System Market Emerging Trajectories
Digital integration between preoperative planning platforms and catheter-based delivery systems is collapsing traditional boundaries between diagnostic imaging and interventional execution, compressing procedural preparation cycles.
Composite material platforms incorporating bioabsorbable polymers are unifying immediate mechanical exclusion performance with future surgical conversion pathways. Academic medical centers in the United States and Germany are piloting these hybrid architectures for younger patient cohorts requiring long-term durability flexibility. This material convergence is compressing the historical trade-off between endovascular minimally invasive appeal and open surgical reversibility.
EU AI Act classification criteria are scrutinizing automated vessel segmentation algorithms bundled with stent graft planning software, reclassifying certain decision-support tools as high-risk medical devices. Manufacturers must now submit clinical validation dossiers for AI-augmented sizing recommendations previously marketed as accessory services. Fenestrated graft planning modules face the steepest compliance burden, with notified bodies demanding prospective outcome studies linking algorithmic outputs to procedural success metrics.
Integrated delivery networks in the United States are consolidating abdominal stent graft procurement through single-source contracting frameworks that bundle devices, planning software, and operator training into per-procedure fees. This displaces traditional capital equipment purchase models and vendor-managed inventory arrangements. Texas and Florida health systems lead this transition, leveraging procedural volume concentration to extract performance guarantees from manufacturers.
Abdominal Stent Graft System Market Segmentation
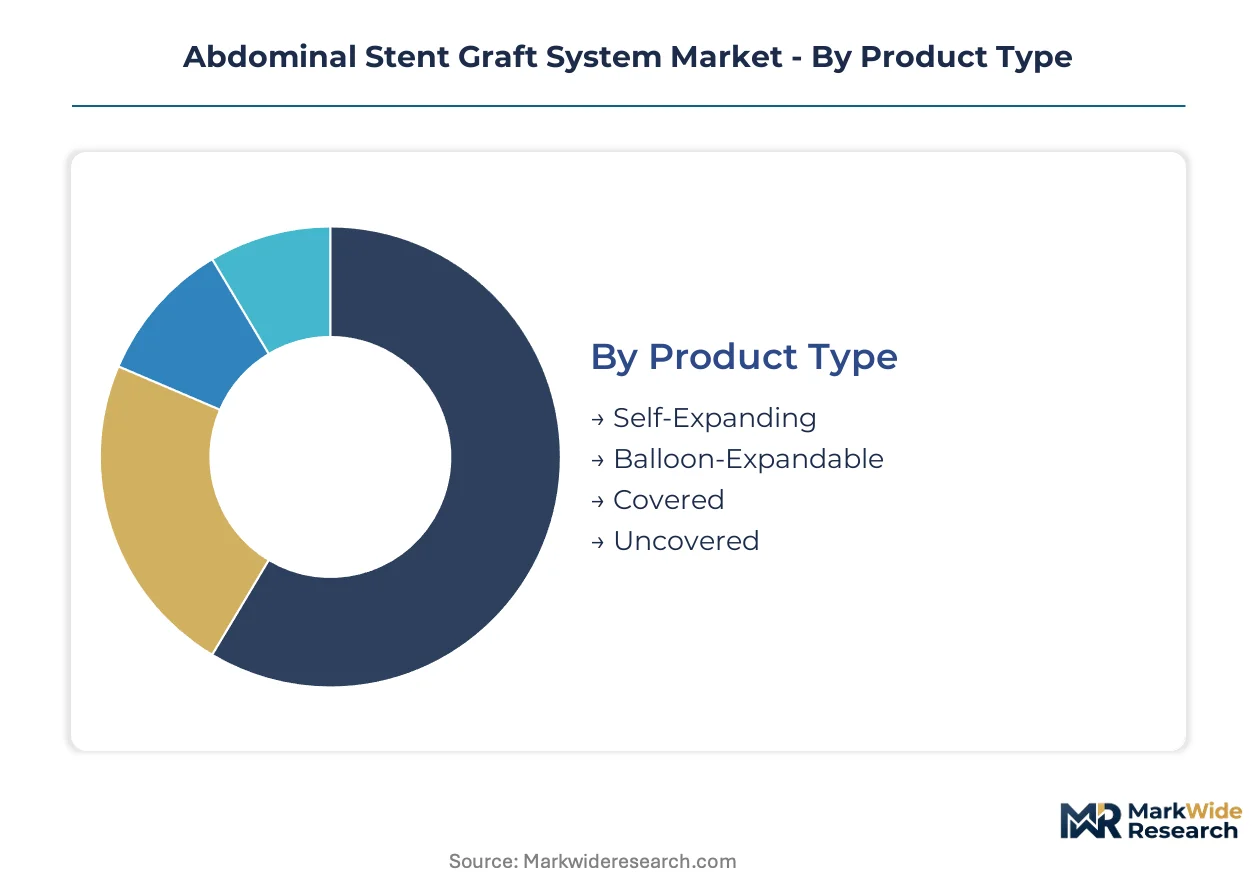
Abdominal stent graft system procurement varies sharply by deployment mechanism and material platform, with FDA PMA pathways and EMA MDR compliance requirements fragmenting competitive positioning across technical specifications. Hospital purchasing committees weight durability claims against reimbursement alignment, creating tiered demand patterns that manufacturers must map precisely.
Product Type:
Self-expanding configurations carry standard FDA 510(k) clearance pathways for established nitinol architectures, while balloon-expandable and novel composite platforms trigger premarket approval demands with extended follow-up obligations.
- Self-Expanding:Nitinol or cobalt-chromium scaffolds with woven polyester or ePTFE coverings deploy via catheter-based introducer sheaths ranging 14-24 French, conforming to tortuous iliac anatomy without balloon assistance. Demand concentrates in United States integrated delivery networks where reimbursement for standard EVAR procedures is codified and operator training pipelines are mature.
- Balloon-Expandable:Stainless steel or cobalt-chromium stents mounted on balloon catheters deliver precise radial force control for landing zones requiring exact diameter achievement. German hospital procurement favors these configurations for juxtarenal anatomies where positional accuracy trumps conformability.
- Covered:Fabric encapsulation of the entire metal scaffold excludes aneurysm sac from systemic pressure, with ePTFE coverings commanding preference in thoracoabdominal extensions.
- Uncovered:Bare metal stent segments preserve branch vessel patency in fenestrated applications, though their use is narrowing as covered alternatives improve side-branch incorporation.
Self-expanding sits at the top of the volume ranking, with composite material configurations climbing the fastest as bioabsorbable integration gains clinical traction.
Delivery System:
Delivery mechanism selection dictates catheterization lab infrastructure requirements and procedural venue eligibility, with cost tiers separating capital-intensive hybrid configurations from standard percutaneous approaches.
- Standard Delivery:18-24 French introducer sheaths deployed via femoral cutdown or percutaneous closure, compatible with conventional catheterization lab setups across hospital tiers.
- Mini-Invasive Delivery:Low-profile 14-16 French systems enable percutaneous access with reduced vascular closure complexity, expanding procedure eligibility to outpatient settings.
- Open Surgery Delivery:Surgical exposure of access vessels accommodates large-bore introducers for complex fenestrated grafts, limiting use to academic medical centers with hybrid operating suites.
- Hybrid Delivery:Combined endovascular and open surgical access supports branched graft deployment, commanding premium pricing tied to custom-manufactured physician preference kits.
Standard delivery retains the highest procedural volume, though mini-invasive systems are gaining share fastest as same-day discharge protocols proliferate.
End User:
Customer type determines contracting structure, with consolidated purchasing networks capturing volume discounts that fragment pricing across hospital systems versus independent surgical centers.
- Hospitals:Integrated delivery networks in Texas and Florida bundle devices with planning software and operator training into per-procedure fees, displacing capital purchase models.
- Surgical Centers:Ambulatory settings concentrate on uncomplicated infrarenal cases, constrained by reimbursement gaps for fenestrated procedures.
- Outpatient Clinics:Limited to diagnostic workup and follow-up imaging, with procedural revenue captured by affiliated hospitals.
- Academic Institutions:Training case volume and investigator-initiated trials justify premium procurement for custom-manufactured fenestrated grafts with extended production cycles.
Hospitals command the dominant revenue share, with surgical centers expanding most quickly as mini-invasive delivery enables venue migration.
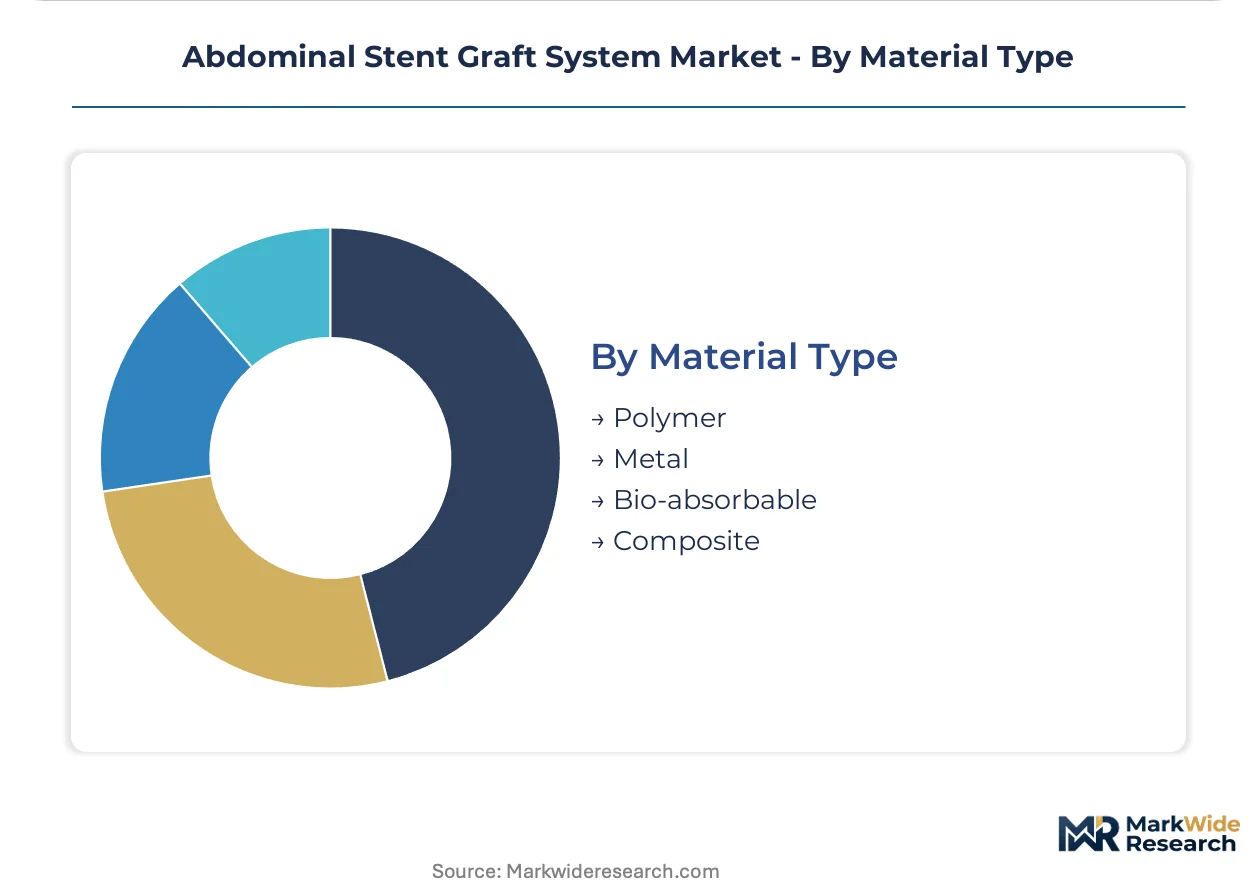
Material Type:
Material platform maturity stratifies regulatory burden, with established metal and polymer configurations navigating streamlined clearance while bioabsorbable and composite architectures face novel biocompatibility scrutiny.
- Polymer:Woven polyester graft coverings dominate standard EVAR applications, with EMA MDR tightening extractables and leachables testing requirements for long-term implantation.
- Metal:Nitinol superelasticity enables self-expanding conformability, though supply concentration among German and Japanese specialty processors exposes manufacturers to raw material cost volatility.
- Bio-absorbable:Polylactic acid and polyglycolic acid scaffolds enable future surgical conversion pathways, piloted in United States and German academic centers for younger patient cohorts.
- Composite:Integration of bioabsorbable polymers with permanent metal scaffolds unifies immediate mechanical performance with long-term flexibility, triggering FDA PMA demands for 5-year durability data.
Metal platforms anchor current volume leadership, with composite materials showing the steepest expansion trajectory as hybrid architectures compress the trade-off between endovascular appeal and surgical reversibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement alignment outpaces German procurement consolidation, while Chinese provincial expansion accelerates faster than Japanese regulatory harmonization. Each geography deploys distinct regulatory levers and infrastructure investments that reshape stent graft commercialization pathways.
United States
Integrated delivery networks in Texas and Florida concentrate fenestrated graft procurement through single-source contracting frameworks. FDA premarket approval pathways demand five-year durability data for composite material platforms, elevating clinical evidence thresholds. Academic medical centers in Boston and Houston pilot bioabsorbable polymer integration for younger patient cohorts requiring future surgical conversion flexibility.
Germany
EMA Medical Device Regulation tightens biocompatibility testing for polymer-based stent grafts, filtering marginal competitors from procurement pools. Nitinol supply concentrates among specialty metal processors in North Rhine-Westphalia, exposing manufacturers to raw material cost volatility. University hospitals in Munich and Heidelberg anchor fenestrated graft training pipelines, creating operator experience bottlenecks that constrain procedural volume expansion.
China
Provincial cardiovascular centers in Sichuan and Shandong provinces remain underpenetrated for endovascular aneurysm repair as catheterization lab infrastructure proliferates. NMPA regulatory harmonization with international standards accelerates approval timelines for imported graft systems. Tier-2 hospital expansion in Chengdu and Jinan creates volume opportunities as minimally invasive techniques displace open surgery in regional markets.
Japan
PMDA reimbursement alignment with endovascular repair techniques accelerates hospital conversion from traditional open surgical approaches. Superelastic alloy supply dependencies on domestic specialty processors create long-term contracting inflexibility for nitinol-dependent manufacturers. Metropolitan medical centers in Tokyo and Osaka concentrate experienced interventional radiologists, limiting fenestrated graft deployment to academic institutions with sufficient case volumes.
Abdominal Stent Graft System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated market structure where scale advantages clash with material innovation agility. Hospital purchasing consolidation favors integrated platform vendors capable of bundling devices with planning software and operator training. Three archetypes dominate: diversified medical technology conglomerates with vascular portfolios, specialized graft material innovators with proprietary polymer platforms, and regional champions leveraging domestic regulatory familiarity. Competitive moves center on M&A for AI-augmented sizing capabilities and strategic partnerships for China market access.
Among diversified platform vendors, Medtronic and Cardinal Health represent scale-driven archetypes that anchor integrated delivery network contracting through bundled service offerings. W. L. Gore & Associates exemplifies the specialized material innovator tier, occupying a position defined by proprietary expanded polytetrafluoroethylene graft coverings. These three entities collectively illustrate how competitive positioning stratifies across procurement consolidation pressures, regulatory evidence requirements, and material platform differentiation vectors.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| Cardinal Health |
| Medtronic |
| MicroPort Scientific Corporation |
| Artivion |
| Cook Medical |
| Terumo Corporation |
| Lombard Medical |
| Endologix |
| Others |
Supply Flow & Price Mechanics
Composite material platform integration with bioabsorbable polymers is compressing per-unit manufacturing economics while concentrating production expertise among German and Japanese specialty processors. This dual shift elevates pricing power for validated suppliers and exposes margin vulnerability for manufacturers lacking captive nitinol supply.
Pricing Analysis
Capacity additions in China's tier-2 cardiovascular centers are reshaping price floors for standard self-expanding configurations. Three-tier pricing structure across premium fenestrated, standard infrarenal, and economy bare-metal tiers separates academic medical center procurement from ambulatory surgical volume. Cost compression in standard EVAR segments is intensifying because integrated delivery networks extract performance guarantees through per-procedure bundling. Ambulatory surgical centers exhibit highest price sensitivity; academic institutions with training case volume demonstrate lowest.
Supply Chain Analysis
Specialized metallurgical engineering talent scarcity in North Rhine-Westphalia and Tokyo constrains nitinol superelastic alloy expansion. Supply concentrates in Germany, Japan, and the United States for nitinol scaffolds; China and the United States for woven polyester graft textiles; Ireland and Japan for ePTFE membrane production. Single-source vulnerability runs through German specialty metal processors for superelastic alloy feedstock. Distribution runs through hospital consignment models and GPO-contracted direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in abdominal stent graft systems rests on AI-augmented planning software bundling and composite material premium tier migration. Bioabsorbable polymer integration enables pricing power unavailable to legacy metal-only platforms.
For Market Incumbents: Cement integrated delivery network lock-in by bundling fenestrated graft planning software with operator training commitments. Backward integration into nitinol processing mitigates raw material cost volatility from German and Japanese specialty suppliers. Defensive patent positioning around bioabsorbable polymer-metal composite architectures blocks emerging entrant technical differentiation. For New Entrants and Emerging Players: Regional distributors with established catheterization lab relationships offer fastest pathway to hospital formulary access. China's Sichuan and Shandong provincial cardiovascular centers represent most penetrable geography as infrastructure investment outpaces established vendor field presence. Reimbursement strategy alignment with NMPA harmonization timelines accelerates commercialization velocity versus direct FDA PMA pathway competition. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialists with fenestrated graft custom-manufacturing capabilities but limited integrated delivery network contract penetration. Long-term viability framing centers on AI-augmented sizing tool acquisition and China market access partnerships as value creation levers. Watch FDA premarket approval timeline compression for composite material platforms as inflection signal for platform consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Five-year durability data requirements elevate clinical evidence thresholds for composite graft architectures. |
| CE Marking Pathway under MDR | Tightened biocompatibility testing filters marginal competitors from EMA procurement pools. |
| Hospital System Partnership | Texas and Florida integrated delivery networks consolidate procurement through single-source contracting frameworks. |
| Software Companion Development | AI-augmented sizing tools bundled with delivery systems create service revenue distinct from device margins. |
| Reimbursement Strategy | Alignment with CMS endovascular repair codes determines fenestrated graft addressable market expansion. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down nitinol supply tracking forms the analytical core. Primary interviews with interventional radiologists, hospital purchasing committee directors, GPO contracts managers, and biomedical engineering specialists combined with FDA PMA filings, EMA MDR submission databases, hospital procurement contract registries, and CMS reimbursement code analysis. Secondary validation draws from SEC 10-K vascular segment disclosures and trade customs data for nitinol alloy imports.
Input-output matrices link catheterization lab infrastructure deployment rates to procedural volume forecasts across self-expanding, balloon-expandable, and composite material platforms. Segmentation dimensions span deployment mechanism, material platform, delivery system profile, and end-user facility tier. CAGRs derive from regression against aging demographic trajectories and reimbursement alignment indicators. Forecast inputs incorporate EMA MDR compliance cost inflation and NMPA harmonization timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA composite material approval friction and China tier-2 hospital infrastructure buildout pacing. Material deviation in nitinol supply concentration or integrated delivery network consolidation velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Global Peripheral Stent Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market