
 Renovascular Hypertension Treatment Market | 2026-2036
Renovascular Hypertension Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Renovascular Hypertension Treatment Market Analytics
CE marking under the EU Medical Device Regulation is rotating the competitive field toward manufacturers with notified body partnerships and quality management system certifications. Abbott Laboratories leverages its structural heart portfolio to extend catheter-based renal artery capabilities. Pfizer Inc. anchors its position through sustained R&D investment in combination antihypertensive therapies that complement interventional procedures. Novartis AG differentiates via its cardiovascular franchise and geographic reach across European and North American hospital networks.
Renovascular hypertension treatment encompasses pharmacological, endovascular, and surgical interventions targeting renal artery stenosis to restore perfusion and control blood pressure, with balloon-expandable stent systems typically constructed from cobalt-chromium or platinum-iridium alloys and drug-eluting coatings designed to limit neointimal hyperplasia. Medication remains the foundational approach for hemodynamically insignificant stenosis, while angioplasty and stenting capture margin concentration in tertiary care centers where procedure reimbursement and operator volume drive profitability. Device type segmentation reveals Doppler ultrasound gaining traction in outpatient screening protocols, and direct sales channels dominate high-value stent and catheter transactions due to capital equipment bundling and clinical training requirements.
FDA premarket approval pathways and the EU MDR clinical evaluation requirements shape product development timelines and market access costs for renal artery intervention devices. Japan's PMDA and its pharmaceutical and medical device agency standards impose additional local clinical testing burdens that filter market entrants. Health Canada and the TGA in Australia maintain parallel but distinct approval frameworks that manufacturers must navigate for comprehensive North American and Asia-Pacific commercialization. Stakeholders should monitor evolving renal denervation reimbursement decisions and comparative effectiveness trial readouts that will reshape interventional versus medical management algorithm positioning.
Market Dynamics
Renal denervation catheter technology is compressing procedural timelines and forcing hospital cath labs to retrain interventional cardiologists on radiofrequency and ultrasound ablation platforms, fundamentally altering workforce deployment and capital allocation across tertiary cardiovascular centers.
Growth Catalysts
- Breakthrough Device Pathway:FDA breakthrough device designations for next-generation renal denervation systems compress premarket review timelines and accelerate hospital formulary adoption in the United States.
- EU MDR CE Marking:Streamlined conformity assessment pathways under the EU Medical Device Regulation enable faster commercialization for manufacturers with established notified body partnerships.
- Japan's Aging Demographics:Elevated prevalence of resistant hypertension among Japan's elderly population drives procedure volume expansion in Tokyo and Osaka metropolitan hospital networks.
Market Restraints
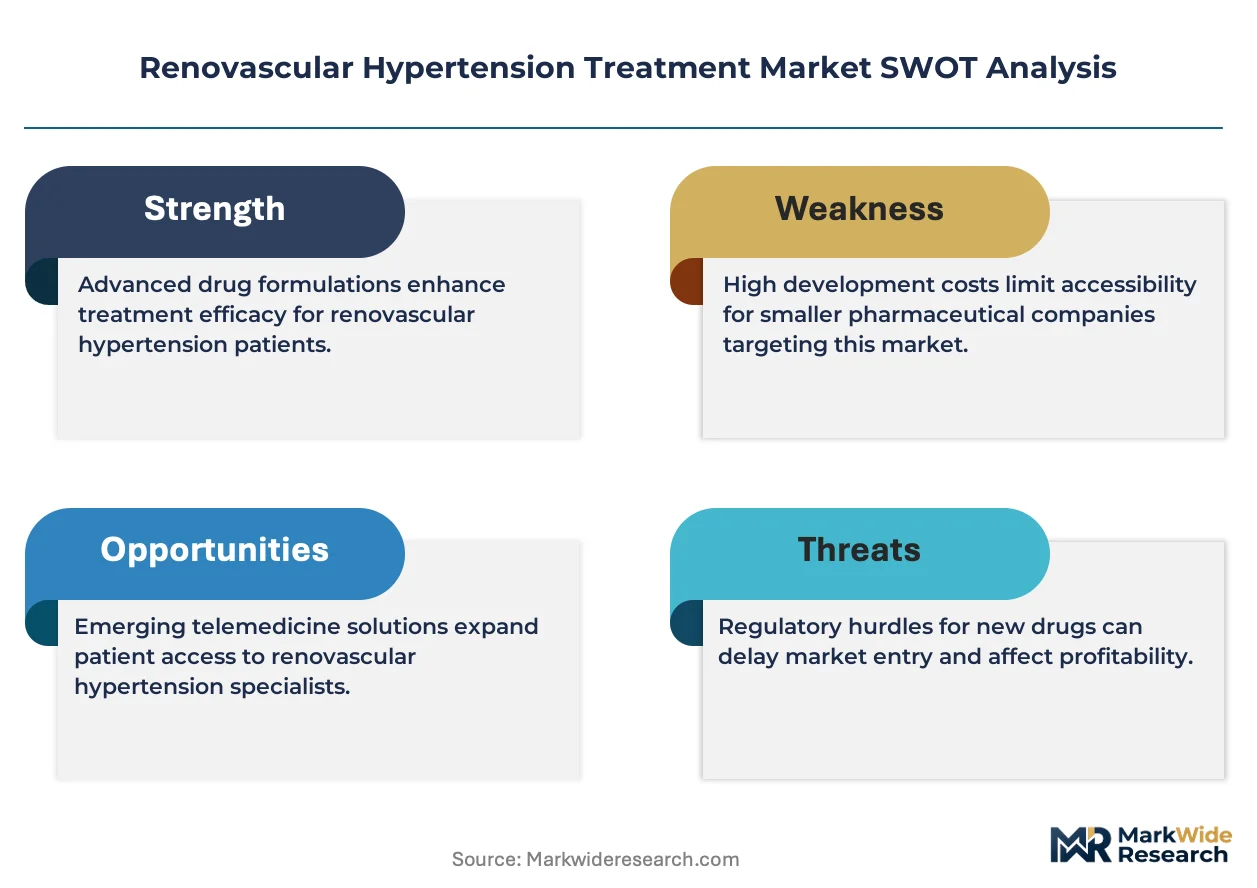
- Platinum-Iridium Alloy Costs:Balloon-expandable stent manufacturing depends on volatile precious metal prices that compress gross margins for device producers.
- PMDA Local Testing Burden:Japan's pharmaceutical and medical device agency requires redundant clinical trials that extend time-to-market by 18-24 months for foreign manufacturers.
- Medical Management Substitution:Optimized triple antihypertensive regimens delay interventional referrals in primary care settings where physicians prioritize pharmacological escalation.
Strategic Opportunities
- German Outpatient Screening:Doppler ultrasound deployment in ambulatory cardiology practices creates upstream patient identification channels for interventional centers in Bavaria and Baden-Württemberg.
- Reimbursement Tailwind:Medicare's transitional pass-through payment status for renal denervation procedures incentivizes hospital investment in ablation catheter inventory.
- AI-Enabled Patient Selection:Machine learning algorithms analyzing CT angiography datasets converge with interventional planning software to optimize renal artery anatomical suitability assessment.
Industry Challenges
- Interventional Cardiology Skill Gap:Renal artery cannulation demands specialized wire manipulation techniques that fewer trainees master as structural heart procedures absorb fellowship training hours.
- MDR Technical Documentation:EU Medical Device Regulation clinical evaluation report requirements consume 12-18 months of regulatory affairs bandwidth for legacy stent system recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renovascular Hypertension Treatment Market |
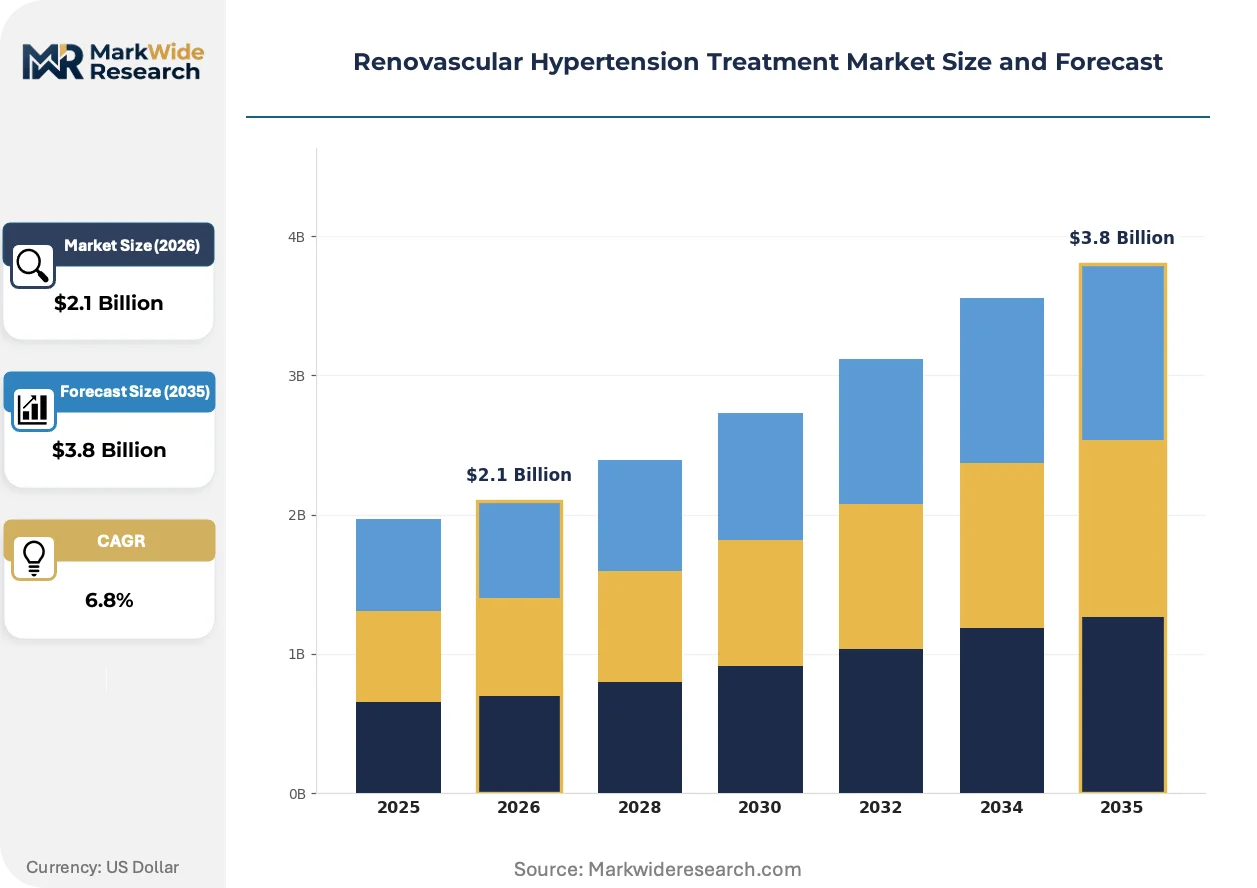
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Angioplasty, Stenting, Surgery, Medication End User: Hospitals, Clinics, Home Care, Outpatient Centers Device Type: Balloon Catheters, Stents, Surgical Instruments, Doppler Ultrasound Distribution Channel: Direct Sales, Medical Distributors, Online Sales, Others |
| Companies Covered | Abbott Laboratories, Pfizer Inc., Novartis AG, Merck & Company, Inc., AstraZeneca plc, Johnson & Johnson, Eli Lilly and Company, Sanofi SA, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renovascular Hypertension Treatment Market Evolving Landscape
Catheter-based renal denervation systems are displacing traditional angioplasty-first protocols, while artificial intelligence and point-of-care diagnostics reshape patient identification workflows across ambulatory and inpatient settings.
Radiofrequency ablation catheter technology targets sympathetic nerve fibers surrounding renal arteries to disrupt pathological signaling. Interventional cardiologists in high-volume US hospital systems are adopting these platforms at accelerating pace following favorable reimbursement determinations. The technology is miniaturizing delivery profiles from 6-French to 4-French catheter diameters, enabling transradial access that reduces vascular complication rates and shortens recovery times.
EU Medical Device Regulation post-market surveillance requirements mandate systematic collection of real-world performance data for renal artery intervention devices. Manufacturers must establish periodic safety update reports and proactive vigilance systems that increase regulatory compliance costs. Class III implantable device categories face the strictest scrutiny, prompting European notified bodies to demand extended follow-up clinical data before renewing CE certificates.
Hospital purchasing committees are consolidating vendor relationships for cardiovascular device categories to extract volume-based pricing concessions. Integrated delivery networks in the United States are displacing traditional distributor intermediaries through direct manufacturer contracts that bundle stent systems with catheter inventory and clinical training support. This concentration is most visible in Texas and Florida health systems where private equity-backed hospital rollups standardize procurement across dozens of facilities.
Renovascular Hypertension Treatment Market Segmentation
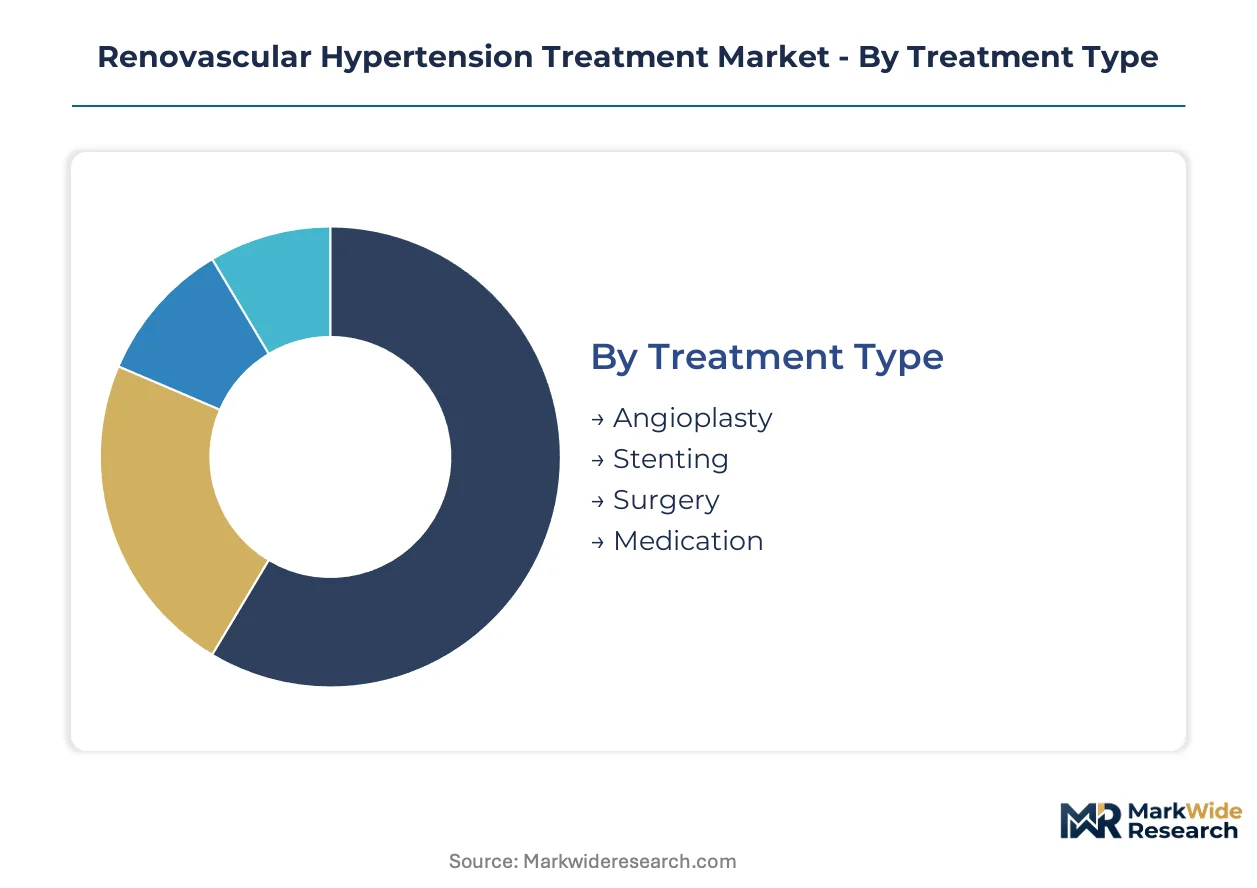
Renovascular hypertension treatment markets fragment across intervention intensity, care setting economics, and device capital requirements. Segment boundaries determine pricing power, regulatory pathway complexity, and vendor competitive moats.
Treatment Type:
Margin pools concentrate in catheter-based interventions where procedure reimbursement rates exceed medical management by substantial multiples.
- Angioplasty:Balloon dilation of renal artery stenosis restores perfusion without permanent implant. Demand clusters in United States tertiary centers where Medicare reimbursement codes support outpatient procedure economics.
- Stenting:Balloon-expandable metal scaffolds maintain luminal patency. Cobalt-chromium and platinum-iridium alloys dominate construction; drug-eluting coatings limit restenosis. Germany's statutory health insurance funds expanded coverage for renal artery stenting, concentrating volume in Bavarian and Baden-Württemberg hospital networks.
- Surgery:Open renal artery reconstruction for complex anatomical disease. Aorto-renal bypass and endarterectomy retain niche indications where endovascular approaches fail.
- Medication:ACE inhibitors, ARBs, and calcium channel blockers constitute first-line therapy for hemodynamically insignificant stenosis. Primary care physicians in Japan's community health systems escalate pharmacologically before interventional referral.
Stenting holds installed capacity. Angioplasty is rotating up the share rankings as renal denervation platforms displace permanent implants.
End User:
Procedure volume distributes unevenly across facility types, with capital equipment requirements filtering participation.
- Hospitals:Tertiary cardiovascular centers house hybrid operating suites and interventional cardiology departments. Tokyo Metropolitan Hospital and Osaka University Hospital anchor Japan's highest-volume renal artery intervention practice.
- Clinics:Ambulatory cardiology practices in Germany's Stuttgart and Munich regions deploy Doppler ultrasound for upstream screening, generating referral pipelines to interventional centers.
- Home Care:Blood pressure monitoring and medication adherence programs extend treatment continuity post-intervention. Remote patient monitoring platforms integrate with hospital electronic health records.
- Outpatient Centers:Freestanding cath labs in Texas and Florida health systems capture same-day discharge cases, extracting volume from inpatient reimbursement categories.
Hospitals command the revenue base. Outpatient centers are climbing the fastest in procedure share.
Device Type:
Technology substitution between diagnostic and therapeutic platforms reshapes vendor competitive positioning.
- Balloon Catheters:Semi-compliant and non-compliant balloon platforms predominate in renal artery dilation. Profile miniaturization to 4-French compatibility enables transradial access adoption.
- Stents:Bare-metal and drug-eluting configurations address varying lesion complexity. FDA premarket approval pathways and EU MDR conformity assessments govern commercialization timelines.
- Surgical Instruments:Vascular clamps, shunts, and reconstruction grafts support open operative approaches. Demand concentrates in academic medical centers maintaining cardiothoracic surgery training programs.
- Doppler Ultrasound:Non-invasive renal artery velocity measurement enables outpatient screening. Japanese primary care clinics integrate resistive index calculation into hypertension workup protocols.
Stents hold installed capacity. Doppler ultrasound is rotating up the share rankings.
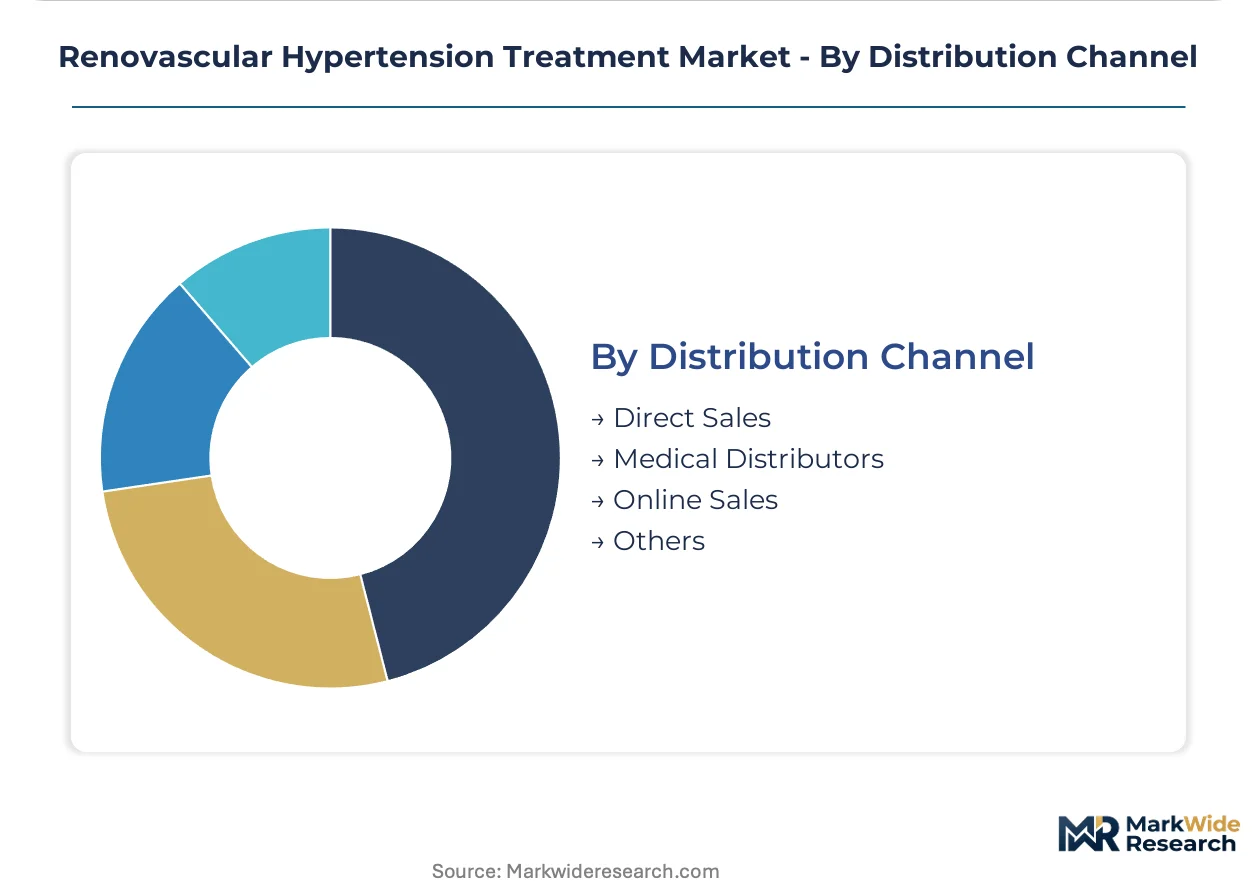
Distribution Channel:
Channel economics diverge sharply between capital equipment bundling and consumable replenishment models.
- Direct Sales:Manufacturer field forces negotiate integrated delivery network contracts bundling stent inventory with clinical training and procedural support. United States hospital purchasing committees consolidate vendor relationships to extract volume pricing.
- Medical Distributors:Regional intermediaries maintain inventory proximity for emergency restocking. German medical device distributors serve mid-tier hospitals lacking direct manufacturer relationships.
- Online Sales:E-procurement platforms penetrate consumable categories where specification standardization permits arm's-length transactions. Blood pressure monitors and home diagnostic devices migrate fastest to digital channels.
- Others:Group purchasing organizations aggregate demand across hospital systems, applying tender-based selection for commodity device categories.
Direct sales holds installed capacity. Online sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital purchasing committees in tertiary cardiovascular centers concentrate demand across four major economies where reimbursement frameworks and aging demographics align. Each market presents distinct regulatory pathways and industrial cluster dynamics.
United States
Medicare's transitional pass-through payment status for renal denervation procedures drives hospital investment in ablation catheter inventory. FDA breakthrough device designations compress premarket review timelines for manufacturers. Texas and Florida health systems lead outpatient procedure volume expansion through private equity-backed hospital rollups.
Germany
Statutory health insurance funds expanded coverage for renal artery stenting, concentrating intervention volume in Bavarian and Baden-Württemberg hospital networks. CE marking under EU MDR enables faster commercialization for manufacturers with notified body partnerships. Stuttgart and Munich ambulatory cardiology practices deploy Doppler ultrasound for upstream patient screening.
Japan
Elevated prevalence of resistant hypertension among Japan's elderly population drives procedure expansion in Tokyo and Osaka metropolitan hospital networks. PMDA local clinical testing requirements extend time-to-market by 18-24 months for foreign manufacturers. Tokyo Metropolitan Hospital and Osaka University Hospital anchor the country's highest-volume renal artery intervention practice.
United Kingdom
NHS England's specialized commissioning frameworks concentrate complex renal artery procedures in designated tertiary cardiovascular centers. MHRA post-Brexit regulatory alignment with EU MDR standards shapes device approval timelines. London and Southeast England hospital trusts maintain hybrid operating suites for endovascular intervention.
Renovascular Hypertension Treatment Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with cardiovascular franchises alongside specialized medical device manufacturers with interventional cardiology expertise. Market structure exhibits tiered consolidation where large-cap therapeutics developers coexist with mid-cap device specialists. Strategic archetypes include integrated pharma-device hybrids, pure-play interventional device developers, and research-intensive biopharmaceutical innovators. Dominant competitive moves encompass portfolio diversification into adjacent cardiovascular segments and strategic partnerships to secure catheter-based technology access.
Among diversified healthcare conglomerates, Abbott Laboratories and Johnson & Johnson occupy positions spanning structural heart and interventional cardiology portfolios. Pfizer Inc. and Novartis AG exemplify pharmaceutical-centric archetypes with sustained cardiovascular R&D investment. These entities represent contrasting strategic postures: device-forward integration versus therapeutics-led market presence.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Pfizer Inc. |
| Novartis AG |
| Merck & Company, Inc. |
| AstraZeneca plc |
| Johnson & Johnson |
| Eli Lilly and Company |
| Sanofi SA |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day catheter inventory cycles at US hospital systems concentrate purchasing leverage among integrated delivery networks, compressing vendor margins while amplifying price transparency across balloon catheter and stent categories. This lead-time compression reshapes how manufacturers allocate working capital between platinum-iridium alloy hedging and finished goods safety stock.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange precious metal prices govern balloon-expandable stent procurement between German statutory health insurers and device manufacturers. Three-tier pricing structure across premium drug-eluting, standard bare-metal, and economy balloon-only tiers separates reimbursement-eligible implants from cash-pay alternatives. Pricing pressure stems from Medicare's site-neutral payment policies that narrow outpatient-to-inpatient reimbursement spreads. Ambulatory surgery centers exhibit highest price sensitivity due to fixed case-rate contracts, while academic medical centers prioritize clinical training support over unit cost.
Supply Chain Analysis
Inventory positioning at 45-60 days for cobalt-chromium alloy feedstock reflects just-in-time manufacturing coordination between Minnesota and Ireland production facilities. Supply concentrates in the United States, Germany, and Japan for precision catheter extrusion and laser-cut stent fabrication. Raw material dependencies include platinum-iridium alloys, cobalt-chromium tubing, and polyether block amide elastomers for catheter shafts. Single-source vulnerability in laser micromachining equipment creates chokepoint exposure. Distribution runs through direct sales forces for high-value stent systems, with regional distributors handling emergency restocking for mid-tier hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through US hospital rollup activity, as private equity-backed health systems in Texas and Florida consolidate procurement committees across dozens of facilities. This aggregation shifts negotiation leverage toward volume-based pricing and bundled service contracts.
For Market Incumbents: Consolidate catheter manufacturing capacity in Ireland and Costa Rica to exploit EU MDR and FDA parallel approval synergies. Lock in multi-year platinum-iridium supply agreements before commodity volatility intensifies. Defend against renal denervation substitution by embedding stent systems into integrated delivery network exclusive contracts that bundle training and inventory management. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks provide regulatory differentiation for radiofrequency ablation platforms targeting resistant hypertension populations underserved by optimized medical management. Target German outpatient cardiology clinics in Stuttgart and Munich for Doppler ultrasound screening partnerships that generate interventional referrals. Pursue white-label manufacturing arrangements with established catheter producers to bypass capital-intensive cleanroom infrastructure requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified cardiovascular conglomerates seeking to monetize non-core renal artery stent franchises amid portfolio rebalancing toward structural heart and electrophysiology. Long-term viability hinges on reimbursement tailwinds for renal denervation persisting through Medicare coverage determinations. Monitor PMDA approval timelines for Japanese market entry as inflection indicator for competitive positioning in Asia-Pacific expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review timelines compress hospital formulary adoption cycles for renal denervation systems. |
| EU MDR CE Marking Pathway | Notified body partnerships enable faster commercialization across German and UK hospital networks. |
| Hospital System Partnership | Integrated delivery network contracts bundle stent inventory with interventional cardiologist training programs. |
| Reimbursement Strategy | Medicare transitional pass-through status drives catheter inventory investment in US tertiary centers. |
| Software Companion Development | AI-enabled CT angiography analysis optimizes renal artery anatomical suitability assessment workflows. |
Research Methodology
A standing panel of interventional cardiologists, hospital purchasing committee directors, regulatory affairs specialists, and GPO contracts managers provided ongoing calibration against secondary validation from FDA premarket approval filings, EU MDR notified body decision databases, CMS Medicare reimbursement determinations, and Japanese PMDA clinical trial registries. Primary interviews with catheter manufacturing executives and biomedical engineering directors combined with bottom-up procedure volume modeling and top-down market size triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include treatment intensity, care setting economics, device capital requirements, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, reimbursement rate evolution, and technology substitution curves. Forecast inputs incorporated renal denervation adoption curves, platinum-iridium price volatility bands, and hospital consolidation timelines.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement and EU MDR implementation continuity; material deviation in renal denervation coverage determinations or precious metal supply disruptions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Perfusion Systems Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
Italy Cardiovascular Devices Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Global Vascular Embolization Market